
 India Security Brokerage Market | 2026-2036
India Security Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
India Security Brokerage Market Insights
The gap between traditional full-service brokerage and self-directed digital trading is collapsing as retail investors migrate toward low-cost execution platforms. Zerodha dominates the discount brokerage segment through its proprietary Kite platform and flat-fee pricing architecture. ICICI Direct anchors the full-service category with integrated research and banking distribution across its parent lender's branch network. HDFC Securities competes through hybrid advisory models that blend human relationship managers with automated portfolio tools.
Security brokerage encompasses the intermediation of financial instrument transactions between buyers and sellers, encompassing order execution, clearing, settlement, and custody services governed by T+1 rolling settlement cycles and SEBI-mandated investor protection frameworks. The primary commercial purpose centers on enabling capital market access while generating transaction-based revenue through commissions, spreads, and ancillary services. Discount brokerage services lead volume metrics as price-sensitive retail traders gravitate toward zero-commission equity delivery and fixed-cost derivatives execution. Full-service brokerage retains margin concentration in high-net-worth segments where bundled research, tax planning, and structured product distribution justify premium fee structures. Robo-advisory represents the fastest-growing service type as algorithmic portfolio construction scales across mass-affluent demographics with sub-Rs 50 lakh investable assets.
SEBI mandates disclosure norms, investor grievance redressal mechanisms, and net-worth requirements that shape broker licensing and operational continuity standards. RBI regulations governing bank-owned brokers like SEBI Securities and Kotak Securities impose additional capital adequacy and firewall provisions between lending and securities activities. BSE and NSE clearing corporation rules determine margin collection timelines, collateral eligibility, and default waterfall structures that directly impact broker liquidity management. Stakeholders must monitor SEBI's proposed T+0 settlement pilot and its implications for intraday funding costs alongside the central bank's digital rupee roadmap for securities settlement infrastructure.
Market Dynamics
SEBI's margin norm tightening is compressing legacy commission structures while mobile-first platforms accelerate retail participation across Maharashtra and Gujarat. This regulatory pressure combined with technology diffusion is collapsing the traditional full-service and discount brokerage boundary.
Growth Catalysts
- SEBI Demat Account Reforms:Simplified onboarding protocols reduce account opening friction for first-generation investors in tier-2 cities, expanding the addressable retail base beyond metropolitan centers.
- Algorithmic Portfolio Construction:Robo-advisory platforms scale across mass-affluent demographics with sub-Rs 50 lakh investable assets, lowering cost-to-serve ratios while maintaining personalization.
- Derivatives Execution Demand:Equity derivatives volume concentrates among price-sensitive traders seeking fixed-cost execution, driving platform infrastructure investments in co-located servers and low-latency order routing.
Market Restraints
- Net-Worth Compliance Burden:SEBI-mandated capital adequacy requirements create licensing barriers for new entrants, consolidating market share among established players with balance sheet depth.
- T+1 Settlement Liquidity Compression:Compressed settlement cycles intensify intraday funding requirements, squeezing working capital efficiency for brokers with limited treasury operations.
- Bank-Owned Broker Firewall Provisions:RBI regulations impose operational separation between lending and securities activities, constraining cross-selling synergies for HDFC Securities and Kotak Securities.
Strategic Opportunities
- Tier-2 City Penetration:Underpenetrated markets in Indore, Surat, and Coimbatore present whitespace for hybrid advisory models blending relationship managers with automated tools.
- Digital Rupee Settlement Infrastructure:RBI's central bank digital currency roadmap offers first-mover advantage for brokers integrating CBDC rails into clearing and settlement workflows.
- API Ecosystem Monetization:Open banking convergence with securities infrastructure enables third-party developer marketplaces, creating recurring revenue streams beyond transaction commissions.
Industry Challenges
- Quantitative Risk Modeling Talent Scarcity:Derivatives-heavy retail participation demands sophisticated margin engine capabilities that outpace domestic quantitative finance talent pipeline development.
- Legacy Core System Integration Friction:Full-service incumbents face technical debt burdens when embedding real-time analytics into decades-old order management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Security Brokerage Market |
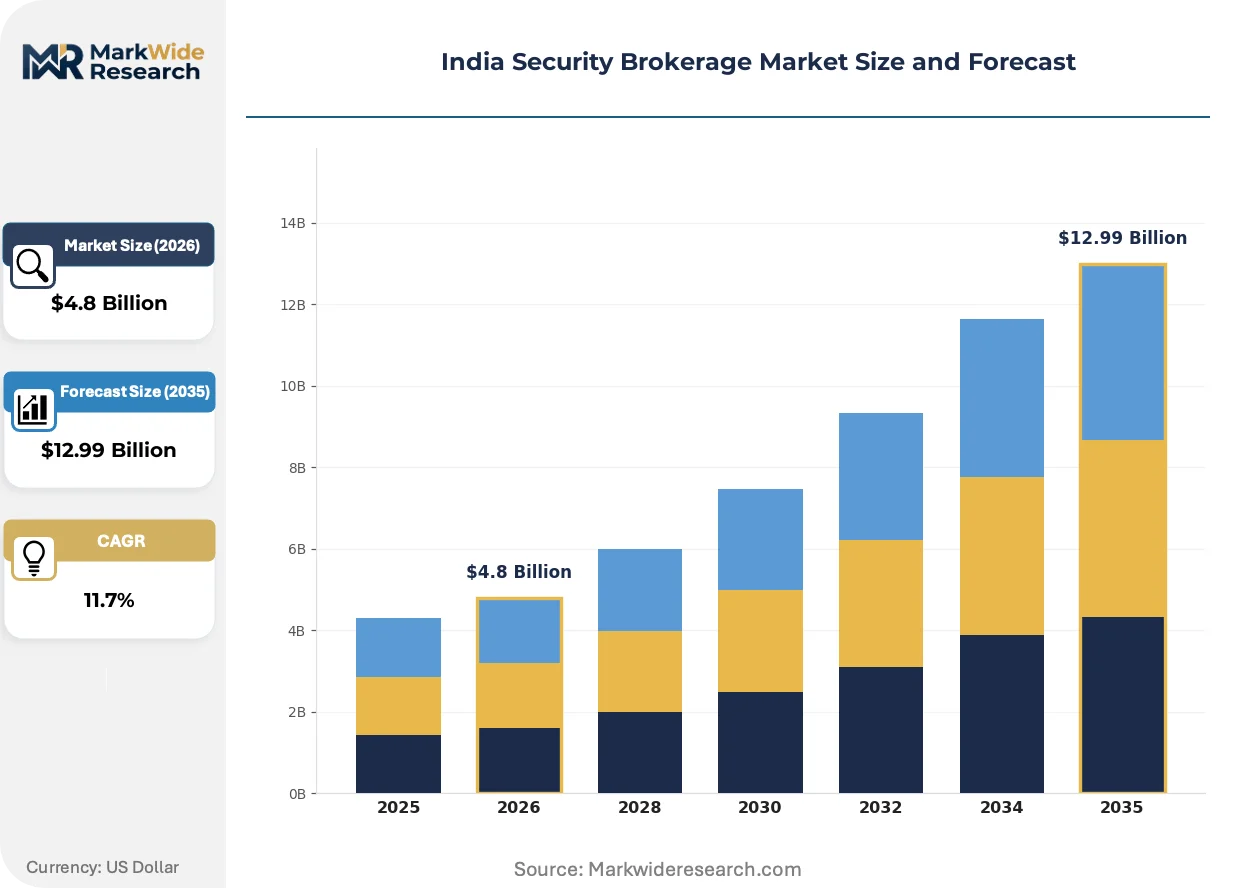
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Equity, Derivatives, Mutual Funds, ETFs Client Type: Retail Investors, Institutional Investors, High Net Worth Individuals, Corporates Service Type: Full-Service Brokerage, Discount Brokerage, Robo-Advisory, Wealth Management Trading Platform: Web-Based, Mobile App, Desktop Client, API Integration |
| Companies Covered | ICICI Direct, HDFC Securities, Zerodha, SBI Securities, Motilal Oswal, Angel One, Kotak Securities, Dhan, Upstox, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Security Brokerage Market Trends and Innovations
Proprietary trading platforms are actively displacing branch-dependent distribution models across Indian brokerage. Technology investments concentrate on reducing latency, automating compliance, and unbundling research from execution.
Artificial intelligence-powered risk engines are displacing manual margin monitoring at discount brokers. Tier-1 cities deploy machine learning models that dynamically adjust intraday exposure limits based on volatility clustering. This capability is compressing operational risk premiums and enabling higher leverage ratios within SEBI-mandated guardrails.
SEBI's proposed T+0 settlement pilot is forcing liquidity infrastructure overhauls across clearing participants. Brokers must pre-position collateral and accelerate fund mobilization to avoid settlement failures. The derivatives segment faces the steepest adaptation curve given its leveraged position structures and mark-to-market frequency.
First-generation investors in Gujarat and Maharashtra are bypassing traditional research intermediaries in favor of social trading signals and crowdsourced sentiment analytics. Telegram channels and Twitter-based analyst followings substitute for formal equity research subscriptions. This behavioral shift pressures full-service brokers to unbundle advisory components or absorb margin compression.
India Security Brokerage Market Segmentation
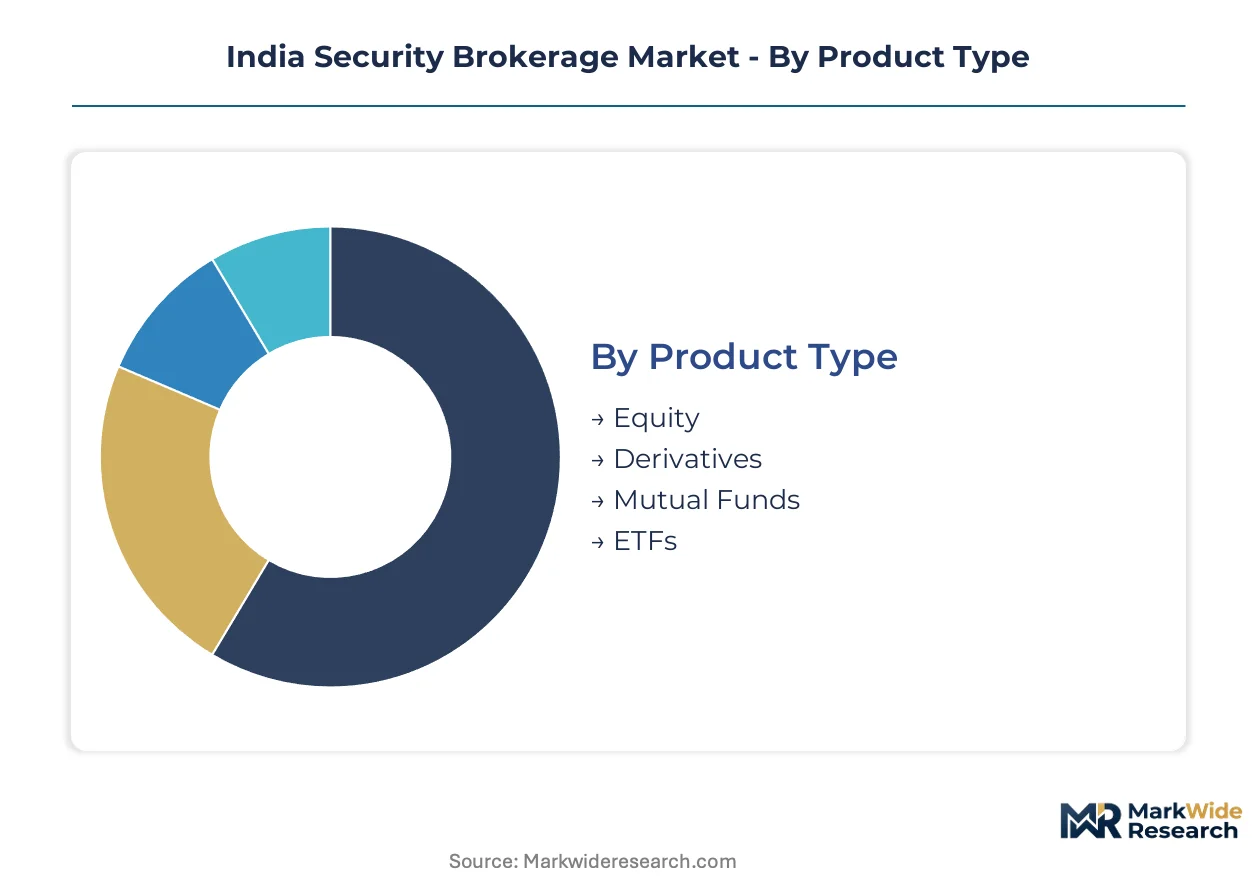
Segmentation in Indian security brokerage reveals how regulatory frameworks and technology diffusion reshape revenue concentration. SEBI's differential margin requirements and demat reforms create distinct operational economics across product and service categories.
Product Type:
SEBI mandates separate margin frameworks for cash market instruments versus leveraged derivatives, creating divergent capital intensity profiles across product lines.
- Equity:Cash market transactions settle on T+1 cycles with SEBI-mandated upfront margin collection. Delivery-based trades in Maharashtra and Gujarat concentrate among first-generation investors using mobile platforms.
- Derivatives:Futures and options contracts demand dynamic margin monitoring with mark-to-market frequency. Tier-2 city traders drive volume expansion through fixed-cost execution platforms.
- Mutual Funds:SEBI-regulated distributor commission structures govern trail revenue economics.
- ETFs:Passive index products with creation-redemption mechanisms require authorized participant relationships.
Equity handles the majority of throughput; derivatives is the fastest mover on share.
Client Type:
Cost-to-serve ratios vary by an order of magnitude between mass retail and institutional mandates, dictating platform architecture investments.
- Retail Investors:Price-sensitive participants with sub-Rs 10 lakh portfolios dominate discount brokerage adoption. Simplified KYC protocols and mobile-first onboarding reduce acquisition friction in Surat and Indore.
- Institutional Investors:Asset managers and foreign portfolio investors require FIX protocol connectivity and direct market access infrastructure. SEBI's FPI registration reforms shape custody and settlement workflows.
- High Net Worth Individuals:Clients with Rs 5 crore-plus investable assets generate cross-selling opportunities across structured products and tax planning.
- Corporates:Treasury desks utilize securities lending and repo markets for liquidity management.
Retail investors handle the majority of throughput; high net worth individuals are expanding most quickly on revenue contribution.
Service Type:
Margin compression in execution-only services forces hybrid models that blend automation with relationship coverage.
- Full-Service Brokerage:Integrated research, advisory, and banking distribution justify premium fee structures. Branch networks in tier-1 cities maintain relevance for complex product distribution.
- Discount Brokerage:Flat-fee pricing and proprietary platforms capture price-sensitive derivatives traders. Co-located servers and low-latency routing infrastructure differentiate execution quality.
- Robo-Advisory:Algorithmic portfolio construction targets mass-affluent demographics with sub-Rs 50 lakh assets.
- Wealth Management:Dedicated relationship coverage serves ultra-high-net-worth families across multi-generational planning.
Discount brokerage handles the majority of throughput; robo-advisory is climbing the fastest on user acquisition.
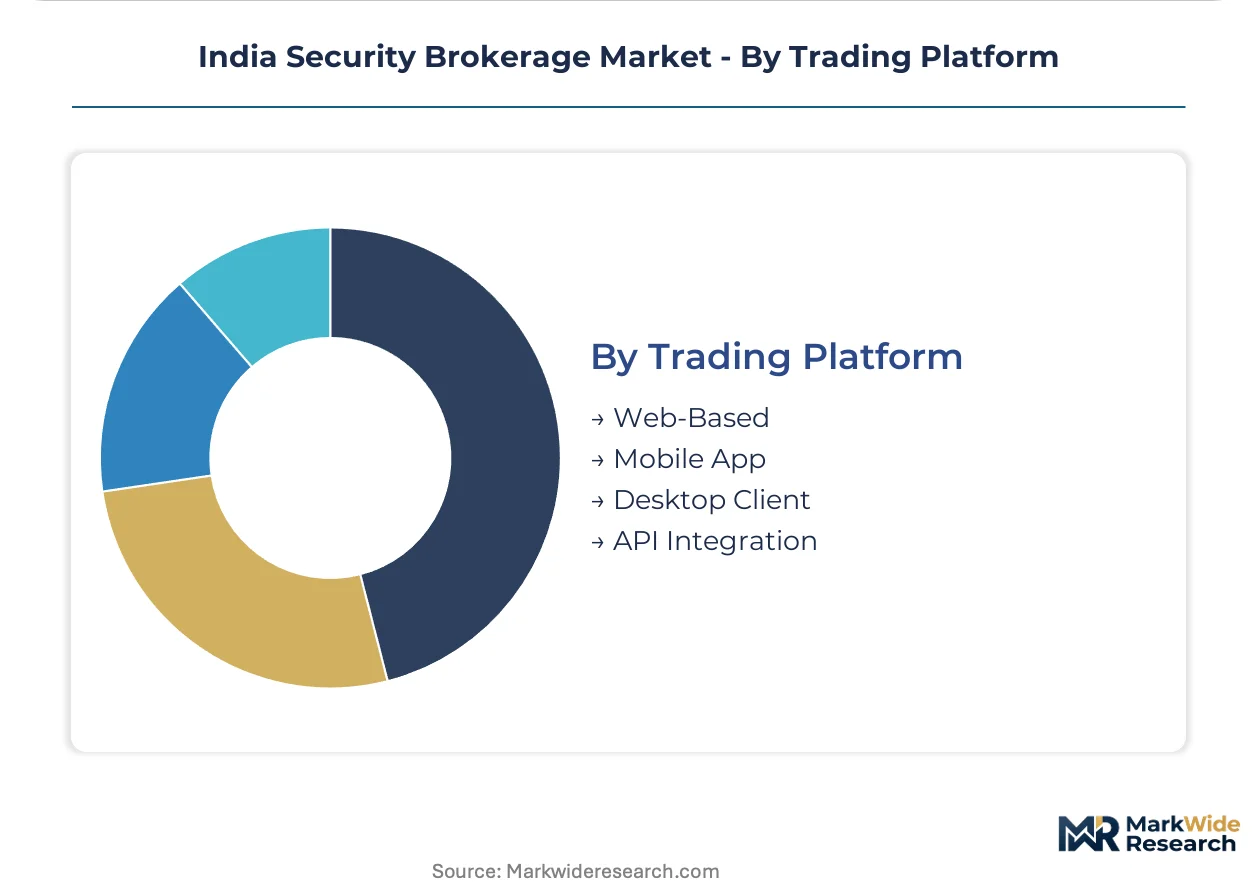
Trading Platform:
Device preference correlates directly with client age cohort and derivatives participation intensity.
- Web-Based:Browser-accessible interfaces retain utility for research-heavy equity investors. SEBI-mandated disclosure pop-ups and risk profiling integrate into onboarding flows.
- Mobile App:Native applications dominate session frequency among derivatives traders in Gujarat. Biometric authentication and UPI fund transfers compress transaction friction.
- Desktop Client:Installable software persists among active traders requiring advanced charting and algorithmic execution.
- API Integration:Programmatic access enables systematic strategies and third-party developer ecosystems.
Mobile app handles the majority of throughput; API integration is gaining share fastest among institutional workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports brokerage technology infrastructure and execution platforms to Southeast Asian markets including Singapore and Indonesia. Cross-border capital flows through Mumbai's financial district anchor the domestic market's international connectivity.
Maharashtra
Mumbai's BSE and NSE headquarters concentrate institutional trading infrastructure and clearing operations. SEBI's T+1 settlement mandate drives liquidity management investments among brokers headquartered in the state. The Mumbai-Pune corridor hosts the highest density of discount brokerage development centers and API integration labs.
Gujarat
First-generation retail investors in Ahmedabad and Surat display the highest mobile app adoption rates for derivatives trading. RBI's digital rupee pilot programs in select Gujarat cities enable early CBDC settlement testing. The Surat-Vadodara industrial belt generates significant commodity derivatives hedging demand from textile and diamond polishing clusters.
Karnataka
Bengaluru's technology workforce supplies quantitative risk modeling talent to algorithmic trading platforms. SEBI's demat account reforms reduce onboarding friction for IT professionals entering equity markets. The city's fintech ecosystem produces robo-advisory startups targeting mass-affluent software employees with sub-Rs 50 lakh portfolios.
Tamil Nadu
Coimbatore's manufacturing base creates corporate treasury demand for securities lending and repo markets. SEBI's margin norm tightening compresses commission structures for traditional brokers serving the region. Chennai's financial district anchors south Indian institutional custody and foreign portfolio investor servicing operations.
Delhi-NCR
National capital region brokers serve government sector employees through hybrid advisory models blending relationship managers with automated tools. SEBI's investor grievance redressal mechanisms receive concentrated regulatory filings from this jurisdiction. Gurugram's startup ecosystem incubates API-first brokerage platforms targeting tier-2 city expansion.
India Security Brokerage Market Competitive Landscape
Listed leaders compete with private specialists across technology platform ownership and capital market access. The market consolidates around bank-affiliated full-service networks and independent discount platforms with proprietary infrastructure. Three archetypes dominate: bank-owned integrated brokers, pure-play discount operators, and hybrid robo-advisory platforms. Competitive moves center on API ecosystem development and tier-2 city branch rationalization.
Within the discount brokerage archetype, Zerodha and Upstox exemplify technology-first positioning through proprietary mobile platforms. ICICI Direct and HDFC Securities occupy positions bridging full-service research distribution with digital execution capabilities. Kotak Securities represents the bank-owned model with integrated lending and securities operations under RBI firewall provisions.
| Leading Market Players |
|---|
| ICICI Direct |
| HDFC Securities |
| Zerodha |
| SBI Securities |
| Motilal Oswal |
| Angel One |
| Kotak Securities |
| Dhan |
| Upstox |
| Others |
Pricing and Supply Chain Analysis
T+1 settlement cycles compress working capital to 24-hour liquidity windows, concentrating pricing power among brokers with deep treasury operations and SEBI-mandated net-worth buffers. This inventory velocity differential separates discount platforms with proprietary clearing infrastructure from full-service incumbents carrying legacy branch cost structures.
Pricing Analysis
Platform-generation pricing gaps separate API-native brokers from web-first incumbents and branch-dependent legacy operators. Discount brokerage runs on fixed-fee transactional models with zero-commission equity delivery, while full-service players command premium spreads through bundled research and advisory. SEBI's margin norm tightening intensifies cost compression in derivatives execution, where price-sensitive retail traders in Gujarat and Maharashtra drive volume. First-generation investors exhibit highest price sensitivity, gravitating toward flat-fee structures; high-net-worth segments remain least sensitive, absorbing bundled fees for tax planning and structured products.
Supply Chain Analysis
Inbound technology costs from Singapore and Indonesia shape platform development economics for Indian brokerage infrastructure. Proprietary trading engines draw from cloud compute clusters in Mumbai, Bengaluru development centers, and co-located servers at BSE-NSE facilities. Single-source vulnerability concentrates in clearing corporation dependencies, where NSE Clearing and BSE's Indian Clearing Corporation control settlement rails. Distribution runs through mobile app stores, UPI payment rails, and parent bank branch networks for affiliated brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
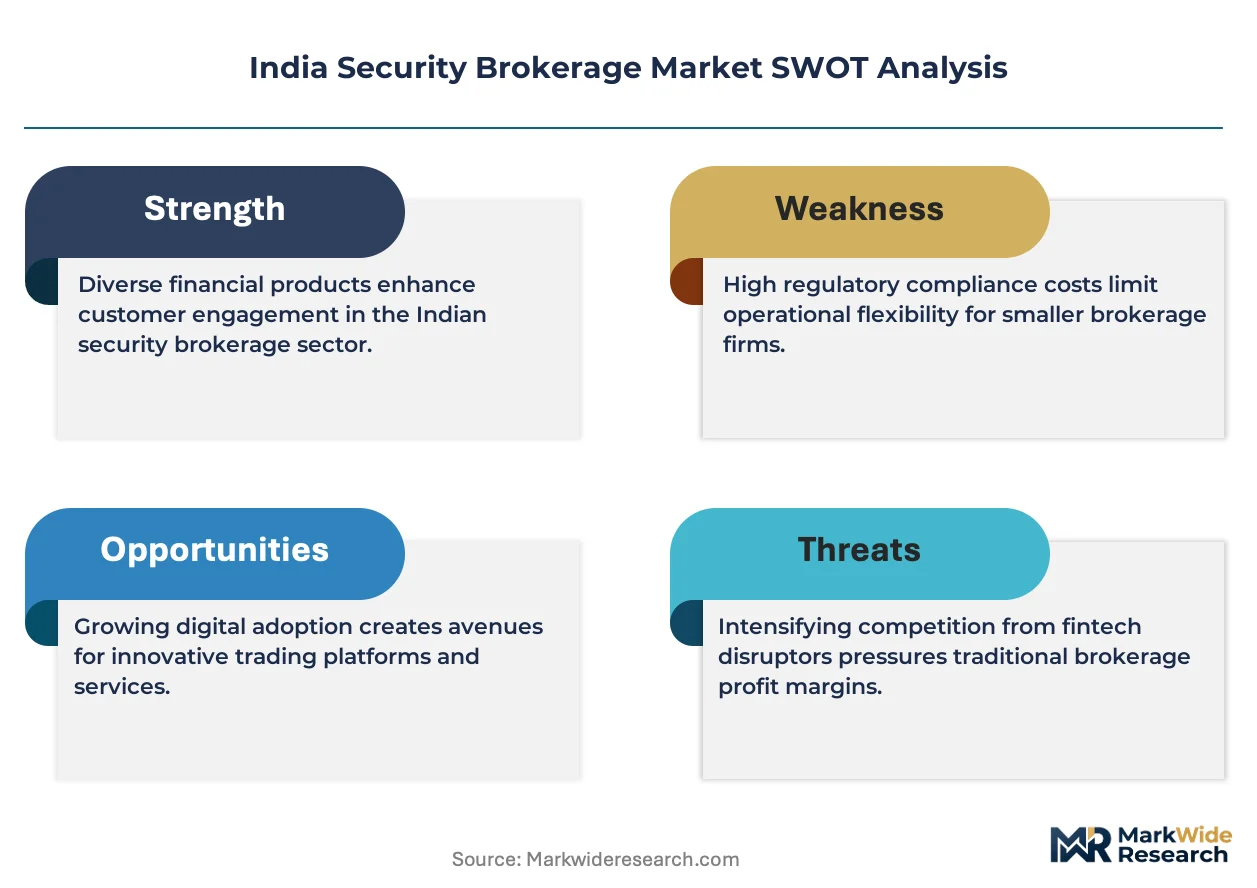
The India Security Brokerage Market functions as a regulatory-moat business where SEBI licensing requirements and net-worth mandates create entrenched barriers. Switching costs for retail investors—rooted in KYC friction and demat account portability limits—cement incumbent positions.
For Market Incumbents: Shield margin concentration by accelerating API ecosystem development before open-banking convergence commoditizes execution infrastructure. Absorb SEBI's proposed T+0 settlement liquidity demands through treasury centralization, offsetting working capital compression that threatens smaller competitors. Consolidate tier-2 city presence in Surat and Indore before hybrid robo-advisory platforms capture first-generation investor acquisition channels. For New Entrants and Emerging Players: Lead with specialized derivatives risk engines targeting quantitative retail traders underserved by generic discount platforms. The most penetrable whitespace sits in algorithmic portfolio construction for mass-affluent IT professionals in Bengaluru with sub-Rs 50 lakh assets. Pursue partnership-first go-to-market models with existing fintech wallets rather than standalone customer acquisition. For Investors and Strategic Acquirers: Carve-out targets emerge from bank-owned brokerage subsidiaries facing RBI firewall constraints on cross-selling synergies. Long-term viability favors platforms owning proprietary clearing infrastructure and API developer ecosystems over pure acquisition-dependent growth models. Monitor SEBI's digital rupee settlement pilot progress as inflection signal for infrastructure-heavy valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Development | Open banking convergence enables third-party developer marketplaces beyond transaction commissions. |
| Tier-2 City Branch Rationalization | Hybrid advisory models in Surat and Indore capture first-generation investor growth. |
| Proprietary Clearing Infrastructure | Direct NSE-BSE connectivity reduces settlement dependency and liquidity costs. |
| Robo-Advisory Platform Launch | Algorithmic construction targets mass-affluent segments with sub-Rs 50 lakh portfolios. |
| Digital Rupee Integration | RBI's CBDC pilot offers first-mover advantage in settlement infrastructure modernization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with brokerage technology heads, SEBI compliance officers, and retail trading platform product managers; and secondary validation through SEBI circular archives, RBI regulatory disclosures, BSE-NSE trading volume databases, and demat account opening statistics. Bottom-up triangulation across broker-reported active client metrics and top-down reconciliation with exchange-traded value data anchored volume and value estimates.
Across the analysis window, forecasts applied segment-specific growth drivers including derivatives participation intensity, mobile adoption curves in Maharashtra and Gujarat, and robo-advisory penetration rates among mass-affluent demographics. Modeled dimensions spanned service type, client tier, trading platform, and regional regulatory cluster. CAGRs derived from historical velocity patterns adjusted for SEBI reform implementation timelines and technology diffusion S-curves.
The analysis sits within stated boundaries; outcomes outside sustained retail participation growth, stable SEBI regulatory frameworks, or intact UPI payment rail functionality would require recalibration. Forecasts reflect documented assumptions regarding margin norm evolution and settlement cycle progression. Specific risk factors include T+0 settlement liquidity shocks, quantitative talent pipeline constraints, and bank-owned broker firewall tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Germany E-Brokerage Market
Financial Services
Middle East Islamic Finance Market
Financial Services
Online Sports Betting Market
Financial Services
South Korea Financial Services Software Market
Financial Services
India Trade Finance Market
Financial Services
E-KYC Market
Financial Services
Multivendor ATM Software Market
Financial Services
Intermediary Service Market
Financial Services
Hyperinflation System Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Europe B2B Legal Services Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Banknote Counters Market
Financial Services
Africa Factoring Services Market
Financial Services
Canada Credit Cards Market