
 Asia-Pacific AI in Insurance Market | 2026-2036
Asia-Pacific AI in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific AI in Insurance Market Analytics
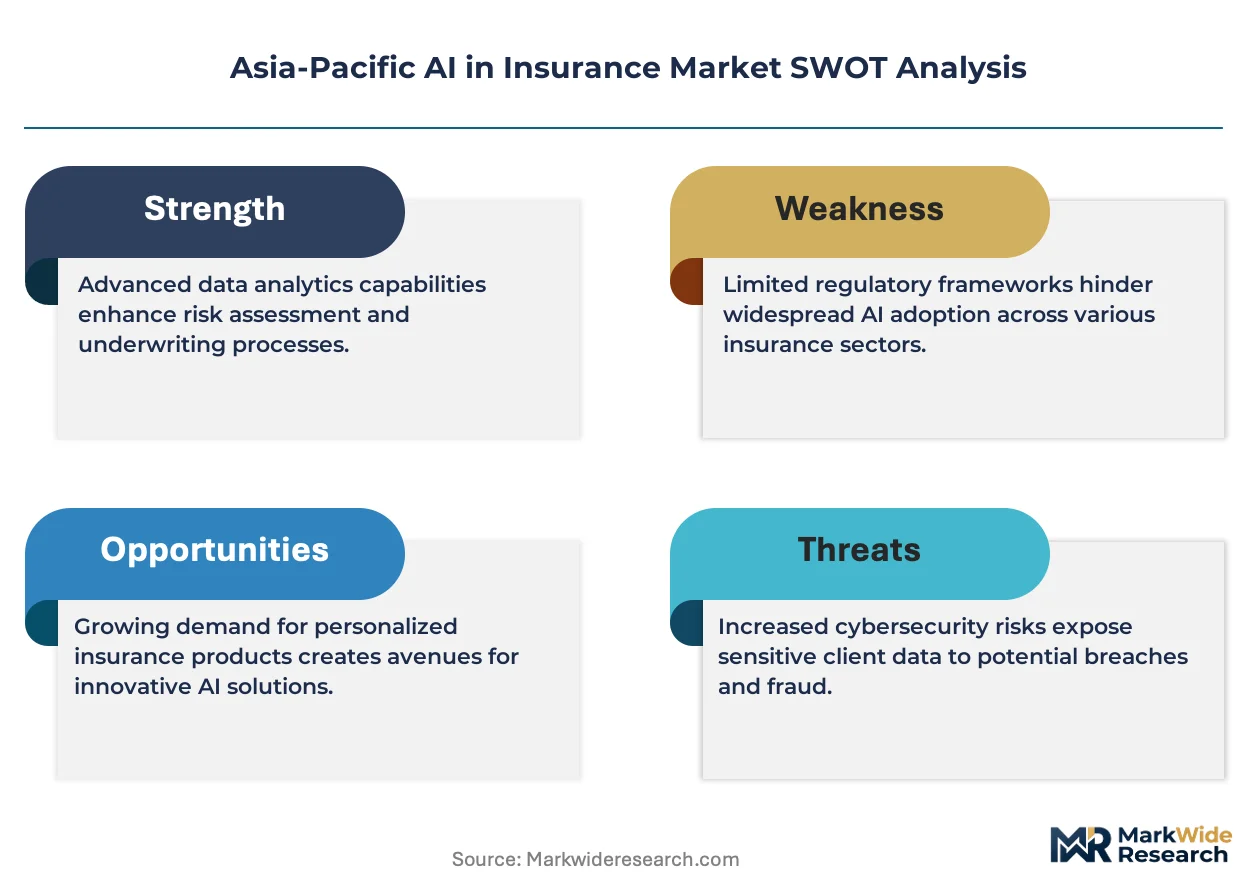
Claims automation revenue is reshaping margin distribution across the Asia-Pacific AI in Insurance landscape. SBI Life Insurance leverages machine learning for policy servicing efficiency across India's tier-two cities. ZhongAn anchors its competitive stance through fully cloud-native infrastructure that eliminates legacy system drag. IBM Corporation extends its presence via natural language processing tools tailored for multilingual customer support across Southeast Asian markets.
Asia-Pacific AI in Insurance encompasses algorithmic systems that ingest structured and unstructured data to execute underwriting decisions, detect anomalous claims patterns, and personalize policy pricing through real-time risk scoring. These platforms rely on neural network architectures processing text, image, and tabular inputs with latency thresholds below 200 milliseconds for customer-facing interactions. Fraud detection applications currently command the largest deployment share as carriers seek to reduce loss adjustment expenses. Machine learning technology leads investment flows, though predictive modeling is gaining traction among reinsurers building parametric coverage products.
India's IRDAI mandates algorithmic transparency disclosures for automated underwriting decisions, while China's NMPA-equivalent financial regulators scrutinize health data usage in AI-driven premium calculations. Japan's FSA guidelines on AI governance require insurers to maintain human oversight loops for claims above specified thresholds. Stakeholders must monitor how divergent national data localization requirements affect cross-border model training and deployment economics.
Market Dynamics
Claims automation revenue is compressing traditional loss adjustment expense structures across Asia-Pacific insurance carriers. Neural network latency requirements below 200 milliseconds for customer-facing interactions are forcing infrastructure rebuilds that favor cloud-native architectures over legacy core systems.
Growth Catalysts
- IRDAI Sandbox Framework:India's regulatory sandbox permits live testing of algorithmic underwriting models, reducing time-to-market for predictive pricing engines by bypassing traditional approval queues.
- Chronic Disease Analytics:China's health insurance sector deploys predictive models for diabetes and cardiovascular risk stratification, creating pull-through demand for real-time premium adjustment capabilities.
- Damage Assessment Automation:Computer vision pipelines for property claim verification are accelerating adoption among Japanese carriers facing labor shortages in field inspection roles.
Market Restraints
- Data Localization Mandates:Divergent national requirements for model training data storage fragment cross-border deployment economics and inflate redundant infrastructure spend.
- Human Oversight Thresholds:Japan's FSA guidelines mandate human-in-the-loop review for claims above specified monetary thresholds, capping full automation penetration in high-value segments.
- Algorithmic Transparency Burden:India's IRDAI disclosure requirements for automated underwriting decisions increase compliance documentation costs and slow model iteration cycles.
Strategic Opportunities
- Tier-Two City Penetration:India's underserved urban centers present white space for AI-enabled policy servicing at cost points unreachable through traditional agent networks.
- Parametric Reinsurance Convergence:Predictive modeling paired with satellite imagery creates new product categories for climate-linked coverage in Southeast Asian agricultural portfolios.
- Multilingual NLP Deployment:Natural language processing tools tailored for mixed-language customer support unlock efficiency gains in Singapore and Malaysia's linguistically diverse markets.
Industry Challenges
- Actuarial-AI Skill Gap:Scarce talent pools combining traditional reserving expertise with neural network architecture design constrain carrier internal build capabilities.
- Core System Integration Friction:Legacy policy administration platforms require expensive API middleware to feed real-time data into machine learning inference pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific AI in Insurance Market |
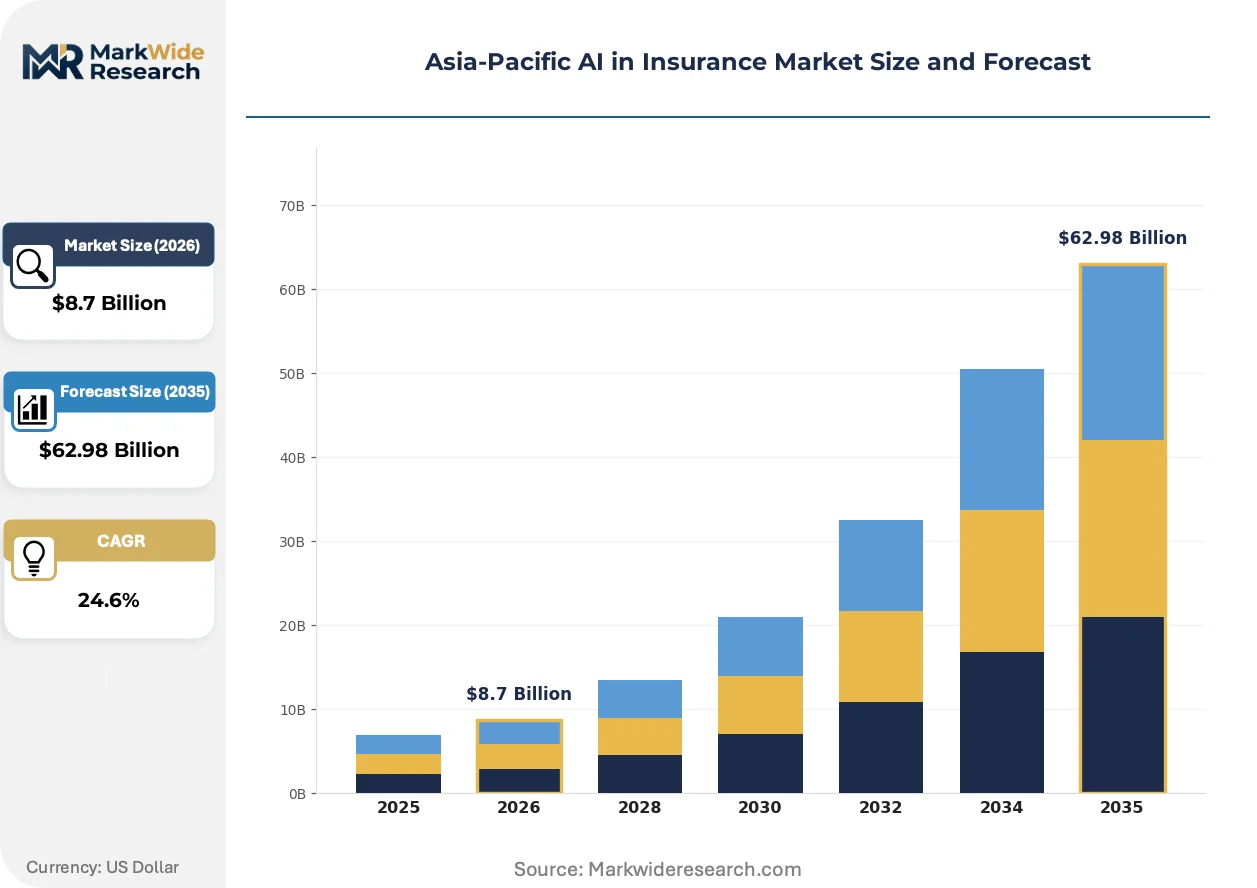
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Claim Processing, Underwriting, Customer Support Technology: Machine Learning, Natural Language Processing, Data Analytics, Predictive Modeling End User: Life Insurance, Property Insurance, Health Insurance, Auto Insurance Deployment: Cloud, On-Premise, Hybrid, Other |
| Companies Covered | SBI Life Insurance, Tractable, ZhongAn, Slice Labs, Shift Technology, AIA Group, Chubb Insurance Malaysia, IBM Corporation, QBE Insurance Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific AI in Insurance Market Evolving Landscape
Real-time risk scoring architectures are compressing policy lifecycle timelines from weeks to minutes. Carriers are rebuilding technology stacks around sub-200-millisecond inference requirements that prioritize speed over historical data depth.
Transformer-based natural language processing is rendering obsolete rule-based chatbot systems that dominated first-generation customer service automation. Southeast Asian carriers adopting multilingual NLP engines report query resolution rates climbing while human escalation volumes compress. The structural consequence is a shift in technology procurement criteria from accuracy benchmarks toward latency and language coverage specifications.
China's NMPA-equivalent financial regulators are intensifying scrutiny of health data usage in AI-driven premium calculations. This regulatory pressure is forcing carriers to segregate training data environments and adopt differential privacy techniques that add computational overhead. Health insurers in Shanghai and Beijing are responding by redirecting R&D spend toward federated learning architectures that minimize raw data movement.
Corporate risk managers are unbundling traditional broker relationships in favor of direct API connections to algorithmic underwriting platforms. This channel disintermediation is most visible among Australian mid-market enterprises seeking instantaneous certificate issuance for contractual compliance. The shift pressures incumbent distribution networks to develop white-label technology offerings or cede premium flow to direct-to-platform competitors.
Asia-Pacific AI in Insurance Market Segmentation
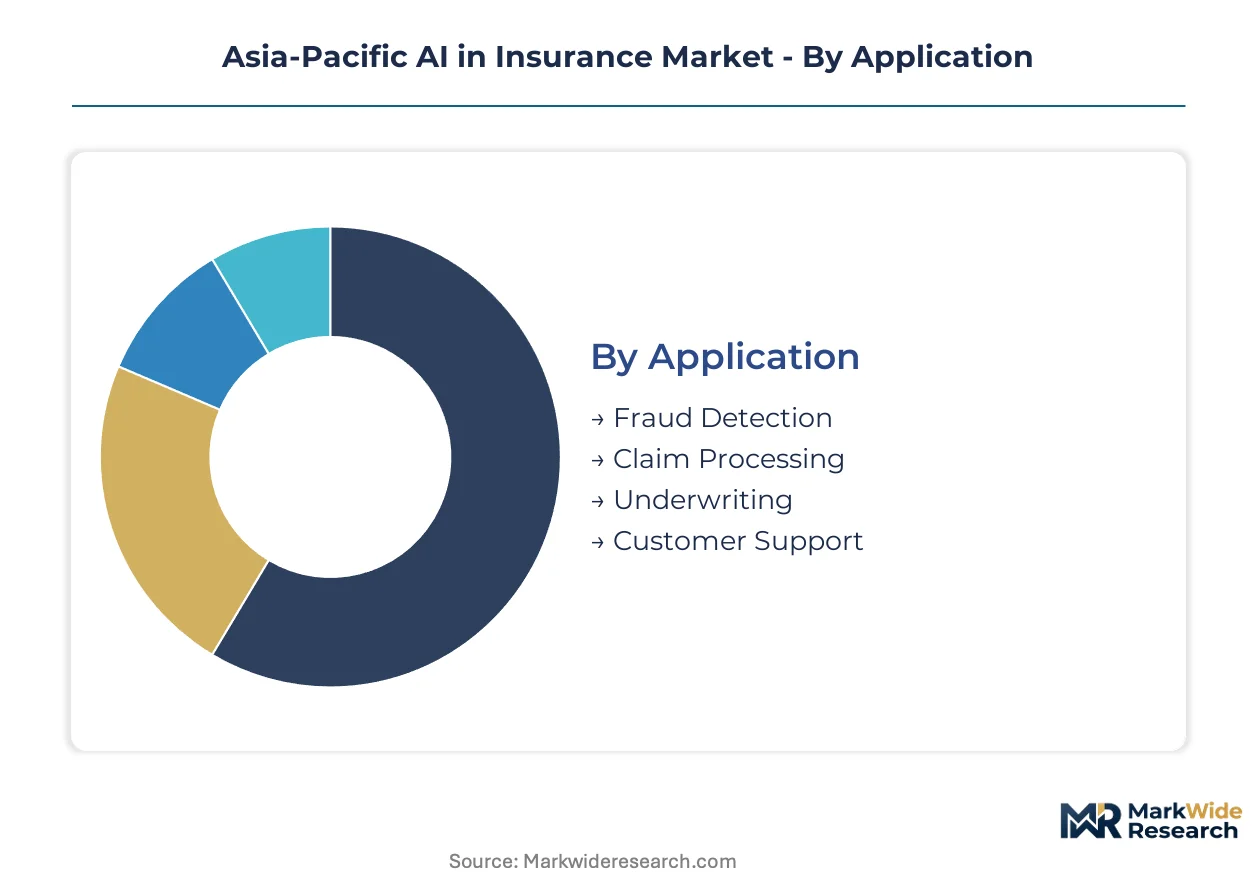
Segmentation in the Asia-Pacific AI in Insurance market reveals how technology investment priorities diverge across risk management workflows. Carriers allocate AI budgets based on regulatory pressure points and legacy system constraints rather than uniform technology adoption curves.
Application:
After-sales-service intensity varies sharply across insurance AI applications, with claims touchpoints demanding continuous model retraining and human escalation protocols.
- Fraud Detection:Neural network architectures process structured claims data and unstructured documents to flag anomalous patterns in real time. Japanese property carriers deploy computer vision pipelines to verify damage photographs, reducing field inspection labor requirements amid demographic contraction.
- Claim Processing:Automated workflows ingest first notice of loss data, route documents through extraction engines, and generate reserve recommendations with sub-200-millisecond latency thresholds. China's health insurers prioritize this segment to manage chronic disease claim volumes in tier-one hospital networks.
- Underwriting:Algorithmic risk scoring engines evaluate applicant data against predictive mortality and morbidity models.
- Customer Support:Conversational AI handles policy inquiries and premium payment assistance across multilingual Southeast Asian markets.
Fraud Detection holds the largest share; momentum sits with Claim Processing.
Technology:
Cost tier stratification in technology procurement separates cloud-native carriers from legacy-dependent competitors facing infrastructure rebuild expenses.
- Machine Learning:Supervised and unsupervised learning algorithms power underwriting decisions, claims triage, and risk scoring with inference latency requirements below 200 milliseconds. Indian life insurers leverage ML for policy servicing automation across tier-two cities where agent networks prove economically unviable.
- Natural Language Processing:Transformer-based models parse policy documents, customer correspondence, and regulatory filings across Chinese, Japanese, Hindi, and Southeast Asian languages. Singaporean carriers deploy multilingual NLP to reduce human escalation volumes in mixed-language customer bases.
- Data Analytics:Descriptive and diagnostic tools aggregate historical claims experience for actuarial reserving and product development.
- Predictive Modeling:Parametric risk engines combine satellite imagery with climate data for agricultural and catastrophe reinsurance applications.
Machine Learning dominates current investment; Predictive Modeling is climbing the fastest as reinsurers build climate-linked coverage products.
End User:
Application intensity maps directly to data availability and regulatory clarity across insurance lines.
- Health Insurance:Predictive analytics stratify chronic disease risk and enable real-time premium adjustments based on wearable device feeds. Chinese carriers face NMPA-equivalent scrutiny over health data usage, forcing differential privacy and federated learning investments.
- Property Insurance:Computer vision automates damage assessment from satellite and drone imagery. Japanese carriers accelerate adoption to offset field inspector shortages.
- Life Insurance:Algorithmic underwriting evaluates mortality risk from electronic health records and behavioral data.
- Auto Insurance:Telematics integration enables usage-based pricing and instantaneous claim initiation from connected vehicles.
Health Insurance captures the largest deployment share; Property Insurance is expanding most quickly on damage assessment automation.
Deployment:
Volume concentration in cloud deployment reflects carrier preferences for elastic compute capacity and reduced capital expenditure.
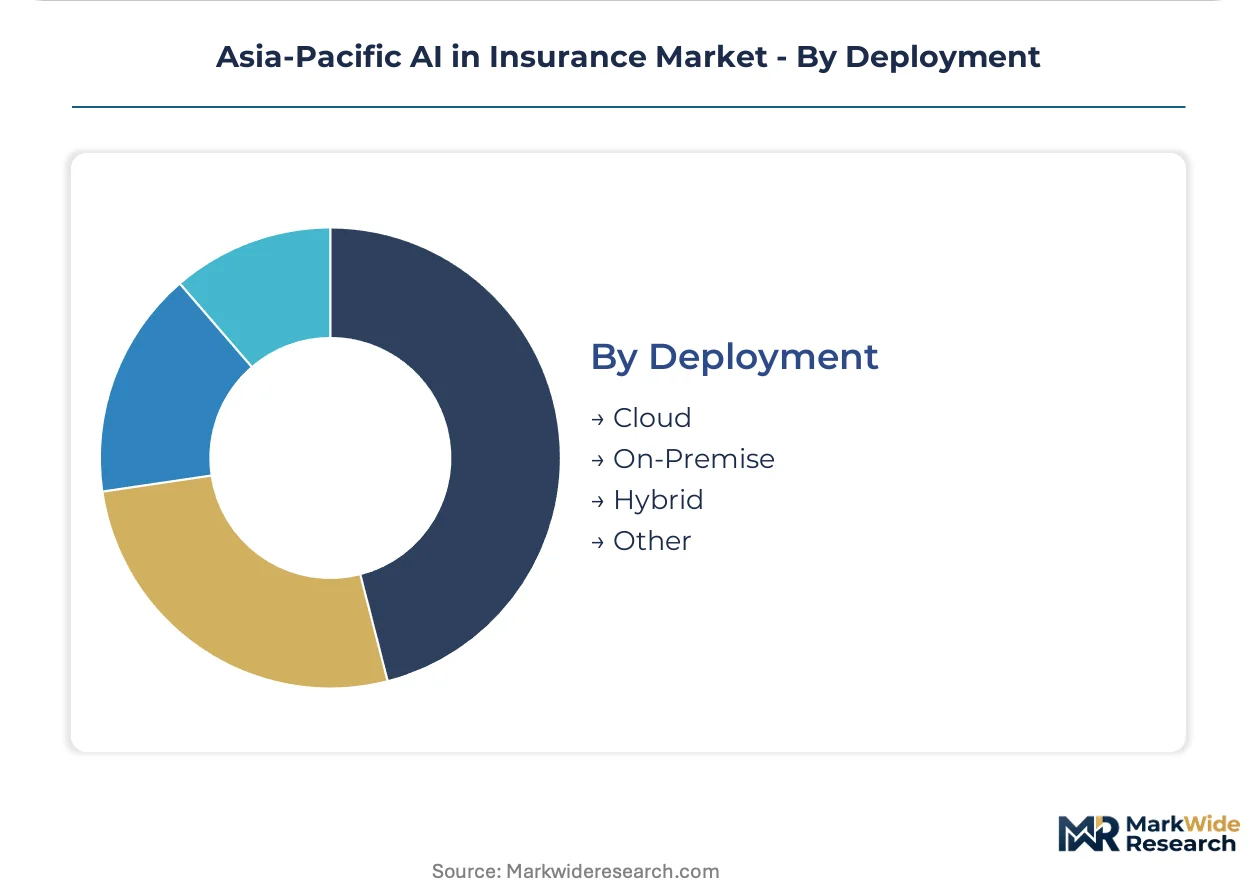
- Cloud:Fully managed infrastructure eliminates legacy system drag and supports auto-scaling during catastrophe event surges. ZhongAn operates cloud-native architecture enabling rapid product iteration without core system constraints.
- Hybrid:Segregated environments keep sensitive training data on-premise while pushing inference workloads to cloud regions. Indian carriers adopt hybrid models to satisfy IRDAI data localization requirements without sacrificing computational flexibility.
- On-Premise:Dedicated hardware supports carriers with stringent data sovereignty mandates or legacy integration dependencies.
- Other:Edge deployment and sovereign cloud variants address specialized latency or jurisdictional requirements.
Cloud holds the dominant position; Hybrid is gaining share fastest on regulatory fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific AI in Insurance landscape. Chinese carriers prioritize predictive health analytics for chronic disease management, while Japanese insurers emphasize computer vision for property damage assessment amid labor shortages. Indian markets concentrate on algorithmic underwriting for underserved tier-two cities.
China
Health insurance carriers deploy predictive analytics for diabetes and cardiovascular risk stratification, creating demand for real-time premium adjustment capabilities. The country's financial regulators scrutinize health data usage in AI-driven premium calculations, forcing adoption of differential privacy and federated learning architectures. Shanghai and Beijing host concentrated R&D activity as carriers segregate training data environments to satisfy compliance requirements.
Japan
Property insurers accelerate computer vision adoption for damage assessment workflows as demographic contraction eliminates field inspector availability. The FSA mandates human oversight loops for claims above specified monetary thresholds, capping full automation penetration in high-value segments. Tokyo-based carriers lead deployment of neural network architectures processing satellite and drone imagery with sub-200-millisecond latency requirements.
India
Life insurers leverage machine learning for policy servicing automation across tier-two cities where traditional agent networks prove economically unviable. IRDAI mandates algorithmic transparency disclosures for automated underwriting decisions and permits live testing through its regulatory sandbox framework. Mumbai and Bangalore concentrate InsurTech development activity as carriers bypass traditional approval queues for predictive pricing engines.
Singapore
Multilingual natural language processing deployment unlocks efficiency gains in linguistically diverse customer support operations across Southeast Asian markets. The Monetary Authority of Singapore maintains oversight of AI governance frameworks for financial services, requiring explainable model outputs for customer-facing decisions. The city-state's technology clusters attract carriers seeking hub-and-spoke deployment models for regional NLP infrastructure.
Australia
Mid-market enterprises seek direct API connections to algorithmic underwriting platforms for instantaneous certificate issuance, disintermediating traditional broker relationships. The Australian Prudential Regulation Authority supervises insurer AI risk management practices, emphasizing operational resilience for automated decision systems. Sydney and Melbourne concentrate corporate risk management demand as buyers unbundle traditional distribution channels.
Asia-Pacific AI in Insurance Market Competitive Landscape
Capability concentration sits with cloud-native specialists; scale advantage sits with incumbent carriers rebuilding legacy infrastructure. The market structures around three tiers: technology vendors supplying AI infrastructure, InsurTechs with purpose-built platforms, and traditional carriers modernizing core systems. Competitive moves center on strategic partnerships bridging capability gaps and geographic expansion capturing regulatory sandbox opportunities.
Within the cloud-native tier, ZhongAn exemplifies fully cloud-native architecture eliminating legacy system drag, while SBI Life Insurance occupies a position among incumbent carriers leveraging machine learning for operational efficiency. IBM Corporation represents the technology vendor archetype extending presence through natural language processing tools. These three anchors illustrate the competitive spectrum from infrastructure providers to algorithmic underwriting platforms to modernized traditional carriers.
| Leading Market Players |
|---|
| SBI Life Insurance |
| Tractable |
| ZhongAn |
| Slice Labs |
| Shift Technology |
| AIA Group |
| Chubb Insurance Malaysia |
| IBM Corporation |
| QBE Insurance Group |
| Others |
Value Network & Pricing Analysis
Regulatory fragmentation across data localization mandates determines both pricing tier spreads and supply chain shape in the Asia-Pacific AI in Insurance market. India's IRDAI disclosure requirements and China's NMPA-equivalent scrutiny force carriers to maintain redundant infrastructure environments, compressing margins on standardized deployments while premium pricing attaches to compliant hybrid architectures.
Pricing Analysis
Long-term SaaS subscription contracts dominate enterprise procurement, with annual licensing anchored to inference volume tiers rather than perpetual seat counts. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native carriers with sub-200-millisecond latency guarantees from legacy-dependent competitors facing middleware integration surcharges. Price differentiation hinges on multilingual NLP coverage breadth and federated learning readiness for health data compliance. Cost compression in standard-tier deployments is intensifying because Japanese carriers demand human-in-the-loop overrides that inflate per-transaction processing costs. Mid-market insurers in Southeast Asia exhibit highest price sensitivity; reinsurers building parametric climate products show least.
Supply Chain Analysis
Upstream GPU and specialized AI accelerator feedstock concentrates in Taiwan, South Korea, and USA foundry output, with Chinese domestic production expanding for non-advanced node inference chips. Cloud infrastructure providers draw from NVIDIA data center silicon, proprietary TPU architectures, and programmable FPGA arrays for low-latency claims processing pipelines. Single-source vulnerability sits with Taiwan semiconductor fabrication for training-grade GPUs, exposing carriers to allocation rationing during demand surges. Distribution runs through hyperscaler marketplaces and direct API licensing to tier-one carriers, with regional system integrators handling hybrid deployment middleware for compliance-bound insurers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in tier-two city penetration and parametric reinsurance convergence, as algorithmic underwriting demand splinters across regulatory jurisdictions and legacy system constraints create defendable niches.
For Market Incumbents: Build regulatory compliance moats through federated learning investments that satisfy China's health data segregation mandates and India's algorithmic transparency requirements. Acquire cloud-native engineering talent in Bangalore and Singapore to accelerate core system API modernization before InsurTech competitors capture mid-market share. Prioritize human-in-the-loop workflow design for Japanese FSA threshold compliance, converting regulatory burden into switching cost stickiness. For New Entrants and Emerging Players: Tier-two Indian cities with sub-scale agent economics represent the most penetrable entry point for AI-enabled policy servicing platforms. Southeast Asian agricultural parametric coverage, pairing satellite imagery with climate predictive models, offers white-space product development with limited incumbent digital presence. Direct API underwriting relationships with Australian mid-market enterprises bypass broker disintermediation risks while establishing referenceable deployment velocity. For Investors and Strategic Acquirers: IRDAI sandbox expansion and NMPA-equivalent federated learning mandates reshape the acquisition landscape toward compliance-embedded technology stacks. Long-term viability across the analysis window favors targets with differentiated privacy-preserving architectures and established carrier pilot programs. Watch carrier R&D redirection toward edge deployment for latency-critical claims processing as inflection signal for infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Architecture Development | Enables health insurers to satisfy Chinese and Indian data localization without raw data movement. |
| Multilingual NLP Platform Integration | Captures efficiency gains in Singapore and Malaysia's linguistically diverse customer support operations. |
| Computer Vision Damage Assessment Partnership | Addresses Japanese field inspector shortages through satellite and drone imagery automation pipelines. |
| Parametric Reinsurance Product Launch | Creates climate-linked coverage categories for Southeast Asian agricultural portfolios using satellite data. |
| Regulatory Sandbox Market Entry | Accelerates time-to-market for predictive pricing engines via India's IRDAI live testing framework. |
Research Methodology
A spread of perspectives from chief underwriting officers, cloud infrastructure procurement leads, regulatory compliance directors, and InsurTech product managers converged on the working assumptions shaping this analysis. Primary interview data combined with secondary validation from IRDAI sandbox disclosures, Japanese FSA guidance documents, Chinese regulatory circulars on health data usage, and hyperscaler AI service expansion announcements. Bottom-up carrier deployment surveys triangulated against top-down technology vendor revenue segmentation across machine learning, natural language processing, and predictive modeling solution categories.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning application intensity, technology cost tier, end-use regulatory clarity, and deployment model elasticity. CAGRs derived from carrier AI budget allocation trajectories, technology procurement pipeline visibility, and reinsurer parametric product development timelines. Inference latency requirements below 200 milliseconds and federated learning architecture adoption curves served as industry-specific forecast sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in regional cloud infrastructure capex cycles or semiconductor export control expansion would shift the trajectory. Forecasts reflect documented assumptions on regulatory sandbox permanence and carrier legacy system replacement urgency. Cross-checking against hyperscaler AI service revenue disclosures and carrier technology spend surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Health Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
Financial Guarantee Market
Insurance
Cannabis Crop Insurance Market
Insurance
Crime Insurance Market
Insurance
China Online Insurance Market
Insurance
United States Insurance Brokerage Market
Insurance
Marine Freight Insurance Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
United States Dental Insurance Market
Insurance
Logistics Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
Business Travel Insurance Market
Insurance
Denmark Property and Casualty Insurance Market