
 Construction Equipment Finance Market | 2026-2036
Construction Equipment Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Equipment Finance Market Insights
Embedded telematics and IoT-enabled asset monitoring is reconfiguring how lenders underwrite construction equipment risk, shifting from collateral-based to usage-based credit models. Caterpillar leverages its captive finance arm to control the full equipment lifecycle from sale to resale. Wells Fargo anchors its construction lending portfolio through long-standing relationships with regional contractors and infrastructure funds. Komatsu differentiates by integrating its KOMTRAX platform with financing terms that adjust to machine utilization rates.
Construction equipment finance encompasses the structured lending, leasing, and rental mechanisms that enable acquisition of heavy machinery with typical collateral values exceeding $500,000 and operational lifespans of 10,000 to 20,000 hours. Its primary commercial purpose is to convert capital-intensive equipment purchases into predictable operating expenditures, preserving liquidity for contractors managing multi-project pipelines. Lease structures dominate the financing type dimension, as they preserve borrower credit capacity and transfer residual value risk to lessors. Earthmoving machines anchor the equipment category segment due to universal applicability across residential, commercial, and civil projects. Medium-term tenures represent the fastest-expanding loan tenure pool, matching the depreciation curves of Tier 4-final and Stage V emission-compliant engines.
EPA emission tiers and EU Green Deal machinery standards are restricting finance eligibility to compliant engine classes, redirecting capital toward newer, higher-cost equipment. SEC climate disclosure rules and Basel III capital adequacy frameworks are reshaping how banks like JPMorgan Chase and Bank of America provision for construction lending portfolios. Stakeholders must monitor whether regulatory capital requirements and emission thresholds converge to limit financing access for older equipment fleets, or whether green bond structures and sustainability-linked loans open parallel funding channels for compliant assets.
Market Dynamics
Embedded telematics infrastructure is compressing underwriting cycles from weeks to hours, forcing lenders to rebuild risk engines around real-time machine utilization data rather than static collateral appraisals.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V emission mandates:Equipment replacement cycles are shortening as non-compliant machines lose finance eligibility, accelerating turnover in earthmoving and material handling fleets.
- India's National Infrastructure Pipeline:State contractors are aggregating demand through hire purchase collectives, concentrating origination volume with captive finance arms of OEMs operating in the subcontinent.
- IoT-enabled predictive maintenance:Lenders are integrating machine health data into covenant structures, reducing default rates on high-hour assets and expanding addressable credit to second-owner operators.
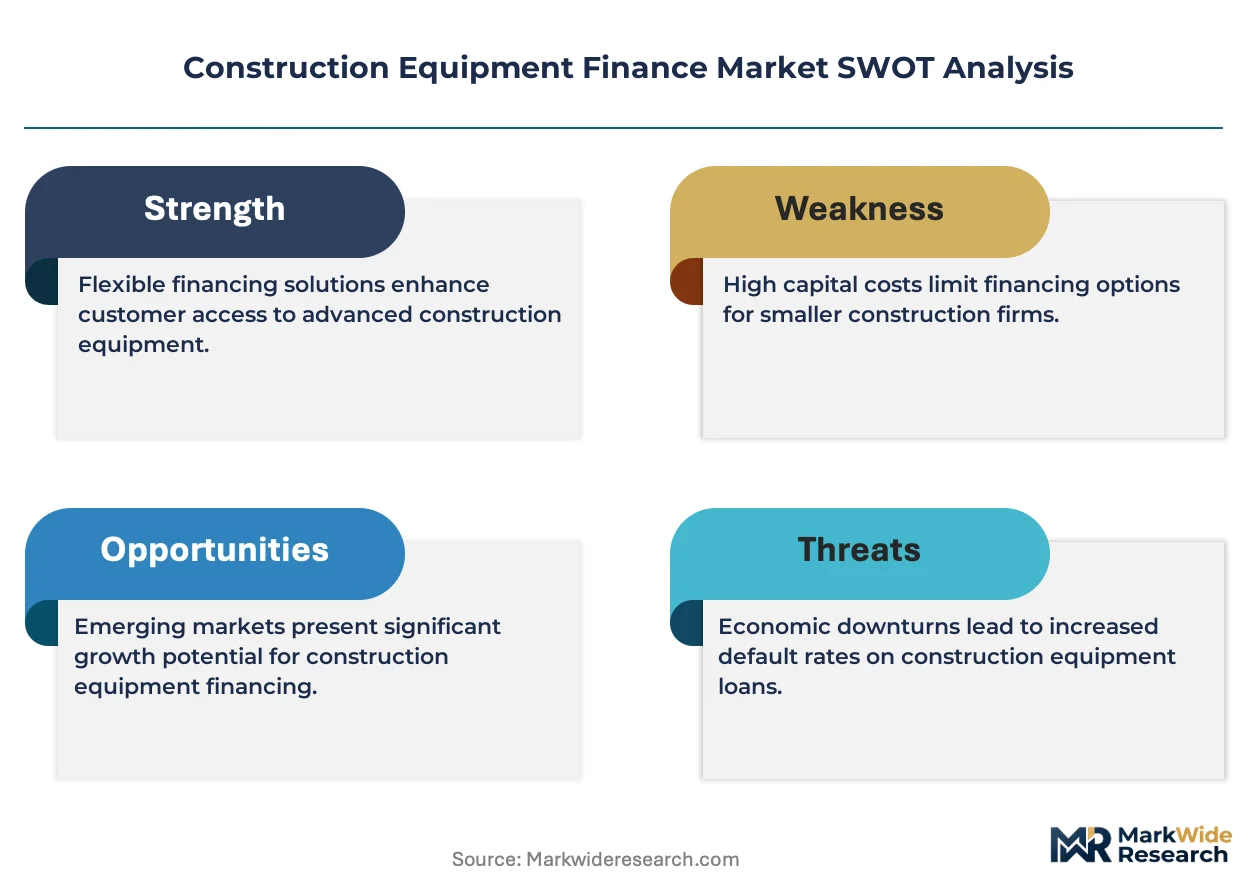
Market Restraints
- Steel and battery metal input volatility:Equipment manufacturers face margin compression from nickel and lithium carbonate price swings, forcing cost pass-throughs that inflate financed asset values.
- Residual value uncertainty for electric variants:Depreciation curves for battery-electric excavators and wheel loaders remain unproven, causing lessors to demand shorter tenures or higher security deposits.
- Basel III capital adequacy requirements:European banks are provisioning additional risk-weighted assets for construction lending, narrowing net interest margins and reducing competitive pressure on specialized equipment financiers.
Strategic Opportunities
- Secondary market auction platforms:Digital remarketing channels are capturing off-lease volume from captive finance arms, enabling independent lessors to arbitrage residual value gaps across regional markets.
- EU Green Deal sustainable finance taxonomy:Eligible low-emission equipment qualifies for preferential capital treatment under the European Investment Bank's lending frameworks, creating rate advantages for compliant fleet acquisitions.
- Telematics-finance bundling:Convergence of asset tracking hardware with usage-based payment structures is opening subscription-style contracting for mid-sized contractors previously excluded from traditional credit programs.
Industry Challenges
- Data interoperability across OEM platforms:Proprietary telematics protocols from Caterpillar, Komatsu, and Volvo Construction Equipment prevent lenders from consolidating machine performance data into unified risk scoring models.
- Tier 4 Final technician certification gaps:Aftermarket service networks lack sufficient density of trained personnel to maintain emission-compliant engines, extending downtime and impairing collateral recovery values.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Equipment Finance Market |
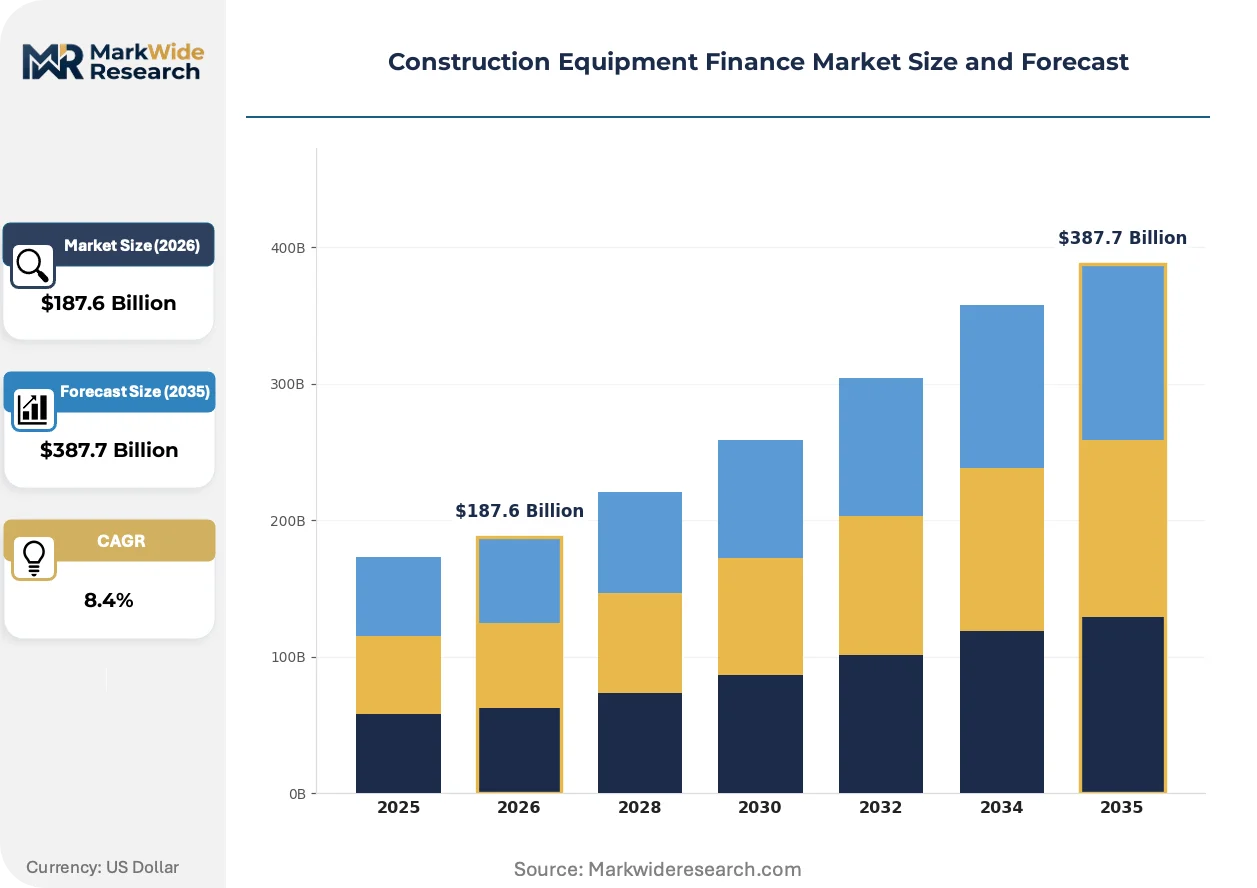
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $387.7 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Lease, Loan, Vendor Financing, Equipment Rental, Hire Purchase Equipment Category: Earthmoving Machines, Material Handling, Concrete Equipment, Compaction Equipment, Road Construction End User: Construction Firms, Mining Companies, Infrastructure Developers, Utility Providers, Quarries Loan Tenure: Short-Term, Medium-Term, Long-Term, Flexible, Balloon Payment |
| Companies Covered | Caterpillar, Deere & Company, Komatsu, AB Volvo, CNH Industrial, Wells Fargo, Bank of America, JPMorgan Chase, DLL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Equipment Finance Market Trends and Innovations
Usage-based financing models are supplanting fixed-term structures, with payment obligations tied to actual machine hours rather than calendar schedules. This shift demands real-time data infrastructure and recalibrated legal frameworks for security interest perfection.
Blockchain-based smart contracts are migrating from pilot programs to live transaction execution, automating payment releases upon verified delivery milestones. Mining contractors in Australia and civil infrastructure consortia in Canada are adopting these instruments for fleet acquisitions exceeding ten units. The technology is compressing documentation cycles and reducing escrow costs, though jurisdictional recognition of on-chain security interests remains uneven.
SEC climate disclosure rules and the EU Corporate Sustainability Reporting Directive are mandating financed equipment emissions reporting through supply chains. Contractors bidding on federal infrastructure projects in the United States must now document Scope 3 emissions from leased machinery, favoring financiers with carbon accounting integration. European infrastructure funds are preemptively excluding non-compliant lessors from approved vendor lists.
Equipment-as-a-service contracting is displacing traditional capital expenditure approvals among mid-market contractors managing project-specific demand spikes. German and Japanese construction firms are piloting bundled offerings combining machinery, maintenance, and telematics under single per-hour rates. This procurement evolution concentrates volume with OEM captive finance arms possessing integrated service networks, marginalizing independent lessors lacking maintenance infrastructure.
Construction Equipment Finance Market Segmentation
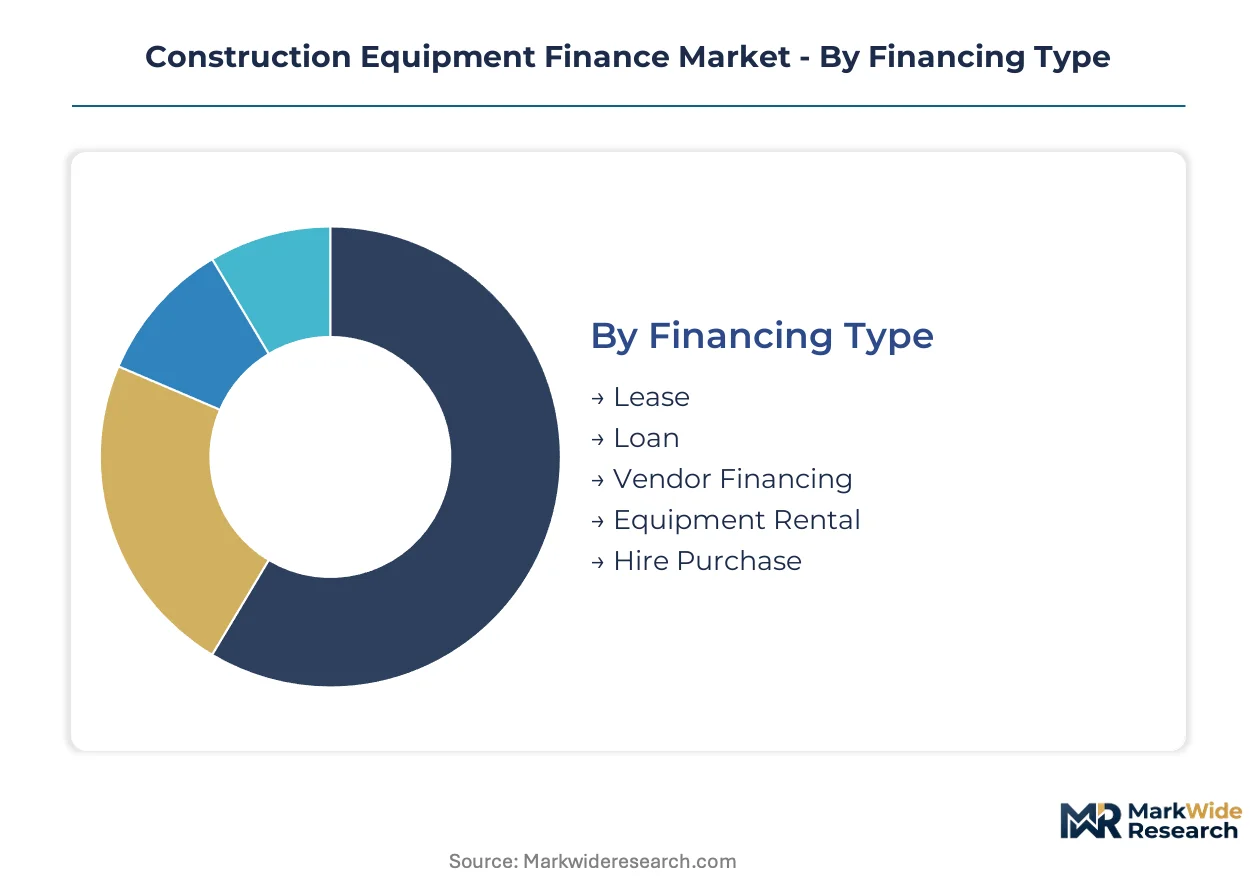
Construction equipment finance segments diverge sharply in collateral risk profiles and origination velocity. Lease structures compress underwriting cycles through residual value retention, while loan products demand extended due diligence on borrower creditworthiness. Equipment category and end-user composition directly determine portfolio concentration limits that lenders impose.
Financing Type:
Cycle times stretch from hours for standardized lease products to weeks for bespoke loan structures with complex covenant packages.
- Lease:Operating and finance lease structures dominate institutional portfolios, transferring residual value exposure to lessors while preserving contractor liquidity for project bonding capacity. Demand clusters with infrastructure developers in India executing National Infrastructure Pipeline contracts through OEM captive arms.
- Loan:Secured term loans collateralized by equipment titles require comprehensive borrower financials and project backlog verification. Regional contractors in the United States anchor volume through relationships with specialized construction lenders.
- Vendor Financing:OEM captive programs streamline origination through pre-approved credit lines tied to equipment delivery schedules.
- Equipment Rental:Short-term rental with purchase options serves project-specific demand spikes without balance sheet recognition.
- Hire Purchase:Title-retention structures concentrate in Commonwealth markets where contractors gain operational control while spreading acquisition costs across depreciation-matched schedules.
Lease dominates installed base. Hire purchase is where expansion concentrates.
Equipment Category:
Cost tiers stratify sharply, with earthmoving machines commanding collateral values exceeding material handling fleets by substantial margins.
- Earthmoving Machines:Excavators, bulldozers, and wheel loaders constitute the highest-value collateral class, with individual units frequently exceeding $500,000. Mining companies in Australia and civil contractors in Canada drive origination through fleet replacement programs tied to EPA Tier 4 Final compliance deadlines.
- Material Handling:Cranes, forklifts, and telehandlers serve vertical construction and logistics applications with faster turnover cycles. Demand is expanding most quickly in India where warehouse and port infrastructure development accelerates equipment procurement.
- Concrete Equipment:Mixer trucks, pumps, and batching plants carry specialized residual value risk tied to regional construction activity levels.
- Compaction Equipment:Rollers and plate compactors support road and site preparation work with lower per-unit financing values.
- Road Construction:Pavers, milling machines, and asphalt plants align with government infrastructure spending cycles.
Earthmoving machines anchor lender collateral pools. Material handling is gaining share fastest.
End User:
Customer type determines payment reliability and covenant structure complexity across the financing spectrum.
- Construction Firms:General and specialty contractors generate the largest origination volume through project-specific equipment needs. Medium-sized firms in Germany are piloting equipment-as-a-service bundles combining machinery, maintenance, and telematics under unified per-hour rates.
- Mining Companies:Surface and underground extraction operators demand specialized underwriting for high-utilization, severe-duty applications. Australian mining contractors are adopting blockchain-based smart contracts for fleet acquisitions exceeding ten units, automating payment releases upon verified delivery milestones.
- Infrastructure Developers:State-backed and private consortiums concentrate demand through multi-year fleet programs.
- Utility Providers:Power and telecommunications infrastructure operators require equipment financing aligned with regulatory rate-base recovery timelines.
- Quarries:Aggregate extraction operations finance crushing and screening equipment with collateral values tied to mineral reserve valuations.
Construction firms dominate origination volume. Mining companies are where premium pricing concentrates.
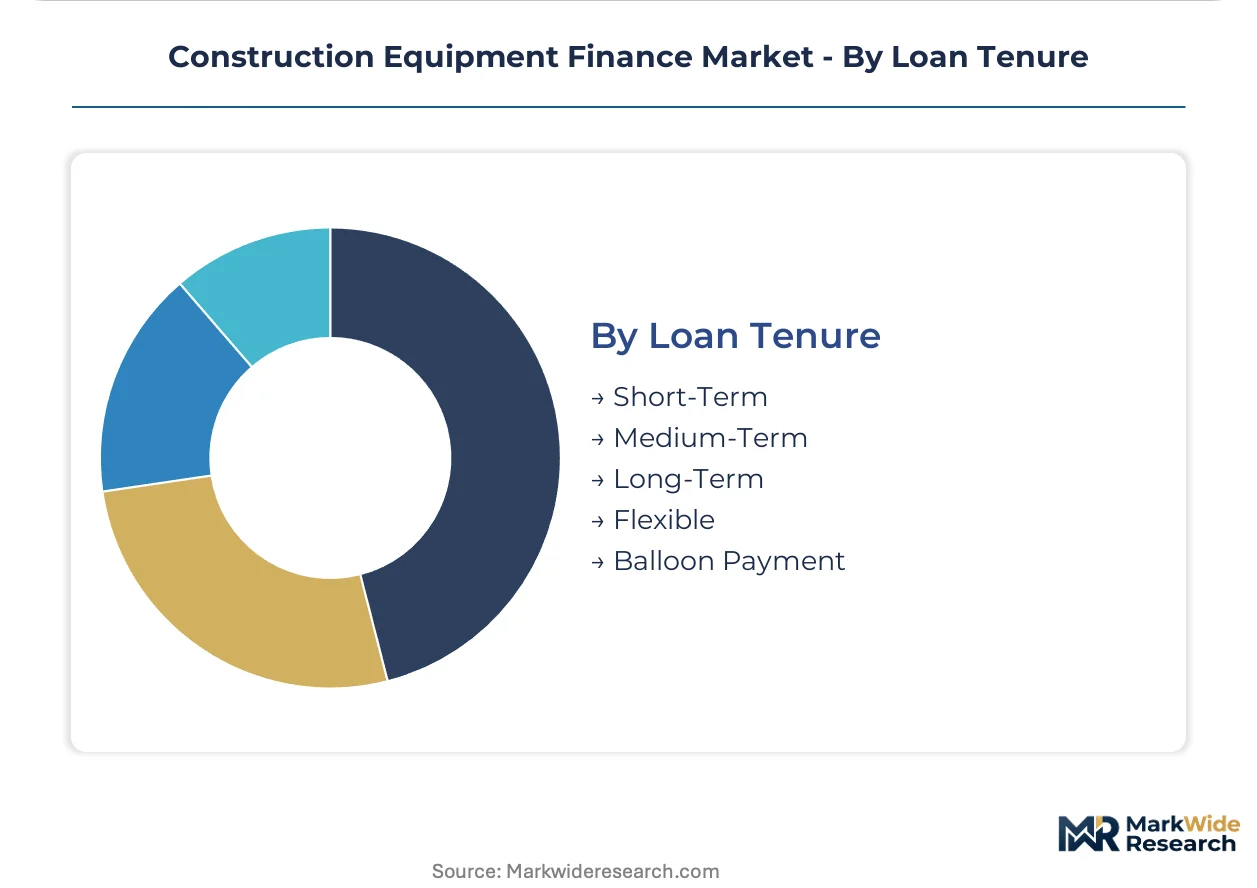
Loan Tenure:
Maturity profiles align with equipment depreciation curves and emission compliance lifecycles.
- Medium-Term:Three-to-seven year structures match Tier 4-final and Stage V engine depreciation schedules, expanding most quickly as lenders adjust to compressed replacement cycles. European banks are provisioning additional risk-weighted assets under Basel III frameworks, narrowing net interest margins.
- Short-Term:One-to-three year facilities serve seasonal contractors and project-specific acquisitions with accelerated amortization.
- Long-Term:Seven-to-ten year tenures persist for low-hour infrastructure equipment with extended operational lifespans.
- Flexible:Revolving structures with seasonal payment adjustments align with agricultural and northern climate construction patterns.
- Balloon Payment:Back-ended principal structures preserve cash flow during high-growth phases, concentrating residual risk with borrowers.
Medium-term tenures dominate new originations. Flexible structures are where product innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor bonding capacity and fleet replacement cycles concentrate demand in markets with active infrastructure pipelines and tightening emission mandates. Equipment financiers calibrate origination strategies to national regulatory deadlines and public procurement scale.
United States
Regional contractors anchor volume through relationships with specialized construction lenders and infrastructure fund commitments. EPA Tier 4 Final compliance deadlines accelerate earthmoving fleet turnover in Texas and California construction corridors. SEC climate disclosure rules now mandate Scope 3 emissions reporting from leased machinery, favoring financiers with integrated carbon accounting.
Germany
Mid-sized construction firms pilot equipment-as-a-service bundles combining machinery, maintenance, and telematics under unified per-hour rates. EU Green Deal sustainable finance taxonomy grants preferential capital treatment to low-emission equipment through European Investment Bank frameworks. Bavaria and North Rhine-Westphalia host dense OEM captive finance operations serving cross-border infrastructure consortia.
India
State contractors aggregate demand through hire purchase collectives, concentrating origination volume with captive finance arms of multinational OEMs. National Infrastructure Pipeline contracts drive earthmoving fleet procurement across Maharashtra and Gujarat. RBI provisioning norms and SEBI infrastructure investment trust regulations shape lender capital deployment timelines.
Australia
Mining contractors adopt blockchain-based smart contracts for fleet acquisitions exceeding ten units, automating payment releases upon verified delivery milestones. Surface extraction operators in Western Australia and Queensland demand specialized underwriting for high-utilization, severe-duty applications. National greenhouse gas reporting obligations extend to financed equipment emissions in extractive sectors.
China
Infrastructure developers finance compaction and road construction equipment through state-backed credit facilities aligned with provincial spending cycles. MIIT emission standards and dual carbon goals redirect capital toward newer, higher-cost compliant engine classes. Yangtze River Delta and Pearl River Delta clusters concentrate OEM captive finance origination for domestic contractors.
Construction Equipment Finance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across origination, residual value management, and service bundling. Captive finance arms of heavy equipment manufacturers command integrated data streams from proprietary telematics platforms. Independent commercial banks and specialized equipment financiers anchor regional contractor relationships through long-tenured credit programs. Dominant competitive moves include telematics-finance bundling and secondary market auction platform development.
Among OEM-anchored financiers, Caterpillar, Komatsu, and Deere & Company exemplify archetypes that control full equipment lifecycles from manufacture through resale. These entities occupy positions where embedded asset monitoring infrastructure enables usage-based credit model transitions. Wells Fargo and Bank of America represent commercial banking archetypes competing through regional contractor relationship density and infrastructure fund partnerships.
| Leading Market Players |
|---|
| Caterpillar |
| Deere & Company |
| Komatsu |
| AB Volvo |
| CNH Industrial |
| Wells Fargo |
| Bank of America |
| JPMorgan Chase |
| DLL |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese steel production compresses equipment manufacturing margins globally, forcing OEMs to absorb input volatility or pass through costs via indexed financing contracts. This utilization imbalance simultaneously pressures lenders to recalibrate collateral valuations and residual value assumptions across their construction equipment portfolios.
Pricing Analysis
Cost-plus contracts with steel price indexation dominate equipment procurement between OEMs and fleet operators. Three-tier pricing structure across premium emission-compliant, standard Tier 4-final, and economy pre-compliant tiers reflects EPA and EU Green Deal certification levels. Pricing pressure stems from nickel and lithium carbonate volatility in battery-electric variants. Mid-sized contractors exhibit highest price sensitivity, while mining operators absorb premiums for severe-duty specifications.
Supply Chain Analysis
Contract manufacturing concentrates with JCB's Indian assembly networks, Caterpillar's Mexican and Brazilian facilities, and Komatsu's Japanese and Indonesian plants. Steel plate and high-grade hydraulics draw from Chinese and South Korean mills. Single-source vulnerability persists in precision engine control modules from German and Japanese suppliers. Distribution runs through OEM captive finance arms and regional equipment dealers with service integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction equipment finance constitutes a high-growth disruption as embedded telematics and IoT-enabled asset monitoring reconfigure underwriting from collateral-based to usage-based credit models. EPA Tier 4 Final and EU Stage V emission mandates accelerate fleet replacement cycles, compressing origination windows for compliant equipment.
For Market Incumbents: Pre-empt telematics-finance bundling disruption by integrating proprietary machine utilization data into covenant structures before independent fintech platforms capture mid-market contractors. Defend position by deepening captive service network density in India and Australia, where National Infrastructure Pipeline contracts and mining fleet programs concentrate origination volume. Invest in technician certification programs for Tier 4 Final engine maintenance to protect collateral recovery values. For New Entrants and Emerging Players: Pursue equipment-as-a-service white space among German and Japanese mid-market contractors piloting per-hour bundled procurement. Target India's hire purchase collectives through partnerships with state contractors aggregating National Infrastructure Pipeline demand. Anchor go-to-market through digital remarketing platforms arbitraging residual value gaps across regional secondary markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric equipment manufacturing as OEMs internalize cell supply and charging infrastructure. Long-term viability favors vertically integrated financiers with integrated telematics and maintenance networks over independent lessors lacking service infrastructure. Acquire specialists with blockchain-based smart contract execution capabilities for mining and civil infrastructure consortia. Monitor EPA enforcement discretion on Tier 4 Final compliance deadlines as fleet turnover inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Finance Bundling | Enables usage-based payment structures for contractors previously excluded from traditional credit programs. |
| Green Bond Issuance | Qualifies low-emission equipment for preferential European Investment Bank capital treatment under EU taxonomy. |
| Secondary Market Platform Development | Captures off-lease volume from captive finance arms to arbitrage residual value across regional markets. |
| Blockchain Smart Contract Deployment | Automates payment releases for Australian mining contractors upon verified delivery milestones. |
| Technician Certification Investment | Addresses Tier 4 Final service network gaps that extend downtime and impair collateral recovery. |
Research Methodology
Desk research of SEC climate disclosure filings, EPA enforcement records, and EU sustainable finance taxonomy documentation preceded structured interviews with construction equipment finance directors, OEM captive lending officers, infrastructure fund portfolio managers, and regional contractor fleet procurement leads. Primary fieldwork with equipment lessors and telematics platform engineers validated secondary data on usage-based credit model transitions. Bottom-up origination volume analysis triangulated against top-down infrastructure spending forecasts.
Assumptions held fixed include EPA Tier 4 Final and EU Stage V emission compliance deadlines, Basel III risk-weighted asset treatment for construction lending, and steel price indexation contract structures. Variables modeled across the analysis window encompass IoT penetration rates in financed fleets, battery-electric equipment depreciation curve stabilization, and hire purchase collective formation velocity in India. Segmentation dimensions include financing type, equipment category, end-user archetype, and loan tenure matched to emission compliance lifecycles. CAGRs derived from equipment replacement cycle compression and infrastructure pipeline contract awards.
Macroeconomic conditions sit as an overlay; deviation in central bank policy rates, steel and battery metal price trajectories, or emission enforcement stringency would shift the trajectory. Forecasts reflect assumptions regarding telematics interoperability standards and residual value model convergence for electric variants. Quarterly review of EPA enforcement discretion, EU Green Deal taxonomy eligibility rulings, and mining capital expenditure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
China Auto Loan Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Student Loan Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
USA Home Loan Market