
 US Insurance Third-Party Administrator Market | 2026-2036
US Insurance Third-Party Administrator Market Size, Share, and Industry Trends Forecast 2026-2036
US Insurance Third-Party Administrator Market Insights
Cloud-native claims architecture is narrowing the cost gap between tier-one TPAs and mid-market competitors, compressing implementation timelines from months to weeks. Sedgwick Claims Management Services leverages its proprietary digital intake platform to sustain dominance in workers' compensation administration across all fifty states. Crawford & Company anchors its competitive position through specialized catastrophe response units that deploy within twenty-four hours of major weather events. Gallagher Bassett Services differentiates via outcome-based fee structures tied to claim closure rates rather than transaction volumes.
A third-party administrator functions as an outsourced entity that manages insurance claims processing, policy servicing, and risk assessment on behalf of insurers, self-funded employers, and government programs, typically operating under ERISA fiduciary standards and HIPAA data security protocols. The primary commercial purpose centers on reducing per-claim administrative costs while accelerating adjudication timelines through standardized workflows and specialized medical expertise. Claims Processing occupies the largest revenue pool within service type segmentation, though AI-Driven Analytics within technology segmentation is capturing disproportionate capital allocation as TPAs automate fraud detection and reserve forecasting. Cloud-Based Solutions leads deployment preference among new TPA engagements, displacing on-premise legacy systems that require dedicated IT maintenance staff.
HIPAA security rule enforcement by HHS Office for Civil Rights shapes data infrastructure investment requirements, while ERISA fiduciary standards from DOL dictate fee disclosure and claims appeal procedures that TPAs must embed operationally. State insurance commissioners in California, New York, and Texas impose additional licensing and solvency monitoring that fragments compliance costs across multi-state operations. Stakeholders must monitor how CMS guidance on price transparency and machine-readable file requirements reshapes the information asymmetry between TPAs, employers, and healthcare providers.
Market Dynamics
Cloud-native infrastructure is compressing the cost gap between tier-one TPAs and mid-market competitors, eroding the historical moat of scale economies that protected incumbent pricing power.
Growth Catalysts
- ERISA Fiduciary Standards:The DOL's fee disclosure mandates and claims appeal procedures push mid-sized employers toward outsourced administration, expanding the addressable base for TPAs serving self-funded health plans.
- Texas Manufacturing Concentration:Heavy industrial employers in Houston and Dallas-Fort Worth corridors are expanding workers' compensation outsourcing to specialized administrators, driving volume in the largest state TPA market.
- AI-Driven Fraud Detection:Machine learning platforms for reserve forecasting and claims pattern analysis are accelerating adjudication timelines, reducing per-claim administrative costs for TPAs deploying these tools.
Market Restraints
- State Licensing Fragmentation:Insurance commissioners in California, New York, and Texas impose non-uniform solvency monitoring and licensing requirements, multiplying compliance overhead for multi-state TPA operations.
- Legacy System Integration Costs:On-premise claims management platforms require dedicated IT maintenance staff, creating a structural cost disadvantage against cloud-native competitors and slowing technology migration.
- HIPAA Infrastructure Investment:HHS Office for Civil Rights enforcement of security rule protocols mandates continuous data infrastructure spending, compressing margins for smaller TPAs with limited capital reserves.
Strategic Opportunities
- Florida Employer Mandate Expansion:The state's large hospitality and agriculture employer populations remain underpenetrated by specialized TPAs, creating whitespace for administrators with bilingual claims intake capabilities.
- No Surprises Act Implementation:Federal surprise billing regulations are forcing hospitals and providers toward transparent pricing negotiations, positioning TPAs as intermediaries for independent dispute resolution.
- Telehealth Claims Convergence:The integration of virtual care utilization data with traditional workers' compensation claims streams enables TPAs to offer outcome-based fee structures tied to return-to-work metrics.
Industry Challenges
- Specialized Medical Expertise Scarcity:TPAs face acute shortages of nurses and physicians trained in occupational medicine, lengthening reserve-setting timelines and increasing reliance on third-party medical review vendors.
- Catastrophe Response Mobilization:Maintaining 24-hour deployment capabilities for weather event claims requires capital-intensive standby infrastructure that sits idle during normal loss periods, straining smaller operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Insurance Third-Party Administrator Market |
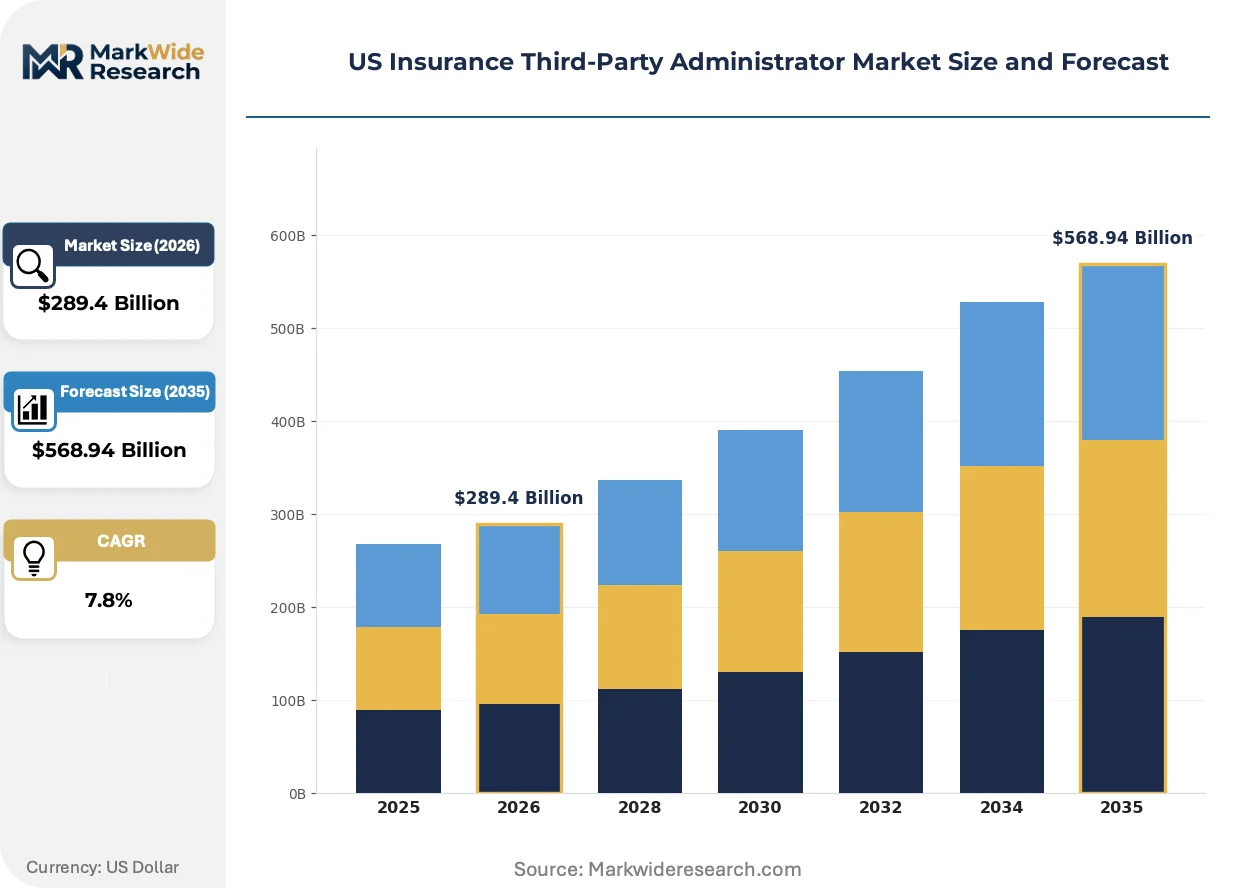
| Market Size in 2026 | $289.4 Billion |
| Market Size in 2035 | $568.94 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Claims Processing, Healthcare Management, Risk Assessment, Policy Administration End User: Insurance Companies, Self-Insured Entities, Employers, Brokers Technology: Cloud-Based Solutions, AI-Driven Analytics, Mobile Platforms, Data Integration Compliance Standard: HIPAA, ISO 27001, ERISA, GDPR |
| Companies Covered | Sedgwick Claims Management Services, Crawford & Company, Gallagher Bassett Services, CorVel Corporation, ESIS, Meritain Health, UMR, Helmsman Management Services, Broadspire, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Insurance Third-Party Administrator Market Trends and Innovations
Administrative automation and regulatory transparency mandates are restructuring how TPAs compete on speed, cost, and compliance depth across employer-sponsored benefit programs.
Machine learning platforms for predictive reserve modeling are digitizing the core actuarial function of claims administration. Self-insured employers in manufacturing and logistics verticals are adopting these tools at accelerating pace, compressing the historical 90-day reserve review cycle to real-time adjustments. This capability gap is digitizing competitive positioning between TPAs with proprietary algorithms and those dependent on manual statistical sampling.
CMS guidance on machine-readable file requirements for price transparency is reshaping information flows between TPAs, employers, and healthcare providers. The mandate forces disclosure of negotiated rates and historical claims data, eroding the information asymmetry that historically protected TPA margin structures. California and Texas employer groups are most affected, pressing administrators to develop client-facing analytics dashboards as retention tools.
Self-insured employers are unbundling traditional administrative service contracts into component modules for claims processing, pharmacy benefit management, and stop-loss placement. This disaggregation disrupts the historical single-source TPA relationship model, favoring administrators with API-first architectures that integrate with best-of-breed specialty vendors. The pattern is most visible among mid-sized manufacturing employers in the Midwest seeking granular cost accountability.
US Insurance Third-Party Administrator Market Segmentation
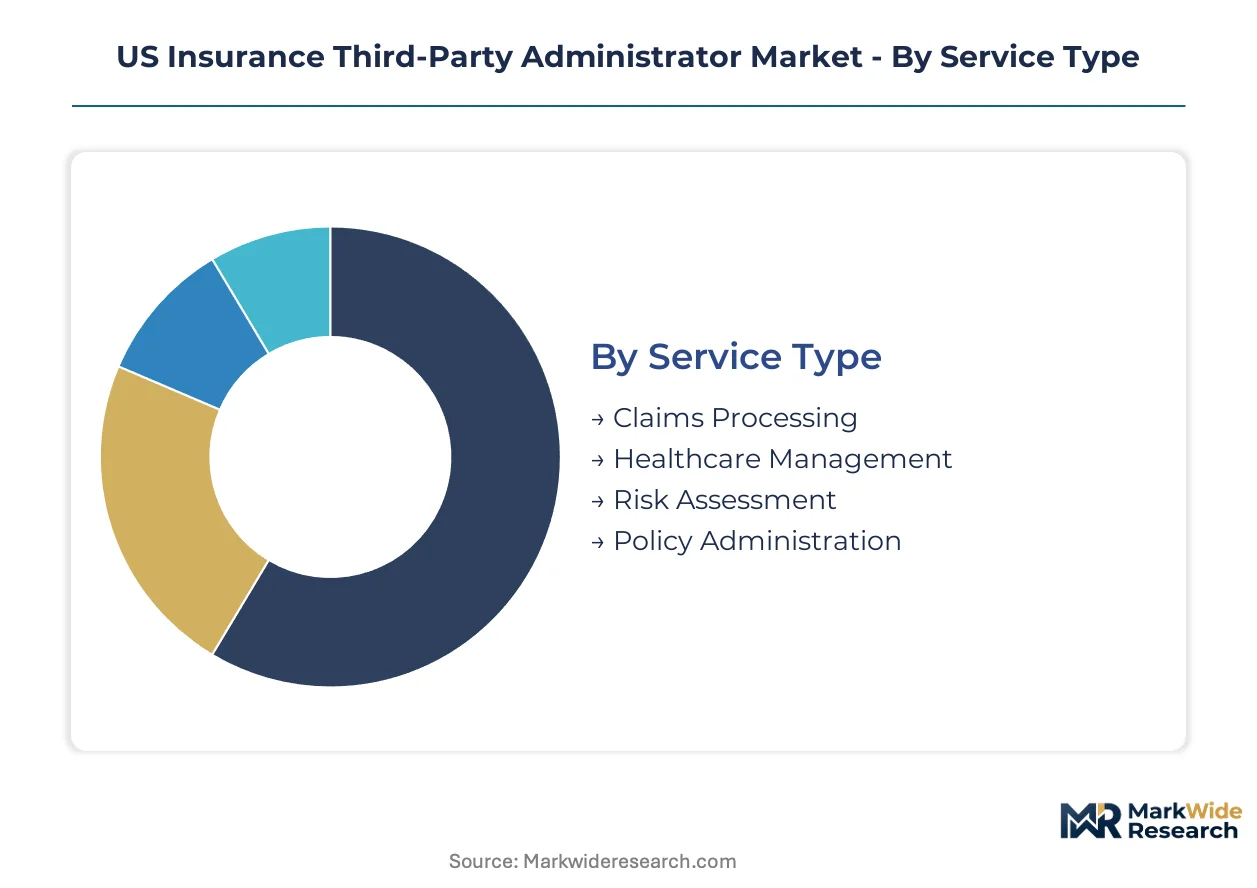
Segmentation in the US TPA market reveals how administrative complexity, regulatory fragmentation, and technology maturity create distinct competitive arenas. Each dimension shapes capital allocation, partnership structures, and margin profiles differently across the value chain.
Service Type:
Mature service lines dominate revenue concentration while emerging specializations capture disproportionate technology investment.
- Claims Processing:Core adjudication workflows for workers' compensation and health benefits generate the largest revenue pool. Texas and California self-insured employers drive volume through outsourced medical bill review and payment integrity services constrained by state fee schedule variations.
- Healthcare Management:Care coordination, utilization review, and network steering functions are expanding fastest among mid-sized manufacturing employers seeking return-to-work optimization. HIPAA security rule enforcement by HHS Office for Civil Rights elevates infrastructure requirements for this segment.
- Risk Assessment:Actuarial reserve setting and predictive modeling services support self-funded plan sponsors. Underwriters in Florida and Illinois rely on TPA-generated loss forecasts for stop-loss placement decisions.
- Policy Administration:Eligibility management, COBRA administration, and premium billing functions serve as retention anchors. DOL ERISA fiduciary standards dictate fee disclosure protocols that complicate pricing transparency.
Claims Processing retains volume leadership; Healthcare Management holds the steepest expansion curve.
End User:
Customer type determines contract structure, with fee models ranging from per-employee-per-month to outcome-based arrangements.
- Insurance Companies:Carriers outsource overflow claims handling and catastrophe response to TPAs with specialized medical expertise. Sedgwick and Crawford maintain dedicated units for hurricane and wildfire event mobilization.
- Self-Insured Entities:Municipalities, school districts, and Taft-Hartley plans represent stable, long-tenure relationships. State surprise billing regulations under the No Surprises Act increase demand for independent dispute resolution services.
- Employers:Manufacturing and logistics employers in Houston, Dallas-Fort Worth, and Chicago corridors are unbundling traditional ASO contracts into component modules. API-first architectures enable integration with best-of-breed pharmacy benefit managers.
- Brokers:Intermediaries increasingly require TPAs to provide client-facing analytics dashboards as differentiation tools. CMS machine-readable file mandates for price transparency erode information asymmetry that historically protected margin structures.
Employers command the largest addressable base; Self-Insured Entities generate the highest contract renewal rates.
Technology:
Deployment architecture separates capital-efficient competitors from legacy-dependent operators facing structural cost disadvantages.
- Cloud-Based Solutions:Native SaaS platforms compress implementation timelines from months to weeks. Multi-tenant infrastructure enables mid-market TPAs to compete with tier-one scale economies.
- AI-Driven Analytics:Machine learning for fraud detection and reserve forecasting accelerates adjudication timelines. Real-time reserve adjustments replace historical 90-day review cycles.
- Mobile Platforms:Claimant self-service apps and adjuster field tools reduce call center dependency. Texas workers' compensation administrators deploy mobile intake for industrial injury reporting.
- Data Integration:API connectivity with electronic health records, pharmacy systems, and telehealth platforms enables outcome-based fee structures. Return-to-work metrics now tie directly to administrator compensation.
Cloud-Based Solutions anchor current deployment preference; AI-Driven Analytics attracts the steepest capital allocation trajectory.
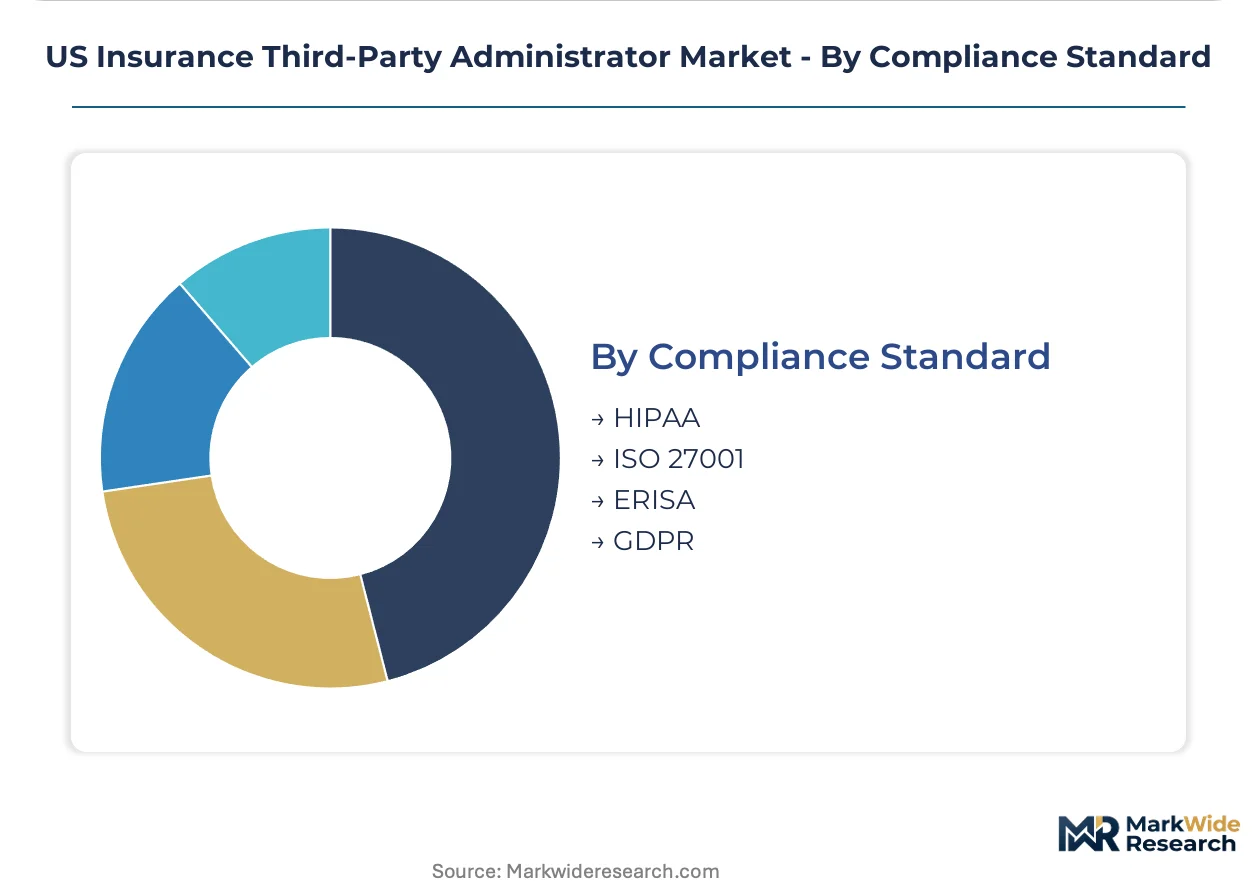
Compliance Standard:
Regulatory scope fragments operational requirements across federal, state, and international frameworks.
- HIPAA:HHS Office for Civil Rights security rule enforcement mandates continuous data infrastructure investment. Breach notification protocols and encryption standards shape vendor selection criteria.
- ISO 27001:Information security management certification serves as a competitive differentiator in RFP processes. Large self-insured employers require third-party attestation.
- ERISA:DOL fiduciary standards govern fee disclosure, claims appeal procedures, and prohibited transaction rules. TPAs must embed operational compliance for plan sponsor clients.
- GDPR:European data protection rules apply to US TPAs handling international employee benefits or cross-border claims. Data localization requirements complicate cloud architecture decisions.
HIPAA commands the broadest operational footprint; ISO 27001 demonstrates the fastest certification adoption rate among growth-stage administrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TPA service flows concentrate within domestic corridors linking high-employment manufacturing zones to specialized claims administrators, with Texas, California, and Florida serving as the primary demand anchors.
Texas
Houston and Dallas-Fort Worth manufacturing corridors generate outsized workers' compensation outsourcing volume. State insurance codes mandate licensed administrators for multi-employer health plans. Industrial employers in the Permian Basin and Gulf Coast petrochemical clusters are expanding TPA engagements for occupational injury management.
California
Los Angeles County and Bay Area technology employers drive health benefit administration complexity. The state's insurance commissioner imposes non-uniform solvency monitoring that fragments compliance costs. Sacramento Valley agricultural employers and San Diego defense contractors are unbundling traditional ASO contracts into component modules.
Florida
Orlando hospitality and Miami-Dade agriculture employer populations remain underpenetrated by specialized administrators. Federal surprise billing regulations under the No Surprises Act increase demand for independent dispute resolution services. Tampa-St. Petersburg logistics clusters are adopting bilingual claims intake capabilities for workers' compensation programs.
Illinois
Chicago metropolitan manufacturing employers seek granular cost accountability through API-first TPA architectures. DOL ERISA fiduciary standards govern fee disclosure protocols for self-funded Taft-Hartley plans. Rockford and Peoria industrial corridors are compressing reserve-setting timelines through predictive modeling services.
New York
New York City financial services and upstate municipal employer segments represent stable, long-tenure TPA relationships. State insurance licensing requirements multiply compliance overhead for administrators operating across Northeast corridors. Buffalo-Niagara manufacturing and Albany government employer clusters are expanding outsourced policy administration for eligibility management.
US Insurance Third-Party Administrator Market Competitive Landscape
On the supply side, the industry is consolidating around tier-one administrators with proprietary technology platforms and mid-market competitors leveraging cloud-native infrastructure to compress implementation timelines. Three archetypes dominate: scale-driven national administrators with catastrophe response capabilities, technology-first platforms with AI-driven analytics, and specialized regional players with deep state regulatory expertise. Dominant competitive moves include M&A to acquire proprietary digital intake platforms and strategic partnerships to integrate telehealth data streams with traditional claims workflows.
Within the tier-one administrator archetype, Sedgwick Claims Management Services, Crawford & Company, and Gallagher Bassett Services exemplify distinct positioning vectors. Sedgwick occupies a position emphasizing workers' compensation administration scale across all fifty states. Crawford anchors a specialization in catastrophe response mobilization within twenty-four hours of major weather events. Gallagher Bassett represents outcome-based fee structuring tied to claim closure metrics rather than transaction volumes. These three entities collectively illustrate how scale, specialization, and pricing innovation define competitive separation in the US TPA market.
| Leading Market Players |
|---|
| Sedgwick Claims Management Services |
| Crawford & Company |
| Gallagher Bassett Services |
| CorVel Corporation |
| ESIS |
| Meritain Health |
| UMR |
| Helmsman Management Services |
| Broadspire |
| Others |
Pricing and Supply Chain Analysis
Houston and Dallas-Fort Worth petrochemical and manufacturing clusters anchor the largest concentration of workers' compensation TPA capacity in the US, with cloud-native infrastructure investments by mid-market competitors compressing the historical scale-economy moat that protected tier-one pricing power. This geographic supply concentration directly shapes downstream fee structures, as Texas-based administrators leverage proximity to industrial employer density to offer outcome-based arrangements that undercut transaction-volume pricing in adjacent states.
Pricing Analysis
Cloud-native versus legacy on-premise infrastructure creates a pronounced technology-generation pricing gap in the US TPA market. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers commanded by Sedgwick and Crawford for catastrophe response and specialized medical expertise, while mid-market competitors compete on compressed implementation timelines. Price differentiation rests on HIPAA security certification level and proprietary AI fraud detection capability. Pricing pressure stems from cloud-native competitors eroding historical scale advantages, with margins tightening fastest in standard-tier claims processing. Mid-sized manufacturing employers in the Midwest exhibit highest price sensitivity, while municipal Taft-Hartley plans demonstrate lowest sensitivity due to regulatory complexity premiums.
Supply Chain Analysis
Tariff exposure between US cloud infrastructure providers and Canadian data center operators dominates supply chain risk planning for multi-state TPA operations. Geographic supply concentration centers on domestic US technology hubs, with critical software components sourced from India and Ireland for development cost arbitrage. Raw material dependencies include proprietary machine learning training datasets, HIPAA-compliant cloud storage infrastructure, and specialized occupational medicine nursing talent pools. Single-source vulnerability in AI model training data from limited healthcare claims repositories threatens competitive differentiation. Distribution runs through direct enterprise sales teams and broker intermediaries, with API-first platforms enabling modular unbundling of traditional administrative service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US TPA market sits at a platform-economics inflection where API-first architectures and modular service unbundling are restructuring competitive advantage around interoperability ecosystems rather than scale economies alone.
For Market Incumbents: Harden proprietary data moats through backward integration into telehealth utilization data streams and predictive reserve modeling algorithms, as cloud-native mid-market competitors erode pricing power in standard claims processing. Defend against modular unbundling by embedding outcome-based fee structures tied to return-to-work metrics that lock in manufacturing employer relationships. Prioritize certification investment in ISO 27001 and expanded HIPAA security infrastructure to maintain RFP differentiation against lower-cost entrants. For New Entrants and Emerging Players: Florida's hospitality and agriculture employer populations represent the most penetrable white-space geography, with bilingual claims intake capabilities serving as a critical go-to-market wedge against established administrators. Target Chicago metropolitan manufacturing corridors for API-first platform adoption, where granular cost accountability demands favor modular service architectures. Independent dispute resolution services under the No Surprises Act offer a specialized entry path with lower capital requirements than full claims administration. For Investors and Strategic Acquirers: Carve-out targets emerge from large insurance carriers spinning off captive TPA units to focus on core underwriting, with these assets offering immediate client relationships and licensed multi-state infrastructure. Long-term viability across the analysis window favors administrators with proprietary AI fraud detection and real-time reserve adjustment capabilities over transaction-volume dependent operators. Watch for inflection signals in CMS machine-readable file compliance rates as a predictor of which administrators can convert price transparency mandates into client retention tools.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables modular unbundling of ASO contracts for Midwest manufacturing employers seeking cost accountability. |
| AI-Driven Fraud Detection Deployment | Accelerates adjudication timelines and supports outcome-based fee structures tied to claim closure rates. |
| Telehealth Data Stream Integration | Combines virtual care utilization with workers' compensation claims for return-to-work optimization metrics. |
| HIPAA Security Infrastructure Expansion | Meets HHS Office for Civil Rights enforcement demands and differentiates in RFP processes for self-insured plans. |
| Catastrophe Response Capacity Buildout | Supports 24-hour deployment capabilities for weather events that strain smaller operators' standby infrastructure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of DOL ERISA guidance documents, HHS HIPAA security rule enforcement records, and state insurance commissioner licensing databases. Primary interviews engaged TPA operations executives, self-insured employer benefits directors, insurance broker intermediaries, and healthcare provider contracting officers across Texas, California, Florida, and Illinois. Secondary validation drew from CMS price transparency machine-readable file repositories, SEC 10-K filings of publicly traded administrators, and NAIC state insurance regulatory reports. Bottom-up employer demand modeling triangulated against top-down service revenue aggregation.
Forecast inputs include service type segmentation by claims processing volume, technology deployment architecture adoption curves, and end-user contract structure evolution across the projection horizon. Modeled dimensions span service type maturity, cloud versus on-premise infrastructure share, and compliance standard certification penetration. CAGRs derived from historical administrative cost inflation patterns and technology-driven efficiency gains. Industry-specific inputs incorporate DOL fiduciary standard enforcement trajectory and CMS guidance implementation timelines for price transparency mandates.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform investments by mid-market competitors or accelerated modular unbundling by manufacturing employers would shift outcomes beyond projected ranges. Regulatory enforcement intensity by HHS Office for Civil Rights and state insurance commissioners represents material revision risk. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Disability Insurance Market
Insurance
IoT Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Cargo Insurance Market
Insurance
Auto Extended Warranty Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Finland Cyber (Liability) Insurance Market
Insurance
Insurance Protection Products Market
Insurance
Spain Group Health Insurance Market
Insurance
Event Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
United Kingdom Parametric Insurance Market