
 UAE Property and Casualty Insurance Market | 2026-2036
UAE Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Property and Casualty Insurance Market Analytics
Enhanced coverage tiers for mega-project risks is collapsing the gap between standard commercial lines and bespoke engineering policies. Emirates Insurance Company leverages its sovereign-linked balance sheet to anchor large infrastructure mandates across the emirates. GIG Gulf competes through Gulf-wide licensing that extends policy portability for cross-border contractors. Abu Dhabi National Insurance Company dominates energy-sector placements with specialized upstream and downstream coverage frameworks.
Property and casualty insurance encompasses risk transfer instruments covering physical asset damage, third-party liability, and business interruption losses, with policy structures specifying per-occurrence limits, aggregate caps, and named-peril or all-risk coverage triggers. Its primary commercial purpose centers on enabling capital deployment by shielding corporate balance sheets from catastrophic asset and liability exposures. Auto insurance under personal lines has matured into a high-volume, regulated-mandatory segment with compressed margins, while liability coverage for construction defect and professional negligence claims represents the fastest-growing margin pool. Commercial customer segments concentrate demand for complex multi-line programs, whereas direct sales channels capture increasing share in standardized personal auto and home policies through digital onboarding.
MOHAP mandates health liability provisions that intersect with casualty coverage for medical malpractice and facility operational risks. The UAE Central Bank's prudential regulations govern insurer solvency, reserving, and risk-based capital requirements that directly shape product availability and pricing floors. Stakeholders must monitor how the Central Bank's evolving fit-and-proper standards for licensed actuaries and underwriters will constrain market entry and reshape competitive dynamics in specialty lines.
Market Dynamics
The UAE Central Bank's tightened capital adequacy framework is compressing insurer balance sheets and forcing selective underwriting discipline across property and casualty lines. This regulatory pressure is reshaping how carriers price mega-project risks and allocate capacity to Dubai's construction pipeline.
Growth Catalysts
- MOHAP health liability mandates:Medical malpractice coverage requirements are creating intersecting demand for casualty policies that protect healthcare facility operational exposures.
- Abu Dhabi energy sector expansion:Upstream and downstream project commitments are pulling specialized property and engineering coverage into long-tail policy structures.
- Digital distribution infrastructure:Direct-to-consumer platforms are capturing standardized personal auto and home policy volumes through automated onboarding and instant quote generation.
Market Restraints
- Reinsurance cost volatility:Global catastrophe loss accumulation is driving retrocession pricing spikes that compress primary insurer margins on property lines.
- Actuarial talent scarcity:The UAE Central Bank's fit-and-proper standards for licensed actuaries are constraining underwriting capacity expansion in specialty segments.
- Construction defect liability accumulation:Latent defect claims in Dubai's rapid-build residential stock are eroding historical loss ratios on contractor all-risk policies.
Strategic Opportunities
- Sharjah and Northern Emirates penetration:Lower insurance density in emerging industrial zones offers first-mover positioning for multi-line commercial programs.
- Parametric coverage innovation:Index-triggered policies for business interruption and natural catastrophe risks are opening alternative risk transfer channels for hospitality operators.
- Cross-border portability frameworks:Gulf-wide licensing harmonization enables policy extension for contractors operating across Saudi Arabia, Qatar, and Kuwait from UAE domiciles.
Industry Challenges
- Legacy system integration friction:Core policy administration platforms at established carriers resist seamless API connectivity with InsurTech distribution partners.
- Specialized underwriter pipeline gaps:Engineering risk assessment expertise for mega-project exposures remains concentrated among a limited cohort of senior practitioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Property and Casualty Insurance Market |
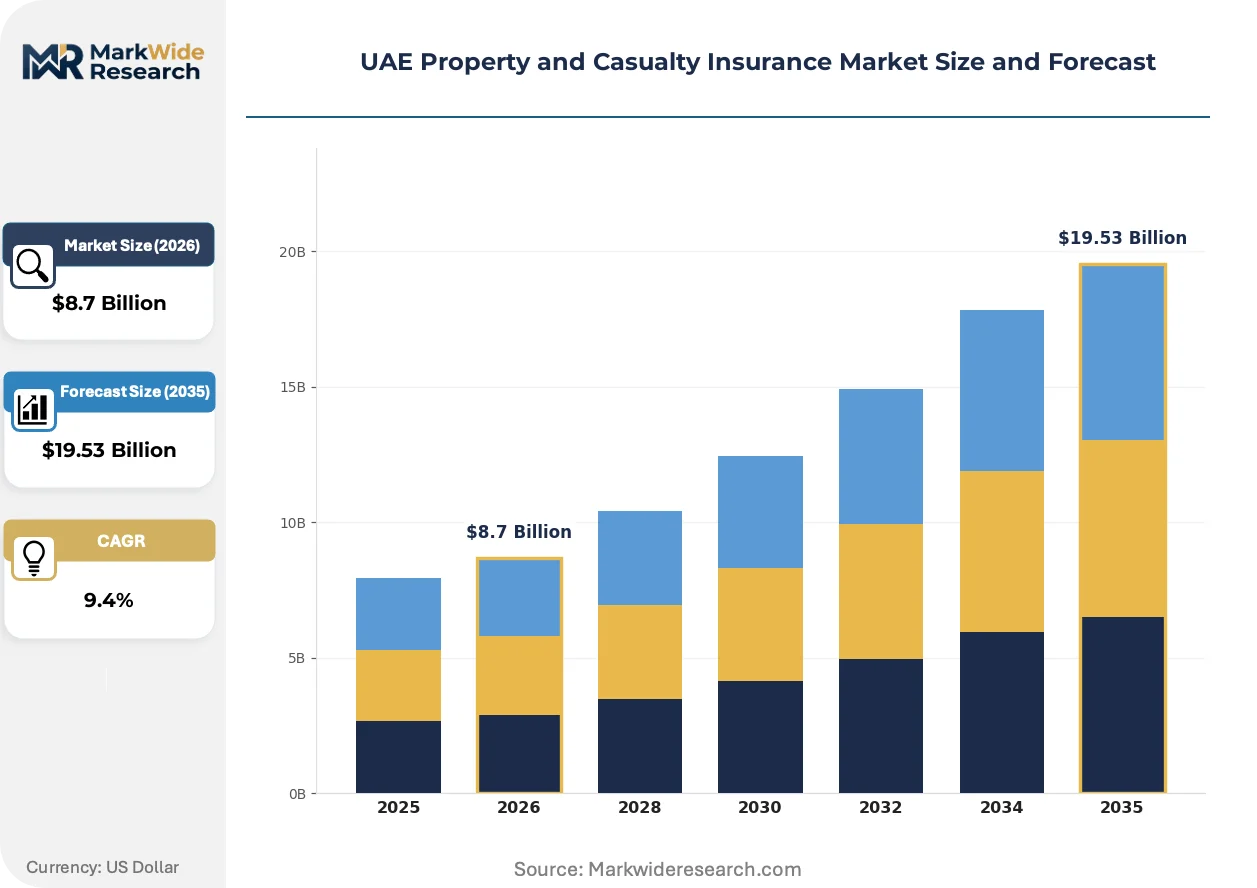
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Home Insurance, Auto Insurance, Liability Insurance, Property Insurance Distribution Channel: Online, Broker, Agent, Direct Sales Customer Type: Individual, Commercial, Small Business, Government Policy Coverage: Comprehensive, Third Party, Fire and Theft, Natural Disaster |
| Companies Covered | Emirates Insurance Company, GIG Gulf, Orient Insurance PJSC, Islamic Arab Insurance Co., Union Insurance Co., Sukoon Insurance, National General Insurance Co., Al Buhaira National Insurance Co., Abu Dhabi National Insurance Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Property and Casualty Insurance Market Evolving Landscape
Technology-enabled risk assessment and regulatory digitization are restructuring how UAE insurers underwrite, distribute, and reserve against property and casualty exposures. These forces are compressing traditional value chain segments while opening new competitive terrain.
Telematics-enabled usage-based auto insurance is displacing traditional annual premium models in the personal lines segment. Dubai-based fleet operators and individual policyholders are adopting real-time driving behavior monitoring at accelerating rates. This data granularity is compressing risk pooling advantages of incumbent carriers while enabling precise individual risk pricing.
The UAE Central Bank's prudential reporting digitization mandates are forcing insurer data infrastructure modernization. Solvency calculations and reserve adequacy submissions now require standardized machine-readable formats. Mid-sized carriers with fragmented legacy systems face the steepest compliance cost burden as they reconfigure actuarial workflows.
Corporate risk managers in Dubai's real estate and hospitality verticals are consolidating procurement through broker-led competitive tenders rather than direct carrier relationships. This buying-pattern shift is disintermediating traditional agency channels for commercial multi-line programs. Abu Dhabi's sovereign-linked entities remain the exception, maintaining captive negotiation leverage with designated domestic carriers.
UAE Property and Casualty Insurance Market Segmentation
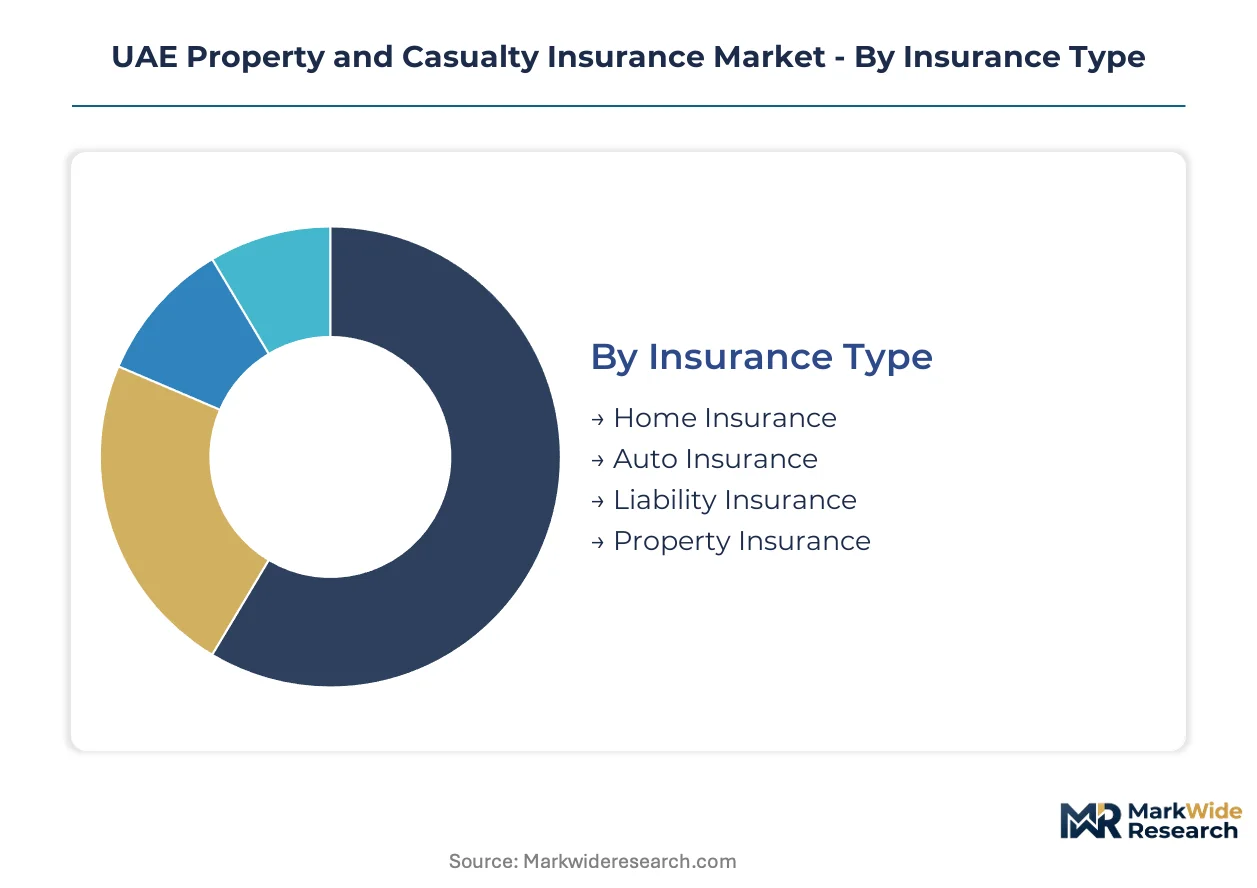
Segmentation in the UAE property and casualty insurance market reveals how regulatory mandates, distribution infrastructure, and risk complexity fragment demand across distinct purchasing behaviors and coverage specifications. Each dimension exposes different margin pools and competitive entry points for carriers.
Insurance Type:
Auto insurance faces the most intense substitution pressure as telematics-enabled usage-based models displace traditional annual premium structures, while liability coverage gains pricing power from construction defect accumulation.
- Auto Insurance:Mandatory third-party coverage anchors volume in personal lines, with real-time driving behavior monitoring compressing risk pooling advantages of incumbent carriers. Dubai fleet operators and individual policyholders are adopting telematics at accelerating rates.
- Liability Insurance:Construction defect and professional negligence claims represent the fastest-growing margin pool, with latent defect exposure in Dubai's rapid-build residential stock eroding historical loss ratios on contractor policies.
- Property Insurance:Physical asset damage coverage for commercial real estate and hospitality assets commands premium pricing from mega-project risk concentration.
- Home Insurance:Standardized dwelling coverage for residential properties remains a low-margin, high-volume segment with limited differentiation.
Auto insurance retains volume leadership; liability insurance holds the steepest expansion curve.
Distribution Channel:
Cost tier fragmentation separates high-touch advisory channels from automated acquisition, with digital platforms capturing standardized policy volumes while complex commercial risks concentrate through intermediated routes.
- Broker:Corporate risk managers in Dubai's real estate and hospitality verticals consolidate procurement through broker-led competitive tenders, disintermediating traditional agency channels for commercial multi-line programs.
- Online:Direct-to-consumer platforms capture standardized personal auto and home policy volumes through automated onboarding and instant quote generation, compressing acquisition costs.
- Agent:Commission-driven intermediaries retain foothold in relationship-heavy segments where policy customization exceeds algorithmic capacity.
- Direct Sales:Abu Dhabi's sovereign-linked entities maintain captive negotiation leverage with designated domestic carriers, bypassing external distribution entirely.
Brokers dominate commercial placement value; online channels scale fastest in personal lines acquisition.
Customer Type:
Application complexity stratifies across customer categories, with government and large commercial accounts demanding bespoke engineering frameworks while individual and small business segments accept standardized policy wordings.
- Commercial:Complex multi-line programs for Dubai construction developers and Abu Dhabi energy operators require specialized property and engineering coverage with long-tail policy structures.
- Government:Sovereign-linked mandates anchor large infrastructure placements across the emirates, with designated domestic carriers capturing exclusive negotiation access.
- Small Business:Lower insurance density in Sharjah and Northern Emirates industrial zones offers first-mover positioning for packaged commercial programs.
- Individual:Regulated-mandatory auto coverage and optional home protection comprise a high-volume, compressed-margin segment with digital onboarding dominance.
Commercial customers generate premium yield; government accounts provide mandate stability.
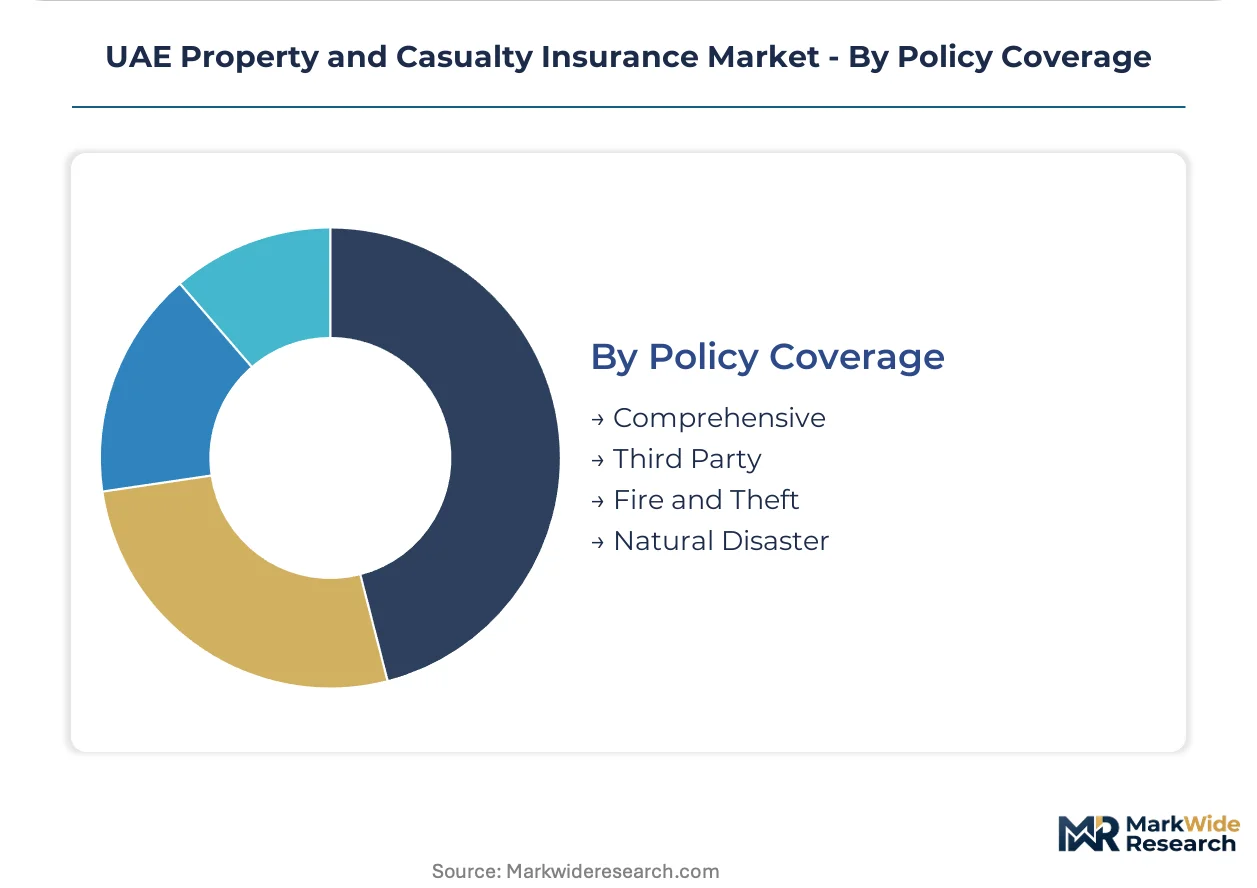
Policy Coverage:
Maturity gradients separate comprehensive all-risk policies from named-peril alternatives, with coverage breadth directly correlating to pricing power and underwriting complexity.
- Comprehensive:All-risk coverage triggers for physical asset damage, third-party liability, and business interruption losses enable capital deployment by shielding corporate balance sheets from catastrophic exposures.
- Natural Disaster:Index-triggered parametric policies for business interruption risks are opening alternative risk transfer channels for hospitality operators facing catastrophe volatility.
- Third Party:Minimum mandatory coverage for auto liability satisfies regulatory floors with minimal underwriting differentiation.
- Fire and Theft:Named-peril coverage for specific asset risks occupies a mid-tier pricing position between comprehensive and third-party structures.
Comprehensive coverage commands premium pricing; natural disaster policies gain share fastest in hospitality verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE's property and casualty insurance sector operates as a net importer of reinsurance capacity, with domestic cedents placing substantial portions of mega-project risks into international retrocession markets. Dubai and Abu Dhabi dominate premium generation through concentrated construction and energy activity.
Dubai
Commercial real estate development and hospitality mega-projects drive demand for contractor all-risk and professional liability coverage. Dubai's Department of Economy and Tourism enforces mandatory insurance requirements for hotel operators and event venues. The Dubai International Financial Centre anchors broker-led placement activity for cross-border corporate programs.
Abu Dhabi
Upstream and downstream energy commitments pull specialized engineering and property coverage into long-tail policy structures. The Abu Dhabi Department of Energy mandates comprehensive operational risk coverage for hydrocarbon facilities. Khalifa Industrial Zone concentrates industrial asset protection demand among petrochemical and manufacturing operators.
Sharjah
Emerging industrial zones and lower insurance density create first-mover positioning for packaged commercial programs targeting small and mid-sized enterprises. Sharjah's Department of Economic Development promotes business establishment through streamlined licensing. Hamriyah Free Zone attracts manufacturing entrants requiring property and liability coverage frameworks.
Northern Emirates
Ras Al Khaimah and Fujairah present underpenetrated markets with concentrated hospitality and logistics infrastructure development. Local economic departments enforce baseline commercial liability requirements for operating licenses. Ras Al Khaimah's tourism and real estate clusters generate specialized property coverage demand from resort and residential developers.
UAE Property and Casualty Insurance Market Competitive Landscape
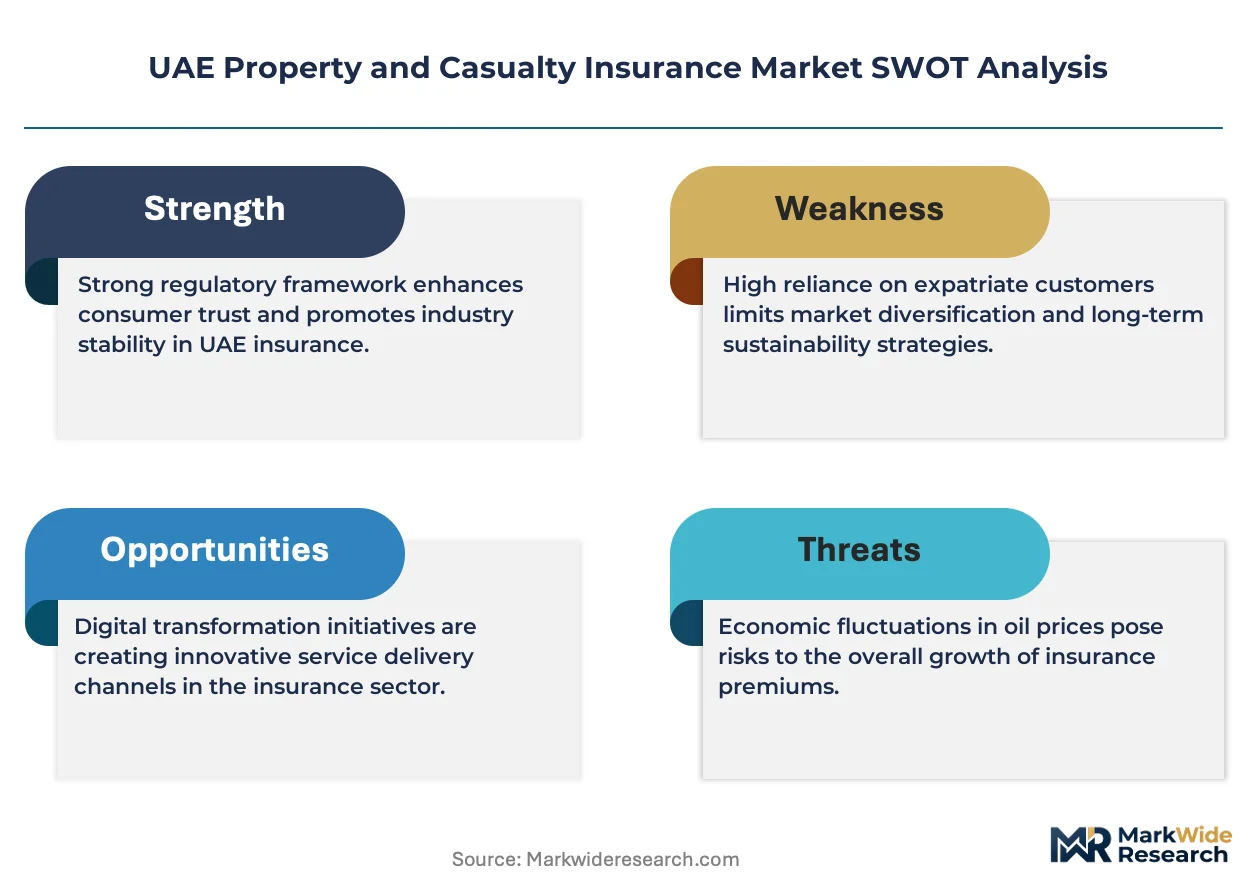
Listed leaders compete with private specialists across capital adequacy and sovereign relationship dimensions. The UAE Central Bank's tightened solvency requirements favor established carriers with robust balance sheets and diversified reinsurance arrangements. Three archetypes dominate: sovereign-linked domestic incumbents with mandate access, Gulf-wide regional platforms leveraging multi-territorial licensing, and specialized takaful operators serving Sharia-compliant demand. Competitive moves concentrate on capacity allocation discipline for mega-project risks and digital distribution infrastructure deployment for personal lines.
Within the sovereign-linked tier, Emirates Insurance Company and Abu Dhabi National Insurance Company anchor large infrastructure placements through exclusive negotiation access with government entities. GIG Gulf exemplifies the Gulf-wide regional platform archetype, extending policy portability across Saudi Arabia, Qatar, and Kuwait from its UAE domicile.
| Leading Market Players |
|---|
| Emirates Insurance Company |
| GIG Gulf |
| Orient Insurance PJSC |
| Islamic Arab Insurance Co. |
| Union Insurance Co. |
| Sukoon Insurance |
| National General Insurance Co. |
| Al Buhaira National Insurance Co. |
| Abu Dhabi National Insurance Company |
| Others |
Value Network & Pricing Analysis
Long-tail policy structures for Abu Dhabi energy and Dubai mega-project risks lock in multi-year capacity commitments while anchoring premium visibility against reinsurance volatility. These contractual frameworks tie primary insurer pricing power directly to retrocession access and sovereign-linked mandate flows.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium engineering policies, standard commercial lines, and economy personal auto coverage. Price differentiation hinges on actuarial sophistication depth and UAE Central Bank solvency tier certification. Cost compression in personal auto intensifies as telematics-enabled usage models erode traditional risk-pooling margins. Small business segments in Sharjah and Northern Emirates exhibit highest price sensitivity; sovereign-linked government accounts show least.
Supply Chain Analysis
Bermuda, London, and Zurich anchor international reinsurance capacity that UAE primary insurers draw from for mega-project property risks. Retrocession treaties, catastrophe bonds, and sidecar vehicles constitute critical risk-transfer inputs. Single-source vulnerability concentrates in engineering risk assessment expertise for long-tail energy coverage. Distribution runs through broker-led competitive tenders for commercial placements and direct digital platforms for standardized personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized underwriting talent for complex engineering and energy risks remains the binding constraint across the UAE property and casualty sector, with UAE Central Bank fit-and-proper standards tightening this scarcity.
For Market Incumbents: Secure captive access to licensed actuarial talent pools through structured training partnerships with regional universities and targeted recruitment from international retrocession hubs. Deepen backward integration into proprietary risk assessment methodologies for mega-project exposures to defend against Gulf-wide regional platforms eroding mandate access. For New Entrants and Emerging Players: Lead with parametric coverage innovation for hospitality business interruption risks in Ras Al Khaimah and Fujairah tourism clusters, where traditional indemnity products leave coverage gaps. Deploy direct digital acquisition infrastructure targeting standardized personal auto and home policies in Sharjah's emerging industrial zones. For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized carriers with fragmented legacy systems but intact sovereign relationships, where technology modernization unlocks compliance efficiency and personal lines scale. Watch for inflection signals in UAE Central Bank digital reporting mandate enforcement timelines that would accelerate consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Actuarial Talent Pipeline Investment | Structured university partnerships with UAE Central Bank licensing alignment secure underwriting capacity expansion. |
| Parametric Product Development | Index-triggered hospitality coverage opens alternative risk transfer channels beyond traditional indemnity structures. |
| Legacy System Modernization | API-enabled core platforms capture InsurTech distribution partnerships for personal lines scale. |
| Gulf-Wide Licensing Harmonization | Multi-territorial policy portability extends contractor coverage across Saudi Arabia, Qatar, and Kuwait. |
| Digital Distribution Infrastructure | Automated onboarding platforms compress acquisition costs in standardized auto and home segments. |
Research Methodology
The analysis maps property, liability, auto, and home insurance sub-sectors, each validated through chief underwriting officers, broker placement executives, risk managers at Dubai real estate developers, and UAE Central Bank regulatory affairs leads. Primary interview findings triangulate against Central Bank solvency filings, insurance association statistical bulletins, customs records on reinsurance cessions, and construction project development databases. Bottom-up policy volume estimates cross-check with top-down premium generation benchmarks.
Consistency checks validate volume and value outputs against retrocession market capacity disclosures and regional competitor financial statements across the projection horizon. Segmentation dimensions modeled include insurance type, distribution channel, customer category, and policy coverage breadth. CAGRs derive from fitted growth curves incorporating construction pipeline commitments, energy sector expansion timelines, and regulatory digitization mandates.
The analysis sits within stated boundaries; outcomes outside sustained mega-project construction activity, stable retrocession pricing, or unchanged Central Bank capital adequacy thresholds would require recalibration. Recalibration cycles align with material shifts in construction defect liability accumulation patterns or sovereign-linked mandate allocation changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Cybersecurity Insurance Market
Insurance
Title Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
Commercial Cyber Insurance Market
Insurance
Property Insurance Market
Insurance
Africa Microinsurance Market
Insurance
Jewelry Insurance Market
Insurance
Self Funded Insurance Market
Insurance
Reinsurance Carriers Market
Insurance
Group Health Insurance Market
Insurance
Digital Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
Finland Cyber (Liability) Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
Saudi Arabia Health & Medical Insurance Market