
 Agriculture Reinsurance Market | 2026-2036
Agriculture Reinsurance Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Reinsurance Market Insights
Commercial growers is hardening as the fastest-expanding customer type, outpacing smallholder uptake in premium volume. Munich Re leverages its parametric weather-index platform to dominate Latin American crop coverage. Swiss Re anchors global capacity through its agricultural risk modeling division, while Hannover Re competes via specialized livestock mortality treaties in European dairy regions.
Agriculture reinsurance is the secondary transfer of agricultural risk from primary insurers to specialized carriers, typically structured through quota-share or excess-of-loss treaties with attachment points calibrated to yield variance or weather-index triggers. Its commercial purpose is to stabilize primary insurer balance sheets against correlated catastrophic losses across crop and livestock portfolios. Crop insurance commands the deepest capacity pools among product types, while weather insurance represents the fastest-growing segment as parametric triggers displace traditional indemnity structures. Broker distribution still occupies the majority placement channel, though bancassurance is extending rapidly in emerging markets where rural banking networks penetrate farming communities.
The EU Green Deal and F-Gas Regulation are reshaping risk models for European agricultural underwriters, while the USDA's Federal Crop Insurance Corporation mandates minimum coverage standards that cascade into reinsurance demand. India's PMFBY scheme and CEA guidelines create structured cession requirements that concentrate treaty flow through domestic brokers. Stakeholders must monitor how climate transition disclosure rules under CSRD and SEC frameworks reshape capital allocation toward sustainable agriculture risk pools.
Market Dynamics
Climate volatility is compressing attachment points and accelerating parametric trigger adoption across crop portfolios, forcing reinsurers to rebuild yield variance models around real-time satellite data feeds.
Growth Catalysts
- USDA Federal Crop Insurance Corporation mandates:Minimum coverage standards in the United States cascade into treaty demand as primary carriers seek capacity backing for correlated drought and flood exposures.
- Brazil's soybean belt concentration:Commercial growers in Mato Grosso and Paraná are expanding quota-share purchases as El Niño intensification raises yield variance across the Cerrado.
- Parametric weather-index platforms:Automated satellite-triggered settlements are displacing traditional indemnity structures, cutting loss adjustment costs and accelerating capital deployment.
Market Restraints
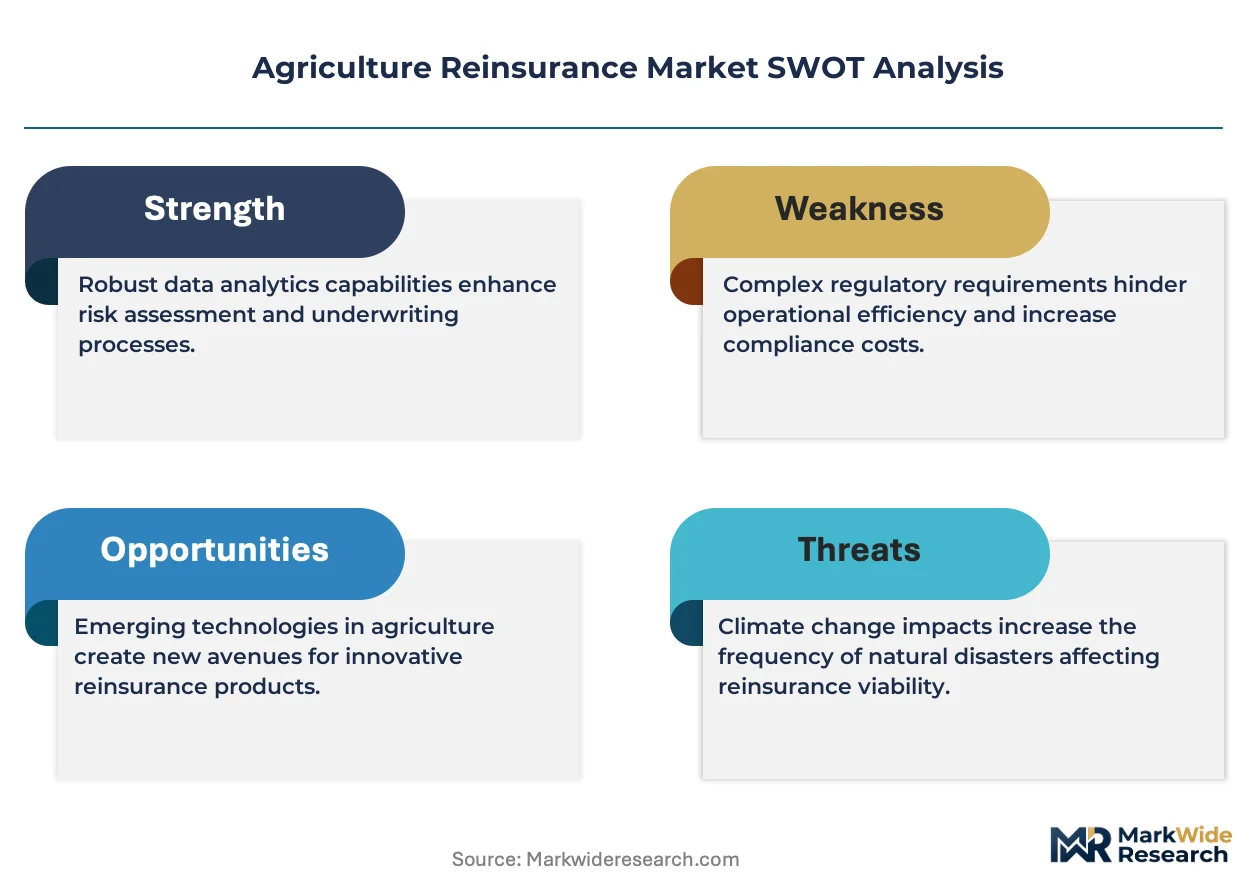
- Basis risk in index structures:Mismatches between parametric triggers and actual farm-level losses limit uptake among smallholders with heterogeneous plot conditions.
- Capacity concentration in Bermuda and London:Catastrophe bond issuance for agricultural risk remains dominated by a narrow pool of ILS investors, creating renewal pricing volatility.
- EU F-Gas Regulation compliance costs:European underwriters face elevated operational expenses from greenhouse gas reporting requirements embedded in agricultural risk assessments.
Strategic Opportunities
- India's PMFBY scheme expansion:Structured cession requirements under CEA guidelines create captive treaty flow through domestic brokers in wheat-growing states of Punjab and Haryana.
- Livestock mortality parametrics:Heat-stress index triggers for dairy herds are opening capacity in European regions where traditional veterinary indemnity models face margin compression.
- Bancassurance channel penetration:Rural banking networks in emerging markets are disintermediating traditional broker placement for smallholder crop coverage.
Industry Challenges
- Agricultural data science talent scarcity:Reinsurers struggle to hire yield modelers with combined expertise in climatology, remote sensing, and actuarial pricing.
- Legacy core system integration:Treaty administration platforms built for property-catastrophe lines require expensive retrofitting to handle satellite-indexed crop schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Reinsurance Market |
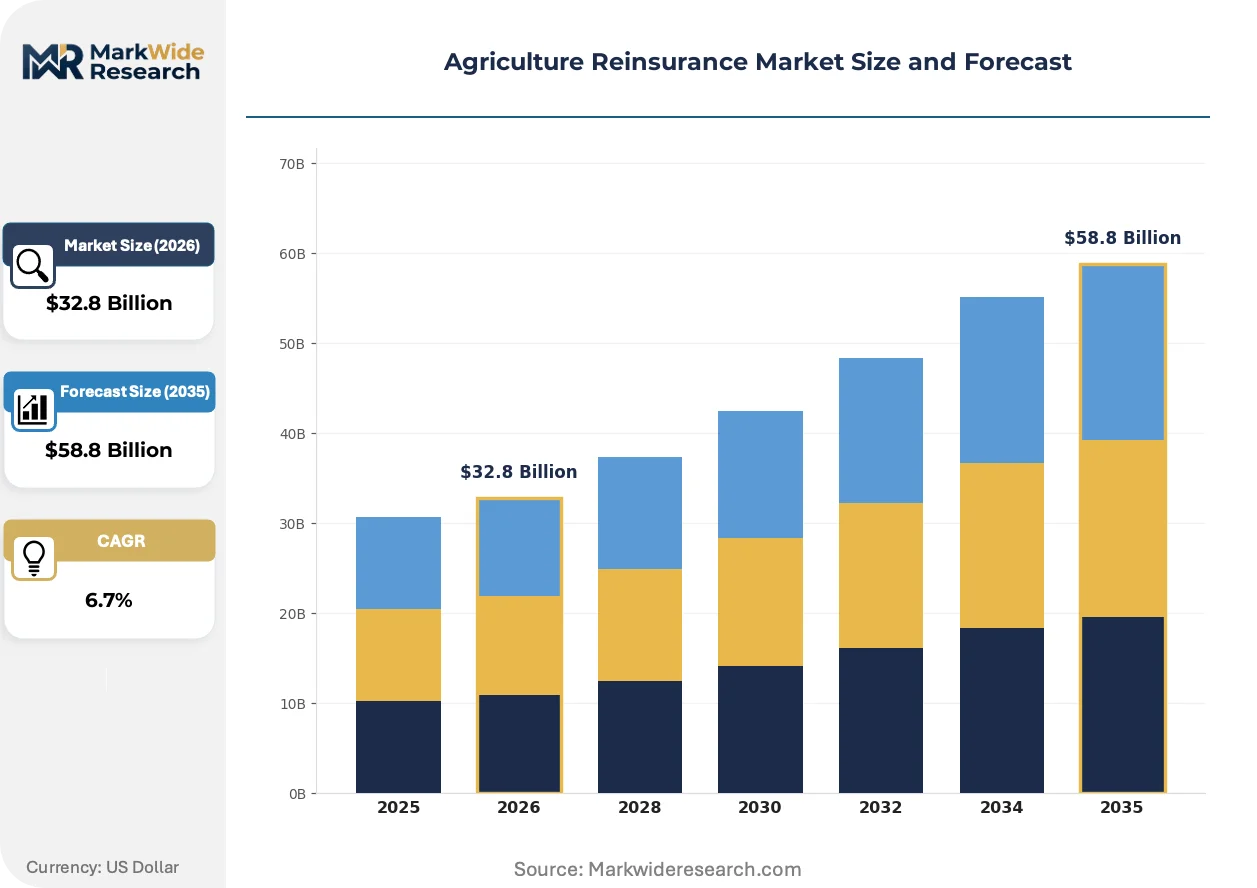
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $58.8 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crop Insurance, Livestock Insurance, Weather Insurance, Multiple Peril Insurance, Hail Insurance Customer Type: Smallholder Farmers, Commercial Growers, Agri-Business Firms, Agricultural Cooperatives, Government Agencies Application: Risk Mitigation, Yield Protection, Income Stabilization, Catastrophe Coverage, Disaster Recovery Distribution Channel: Brokers, Direct Sales, Online Platforms, Bancassurance, Agent Networks |
| Companies Covered | Swiss Re, Munich Re, Hannover Re, PartnerRe, SCOR, Everest Re, Berkshire Hathaway, Sompo International, Allianz Re, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Reinsurance Market Trends and Innovations
Satellite-derived agronomy is compressing the information asymmetry between cedents and reinsurers, while regulatory disclosure mandates are reshaping capital allocation toward climate-resilient agriculture portfolios.
Machine learning yield forecasting is unifying disparate data streams from Sentinel-2 imagery, soil moisture probes, and weather station networks into single predictive models. Commercial carriers in North America are deploying these platforms to pre-position loss adjustment resources before harvest failures materialize. The structural consequence is unifying previously siloed crop science and actuarial functions inside underwriting divisions.
The EU Green Deal's sustainable agriculture mandates are embedding carbon sequestration metrics into risk selection criteria for European treaty renewals. Primary insurers must now document regenerative farming practices to access preferential reinsurance terms. Specialty crop underwriters in Spain and Italy are responding by developing coverages that reward cover-crop adoption with reduced premium rates.
Buyer concentration among agribusiness conglomerates is consolidating placement power into fewer hands, compressing broker commissions and accelerating direct reinsurer relationships. Large-scale grain traders in Argentina and the Black Sea region are bypassing traditional intermediaries to negotiate captive quota-shares. This shift is most visible in Brazil, where vertically integrated soybean processors now structure multi-year treaties directly with capacity providers.
Agriculture Reinsurance Market Segmentation
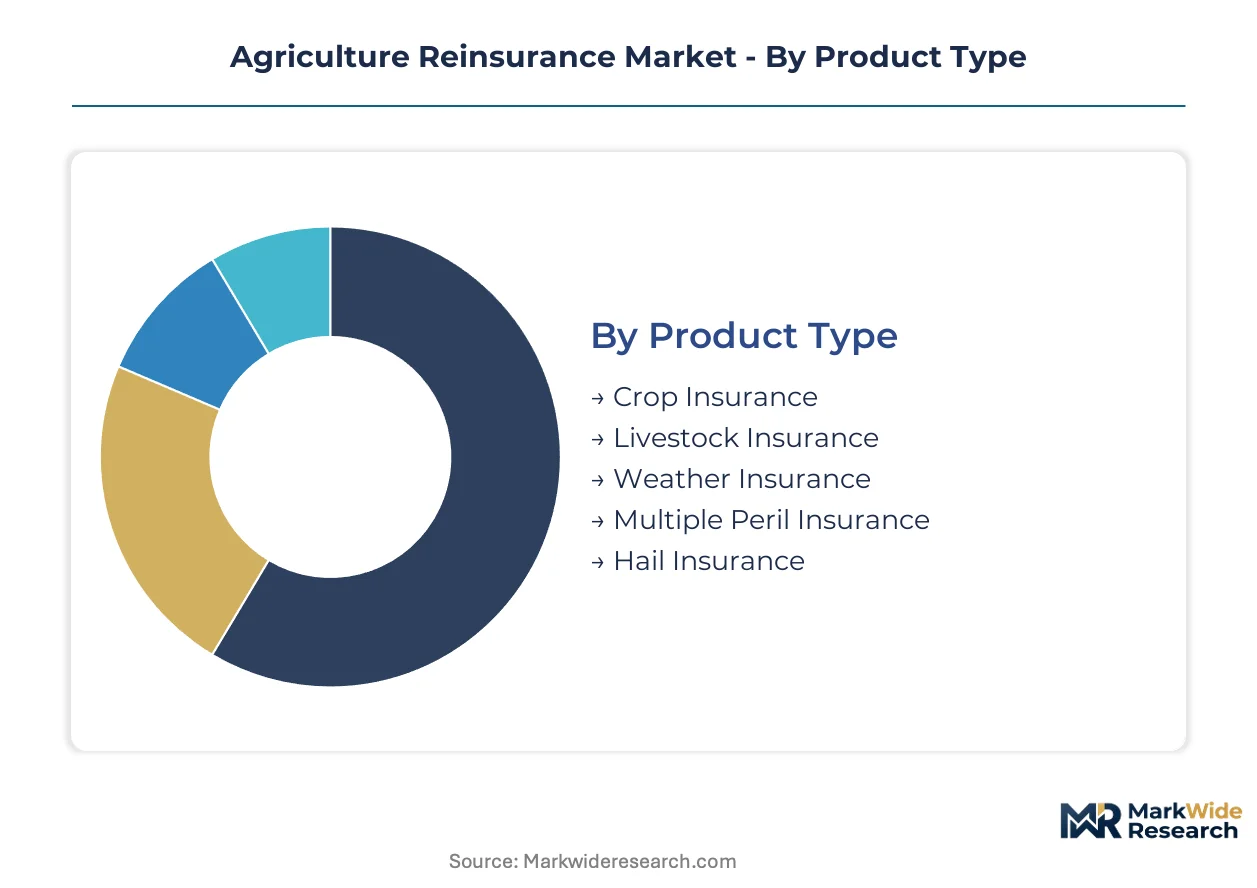
Reinsurance placement patterns vary sharply across product structures and buyer profiles, with treaty pricing and attachment points calibrated to each segment's loss correlation and data availability. Capacity allocation decisions depend on matching parametric triggers to specific agricultural exposures.
Product Type:
Replacement of legacy indemnity structures with automated settlement mechanisms is reshaping product development roadmaps across major reinsurance carriers.
- Crop Insurance:Treaty structures cover yield shortfalls across grains, oilseeds, and specialty crops through area-based or individual farm triggers. Demand concentrates in Brazil's Mato Grosso soybean belt and Iowa corn counties as El Niño volatility compresses attachment points.
- Weather Insurance:Satellite-indexed parametric products trigger automatic payouts based on rainfall deficits, temperature extremes, or vegetation indices. Adoption is accelerating in India's wheat-growing states where PMFBY mandates create structured cession flows through domestic brokers.
- Livestock Insurance:Mortality and productivity covers for dairy and beef herds, traditionally indemnity-based but shifting toward heat-stress index triggers.
- Multiple Peril Insurance:Bundled coverage combining weather, disease, and market price risks into single treaty structures.
- Hail Insurance:Named-peril coverage for physical crop damage, retaining relevance in European viticulture and North American high-plains wheat.
Crop Insurance sits at the top of the volume ranking, with Weather Insurance climbing the fastest.
Customer Type:
Margin profiles diverge sharply between price-sensitive smallholders and data-rich commercial operations that command preferential treaty terms.
- Commercial Growers:Large-scale farming enterprises with consolidated landholdings and precision agriculture data streams. Treaty negotiations in Argentina's Pampas and Ukraine's Black Sea corridor bypass traditional brokers for direct capacity access.
- Agri-Business Firms:Vertically integrated grain traders and processors structuring captive quota-shares to hedge procurement exposure. Black Sea wheat exporters and Brazilian soybean processors lead multi-year treaty innovation.
- Smallholder Farmers:Fragmented landholders with heterogeneous plot conditions and limited yield history, creating basis risk challenges for index products.
- Agricultural Cooperatives:Pooled purchasing entities aggregating coverage across member farms to achieve scale economies in treaty placement.
- Government Agencies:Public-sector risk pools including India's PMFBY implementing agencies and USDA's Risk Management Agency ceding correlated exposures.
Commercial Growers dominate premium volume, while Agri-Business Firms are expanding treaty participation most rapidly.
Application:
Functional use cases determine trigger design, with catastrophe covers requiring broader geographic diversification than yield protection treaties.
- Risk Mitigation:Core reinsurance function transferring correlated agricultural losses from primary balance sheets to specialized carriers.
- Yield Protection:Revenue stabilization against production shortfalls, with satellite-derived agronomy enabling pre-harvest loss forecasting.
- Income Stabilization:Price-yield combination products hedging both quantity and commodity price risk.
- Catastrophe Coverage:Excess-of-loss structures attaching at systemic loss levels, concentrating capacity demand in Bermuda and London ILS markets.
- Disaster Recovery:Post-event liquidity provision through parametric triggers, accelerating capital deployment versus traditional loss adjustment.
Risk Mitigation accounts for the largest treaty flow, with Catastrophe Coverage commanding the steepest expansion trajectory as climate volatility intensifies.
Distribution Channel:
Channel economics reflect customer sophistication, with complex commercial placements favoring advisory relationships and standardized smallholder products migrating toward banking networks.
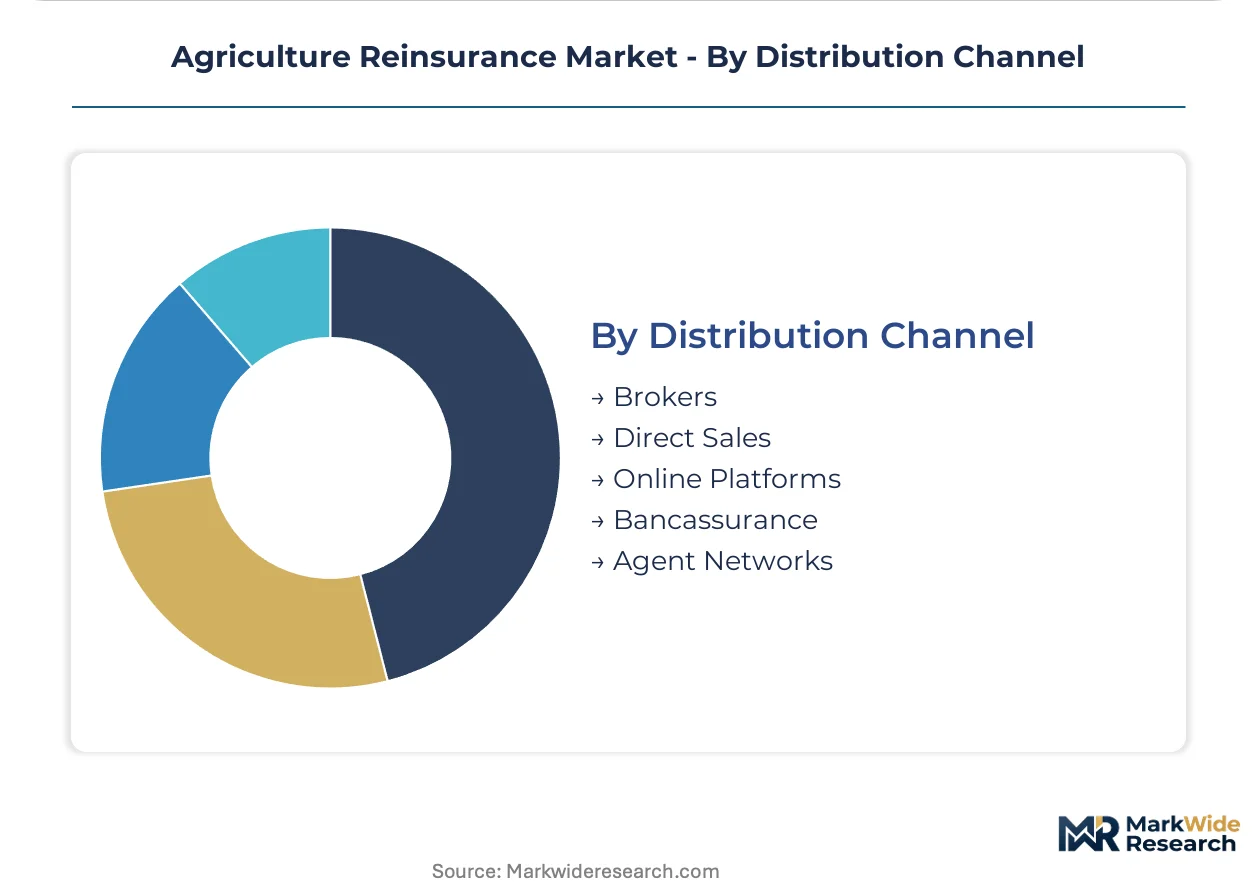
- Brokers:Traditional intermediaries dominating treaty placement for commercial growers and complex multi-peril structures.
- Bancassurance:Rural banking networks in emerging markets disintermediating brokers for smallholder crop coverage, with India's regional rural banks and Brazil's agricultural credit cooperatives leading penetration.
- Direct Sales:Reinsurer-cedent relationships for large agri-business accounts with in-house risk management capabilities.
- Online Platforms:Digital quotation and binding tools for standardized weather-index products with transparent trigger mechanics.
- Agent Networks:Field-based distribution retaining relevance in territories with limited digital infrastructure or complex indemnity verification requirements.
Brokers retain the largest placement share, with Bancassurance gaining ground fastest in emerging market smallholder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting treaty placement flows as carriers seek capacity in markets with lighter climate-disclosure burdens. Cost-of-compliance gaps are widening between EU Green Deal jurisdictions and emerging economies with nascent ESG frameworks.
United States
The USDA's Federal Crop Insurance Corporation mandates minimum coverage standards that cascade into substantial treaty demand. Commercial growers in Iowa and Illinois corn counties are expanding quota-share purchases as drought frequency intensifies across the Corn Belt. Primary carriers cede correlated weather exposures to Bermuda and London capacity providers.
Brazil
El Niño intensification is compressing attachment points across Mato Grosso and Paraná soybean operations. ANVISA-aligned agricultural data standards are enabling satellite-index trigger adoption among commercial growers in the Cerrado region. Vertically integrated processors in Rondonópolis are negotiating direct multi-year treaties with international reinsurers.
India
PMFBY scheme expansion in Punjab and Haryana wheat-growing states is generating structured cession flows through domestic brokers. CEA guidelines mandate minimum retention ratios that concentrate treaty placement through Mumbai and Delhi underwriting hubs. Regional rural banks are disintermediating traditional broker channels for smallholder coverage.
Germany
EU F-Gas Regulation compliance costs are elevating operational expenses for agricultural risk assessments across Bavarian and Lower Saxon dairy regions. Heat-stress index triggers for livestock mortality are displacing traditional veterinary indemnity models. Hannover Re anchors European capacity from its Hanover headquarters.
China
Dual carbon goals under MEE frameworks are embedding climate resilience metrics into provincial agricultural insurance schemes. Yield protection demand concentrates in Heilongjiang corn and soybean belts where satellite-derived agronomy is compressing information asymmetry. Domestic carriers cede catastrophe exposures to international markets.
Agriculture Reinsurance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with capacity providers tiering between global multi-line reinsurers and agricultural-focused niche carriers. Market structure concentrates treaty flow among five dominant carriers controlling parametric platform development and satellite data partnerships. Two strategic archetypes define competitive positioning: integrated climate-risk modelers with proprietary yield forecasting capabilities, and capacity aggregators specializing in livestock mortality and specialty crop treaties. Portfolio diversification into adjacent weather-risk lines and geographic expansion through regional hub establishment represent the dominant competitive moves.
Among European-headquartered carriers, Swiss Re and Munich Re exemplify the integrated climate-risk archetype through their agricultural risk modeling divisions and parametric weather-index platforms. Hannover Re occupies a position within the specialty treaty tier, anchoring capacity for livestock mortality structures in European dairy regions. These three carriers collectively represent the premium-tier vector where satellite-triggered settlements and automated loss adjustment capabilities differentiate placement terms.
| Leading Market Players |
|---|
| Swiss Re |
| Munich Re |
| Hannover Re |
| PartnerRe |
| SCOR |
| Everest Re |
| Berkshire Hathaway |
| Sompo International |
| Allianz Re |
| Others |
Pricing and Supply Chain Analysis
Parametric weather-index platforms are compressing loss adjustment expenses while concentrating treaty placement power among carriers with proprietary satellite data partnerships. This technological shift simultaneously reduces operational costs for automated settlements and elevates barriers for reinsurers lacking direct Sentinel-2 or MODIS feed integrations.
Pricing Analysis
Broker commission layers dominate placement economics, with traditional intermediaries capturing margin on commercial grower treaties while bancassurance channels compress fees for smallholder products. Three-tier pricing structure across premium, standard, and economy levels reflects data sophistication: commercial growers with precision agriculture streams command preferential terms, smallholders face basis risk premiums, and government scheme cessions carry mandated retention ratios. Pricing pressure stems from buyer consolidation among Brazilian soybean processors and Black Sea grain traders negotiating direct multi-year treaties. Agri-business conglomerates exhibit lowest price sensitivity due to captive procurement hedging needs, while fragmented smallholders in India's wheat belt remain most cost-conscious.
Supply Chain Analysis
Satellite imagery supply rests on European Space Agency Sentinel-2 constellations, NASA MODIS platforms, and commercial providers in the United States. Treaty capacity draws from Bermuda ILS markets, London Lloyd's syndicates, and continental European carriers in Germany and Switzerland. Raw material dependencies include meteorological data feeds, yield history databases, and soil moisture sensor networks. Single-source vulnerability concentrates in satellite ground station infrastructure for real-time trigger verification. Distribution runs through broker networks for complex commercial placements, bancassurance partnerships for emerging market smallholders, and direct reinsurer relationships for vertically integrated agri-business accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in agriculture reinsurance hinges on satellite-triggered automation reducing loss adjustment costs, while premium-tier differentiation rewards carriers with proprietary yield modeling capabilities.
For Market Incumbents: To counter buyer consolidation among Brazilian soybean processors and Black Sea grain traders, Swiss Re and Munich Re should deepen direct treaty relationships through multi-year parametric platforms. Hannover Re can anchor livestock mortality capacity in European dairy regions via heat-stress index specialization. Investment in climatology-actuarial hybrid talent pools represents the critical defensive lever against model obsolescence. For New Entrants and Emerging Players: Enter via India's PMFBY scheme expansion in Punjab and Haryana, where structured cession requirements create captive treaty flow through domestic brokers. Livestock parametrics in European heat-stress zones offer white-space penetration with lower incumbent saturation. Bancassurance channel partnerships with regional rural banks provide the most scalable go-to-market angle for smallholder coverage. For Investors and Strategic Acquirers: Valuations sit cheapest among agricultural niche carriers lacking satellite data partnerships but holding established livestock or specialty crop treaties. Long-term viability favors integrated climate-risk modelers with proprietary yield forecasting over pure capacity aggregators. Watch for inflection in catastrophe bond issuance volumes for agricultural risk as the signal of ILP market depth expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Platform Development | Automated satellite-triggered settlements displace traditional indemnity structures in Brazil's Cerrado region. |
| Satellite Data Partnership | Direct Sentinel-2 feed integrations compress information asymmetry between cedents and reinsurers. |
| Livestock Mortality Specialization | Heat-stress index triggers open capacity in European dairy regions facing veterinary indemnity margin compression. |
| Bancassurance Channel Expansion | Rural banking networks in India disintermediate traditional brokers for PMFBY-mandated smallholder coverage. |
| Climate-Resilient Portfolio Allocation | EU Green Deal carbon sequestration metrics reshape capital allocation toward regenerative farming treaties. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with treaty underwriters, agricultural risk modelers, broker placement specialists, and primary insurer cession managers alongside secondary validation. Sources included regulatory filings from USDA's Risk Management Agency and India's CEA, reinsurance treaty disclosure databases, satellite agronomy research from European Space Agency technical documentation, and customs data on agricultural commodity flows. Bottom-up treaty flow analysis and top-down capacity allocation modeling provided triangulation across estimation approaches.
Historical reference periods anchored yield variance trends and premium volume trajectories to establish baseline correlation structures across the modeling period. Segmentation dimensions encompassed product type, customer archetype, application function, and distribution channel, with additional modeling of parametric trigger adoption rates. CAGRs derived from curve-fitting historical treaty growth patterns against projected climate volatility intensification. Forecast inputs incorporated El Niño cycle projections and regulatory scheme expansion timelines for India's PMFBY.
The model holds under stable regulatory mandate continuity and satellite data feed reliability; deviation in climate disclosure rule stringency under CSRD or SEC frameworks would shift capacity allocation patterns. Treaty renewal pricing volatility from ILS investor concentration represents the primary revision risk. A small set of named triggers warrants ongoing watch: catastrophe bond issuance volumes for agricultural risk, parametric trigger adoption rates among commercial growers, and bancassurance penetration metrics in emerging market wheat belts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Travel Insurance Market
Insurance
Djibouti Insurance Market
Insurance
Telematics-Based Auto Insurance Market
Insurance
Term Insurance Market
Insurance
Digital Monetary Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
United States Dental Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Europe Health Insurance Market
Insurance
Insurance Aggregators Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Global Home Insurance Market