
 Takaful Insurance Market | 2026-2036
Takaful Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Takaful Insurance Market Intelligence
Market Context with Strategic Players
Malaysia's Risk-Based Capital Framework for Takaful is consolidating operational standards across ASEAN markets and compelling insurers to strengthen capital reserves. SALAMA Islamic Arab Insurance Company leverages its Gulf-centric distribution network to sustain premium growth in family protection lines. Great Eastern Takaful Berhad anchors Southeast Asian market presence through bancassurance partnerships with regional banking networks. Etiqa competes aggressively on digital onboarding infrastructure, while Syarikat Takaful Malaysia dominates the Malaysian general Takaful segment through motor and fire coverage specialization.
Technical Definition and Structural Segments
Takaful is a cooperative risk-sharing mechanism grounded in Islamic principles of mutual assistance (taawun) and donation (tabarru), where participants contribute to a pooled fund managed by an operator under Shariah supervision, with surplus distributed according to pre-agreed ratios rather than transferred as profit to shareholders. The primary commercial purpose is to provide Shariah-compliant alternatives to conventional insurance, eliminating gharar (excessive uncertainty), maysir (gambling), and riba (interest) from contractual structures. Family Takaful leads product type segmentation by premium volume, reflecting demographic youth bulges and hajj/umrah savings-linked endowment demand across Muslim-majority economies. General Takaful registers the fastest structural growth in motor and property lines, particularly where regulatory mandates replace conventional coverage. Bancassurance controls the dominant distribution channel position in Malaysia and Indonesia, though online platforms are displacing traditional broker networks among digitally native customer segments in urban Gulf markets.
Regulatory Frame and Forward Outlook
Bank Negara Malaysia's Shariah Governance Framework, the UAE Insurance Authority's Takaful regulations, and Indonesia's OJK Shariah product standards collectively shape capital adequacy, investment compliance, and market access requirements across the industry's core geographies. These frameworks mandate Shariah board oversight, restrict conventional reinsurance cessions, and prescribe segregated participant and shareholder funds, directly influencing product architecture and operational cost structures. Stakeholders must monitor evolving Islamic fintech licensing regimes and cross-border Takaful passporting negotiations, as regulatory harmonization between Gulf Cooperation Council and ASEAN jurisdictions will determine scalable expansion pathways for operators seeking multi-market footprint without redundant capital localization.
Market Dynamics
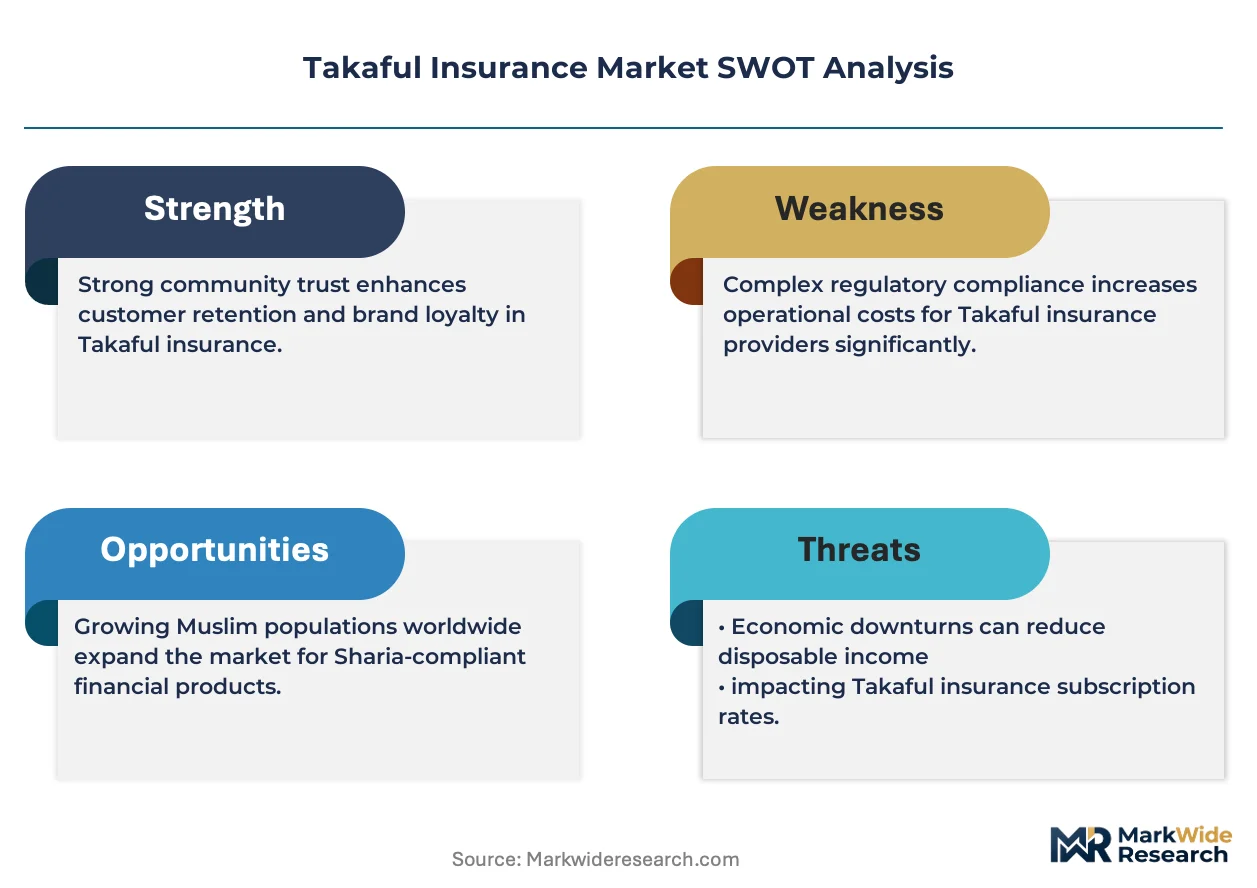
Bank Negara Malaysia's tightening Shariah Governance Framework is forcing Takaful operators across ASEAN to restructure capital reserves and accelerate digital infrastructure deployment, compressing operational timelines for compliance while opening competitive gaps between capitalized and undercapitalized players.
Growth Catalysts
- Indonesia's OJK Shariah Mandates:Regulatory requirements for state-owned enterprises to convert conventional coverage to Takaful products are creating mandatory policyholder migrations in the archipelago's public sector.
- Blockchain-Enabled Smart Takaful Contracts:Distributed ledger implementations for automated claims processing and surplus distribution are reducing operational overhead and accelerating participant fund transparency.
- Malaysia's Risk-Based Capital Framework:Stricter solvency requirements are consolidating market share among well-capitalized operators while eliminating marginal competitors.
Market Restraints
- Shariah Scholar Scarcity:Qualified Islamic jurists capable of certifying complex Takaful products command premium retainers, inflating compliance costs for smaller operators.
- Reinsurance Capacity Constraints:Limited availability of Shariah-compliant retakaful capacity in Gulf Cooperation Council markets forces operators to retain catastrophic risk or accept conventional reinsurance with structural modifications.
- Investment-Grade Sukuk Pipeline:Restricted supply of Shariah-compliant securities suitable for Takaful fund deployment compresses investment yields and constrains surplus distribution capacity.
Strategic Opportunities
- Bangladesh Rural Penetration:Micro-Takaful products distributed through agricultural cooperatives and mobile network operator partnerships address unbanked populations in the country's delta regions.
- Embedded Takaful APIs:Integration of parametric coverage into ride-hailing, e-commerce, and gig-economy platforms enables point-of-transaction policy activation without traditional distribution overhead.
- Saudi Arabia's Vision 2030 Financial Sector Development Program:State-backed incentives for Islamic fintech licensing and regulatory sandbox participation lower barriers for digital-native Takaful entrants.
Industry Challenges
- Actuarial Talent Specialized in Takaful Mathematics:Shortage of professionals trained in participant risk pooling, surplus distribution modeling, and Shariah-compliant reserving methodologies constrains product innovation cycles.
- Legacy Core System Migration:Decades-old policy administration platforms require costly replacement to support real-time participant fund segregation and automated Shariah compliance reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Takaful Insurance Market |
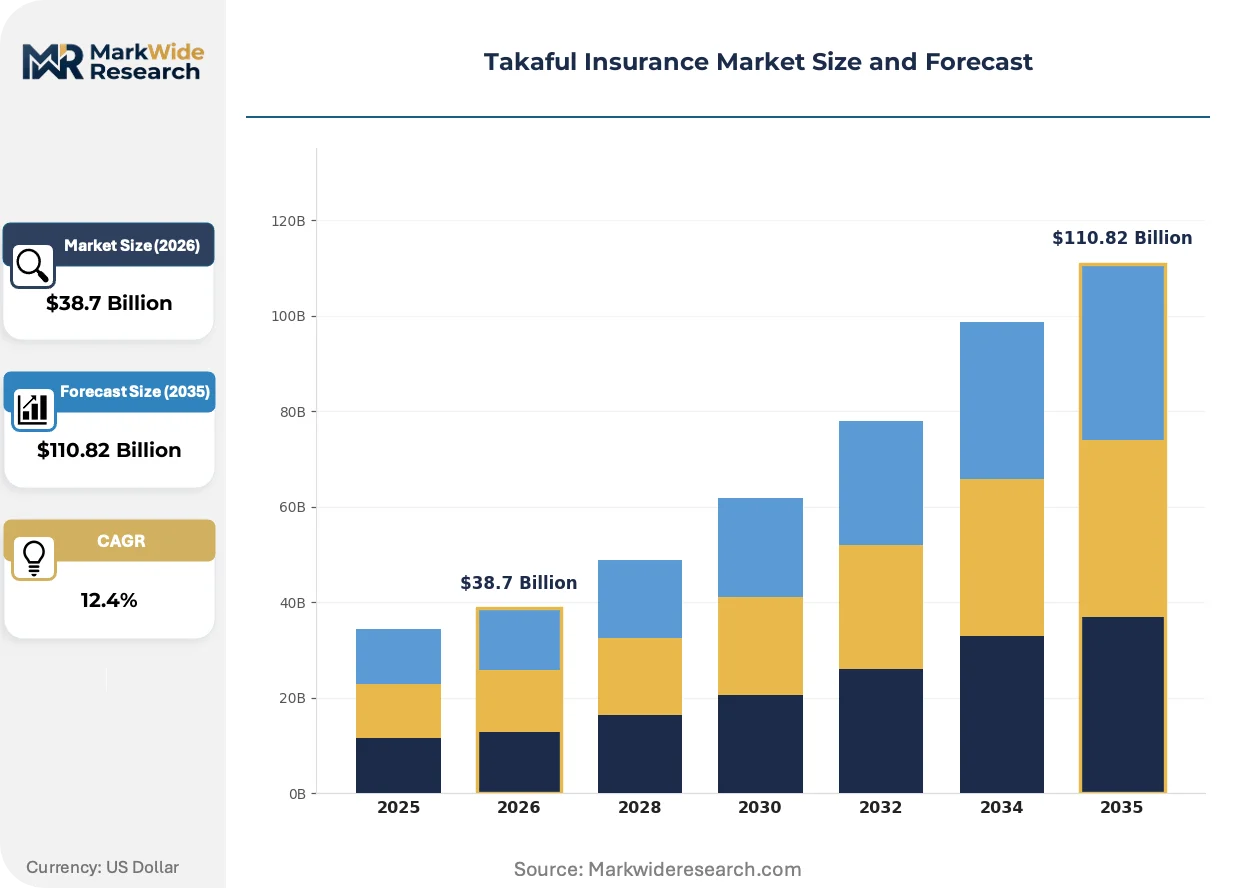
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $110.82 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Family Takaful, General Takaful, Investment Takaful, Health Takaful Distribution Channel: Direct Sales, Brokers, Online Platforms, Bancassurance Customer Type: Individuals, Corporates, SMEs, Non-profit Organizations Investment Strategy: Shariah-compliant Funds, Conventional Funds, Hybrid Funds, Sukuk |
| Companies Covered | SALAMA Islamic Arab Insurance Company, Great Eastern Takaful Berhad, Abu Dhabi National Takaful, Takaful Emarat, Qatar Islamic Insurance Company, Etiqa, Prudential BSN Takaful, Gulf Insurance Group, Syarikat Takaful Malaysia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Takaful Insurance Market Strategic Shifts & Innovations
Digitization is restructuring Takaful value chains from participant onboarding through claims settlement, with artificial intelligence and distributed infrastructure compressing operational costs while regulatory technology mandates accelerate competitive differentiation between technology-native and legacy-dependent operators.
Blockchain-based smart contracts are decentralizing claims adjudication and surplus distribution processes across family Takaful lines. Southeast Asian operators in Malaysia and Indonesia are deploying these systems to automate tabarru fund allocations and participant payouts without centralized administrative intervention. This architecture is decentralizing trust mechanisms previously concentrated in operator-controlled governance structures, enabling direct participant oversight of pooled fund movements.
The UAE Insurance Authority's Takaful regulations now mandate segregated participant and shareholder accounting with quarterly Shariah compliance attestation. Operators must maintain distinct investment portfolios for each fund type, with restricted asset classes and prohibited income purification protocols. General Takaful motor lines face the steepest compliance burden, with operators restructuring product architectures to eliminate conventional reinsurance dependencies.
Young Muslim households in urban Indonesian centers are bypassing traditional bancassurance channels for direct-to-consumer mobile platforms. These digitally native buyers prioritize transparent surplus-sharing mechanisms and instant policy customization over relationship-based sales. The shift is most pronounced in Jakarta and Surabaya, where smartphone penetration enables fully digital onboarding without physical branch interaction.
Takaful Insurance Market Segmentation
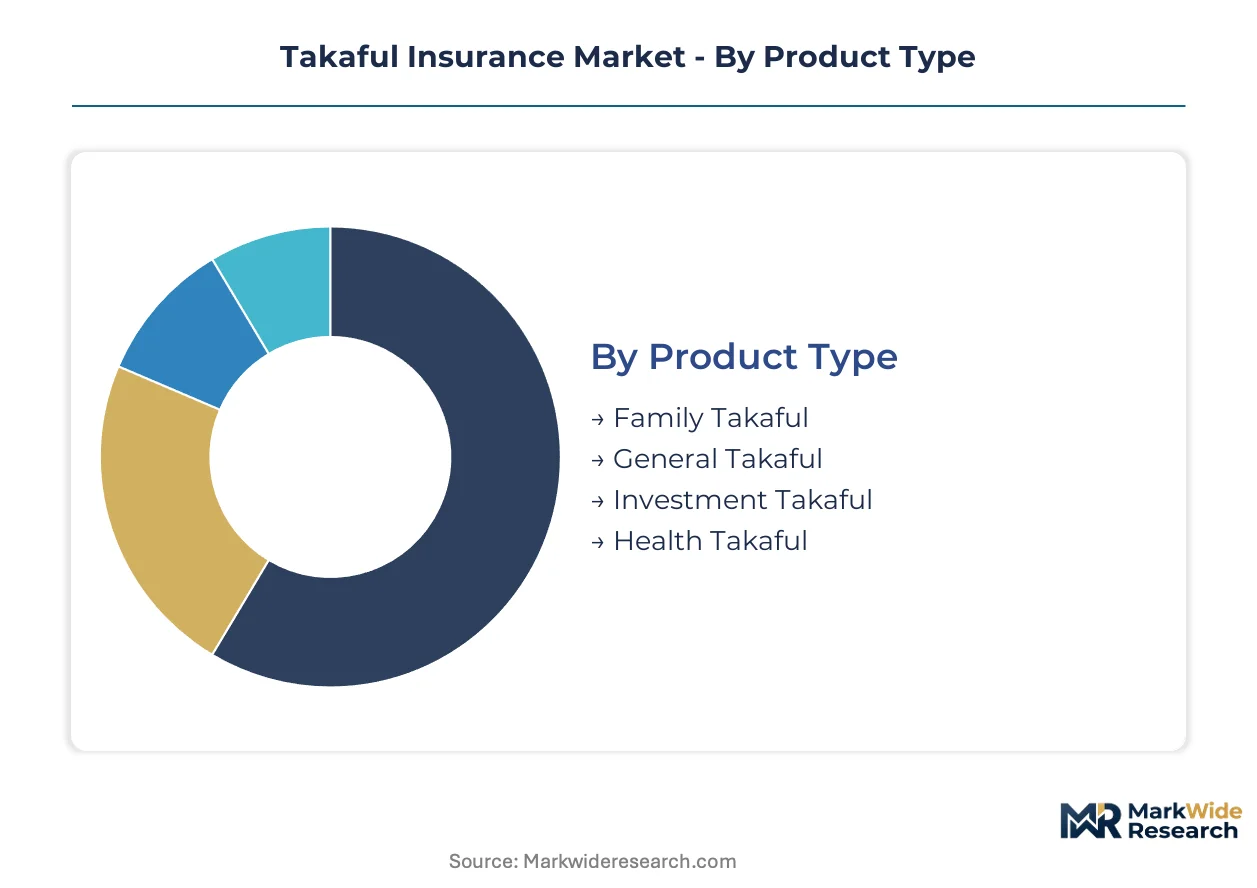
Takaful operators structure product portfolios around Shariah compliance requirements, distribution economics, and participant risk profiles. Segmentation choices directly determine capital reserve calculations, regulatory filing obligations, and surplus distribution mechanics across family and general lines.
Product Type:
Buyers differentiate primarily by protection horizon and savings linkage, with hajj/umrah endowment demand pulling toward longer-duration contracts.
- Family Takaful:Combines term protection with participant investment accounts structured as mudarabah or wakala contracts. Young Muslim households in Indonesia's urban corridors are migrating from conventional endowments to Shariah-compliant alternatives with transparent surplus-sharing ratios.
- General Takaful:Covers motor, property, and liability risks through short-term tabarru-based pooling. Malaysia's mandatory motor coverage conversion is accelerating policyholder migrations from conventional insurers.
- Investment Takaful:Unit-linked structures with equity participation in Shariah-screened securities attract affluent participants seeking wealth accumulation with religious compliance.
- Health Takaful:Medical expense pooling with takaful operator administration serves gaps in state healthcare coverage across Gulf Cooperation Council jurisdictions.
Family Takaful leads volumes today; General Takaful is gaining share fastest.
Distribution Channel:
Channel economics vary sharply by customer acquisition cost and regulatory capital treatment for prepaid commission structures.
- Bancassurance:Dominates premium flow in Malaysia and Indonesia through captive banking networks with embedded Shariah product shelf space.
- Online Platforms:Mobile-first onboarding with instant tabarru contribution calculations is displacing branch networks among Jakarta and Kuala Lumpur millennials.
- Brokers:Independent intermediaries retain relevance in commercial general Takaful placements requiring complex risk engineering.
- Direct Sales:Operator-employed agents sustain penetration in rural Bangladesh and Indonesian archipelago regions with limited banking infrastructure.
Bancassurance captures the largest premium share; Online Platforms are climbing the fastest.
Customer Type:
Risk pooling scale and surplus distribution frequency diverge significantly between individual and institutional participant structures.
- Individuals:Household-level family Takaful participation concentrates premium flow in protection-plus-savings hybrids with hajj liquidity features.
- Corporates:Group medical and term coverage for employee benefits mandates Shariah-compliant alternatives to conventional group life in Malaysia's public sector.
- SMEs:Micro-enterprise general Takaful for fire and business interruption addresses underpenetrated merchant classes in Indonesia's provincial cities.
- Non-profit Organizations:Cooperative and waqf-based entities seek participant-governed risk pools with direct surplus allocation control.
Individuals dominate premium volumes; SMEs show the steepest expansion trajectory.
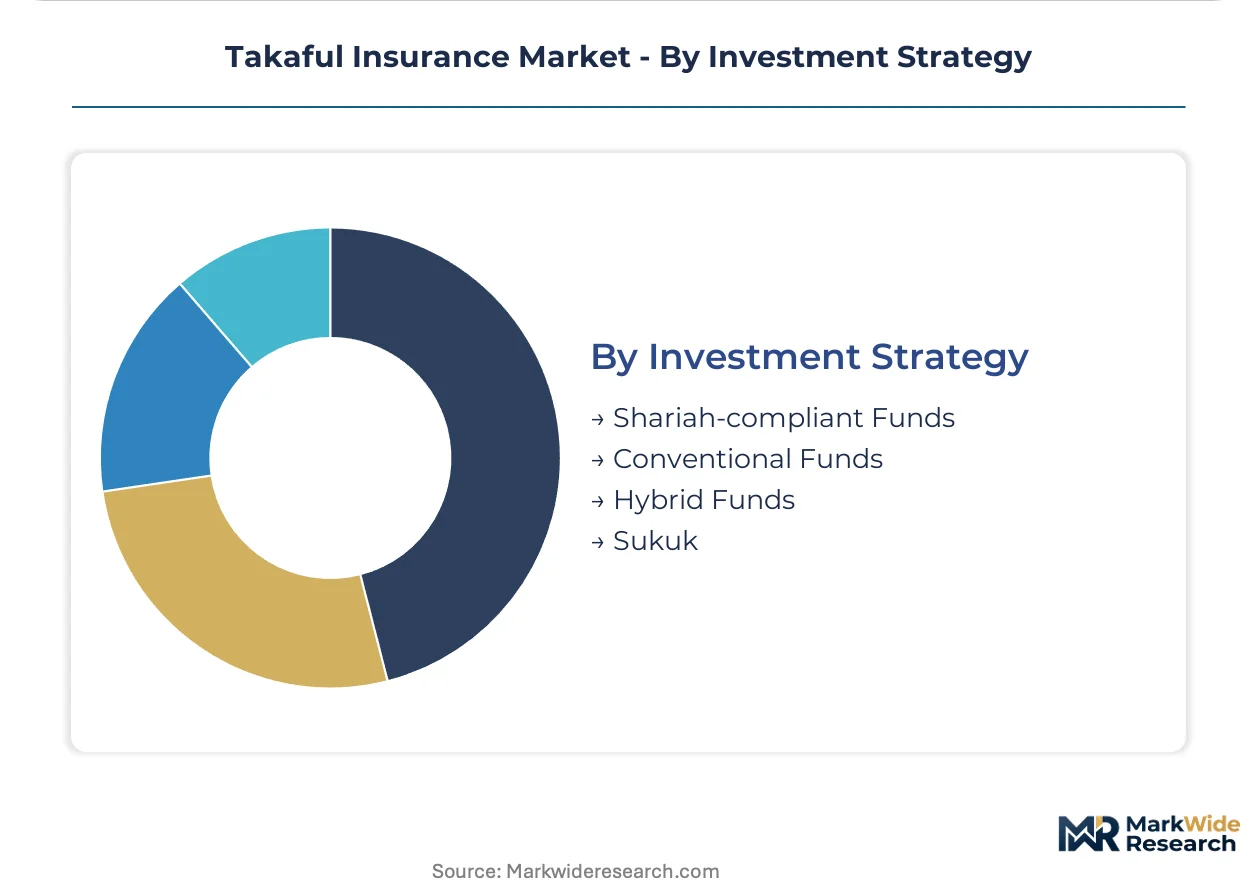
Investment Strategy:
Fund segregation requirements and prohibited income purification protocols constrain deployable asset classes and yield compression.
- Shariah-compliant Funds:Equity portfolios screened for debt-to-asset ratios and non-halal revenue exposure support participant account growth with religious compliance.
- Sukuk:Islamic bond instruments provide fixed-income exposure without interest-bearing structures, though supply constraints limit large-scale deployment.
- Hybrid Funds:Blended conventional and Shariah-compliant allocations with income purification mechanisms appeal to operators seeking yield enhancement within regulatory tolerance.
- Conventional Funds:Non-compliant assets held temporarily during portfolio transition or for shareholder fund portions subject to takaful structure.
Shariah-compliant Funds anchor current allocations; Sukuk is gaining preference fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Takaful insurance originated in Sudan during the late 1970s before scaling through Malaysia's regulatory codification in the 1980s. The industry's geographic footprint now spans Gulf Cooperation Council financial centers and Southeast Asian Muslim-majority economies with distinct regulatory maturities.
Malaysia
Family Takaful penetration among young Muslim households accelerates through bancassurance partnerships with Maybank and CIMB networks. Bank Negara Malaysia's Risk-Based Capital Framework and Shariah Governance Framework mandate segregated participant funds with quarterly compliance attestation. Kuala Lumpur's financial district hosts Etiqa and Syarikat Takaful Malaysia headquarters, where operators deploy digital onboarding infrastructure to capture millennial policyholders.
Indonesia
Unpenetrated rural populations and government financial inclusion mandates create new policyholder pools across the archipelago. OJK Shariah product standards require state-owned enterprises to convert conventional coverage to Takaful alternatives, forcing mandatory migrations in the public sector. Jakarta and Surabaya concentrate mobile-first distribution, where smartphone penetration enables fully digital onboarding without branch interaction.
Saudi Arabia
Vision 2030 Financial Sector Development Program incentivizes Islamic fintech licensing through regulatory sandbox participation. The central bank's SAMA oversees Takaful capital adequacy requirements while lowering barriers for digital-native entrants. Riyadh anchors family protection line growth, with operators targeting hajj and umrah savings-linked endowment demand among pilgrim households.
United Arab Emirates
The UAE Insurance Authority's Takaful regulations prescribe segregated participant and shareholder accounting with restricted asset classes for each fund type. Dubai International Financial Centre hosts retakaful capacity providers serving regional cession needs. Abu Dhabi National Takaful and Takaful Emarat compete on Shariah board credibility and surplus distribution transparency in the emirates' saturated protection markets.
Qatar
Qatar Central Bank's Islamic finance regulations enforce Shariah compliance across domestic Takaful operations with strict investment screening protocols. Doha's liquefied natural gas revenue concentration generates corporate group medical and term coverage demand for expatriate workforces. Qatar Islamic Insurance Company leverages captive energy sector relationships to sustain premium flow in general Takaful lines.
Takaful Insurance Market Key Industry Players
Premium-margin players sit above commodity-margin players across Shariah governance credibility and digital infrastructure sophistication. The market consolidates around well-capitalized operators with captive banking distribution, while smaller competitors face elimination under tightening solvency requirements. Three archetypes dominate: Gulf-centric specialists with retakaful network access, ASEAN bancassurance-anchored conglomerates, and digital-native challengers with API-first distribution. Competitive dynamics center on M&A consolidation of undercapitalized operators and strategic partnerships with Islamic fintech platforms for embedded coverage integration.
Among Gulf-based specialists, SALAMA Islamic Arab Insurance Company and Qatar Islamic Insurance Company exemplify the retakaful-network-dependent archetype, sustaining premium growth through regional reinsurance reciprocity arrangements. In the ASEAN tier, Great Eastern Takaful Berhad and Syarikat Takaful Malaysia occupy positions defined by bancassurance captive channels and motor coverage specialization respectively. Etiqa represents the digital infrastructure vector, competing through automated onboarding and real-time participant fund transparency tools.
| Leading Market Players |
|---|
| SALAMA Islamic Arab Insurance Company |
| Great Eastern Takaful Berhad |
| Abu Dhabi National Takaful |
| Takaful Emarat |
| Qatar Islamic Insurance Company |
| Etiqa |
| Prudential BSN Takaful |
| Gulf Insurance Group |
| Syarikat Takaful Malaysia |
| Others |
Cost & Logistics Intelligence
Shariah scholar scarcity concentrated in Gulf Cooperation Council financial centers widens pricing spreads between premium-certified and standard-tier Takaful products, as labor-cost differentials for qualified jurists cascade through compliance overhead structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates participants by Shariah board reputation and surplus distribution transparency. Price differentiation hinges on certification grade from recognized Gulf-based scholars and digital infrastructure sophistication. Pricing pressure stems from Bank Negara Malaysia's Risk-Based Capital Framework compressing margins for undercapitalized operators. SMEs exhibit highest price sensitivity, while affluent hajj-savings participants tolerate premium tiers for scholar credibility.
Supply Chain Analysis
Retakaful capacity flows and surplus distribution returns concentrate operational complexity in Malaysia, Saudi Arabia, and the UAE. Sukuk issuance pipelines and Shariah-compliant securities sourcing draw from Gulf debt markets and Malaysian sovereign issuance. Single-source vulnerability in qualified retakaful providers forces catastrophic risk retention. Distribution runs through bancassurance partnerships with Maybank and CIMB networks anchoring premium flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in digital onboarding automation and Shariah governance cost compression, as cloud-native infrastructure displaces legacy system maintenance burdens.
For Market Incumbents: To counter digital-native entrants with API-first distribution, Etiqa and Syarikat Takaful Malaysia should deepen captive banking channel control through exclusive Maybank and CIMB shelf-space agreements, while accelerating blockchain-enabled smart contract deployment for automated tabarru fund management. For New Entrants and Emerging Players: Launch via embedded Takaful APIs in ride-hailing and e-commerce platforms to capture Jakarta and Surabaya millennials bypassing traditional bancassurance. Micro-Takaful cooperatives in Bangladesh's delta regions offer lowest competitive density for agricultural risk pooling partnerships. For Investors and Strategic Acquirers: Islamic fintech platforms with regulatory sandbox licenses are the most active acquirer in this space, targeting undercapitalized operators facing Bank Negara Malaysia solvency compression. Monitor OJK mandate enforcement velocity in Indonesian state-owned enterprise conversions as inflection indicator for mandatory policyholder migration volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Smart Contract Deployment | Automated tabarru allocation reduces Shariah compliance overhead for Malaysian operators. |
| Retakaful Network Expansion | Gulf-based reciprocity arrangements unlock catastrophic risk capacity for ASEAN general lines. |
| Embedded API Integration | Point-of-transaction activation captures Jakarta millennials without branch infrastructure. |
| Shariah Scholar Certification Investment | Premium-tier pricing power rests on Bank Negara Malaysia-recognized board credibility. |
| Micro-Takaful Cooperative Partnership | Bangladesh agricultural network access penetrates unbanked rural policyholder pools. |
Research Approach
Direct dialogue with Takaful operators' Shariah compliance officers, digital transformation leads, and bancassurance partnership directors grounded qualitative findings, cross-referenced with Bank Negara Malaysia regulatory filings, OJK product registration databases, and UAE Insurance Authority capital adequacy disclosures. Bottom-up policyholder segmentation data triangulated against top-down premium flow estimates from regional banking network disclosures.
Market size outputs across the projection horizon reflect modeled trajectories for family, general, investment, and health Takaful lines, with distribution channel splits between bancassurance, online platforms, brokers, and direct sales. CAGRs derived from historical premium growth patterns, regulatory mandate implementation schedules, and smartphone penetration diffusion curves in Indonesian urban corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Shariah scholar supply shocks or retakaful capacity contractions. Practitioners should monitor OJK enforcement timelines and SAMA sandbox licensing velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Financial Protection Market
Insurance
Peru Insurance Market
Insurance
India Property & Casualty Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
Dental Insurance Market
Insurance
Crop Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Event Insurance Market
Insurance
Umbrella Insurance Market
Insurance
Insurance Third Party Administrators Market
Insurance
Europe Health Insurance Market
Insurance
Microinsurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
Global Flood Insurance Market
Insurance
United Kingdom Car Insurance Market