
 Earthquake Insurance Market | 2026-2036
Earthquake Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Earthquake Insurance Market Analysis
Actuarial talent with catastrophe modeling expertise is rotating toward parametric and sensor-integrated underwriting platforms, tightening availability for traditional indemnity teams. Chubb Ltd. Group leverages its global facultative reinsurance relationships to anchor capacity in high-exposure West Coast markets. Travelers Group sustains competitive positioning through proprietary geospatial risk scoring that differentiates its commercial portfolio selection.
Earthquake insurance constitutes a specialized property and casualty contract that transfers seismic risk from policyholders to carriers through defined peril triggers, typically incorporating deductibles of 10-15 percent of insured value and sub-limits for contents and additional living expenses. Its primary commercial purpose is to restore capital solvency for mortgage lenders and property investors following fault-rupture events that standard homeowner policies exclude. Residential policy types dominate premium volume in mature markets, while commercial and industrial segments concentrate margin pools where business interruption endorsements attach. Structural coverage commands the highest attachment frequency, though full coverage packages are expanding fastest in new markets as lenders mandate comprehensive peril protection.
California Earthquake Authority operates under state-enacted rate oversight from the California Department of Insurance, while Japan's Non-Life Insurance Rating Organization of Japan files standardized rates subject to Financial Services Agency approval. The National Flood Insurance Program's post-event borrowing authority at the U.S. Treasury indirectly shapes congressional appetite for federal earthquake backstop legislation. Stakeholders must monitor whether parametric trigger designs gain regulatory acceptance as alternatives to indemnity-based loss adjustment, since this determination will reshape capital requirements and distribution economics for carriers and MGAs alike.
Market Dynamics
Parametric trigger designs are displacing traditional indemnity adjustment in high-frequency seismic corridors, compressing claims settlement cycles from months to days and rewiring carrier capital requirements.
Growth Catalysts
- California's Mandatory Disclosure Laws:Property transaction rules force seismic risk visibility, accelerating residential policy uptake in fault-adjacent counties.
- Sensor-Integrated Underwriting:Real-time ground-motion monitoring enables dynamic pricing models that expand addressable risk pools beyond historical actuarial boundaries.
- Tokai-Kanto Corridor Concentration:Japan's dense commercial infrastructure and private-public partnership frameworks sustain premium volume expansion in the world's most seismically active economic zone.
Market Restraints
- Reinsurance Capacity Volatility:Catastrophe bond spreads and collateralized reinsurance pricing fluctuate with North Atlantic hurricane season correlations, squeezing primary carrier margins.
- Actuarial Talent Scarcity:Catastrophe modeling specialists are migrating to parametric platforms, leaving traditional indemnity teams understaffed for complex structural damage assessment.
- Federal Backstop Absence:Congressional reluctance to extend Treasury borrowing authority to seismic perils, unlike the National Flood Insurance Program, limits market depth in high-exposure zones.
Strategic Opportunities
- Mexico's Underpenetrated Pacific Coast:Guerrero Gap exposure and nascent mortgage securitization create first-mover advantages for parametric residential products.
- New Zealand's Residential Retrofit Mandates:Government subsidies for base-isolation and structural reinforcement generate bundled coverage opportunities linking engineering to insurance.
- Blockchain-Enabled Smart Contracts:Automated parametric payouts via distributed ledger technology reduce fraud verification costs and administrative overhead for carriers.
Industry Challenges
- Legacy System Integration:Core policy administration platforms require costly middleware development to ingest real-time seismic sensor feeds and execute instant claims triggers.
- Geospatial Data Standardization:Inconsistent fault mapping granularity across national geological surveys complicates cross-border portfolio risk aggregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earthquake Insurance Market |
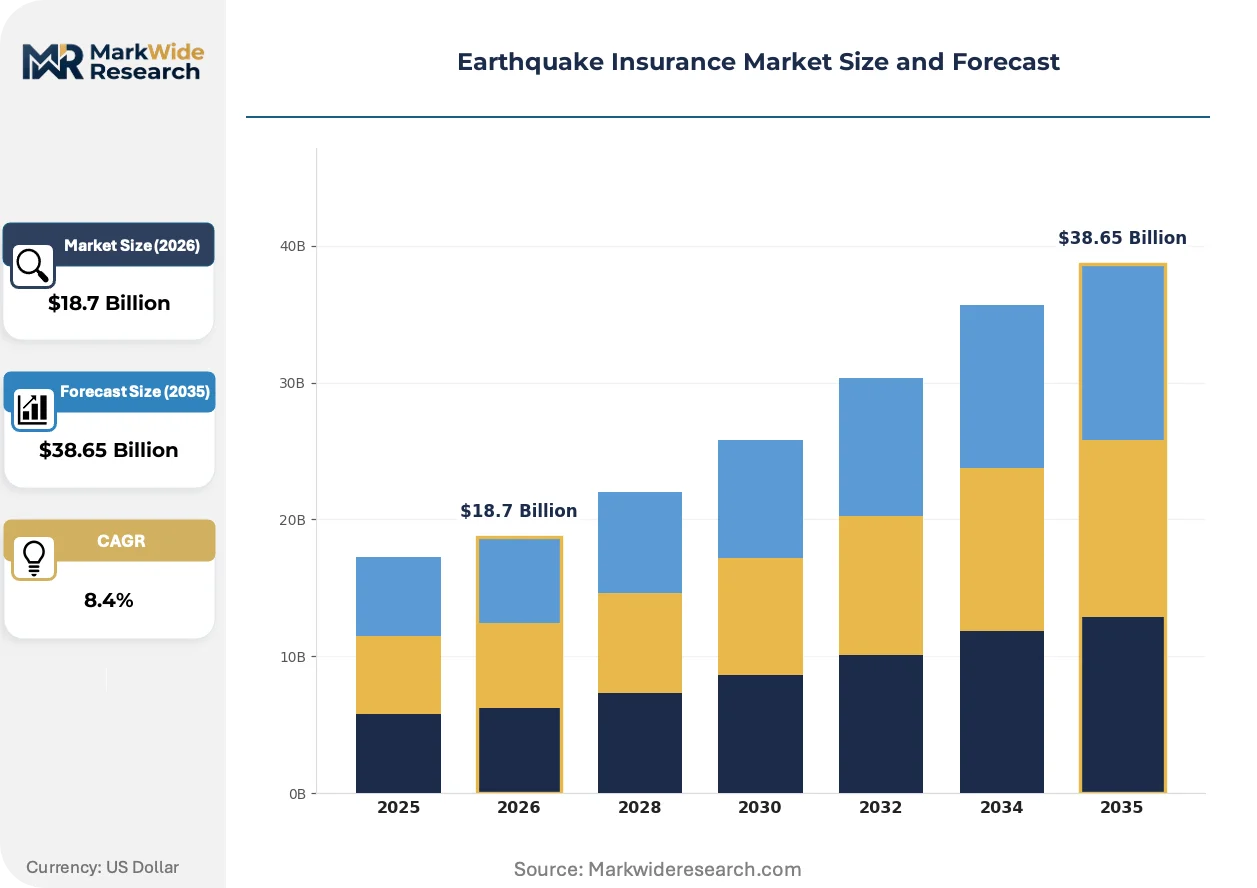
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Structural, Non-Structural, Full Coverage, Limited Coverage Policy Type: Residential, Commercial, Industrial, Government Premium Payment Mode: Annual, Semi-Annual, Monthly, One-Time Claim Process: Standard, Fast-Track, Direct Pay, Dispute Resolution |
| Companies Covered | Chubb Ltd. Group, Travelers Group, California Earthquake Authority, Palomar Specialty Insurance Co., GeoVera Holdings Inc. Group, State Farm Group, American International Group, Liberty Mutual Group, Zurich Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earthquake Insurance Market Emerging Trajectories
Seismic risk transfer mechanisms are fragmenting across indemnity, parametric, and hybrid architectures, with sensor density and algorithmic trigger design becoming primary competitive differentiators.
Internet-of-Things accelerograph networks are miniaturizing. These embedded ground-motion sensors transmit millisecond-resolution data to cloud-based underwriting engines. Commercial property managers in Japan and California are retrofitting portfolios with dense sensor arrays. The technology is miniaturizing capital deployment timelines and enabling real-time exposure management that static risk maps cannot replicate.
Japan's Financial Services Agency is tightening approval standards for parametric trigger designs that deviate from standardized loss adjustment protocols. Carriers must demonstrate correlation between sensor-triggered payouts and actual structural damage through empirical validation studies. Commercial earthquake riders in the Tokai corridor face extended filing timelines as regulators scrutinize basis risk disclosures.
Mortgage lenders are unbundling seismic coverage from standard property policies and mandating standalone earthquake endorsements as loan conditions. This procurement pattern shift concentrates buyer power with institutional originators rather than dispersed homeowners. Wholesale distribution channels connecting carriers to lender platforms are displacing retail agency relationships in California, Texas, and Washington state corridors.
Earthquake Insurance Market Segmentation
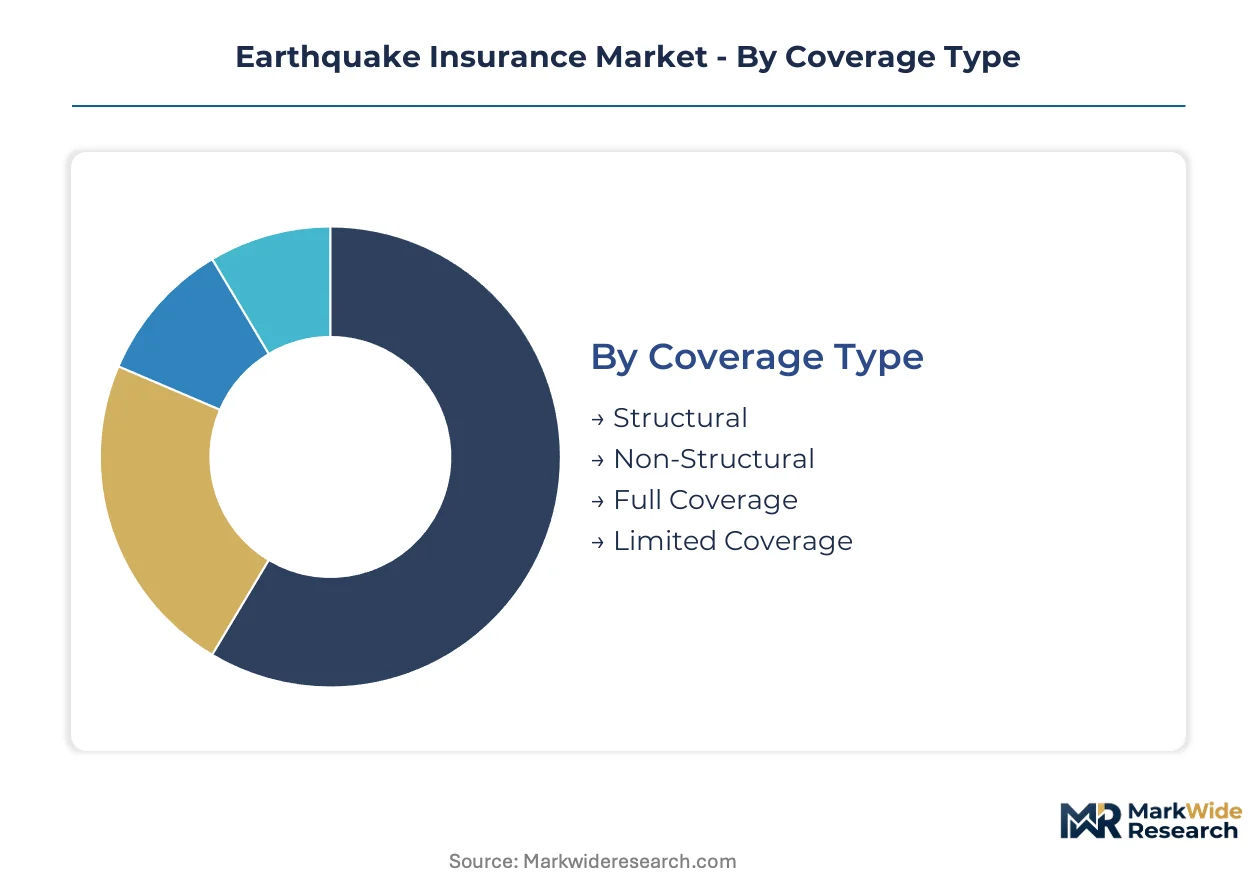
Earthquake insurance markets fragment across coverage scope, policyholder type, payment structure, and claims mechanics. Each dimension shapes carrier capital requirements, distribution economics, and regulatory filing obligations differently.
Coverage Type:
Structural coverage dominates domestic premium pools in California and Japan, while full coverage packages concentrate export-led demand from mortgage securitization platforms in Mexico and Chile.
- Structural:Protects load-bearing elements, foundations, and permanent fixtures against fault-rupture damage. California Earthquake Authority filings show this segment absorbing the majority of residential premium volume in fault-adjacent counties where lender mandates are strictest.
- Full Coverage:Bundles structural, contents, and additional living expense protections in a single contract. Japanese commercial property managers in the Tokai corridor are driving fastest uptake as Financial Services Agency disclosure rules tighten.
- Non-Structural:Covers interior systems, equipment, and tenant improvements without load-bearing protection. Demand concentrates in commercial lease structures where landlords shift improvement risk to occupants.
- Limited Coverage:Applies sub-limits and named-peril restrictions to reduce premium exposure. Emerging markets with nascent mortgage securitization use this tier for entry-level affordability.
Structural coverage holds the largest share; momentum sits with full coverage packages.
Policy Type:
Residential policies generate volume through lender-mandated procurement, while commercial and industrial segments command margin premiums where business interruption endorsements attach.
- Residential:Single-family and multi-unit dwelling contracts with standardized deductibles. California's mandatory disclosure laws in property transactions are accelerating uptake in Los Angeles, San Francisco, and San Diego metropolitan corridors.
- Commercial:Office, retail, and hospitality properties with customizable sub-limits. Japan's private-public partnership frameworks sustain penetration in Osaka and Nagoya commercial districts where sensor-integrated underwriting is expanding.
- Industrial:Manufacturing, warehousing, and critical infrastructure with specialized equipment riders. Supply chain concentration in Mexico's Guerrero Gap corridor is driving parametric product development.
- Government:Public buildings, schools, and emergency facilities with sovereign guarantee backing. New Zealand's Earthquake Commission maintains dominant position in Christchurch and Wellington metropolitan retrofits.
Residential policies anchor premium volume; commercial lines are climbing the fastest.
Premium Payment Mode:
Annual payment structures align with property tax cycles and mortgage escrow requirements, while monthly modes expand addressable pools among liquidity-constrained homeowners.
- Annual:Single upfront payment with maximum carrier working capital efficiency. Dominates California's CEA-participating insurer arrangements where escrow integration is standard.
- Monthly:Automated withdrawal structures reducing policy lapse rates. Expanding most quickly in Texas and Washington state corridors where non-CEA private carriers compete on payment flexibility.
- Semi-Annual:Biannual installments balancing administrative cost with policyholder cash flow. Common in commercial middle-market segments.
- One-Time:Single premium for multi-year term policies. Concentrates in parametric products where trigger-based payouts eliminate renewal uncertainty.
Annual payment holds the largest share; monthly modes are gaining share fastest.
Claim Process:
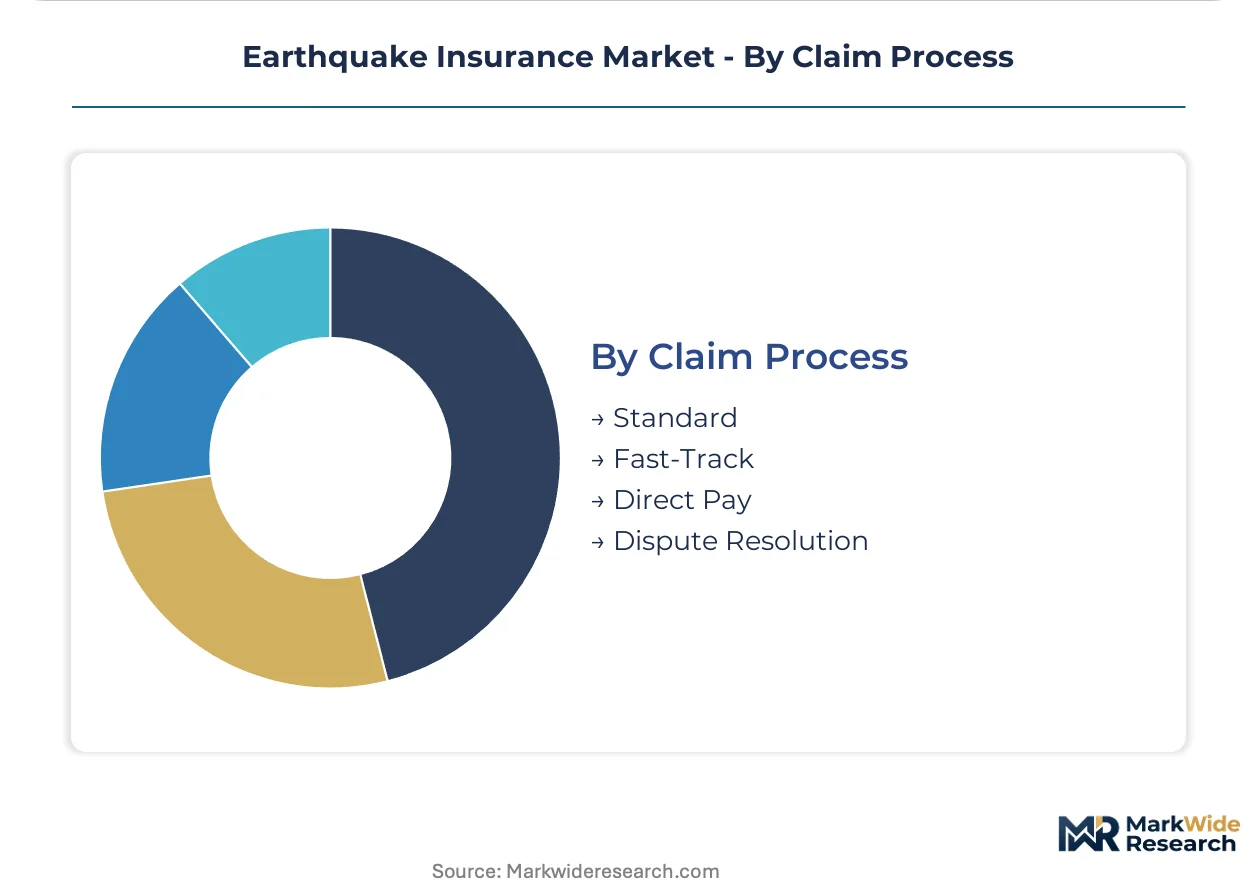
Standard indemnity adjustment dominates legacy portfolios, while fast-track and direct-pay mechanisms are displacing traditional workflows in sensor-integrated parametric contracts.
- Standard:Adjuster inspection, damage documentation, and negotiated settlement timelines spanning weeks to months. Still required for complex structural damage assessments in traditional indemnity frameworks.
- Fast-Track:Pre-approved repair networks and simplified documentation for claims below threshold limits. Japan's Non-Life Insurance Rating Organization of Japan is standardizing protocols for residential contents.
- Direct Pay:Automated disbursement to pre-registered contractors without policyholder intermediation. Emerging in California's lender-mandated coverage where mortgage servicers control repair quality.
- Dispute Resolution:Arbitration and appraisal clauses for valuation disagreements. Concentrates in commercial industrial segments with high-value specialized equipment.
Standard claims processing holds the largest share; fast-track mechanisms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The California Department of Insurance anchors the dominant geography through rate oversight of the California Earthquake Authority, while Japan's Financial Services Agency and New Zealand's Earthquake Commission shape parallel regulatory frameworks across the Pacific Rim.
United States
Mandatory seismic risk disclosure laws in property transactions accelerate residential policy uptake in fault-adjacent counties. The California Earthquake Authority operates under state-enacted rate oversight, pooling capacity across participating insurers. Los Angeles, San Francisco, and San Diego metropolitan corridors concentrate premium volume where lender mandates are strictest.
Japan
Private-public partnership frameworks sustain penetration in the world's most seismically active economic zone. The Financial Services Agency files standardized rates subject to approval while tightening standards for parametric trigger designs. Osaka and Nagoya commercial districts drive sensor-integrated underwriting expansion in the Tokai-Kanto corridor.
New Zealand
Government subsidies for base-isolation and structural reinforcement generate bundled coverage opportunities linking engineering to insurance. The Earthquake Commission maintains dominant position in Christchurch and Wellington metropolitan retrofits. Canterbury region rebuilding programs concentrate demand for comprehensive peril protection.
Mexico
Nascent mortgage securitization and Guerrero Gap exposure create first-mover advantages for parametric residential products. The country's national insurance regulator oversees filing requirements for catastrophe-linked securities. Mexico City metropolitan area anchors commercial infrastructure demand as supply chain concentration drives specialized product development.
Chile
Export-led demand from mortgage securitization platforms concentrates full coverage package uptake. The national financial regulator supervises solvency requirements for catastrophe-exposed carriers. Santiago metropolitan corridor and Valparaíso region house the densest commercial property portfolios requiring seismic protection.
Earthquake Insurance Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with global facultative reinsurance relationships separating scale players from regional carriers. The market fragments across indemnity-based incumbents, parametric innovators, and hybrid platform operators. Strategic archetypes include sensor-integrated underwriters, public-private partnership anchors, and reinsurance-dependent capacity providers. Competitive moves center on parametric trigger design licensing and middleware integration for real-time seismic feeds.
Within the integrated multinational tier, Chubb Ltd. Group and Zurich Insurance Group occupy positions defined by global reinsurance network access, while Travelers Group exemplifies the geospatial risk-scoring specialist archetype. These carriers anchor capacity in high-exposure West Coast markets through differentiated data capabilities rather than brute premium scale.
| Leading Market Players |
|---|
| Chubb Ltd. Group |
| Travelers Group |
| California Earthquake Authority |
| Palomar Specialty Insurance Co. |
| GeoVera Holdings Inc. Group |
| State Farm Group |
| American International Group |
| Liberty Mutual Group |
| Zurich Insurance Group |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with reinsurance panels lock in both retrocession access and rate visibility for primary carriers operating in California and Japan. These multi-year treaties tether pricing stability to collateralized security issuance cycles, compressing margin volatility for underwriters who secure dedicated capacity ahead of hurricane-season spread fluctuations.
Pricing Analysis
California residential premiums run 40-60 percent above comparable Japanese coverage after accounting for deductible differentials and sub-limit structures. Three-tier pricing structure across premium, standard, and economy levels separates lender-mandated full coverage from bare-structural policies and parametric micro-products. Cost compression in the standard tier is intensifying because sensor-integrated underwriting platforms are collapsing loss-adjustment overhead. First-time homebuyers in Texas and Washington state corridors exhibit highest price sensitivity, while institutional mortgage servicers in Los Angeles and San Francisco prioritize coverage completeness over premium minimization.
Supply Chain Analysis
Collateral buildup in Bermuda and Cayman domiciled special purpose vehicles extends lead times for catastrophe bond issuance by 8-12 weeks during peak structuring windows. Retrocession capacity concentrates in Bermuda, London, and Zurich, with collateralized reinsurance drawing from ILS fund managers and pension-backed alternative capital pools. Single-source vulnerability sits with the three dominant catastrophe modeling vendors whose software licenses tether pricing authority across 80 percent of primary carrier portfolios. Distribution runs through wholesale broker networks connecting carrier underwriting platforms to mortgage lender procurement systems, bypassing traditional retail agency channels in high-volume corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parametric trigger products threaten traditional indemnity carriers by collapsing claims settlement cycles and eliminating loss-adjustor value chains. Incumbents must defend against disintermediation while capturing sensor-integrated platform economics.
For Market Incumbents: Fortify facultative reinsurance relationships ahead of collateralized capacity tightening during North Atlantic hurricane correlations. Secure exclusive licensing agreements for dense accelerograph network data in California's San Francisco Bay and Los Angeles basins. Vertical integration into sensor hardware deployment locks out parametric specialists from ground-truth data access. California Department of Insurance rate filing timelines remain the critical regulatory lever for margin defense. For New Entrants and Emerging Players: Lead with parametric micro-products targeting Mexico's Guerrero Gap corridor where mortgage securitization is nascent and traditional indemnity infrastructure is sparse. Embed blockchain-enabled smart contracts for automated payout execution, reducing fraud verification overhead that burdens legacy carriers. White-space concentration sits with residential retrofit-linked policies in New Zealand's Canterbury region where government subsidies for base-isolation create bundled engineering-insurance procurement opportunities. For Investors and Strategic Acquirers: Capital is best deployed toward sensor-integrated underwriting platforms with demonstrated empirical validation studies satisfying Japan's Financial Services Agency trigger approval standards. Long-term viability hinges on regulatory acceptance of parametric designs as alternatives to indemnity-based loss adjustment. Watch for legislative movement on federal earthquake backstop authority comparable to the National Flood Insurance Program's Treasury borrowing structure as the inflection signal for market depth expansion in high-exposure US corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Trigger Licensing | Japan's Financial Services Agency approval validates correlation between sensor data and structural damage. |
| Sensor Network Deployment | Dense accelerograph arrays in Tokai-Kanto corridor enable real-time exposure management for commercial portfolios. |
| Reinsurance Panel Diversification | Bermuda and London capacity reduces dependence on collateralized ILS spreads during hurricane season. |
| Blockchain Smart Contract Integration | Distributed ledger automation eliminates fraud verification costs in high-frequency seismic corridors. |
| Mortgage Platform Integration | Wholesale distribution through lender procurement systems displaces retail agency relationships in California. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of California Department of Insurance rate filings, Japan's Non-Life Insurance Rating Organization of Japan standardized rate submissions, and catastrophe bond issuance databases. Underwriting executives at CEA-participating insurers, catastrophe modeling specialists, reinsurance broker placement teams, and mortgage servicer procurement officers provided structured interviews. Secondary validation drew from SEC 10-K insurance segment disclosures, Bermuda Monetary Authority catastrophe bond registrations, and geospatial fault mapping from national geological surveys. Bottom-up premium volume estimates triangulate against top-down reinsurance capacity allocation data.
Segmentation dimensions modeled include coverage scope, policyholder type, premium payment mode, and claims process mechanics across the analysis window. Structural versus full coverage splits, residential-commercial-industrial-government policy mix, and standard versus fast-track versus parametric claim settlement pathways anchor the analytical framework. CAGRs derive from cohort-based growth rate analysis applied to lender-mandated penetration curves in fault-adjacent counties and private-public partnership expansion trajectories in Japan's Tokai-Kanto corridor. Parametric trigger adoption rates and sensor network deployment densities serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained regulatory acceptance of parametric designs or congressional movement on federal backstop legislation would require recalibration. Forecasts reflect documented assumptions regarding reinsurance capacity availability, actuarial talent migration patterns, and mortgage lender coverage mandate expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Endowment Insurances Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Spain Group Health Insurance Market
Insurance
Crime Insurance Market
Insurance
Norway Property and Casualty Insurance Market
Insurance
India Online Insurance Market
Insurance
Disability Insurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
UK Travel Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Japan Liability Insurance Market
Insurance
Peru Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Single Trip Travel Insurance Market