
 United Kingdom Parametric Insurance Market | 2026-2036
United Kingdom Parametric Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Parametric Insurance Market Insights
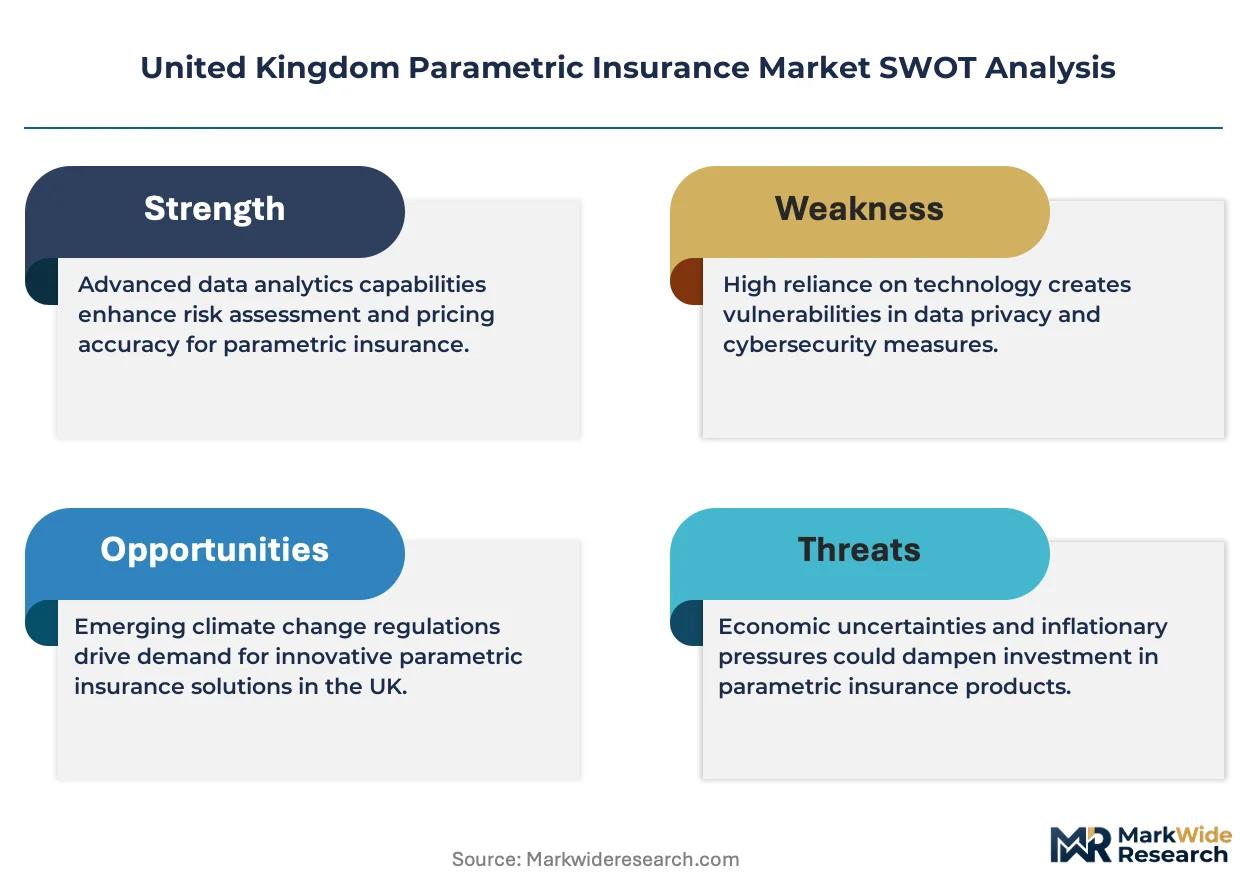
London's reinsurance broker cluster is consolidating around parametric structuring capabilities. Munich Reinsurance Company leverages its proprietary weather index platform to anchor bespoke coverage for UK agricultural clients. Swiss Reinsurance Company sustains dominance in natural catastrophe triggers through its Sigma research unit's hazard modeling. Aon plc competes via its Capital Markets division, which structures catastrophe bonds alongside direct parametric policies for corporate buyers.
Parametric insurance deploys predefined triggers—such as earthquake magnitude, rainfall millimeters, or wind speed thresholds—to automate claims settlement without loss adjustment. The mechanism eliminates indemnity verification through objective data feeds from satellites, weather stations, or seismic sensors, delivering liquidity within days rather than months. Weather policies lead the Policy Type segment as flooding and drought coverage absorbs rising homeowner demand, while Digital Platforms represent the fastest-growing Distribution Channel as insurtech APIs embed quotes directly into lender and utility portals. Crop Yield policies occupy concentrated margin pools where basis risk engineering commands specialist actuarial premiums.
The Prudential Regulation Authority's climate stress testing framework shapes carrier capital reserves for parametric exposures, while Flood Re's transitional reinsurance scheme dictates pricing floors for residential flood triggers. The Financial Conduct Authority's consumer duty rules force distributors to demonstrate that automated parametric payouts align with policyholder understanding of trigger mechanics. Stakeholders must monitor whether the Bank of England's forthcoming nature-related financial disclosure requirements expand parametric mandates into biodiversity and soil degradation risks.
Market Dynamics
The Prudential Regulation Authority's climate stress testing framework is forcing UK carriers to recalibrate capital reserves against parametric weather exposures, while Flood Re's transitional reinsurance scheme compresses pricing floors for residential flood triggers. This dual regulatory pressure is accelerating product innovation and carrier specialization.
Growth Catalysts
- Renewable Energy Expansion:Wind farm operators and solar developers across Scotland and East Anglia are purchasing parametric policies against wind speed shortfalls and solar irradiance deficits, creating concentrated demand pools for capacity providers.
- Flood Re Scheme Transition:The UK's government-backed reinsurance pool for residential flood risk is gradually ceding coverage to private markets, opening parametric triggers for household flood policies previously underwritten through traditional indemnity structures.
- Agricultural Cooperative Consolidation:Crop yield cooperatives in Lincolnshire and East Anglia are replacing indemnity-based farm coverage with index-linked parametric products, reducing loss adjustment costs and settlement timelines.
Market Restraints
- Basis Risk Engineering Costs:Specialist actuarial talent required to model correlation gaps between parametric triggers and actual crop losses commands premium compensation, elevating policy pricing for agricultural segments.
- Data Feed Dependency:Settlement automation relies on satellite imagery and weather station networks concentrated among European Space Agency and Met Office sources, creating single-point vulnerability for trigger verification.
- Consumer Understanding Gaps:The Financial Conduct Authority's consumer duty rules require distributors to demonstrate policyholder comprehension of automated payout mechanics, adding compliance friction to digital distribution channels.
Strategic Opportunities
- Nature-Related Disclosures:The Bank of England's forthcoming biodiversity and soil degradation risk reporting requirements may expand parametric mandates beyond weather into ecological indices, opening coverage for land degradation and habitat loss.
- API Distribution Integration:Insurtech platforms embedding parametric quotes directly into mortgage lender and utility customer portals are capturing policyholders at point-of-need, bypassing traditional broker intermediation.
- Soil Health Index Products:Emerging applications in regenerative agriculture are piloting parametric coverage tied to soil carbon sequestration measurements, targeting farmland investors and sustainability-linked loan covenants.
Industry Challenges
- Actuarial Talent Scarcity:The intersection of climate science, satellite data analytics, and insurance pricing requires hybrid skill sets that UK universities and professional bodies have not yet scaled to market demand.
- Legacy System Integration:Established carriers attempting to embed parametric products into traditional policy administration platforms face middleware complexity that delays product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Parametric Insurance Market |
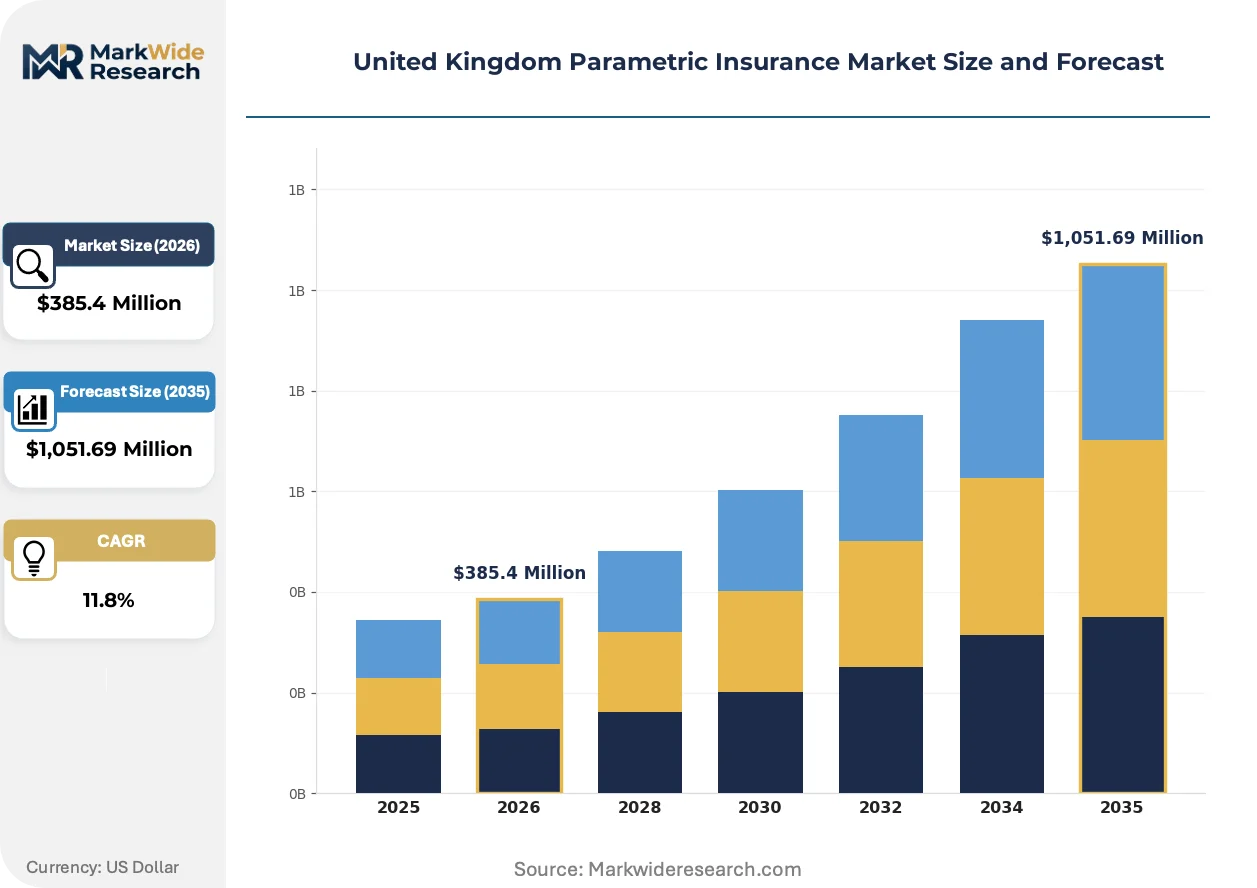
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,051.69 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Weather, Crop Yield, Natural Disaster, Energy Production Distribution Channel: Brokers, Direct Sales, Digital Platforms, Bancassurance End User: Agribusiness, Renewable Energy Operators, Maritime Operators, Construction Firms Risk Trigger: Earthquake, Flood, Hurricane, Drought, Temperature Threshold |
| Companies Covered | Swiss Reinsurance Company, Hannover Re, Allianz SE, Aon plc, SCOR SE, Zurich Insurance Group Ltd, Munich Reinsurance Company, Willis Towers Watson, AXA SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Parametric Insurance Market Trends and Innovations
Parametric insurance in the United Kingdom is undergoing structural transformation through data infrastructure modernization, regulatory disclosure evolution, and buyer channel migration. These shifts are compressing settlement timelines while expanding addressable risk categories.
Blockchain-enabled smart contracts are decentralizing claims settlement execution by automating payout triggers through distributed ledger verification. Agricultural cooperatives and renewable energy operators are piloting these instruments for crop yield and wind speed policies. This technology is decentralizing control over settlement timing away from carrier claims departments toward algorithmic execution.
The Financial Conduct Authority's consumer duty framework is mandating enhanced disclosure of trigger mechanics and basis risk exposure for retail parametric purchasers. Carriers must now demonstrate that automated payout structures align with policyholder understanding of index-linked settlement conditions. Residential flood and weather products face the steepest compliance adaptation requirements.
Corporate risk managers are unbundling parametric coverage from bundled property programs, purchasing standalone weather and natural catastrophe triggers through direct carrier relationships or specialized brokers. This disintermediation bypasses traditional wholesale market channels. The shift is most visible among London-headquartered renewable energy developers and agricultural processing firms with concentrated weather exposures.
United Kingdom Parametric Insurance Market Segmentation
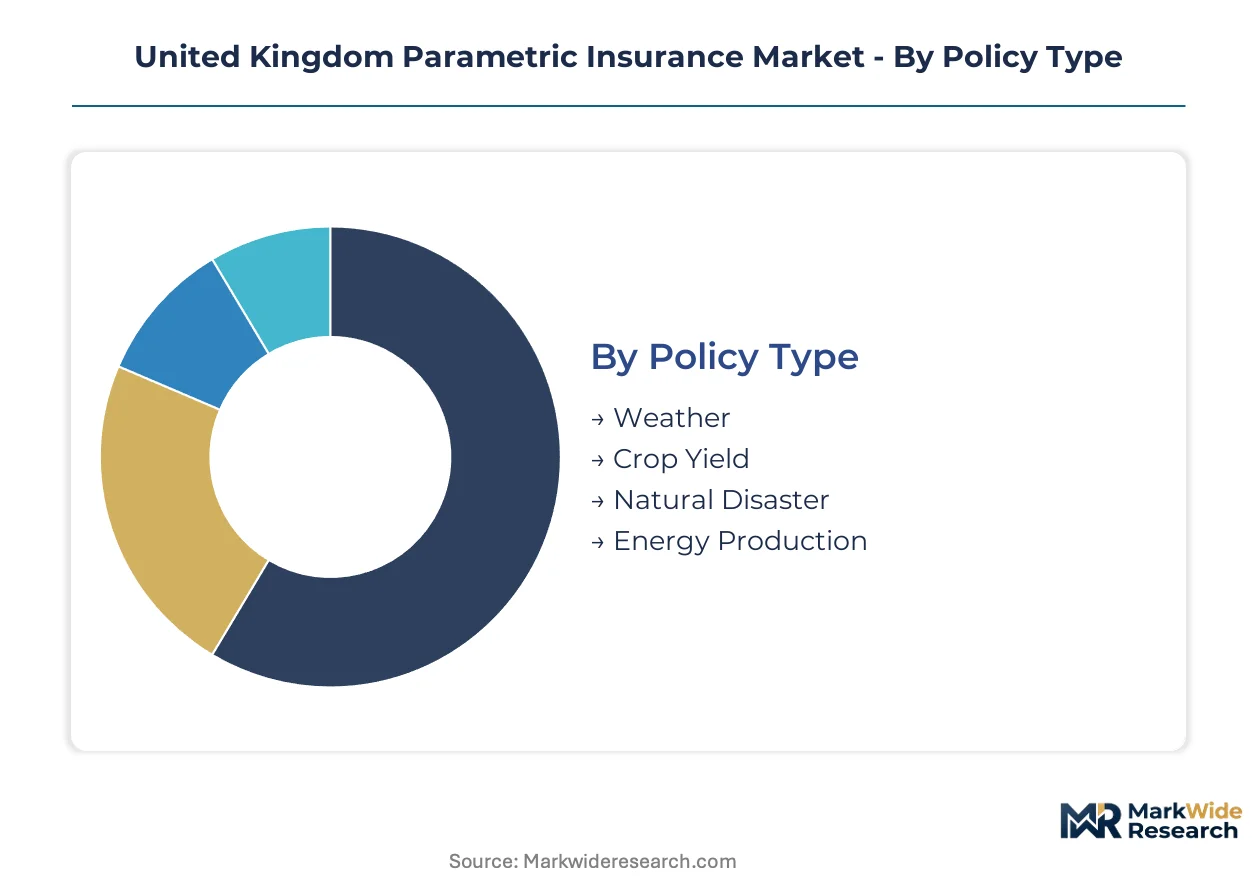
Parametric insurance in the United Kingdom fragments across four structural dimensions that determine pricing precision, settlement velocity, and basis risk exposure. Each segmentation axis reflects distinct buyer capabilities, data infrastructure maturity, and regulatory touchpoints that shape product design.
Policy Type:
Customization intensity varies sharply across this category, from commoditized weather indices to bespoke energy production structures requiring embedded optionality.
- Weather:Precipitation, wind speed, and temperature thresholds trigger automated payouts for property damage and business interruption. Flood coverage dominates household demand in Thames Gateway and Severn Valley corridors, where Flood Re's transitional pricing creates arbitrage opportunities for private parametric alternatives.
- Crop Yield:Satellite-derived vegetation indices and rainfall accumulation models replace traditional indemnity verification for agricultural cooperatives. Lincolnshire grain producers and East Anglia sugar beet growers absorb rising basis risk engineering costs to accelerate liquidity during harvest failures.
- Natural Disaster:Earthquake magnitude and flood depth triggers serve corporate property portfolios with concentrated catastrophe exposure. Demand clusters among London commercial real estate investment trusts seeking gap coverage against Flood Re's coverage limits.
- Energy Production:Wind speed deficits and solar irradiance shortfalls protect renewable asset cash flows. Scottish onshore wind farms and East Anglia solar arrays purchase these structures to secure debt service coverage ratios against weather-driven revenue volatility.
Most installed capacity flows through Weather. Expansion is steepest in Crop Yield.
Distribution Channel:
Channel selection reflects buyer sophistication gradients, from price-sensitive retail purchasers to institutional risk managers demanding structuring capabilities.
- Brokers:London's reinsurance broker cluster dominates corporate placement, with catastrophe bond structurers and weather derivative specialists competing for renewable energy and agricultural mandates. Lloyd's coverholders access delegated authority for standardized weather products.
- Direct Sales:Carrier captive agents target mid-market property owners with simplified flood and storm triggers, bypassing commission loadings. The PRA's consumer duty rules force enhanced disclosure of basis risk mechanics in this channel.
- Digital Platforms:Insurtech APIs embed parametric quotes into mortgage lender portals and utility customer journeys, capturing policyholders at point-of-need. This channel is expanding most quickly as embedded finance architectures mature.
- Bancassurance:High street banks distribute residential flood triggers alongside mortgage origination, leveraging Flood Re's transitional reinsurance pricing floors. Compliance friction from FCA consumer duty adaptation slows product rollout timelines.
Transaction volume concentrates through Brokers. Digital Platforms are gaining share fastest.
End User:
End-user segmentation maps directly to data feed availability and correlation modeling complexity, with renewable energy operators commanding premium actuarial resources.
- Agribusiness:Agricultural cooperatives and corporate farming operations in East Anglia and the East Midlands replace traditional crop insurance with index-linked yield protection. Settlement automation reduces administrative burden during peak harvest disruption periods.
- Renewable Energy Operators:Wind farm developers across Scotland and solar asset owners in East Anglia structure parametric coverage against resource availability risk. These buyers demand the most sophisticated basis risk engineering and satellite data integration.
- Maritime Operators:Port authorities and coastal logistics firms purchase wave height and wind speed triggers to protect against terminal closure and supply chain interruption. Demand remains concentrated at Felixstowe and Southampton.
- Construction Firms:Infrastructure contractors deploy rainfall and temperature threshold policies to manage liquidated damages exposure on fixed-price contracts. Uptake lags due to project-specific trigger calibration requirements.
Renewable Energy Operators deploy the most premium capacity. Agribusiness is expanding most quickly.
Risk Trigger:
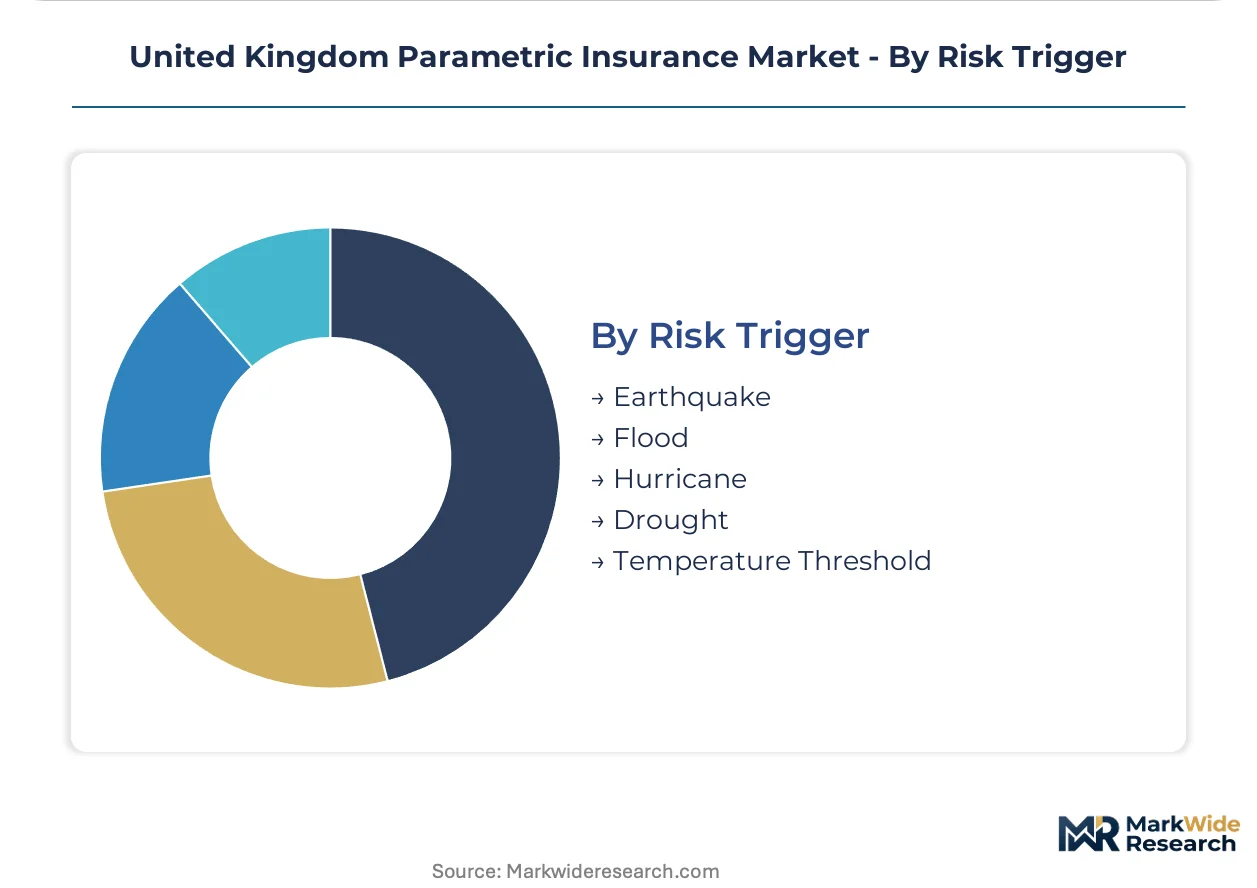
Trigger selection determines settlement velocity and data feed dependency, with flood and drought indices leveraging established Met Office infrastructure while temperature thresholds require denser sensor networks.
- Earthquake:Magnitude thresholds from British Geological Survey seismic networks trigger payouts for commercial property damage. UK seismic exposure remains limited compared to European tectonic zones, constraining market depth.
- Flood:River gauge and satellite-derived inundation indices dominate residential and commercial deployment. Flood Re's transitional scheme compresses pricing floors while expanding addressable risk pools for private carriers.
- Hurricane:Extratropical cyclone wind speed triggers protect coastal infrastructure and renewable assets. Named storm definitions from the Met Office provide settlement clarity absent in indemnity structures.
- Drought:Soil moisture deficit and precipitation shortfall indices serve agricultural and water utility buyers. Climate stress testing from the Bank of England is reshaping carrier capital allocation toward these longer-tailed exposures.
- Temperature Threshold:Heating and cooling degree-day indices protect energy retailers and agricultural cold chain operators. Urban heat island effects in London and Birmingham create localized calibration challenges.
Flood absorbs the most bound capacity. Drought is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands deeper agricultural parametric penetration than the United Kingdom, while France leads renewable energy coverage integration. Both markets operate under distinct regulatory frameworks that shape carrier capital deployment and product standardization.
London and the Southeast
London's reinsurance broker cluster concentrates parametric structuring expertise for corporate buyers. The Prudential Regulation Authority's climate stress testing framework forces carriers to recalibrate capital reserves against weather exposures. Lloyd's coverholders in the City and Canary Wharf access delegated authority for standardized flood and storm products.
East Anglia
Agricultural cooperatives in Lincolnshire and Norfolk replace traditional crop insurance with index-linked yield protection. The Flood Re scheme's transitional reinsurance pricing creates arbitrage opportunities for private parametric alternatives. Norwich and Ipswich host satellite data analytics firms calibrating vegetation indices for sugar beet and grain producers.
Scotland
Onshore wind farm operators across the Highlands and Borders purchase parametric coverage against wind speed deficits. The Scottish Government's climate adaptation strategy encourages index-linked products for renewable asset cash flow protection. Edinburgh's financial services cluster supports carrier back-office functions for policy administration.
Midlands
Construction firms in Birmingham and the West Midlands deploy rainfall threshold policies to manage liquidated damages exposure. The Financial Conduct Authority's consumer duty rules force enhanced disclosure of trigger mechanics for mid-market property owners. Leicester and Nottingham host insurtech platforms embedding parametric quotes into utility customer portals.
North England
Industrial property portfolios in Manchester and Leeds seek gap coverage against Flood Re's coverage limits. The Environment Agency's flood risk mapping informs trigger calibration for river gauge and satellite-derived inundation indices. Sheffield's advanced manufacturing sector pilots parametric coverage tied to supply chain interruption triggers.
United Kingdom Parametric Insurance Market Competitive Landscape
Continental European reinsurers anchor the capacity tier; London-based brokers and intermediaries hold the distribution and structuring layer. The market presents a consolidated structure where global reinsurance groups deploy proprietary weather index platforms alongside specialized catastrophe modeling units. Three archetypes dominate: integrated reinsurance carriers with captive data infrastructure, broker-led structuring specialists, and insurtech platforms with API distribution capabilities. Competitive dynamics center on M&A activity targeting satellite analytics capabilities and strategic partnerships embedding parametric products into lender and utility ecosystems.
Among the integrated reinsurance tier, Munich Reinsurance Company and Swiss Reinsurance Company exemplify carriers with proprietary hazard modeling and weather index platforms. Aon plc occupies a position within the broker-led structuring specialist archetype, competing through catastrophe bond placement alongside direct parametric policy design. These three entities represent the dominant competitive anchors shaping market capacity allocation and pricing benchmarks.
| Leading Market Players |
|---|
| Swiss Reinsurance Company |
| Hannover Re |
| Allianz SE |
| Aon plc |
| SCOR SE |
| Zurich Insurance Group Ltd |
| Munich Reinsurance Company |
| Willis Towers Watson |
| AXA SA |
| Others |
Pricing and Supply Chain Analysis
Renewable energy operators in Scotland and East Anglia anchor premium-tier pricing through sophisticated basis risk engineering demands, while agricultural cooperatives absorb compressed margins as Flood Re's transitional reinsurance scheme flattens residential flood price floors. This buyer-archetype divergence shapes carrier capacity allocation between bespoke structuring and standardized product lines.
Pricing Analysis
Capacity additions in Lloyd's syndicates and London company markets are reshaping price floors for weather-triggered coverage as Munich Re and Swiss Re deploy proprietary index platforms. Three-tier pricing structure across premium, standard, and economy levels separates renewable energy operators demanding embedded optionality from household flood purchasers selecting Flood Re-linked alternatives. Pricing pressure stems from actuarial talent scarcity elevating specialist compensation costs. Agricultural cooperatives exhibit highest price sensitivity, while renewable developers prioritize settlement velocity over premium expenditure.
Supply Chain Analysis
Regional distribution centers in London and Edinburgh coordinate satellite data feed aggregation from European Space Agency and Met Office sources. Supply concentration rests on Germany, Switzerland, and the United Kingdom for reinsurance capacity, while satellite imagery analytics draw from Netherlands and France. Single-source vulnerability permeates trigger verification infrastructure concentrated among European Space Agency Sentinel platforms. Distribution runs through Lloyd's broker networks for corporate placement, with digital platforms capturing direct-to-consumer growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parametric insurance in the United Kingdom presents a margin-expansion story as automated settlement mechanisms compress loss adjustment expenses and accelerate capital velocity for carriers mastering basis risk engineering.
For Market Incumbents: Hedge basis risk exposure through captive satellite analytics capabilities as insurtech platforms disintermediate traditional broker channels. Invest in proprietary weather index infrastructure to defend pricing power against Munich Re and Swiss Re platforms. Prioritize Flood Re transition arbitrage before government-backed pricing floors expire. For New Entrants and Emerging Players: The mid-market gap between Lloyd's catastrophe bond structures and direct-to-consumer digital platforms offers white-space entry. Target agricultural cooperatives in Lincolnshire and Norfolk with simplified crop yield indices bypassing specialist broker fees. Embed parametric quotes through utility customer portals to capture policyholders at point-of-need. For Investors and Strategic Acquirers: Reinsurance carriers with proprietary data infrastructure are the most active acquirers in this space, consolidating satellite analytics firms to secure trigger verification control. Acquire targets exhibiting hybrid climate science-actuarial talent pools and API distribution capabilities. Monitor Bank of England nature-related disclosure implementation as inflection indicator for biodiversity index product expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Weather Index Platform Development | Carriers owning satellite calibration capabilities command pricing power against broker-structured alternatives. |
| API Distribution Integration | Insurtech platforms embedding quotes into mortgage lender portals bypass traditional intermediary commissions. |
| Basis Risk Engineering Talent Acquisition | Hybrid climate science-actuarial skill scarcity elevates specialist compensation and delays product launches. |
| Flood Re Transition Arbitrage | Private carriers exploit government-backed pricing floors before residential flood risk cedes to market mechanisms. |
| Blockchain Smart Contract Piloting | Distributed ledger automation decentralizes settlement execution away from carrier claims departments. |
Research Methodology
Multiple input streams — carrier underwriting executives, Lloyd's broker structuring specialists, agricultural cooperative risk managers, and satellite data analytics firms — were reconciled against regulatory filings from the Prudential Regulation Authority and Financial Conduct Authority. Secondary validation drew from Flood Re annual reports, European Space Agency satellite mission disclosures, Met Office climate data repositories, and Lloyd's market returns. Bottom-up policy binding data and top-down reinsurance capacity estimates underwent cross-referencing to establish market sizing boundaries.
Historical premium growth trajectories were cross-referenced against panel input from renewable energy developers and agricultural processors to establish projection parameters across the analysis window. Segmentation modeling incorporated policy type, distribution channel, end-user vertical, and risk trigger dimensions. CAGRs derived from carrier capacity deployment patterns and regulatory disclosure timelines. Forecast inputs included Flood Re transitional scheme phase-out schedules and Bank of England climate stress testing framework evolution.
Caveats apply where regulatory disclosure delays or satellite data feed disruptions could materially shift the outlook. Forecasts reflect stated assumptions regarding basis risk correlation modeling accuracy and automated settlement infrastructure adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Agriculture Insurance Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
Insurance Brokerage Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Dental Insurance Market
Insurance
Green Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Peru Insurance Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
GCC Health Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Directors and Officers (Dando) Insurance Market