
 United Kingdom Car Insurance Market | 2026-2036
United Kingdom Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Car Insurance Market Insights
Telematics hardware is expanding its share of policy pricing infrastructure across the United Kingdom. Admiral Group leverages proprietary data algorithms to sustain competitive positioning in usage-based segments. Direct Line Group anchors its portfolio around direct-to-consumer digital distribution, while Aviva competes through integrated banking-insurance cross-sell capabilities.
United Kingdom car insurance constitutes a risk-transfer contract indemnifying policyholders against financial loss from vehicle damage, theft, or third-party liability, underwritten through actuarial pricing models incorporating driver history, vehicle specification, and geographic risk density. Comprehensive coverage dominates premium volumes, though usage-based payment models are capturing the fastest policy growth as telematics penetration deepens. Young driver segments command elevated rate tiers, while annual policy duration structures retain the largest residual margin pool across distribution channels.
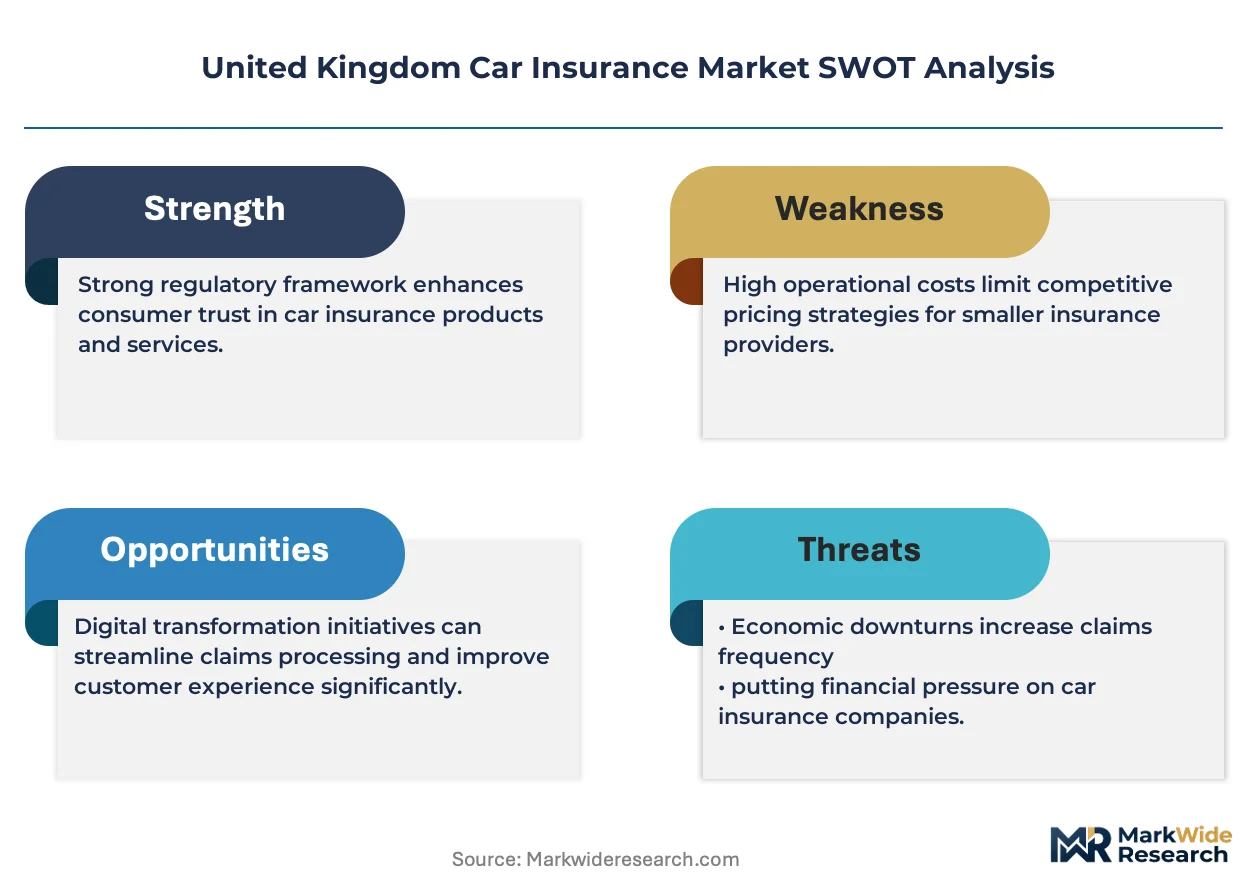
The Financial Conduct Authority's consumer duty framework and the Prudential Regulation Authority's solvency standards jointly shape capital allocation and pricing transparency obligations for United Kingdom underwriters. The FCA's pricing remedy rules specifically restrict loyalty penalty practices, forcing carriers to rebalance new business and renewal rate structures. Stakeholders must monitor telematics data ownership disputes and evolving autonomous vehicle liability frameworks as these will determine next-generation product design and risk transfer mechanics.
Market Dynamics
Telematics penetration is restructuring actuarial pricing foundations across the United Kingdom car insurance sector, compressing traditional risk-pooling models and forcing carriers to rebuild data infrastructure around real-time driving telemetry rather than historical claims patterns.
Growth Catalysts
- FCA Consumer Duty framework:The Financial Conduct Authority's pricing transparency mandates are eliminating loyalty penalties and creating competitive openings for carriers with cleaner renewal rate structures.
- Usage-based insurance models:Pay-per-mile and behavioral scoring products are capturing young driver segments in Greater London through smartphone-integrated telematics platforms.
- Fleet operator procurement:Commercial vehicle operators are consolidating coverage contracts and demanding integrated risk management dashboards with live vehicle tracking.
Market Restraints
- Telematics data ownership disputes:Unclear legal frameworks governing who controls and monetizes driver behavioral data are creating litigation exposure for insurers and device manufacturers.
- Legacy core system architecture:Incumbent carriers remain tethered to decades-old policy administration platforms that cannot ingest real-time telematics streams without multimillion-pound replacement cycles.
- Autonomous vehicle liability ambiguity:The absence of statutory frameworks assigning fault between vehicle manufacturers, software providers, and policyholders is freezing product development for self-driving coverage.
Strategic Opportunities
- Embedded insurance distribution:Point-of-sale coverage integration with automotive OEMs and dealership networks is bypassing traditional aggregator channels.
- Climate risk parametric products:Flood and storm damage policies triggered by meteorological data rather than physical inspection are addressing gaps in standard comprehensive coverage.
- Open banking cross-sell:The United Kingdom's open banking infrastructure permits real-time affordability scoring and premium financing integration at quote stage.
Industry Challenges
- Actuarial talent scarcity:The profession faces acute shortages of data scientists capable of building predictive models from unstructured telematics feeds rather than traditional rating factors.
- Legacy-to-cloud migration complexity:Core policy systems require staged decoupling from on-premise mainframes without disrupting annual renewal cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Car Insurance Market |
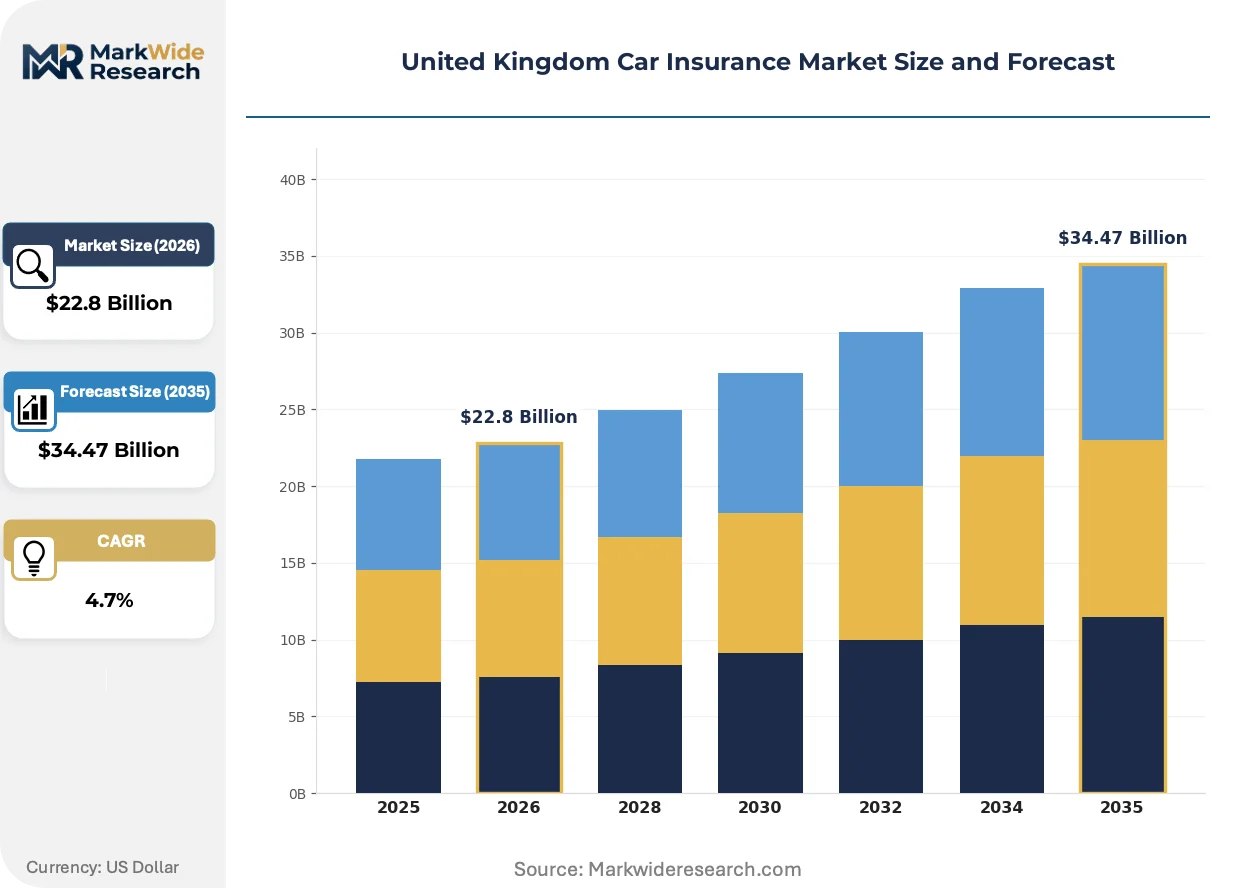
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.47 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Third Party, Comprehensive, Fire and Theft, Comprehensive Plus Policy Duration: Monthly, Annual, Short-term, Multi-year Customer Segment: Young Drivers, Families, Business Travelers, Senior Citizens Payment Model: Pay-as-you-go, Fixed Premium, Usage-based, Annual Payment |
| Companies Covered | Admiral Group, Direct Line Group, Aviva, Hastings, AXA, LV= General Insurance, Esure, RSA, Ageas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Car Insurance Market Trends and Innovations
Digital distribution infrastructure and connected vehicle data streams are collapsing the traditional separation between underwriting, pricing, and claims functions. Carriers are rebuilding operating models around continuous customer engagement rather than annual policy events.
Telematics hardware paired with machine learning scoring algorithms is decentralizing risk assessment from centralized actuarial departments to individual driver profiles. Young motorists in Greater London and the South East are adopting smartphone-based monitoring apps at the fastest clip. This shift is compressing cross-subsidies between high-risk and low-risk policyholders and forcing carriers to defend margin through data exclusivity rather than portfolio diversification.
The Financial Conduct Authority's pricing remedy rules are mandating equivalent treatment of new business and renewal customers, eliminating the historical practice of subsidizing acquisition discounts through elevated retention rates. Smaller digital-native insurers are capturing disaffected switchers through transparent rate structures. The regulatory pressure is most acute among mid-tier carriers with legacy book concentration in auto-renewal segments.
Aggregator channel dependence is fragmenting as direct-to-carrier digital journeys improve conversion rates. Price comparison websites still dominate quote initiation but lose increasing volumes at checkout to insurer-owned platforms with streamlined authentication. This behavioral pivot is most visible among tech-savvy demographics in urban centers where mobile-first policy management has become the default expectation.
United Kingdom Car Insurance Market Segmentation
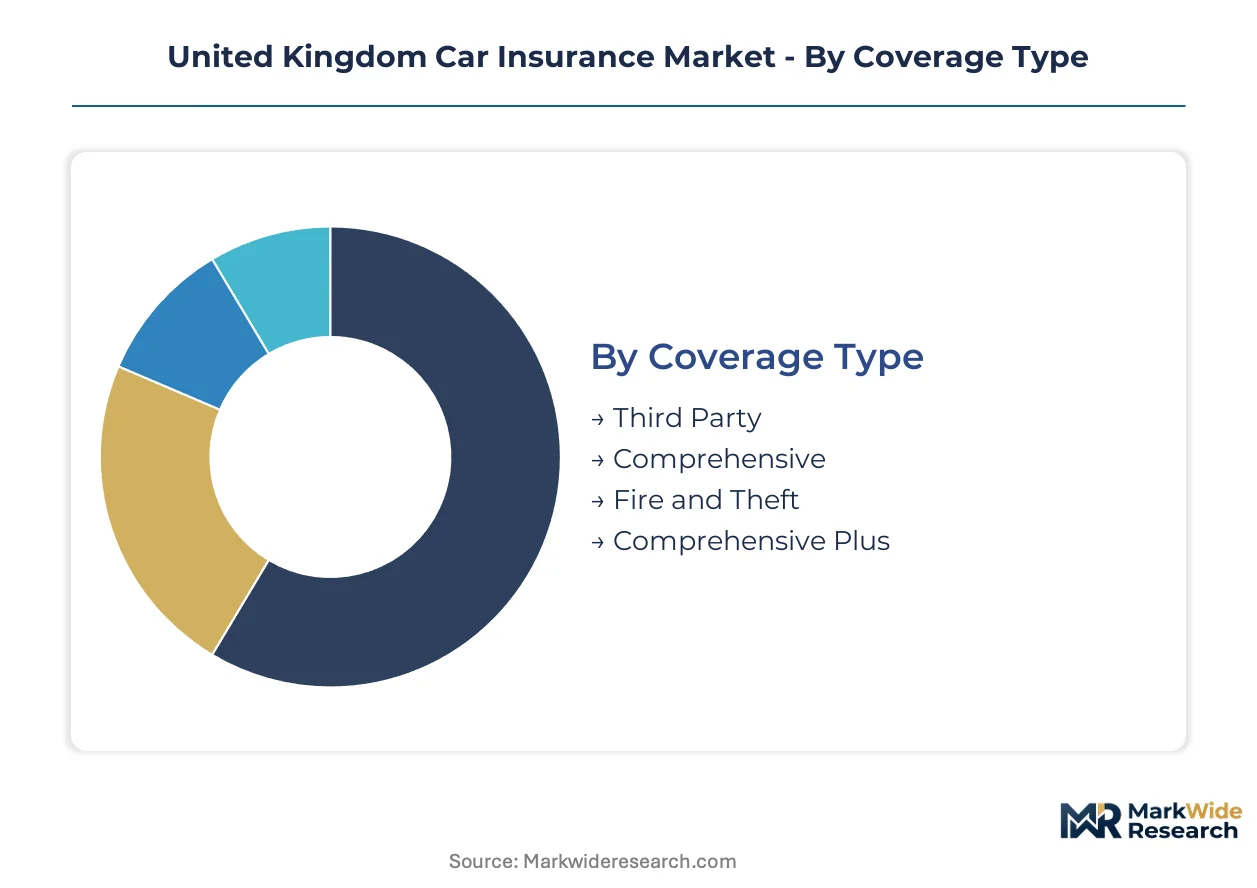
United Kingdom car insurance segmentation reveals how coverage design, policy structure, and customer economics interact to determine carrier profitability. Understanding these axes clarifies where telematics disruption concentrates and which segments retain pricing power under FCA transparency rules.
Coverage Type:
Technical specifications define risk transfer scope and capital reserving requirements across the four coverage tiers.
- Third Party:Minimum legal coverage indemnifying against injury or damage to others. Demand concentrates among price-sensitive motorists in Northern England and the Midlands where vehicle values fall below comprehensive premium thresholds. Regulatory minimums sustain volume despite thin margins.
- Comprehensive:Full protection extending to policyholder vehicle damage, theft, and third-party liability. Families in the South East and Greater London dominate procurement, driven by higher vehicle values and financed-car contractual requirements. This segment anchors premium income across major carriers.
- Fire and Theft:Intermediate coverage excluding collision damage. Classic vehicle owners and low-mileage rural drivers in Wales and Scotland select this tier to balance protection against premium outlay.
- Comprehensive Plus:Enhanced coverage adding courtesy vehicles, legal expenses, and windscreen protection. Business travelers and fleet operators in urban corridors demand these extensions for operational continuity.
Comprehensive leads on scale; Comprehensive Plus leads on momentum.
Policy Duration:
Contract length shapes customer lifetime value calculations and retention strategy economics.
- Annual:Standard twelve-month terms with guaranteed rate stability. The residual margin pool concentrates here, though FCA pricing remedies now compress new-renewal spreads. Incumbent carriers defend this base through auto-renewal infrastructure.
- Monthly:Instalment plans attracting cash-constrained young drivers in Greater London. Premium finance charges offset elevated cancellation risk. Telematics integration enables real-time payment adjustments based on verified mileage.
- Short-term:Daily to weekly coverage for temporary vehicle use. Visitors, test drives, and shared mobility users in airport-adjacent postal codes drive intermittent demand. Distribution runs through digital-native platforms with instant policy issuance.
- Multi-year:Two to five year fixed-rate contracts. Price certainty appeals to risk-averse families and senior citizens seeking inflation protection. Limited carrier appetite reflects uncertainty in repair cost and claims frequency projections.
Annual dominates premium volume; monthly expands most quickly among digitally acquired policies.
Customer Segment:
Demographic risk profiles determine rate tier placement and cross-sell potential across distribution channels.
- Young Drivers:Motorists under twenty-five facing elevated actuarial risk scores. Smartphone telematics adoption is climbing the fastest in this cohort as behavioral scoring unlocks affordable entry rates. Greater London and South East postcodes show highest penetration.
- Families:Multi-vehicle households with mid-range risk profiles and high lifetime value potential. Integrated home and motor coverage drives carrier preference, with cross-sell economics justifying acquisition investment.
- Business Travelers:High-mileage professionals requiring flexible coverage and rapid claims resolution. Corporate fleet procurement channels and executive policy tiers service this demand.
- Senior Citizens:Experienced drivers with favorable claims histories but accelerating injury severity costs. Retention-focused carriers deploy dedicated service teams and simplified digital interfaces.
Families lead on scale; young drivers lead on momentum.
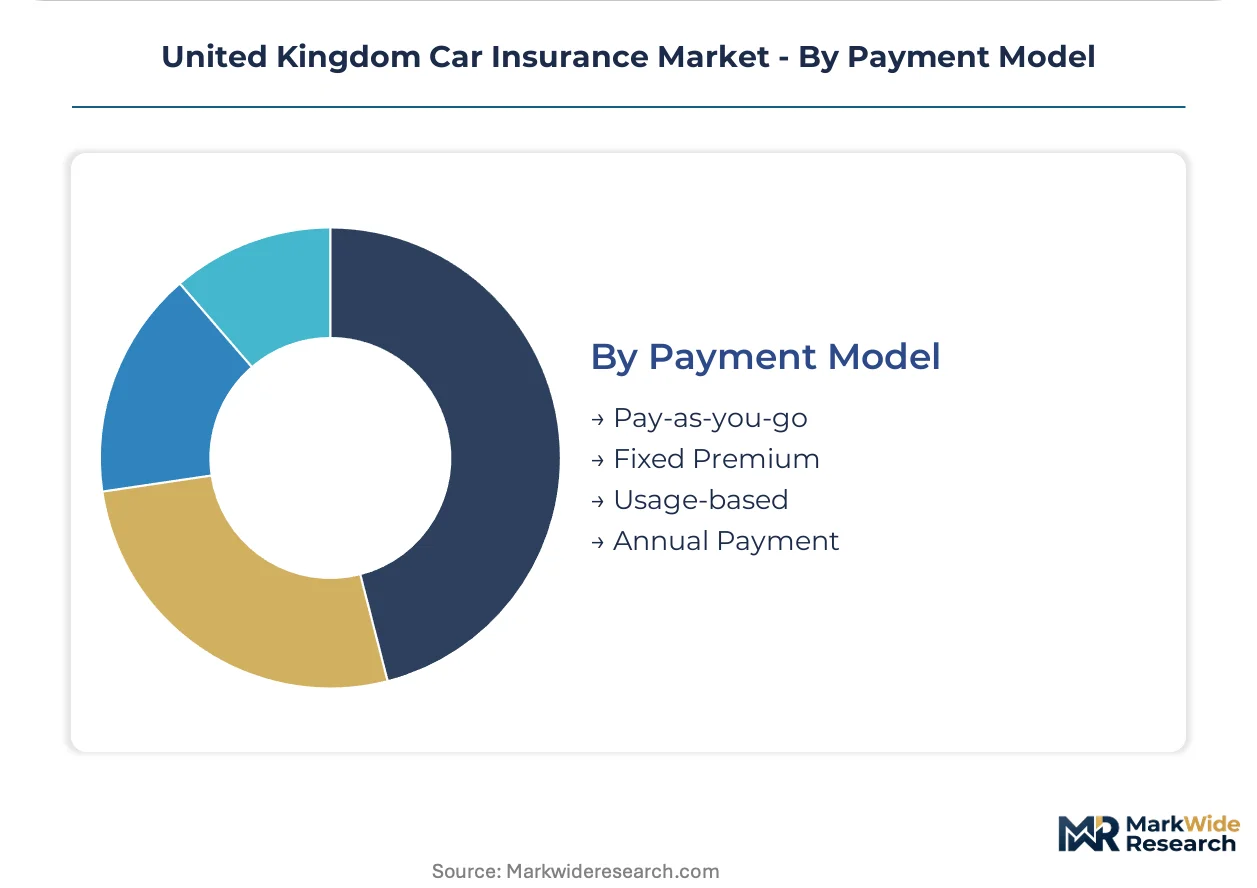
Payment Model:
Premium collection mechanics determine cash flow timing and customer engagement frequency.
- Fixed Premium:Pre-calculated annual or monthly payments based on declared risk factors. Traditional actuarial pricing dominates, though FCA transparency requirements now mandate clearer factor disclosure.
- Usage-based:Dynamic pricing tied to verified mileage and driving behavior through installed telematics. Young driver segments in urban centers adopt this model fastest as it directly links cost to exposure.
- Pay-as-you-go:Top-up credit systems for occasional drivers. Low-mileage retirees and second-vehicle owners in rural postcodes favor this structure for cost control.
- Annual Payment:Single upfront settlement capturing discount incentives. Financially liquid policyholders and commercial fleet operators prefer this for administrative simplicity.
Fixed premium leads on scale; usage-based leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London anchors United Kingdom car insurance demand through its concentration of young driver populations, high vehicle density, and fleet operator headquarters. The Financial Conduct Authority's consumer duty framework applies uniformly across England, Scotland, Wales, and Northern Ireland, though regional risk profiles and regulatory interpretations create measurable pricing dispersion.
Greater London and the South East
Telematics adoption concentrates among under-25 motorists in London boroughs and Surrey commuter belts where behavioral scoring unlocks affordable entry rates. The FCA's pricing remedy rules have forced carriers to eliminate loyalty penalties fastest in this high-churn region. Admiral Group and Direct Line Group maintain significant data science operations in Cardiff and Bromley respectively, feeding algorithmic pricing models deployed across southeastern postcodes.
Midlands
Manufacturing and logistics hubs around Birmingham and Coventry drive commercial fleet procurement with integrated risk management requirements. The Prudential Regulation Authority's solvency standards shape capital allocation for Midlands-based underwriters serving SME transport operators. Telematics penetration lags London by approximately three years, preserving traditional risk-pooling margins for incumbent carriers with legacy book concentration.
North England
Price-sensitive motorists in Manchester, Leeds, and Liverpool postcodes favor third-party minimum coverage where vehicle values fall below comprehensive premium thresholds. The FCA's transparency mandates have accelerated aggregator channel switching in this cost-conscious segment. Regional repair cost inflation and theft frequency differentials sustain actuarial rate tier elevation compared to southern counterparts.
Scotland
Low-mileage rural drivers in Highland and Grampian regions select fire-and-theft intermediate coverage to balance protection against premium outlay. The Scottish Government's distinct consumer protection frameworks interact with UK-wide FCA rules, creating marginal regulatory friction for cross-border policy administration. Edinburgh and Glasgow retain concentrated broker distribution networks serving dispersed rural policyholders.
Wales
Flood risk exposure in valley communities drives demand for climate parametric products triggered by meteorological data rather than physical inspection. The Welsh Government's active travel policies are gradually reducing per-capita vehicle ownership in Cardiff and Swansea urban cores. Admiral Group's headquarters presence in Cardiff anchors regional employment in insurance data analytics and customer operations.
United Kingdom Car Insurance Market Competitive Landscape
Portfolio diversification dominates the current landscape as carriers rebalance between direct-to-consumer digital channels and embedded automotive partnerships. The United Kingdom car insurance sector exhibits consolidated tiering with three national-scale underwriters commanding significant data infrastructure advantages and a long tail of digital-native specialists capturing switching volumes. Strategic archetypes separate into telematics-integrated direct writers, traditional broker-dependent insurers, and bancassurance-anchored composite carriers. M&A activity concentrates on telematics data assets and digital distribution platforms, while capacity expansion manifests through cloud-native policy administration rebuilds.
Among London-listed composite insurers, Aviva and Direct Line Group exemplify divergent strategic positioning within the same regulatory environment. Admiral Group occupies a distinctive position as a telematics-native direct writer with proprietary behavioral scoring capabilities. These three entities collectively represent the spectrum of competitive responses to FCA pricing transparency mandates, each deploying distinct data architectures and customer acquisition economics.
| Leading Market Players |
|---|
| Admiral Group |
| Direct Line Group |
| Aviva |
| Hastings |
| AXA |
| LV= General Insurance |
| Esure |
| RSA |
| Ageas |
| Others |
Pricing and Supply Chain Analysis
Claims cost inflation flows from repair labor rates and replacement part tariffs through to renewal premium tiers, with Greater London policyholders absorbing steeper pass-through than Midlands counterparts due to garage density and theft frequency differentials.
Pricing Analysis
Input-cost pass-through from telematics hardware and data infrastructure investments is compressing margins on usage-based policies while fixed-premium comprehensive coverage retains residual pricing power. Price differentiation rests on behavioral scoring granularity and digital distribution efficiency, with smartphone-integrated platforms commanding premium positioning against broker-dependent incumbents. Pricing pressure stems from FCA transparency mandates eliminating loyalty penalty cross-subsidies. Young drivers in urban centers exhibit highest price sensitivity; fleet operators demonstrate lowest sensitivity due to integrated risk management requirements.
Supply Chain Analysis
Reverse-logistics flows for telematics device refurbishment and redeployment create secondary supply channels for cost-conscious insurers expanding usage-based portfolios. Hardware sourcing concentrates in China, Taiwan, and South Korea for GPS modules and cellular chipsets. Component dependencies include semiconductor memory, lithium-ion power cells, and injection-molded housings. Single-source vulnerability in cellular network provisioning poses concentrated risk. Distribution runs through OEM installation partnerships, aftermarket fitters, and direct-to-consumer mail fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in telematics-enabled premium tiers where behavioral data exclusivity defends rate adequacy against regulatory transparency compression.
For Market Incumbents: Lock in telematics data infrastructure advantages through proprietary scoring algorithm development and exclusive hardware partnerships before FCA-mandated data portability rules crystallize. Legacy core system replacement cycles must accelerate to ingest real-time telemetry without multimillion-pound disruption. Cloud-native policy administration investment represents the critical defensive lever against digital-native entrants. For New Entrants and Emerging Players: Smartphone-native behavioral scoring platforms offer the most penetrable wedge for capturing young driver segments in Greater London and South East postcodes where incumbent renewal rate structures face regulatory dismantling. White-space targets include pay-per-mile products for low-mileage rural retirees and embedded insurance integration with automotive OEM point-of-sale channels. Direct-to-consumer mobile acquisition with instant policy issuance provides the optimal go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier carriers with legacy auto-renewal concentration face acute margin compression from FCA pricing remedy enforcement. Long-term viability favors carriers with telematics-native data architectures and direct distribution scale over broker-dependent incumbents with cloud migration backlogs. Acquisition target archetypes include digital-native insurers with proprietary behavioral scoring capabilities and embedded insurance platform specialists. Signal to monitor: regulatory clarity on telematics data ownership frameworks as inflection indicator for next-generation product design economics.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Infrastructure Investment | Proprietary behavioral scoring algorithms defend rate adequacy against FCA transparency compression. |
| Cloud-Native Policy Administration Rebuild | Real-time telemetry ingestion enables usage-based product expansion without legacy system constraints. |
| Embedded Insurance Partnership | OEM point-of-sale integration bypasses aggregator channel fragmentation and captures vehicle-finance-linked demand. |
| Open Banking Premium Financing Integration | Real-time affordability scoring at quote stage reduces friction in young driver acquisition funnels. |
| Climate Parametric Product Development | Flood and storm triggers address coverage gaps in comprehensive policies for Welsh valley communities. |
Research Methodology
Coverage spans England, Scotland, Wales, and Northern Ireland, with primary inputs from each constituent nation informing regional risk profile differentiation. The analysis combines primary interviews with actuarial directors, telematics platform engineers, FCA policy specialists, and fleet procurement managers with secondary validation from regulatory filings, insurance sector trade data, and vehicle registration databases. Bottom-up policy volume modeling and top-down premium income triangulation cross-validate segment-level estimates.
Granularity-level modeling operates at coverage type, policy duration, customer segment, and payment model dimensions, with additional disaggregation by metropolitan statistical area for pricing dispersion analysis. CAGRs derive from trend extrapolation of telematics penetration curves, FCA regulatory implementation timelines, and fleet operator procurement cycle patterns. Forecast inputs incorporate repair cost inflation indices, theft frequency regional differentials, and autonomous vehicle liability framework evolution scenarios across the projection horizon.
The model holds under stable regulatory implementation schedules and gradual telematics adoption curves; deviation in FCA enforcement intensity or breakthrough autonomous vehicle liability legislation would shift carrier capital allocation and product development priorities. Forecasts reflect these baseline assumptions with explicit sensitivity to data ownership litigation outcomes and legacy system replacement cycle disruptions. Practitioners should monitor FCA supervisory statement releases and telematics patent dispute resolutions for early signals of structural inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
China Parametric Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
Microinsurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
Europe Entertainment Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Aviation Insurance Market
Insurance
Reinsurance Carriers Market
Insurance
Property and Casualty Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Liability Insurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Digital Insurance Market
Insurance
Data Analytics in Insurance Market