
 Travel Insurance Market | 2026-2036
Travel Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Travel Insurance Market Intelligence
Buyer concentration among online travel agencies is expanding as digital distribution captures a larger share of policy placements. Allianz Travel leverages its airline partnership network to sustain premium volume. AIG Travel Guard competes through specialized medical evacuation capabilities. Berkshire Hathaway Travel Protection differentiates on streamlined claims automation.
Travel insurance is a short-term risk-transfer contract indemnifying policyholders against financial losses from trip cancellation, medical emergencies, or baggage incidents during journeys, typically underwritten through aggregated actuarial pools and distributed via embedded checkout integrations. Its primary commercial purpose is to reduce traveler exposure to high-severity, low-probability financial shocks while enabling tourism and business mobility. Single Trip coverage anchors the product mix for occasional leisure travelers, while Annual Multi-Trip policies command higher renewal rates and customer lifetime value among frequent flyers. Distribution through mobile apps represents the fastest-growing channel, capturing younger demographics and last-minute purchase behavior.
Regulators including the EU's EIOPA, the US state insurance commissioners through the NAIC model laws, and the UK's FCA conduct standards shape solvency requirements, policy disclosure rules, and claims handling timelines that directly affect product design and pricing latitude. GDPR and emerging AI governance frameworks in Europe impose data processing constraints on automated underwriting and claims algorithms. Stakeholders must monitor how evolving consumer protection mandates interact with digital distribution scale to determine capital allocation between direct-to-consumer platforms and traditional broker networks.
Market Dynamics
Embedded checkout integrations and mobile-first distribution are compressing purchase cycles while EU AI Act compliance costs force algorithmic underwriting redesigns across European portfolios.
Growth Catalysts
- Post-pandemic corporate mobility:Business travelers are expanding coverage purchases as employer duty-of-care obligations tighten and international assignment volumes recover.
- GDPR-compliant automation:European insurers are deploying privacy-preserving claims algorithms that reduce settlement timelines while satisfying supervisory authority mandates.
- Airline partnership density:Flagship carriers are embedding trip protection at point-of-sale, converting previously uninsured leisure passengers into policyholders.
Market Restraints
- Medical cost inflation:Emergency evacuation and hospitalization claims in the United States and Switzerland are experiencing input cost volatility that compresses loss ratios.
- Reinsurance capacity concentration:London and Bermuda markets dominate catastrophe-backed travel covers, creating geographic supply concentration risk for peak peril exposures.
- Algorithmic bias liability:The EU AI Act's prohibited-practice categories are constraining automated underwriting models and forcing manual review layer additions.
Strategic Opportunities
- India outbound tourism:Underpenetrated middle-class travelers from Mumbai and Delhi represent expansion white space for annual multi-trip products.
- Parametric weather triggers:Convergence of satellite data streams with smart contract infrastructure enables automatic cancellation payouts without claims documentation.
- Digital nomad visas:Portugal, Estonia, and Costa Rica are creating regulatory tailwinds for long-stay medical and equipment coverage products.
Industry Challenges
- Actuarial-data science integration:Traditional reserving teams lack fluency in machine-learning model validation required by emerging AI governance frameworks.
- Legacy core system modernization:Policy administration platforms built for annual renewal cycles require expensive reconfiguration to support real-time embedded distribution.
- Cross-border licensing complexity:Passporting arrangements under Solvency II demand specialized compliance functions that strain mid-tier carrier organizational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel Insurance Market |
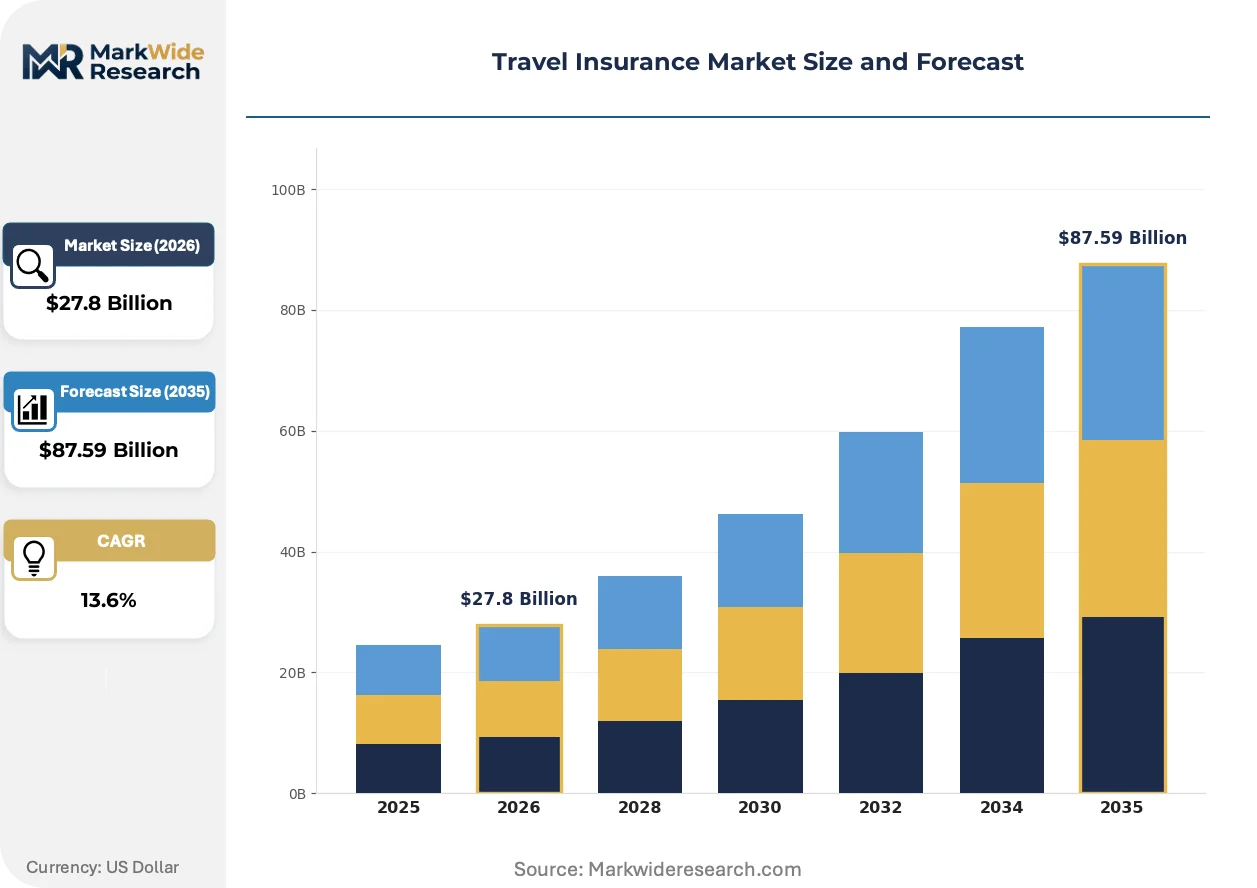
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $87.59 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Trip, Annual Multi-Trip, Backpacker, Family Coverage Type: Medical Expenses, Trip Cancellation, Lost Luggage, Personal Liability Distribution Channel: Direct Sales, Online Travel Agencies, Insurance Brokers, Mobile Apps Customer Type: Individual Travelers, Business Travelers, Families, Students |
| Companies Covered | Travelex Insurance, World Nomads, Allianz Travel, Berkshire Hathaway Travel Protection, Trawick International, AIG Travel Guard, Nationwide, HTH Travel Insurance, Seven Corners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel Insurance Market Strategic Shifts & Innovations
Real-time data streams and automated decision infrastructure are displacing batch-processed underwriting while regulatory technology investments absorb compliance overhead previously handled through legal staffing.
Machine learning risk scoring is integrating telematics from wearables and mobile location data to dynamically price adventure sports and senior traveler segments. InsurTech platforms serving the 25-40 demographic are adopting these models fastest. The technology is compressing traditional age-band pricing into individualized risk curves that reward behavioral data sharing.
The EU AI Act's risk-classification framework is forcing insurers to restructure automated claims algorithms around human-in-the-loop requirements. High-risk system designations now trigger conformity assessments that extend product launch timelines. European carriers are responding by segmenting algorithmic decisions between fully automated low-value claims and escalated manual review pathways for disputed or high-severity cases.
Last-minute mobile purchase behavior is fragmenting distribution away from broker-mediated annual policies toward app-embedded single-trip covers triggered by booking confirmations. Online travel agencies are capturing this shift through white-label partnerships that displace direct insurer relationships. The United States and United Kingdom display the highest concentration of these impulse purchases, particularly among weekend leisure travelers.
Travel Insurance Market Segmentation
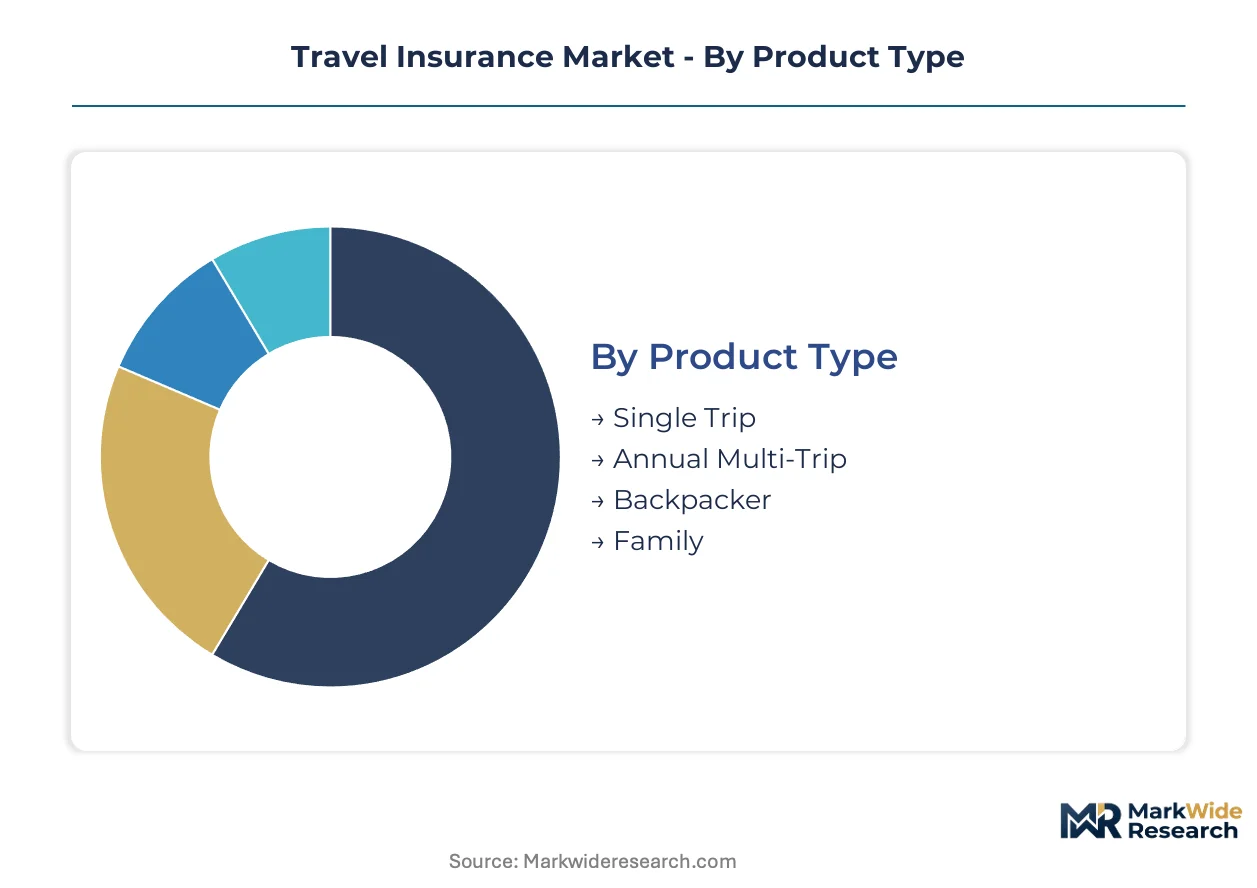
Travel insurance segmentation reflects divergent risk profiles, purchase timing, and distribution economics. Product architecture and channel selection determine margin capture and renewal economics across traveler cohorts.
Product Type:
Travelers segment by trip frequency and duration tolerance, with pricing models calibrated to expected claim incidence and administrative cost recovery.
- Single Trip:Short-duration coverage activated per journey with fixed premium-to-benefit ratios. Casual leisure travelers in the United States and United Kingdom dominate uptake, driven by airline checkout embedding and impulse purchase mechanics at booking confirmation.
- Annual Multi-Trip:Year-round protection for unlimited journeys within geographic limits, commanding higher upfront premiums but superior lifetime value through renewal retention. Frequent corporate flyers and retired leisure travelers in Germany and Australia concentrate demand, reinforced by employer duty-of-care mandates and snowbird migration patterns.
- Backpacker:Extended-duration coverage for multi-month journeys with adventure activity inclusions and higher medical evacuation limits. Budget-conscious long-haul travelers from the Netherlands and Canada select this tier.
- Family:Bundled protection covering multiple travelers under single policy structures with dependent-inclusive pricing. School-holiday vacationers in France and Spain drive seasonal volume spikes.
Single Trip leads volumes today; Annual Multi-Trip is gaining share fastest.
Coverage Type:
Benefit design prioritizes either high-frequency low-severity events or catastrophic financial exposure, with premium allocation reflecting actuarial loss cost differentials.
- Medical Expenses:Reimbursement for emergency treatment and hospitalization abroad, typically the largest claim severity category. United States travelers purchasing coverage for European destinations concentrate demand, responding to domestic healthcare cost differentials and Schengen visa insurance mandates.
- Trip Cancellation:Indemnity for prepaid non-refundable travel investments when insured events prevent departure. Business travelers with high-value conference registrations and luxury leisure segments in Switzerland and Singapore drive attachment rates.
- Lost Luggage:Coverage for baggage delay, damage, or permanent loss during transit. Airline partnership distribution channels in the United Kingdom and United Arab Emirates push this as add-on coverage.
- Personal Liability:Protection against third-party injury or property damage claims during travel. Long-stay visa holders in Portugal and Costa Rica select this for legal system exposure in unfamiliar jurisdictions.
Medical Expenses anchors premium volume; Trip Cancellation is climbing the fastest as post-pandemic cancellation anxiety persists.
Distribution Channel:
Channel economics vary by customer acquisition cost, conversion timing, and data ownership, with digital intermediaries capturing margin from traditional broker relationships.
- Direct Sales:Insurer-controlled websites and call centers capturing full margin but bearing marketing expenditure burden. Established carriers with brand recognition in Germany and Japan maintain this channel for policyholder data retention.
- Online Travel Agencies:Embedded checkout placement converting travel bookers at point-of-sale with minimal friction. Expedia and Booking.com partnerships dominate in the United States and United Kingdom, displacing direct insurer relationships through white-label economics.
- Insurance Brokers:Advisory-led placement for complex multi-trip or corporate programs requiring customization. Small and medium enterprises in Italy and Australia rely on broker counsel for duty-of-care compliance.
- Mobile Apps:Last-minute purchase interface capturing impulse demand and younger demographics. Fintech-integrated platforms in South Korea and Brazil are expanding fastest through wallet and payment app embedding.
Online Travel Agencies currently dominate placement volume; Mobile Apps show the steepest expansion trajectory as smartphone booking penetration deepens.
Customer Type:
Buyer classification reflects trip purpose, decision-making unit size, and risk tolerance, with product bundling adapted to group dynamics and organizational procurement.
- Individual Travelers:Solo policyholders purchasing for personal leisure or independent business travel. Urban professionals in the United States and United Kingdom represent the core volume base, with purchase timing increasingly compressed toward departure dates.
- Business Travelers:Corporate-funded or reimbursed coverage tied to employer travel policies and duty-of-care obligations. Technology and professional services firms in Ireland and the Netherlands are expanding coverage mandates as international assignment volumes recover.
- Families:Multi-traveler households requiring dependent coverage and simplified claims processes for group disruptions. School-holiday planners in France and Australia concentrate seasonal demand.
- Students:Younger travelers on exchange programs or gap-year journeys with extended stay durations and budget constraints. Study-abroad participants from India and China selecting European and North American destinations drive this segment.
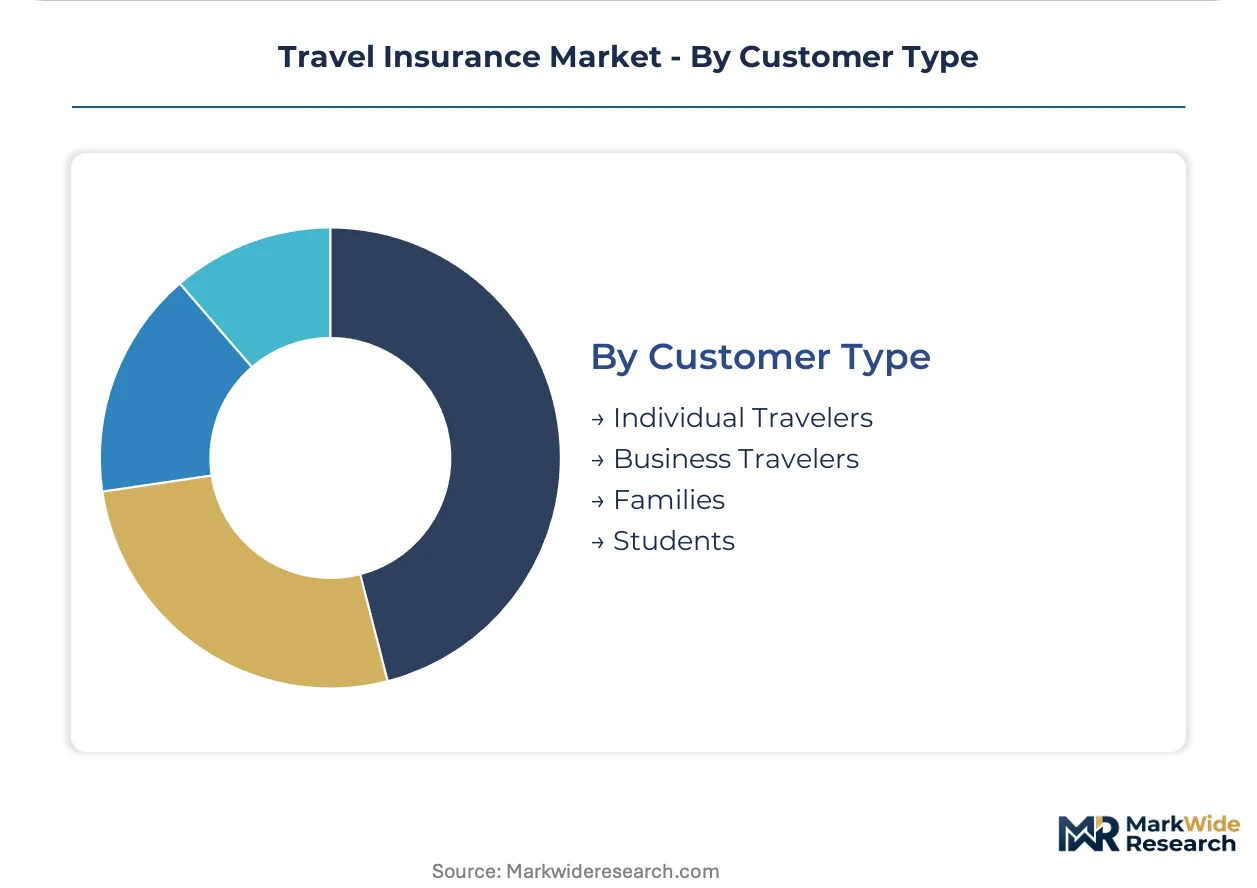
Individual Travelers generate the highest absolute policy count; Business Travelers are expanding most quickly as corporate mobility budgets normalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates premium volume through airline checkout embedding that the United Kingdom matches through online travel agency partnerships, while Germany and Australia sustain renewal economics through employer-mandated annual multi-trip coverage.
United States
Domestic travel volume recovery and outbound tourism expansion concentrate demand in California and Florida gateways. State insurance commissioners through NAIC model laws govern solvency and disclosure requirements. New York and Chicago corporate headquarters drive employer-funded business travel policy expansions as duty-of-care obligations tighten.
Germany
Frequent corporate flyers and retired leisure travelers sustain annual multi-trip renewal rates above European averages. EIOPA standards and GDPR compliance reshape automated underwriting algorithm design. Munich and Frankfurt insurance clusters host actuarial teams integrating privacy-preserving claims automation.
United Kingdom
Impulse single-trip purchases through mobile apps capture weekend leisure travelers departing from London and Manchester. FCA conduct standards govern policy disclosure and claims handling timelines. Edinburgh and Birmingham distribution centers white-label embedded checkout products for online travel agencies.
Australia
Snowbird migration patterns and employer duty-of-care mandates concentrate annual multi-trip demand in Sydney and Melbourne. APRA prudential standards govern capital adequacy for travel underwriters. Brisbane and Perth hubs process claims automation for Asia-Pacific outbound segments.
India
Underpenetrated middle-class travelers from Mumbai and Delhi represent expansion white space for annual multi-trip products. IRDAI regulations govern foreign reinsurance dependencies and distribution licensing. Bangalore and Hyderabad insurtech clusters develop mobile-first distribution platforms for last-minute purchase behavior.
Travel Insurance Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Large multi-line carriers leverage balance sheet capacity and airline partnership networks to sustain premium volume, while specialized travel underwriters differentiate through medical evacuation capabilities and claims automation speed. Three strategic archetypes dominate: integrated financial services groups with travel divisions, dedicated travel insurance specialists, and technology-enabled managing general agents. Competitive intensity concentrates on embedded distribution partnerships and algorithmic underwriting investments that compress quote-to-bind timelines.
Among diversified insurance groups, Allianz Travel and AIG Travel Guard occupy positions representing scale-driven distribution density and specialized risk transfer capabilities respectively. Berkshire Hathaway Travel Protection exemplifies the technology-forward archetype through streamlined claims automation infrastructure. These three anchors illustrate how market participants segment between partnership-network scale, medical evacuation specialization, and digital process efficiency as distinct competitive vectors.
| Leading Market Players |
|---|
| Travelex Insurance |
| World Nomads |
| Allianz Travel |
| Berkshire Hathaway Travel Protection |
| Trawick International |
| AIG Travel Guard |
| Nationwide |
| HTH Travel Insurance |
| Seven Corners |
| Others |
Cost & Logistics Intelligence
Actuarial talent concentration in London and Bermuda sustains labor-cost differentials that widen pricing-tier spreads between algorithmic low-touch products and manually underwritten specialty covers. GDPR compliance investments in European portfolios compress margins on standard-tier offerings while premium-tier evacuation policies retain pricing power through medical network exclusivity.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for standard single-trip coverage as insurtech platforms automate underwriting at reduced acquisition cost. Pricing stratifies across premium evacuation services, standard bundled protection, and economy medical-only tiers, with differentiation driven by medical network breadth and claims automation speed. Pricing pressure stems from embedded checkout commissions captured by online travel agencies. Leisure travelers booking through airline partnerships show highest price sensitivity; corporate accounts with duty-of-care mandates demonstrate lowest.
Supply Chain Analysis
GDPR certification and Solvency II compliance gating restrict algorithmic underwriting platform deployment to carriers with established European regulatory infrastructure. Reinsurance capacity concentrates in Bermuda, London, and Zurich, with medical evacuation networks anchored in South Africa, Thailand, and Germany. The supply chain draws from satellite data providers, wearable telemetry platforms, and emergency medical service networks. Single-source vulnerability runs through London market catastrophe reinsurance for peak peril exposures. Distribution runs through embedded checkout integrations at online travel agencies and airline booking engines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The travel insurance market functions as a geographic-arbitrage play where European compliance costs exceed Asian insurtech operational expenses, creating margin expansion opportunities for carriers with modular regulatory infrastructure.
For Market Incumbents: Acquire parametric weather data and smart contract infrastructure to automate cancellation payouts before insurtech entrants capture last-minute mobile distribution. Defend renewal economics in annual multi-trip segments through employer duty-of-care partnership deepening. Offset algorithmic bias liability exposure under EU AI Act by segmenting decisions between automated low-value claims and escalated manual review pathways. For New Entrants and Emerging Players: Embedded parametric triggers represent the most penetrable technology-first wedge for new market entry, converting weather satellite data into automatic payout infrastructure without claims documentation friction. Target underpenetrated middle-class outbound travelers from Mumbai and Delhi through mobile-first annual multi-trip products. Pursue white-label partnerships with fintech payment apps in South Korea and Brazil to capture impulse purchase behavior. For Investors and Strategic Acquirers: Managing general agents with embedded distribution partnerships are the most active acquirer targets in this space, as traditional carriers seek algorithmic underwriting capabilities without legacy system reconfiguration. Long-term viability hinges on regulatory technology investments that absorb compliance overhead previously handled through legal staffing. Watch for inflection signals in digital nomad visa issuance volumes from Portugal, Estonia, and Costa Rica as indicators of long-stay coverage product demand.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Claims Automation | Smart contract infrastructure enables automatic cancellation payouts without documentation friction. |
| Embedded Checkout Partnership | Online travel agency white-label agreements displace direct insurer relationships at point-of-sale. |
| GDPR-Compliant Algorithm Redesign | Privacy-preserving claims automation satisfies EIOPA mandates while reducing settlement timelines. |
| Digital Nomad Visa Product Development | Long-stay medical and equipment coverage captures regulatory tailwinds from Portugal and Estonia. |
| Mobile-First Distribution Platform | App-embedded single-trip covers capture last-minute purchase behavior in United States and United Kingdom. |
Research Approach
Multiple input streams — executive interviews with travel insurance underwriters, actuarial directors, and online travel agency partnership leads; secondary validation through EIOPA regulatory filings, NAIC model law databases, and airline partnership disclosure documents; plus embedded checkout transaction data — were reconciled through bottom-up policy volume estimation and top-down premium aggregation triangulation.
Historical claims frequency patterns were cross-referenced against panel input from reinsurance brokers and medical evacuation network operators to anchor projections. The analytical framework segmented across product type, coverage design, distribution channel, and customer archetype throughout the forecast period. CAGRs were derived from trend extrapolation adjusted for regulatory intervention timing and technology adoption curves, with medical cost inflation and reinsurance capacity concentration as specific forecast sensitivity inputs.
The model holds under stable regulatory enforcement intensity; deviation in EU AI Act prohibited-practice interpretations or sudden reinsurance capacity withdrawal would shift trajectory. Forecasts reflect documented assumptions regarding embedded checkout penetration rates and corporate mobility recovery pace. A model refresh is warranted upon material change in digital nomad visa issuance policy or airline partnership exclusivity arrangements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
India Liability Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
IoT Insurance Market
Insurance
Musical Instrument Insurance Market
Insurance
Takaful Market
Insurance
Reinsurance Carriers Market
Insurance
China Business Income Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
New Zealand Property and Casualty Insurance Market