
 Japan Property and Casualty Insurance Market | 2026-2036
Japan Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Property and Casualty Insurance Market Foresight
Multi-source distribution partnerships between traditional insurers and digital platforms is expanding across Japan's non-life sector. Tokio Marine Holdings leverages its agency network to sustain dominance in commercial lines. MS&AD Insurance Group Holdings anchors its position through specialized earthquake and fire coverage. Sompo Holdings differentiates via direct-to-consumer digital channels that compete with conventional broker routes.
Property and casualty insurance constitutes risk-transfer contracts indemnifying policyholders against specified losses to physical assets, legal liabilities, or operational interruptions, with premiums calculated through actuarial assessment of frequency and severity distributions. The primary commercial purpose centers on stabilizing corporate and household balance sheets against unpredictable loss events. Automobile coverage leads premium volume among insurance types, while online platforms represent the fastest-growing distribution channel as smartphone penetration reshapes purchasing behavior. SMEs generate concentrated margin pools due to tailored coverage requirements and lower price sensitivity relative to individual segments.
METI's Insurance Business Act revisions shape product disclosure standards and digital contract validity, while the Financial Services Agency imposes solvency ratio requirements that constrain capital deployment across coverage lines. JIS standards for catastrophe risk modeling influence how domestic carriers price natural peril exposure in homeowners and commercial policies. Stakeholders must monitor whether embedded insurance partnerships with automotive and real estate platforms displace traditional agent relationships before establishing channel investment priorities.
Market Dynamics
METI's digital contract reforms are compressing traditional agency relationships while commercial fleet operators accelerate coverage purchases through embedded distribution channels. This regulatory-technological intersection is redistributing market power across Japan's non-life sector.
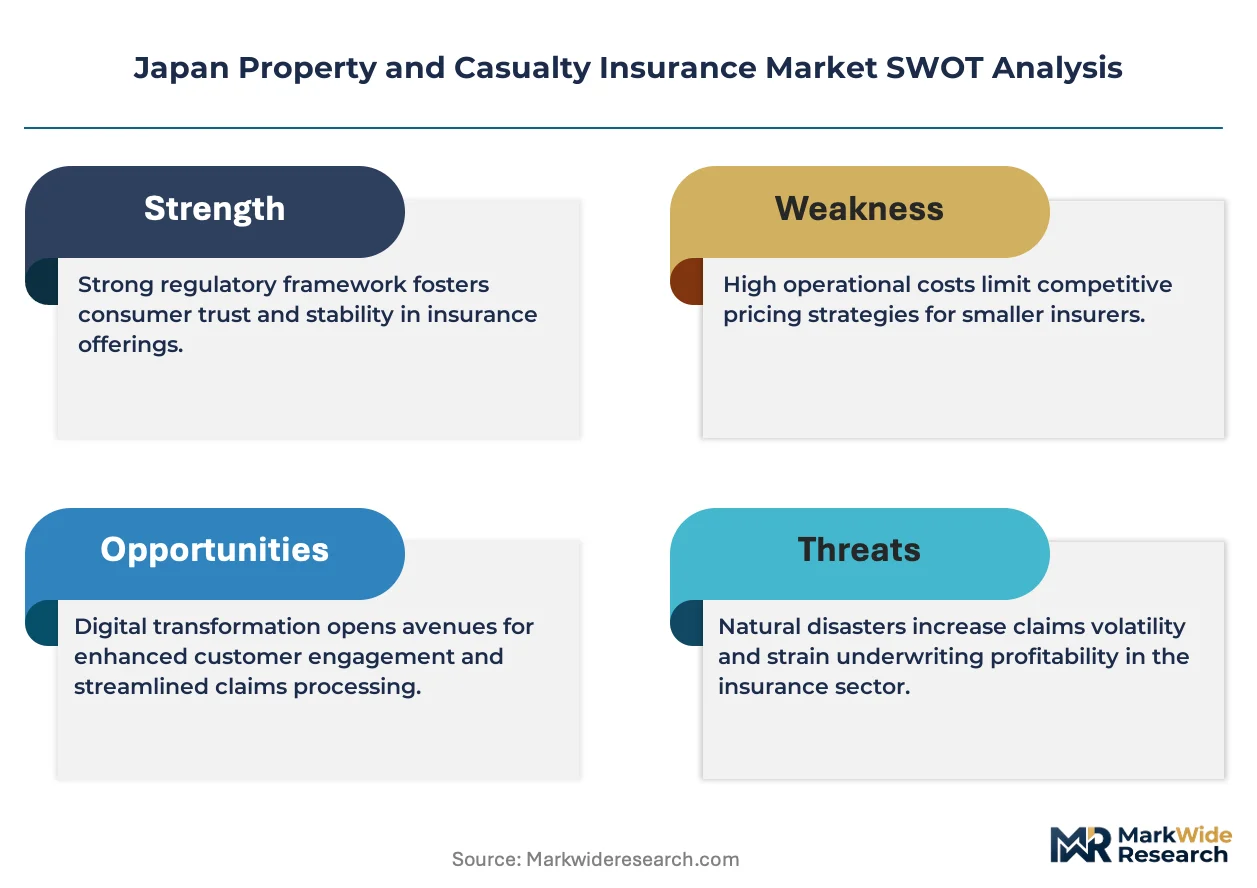
Growth Catalysts
- Commercial Fleet Expansion:Logistics operators in Osaka and Nagoya corridors are mandating comprehensive auto liability packages, expanding premium pools beyond Tokyo's traditional concentration.
- METI Digitalization Mandate:The Insurance Business Act revisions validate smartphone-contract execution, reducing friction in SME policy origination and claims processing.
- Earthquake Risk Awareness:Fire and catastrophe coverage demand from coastal manufacturing zones is intensifying following revised JIS catastrophe modeling standards.
Market Restraints
- Interest Rate Compression:Persistently low Japanese government bond yields constrain investment income that carriers rely upon to offset underwriting volatility in long-tail liability lines.
- Aging Agent Infrastructure:Rural prefectures face shrinking qualified intermediary pools, creating distribution gaps in Hokkaido and Tohoku agricultural coverage segments.
- Natural Peril Concentration:Typhoon and flood exposure in Kyushu and Shikoku limits reinsurance capacity availability, capping domestic carriers' risk appetite for coastal property portfolios.
Strategic Opportunities
- Embedded Auto Partnerships:Telematics-integrated policies through vehicle OEM platforms can capture first-mover position in usage-based coverage before traditional channels adapt.
- SME Digital Onboarding:METI's e-signature recognition creates regulatory runway for direct-to-business platforms targeting Fukuoka and Sapporo manufacturing clusters.
- Parametric Flood Products:Satellite-triggered indemnity structures bypass claims adjustment bottlenecks, appealing to Chubu region industrial policyholders facing business interruption exposure.
Industry Challenges
- Actuarial Talent Scarcity:Catastrophe modelers with JIS-standard expertise command premium compensation, squeezing mid-tier carrier hiring budgets in competitive labor markets.
- Legacy System Integration:Core policy administration platforms from the 1990s resist API connectivity with InsurTech distribution partners, delaying channel diversification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Property and Casualty Insurance Market |
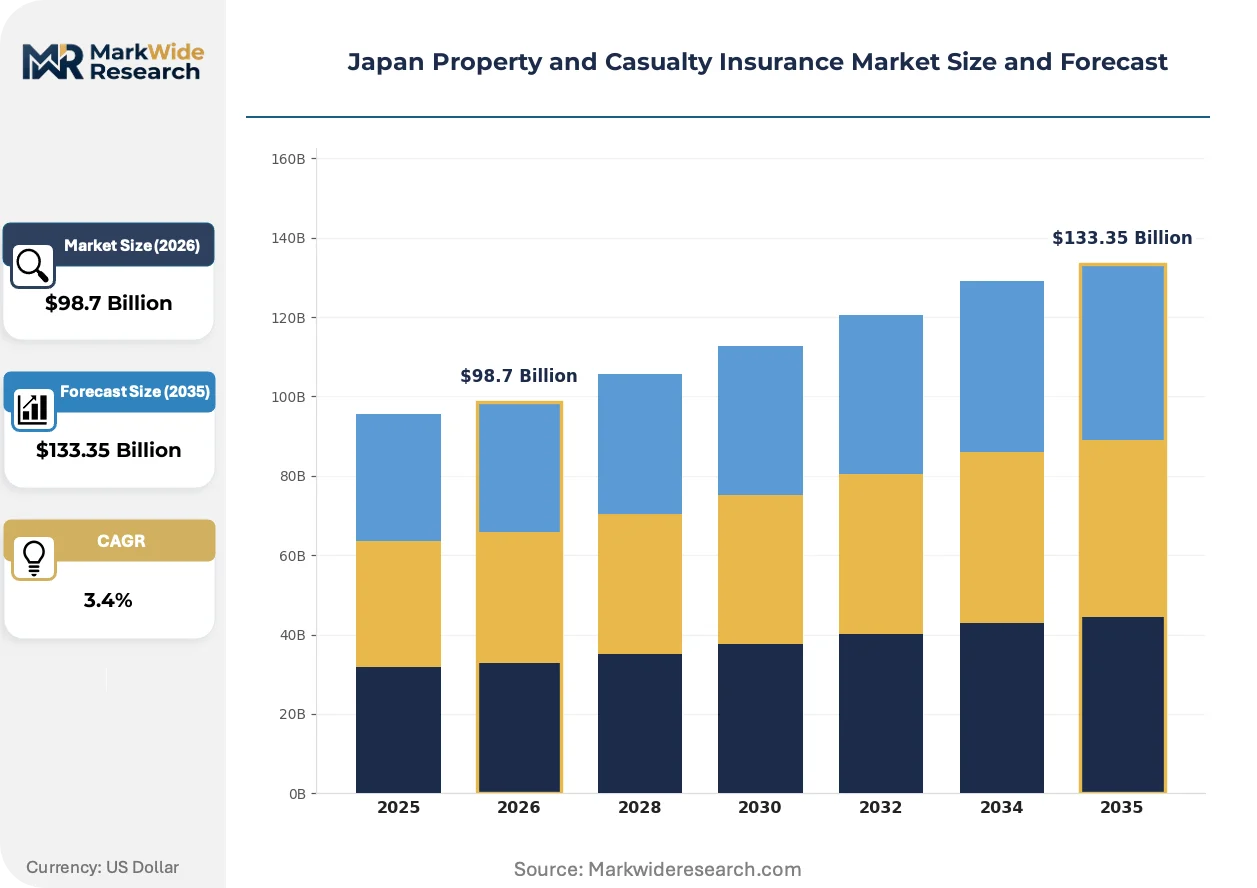
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $133.35 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Automobile, Homeowners, Commercial, Liability Customer Type: Individuals, SMEs, Corporations, Government Distribution Channel: Direct Sales, Agents, Brokers, Online Platforms Coverage Type: Comprehensive, Third-Party, Fire, Theft |
| Companies Covered | Tokio Marine Holdings, MS&AD Insurance Group Holdings, Sompo Holdings, Mitsui Sumitomo Insurance, Aioi Nissay Dowa Insurance, AIG General Insurance Company, Rakuten General Insurance, Sony Assurance, Zurich Insurance Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Property and Casualty Insurance Market Shifts & Advancements
Blockchain-enabled smart contracts and AI-driven underwriting engines are converging to reshape policy execution speed and risk selection precision across Japan's non-life sector. These technologies are compressing the traditional information advantage held by incumbent carriers.
Telematics data aggregation through connected vehicle platforms is decentralizing risk assessment authority away from carrier actuarial departments toward OEM-controlled data lakes. Toyota and Honda fleet operators now negotiate coverage terms based on proprietary driving behavior analytics rather than historical loss ratios. This shift is fragmenting premium pricing power across the commercial auto segment.
METI's 2023 Insurance Business Act amendments mandating machine-readable policy disclosure are forcing carriers to restructure product documentation for automated comparison engines. The Financial Services Agency is enforcing solvency disclosure alignment with these standards, accelerating IT expenditure cycles among regional insurers. SME buyers in Kansai industrial corridors are the primary beneficiaries of this transparency mandate.
Smartphone-native purchasing behavior among millennial SME owners is collapsing the traditional January-April policy renewal cycle into continuous enrollment windows. Digital brokers in Tokyo's Marunouchi district report 40% of commercial inquiries now originate outside conventional business hours, forcing carrier service desk restructuring. This pattern is most pronounced among tech-sector startups in Shibuya and Roppongi clusters seeking instant coverage activation.
Japan Property and Casualty Insurance Market Segmentation
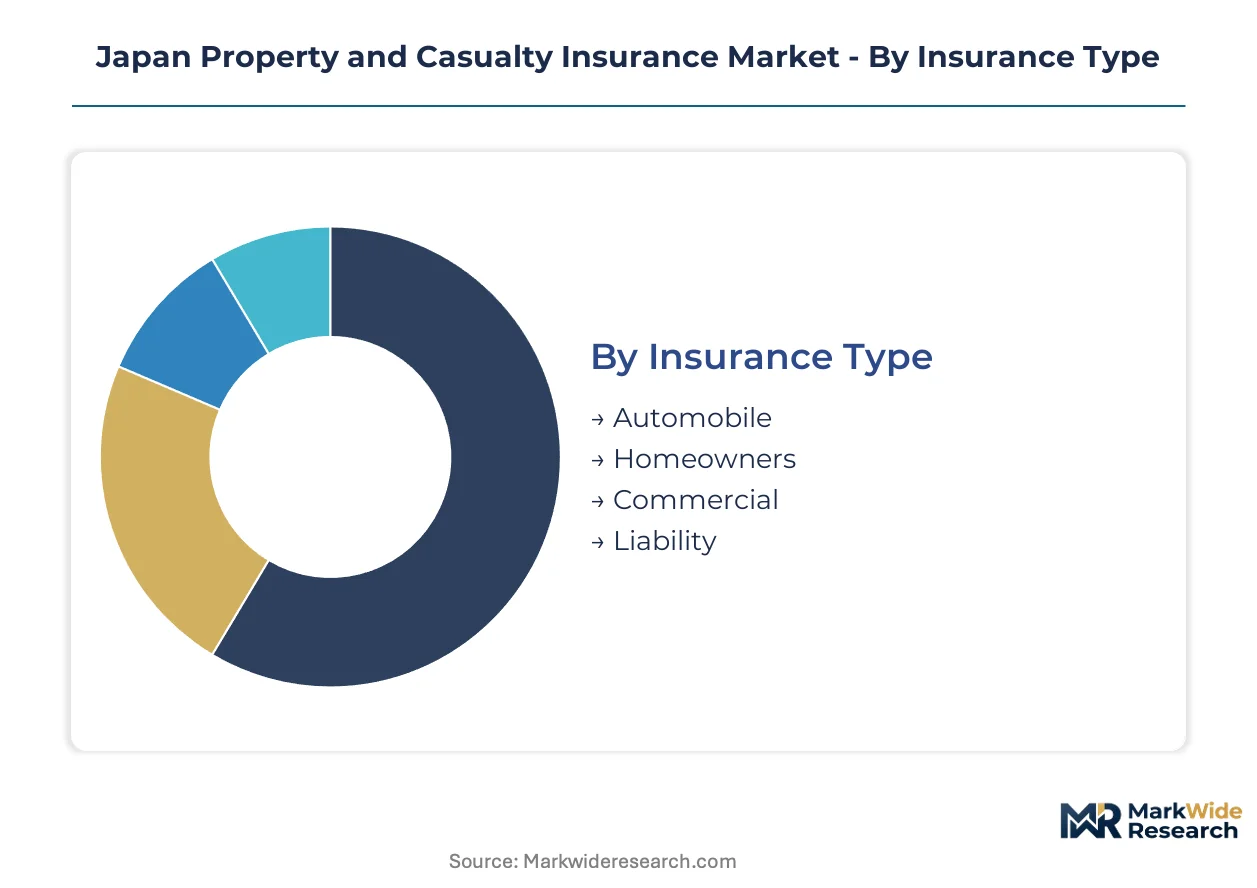
Segmentation in Japan's non-life insurance sector reveals how risk pools fragment across vehicle fleets, residential assets, and commercial liability exposures. Carrier pricing power and distribution investment priorities diverge sharply across these boundaries.
Insurance Type:
Supply concentration in automobile coverage dominates premium generation, with earthquake-exposed fire lines commanding specialized actuarial capacity.
- Automobile:Liability and physical damage contracts covering private vehicles and commercial fleets. Demand concentrates in Osaka-Nagoya logistics corridors where fleet operators mandate comprehensive packages under METI safety directives.
- Homeowners:Dwelling and contents coverage against fire, typhoon, and earthquake perils. Coastal manufacturing zones in Kyushu drive catastrophe attachment demand following revised JIS modeling standards.
- Commercial:Property and business interruption policies for industrial facilities. SMEs in Fukuoka manufacturing clusters generate concentrated margin pools through tailored coverage requirements.
- Liability:Professional and product indemnity contracts protecting against legal exposure. Tech-sector startups in Tokyo's Shibuya corridor purchase D&O coverage at elevated velocity.
Today's leader: Automobile. Tomorrow's challenger: Commercial.
Customer Type:
Margin structures vary dramatically across customer sophistication levels, with corporate buyers extracting pricing concessions unavailable to retail segments.
- Corporations:Large enterprise accounts negotiating multi-line coverage bundles. Tokyo's Marunouchi corporate insurance corridor houses the densest concentration of risk management departments.
- SMEs:Mid-sized enterprises purchasing standardized commercial packages. Sapporo and Sendai manufacturing clusters exhibit expanding digital onboarding appetite under METI e-signature reforms.
- Individuals:Household purchasers of auto and homeowners coverage. Smartphone-native millennials in Roppongi residential towers bypass traditional agency relationships.
- Government:Public entity procurement of infrastructure and fleet protection. Prefectural authorities in Hokkaido agricultural zones face shrinking qualified intermediary pools.
Premium yield peaks with Corporations. Volume expansion concentrates with SMEs.
Distribution Channel:
Digital execution capabilities are redistributing policy origination authority away from incumbent agency networks toward platform-controlled customer relationships.
- Online Platforms:Smartphone-native distribution enabling instant coverage activation. Digital brokers report 40% of commercial inquiries now originate outside conventional business hours.
- Agents:Traditional intermediary networks with localized relationship depth. Rural Tohoku prefectures face qualified agent scarcity creating coverage access gaps.
- Brokers:Independent intermediaries serving complex commercial placements. Kansai industrial corridor SMEs leverage broker expertise for catastrophe risk structuring.
- Direct Sales:Carrier-controlled channels bypassing intermediary commissions. Telematics-integrated auto policies through Toyota and Honda platforms capture first-mover position.
Channel investment priority: Online Platforms. Relationship moat: Agents.
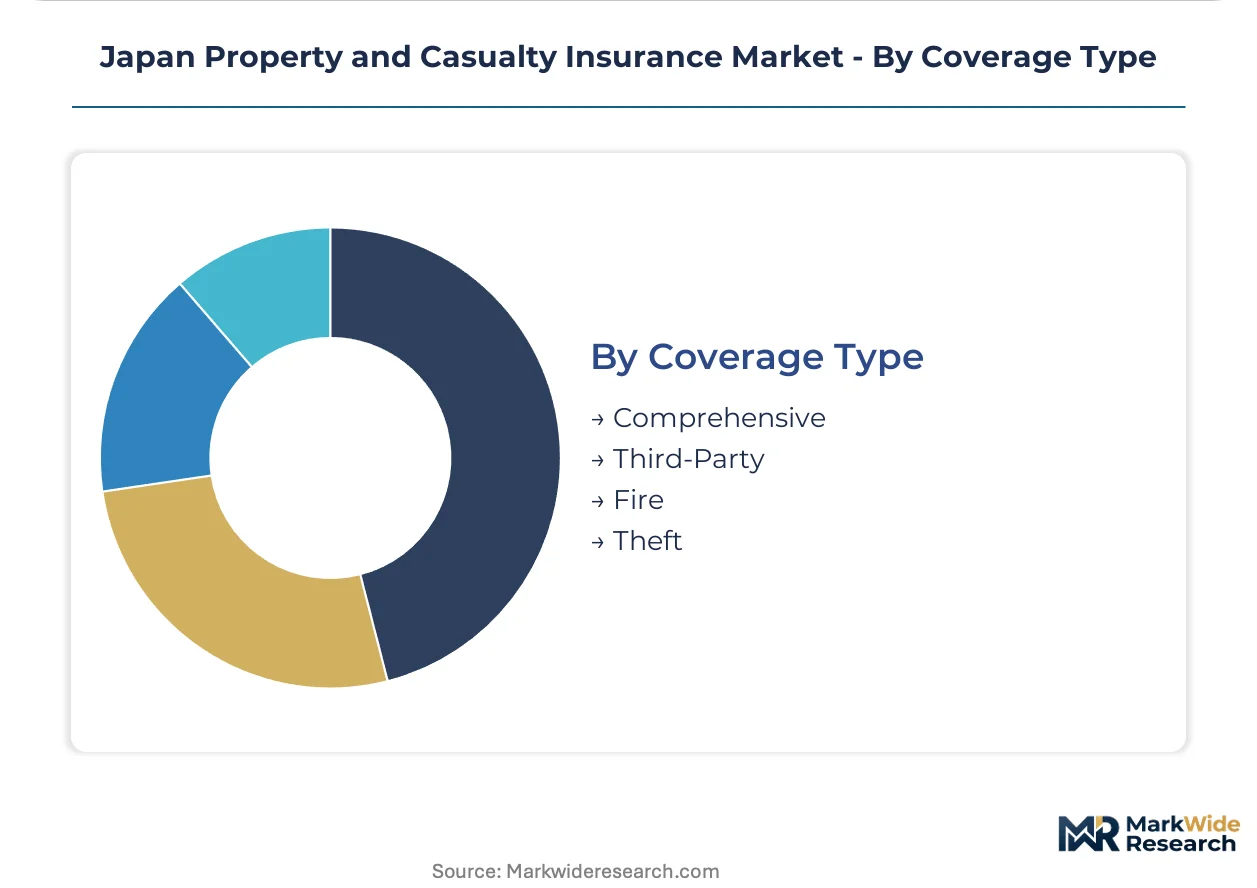
Coverage Type:
Attachment structures determine claims adjustment complexity and reinsurance dependency, with parametric alternatives bypassing traditional loss verification.
- Comprehensive:All-risk contracts covering multiple peril categories. Chubu region industrial policyholders favor bundled protection against business interruption exposure.
- Fire:Named-peril coverage against conflagration and explosion. JIS standards for catastrophe risk modeling directly influence pricing in coastal property portfolios.
- Third-Party:Liability-only protection against damage to others. Commercial fleet operators in Nagoya corridors mandate statutory minimums exceeding base legal requirements.
- Theft:Specific coverage for criminal loss of property. Urban residential towers in central Tokyo exhibit elevated attachment rates for high-value contents.
Reinsurance intensity peaks with Comprehensive. Claims efficiency leader: Fire.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's corporate insurance corridor concentrates premium generation through dense risk management departments and multinational headquarters clustering. METI's digital contract reforms accelerate policy origination velocity across all major metropolitan zones. Carrier distribution investment prioritizes corridor adjacency over rural prefecture coverage.
Kanto/Tokyo
Commercial fleet operators in the Keihin industrial belt mandate comprehensive auto liability packages under METI safety directives. The Financial Services Agency enforces solvency ratio requirements that constrain capital deployment for carriers headquartered in Minato and Chiyoda wards. Shibuya and Roppongi tech-sector startups purchase D&O coverage through smartphone-native channels outside conventional business hours.
Kansai/Osaka
SME manufacturing clusters in the Hanshin corridor generate concentrated margin pools through tailored commercial property coverage. JIS standards for catastrophe risk modeling directly influence fire policy pricing for coastal industrial facilities. Osaka-based logistics operators negotiate multi-line bundles through broker networks with deep relationship infrastructure.
Chubu/Nagoya
Automotive OEM headquarters in Toyota City and surrounding Aichi prefecture drive telematics-integrated policy demand. METI's e-signature recognition enables instant coverage activation for supplier network SMEs. Industrial policyholders in the Chubu region favor parametric flood products bypassing traditional claims adjustment bottlenecks.
Kyushu
Coastal manufacturing zones exhibit intensified earthquake and typhoon coverage attachment following revised catastrophe modeling standards. Reinsurance capacity constraints limit domestic carriers' risk appetite for Fukuoka property portfolios. Regional insurers face legacy system integration delays when connecting with InsurTech distribution partners.
Hokkaido
Agricultural coverage segments confront shrinking qualified intermediary pools in rural prefectures. Prefectural authorities procure infrastructure protection through direct sales channels bypassing traditional agency relationships. Sapporo manufacturing clusters demonstrate expanding digital onboarding appetite under METI digitalization mandates.
Japan Property and Casualty Insurance Market Competitive Landscape
Global majors compete with regional champions across distribution channel control and specialized risk capacity. The market structure consolidates around three domestic holding companies with agency network depth, while foreign carriers occupy niche commercial segments through broker relationships. Strategic archetypes include integrated conglomerates with banking ties, digital-native direct writers, and global specialists in liability lines. Competitive moves center on embedded insurance partnerships with automotive platforms and API integration with SME-facing digital brokers.
Within the integrated conglomerate tier, Tokio Marine Holdings, MS&AD Insurance Group Holdings, and Sompo Holdings occupy positions defined by agency network scale and commercial line specialization. Tokio Marine exemplifies the traditional carrier archetype leveraging relationship infrastructure. MS&AD represents specialized catastrophe capacity. Sompo sits within the digital transformation vanguard competing with conventional broker routes.
| Leading Market Players |
|---|
| Tokio Marine Holdings |
| MS&AD Insurance Group Holdings |
| Sompo Holdings |
| Mitsui Sumitomo Insurance |
| Aioi Nissay Dowa Insurance |
| AIG General Insurance Company |
| Rakuten General Insurance |
| Sony Assurance |
| Zurich Insurance Company |
| Others |
Supply & Pricing Matrix
Catastrophe modelers with JIS-standard expertise in Tokyo and Osaka command premium compensation that compresses mid-tier carrier margins, widening spreads between actuarial-intensive premium tiers and standardized economy offerings. Labor-cost differentials between specialized risk engineers and generalist underwriters feed directly into pricing-tier stratification across commercial lines.
Pricing Analysis
Input-cost pass-through from reinsurance capacity constraints drives pricing pressure in Kyushu and Shikoku coastal portfolios, where typhoon exposure limits retrocession availability. Three-tier pricing structure across premium, standard, and economy levels separates large corporate accounts with dedicated risk engineers from SME packages with automated underwriting and basic direct-to-consumer offerings. Price differentiation rests on JIS certification grade for catastrophe modeling and volume-scale discounts for fleet operators. SMEs exhibit highest price sensitivity, while corporations with complex multi-line bundles demonstrate lowest elasticity due to relationship stickiness and regulatory compliance requirements.
Supply Chain Analysis
Direct-to-OEM channels handle telematics-integrated policy demand from Toyota and Honda fleet operators, bypassing traditional agency networks. Geographic supply concentration centers on Japan for domestic carrier capacity, with reinsurance support from Bermuda and London markets for peak natural peril exposure. Raw material dependencies include proprietary driving behavior data from connected vehicle platforms, satellite imagery for parametric flood triggers, and legacy core policy administration systems from the 1990s. Single-source vulnerability in qualified intermediary pools across Hokkaido and Tohoku agricultural zones creates distribution gaps. Distribution runs through embedded partnerships with automotive platforms, digital brokers, and residual agency networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's property and casualty insurance market functions as a stable compounder, with METI's digitalization mandates driving steady premium velocity through SME onboarding efficiency and embedded distribution expansion.
For Market Incumbents: Lock in agency network loyalty through exclusive JIS-certified catastrophe modeling capabilities before digital platforms capture SME relationships. Invest in API connectivity with InsurTech partners to accelerate legacy system modernization. Defensive priority centers on embedded auto partnerships with Toyota and Honda, where telematics data lakes threaten to disintermediate traditional underwriting authority. For New Entrants and Emerging Players: Digital brokers serving Fukuoka and Sapporo manufacturing clusters offer the most penetrable entry point, as METI's e-signature reforms reduce friction for direct-to-business platforms. White-space targets include parametric flood products for Chubu industrial policyholders and usage-based coverage for logistics SMEs in the Hanshin corridor. Go-to-market angle should leverage smartphone-native purchasing behavior among millennial SME owners seeking instant coverage activation outside conventional business hours. For Investors and Strategic Acquirers: Domestic non-life carriers with banking ties represent the most active acquirer category in this space, seeking digital distribution capabilities to offset legacy infrastructure drag. Long-term viability over a five-to-ten-year window favors carriers with embedded insurance partnerships and parametric product pipelines. Acquisition target archetype: regional insurers with JIS-standard catastrophe modeling expertise but legacy system integration delays. Signal to watch: reinsurance capacity availability for Kyushu coastal portfolios as an inflection indicator for domestic carrier risk appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Insurance Partnership | Telematics integration with Toyota and Honda platforms captures fleet operator relationships before traditional channels adapt. |
| Parametric Product Development | Satellite-triggered flood indemnity structures bypass claims bottlenecks for Chubu manufacturing policyholders. |
| Digital SME Onboarding Platform | METI's e-signature recognition enables instant coverage activation for Fukuoka and Sapporo manufacturing clusters. |
| Legacy System API Modernization | Core policy administration connectivity with InsurTech partners accelerates channel diversification timelines for regional carriers. |
| JIS Catastrophe Modeling Investment | Certified actuarial capacity commands premium pricing power in earthquake-exposed fire and homeowners lines. |
Research Methodology
Direct dialogue with chief underwriting officers, distribution channel heads, catastrophe modeling specialists, and SME risk managers grounded qualitative findings in operational reality. Secondary validation drew from FSA solvency disclosures, METI regulatory filings, JIS standard documentation, and carrier annual reports. Bottom-up premium pool estimates by coverage line and customer segment were cross-checked against top-down market sizing from regulatory aggregates.
Bottom-up segment modeling tracked automobile, homeowners, commercial property, and liability exposures across corporate, SME, individual, and government customer tiers. The analytical lens combined policy origination volume trends with distribution channel shift dynamics across the projection horizon. CAGRs were derived from actuarial assessment of frequency and severity distributions, with inputs including commercial fleet expansion rates in Osaka-Nagoya corridors and smartphone-native purchasing penetration among millennial SME owners.
Revisions become necessary when METI regulatory amendments alter digital contract validity standards, when reinsurance capacity constraints intensify for coastal natural peril exposure, or when embedded insurance partnerships materially displace traditional agency relationships. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
Single Trip Travel Insurance Market
Insurance
Europe Parametric Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
Norway Property and Casualty Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
United States Dental Insurance Market
Insurance
France Car Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
China Liability Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Africa Microinsurance Market
Insurance
Europe Extended Warranty Market
Insurance
China Parametric Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Auto Compulsory Insurance Market