
 South Korea Liability Insurance Market | 2026-2036
South Korea Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Liability Insurance Market Insights
Usage-based premium modules is realigning how liability coverage gets packaged and renewed in South Korea. Samsung Fire & Marine Insurance Co., Ltd. dominates the traditional corporate liability segment with extensive branch infrastructure. Hyundai Marine & Fire Insurance Co., Ltd. leverages its automotive parent relationships to anchor manufacturing liability portfolios. Meritz Fire & Marine Insurance Co., Ltd. specializes in professional liability for financial services clients, competing on underwriting precision.
Liability insurance constitutes a risk-transfer mechanism whereby insurers assume legal and financial obligations arising from third-party bodily injury, property damage, or professional negligence, with policies structured around per-occurrence limits, aggregate caps, and retroactive date provisions. Its primary commercial purpose is to shield corporate balance sheets from litigation-driven volatility. Professional liability coverage for financial and legal services firms commands premium pricing due to specialized underwriting complexity, while cyber liability represents the fastest-expanding policy type as digital asset exposures multiply across Korean enterprises. General liability maintains volume leadership among manufacturing clients, though margin pools are thinning in commoditized local coverage tiers.
The Financial Services Commission enforces risk-based capital standards that compel insurers to hold reserves calibrated to liability tail risks, while MFDS pharmaceutical safety regulations generate product liability demand across life sciences supply chains. The Personal Information Protection Act, enforced by the Personal Information Protection Commission, directly expands cyber liability coverage requirements for data handlers. Stakeholders must monitor how Korea's forthcoming climate disclosure mandates will reshape directors and officers liability exposures for listed conglomerates.
Market Dynamics
The Financial Services Commission's risk-based capital framework is compressing insurer capital efficiency and forcing portfolio rebalancing toward lower-severity liability lines. Korean carriers now face binding constraints on how they deploy capacity across long-tail commercial exposures.
Growth Catalysts
- MFDS pharmaceutical safety mandates:Life sciences manufacturers must secure product liability coverage for clinical trial participants and post-market surveillance claims, expanding policy volumes across Seoul's biotech corridor.
- Cyber asset proliferation:Korean enterprises are digitizing core operations, generating first-party cyber liability demand that outpaces traditional general liability growth rates in the Incheon Free Economic Zone.
- Climate disclosure preparation:Listed conglomerates in Busan and Gwangju are purchasing directors and officers liability extensions to cover securities litigation risks from impending carbon reporting obligations.
Market Restraints
- Reinsurance capacity tightness:Korean primary carriers depend on Lloyd's and Bermudian markets for catastrophe excess layers, with renewal costs rising for umbrella and excess liability towers.
- Actuarial data scarcity:Emerging cyber and climate liability lines lack Korean claims history, forcing conservative pricing that limits market penetration among mid-market enterprises.
- Long-tail reserve volatility:Asbestos and environmental liability from Korea's heavy industrial past continue generating adverse development, trapping capital in runoff portfolios.
Strategic Opportunities
- Jeju Island captive formation:Korean conglomerates are establishing self-insurance vehicles under the Jeju Free International City framework to retain predictable liability layers and access reinsurance directly.
- Parametric liability triggers:Insurtech platforms are piloting index-based settlement mechanisms for business interruption and supply chain liability, compressing claims resolution cycles.
- Professional liability for K-content exports:Entertainment and gaming studios in Pangyo require media liability coverage for intellectual property and defamation exposures in North American distribution markets.
Industry Challenges
- Cyber underwriting talent scarcity:Korean actuarial teams lack depth in digital asset risk modeling, forcing reliance on foreign consulting partners for cyber liability pricing.
- Legacy policy administration systems:Mid-tier carriers operate on 1990s-era platforms that cannot support usage-based premium modules or real-time exposure monitoring.
- Cross-border claims coordination:Korean manufacturers with Southeast Asian production facilities face jurisdictional complexity when product liability suits originate in multiple ASEAN legal systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Liability Insurance Market |
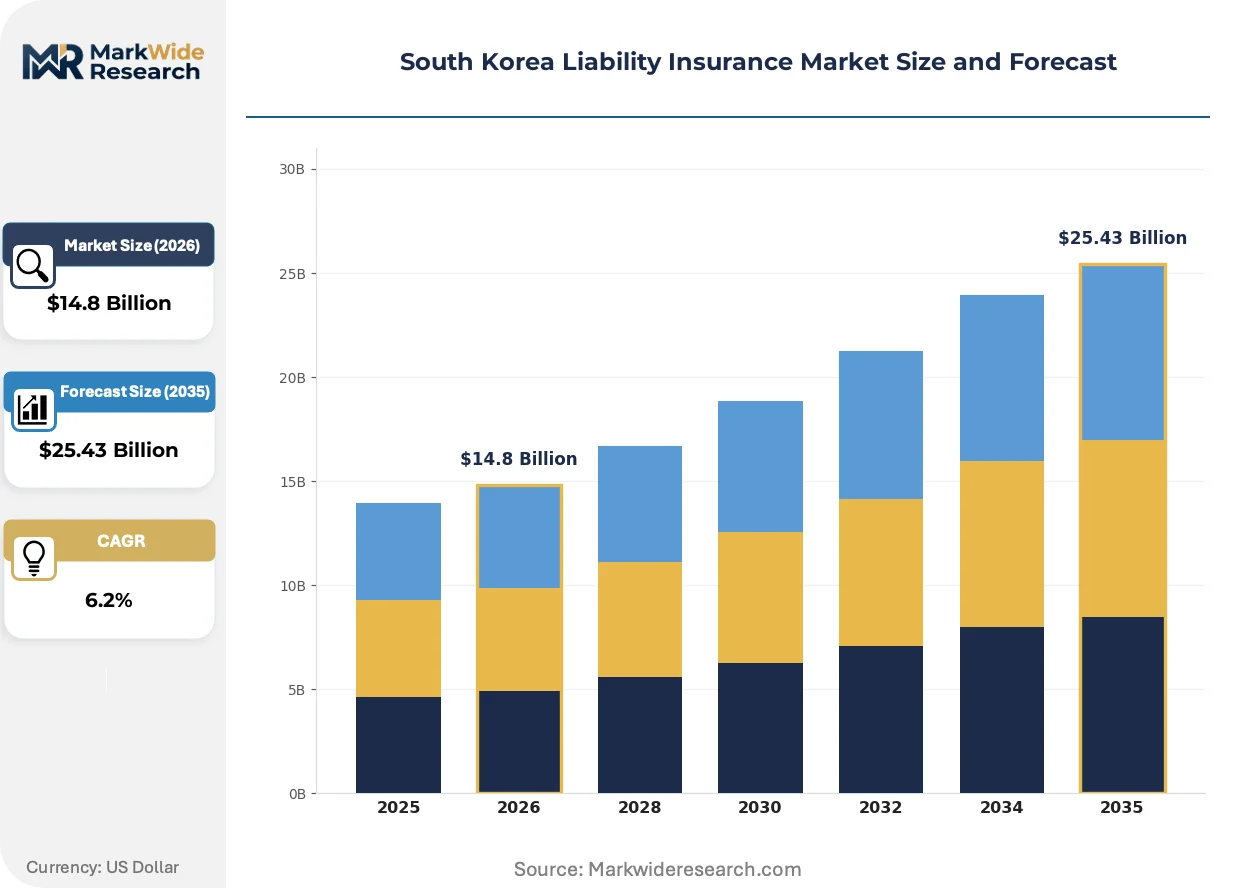
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: General Liability, Professional Liability, Product Liability, Cyber Liability Customer Type: Corporations, SMEs, Startups, Non-Profits Distribution Channel: Direct Sales, Agents, Brokers, Online Platforms Coverage Scope: Local Coverage, Regional Coverage, National Coverage, International Coverage |
| Companies Covered | KB Insurance Co., Ltd., Korean Reinsurance Company, Samsung Fire & Marine Insurance Co., Ltd., Mirae Asset Financial Group, Allianz Commercial, Hyundai Marine & Fire Insurance Co., Ltd., Meritz Fire & Marine Insurance Co., Ltd., Carrot General Insurance Corp., DB Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Liability Insurance Market Trends and Innovations
Telematics and sensor-based exposure monitoring are reconfiguring how Korean underwriters assess and price liability risk in real time. The transition from static annual policies to dynamic coverage modules is accelerating across commercial lines.
Artificial intelligence-driven claims triage is consolidating operational efficiency at Korean insurers, with natural language processing extracting liability allegations from legal filings and medical records automatically. Samsung Fire and Hyundai Marine have deployed machine learning models across their corporate liability books, reducing manual review hours by half for straightforward bodily injury claims. The technology is consolidating claims handling into centralized hubs, eliminating regional branch adjudication roles.
The Personal Information Protection Act, enforced by the Personal Information Protection Commission, mandates data breach notification within seventy-two hours and imposes statutory damages for privacy violations. Korean enterprises in financial services and healthcare are purchasing standalone cyber liability policies with regulatory defense sublimits to cover PIPC investigation costs. The regulation is driving premium growth fastest among mid-sized fintechs in Seoul's Gangnam district that previously relied on packaged coverage.
Mid-market manufacturers are unbundling their insurance procurement from traditional broker relationships and accessing liability coverage through digital placement platforms. These buyers now compare quoted layers from multiple Korean carriers simultaneously, compressing renewal cycles from ninety days to under thirty. The shift is most visible among automotive parts suppliers in Ulsan and Daegu, where procurement teams prioritize price transparency over longstanding agency ties.
South Korea Liability Insurance Market Segmentation
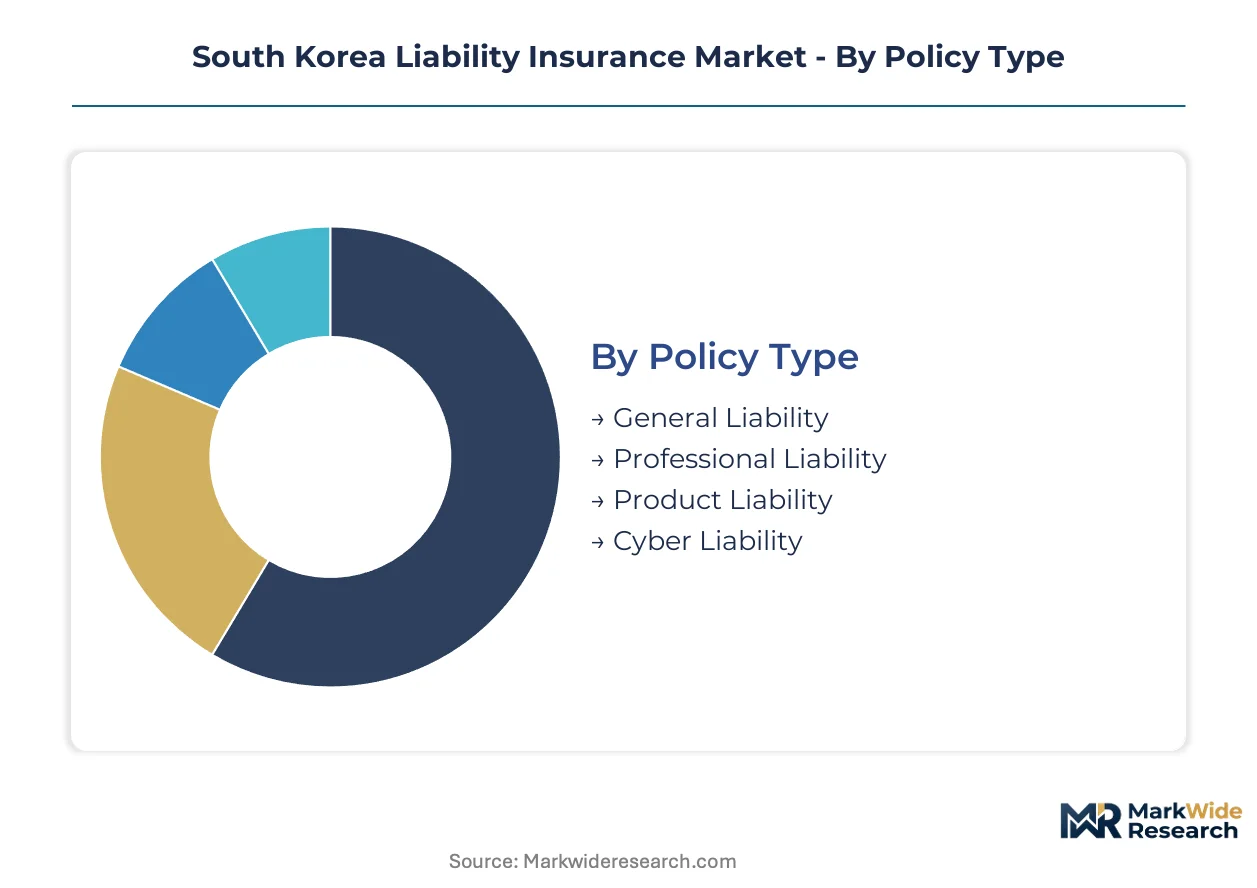
Liability coverage in South Korea fragments across policy structures, buyer sophistication, and distribution economics. Insurers calibrate capital deployment and pricing precision by segment, with divergent margin profiles between commoditized local lines and specialized international towers.
Policy Type:
General Liability commands the largest premium volume, while Cyber Liability generates the steepest expansion trajectory.
- General Liability:Covers third-party bodily injury and property damage from business operations. Manufacturing conglomerates in Ulsan and Gwangju anchor demand, though rate competition in standard local tiers compresses carrier margins.
- Professional Liability:Protects against negligence claims in advisory services. Financial services firms in Seoul's Yeouido district drive premium concentration, with law and accounting partnerships requiring E&O towers calibrated to securities litigation exposures.
- Product Liability:Korean automotive and electronics exporters purchase coverage for design defect and failure-to-warn claims originating in North American and European jurisdictions.
- Cyber Liability:Mid-sized fintechs in Gangnam and healthcare data processors under MFDS oversight are expanding coverage for regulatory defense costs and breach notification obligations.
Mature deployment sits with General Liability. Newer deployment is concentrated in Cyber Liability.
Customer Type:
Corporate buyers absorb the majority of capacity, while Startup procurement patterns are reshaping distribution economics.
- Corporations:Chaebol affiliates and listed manufacturers purchase layered towers with umbrella and excess structures. Their risk management departments negotiate manuscript endorsements and captive participation in Jeju-structured vehicles.
- SMEs:Mid-market enterprises in Daegu and Daejeon access packaged coverage through agency networks, with premium sensitivity driving consolidation toward standard policy forms.
- Startups:Venture-backed technology firms in Pangyo and Seongnam are purchasing D&O and cyber coverage through digital placement platforms, bypassing traditional broker relationships.
- Non-Profits:Social service organizations and educational institutions carry limited professional liability exposure, with demand concentrated in Seoul's metropolitan welfare sector.
Established risk transfer dominates among Corporations. Emerging buyer behavior is most visible among Startups.
Distribution Channel:
Agent networks retain volume leadership in regional markets, while Online Platforms are gaining share fastest in standard commercial lines.
- Direct Sales:Samsung Fire & Marine and Hyundai Marine deploy captive agency forces for large corporate accounts, with relationship managers embedding in client risk committees.
- Agents:Local producers in Busan and Incheon handle SME placement, earning contingent commissions on renewal retention.
- Brokers:International brokers structure multi-national programs for Korean exporters with ASEAN and North American production footprints.
- Online Platforms:Digital placement engines are compressing quote cycles for standard general liability, with automotive parts suppliers in Ulsan comparing multiple carrier layers simultaneously.
Traditional intermediation persists through Direct Sales. Channel disruption is advancing most rapidly through Online Platforms.
Coverage Scope:
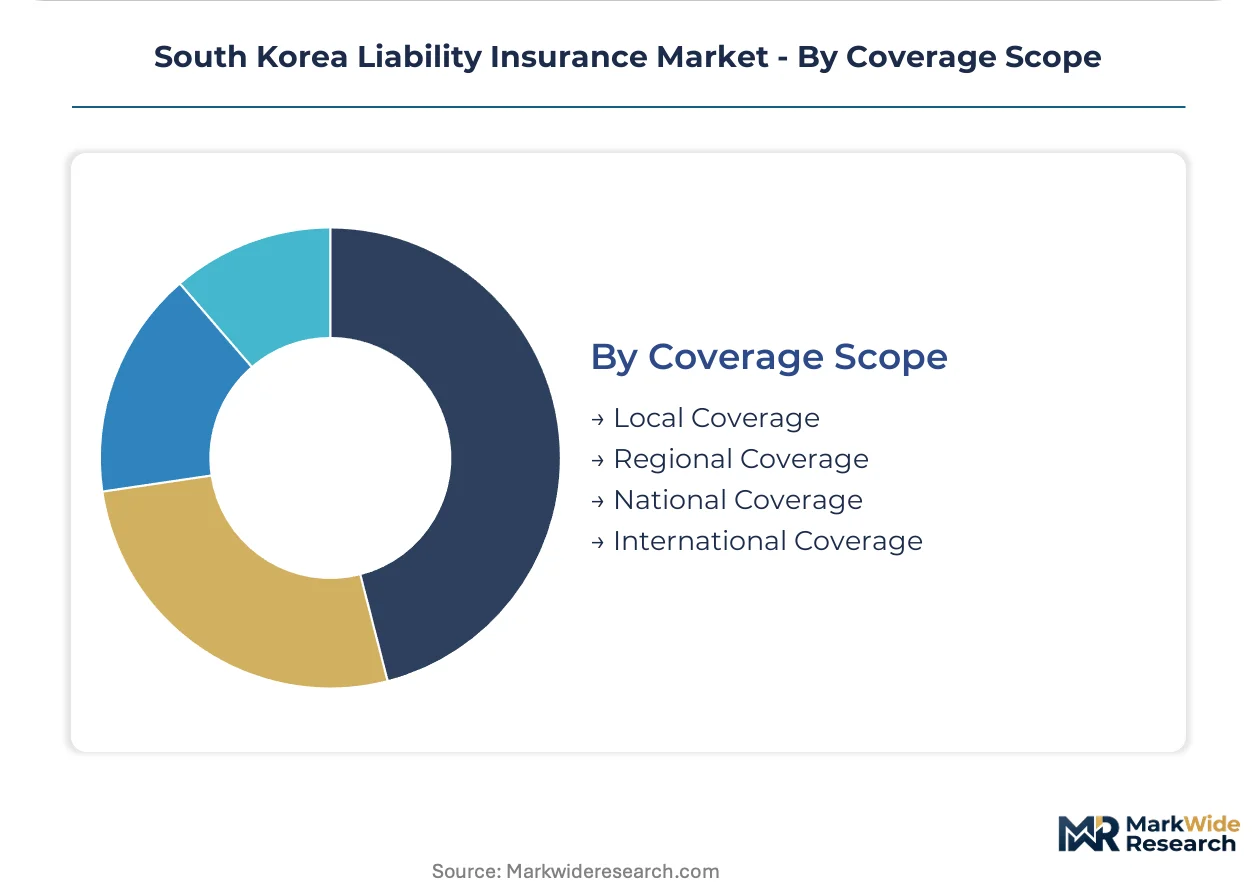
Local Coverage generates policy count leadership, though International Coverage commands the highest premium per unit.
- Local Coverage:Domestic-only policies serve Korean-domiciled enterprises with no cross-border exposure, with regulatory defense sublimits aligned to Financial Services Commission requirements.
- Regional Coverage:Manufacturers with Southeast Asian production facilities purchase ASEAN-wide programs to coordinate product liability defense across multiple legal systems.
- National Coverage:Extended territorial clauses cover Korean enterprises with sporadic export activity, excluding North America and EU jurisdictions with higher litigation severity.
- International Coverage:Global towers with London market reinsurance support Korean exporters facing class action exposure in US federal courts and EU product liability directives.
Standard protection concentrates in Local Coverage. Complexity and pricing escalation cluster in International Coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area generates the highest liability premium density, while Busan-Ulsan and Daegu-Gyeongbuk concentrate industrial manufacturing exposures. Regional disparities in regulatory enforcement intensity and corporate risk sophistication shape carrier deployment strategies.
Seoul Capital Area
Financial services conglomerates in Yeouido and Gangnam drive professional liability demand for directors and officers coverage. The Personal Information Protection Commission enforces strict data breach notification rules, expanding cyber liability procurement among fintechs. Risk management departments of listed chaebols negotiate manuscript endorsements and captive structures through Jeju-registered vehicles.
Busan-Ulsan
Shipbuilding and automotive manufacturing clusters generate product liability exposure for export-oriented exporters. MFDS pharmaceutical safety mandates compel life sciences manufacturers to secure clinical trial coverage. Hyundai Heavy Industries affiliates anchor general liability purchasing in layered tower structures with London market reinsurance support.
Daegu-Gyeongbuk
Textile and electronics component suppliers face supply chain disruption liability from ASEAN production footprints. The Financial Services Commission's risk-based capital framework constrains local carrier capacity for long-tail exposures. Mid-market manufacturers in Gumi Industrial Complex access coverage through digital placement platforms rather than traditional agency networks.
Daejeon-Sejong
Government research institutes and public sector entities carry limited professional liability exposure compared to commercial counterparts. Science-based startups in Daedeok Innopolis purchase technology errors and omissions coverage for grant-funded projects. Regulatory defense sublimits align to national procurement standards rather than international litigation severity.
Gwangju-Honam
Agricultural processing and regional banking generate modest general liability volumes relative to national averages. Climate disclosure preparation is driving preliminary directors and officers liability interest among listed conglomerates with Honam operations. Local agency networks retain dominance in SME placement despite gradual digital channel penetration.
South Korea Liability Insurance Market Competitive Landscape
Top-tier vendors anchor the national corporate segment, while mid-tier specialists compete on underwriting precision in niche lines. The market exhibits tiered concentration around fire and marine incumbents with extensive branch infrastructure. Strategic archetypes include integrated financial conglomerates, automotive-affiliated carriers, and digital-native insurtech entrants. Competitive moves center on captive formation advisory services and parametric product development.
Among established fire and marine carriers, Samsung Fire & Marine Insurance Co., Ltd. and Hyundai Marine & Fire Insurance Co., Ltd. exemplify the integrated conglomerate archetype with captive agency forces embedding in client risk committees. Meritz Fire & Marine Insurance Co., Ltd. occupies a position within the specialist tier, representing underwriting precision approaches for financial services professional liability. Korean Reinsurance Company anchors the domestic reinsurance layer, enabling primary carriers to access international catastrophe excess capacity.
| Leading Market Players |
|---|
| KB Insurance Co., Ltd. |
| Korean Reinsurance Company |
| Samsung Fire & Marine Insurance Co., Ltd. |
| Mirae Asset Financial Group |
| Allianz Commercial |
| Hyundai Marine & Fire Insurance Co., Ltd. |
| Meritz Fire & Marine Insurance Co., Ltd. |
| Carrot General Insurance Corp. |
| DB Insurance |
| Others |
Pricing and Supply Chain Analysis
Actuarial talent concentration in Seoul's Gangnam and Yeouido districts widens pricing-tier spreads between sophisticated international programs and commoditized local coverage, as labor-cost differentials between certified pricing specialists and standard underwriters feed directly into premium stratification across corporate liability lines.
Pricing Analysis
Margin tightening in standard general liability reflects rate competition among mid-tier carriers deploying legacy policy administration systems. Three-tier pricing structure across premium, standard, and economy levels separates multinational tower placements from domestic packaged coverage and bare-minimum statutory limits. Price differentiation hinges on reinsurance backing quality and claims handling automation depth. SME buyers in Daegu and Gwangju exhibit acute price sensitivity, while chaebol risk managers prioritize manuscript endorsement flexibility over premium minimization.
Supply Chain Analysis
Reverse-logistics capacity for runoff portfolio management concentrates in Seoul and Singapore, where specialized reinsurance brokers handle asbestos and environmental liability reserve transfers. Primary carrier capacity draws from Korean Reinsurance Company domestic support and Lloyd's of London excess layers. Raw material dependencies span actuarial software licenses, claims data analytics platforms, and regulatory filing systems. Single-source vulnerability sits with legacy policy administration vendors whose 1990s-era architectures cannot support real-time exposure monitoring. Distribution runs through captive agency forces for large accounts and digital placement platforms for mid-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea liability insurance market sits in a technology-transition phase, with AI-driven claims triage and parametric settlement mechanisms displacing manual underwriting and branch-based adjudication workflows.
For Market Incumbents: To counter insurtech platform disruption in mid-market placement, Samsung Fire & Marine and Hyundai Marine should accelerate captive advisory services for Jeju-structured vehicles while retrofitting legacy policy systems to support usage-based premium modules. Channel control through embedded risk managers in client committees remains the critical defensive lever against digital-native competitors. For New Entrants and Emerging Players: Enter via cyber liability specialization for Gangnam fintechs and Pangyo gaming studios, where incumbent actuarial teams lack digital asset risk modeling depth. White-space concentration sits with parametric business interruption products for supply chain disruption exposures. A direct-to-enterprise digital placement angle, bypassing traditional broker relationships, offers the fastest penetration path. For Investors and Strategic Acquirers: Re-rating potential sits with cyber underwriting specialists given PIPC enforcement intensity and breach notification mandate expansion. Long-term viability favors platforms with proprietary sensor-based exposure monitoring capabilities. The signal to watch is regulatory approval velocity for index-based settlement mechanisms as inflection indicator for parametric product scalability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Claims Triage Deployment | Samsung Fire and Hyundai Marine have reduced manual review hours by half through natural language processing extraction from legal filings. |
| Jeju Captive Formation Advisory | Chaebol risk committees increasingly retain predictable liability layers through self-insurance vehicles under the Free International City framework. |
| Cyber Liability Product Expansion | Mid-sized fintechs in Gangnam purchase standalone policies with regulatory defense sublimits covering PIPC investigation costs. |
| Parametric Settlement Mechanism Pilot | Insurtech platforms compress claims resolution cycles through index-based triggers for business interruption and supply chain liability. |
| Legacy System Modernization | Mid-tier carriers must replace 1990s-era platforms to support real-time exposure monitoring and usage-based premium modules. |
Research Methodology
Independent corroboration across primary interviews with underwriting directors, claims operations heads, and risk management consultants, combined with secondary validation through Financial Services Commission regulatory filings, Korean Reinsurance Company market reports, and Lloyd's market renewal data, underwrites the qualitative findings. Bottom-up triangulation from individual carrier portfolio disclosures and top-down reconciliation against national premium aggregates anchor the analysis.
Comparable-period anchoring to historical risk-based capital framework implementation phases shapes the projection methodology across the analysis window. Segmentation dimensions modeled include policy type, customer sophistication tier, distribution channel, and coverage territorial scope. CAGRs derive from premium volume trajectory analysis calibrated to regulatory capital constraint evolution and reinsurance capacity cycle positioning. Forecast inputs incorporate MFDS pharmaceutical safety mandate expansion timelines and PIPC enforcement intensity indices.
Revisions become necessary when Financial Services Commission solvency requirement adjustments, Lloyd's market catastrophe excess layer pricing shocks, or climate disclosure mandate implementation delays materialize. Practitioners should monitor regulatory filing velocity for captive formation approvals and cyber liability policy count growth rates for early signals of segment inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
China Online Insurance Market
Insurance
Small Business Insurance Market
Insurance
Dental Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
Cargo Insurance Market
Insurance
Agriculture Reinsurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Indonesia Private Health Insurance Market
Insurance
Boiler Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Disability Insurance Market
Insurance
Gap Insurance Market
Insurance
Europe Mobile Phone Insurance Market