
 Inhibited Propylene Glycol Market | 2026-2036
Inhibited Propylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Inhibited Propylene Glycol Market Analytics
Ethylene glycol is rebalancing toward inhibited propylene glycol across closed-loop HVAC and food-processing cooling circuits as facilities prioritize lower acute toxicity and simplified disposal pathways. Dow Chemical Company leverages captive epichlorohydrin and propylene oxide supply chains to control input costs for US-based inhibited glycol production. Dynalene sustains a specialized position in custom-formulated heat transfer fluids for laboratory and semiconductor cooling, where inhibitor compatibility with exotic metallurgy commands premium positioning. Houghton Chemical anchors New England distribution through regional blending capacity and technical service density for institutional accounts.
Inhibited propylene glycol denotes propylene glycol base fluid dosed with corrosion inhibitor packages—typically combining borates, nitrites, triazoles, and organic acids at 500–5,000 ppm total active content—to protect ferrous and non-ferrous metals in recirculating systems. The formulation prevents galvanic corrosion, cavitation erosion, and scale deposition in equipment ranging from commercial boilers to food-grade ice slurry generators. Industrial Grade product dominates volume flows into antifreeze and chemical intermediate applications, while Pharmaceutical Grade commands margin concentration through USP and EP compliance burdens that limit qualified suppliers. Food Additive application is expanding fastest as clean-label processor demand drives substitution of glycerin and sorbitol in select moisture-retention roles, though regulatory purity thresholds constrain entrants.
EPA SNAP reviews, FDA food-contact substance notifications, and REACH Annex XIV authorization requirements collectively shape formulation chemistry and market access corridors for inhibited glycol suppliers. The EPA's evolving stance on certain azole-based inhibitors under SNAP is forcing reformulation cycles, while FDA compliance for indirect food additive use demands migration testing documentation that smaller blenders struggle to assemble. Stakeholders must monitor emerging state-level restrictions on boron-containing discharge streams and position inhibitor portfolios for multi-jurisdictional registration resilience.
Market Dynamics
Reformulation cycles driven by EPA SNAP reviews on azole-based inhibitors are forcing glycol suppliers to redesign corrosion protection packages while maintaining performance in closed-loop HVAC and food-processing systems.
Growth Catalysts
- Chilled-water infrastructure retrofits:Aging commercial buildings across the United States are replacing ethylene glycol with inhibited propylene glycol to meet lower toxicity disposal requirements and simplify regulatory compliance.
- REACH Annex XIV authorization:European formulators are accelerating migration to alternative inhibitor chemistries ahead of sunset dates for legacy substances, expanding the qualified supplier base for USP-grade fluids.
- Data center cooling projects:Hyperscale facility operators are specifying pre-inhibited propylene glycol solutions for secondary loop cooling to protect copper-nickel heat exchangers from galvanic corrosion.
Market Restraints
- Propylene oxide feedstock volatility:Inhibited glycol production costs track propylene oxide spot markets, with US Gulf Coast supply disruptions compressing blender margins during peak HVAC installation seasons.
- Qualified supplier concentration:Pharmaceutical Grade USP/EP certification burdens limit production to a handful of North American and European facilities, creating single-source risk for food-contact applications.
- Glycerin substitution in food additives:Clean-label processors are reverting to glycerin for moisture-retention roles where propylene glycol faces consumer perception headwinds despite functional superiority.
Strategic Opportunities
- Semiconductor fabrication cooling:Custom-formulated inhibited glycols compatible with exotic metallurgy in EUV lithography systems command premium positioning as fabs expand in Arizona and Texas.
- State-level boron discharge restrictions:Emerging limits on borate-containing effluents in California and Great Lakes states are creating first-mover advantage for nitrite-triazole alternative packages.
- Direct-to-contractor digital channels:HVAC service firms are bypassing traditional distribution through technical e-commerce platforms that bundle inhibitor compatibility testing with fluid procurement.
Industry Challenges
- Multi-jurisdictional registration assembly:Smaller blenders struggle to compile FDA food-contact migration studies, EPA SNAP submissions, and REACH dossiers simultaneously, ceding share to integrated chemical majors.
- Inhibitor-metallurgy compatibility testing:Each new HVAC or industrial system design requires validated corrosion protection protocols, extending qualification timelines and freezing formulation decisions until late project stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inhibited Propylene Glycol Market |
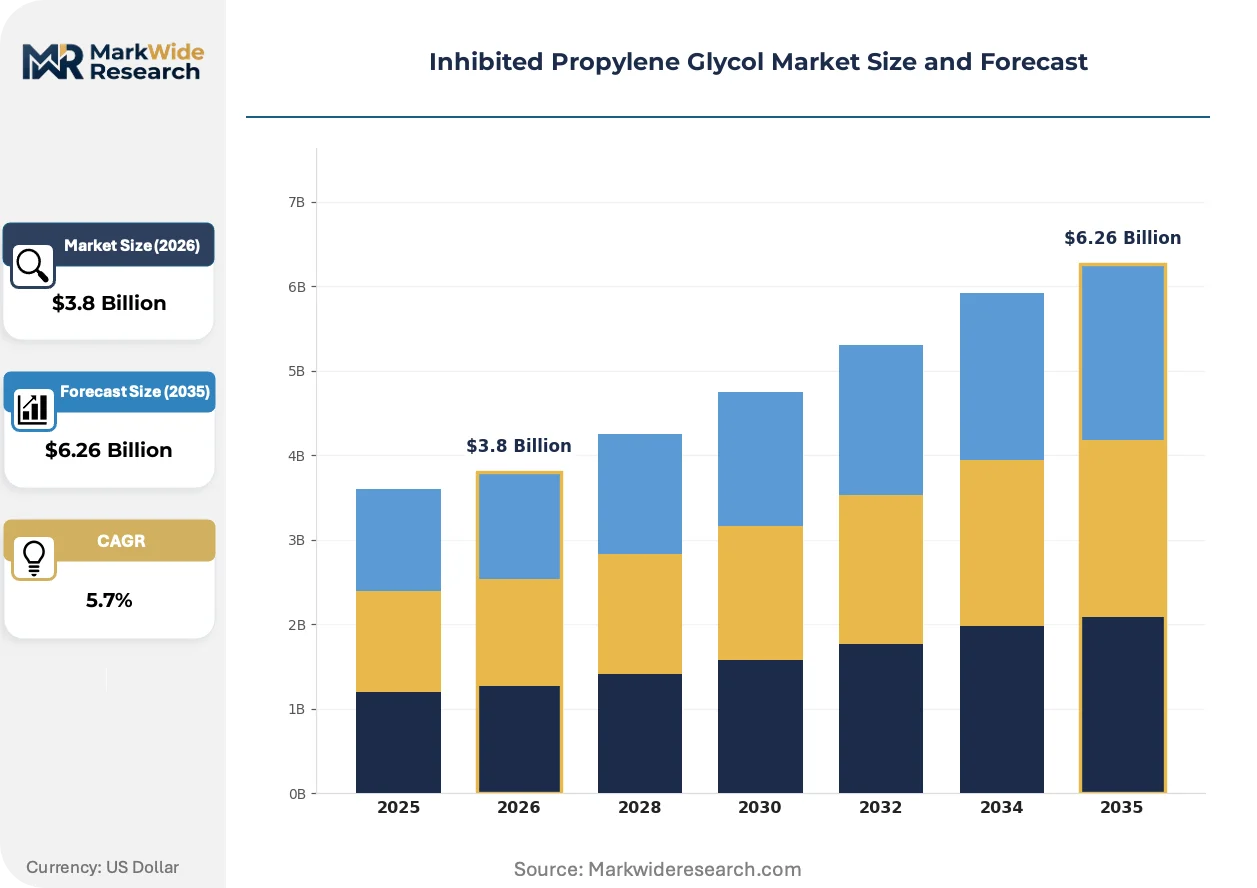
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Technical Grade Application: Antifreeze, Food Additive, Pharmaceutical Solvent, Chemical Intermediate End User: Manufacturing, Food Processing, Pharmaceuticals, Automotive Packaging Type: Drums, IBC Totes, Bulk Containers, Bottles |
| Companies Covered | Dow Chemical Company, Dynalene, Houghton Chemical, Guardian Chemical, ChemWorld, Solvents and Petroleum Service, Chemtex Specialty Ltd., Rhomar Water, Nu-Calgon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inhibited Propylene Glycol Market Evolving Landscape
Formulation chemistry is pivoting toward bio-based inhibitor packages and automated blending systems that compress batch-to-batch variability while meeting tightening purity thresholds for food-contact and pharmaceutical applications.
Smart dosing systems integrated with building management platforms are automating inhibitor level monitoring in large commercial HVAC loops. Facility operators in Class A office buildings are deploying these sensors to trigger replenishment before corrosion thresholds breach. The technology is automating service contract structures and compressing the role of traditional fluid analysis laboratories.
EPA SNAP reviews of certain triazole compounds are accelerating reformulation timelines for heat transfer fluid suppliers serving the US market. The agency's evolving stance is pushing formulators toward nitrite-organic acid hybrid packages that maintain ferrous protection without flagged substances. Food-grade applications face the steepest compliance documentation burdens as FDA indirect additive notifications require extensive migration testing.
Consolidated procurement by national HVAC service chains is displacing fragmented regional distributor relationships across the United States. Large mechanical contractors are negotiating direct supply agreements with inhibited glycol blenders that bundle technical service, inventory management, and disposal logistics. This concentration is most visible in Sun Belt metropolitan markets where new construction and retrofit activity overlap.
Inhibited Propylene Glycol Market Segmentation
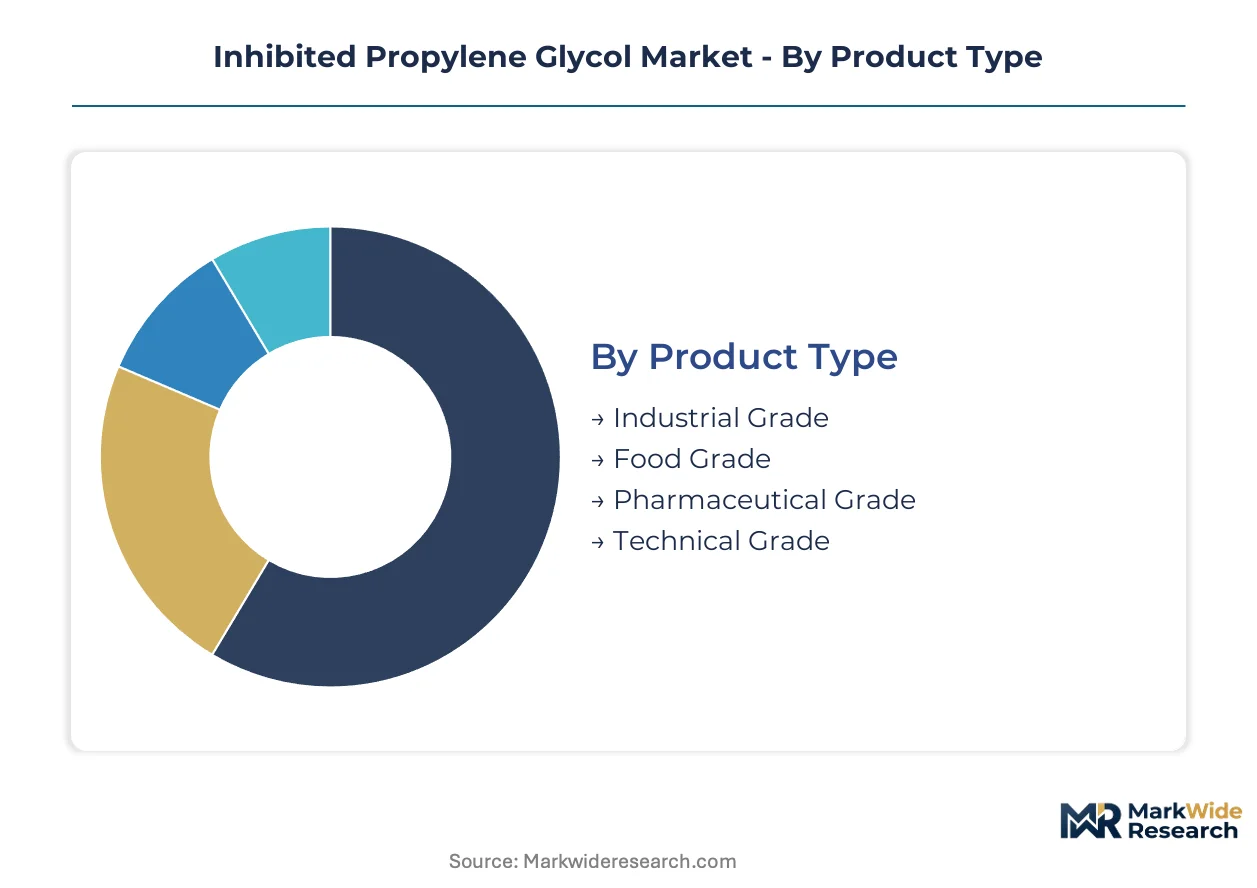
Product purity tiers and application-specific compliance burdens fragment the inhibited propylene glycol landscape into sharply differentiated margin pools. Capital deployment and regulatory qualification requirements vary dramatically across these boundaries, determining which suppliers can compete in each segment.
Product Type:
Pharmaceutical Grade demands the steepest capital commitment, requiring dedicated USP/EP-certified production lines and extensive validation documentation.
- Industrial Grade:Formulations carry corrosion inhibitor packages at 500–5,000 ppm active content for closed-loop HVAC and antifreeze applications. Demand concentrates in United States commercial building retrofits where ethylene glycol displacement is accelerating for simplified disposal compliance.
- Pharmaceutical Grade:USP and EP compliance mandates dedicated manufacturing suites, extensive cleaning validation, and batch release testing that limits qualified suppliers to a handful of North American and European facilities. FDA migration study documentation creates multi-year qualification barriers for new entrants.
- Food Grade:FDA indirect food additive notifications and FSSAI compliance in India govern moisture-retention applications in processed foods.
- Technical Grade:Lower purity specifications serve chemical intermediate and de-icing formulations where inhibitor precision is less critical.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Pharmaceutical Grade.
Application:
Volume concentration and margin structure diverge sharply between commodity heat transfer fluids and regulated food-contact or pharmaceutical uses.
- Antifreeze:Closed-loop HVAC systems and automotive coolant circuits represent the volume anchor, with pre-inhibited formulations displacing field-blended alternatives in United States commercial installations. Data center cooling projects in Arizona and Texas are specifying these fluids for copper-nickel heat exchanger protection.
- Food Additive:Clean-label processor demand is expanding moisture-retention applications despite glycerin substitution headwinds in consumer-facing products. FDA migration testing and state-level discharge restrictions on boron-containing effluents are reshaping inhibitor package selection.
- Pharmaceutical Solvent:USP-grade fluids serve as excipients and processing aids with stringent endotoxin and heavy metal specifications.
- Chemical Intermediate:Feedstock applications in unsaturated polyester resins and plasticizers tolerate broader purity ranges.
Antifreeze commands the largest volume position. Food Additive is climbing the fastest.
End User:
Customer technical sophistication and procurement scale determine service intensity and pricing power for blenders.
- Manufacturing:Broad industrial cooling and process heating applications span metalworking, plastics, and electronics fabrication. Semiconductor fabs in the United States are demanding custom inhibitor compatibility with exotic metallurgy in EUV lithography systems, commanding premium positioning.
- Food Processing:Clean-label meat, dairy, and bakery operations require food-grade fluids with full FDA food-contact substance notification documentation.
- Pharmaceuticals:Contract manufacturing organizations and innovator drug companies enforce stringent supplier qualification protocols.
- Automotive:OEM coolant specifications and aftermarket service chains drive volume with lower service intensity than industrial accounts.
Manufacturing absorbs the greatest fluid volume. Food Processing shows the steepest demand trajectory.
Packaging Type:
Logistics economics and customer scale determine packaging selection, with bulk infrastructure requiring dedicated capital.
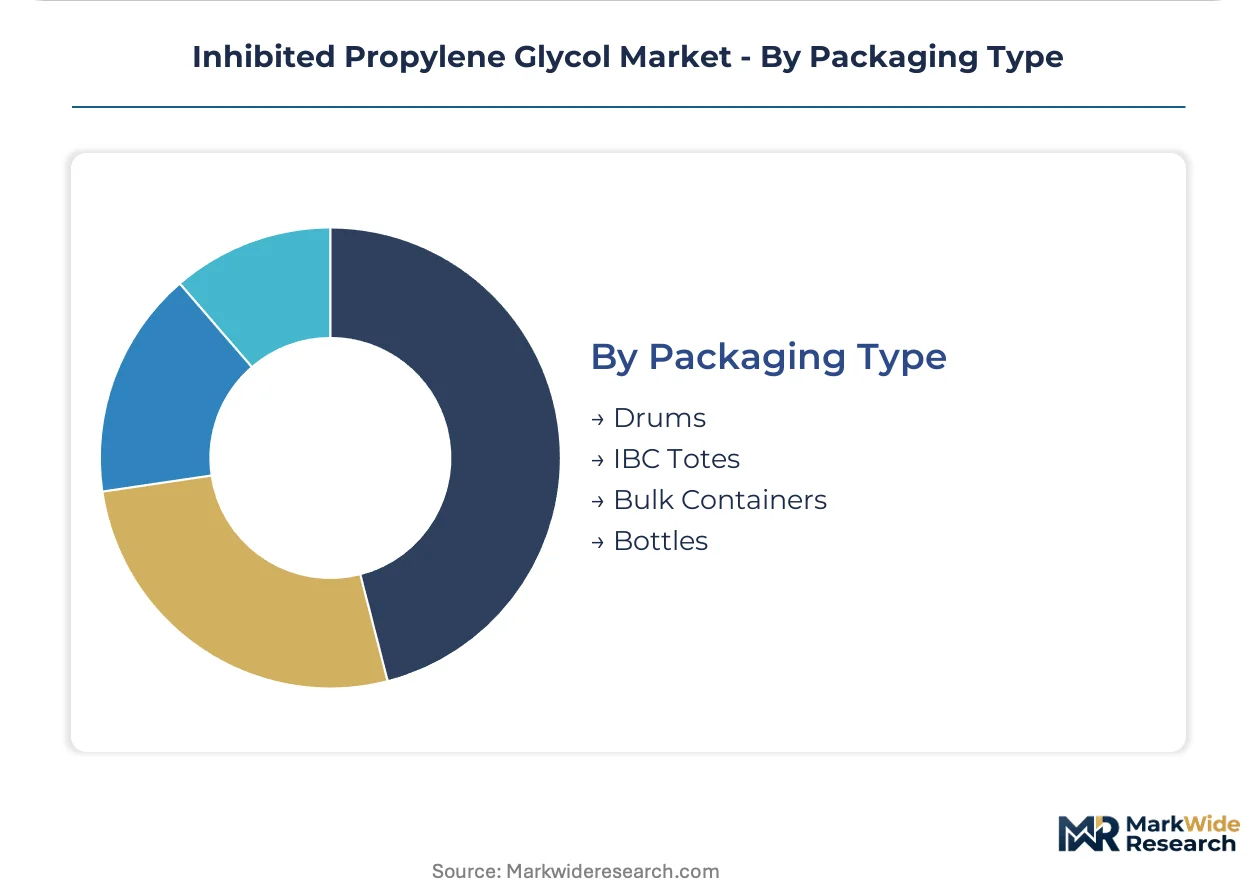
- Bulk Containers:Tank truck and railcar deliveries serve national HVAC service chains and large industrial accounts with direct-to-site logistics. These arrangements bundle inventory management and disposal services, compressing regional distributor roles.
- Drums:55-gallon steel and poly drums remain the workhorse for mid-scale industrial maintenance departments and smaller mechanical contractors.
- IBC Totes:Intermediate bulk containers bridge drum and bulk economics for facilities without tankage infrastructure.
- Bottles:Quart and gallon containers serve laboratory, residential, and small repair applications with highest per-unit packaging cost.
Bulk Containers dominate procurement value. Bottles are gaining share fastest in direct-to-contractor digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States chilled-water infrastructure retrofits and data center cooling projects anchor demand for corrosion-protected heat transfer fluids. Regional procurement patterns concentrate in Sun Belt metropolitan markets and Great Lakes manufacturing corridors.
United States
Commercial building HVAC retrofits and hyperscale data center construction in Arizona and Texas drive procurement of pre-inhibited propylene glycol solutions. EPA SNAP reviews on azole-based inhibitors force reformulation cycles among domestic blenders. The Great Lakes industrial corridor sustains demand for food-grade fluids in meat and dairy processing operations.
Germany
REACH Annex XIV authorization deadlines accelerate migration to alternative inhibitor chemistries among European formulators. ECHA regulatory pressure on legacy substances expands the qualified supplier base for USP-grade fluids. The Rhine-Ruhr industrial cluster hosts specialized blending capacity serving pharmaceutical and automotive coolant specifications.
China
Dual carbon goals and expanding semiconductor fabrication capacity in Yangtze River Delta cities stimulate demand for exotic metallurgy-compatible heat transfer fluids. MEE discharge standards on boron-containing effluents reshape inhibitor package selection. Shanghai-based chemical majors invest in dedicated USP-certified production lines for export markets.
India
FSSAI compliance requirements for indirect food additives govern moisture-retention applications in processed foods. Clean-label processor demand expands despite glycerin substitution headwinds in consumer-facing products. The Gujarat chemical corridor concentrates blending capacity serving domestic pharmaceutical and food processing industries.
Japan
METI energy efficiency standards for commercial buildings accelerate ethylene glycol displacement in closed-loop HVAC systems. Semiconductor fabs in Kyushu demand custom inhibitor compatibility with EUV lithography metallurgy. Osaka-based chemical distributors maintain technical service density for precision manufacturing accounts.
Inhibited Propylene Glycol Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and regulatory qualification capabilities. The vendor base stratifies between integrated chemical majors with captive feedstock supply and specialized blenders focused on custom inhibitor packages. Three archetypes dominate: upstream-integrated producers controlling propylene oxide inputs, regional technical service specialists, and pharmaceutical-grade purity specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines extend.
Among North American integrated producers, Dow Chemical Company anchors the upstream-integrated tier with captive epichlorohydrin and propylene oxide supply chains. Dynalene occupies a specialized position in custom-formulated heat transfer fluids for laboratory and semiconductor cooling applications. Houghton Chemical exemplifies the regional technical service model through New England distribution density and institutional account relationships.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Dynalene |
| Houghton Chemical |
| Guardian Chemical |
| ChemWorld |
| Solvents and Petroleum Service |
| Chemtex Specialty Ltd. |
| Rhomar Water |
| Nu-Calgon |
| Others |
Value Network & Pricing Analysis
Propylene oxide spot prices on the US Gulf Coast cascade through inhibitor package costs and blending economics to stratify final fluid pricing across pharmaceutical, industrial, and technical grades. Dow Chemical's captive epichlorohydrin supply insulates its US-based production from this volatility, while regional blenders absorb margin compression during peak HVAC installation seasons.
Pricing Analysis
Input-cost pass-through from propylene oxide and specialty inhibitor chemicals determines contract and spot pricing structures across the value chain. Three-tier pricing structure across pharmaceutical, industrial, and technical grades reflects USP/EP certification burdens and batch-release testing requirements. Pricing pressure stems from glycerin substitution in food-additive applications where clean-label processors trade functional performance for consumer perception benefits. Mid-scale industrial maintenance departments exhibit highest price sensitivity, while semiconductor fabs and pharmaceutical CMOs prioritize metallurgy compatibility and regulatory documentation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from national HVAC service chains and hyperscale data center operators mandate multi-supplier qualification for corrosion inhibitor packages and base fluid supply. Production concentrates in the United States, Germany, and China, with each hub serving distinct regulatory compliance corridors. Raw material dependencies span propylene oxide from Gulf Coast crackers, borate and triazole inhibitor chemicals from domestic specialty producers, and food-grade packaging materials. Single-source vulnerability concentrates in USP-certified pharmaceutical grade capacity, where qualified facilities number fewer than ten globally. Distribution runs through direct tank-truck and railcar arrangements for bulk accounts, compressing traditional regional distributor roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
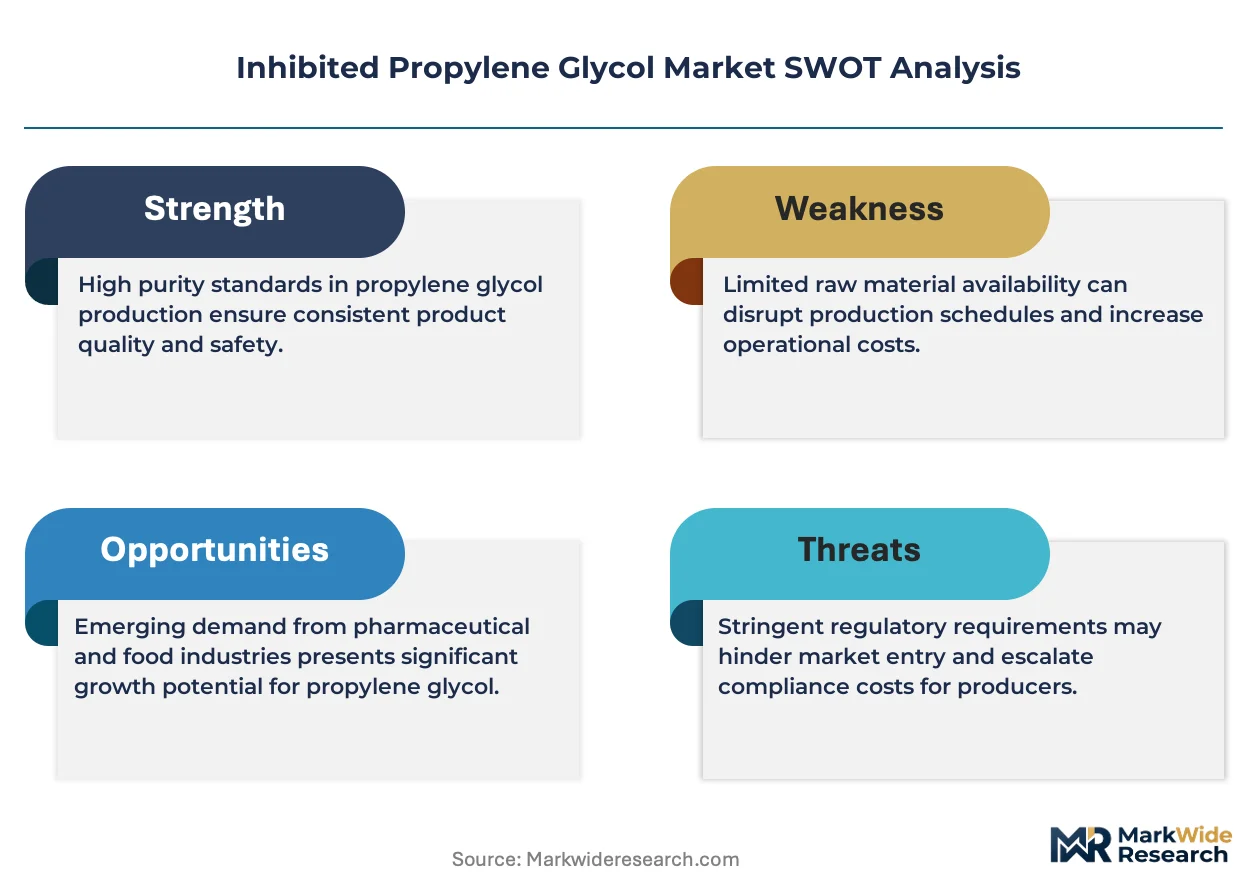
This market functions as a geographic-arbitrage play between US Gulf Coast feedstock access and European REACH compliance costs, with margin capture favoring producers with integrated propylene oxide supply and multi-jurisdictional registration capabilities.
For Market Incumbents: Deploy backward integration into captive propylene oxide supply to defend margin position against feedstock volatility and emerging Chinese capacity. Consolidate regional technical service density in Sun Belt metropolitan markets where national HVAC chains are displacing fragmented distribution. Counter glycerin substitution threats in food-additive segments by bundling FDA migration study documentation with volume commitments. For New Entrants and Emerging Players: National HVAC service chains represent the most penetrable channel partner type for pre-inhibited fluid procurement bypassing traditional distribution. Target state-level boron discharge restrictions in California and Great Lakes states as a white-space entry point for nitrite-triazole alternative packages. Pursue direct-to-contractor digital channels that bundle inhibitor compatibility testing with fluid procurement to capture service-intensive mid-scale accounts. For Investors and Strategic Acquirers: Asymmetric upside sits with pharmaceutical-grade purity specialists holding USP/EP-certified production suites and established FDA food-contact substance notifications. Long-term viability centers on qualification moats that extend multi-year barriers against commodity blending competition. Watch EPA SNAP review outcomes on azole-based inhibitors as the inflection signal for reformulation-driven supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Captive feedstock supply insulates margin from Gulf Coast spot volatility during peak HVAC seasons. |
| Multi-Jurisdictional Registration Investment | Simultaneous FDA, EPA SNAP, and REACH dossier assembly cedes share from smaller blenders to integrated majors. |
| Custom Formulation for EUV Lithography | Semiconductor fab expansion in Arizona and Texas commands premium positioning for exotic metallurgy compatibility. |
| Direct-to-Contractor Digital Platform | Technical e-commerce bundling inhibitor testing with procurement displaces traditional fluid analysis laboratories. |
| Nitrite-Triazole Alternative Package Development | First-mover positioning in California and Great Lakes boron discharge restrictions captures regulatory-driven switching demand. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market informing demand calibration and regulatory trajectory assessment. Primary interviews with plant managers at blending facilities, procurement leads at downstream HVAC service chains, technical R&D directors at inhibitor suppliers, and regulatory affairs specialists at pharmaceutical CMOs were combined with secondary validation from EPA SNAP submissions, ECHA REACH dossiers, FDA food-contact substance notifications, and customs/trade data. Bottom-up volume builds across grade tiers and applications were triangulated against top-down market sizing from integrated chemical majors.
Rate-of-change decomposition across the analysis window disaggregates volume expansion into retrofit-driven replacement demand, new construction absorption, and grade-mix shifts toward pharmaceutical and food-additive specifications. Segmentation dimensions modeled include product purity tier, end-use application, packaging format, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules. Industry-specific forecast inputs incorporate EPA SNAP review timelines, state-level boron discharge restriction adoption patterns, and hyperscale data center cooling project pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to propylene oxide feedstock volatility, REACH Annex XIV authorization scope expansion, and glycerin substitution acceleration in food-contact applications. Deviation in EPA SNAP regulatory stance on azole-based inhibitors would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Europe Citric Acid Market
Additives
Global Pour Point Depressant Market
Additives
Ammonium Acetate Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Fluoropolymer Additives Market
Additives
Paint Additives Market
Additives
Thallium Acetate Market
Additives
Metallic Stearate Market
Additives
Rosin Ester Market
Additives
North America Phosphate Esters Market
Additives
Global Lubricating Oil Additives Market
Additives
Polymeric Plasticizer Market
Additives
Antiblock Agents Market
Additives
Fluid Loss Additives Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
1,4 Butanediol Derivatives Market