
 Polymeric Plasticizer Market | 2026-2036
Polymeric Plasticizer Market Size, Share, and Industry Trends Forecast 2026-2036
Polymeric Plasticizer Market Intelligence
The European Union's REACH regulation, which restricts the use of certain ortho-phthalates, is consolidating demand toward higher-performance, lower-migration polymeric plasticizers. BASF SE leverages its extensive chemical portfolio to offer a range of plasticizer solutions for various end-use requirements. Eastman Chemical Company specializes in non-phthalate plasticizers, positioning itself to benefit from these regulatory shifts. Meanwhile, Lanxess AG competes with a focus on specialty additives for high-performance applications in demanding industrial environments.
Polymeric plasticizers are high molecular weight polyesters, distinct from monomeric types due to their larger molecular structure and lower volatility. This composition results in minimal migration, making them essential for enhancing the flexibility and permanence of polymers in sensitive applications. Within end-use industries, the automotive and construction sectors command a significant share due to the need for long-lasting material performance. Applications in flooring and coatings represent a mature segment, while use in specialized films and adhesives is expanding.
Regulatory frameworks, including the EU's REACH, the US EPA's chemical safety assessments, and China's GB standards, directly influence product formulation and market access. These regulations are pushing manufacturers away from certain traditional phthalates toward polymeric and bio-based alternatives. Stakeholder success will depend on navigating this complex regulatory environment while investing in the development of cost-effective, high-permanence plasticizer technologies.
Market Dynamics
The primary structural force shaping the polymeric plasticizer market is a global regulatory clampdown on specific ortho-phthalates, which is accelerating the substitution toward higher-permanence, lower-migration alternatives in sensitive applications.
Growth Catalysts
- Regulatory Substitution:The EU's REACH framework restricts certain phthalates, creating a direct mandate for manufacturers to adopt polymeric alternatives for market access.
- Automotive Performance Needs:Demand for durable, low-fogging interior components in the automotive sector necessitates the use of high-permanence polymeric plasticizers for long-term stability.
- Bio-Based Innovation:Development of plasticizers from renewable feedstocks aligns with corporate sustainability goals and appeals to specifiers in green building projects.
Market Restraints
- Cost Disadvantage:Higher production costs relative to commodity phthalates, rooted in complex polyester synthesis, limit adoption in price-sensitive applications.
- Alternative Plasticizers:Competition from other non-phthalate options like benzoates and citrates poses a substitution threat in less demanding applications.
- Processing Complexity:The inherent high viscosity of polymeric plasticizers can complicate processing for some PVC compounders, requiring equipment or formulation adjustments.
Strategic Opportunities
- Medical and Food Contact:Strict migration limits under FDA and EFSA regulations create opportunities for high-purity polymeric plasticizers in sensitive applications.
- Emerging Market Penetration:Expanding into India and Southeast Asia offers growth as industrial safety standards and consumer awareness in those regions increase.
- Green Building Materials:Formulating products to meet criteria for certifications like LEED provides a value proposition for use in sustainable construction projects.
Industry Challenges
- Regulatory Divergence:Manufacturers face operational friction navigating disparate chemical safety regulations from the US EPA, Europe's ECHA, and China's MEE.
- Feedstock Volatility:The supply and price of key raw materials, such as adipic acid and various diols, are subject to fluctuations in the broader petrochemical market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymeric Plasticizer Market |
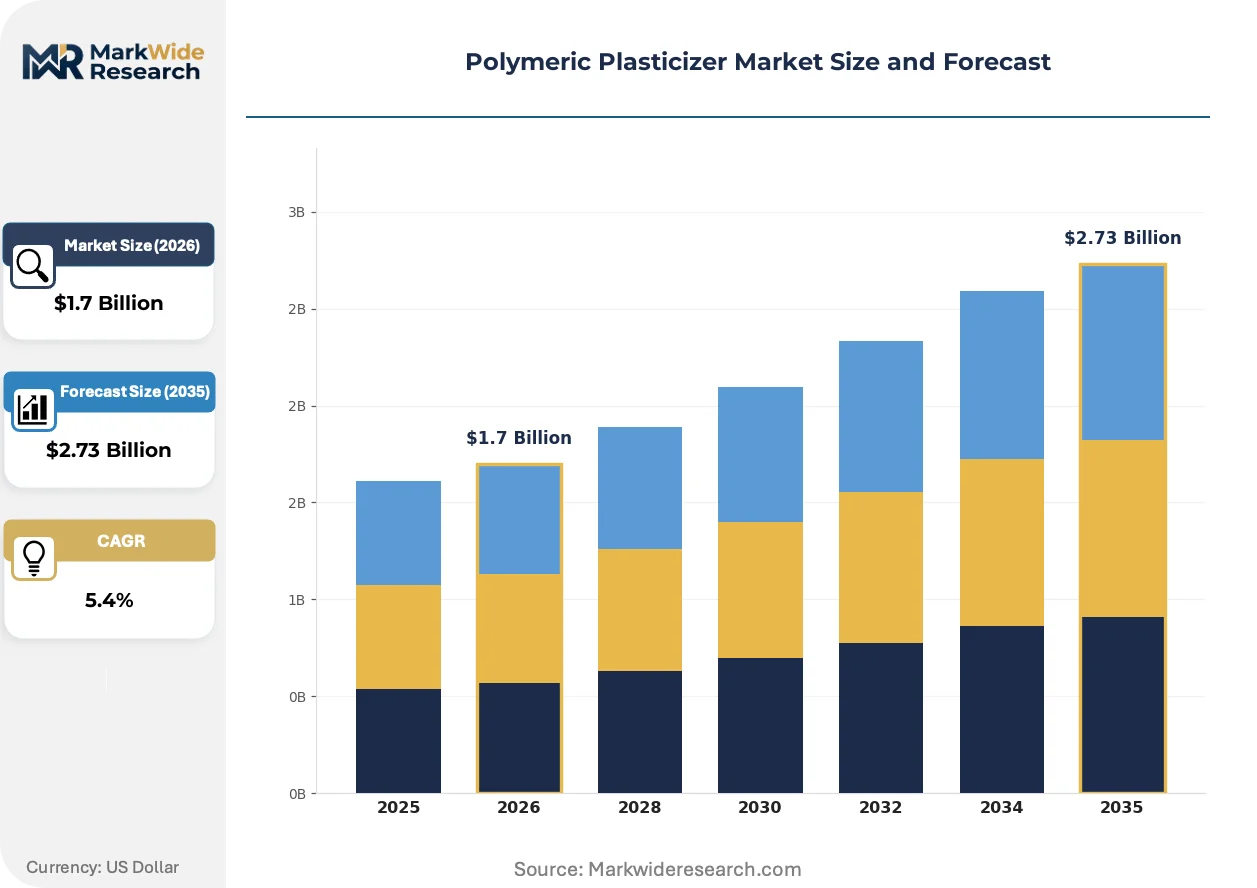
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phthalate-Based, Non-Phthalate, Bio-Based, Polymer Blends End Use Industry: Automotive, Construction, Electronics, Consumer Goods Application: Flooring, Coatings, Adhesives, Films Form: Liquid, Solid, Granular, Paste |
| Companies Covered | Arkema S.A, The Dow Chemical Company, BASF SE, Evonik Industries AG, Lanxess AG, ExxonMobil Chemical, LG Chem, Ineos Group, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymeric Plasticizer Market Strategic Shifts & Innovations
Product development is aligning with sustainability mandates and stringent performance requirements. This evolution prioritizes materials that offer enhanced permanence and a reduced environmental footprint without compromising processability for end-users.
High-molecular-weight polyester chemistry delivers superior permanence and resistance to extraction. The automotive and wire and cable industries are steadily adopting these advanced formulations for critical components exposed to extreme temperatures. This technological focus is consolidating the market around suppliers with sophisticated polymerization control, squeezing out competitors unable to meet stringent performance specifications.
The US EPA's ongoing risk evaluations of chemicals under the Toxic Substances Control Act (TSCA) are prompting proactive reformulation. These assessments create market uncertainty for some legacy chemicals, encouraging a shift toward materials with established safety profiles. The electrical and electronics sector is particularly responsive, updating material specifications to favor TSCA-compliant polymeric plasticizers to ensure supply chain continuity.
Specification based on eco-label compliance is altering purchasing behavior. End-product manufacturers now often bypass traditional distribution channels to engage directly with plasticizer producers for certified performance data. This pattern is most pronounced in the European construction sector, where adherence to standards like BREEAM for flooring and roofing membranes is a key differentiator.
Polymeric Plasticizer Market Segmentation
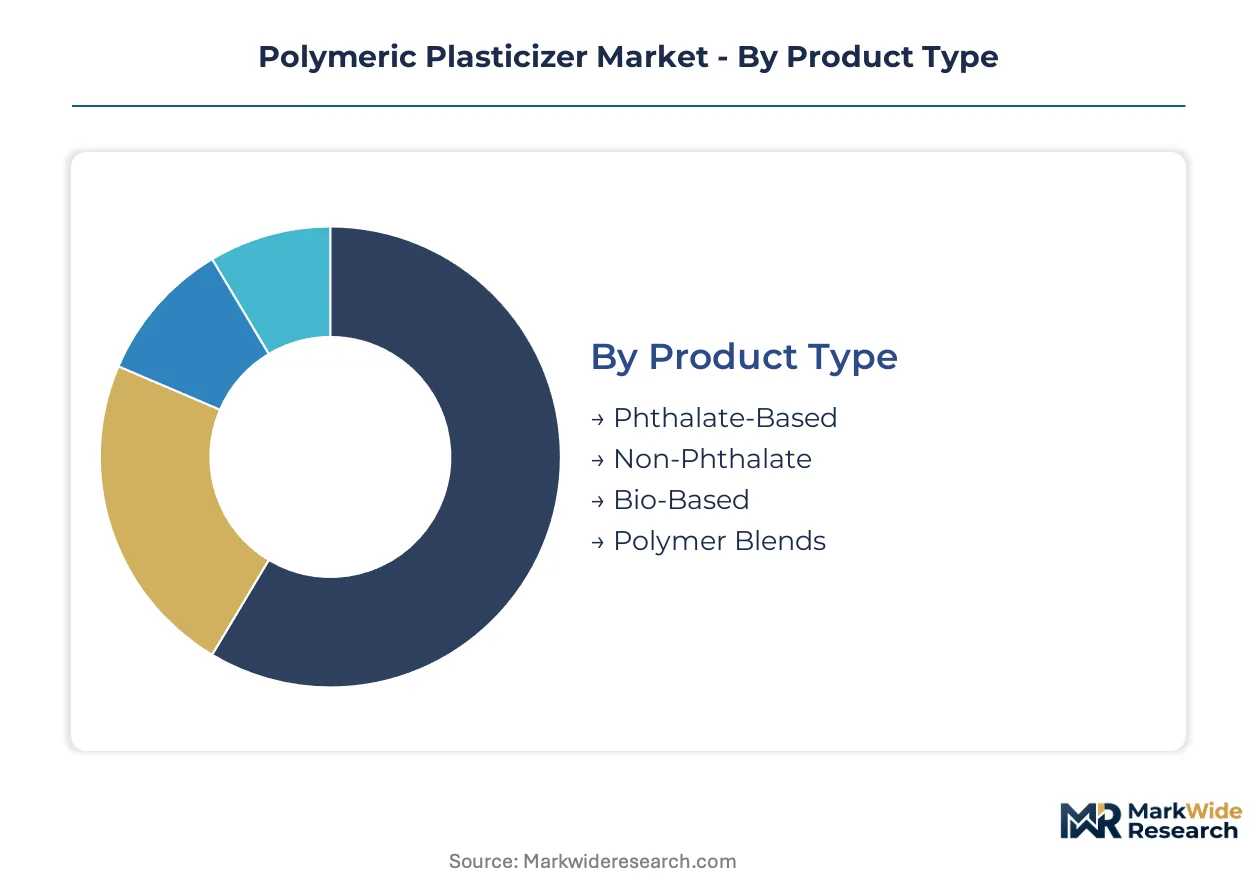
The polymeric plasticizer market is intrinsically complex, driven by diverse material requirements and evolving regulatory mandates across various end-use sectors. Understanding these distinct segments provides clarity on demand drivers and technological focus for manufacturers.
Product Type:
The product type segmentation reflects a spectrum from highly standardized formulations to specialized, customized blends for specific performance profiles.
- Non-Phthalate:These plasticizers, including adipates and trimellitates, offer reduced migration and lower toxicity, addressing stringent regulatory requirements from the EU's REACH framework. Demand concentrates in sensitive applications like medical devices and food contact materials, particularly in Europe and North America.
- Bio-Based:Derived from renewable feedstocks such as epoxidized soybean oil or castor oil, these alternatives align with corporate sustainability goals. Their demand is concentrating in green building projects and consumer goods sectors seeking a reduced environmental footprint.
- Phthalate-Based:Traditional plasticizers like DEHP and DINP still hold market share due to cost-effectiveness, but their use is increasingly restricted. Procurement patterns are shifting away from these in regulated markets, especially within the EU.
- Polymer Blends:These advanced formulations combine different plasticizer chemistries to achieve tailored performance characteristics for specific polymer matrices.
Leading the category by volume: Non-Phthalate. Growing fastest: Bio-Based.
End Use Industry:
End-use industry segmentation highlights specific application-specific demands, dictating material specifications and performance criteria for polymeric plasticizers.
- Automotive:This sector requires high-performance polymeric plasticizers for durable interior components, ensuring low-fogging and long-term flexibility. Demand for these materials is particularly high in Germany and Japan, driven by stringent quality standards.
- Construction:Polymeric plasticizers enhance the longevity and flexibility of materials used in roofing membranes, flooring, and sealants. This industry segment focuses on materials offering extended service life and weather resistance in large infrastructure projects.
- Electronics:Polymeric plasticizers are vital for insulating cables and components, providing flexibility and flame retardancy without compromising electrical properties. Manufacturers in South Korea and Taiwan are particularly focused on these specialized formulations.
- Consumer Goods:This segment includes toys, packaging, and household items, where safety and non-toxicity are paramount.
Automotive applications drive significant consumption, while Electronics exhibits rapid expansion.
Application:
The application segment delineates where polymeric plasticizers are integrated, each with distinct volume requirements and performance expectations.
- Films:Polymeric plasticizers provide essential flexibility, durability, and barrier properties to various film types, including agricultural and packaging films. The demand for high-permanence films is strong in China's manufacturing sector for both domestic and export markets.
- Adhesives:These plasticizers improve the tack, flexibility, and aging resistance of adhesive formulations across diverse industries. Specialized adhesives for automotive and construction applications show particular growth.
- Flooring:Polymeric plasticizers are extensively used in PVC flooring to enhance flexibility, wear resistance, and longevity. This application represents a mature segment with consistent demand in residential and commercial construction.
- Coatings:Plasticizers impart flexibility and crack resistance to various coating formulations, including protective and decorative paints.
Flooring applications command substantial volume, with Films showing considerable growth.
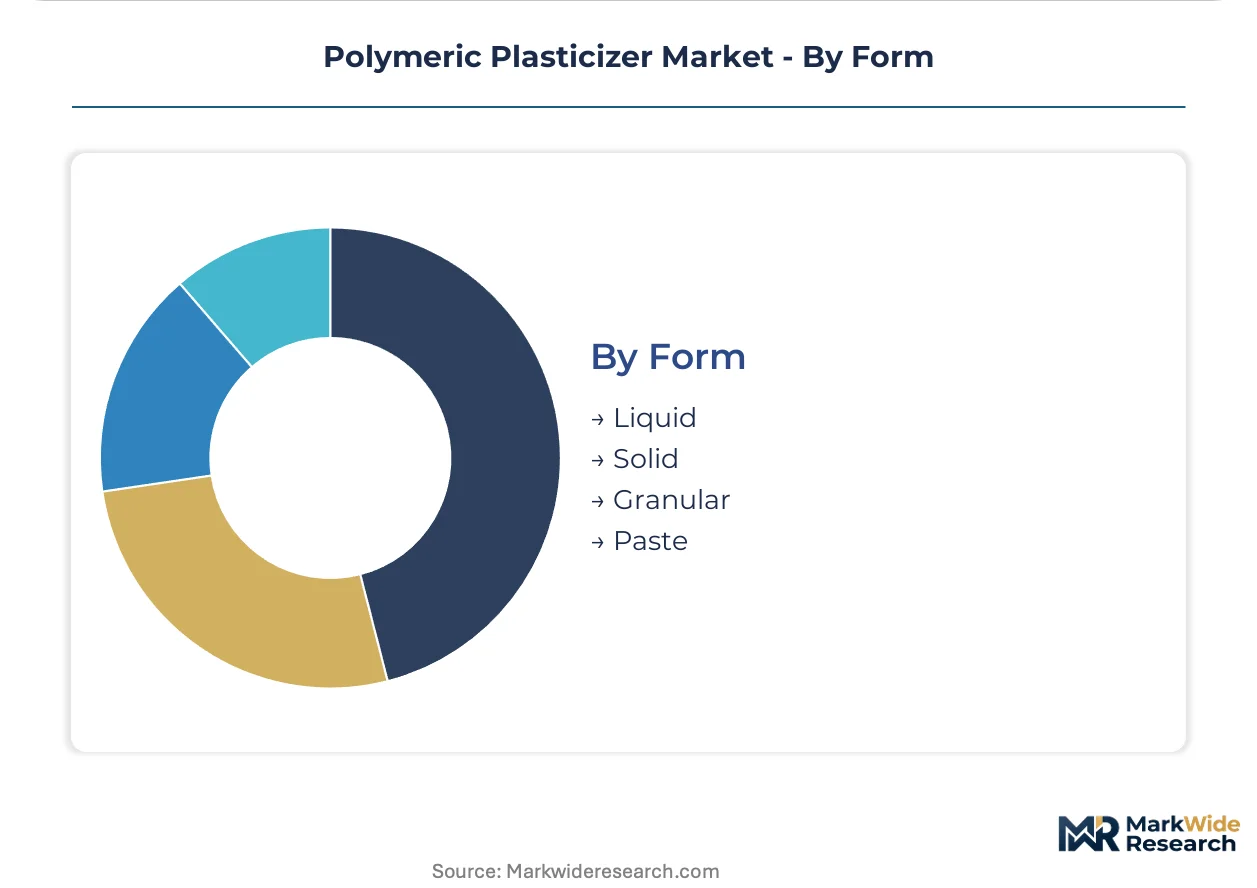
Form:
The form segmentation addresses the physical state of the plasticizer, directly impacting processing characteristics and ease of integration into polymer matrices.
- Liquid:Liquid polymeric plasticizers are typically easy to incorporate into polymer compounds, offering efficient mixing and processing. This form is widely adopted across various industries due to its versatility and handling convenience.
- Solid:Solid forms, often in pellet or powder, are used for specific compounding processes where low volatility or controlled release is critical. These forms are preferred in applications requiring precise dosing and minimal migration.
- Granular:Granular plasticizers offer good flow properties and are suitable for dry blending operations in PVC compounding. Manufacturers in India are increasingly utilizing granular forms for bulk processing.
- Paste:Paste forms facilitate uniform dispersion in specific polymer systems, particularly in plastisol applications.
Liquid forms dominate processing ease, while Paste forms are gaining traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The polymeric plasticizer market exhibits a distinct production-versus-consumption dynamic, with manufacturing hubs driving demand for specialized materials while regulatory landscapes dictate product formulation. Countries with robust automotive and construction sectors demonstrate particularly strong demand for high-permanence plasticizers.
China
China's manufacturing sector drives significant demand for polymeric plasticizers in films and automotive components, supporting both domestic consumption and global exports. The nation's GB standards increasingly influence material specifications, accelerating the shift away from traditional phthalates. Industrial clusters in the Yangtze River Delta actively integrate these advanced materials into diverse end products.
Germany
Germany's sophisticated automotive industry requires high-performance polymeric plasticizers for durable interior components and wire insulation. The EU's REACH regulation strongly influences material selection, accelerating the shift away from restricted phthalates. Automotive manufacturing centers in Bavaria and Baden-Württemberg lead the adoption of these specialized plasticizers.
United States
Demand in the United States stems from robust construction and automotive sectors, prioritizing long-term material performance and safety. The US EPA's ongoing chemical safety assessments under TSCA encourage manufacturers to reformulate products with established safety profiles. Chemical production facilities along the Gulf Coast are expanding capacity for advanced polymeric plasticizer synthesis.
India
India presents a significant opportunity for market penetration as industrial safety standards and consumer awareness gradually increase across various sectors. The Bureau of Indian Standards (BIS) is developing new guidelines that could favor polymeric alternatives in sensitive applications. Rapid industrialization in Maharashtra and Gujarat creates a growing need for durable construction materials.
Japan
Japan's advanced electronics and automotive industries require high-permanence polymeric plasticizers for critical components. Japanese Industrial Standards (JIS) emphasize material quality and longevity, driving innovation in plasticizer chemistry. The Kanto region, with its dense concentration of high-tech manufacturing, actively specifies these specialized formulations.
Polymeric Plasticizer Market Key Industry Players
The competitive structure tilts toward a moderately consolidated landscape, with a blend of large-scale chemical conglomerates and specialized niche players. Strategic archetypes include diversified chemical producers, non-phthalate specialists, and high-performance additive providers. Dominant competitive moves involve significant investment in research and development and strategic portfolio diversification to meet evolving regulatory and performance requirements.
Specialists in advanced chemical solutions, BASF SE and Lanxess AG, exemplify the diversified chemical producer archetype, leveraging extensive chemical portfolios to offer a broad range of plasticizer solutions across various end-use requirements. Eastman Chemical Company, on the other hand, represents the non-phthalate specialist, positioning itself to benefit significantly from stringent regulatory shifts and increasing demand for bio-based alternatives. These companies anchor innovation in areas like lower-migration and high-permanence formulations, crucial for sensitive applications.
| Leading Market Players |
|---|
| Arkema S.A |
| The Dow Chemical Company |
| BASF SE |
| Evonik Industries AG |
| Lanxess AG |
| ExxonMobil Chemical |
| LG Chem |
| Ineos Group |
| Eastman Chemical Company |
| Others |
Cost & Logistics Intelligence
European Union's REACH framework, which restricts certain ortho-phthalates, gates both qualified supply and premium-tier pricing access for polymeric plasticizers. This regulatory pressure compels manufacturers to invest in higher-performance, lower-migration alternatives for market viability.
Pricing Analysis
Product performance in critical applications serves as the primary value-based pricing anchor for polymeric plasticizers. Pricing differentiation stems from the material's permanence, its migration resistance, and specific end-use certifications like FDA or EFSA compliance. Pricing pressure stems from the higher production costs of polymeric plasticizers compared to commodity phthalates, limiting adoption in price-sensitive applications. The construction sector exhibits higher price sensitivity, while automotive and medical industries prioritize performance over cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized chemical producers for key intermediates such as adipic acid and various diols. Geographic supply concentration for these critical raw materials includes China and the United States, influencing global availability. Commodity price volatility for petrochemical feedstocks presents a structural risk to the polymeric plasticizer supply chain. Downstream distribution runs through a mix of direct sales to large compounders and specialized chemical distributors serving smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polymeric plasticizer market is a consolidation play, with stringent regulatory shifts forcing weaker players out of sensitive application segments.
For Market Incumbents: To counter the persistent threat of feedstock volatility, incumbents should deepen backward integration into key raw material production. Strategic capacity additions in regions like the US Gulf Coast can secure supply. Investment in advanced polymerization control ensures consistent product quality and meets evolving performance specifications for automotive components.
For New Entrants and Emerging Players: Enter via niche applications requiring high purity and low migration, such as medical devices or food contact materials. Targeting emerging markets like India, where industrial safety standards are increasing, offers growth opportunities. A strong go-to-market angle involves offering bio-based alternatives that align with corporate sustainability mandates.
For Investors and Strategic Acquirers: Significant investment in bio-based plasticizer innovation is the leading indicator that signals long-term market leadership. The market remains viable over the next decade, driven by regulatory tailwinds and performance needs. Acquisition targets should be specialized non-phthalate producers with established intellectual property in high-permanence formulations. Outcomes are best read as a band of plausibility, not a single trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Non-Phthalates | This move secures future supply for growing demand in regulated markets like Europe and North America. |
| R&D in Bio-Based Chemistry | Developing renewable feedstock plasticizers appeals to green building projects and sustainability-focused consumer brands. |
| Certification for Medical/Food Contact | Achieving FDA or EFSA compliance unlocks premium segments with stringent migration limits. |
| Strategic Partnerships with OEMs | Collaborating with automotive manufacturers ensures early integration into new vehicle platforms and material specifications. |
| Investment in Processing Expertise | Supporting PVC compounders with technical guidance overcomes processing complexity challenges for high-viscosity polymeric plasticizers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary research involved interviews with plant managers, R&D directors, procurement leads at automotive and construction OEMs, and regulatory affairs specialists. This approach combined bottom-up market sizing with top-down validation across all segments.
Data-stream reconciliation formed the analytical framework for market projections across the analysis window. Segmentation dimensions modeled included product type, end-use industry, application, form, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected future demand, incorporating inputs such as raw material price indices and regulatory compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme feedstock volatility or unforeseen regulatory divergence. All forecasts reflect assumptions regarding technological advancements and macroeconomic stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Viscosity Index Improvers Market
Additives
Sodium Stearyl Fumarate Market
Additives
Automotive Coolant Additives Market
Additives
Iso-Butyric Acid Market
Additives
Micronized Powder Market
Additives
South Africa Acidulants Market
Additives
Global Propyl Acetate Market
Additives
Plasticizers Market
Additives
Anti-Block Additives Market
Additives
Magnesium Stearate Market
Additives
Foundry Additives Market
Additives
Green Polymer Additive Market
Additives
Bromine Derivatives Market
Additives
Global Formulation Additives Market
Additives
Caustic Sulphite Caramel Market
Additives
Calcium Acetate Market