
 Thallium Acetate Market | 2026-2036
Thallium Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Thallium Acetate Market Insights
China is narrowing its dominance in thallium salt refining capacity as environmental audits restrict smaller producers. American Elements sustains a vertically integrated position from raw thallium sourcing through purified acetate output. ProChem specializes in custom synthesis for research-grade specifications, while Sigma-Aldrich controls distribution channels across North American academic and pharmaceutical accounts.
Thallium acetate is a white crystalline salt of thallium and acetic acid, typically synthesized through reaction of thallium carbonate or thallium hydroxide with acetic acid, and is valued for its high solubility in aqueous systems and precise stoichiometry in thin-film deposition processes. The compound serves primarily as a dopant precursor in semiconductor manufacturing and as a reagent in specialized organic synthesis. Analytical-grade material commands premium positioning due to stringent trace-metal specifications required by photovoltaic research, while industrial-grade output serves bulk chemical synthesis with lower purity tolerances. Pharmaceutical-grade supply remains constrained by toxicity handling protocols and limited qualified production facilities.
EPA regulates thallium compounds under the Toxic Substances Control Act, requiring detailed reporting for manufacture and import, while OSHA mandates specific exposure limits in workplace environments handling soluble thallium salts. REACH registration in the European Union imposes comprehensive toxicity data requirements that filter market participants by compliance capability. Stakeholders must monitor evolving substitution trends in electronics manufacturing, where indium and gallium compounds compete for similar optoelectronic applications, and assess whether thallium acetate retains cost-performance advantages in next-generation thin-film architectures.
Market Dynamics
REACH compliance requirements are compressing the supplier base across the European Union, as analytical-grade thallium acetate procurement concentrates among Bavarian precision materials clusters serving semiconductor research.
Growth Catalysts
- Photovoltaic Research Expansion:Thin-film perovskite architectures require high-purity dopant precursors. Bavarian research facilities are scaling procurement volumes for next-generation cell development.
- REACH Registration Thresholds:Comprehensive toxicity data requirements filter out marginal producers. Qualified suppliers capture expanded market share as compliance costs rise.
- Semiconductor Doping Applications:Thallium acetate delivers precise stoichiometry for compound semiconductor manufacturing. Specialty chemical manufacturers in Germany are expanding analytical-grade production lines.
Market Restraints
- Raw Material Concentration Risk:Thallium ore refining capacity clusters in China, where environmental audits restrict smaller producers. Supply security concerns constrain European procurement planning.
- Substitution Pressure from Indium Compounds:Indium tin oxide and gallium arsenide compete for optoelectronic applications. Cost-performance tradeoffs favor alternatives in display manufacturing.
- OSHA Exposure Limit Compliance:Soluble thallium salt handling mandates specialized infrastructure. Workplace safety protocols elevate operational costs above commodity chemical benchmarks.
Strategic Opportunities
- Underpenetrated North American Academic Distribution:Research-grade specifications remain underserved outside established pharmaceutical channels. Direct synthesis partnerships with university procurement offices offer expansion potential.
- EU Green Deal Chemical Sustainability Mandates:Circular economy frameworks incentivize closed-loop thallium recovery. Qualified facilities can position acetate production within preferred supplier networks.
- Digital Procurement Platform Integration:Specialty chemical marketplaces are disintermediating traditional distributor relationships. Early platform adoption reduces customer acquisition costs for analytical-grade suppliers.
Industry Challenges
- Toxicity Handling Certification Bottlenecks:Pharmaceutical-grade qualification requires extended facility audits. Limited qualified production capacity constrains premium segment expansion.
- Legacy Synthesis Equipment Retrofit Requirements:Acetic acid reaction containment systems demand capital-intensive upgrades. Smaller producers face asset replacement decisions under compressed timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thallium Acetate Market |
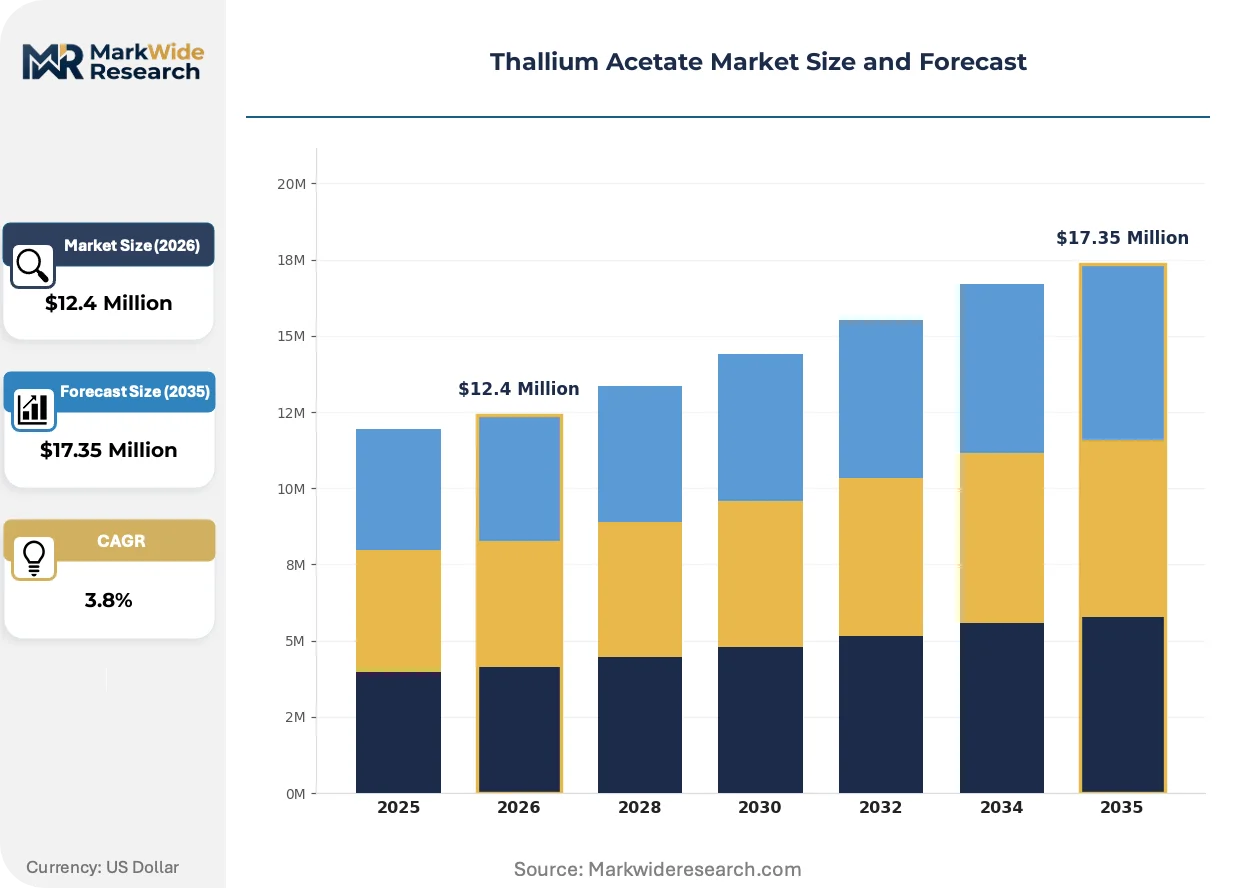
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $17.35 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Analytical Grade, Reagent Grade, Pharmaceutical Grade End User: Chemical Manufacturers, Research Laboratories, Pharmaceutical Companies, Academic Institutions Application: Photovoltaics, Electronics, Chemical Synthesis, Drug Development Packaging Type: Drums, Bags, Totes, Bottles |
| Companies Covered | ProChem, NOAH TECHNOLOGIES CORPORATION, American Elements, Alfa Aesar, Sigma-Aldrich, NANOSHEL, Ereztech, Oakwood Products, Chemdyes Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thallium Acetate Market Trends and Innovations
Computational materials science is compressing experimental iteration cycles, while regulatory digitization and procurement centralization reshape how specialty chemicals reach end-users.
High-throughput computational screening is virtualizing traditional wet-lab dopant optimization workflows. Semiconductor manufacturers in Germany and Japan are adopting machine-learning-guided precursor selection, reducing physical testing volumes by orders of magnitude. This compression is virtualizing the market's historical reliance on iterative synthesis batches, concentrating demand among suppliers with integrated computational validation capabilities.
ECHA's SCIP database requirements for Substances of Very High Concern are mandating granular supply chain transparency across the European Union. Industrial users of thallium acetate must now document full material provenance from ore source to final application. Specialty chemical distributors serving Bavarian research clusters are investing in blockchain-traceability systems to maintain market access under these disclosure protocols.
Research consortia procurement is consolidating previously fragmented academic purchasing into multi-institutional framework agreements. German Max Planck Institutes and Fraunhofer centers are negotiating collective thallium acetate supply contracts with purity-grade tiering. This concentration is displacing individual laboratory spot-buying patterns, favoring suppliers with scaleable analytical-grade production and documented batch-to-batch consistency.
Thallium Acetate Market Segmentation
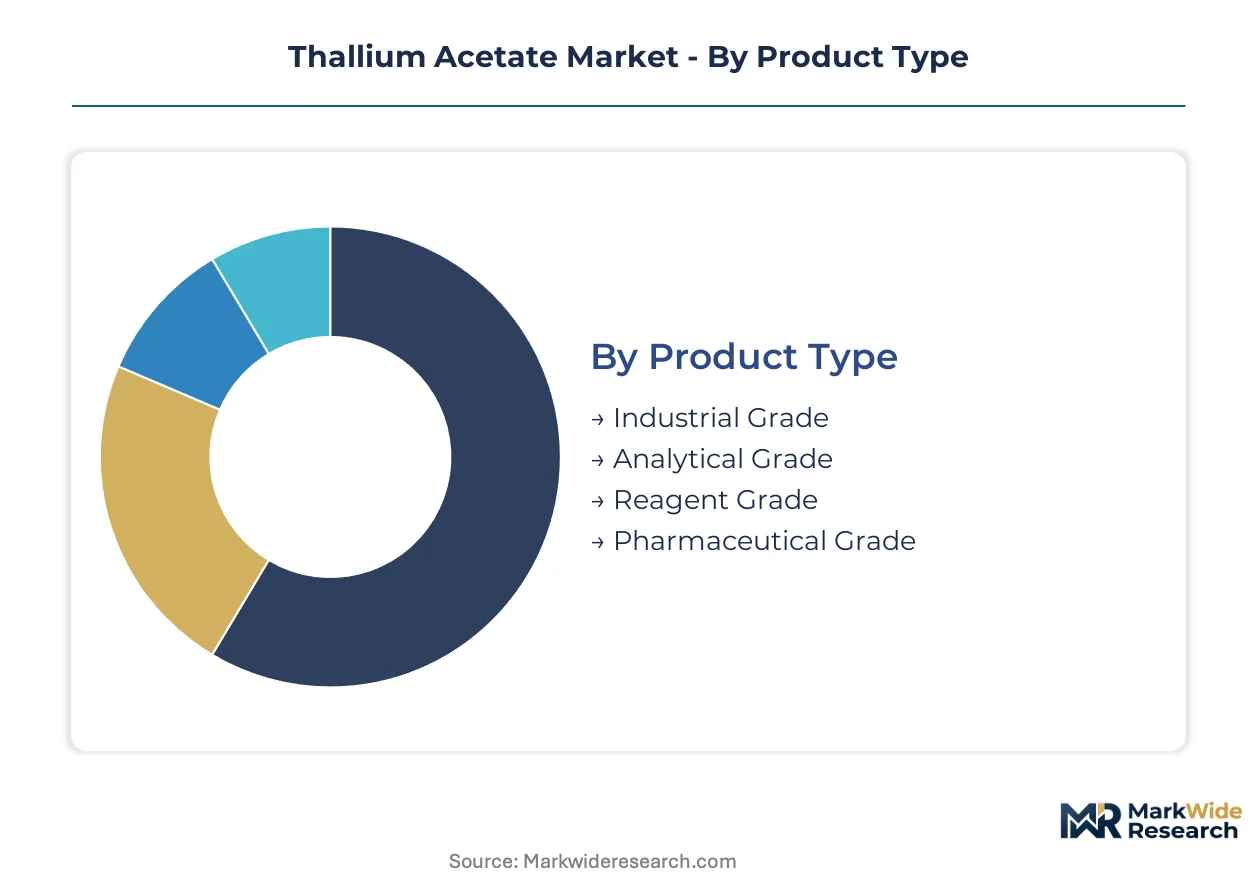
Thallium acetate procurement patterns diverge sharply across purity grades and institutional buyer types. Semiconductor manufacturers demand analytical-grade consistency, while bulk chemical processors prioritize cost-efficient industrial specifications.
Product Type:
Purity thresholds determine handling protocols, pricing tiers, and regulatory documentation burdens across the use-case spectrum.
- Analytical Grade:Material meeting stringent trace-metal specifications below 10 ppm total impurities serves thin-film deposition and photovoltaic research. Bavarian precision materials clusters in Germany are scaling procurement volumes for perovskite cell development, with REACH documentation requirements filtering supplier qualification.
- Industrial Grade:Soluble salt with moderate purity tolerances supports bulk organic synthesis and intermediate chemical production. Chinese environmental audits restricting smaller thallium refiners are compressing supply security for European chemical manufacturers dependent on cost-efficient feedstock.
- Reagent Grade:Laboratory-scale batches with documented batch-to-batch consistency support academic research workflows. Sigma-Aldrich distribution channels dominate North American procurement for this specification tier.
- Pharmaceutical Grade:Toxicity handling certification and extended facility audits constrain qualified production capacity. Limited GMP-compliant manufacturing sites restrict segment expansion despite premium pricing potential.
Established volume favors industrial grade; emerging adoption favors analytical grade.
End User:
Customer sophistication and procurement scale create divergent service requirements across institutional categories.
- Research Laboratories:Small-batch, high-frequency orders with exacting documentation demands characterize Fraunhofer center and Max Planck Institute procurement in Germany. Multi-institutional framework agreements are consolidating previously fragmented purchasing into collective supply contracts with purity-grade tiering.
- Chemical Manufacturers:Volume procurement of industrial-grade material for intermediate synthesis drives demand concentration among specialty chemical producers. Acetic acid reaction containment retrofit requirements are forcing asset replacement decisions under compressed timelines.
- Academic Institutions:Research-grade specifications remain underserved outside established pharmaceutical distribution channels. Direct synthesis partnerships with university procurement offices offer expansion potential for qualified suppliers.
- Pharmaceutical Companies:Stringent toxicity handling protocols and limited qualified production facilities constrain supply availability. OSHA exposure limit compliance mandates specialized infrastructure elevating operational costs above commodity chemical benchmarks.
Procurement consolidation favors research laboratories; margin expansion favors pharmaceutical companies.
Application:
Functional performance requirements in optoelectronic systems drive grade selection and supplier qualification intensity.
- Electronics:Precise stoichiometry in compound semiconductor doping applications commands analytical-grade specifications. German specialty chemical manufacturers are expanding production lines to serve this segment.
- Photovoltaics:Thin-film perovskite architectures require high-purity dopant precursors with documented provenance. ECHA SCIP database mandates are forcing blockchain-traceability investments among Bavarian research cluster distributors.
- Chemical Synthesis:Bulk organic transformation reactions utilize industrial-grade material with lower purity tolerances. Substitution pressure from indium and gallium compounds competes for similar process applications.
- Drug Development:Specialized reagent applications in pharmaceutical research face constrained supply from limited GMP-qualified facilities. Toxicity handling certification bottlenecks restrict premium segment expansion.
Technology transition favors photovoltaics; process substitution risk favors chemical synthesis.
Packaging Type:
Containment specifications align with toxicity classification and handling infrastructure at destination facilities.
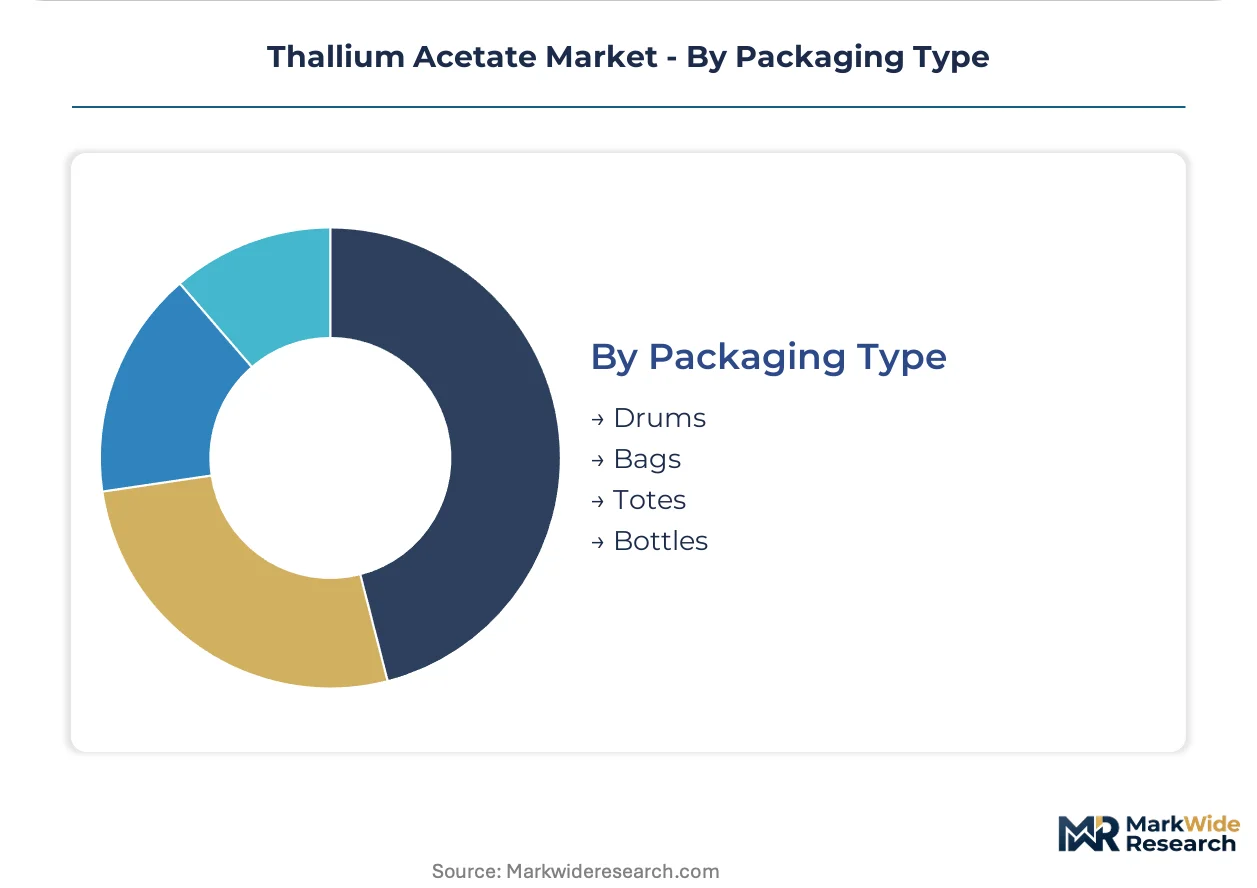
- Drums:Standard industrial containment for bulk chemical manufacturer procurement with established hazardous material handling protocols.
- Bottles:Laboratory-scale packaging dominates research laboratory and academic institution procurement patterns.
- Totes:Intermediate bulk containers serve chemical synthesis applications requiring moderate volume with reduced handling frequency.
- Bags:Specialized barrier packaging supports select pharmaceutical and reagent-grade distribution with moisture protection requirements.
Operational scale favors drums; handling precision favors bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thallium ore refining capacity clusters in China, where environmental audits restrict smaller producers and concentrate supply among compliant operators. This geographic concentration creates procurement security concerns for European and North American chemical manufacturers dependent on purified acetate feedstock.
China
Environmental audits by the Ministry of Ecology and Environment restrict smaller thallium refiners, compressing supply among compliant producers. The country's dual carbon goals accelerate facility consolidation in Hunan and Yunnan provinces. Yangtze River Delta chemical processors face feedstock security planning challenges as qualified ore sources narrow.
Germany
Bavarian precision materials clusters scale analytical-grade thallium acetate procurement for perovskite photovoltaic research. REACH registration thresholds filter supplier qualification through comprehensive toxicity data requirements. Fraunhofer centers in Munich negotiate multi-institutional framework agreements with purity-grade tiering.
United States
EPA Toxic Substances Control Act reporting mandates shape manufacturer and importer compliance infrastructure. OSHA exposure limits for soluble thallium salts elevate workplace safety protocol costs above commodity chemical benchmarks. Greater Boston research corridors concentrate pharmaceutical-grade demand among limited qualified production facilities.
Japan
METI industrial standards guide semiconductor doping precursor specifications for compound manufacturing. Machine-learning-guided precursor selection reduces physical testing volumes at Kansai research facilities. Osaka-based specialty chemical distributors invest in computational validation capabilities to serve compressed experimental iteration cycles.
India
BIS certification requirements for imported specialty chemicals create documentation barriers for thallium compound procurement. DGFT trade protocols govern hazardous material import licensing for research and industrial applications. Maharashtra pharmaceutical clusters face constrained supply from limited GMP-qualified manufacturing sites.
Thallium Acetate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base compresses around REACH-compliant producers capable of analytical-grade documentation. Three archetypes dominate: vertically integrated raw-material-to-acetate producers, custom synthesis laboratories serving research specifications, and distributor-curators managing multi-origin supply chains. Capacity expansion and regulatory compliance certification constitute the dominant competitive moves.
Among North American suppliers, American Elements exemplifies integrated production architecture from ore sourcing through purified output. ProChem occupies a position within the custom synthesis tier, serving research-grade specifications. Sigma-Aldrich anchors distribution channel control across academic and pharmaceutical accounts. These three represent distinct strategic postures: captive supply security, tailored synthesis capability, and procurement aggregation scale.
| Leading Market Players |
|---|
| ProChem |
| NOAH TECHNOLOGIES CORPORATION |
| American Elements |
| Alfa Aesar |
| Sigma-Aldrich |
| NANOSHEL |
| Ereztech |
| Oakwood Products |
| Chemdyes Corporation |
| Others |
Pricing and Supply Chain Analysis
Hunan and Yunnan provinces concentrate thallium ore refining capacity, where environmental audits by China's Ministry of Ecology and Environment compress supply among compliant operators and amplify pricing power for qualified acetate producers serving European and North American buyers.
Pricing Analysis
REACH registration thresholds dictate the pricing tier structure across the European Union, separating pharmaceutical-grade certification from industrial-grade bulk supply. Three-tier pricing structure across premium, standard, and economy levels reflects purity specifications, toxicity handling protocols, and documentation intensity. Cost compression in industrial-grade tiers is intensifying because Chinese environmental audits restrict feedstock availability. Academic institutions exhibit highest price sensitivity due to fragmented procurement budgets, while semiconductor manufacturers demonstrate lowest sensitivity given dopant precursor criticality.
Supply Chain Analysis
Thallium metal feedstock draws from Chinese ore refining clusters in Hunan, Yunnan, and select Kazakh mining operations. Acetic acid reaction chemistry and analytical-grade purification equipment constitute secondary dependencies. Single-source vulnerability concentrates in Yangtze River Delta chemical processors dependent on narrowing qualified ore sources. Distribution runs through specialty chemical distributors with REACH-compliant documentation capabilities serving Bavarian precision materials clusters and North American research corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thallium acetate procurement represents a service-attach opportunity where compliance documentation, batch-to-batch certification, and closed-loop recovery programs generate recurring revenue streams expanding faster than commodity chemical sales.
For Market Incumbents: Pre-empt substitution pressure from indium and gallium compounds by embedding computational validation capabilities into precursor selection workflows. Secure captive supply of raw thallium through backward integration into Kazakh ore partnerships or long-term offtake agreements with Chinese refiners surviving environmental consolidation. Invest in blockchain-traceability infrastructure ahead of ECHA SCIP database enforcement. For New Entrants and Emerging Players: North American academic institutions outside established pharmaceutical distribution channels represent the most penetrable entry point for research-grade specifications. Direct synthesis partnerships with university procurement offices bypass Sigma-Aldrich channel control. Target consortia framework agreements at German Max Planck Institutes and Fraunhofer centers where multi-institutional purchasing concentrates volume. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among REACH-compliant analytical-grade producers with documented batch consistency and circular economy recovery capabilities. Five-to-ten year viability hinges on thallium acetate retaining cost-performance advantages in perovskite photovoltaic architectures against indium tin oxide alternatives. Monitor substitution ratios in next-generation thin-film deposition equipment as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Sourcing | Captive thallium supply from Kazakh or compliant Chinese refiners insulates against environmental audit disruptions. |
| REACH Registration Investment | Comprehensive toxicity data submission filters competitors and secures EU market access for qualified producers. |
| Blockchain-Traceability Deployment | ECHA SCIP database compliance requires granular provenance documentation from ore source to final application. |
| Closed-Loop Recovery Program | EU Green Deal circular economy frameworks incentivize preferred supplier positioning for acetate production. |
| Computational Validation Capability | Machine-learning-guided precursor selection reduces physical testing volumes at semiconductor research facilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing specialty chemical procurement managers at Bavarian semiconductor research facilities, plant managers at thallium salt refiners in Hunan province, distribution channel partners serving North American academic accounts, and technical R&D directors at photovoltaic research consortia. Secondary validation drew from customs and trade data, ECHA registration filings, SEC 10-K disclosures from chemical manufacturers, and OECD chemical safety assessments. Bottom-up volume estimates from end-use application analysis were triangulated against top-down market sizing from production capacity and trade flow data.
Calibration against historical price realizations and volume shipments anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry, packaging format, and regional regulatory cluster. CAGRs were derived from regression analysis of demand drivers against application-specific consumption intensities. Forecast inputs incorporated photovoltaic research funding trajectories, semiconductor doping precursor substitution elasticities, and REACH compliance cost pass-through coefficients.
Practitioners should monitor substitution rates in perovskite cell architectures, Chinese environmental audit enforcement intensity, and ECHA disclosure protocol expansion for early signals requiring forecast revision. Cross-checking against IEA photovoltaic technology roadmaps and SEMI semiconductor materials demand surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
South America Sodium Reduction Agents Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Rheological Additives Market
Additives
Binding Agents Market
Additives
Ruminant Feed Additive Market
Additives
Global Corrosion Inhibitor Market
Additives
Thermal Conductive Additives Market
Additives
Supplemental Coolant Additives Market
Additives
Carboxymethyl Cellulose Market
Additives
Automotive Additives Market
Additives
Global Anti-Fog Additives Market
Additives
Alginic Acid Market
Additives
Glyceryl Caprylate Market
Additives
Stabilizers Market
Additives
Encapsulated Citric Acid Market
Additives
Tragacanth Market