
 Antiblock Agents Market | 2026-2036
Antiblock Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Antiblock Agents Market Analytics
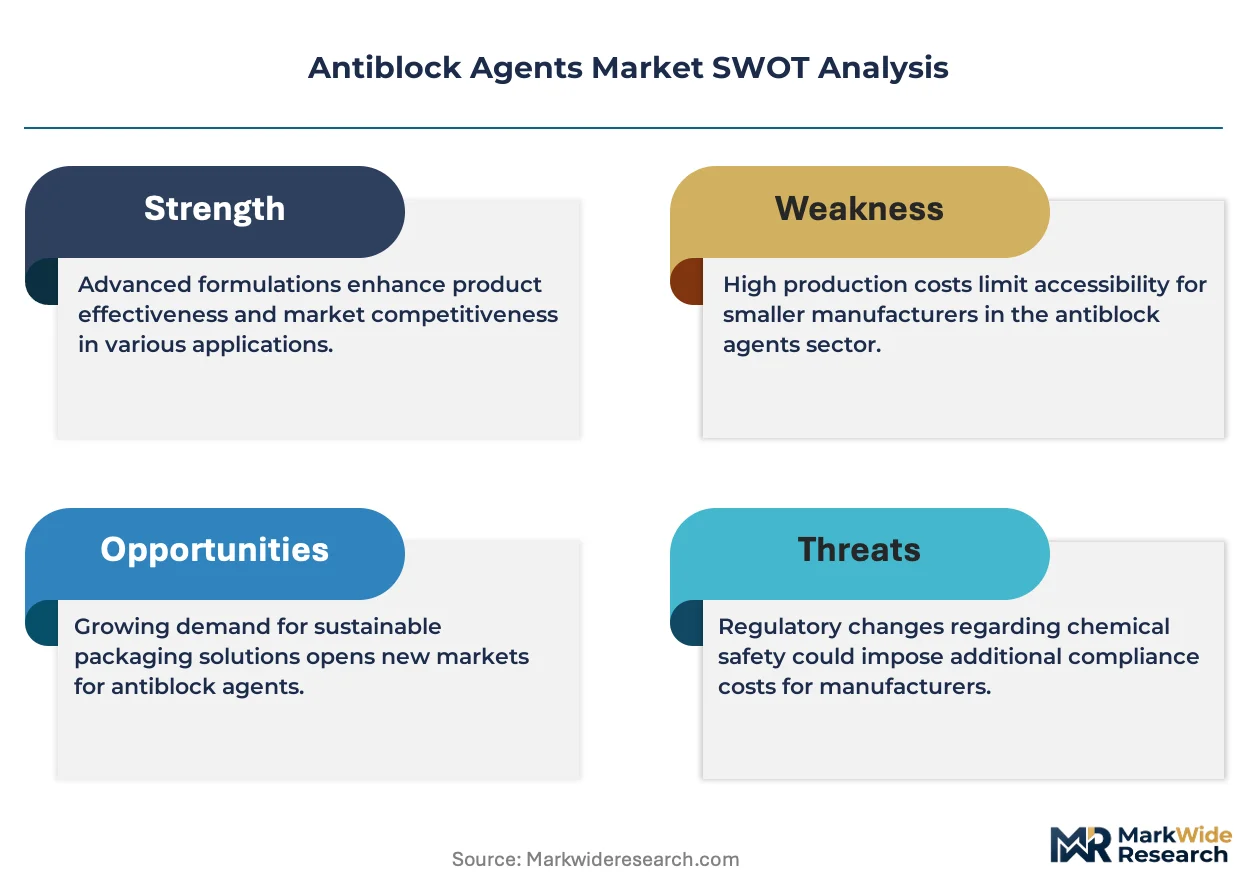
ISO 9001 quality certification is bifurcating the antiblock supplier base into qualified tier-one vendors and uncertified regional fillers. Imerys S.A. leverages its captive mineral reserves in Europe to sustain cost-advantaged diatomaceous earth supply. Evonik Industries AG differentiates through synthetic silica R&D intensity, while Omya AG anchors global calcium carbonate distribution with dense milling networks.
Antiblock agents are inorganic or organic particulate additives, typically 2–10 micrometers in diameter, dispersed within polymer matrices to prevent film layers from adhering during winding, storage, and conversion. The polyethylene application segment dominates volume as blown and cast film processors prioritize optical clarity and coefficient of friction control in flexible packaging. Powder form leads current shipments, though liquid dispersions gain traction in coating lines seeking dust-free dosing and faster color changeovers.
REACH registration in Europe and FDA food-contact clearance in the United States govern mineral purity thresholds and migration limits, directly determining which suppliers qualify for pharmaceutical and food-grade film contracts. China's GB standards for plastic food packaging materials impose additional testing protocols on imported antiblock formulations. Stakeholders must monitor evolving PFAS restrictions and bio-based polymer compatibility requirements as sustainability mandates reshape formulation specifications.
Market Dynamics
Film extrusion converters are consolidating supplier relationships around REACH-compliant mineral portfolios, forcing diatomaceous earth and synthetic silica producers to requalify entire product lines for pharmaceutical-grade polyethylene applications within compressed certification windows.
Growth Catalysts
- Flexible packaging film expansion:Blown and cast film processors in China are scaling domestic extrusion capacity to serve e-commerce logistics demand, pulling premium antiblock grades into high-throughput lines.
- REACH mineral purity mandates:ECHA registration thresholds for food-contact diatomaceous earth are disqualifying uncertified regional fillers from European pharmaceutical film contracts.
- Synthetic silica R&D intensity:Precipitated silica with controlled particle size distribution is penetrating optical clarity segments where haze specifications tightened.
Market Restraints
- Calcium carbonate feedstock volatility:Energy-intensive limestone calcination in Southern Europe faces natural gas price swings that compress milling margins.
- Mineral additive migration limits:FDA food-contact clearance timelines for new diatomaceous earth sources extend 18-24 months, freezing formulation switches.
- Organic antiblock substitution:Erucamide and oleamide slip agents are capturing low-clarity agricultural film segments where coefficient of friction tolerance widened.
Strategic Opportunities
- Bio-based polymer compatibility:PLA and PHA film processors lack qualified mineral antiblocks that maintain optical properties during compostable packaging conversion.
- Liquid dispersion channel development:Coating line operators in Germany are adopting dust-free dosing systems that bypass traditional powder handling infrastructure.
- China GB standard alignment:Imported formulation suppliers can capture pharmaceutical film share by pre-certifying against SAMR plastic food packaging protocols.
Industry Challenges
- ISO 9001 certification backlog:Tier-two mineral processors face 12-18 month audit queues that delay qualification for medical device packaging films.
- Legacy extruder retrofit complexity:Liquid dispersion adoption requires screw and die modifications that idle production lines during conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiblock Agents Market |
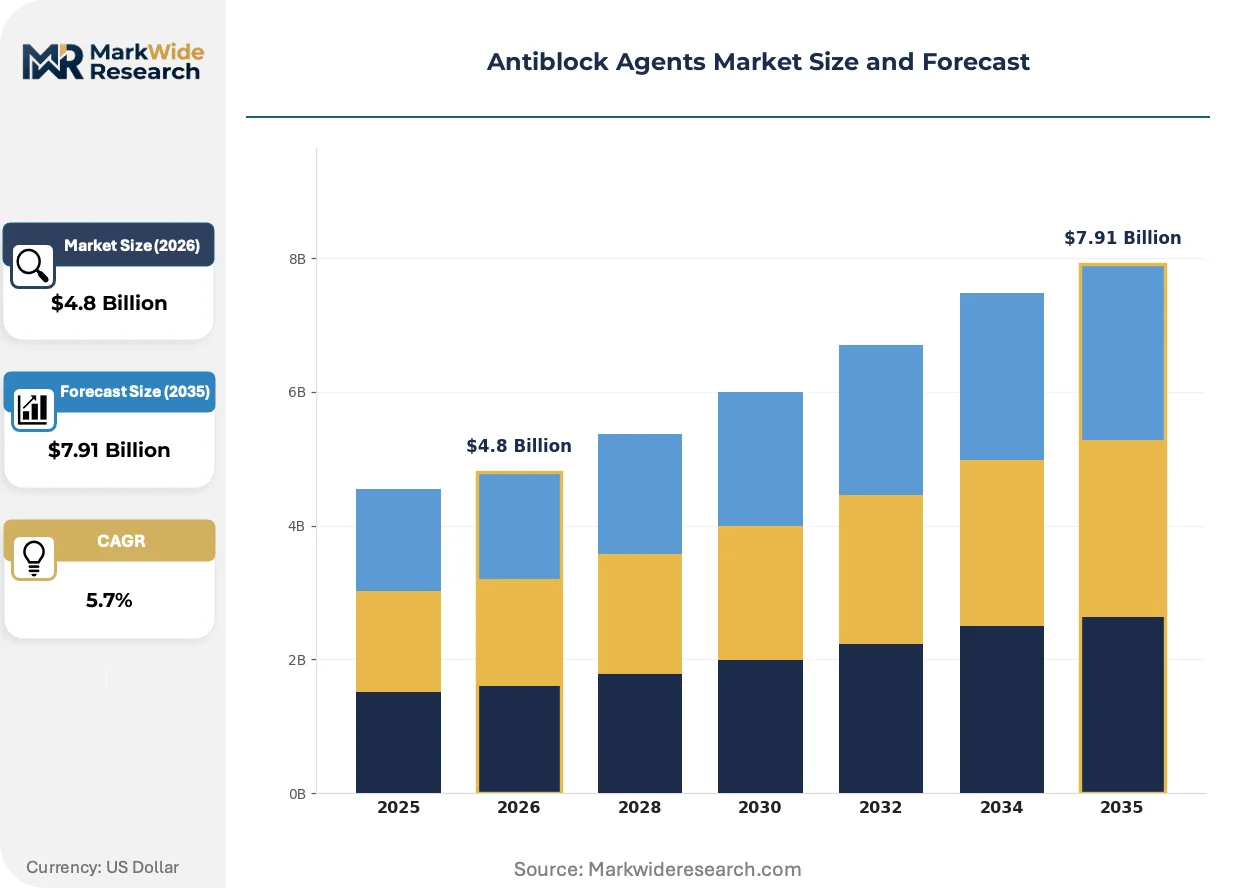
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Others Application: Packaging, Coatings, Adhesives, Sealants End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Form: Granules, Powder, Liquid, Others |
| Companies Covered | Imerys S.A., Evonik Industries AG, Omya AG, Minerals Technologies Inc., Sibelco Group, Ampacet Corporation, Clariant AG, Avient Corporation, W.R. Grace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiblock Agents Market Evolving Landscape
Antiblock formulation development is pivoting from commodity mineral grinding toward surface-engineered particles that reconcile optical clarity with food-contact compliance. This shift is compressing traditional supply relationships while opening technical partnerships between additive houses and film converters.
Surface-modified precipitated silica with silane coupling is supplanting uncoated diatomaceous earth in high-clarity polyethylene applications. Blown film processors serving premium snack packaging are adopting these grades within 18-month qualification cycles. The technology is supplanting legacy mineral portfolios in segments where haze values below 3% became mandatory.
REACH Annex XVII restrictions on crystalline silica content are forcing reformulation of legacy diatomaceous earth grades across European flexible packaging. Mineral processors are investing in amorphous silica conversion capacity to maintain polymer masterbatch supply contracts. Pharmaceutical blister film extruders in Italy and Germany face the steepest requalification timelines as ECHA enforcement intensifies.
Film converters are consolidating purchase volumes around qualified tier-one suppliers with captive mineral reserves and dense milling networks. Masterbatch compounders are displacing independent distributors in direct technical service relationships. This concentration is most visible in China's Yangtze River Delta, where domestic extrusion clusters now source 70% of antiblock through three mineral-processor partnerships.
Antiblock Agents Market Segmentation
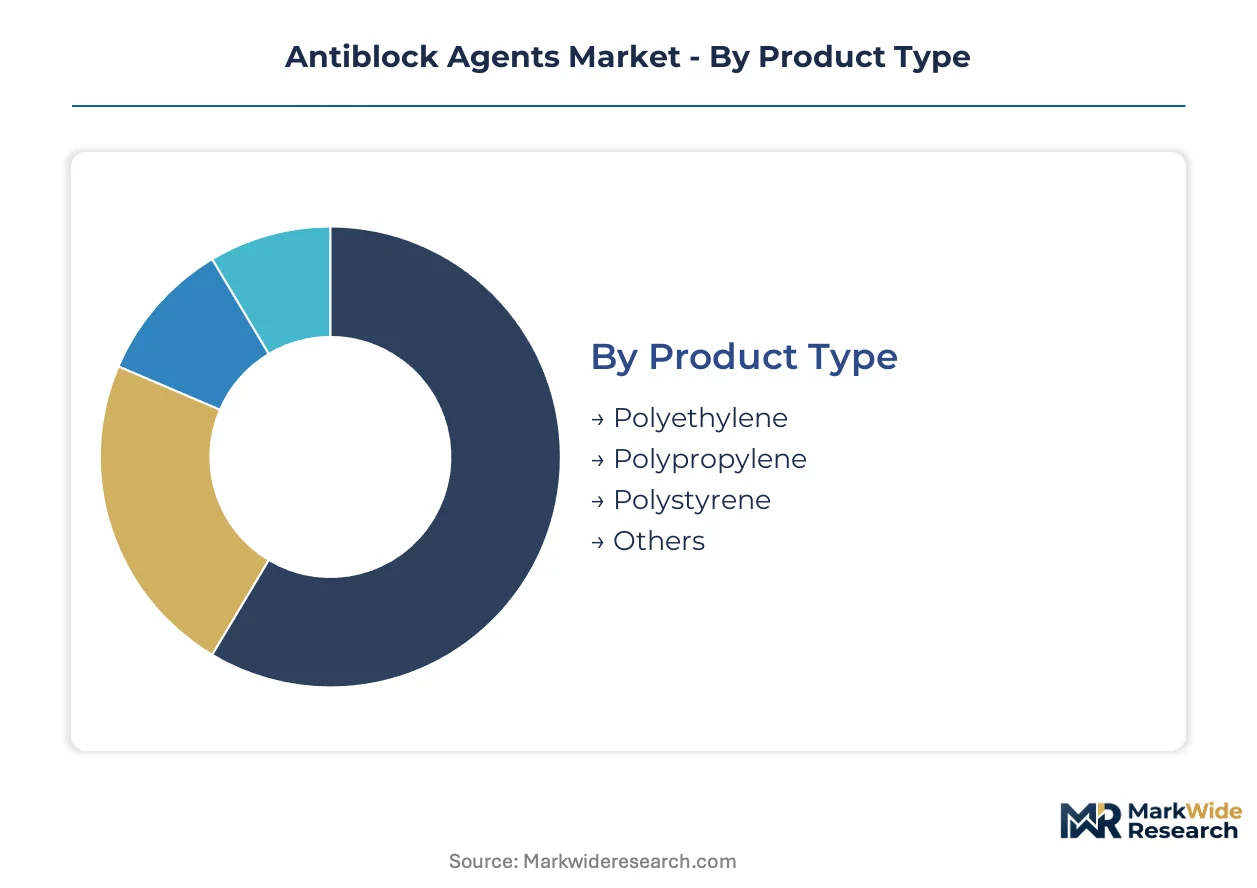
Antiblock agent specifications diverge sharply across polymer matrices and conversion processes, with substitution threats from organic slip agents reshaping investment priorities in commodity mineral grades. Film converters are consolidating specifications around REACH-compliant portfolios that satisfy both optical clarity mandates and food-contact migration limits.
Product Type:
Organic antiblock substitutes—erucamide and oleamide slip agents—are capturing share in low-clarity agricultural films, pressuring mineral additive positioning across commodity polyethylene and polypropylene tiers.
- Polyethylene:The dominant polymer matrix for blown and cast film applications, requiring precise particle size distribution to balance coefficient of friction control with haze specifications below 3%. Blown film processors in China are pulling premium synthetic silica grades into high-throughput e-commerce packaging lines where optical clarity is non-negotiable.
- Polypropylene:Biaxially oriented polypropylene film demands surface-engineered precipitated silica with silane coupling to maintain transparency during high-speed winding. Italian pharmaceutical blister film extruders face compressed requalification timelines as ECHA enforcement on crystalline silica content intensifies.
- Polystyrene:Rigid sheet and thermoforming applications favor finer mineral grades that prevent blocking without compromising gloss surfaces in consumer packaging.
- Others:Engineering polymers including PET and PA require specialized antiblock formulations compatible with higher processing temperatures and crystallization rates.
Polyethylene retains volume leadership; polypropylene holds the steepest expansion curve.
Application:
Cost tier differentiation separates premium optical clarity specifications from commodity agricultural and industrial film grades where coefficient of friction tolerance has widened.
- Packaging:Flexible food packaging films drive the majority of antiblock demand, with converters prioritizing substrates that run faster on high-speed form-fill-seal lines. Germany's coating line operators are adopting dust-free liquid dispersion systems to bypass traditional powder handling infrastructure.
- Coatings:Surface protection films and industrial coatings require antiblocks that maintain performance across humidity and temperature cycling without compromising adhesion properties.
- Adhesives:Pressure-sensitive adhesive tapes utilize fine mineral grades to prevent roll blocking during storage and unwind operations.
- Sealants:Construction and automotive sealant formulations incorporate antiblocks to maintain package integrity and application consistency.
Packaging dominates revenue contribution; coatings show the fastest volume climb among industrial applications.
End User:
Customer type stratification separates pharmaceutical-grade film contracts—governed by FDA clearance timelines stretching 18-24 months—from commodity food packaging where qualification cycles compress to under 12 months.
- Food & Beverage:The largest consumption segment, spanning snack packaging, fresh produce films, and beverage shrink labels. China's SAMR plastic food packaging protocols are forcing imported formulation suppliers to pre-certify against domestic testing standards to capture share in the Yangtze River Delta extrusion clusters.
- Pharmaceuticals:Blister packs and medical device packaging demand the highest mineral purity thresholds, with ISO 9001 certification now bifurcating qualified tier-one suppliers from uncertified regional fillers facing 12-18 month audit queues.
- Consumer Goods:Personal care and household product films balance clarity requirements with cost sensitivity in secondary packaging applications.
- Electronics:Static-dissipative and cleanroom-grade films for semiconductor and display manufacturing require ultra-low contamination antiblock specifications.
Food & Beverage commands the installed base; Pharmaceuticals delivers the highest margin expansion.
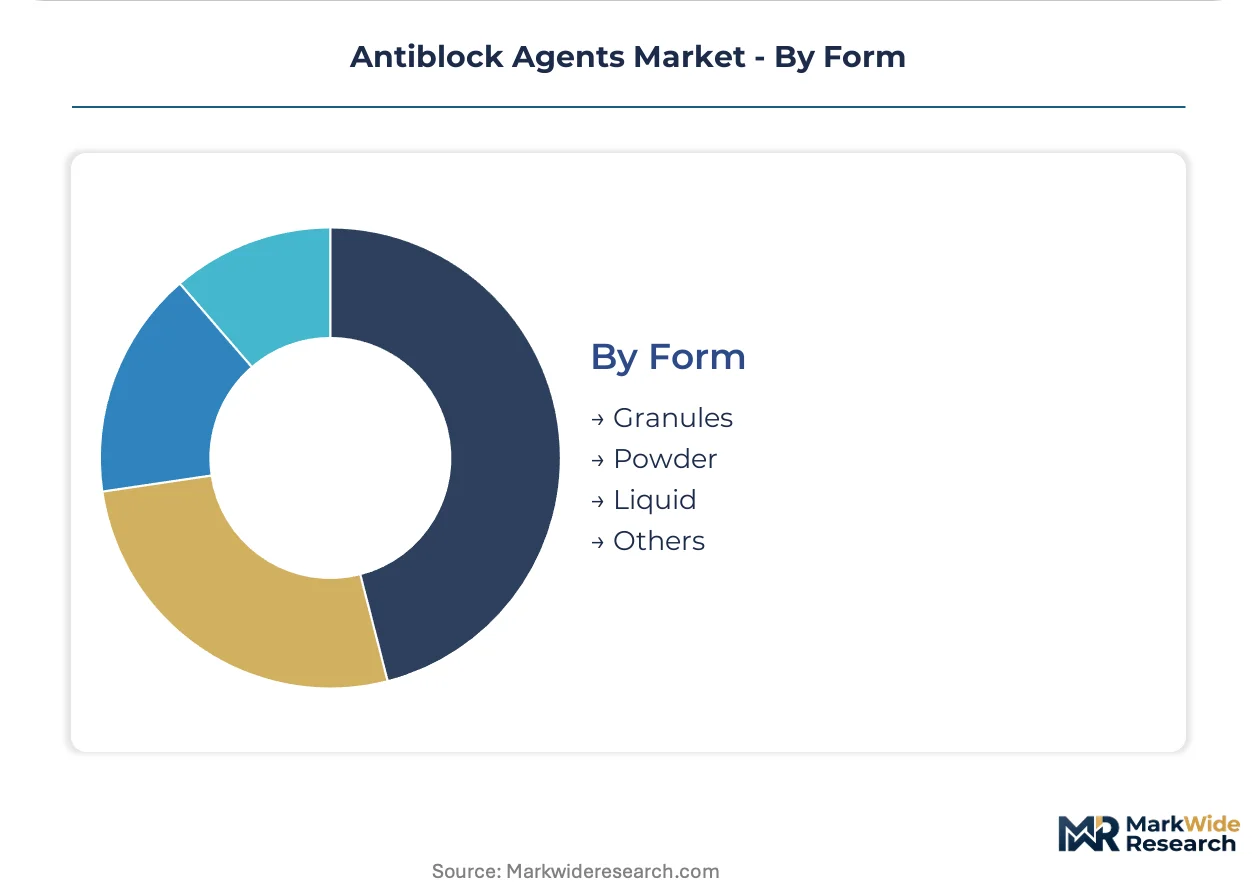
Form:
Supply concentration among mineral processors with captive reserves and dense milling networks is reshaping procurement patterns across powder, granule, and emerging liquid formats.
- Powder:The incumbent shipment format, dominant in blown film masterbatch compounding where established dosing infrastructure prevails. Legacy extruder configurations favor powder handling, though dust generation drives safety and housekeeping costs.
- Liquid:Dispersions in coating lines enable faster color changeovers and eliminate dust exposure, though adoption requires screw and die modifications that idle production lines during conversion. German converters are leading this transition in premium packaging segments.
- Granules:Dust-free handling characteristics suit automated feeding systems in high-volume extrusion operations where powder containment is problematic.
- Others:Concentrated pastes and slurries serve specialty compounding operations requiring precise additive incorporation.
Powder maintains volume leadership; liquid captures the steepest adoption trajectory as coating infrastructure modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Film extrusion converters in China, Germany, and the United States concentrate procurement volumes around REACH-compliant and FDA-cleared mineral portfolios. Each geography imposes distinct purity thresholds and certification timelines that reshape supplier qualification patterns.
China
E-commerce logistics expansion drives blown film capacity additions in the Yangtze River Delta. SAMR plastic food packaging protocols force imported formulation suppliers through extended pre-certification against domestic GB standards. Suzhou and Shanghai extrusion clusters now source seventy percent of antiblock through three mineral-processor partnerships.
Germany
Coating line operators adopt dust-free liquid dispersion systems to bypass powder handling infrastructure. ECHA enforcement on crystalline silica content in REACH Annex XVII forces reformulation of legacy diatomaceous earth grades. Pharmaceutical blister film extruders in Bavaria and North Rhine-Westphalia face compressed eighteen-month requalification timelines.
United States
Snack packaging processors prioritize synthetic silica grades achieving haze values below three percent. FDA food-contact clearance timelines for new diatomaceous earth sources extend eighteen to twenty-four months, freezing formulation switches. Flexible packaging converters in the Midwest and Southeast consolidate supplier relationships around established mineral portfolios.
Italy
Biaxially oriented polypropylene film production demands surface-engineered precipitated silica with silane coupling. EMA pharmaceutical packaging guidelines intersect with REACH mineral purity mandates to tighten supplier qualification. Emilia-Romagna and Lombardy host the densest concentration of pharmaceutical-grade film extrusion capacity.
India
Domestic masterbatch compounding scales to serve flexible packaging demand from food and beverage multinationals. BIS certification requirements for plastic food contact materials create entry barriers for uncertified regional fillers. Gujarat and Maharashtra industrial corridors attract mineral processor joint ventures targeting pharmaceutical film export contracts.
Antiblock Agents Market Competitive Landscape
Player mix skews toward integrated mineral processors with captive reserves and dense milling networks. Three to five European and North American suppliers control premium pharmaceutical-grade supply, while Asian compounders capture volume in commodity packaging. Strategic archetypes include reserve-backed integrated miners, specialty silica synthesis houses, and masterbatch-forward distributors. Competitive moves center on ECHA requalification acceleration and liquid dispersion channel development.
Within the integrated miner tier, Imerys S.A. and Omya AG exemplify reserve-backed positioning with European captive mineral assets. Evonik Industries AG represents the synthesis-intensive archetype, occupying a position defined by precipitated silica R&D depth. These three entities anchor the supplier base bifurcation between ISO 9001-certified tier-one vendors and uncertified regional fillers.
| Leading Market Players |
|---|
| Imerys S.A. |
| Evonik Industries AG |
| Omya AG |
| Minerals Technologies Inc. |
| Sibelco Group |
| Ampacet Corporation |
| Clariant AG |
| Avient Corporation |
| W.R. Grace |
| Others |
Value Network & Pricing Analysis
Capacity utilization at European diatomaceous earth milling operations sits above 85 percent, compressing marginal cost curves and anchoring price floors for pharmaceutical-grade mineral portfolios. This scale concentration rewards integrated processors with captive limestone reserves while forcing regional fillers into commodity spot markets with thinner coverage.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate European calcium carbonate supply agreements, insulating processors from energy volatility while passing through calcination costs. Pricing stratifies across pharmaceutical-grade, food-contact, and industrial tiers based on REACH registration status and ISO 9001 certification. Cost compression in standard-grade diatomaceous earth is intensifying as Chinese synthetic silica exports penetrate flexible packaging segments. Agricultural film converters show highest price sensitivity; pharmaceutical blister pack extruders accept premiums for documented migration compliance.
Supply Chain Analysis
Inventory buffers at German masterbatch compounders stretch 6-8 weeks for precipitated silica, reflecting just-in-time coordination with Bavarian pharmaceutical film extruders. Supply concentrates in France, China, and the United States for diatomaceous earth, synthetic silica, and surface-modified precipitated grades respectively. The chain draws from limestone deposits, sodium silicate feedstock, and silane coupling agents. Single-source vulnerability runs through Chinese amorphous silica conversion capacity added to circumvent REACH crystalline silica restrictions. Distribution runs through direct technical service relationships displacing independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified mineral reserves and dense milling networks sit with fewer than eight integrated processors globally, creating acute bottlenecks for pharmaceutical-grade film certification. This asset scarcity rewards early movers in ECHA requalification and liquid dispersion channel development.
For Market Incumbents: Compound certification advantages by accelerating ISO 9001 audit completion for tier-two mineral processors before 18-month queues lengthen. Deepen backward integration into amorphous silica conversion capacity to neutralize REACH Annex XVII crystalline silica restrictions threatening legacy diatomaceous earth portfolios. Prioritize liquid dispersion partnerships with German coating line operators retrofitting dust-free dosing infrastructure. For New Entrants and Emerging Players: Lead with bio-based polymer compatibility testing for PLA and PHA film processors lacking qualified mineral antiblocks. Capture share in China's Yangtze River Delta by pre-certifying against SAMR GB standards before imported formulation suppliers complete domestic protocol alignment. Establish technical partnerships with compostable packaging converters seeking optical clarity maintenance during qualification cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors synthesis-intensive specialty silica houses over reserve-backed integrated miners as surface-engineered particles displace uncoated minerals. Long-term viability hinges on R&D depth in controlled particle size distribution rather than captive quarry access. Target acquisition archetypes include precipitated silica developers with silane coupling expertise. Watch synthetic silica penetration rates in snack packaging haze specifications below 3 percent as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Requalification Acceleration | ECHA enforcement timelines compress supplier windows for pharmaceutical film contracts in Germany and Italy. |
| Liquid Dispersion Channel Development | Dust-free dosing systems bypass powder infrastructure for German coating line operators. |
| Amorphous Silica Conversion Investment | REACH Annex XVII crystalline silica restrictions force reformulation of legacy diatomaceous earth grades. |
| Bio-Based Polymer Compatibility Testing | PLA and PHA film processors lack qualified mineral antiblocks for compostable packaging conversion. |
| China GB Standard Pre-Certification | SAMR protocols create entry barriers for imported formulation suppliers in Yangtze River Delta clusters. |
Research Methodology
Initial hypotheses were tested against primary input from film extrusion plant managers, masterbatch procurement leads, mineral processor technical R&D directors, and pharmaceutical packaging regulatory affairs specialists and refined through secondary validation. Sources included customs and trade flow databases, European Chemicals Agency registration filings, SEC 10-K disclosures from listed additive suppliers, and China SAMR plastic food packaging standard protocols. Bottom-up volume estimates from polymer matrix consumption patterns were triangulated against top-down mineral processor capacity assessments.
Variance decomposition across the projection horizon isolates volume drivers by polymer matrix, application clarity tier, certification grade, and regional regulatory cluster. Segmentation modeling captures polyethylene, polypropylene, polystyrene, and engineering polymer matrices crossed with packaging, coatings, adhesives, and sealant applications. CAGRs were derived from extrusion capacity expansion pipelines and substitution elasticity between mineral and organic antiblock alternatives. Forecast inputs include e-commerce logistics film demand curves and ECHA enforcement intensity scenarios.
The analysis sits within stated boundaries; outcomes outside sustained REACH compliance timelines or synthetic silica R&D diffusion rates would require recalibration. Forecasts reflect assumptions regarding mineral purity threshold evolution and pharmaceutical-grade qualification cycle stability. Energy cost volatility in European limestone calcination and PFAS restriction expansion present revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Chelating Agents Market
Additives
Canada Anti-Caking Market
Additives
Dry-Mix Mortar Additives and Chemicals Market
Additives
High Performing Matting Agents Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Competitive Inhibitors Market
Additives
Tricalcium Citrate Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Global Silica-Based Matting Agents Market
Additives
Grinding Aids Market
Additives
Global Corrosion Inhibitor Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Lactic Acid Ester Market
Additives
Battery Additives Market
Additives
Bromine Derivatives Market
Additives
Inorganic Filler Market