
 Propylene Glycol Market | 2026-2036
Propylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Propylene Glycol Market Intelligence
Ethylene glycol is consolidating its replacement by propylene glycol in coolant and de-icing formulations across automotive and aviation sectors due to lower mammalian toxicity profiles. Dow leverages integrated propylene oxide supply chains to sustain cost leadership in North American industrial grade production. BASF SE anchors European pharmaceutical-grade capacity through backward integration into glycerol-based bio-routes, while Archer Daniels Midland Company competes in food-grade segments via fermentation-derived propylene glycol from corn-derived feedstocks.
Propylene glycol designates a synthetic organic compound with the formula C₃H₈O₂, typically manufactured through hydration of propylene oxide or catalytic conversion of glycerol, yielding a viscous liquid with hygroscopic properties and a freezing point depression capability of approximately -59°C in aqueous solution. USP Grade production commands premium positioning due to stringent monograph compliance for inhalation and parenteral pharmaceutical applications, whereas Industrial Grade occupies volume leadership in polyester resin and unsaturated polyester compound manufacturing. Cosmetic Ingredient demand within the Application dimension is accelerating fastest, driven by clean-label formulation trends that favor propylene glycol over petroleum-derived alternatives in personal care products.
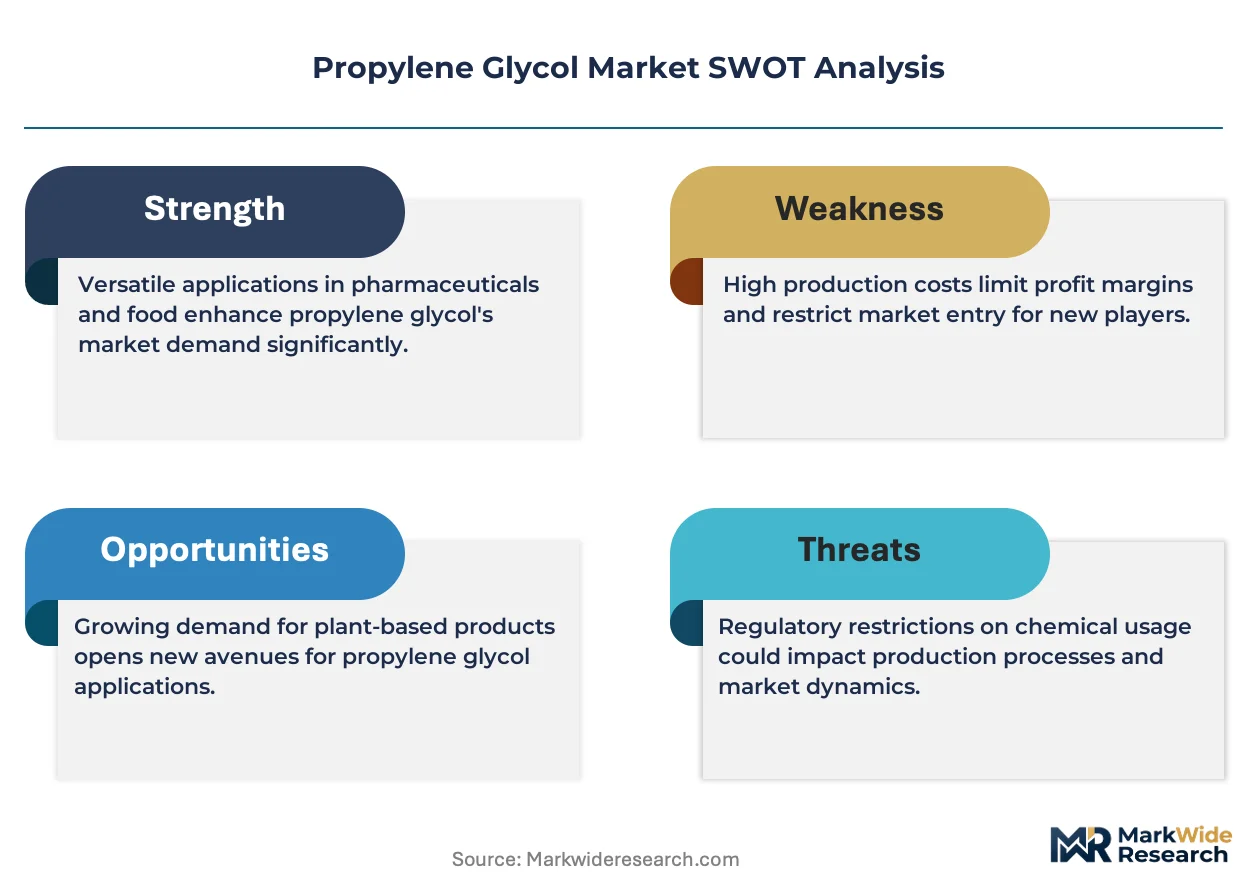
FDA monograph standards govern US pharmaceutical and food additive specifications, while REACH registration requirements and ECHA substance evaluation protocols constrain import and formulation standards across European value chains. The EU Green Deal's chemical sustainability targets are forcing capacity investments toward bio-based propylene glycol derived from renewable glycerol streams rather than fossil propylene oxide. Stakeholders must monitor feedstock cost divergence between petrochemical and agricultural pathways, as this spread will determine regional manufacturing competitiveness and capital allocation priorities for new capacity.
Market Dynamics
EU Green Deal mandates are redirecting capital toward glycerol-based bio-routes, compressing fossil propylene oxide economics while specialty chemical clusters in Germany and Belgium absorb the transition costs through backward integration into agricultural feedstocks.
Growth Catalysts
- REACH registration tiering:ECHA substance evaluation protocols favor pharmaceutical-grade purity standards, pulling capacity investments toward USP monograph compliance in inhalation and parenteral applications.
- Automotive coolant reformulation:NHTSA and FAA toxicity guidelines are accelerating ethylene glycol displacement in de-icing and thermal management fluids across commercial aviation and electric vehicle platforms.
- Clean-label cosmetics:Personal care formulators are substituting petroleum-derived solvents with propylene glycol in skincare humectant applications, responding to consumer ingredient transparency demands.
Market Restraints
- Feedstock cost divergence:Agricultural glycerol price volatility against stable propylene oxide naphtha spreads creates margin compression for bio-route operators during crude oil price troughs.
- Capacity concentration:Industrial-grade supply chains cluster around integrated propylene oxide producers on the US Gulf Coast, limiting spot market liquidity and regional price discovery.
- Substitution by 1,3-propanediol:Bio-based PDO from corn sugar fermentation offers comparable humectant performance in select cosmetic and polymer applications.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO bulk drug park incentives and PLI scheme subsidies create localized USP-grade demand as domestic formulation capacity expands.
- Carbon accounting integration:EU CSRD disclosure requirements and product-level carbon footprinting are creating premium pricing tiers for certified bio-based propylene glycol in European value chains.
- Food-grade fermentation pathways:Corn-derived glycerol-to-propylene glycol catalytic conversion offers non-petroleum routes for FSSAI and FDA-compliant food additive applications.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP monograph compliance for inhalation-grade material requires 18-24 month validation cycles, constraining speed-to-market for new capacity.
- Multi-feedstock process engineering:Switching between propylene oxide hydration and glycerol hydrogenolysis requires catalyst system retrofits and operational retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propylene Glycol Market |
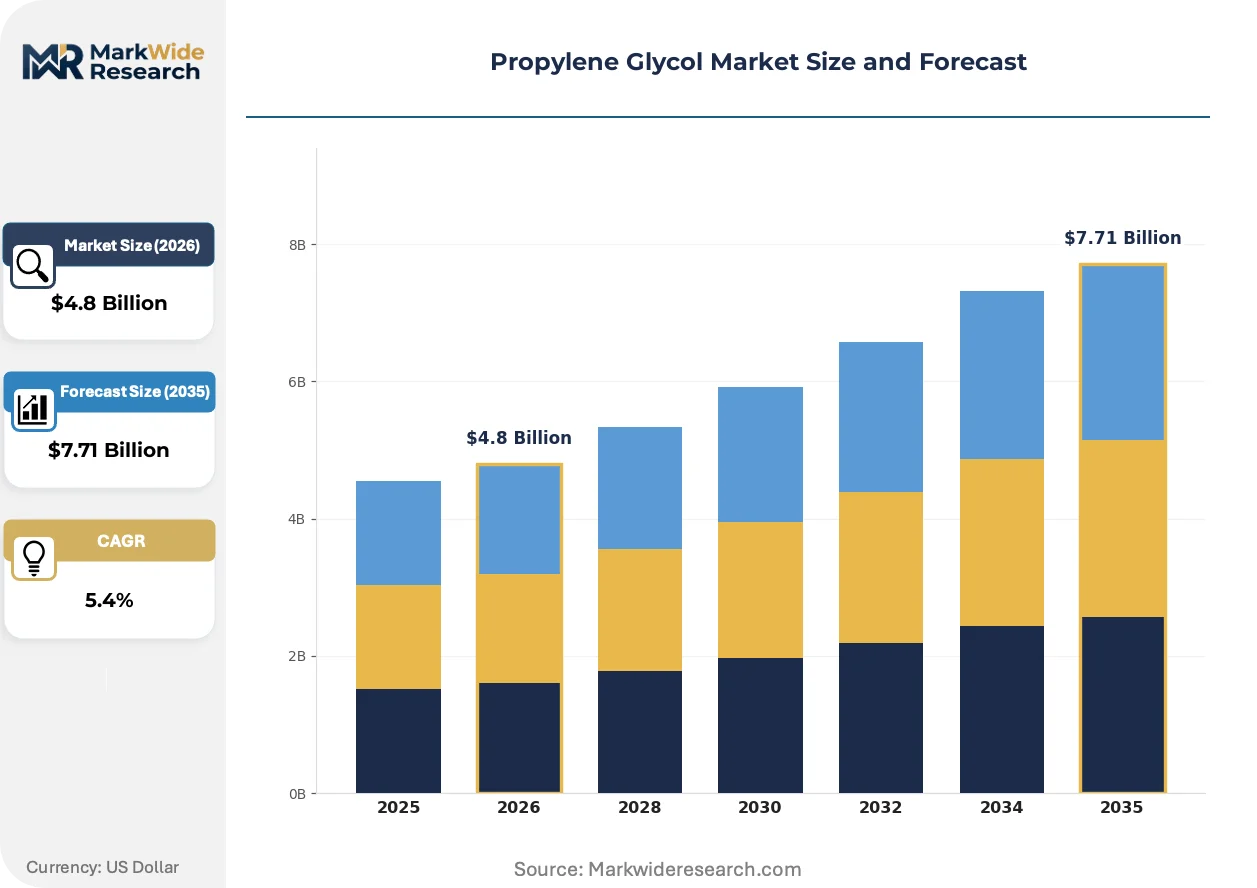
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, USP Grade, Food Grade, Cosmetic Grade Application: Food Additive, Pharmaceutical Solvent, Antifreeze Agent, Cosmetic Ingredient End User: Food & Beverage, Pharmaceuticals, Cosmetics, Automotive Packaging Type: Drums, Totes, Cylinders, Bulk Containers |
| Companies Covered | Dow, LyondellBasell Industries Holdings B.V., BASF SE, INEOS, Archer Daniels Midland Company, Shell plc, Huntsman International LLC, ADEKA Corporation, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propylene Glycol Market Strategic Shifts & Innovations
Continuous processing technology and renewable feedstock catalysis are compressing batch cycle times while regulatory carbon accounting forces transparency through supply chain digitization.
Membrane separation technology is automating pharmaceutical-grade purification, replacing energy-intensive distillation towers. Contract manufacturers serving inhalation drug delivery platforms are adopting these systems fastest. The capital efficiency gain is automating capacity expansion decisions away from greenfield builds toward modular retrofits.
REACH authorization sunset dates for fossil-derived intermediates are tightening substance evaluation protocols across European value chains. ECHA's 2024-2027 work program prioritizes glycol ether alternatives assessment. Formulators in Germany and the Netherlands are accelerating bio-route qualification to preempt supply disruption.
Ingredient disclosure mandates are fragmenting procurement specifications across personal care brands. Sephora and Ulta clean beauty standards now require propylene glycol origin certification. This specification proliferation is most visible in North American and Western European cosmetic contract manufacturing.
Propylene Glycol Market Segmentation
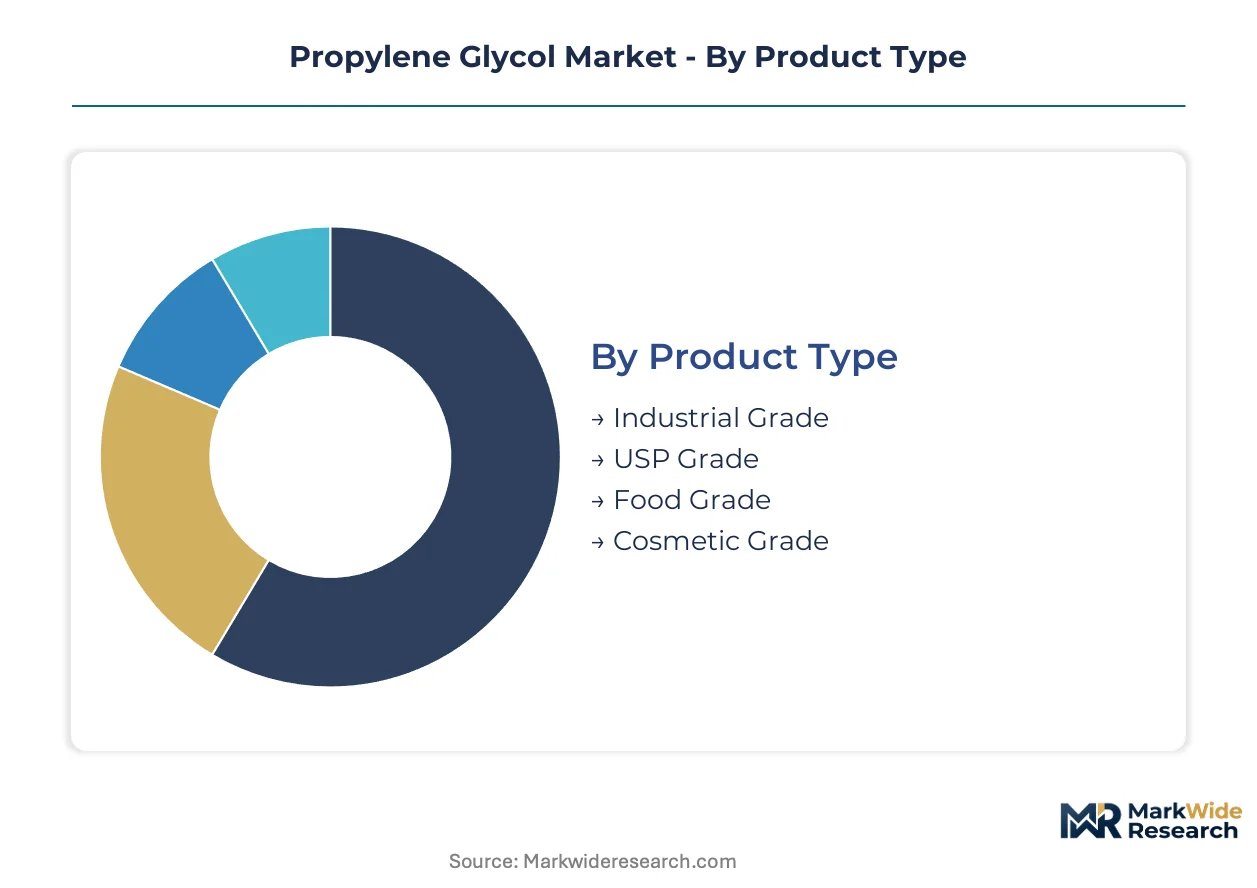
Propylene glycol procurement specifications diverge sharply across end-use industries, with pharmaceutical and food additive buyers demanding certified purity while industrial operators prioritize volume economics. Understanding these tiered requirements exposes where margin compression and premium pricing opportunities concentrate.
Product Type:
Buyers select grade tiers based on regulatory exposure and liability thresholds rather than functional performance alone.
- Industrial Grade:Technical specifications center on 99.5% minimum purity with controlled moisture content for polyester resin synthesis. Demand clusters around US Gulf Coast petrochemical corridors where propylene oxide feedstock integration sustains cost leadership in unsaturated polyester compound manufacturing.
- USP Grade:Monograph compliance for inhalation and parenteral applications mandates sub-ppm impurity thresholds validated through 18-24 month pharmacopeial certification cycles. German pharmaceutical clusters around Ludwigshafen and Leverkusen anchor European capacity due to backward integration into glycerol-based bio-routes meeting EMA purity protocols.
- Food Grade:FDA and FSSAI additive specifications govern direct food contact applications including flavor carriers and moisture retention agents.
- Cosmetic Grade:Sephora and Ulta clean beauty certification requirements now mandate origin disclosure for humectant applications in skincare formulations.
Volume sits with Industrial Grade; growth tilts toward USP Grade.
Application:
Functional performance requirements and regulatory scrutiny intensity determine substitution economics and supplier stickiness.
- Pharmaceutical Solvent:Parenteral and inhalation drug delivery platforms demand validated supply chains with documented batch genealogy. CDSCO bulk drug park incentives in India are localizing USP-grade demand as domestic formulation capacity expands.
- Cosmetic Ingredient:Clean-label formulation trends favor propylene glycol over petroleum-derived alternatives in humectant and solvent applications. EU Green Deal chemical sustainability targets accelerate bio-route qualification among German and Dutch contract manufacturers.
- Food Additive:Moisture retention and flavor carrier functions in processed foods face FSSAI and FDA compliance verification.
- Antifreeze Agent:NHTSA and FAA toxicity guidelines accelerate ethylene glycol displacement in automotive and aviation thermal management fluids.
Revenue concentrates in Pharmaceutical Solvent; Cosmetic Ingredient climbs the fastest.
End User:
Procurement scale and specification fragmentation create divergent supplier strategies across buyer categories.
- Pharmaceuticals:Inhalation and injectable drug manufacturers enforce vendor qualification protocols with 24-36 month approval timelines. EMA and FDA dual-track submissions compress supplier switching flexibility.
- Automotive:Electric vehicle thermal management system OEMs specify low-toxicity coolant formulations displacing ethylene glycol in battery pack cooling circuits.
- Food & Beverage:Processed food manufacturers prioritize cost-stable supply contracts for additive-grade material in flavor systems.
- Cosmetics:Clean beauty brand procurement teams now require carbon footprint documentation and renewable feedstock certification.
Scale advantages flow to Pharmaceuticals; specification intensity peaks in Cosmetics.
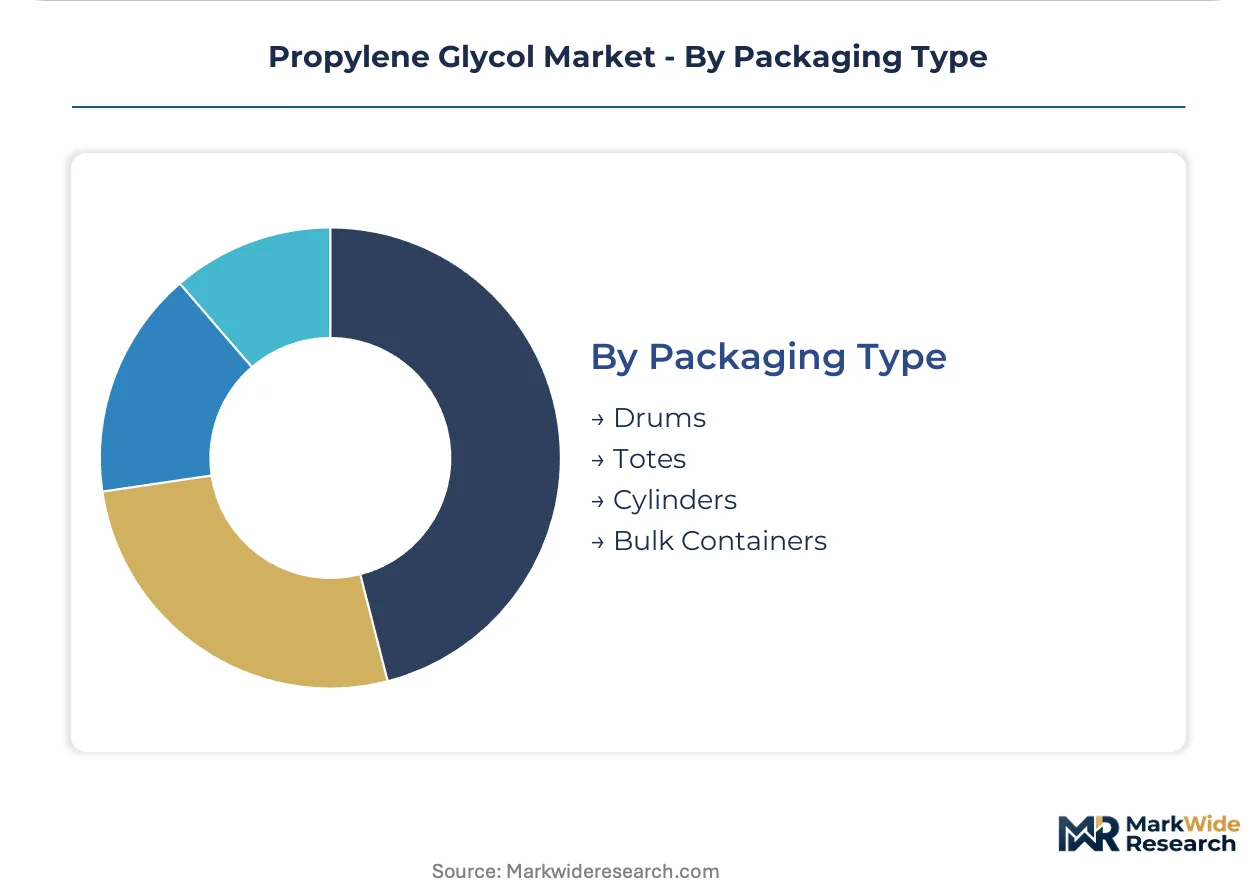
Packaging Type:
Logistics economics and contamination risk thresholds shape container selection across supply chain tiers.
- Bulk Containers:Integrated propylene oxide producers on the US Gulf Coast deploy railcar and tanker shipments to polyester resin manufacturers, capturing freight cost efficiencies at 20,000+ gallon volumes.
- Drums:55-gallon steel and polyethylene drums serve pharmaceutical and food-grade distributors requiring lot segregation and chain-of-custody documentation.
- Totes:Intermediate bulk containers balance handling efficiency with contamination control for mid-volume cosmetic and specialty chemical formulators.
- Cylinders:Compressed gas-style packaging serves laboratory and R&D applications with ultra-high purity requirements.
Shipment value concentrates in Bulk Containers; traceability requirements favor Drums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical parks in Ludwigshafen and Leverkusen concentrate European pharmaceutical-grade capacity through integrated glycerol-based production corridors. Tax incentives under Germany's Chemical Industry Transformation program accelerate bio-route capital deployment. These zones anchor regional supply security as REACH authorization timelines tighten.
United States
Propylene oxide integration on the Gulf Coast sustains industrial-grade cost leadership for polyester resin manufacturers. NHTSA coolant toxicity guidelines accelerate ethylene glycol displacement in electric vehicle thermal management systems. Houston-Baytown petrochemical corridors capture freight efficiencies through 20,000+ gallon bulk shipments to automotive OEMs.
Germany
Pharmaceutical solvent demand clusters around EMA-regulated inhalation drug delivery platforms requiring USP monograph compliance. EU Green Deal chemical sustainability targets compress fossil propylene oxide economics while favoring glycerol hydrogenolysis pathways. BASF SE anchors backward integration into agricultural feedstocks through Ludwigshafen specialty chemical infrastructure.
India
CDSCO bulk drug park incentives and PLI scheme subsidies localize USP-grade demand as domestic formulation capacity expands. FSSAI food additive specifications govern direct contact applications in processed flavor systems. Gujarat and Maharashtra pharmaceutical clusters absorb capital investments targeting inhalation-grade material for export markets.
China
Propylene oxide hydration capacity serves domestic unsaturated polyester compound manufacturing for construction and automotive sectors. MIIT industrial standards govern technical grade specifications while NMPA pharmaceutical protocols constrain import competition. Yangtze River Delta chemical parks concentrate glycerol-to-propylene glycol catalytic conversion investments.
Japan
Cosmetic ingredient procurement enforces METI chemical substance reporting for humectant applications in skincare formulations. PMDA pharmaceutical-grade standards align with USP and EP monograph requirements for parenteral drug delivery. Kanto region contract manufacturers qualify bio-based propylene glycol for clean beauty export specifications.
Propylene Glycol Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical producers dominating industrial-grade volume and fermentation-based operators capturing food-grade premiums. Market structure tilts toward consolidation at the upstream propylene oxide level while downstream formulation remains fragmented across pharmaceutical, cosmetic, and food additive channels. Three archetypes define competitive positioning: integrated petrochemical majors with captive feedstock access, agricultural processors leveraging corn-derived glycerol streams, and regional distributors serving spot-market industrial buyers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, particularly around bio-route technology licensing and pharmaceutical-grade certification pipelines.
Among North American integrated producers, Dow and Huntsman International LLC exemplify petrochemical archetypes with Gulf Coast propylene oxide integration. Archer Daniels Midland Company represents agricultural pathway specialists converting corn-derived feedstocks through fermentation-derived glycerol intermediates. These three anchors demonstrate how feedstock origin—fossil versus renewable—determines regional manufacturing competitiveness and capital allocation priorities for new capacity.
| Leading Market Players |
|---|
| Dow |
| LyondellBasell Industries Holdings B.V. |
| BASF SE |
| INEOS |
| Archer Daniels Midland Company |
| Shell plc |
| Huntsman International LLC |
| ADEKA Corporation |
| Cargill, Incorporated |
| Others |
Cost & Logistics Intelligence
Integrated petrochemical majors with captive Gulf Coast propylene oxide access exercise pricing discipline through long-term offtake contracts, while agricultural processors converting corn-derived glycerol compete on carbon-accounting premiums rather than unit economics alone. This bifurcation concentrates margin capture upstream with fossil-route operators during crude price troughs, yet rewards bio-route specialists when EU CSRD disclosure requirements activate premium tiers.
Pricing Analysis
Short lead-time premiums for USP-grade material with validated pharmacopeial certification command substantial markups over spot industrial-grade inventory held in Houston-Baytown storage terminals. Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels reflects impurity threshold differentiation and batch documentation depth. Pricing pressure stems from agricultural glycerol feedstock volatility compressing bio-route margins when naphtha spreads tighten. Industrial polyester resin manufacturers exhibit highest price sensitivity due to volume procurement scale and substitution elasticity, whereas inhalation drug delivery platforms accept premium positioning for validated supply security.
Supply Chain Analysis
Pharmacopeial certification gating through 18-24 month USP and EP monograph validation cycles constrains supplier qualification velocity and locks downstream formulators into approved vendor lists. Production concentrates in the United States, Germany, and China, with each hub serving distinct grade-tier demand pools. Raw material flows draw from propylene oxide hydration feedstocks and glycerol hydrogenolysis pathways, with catalyst systems and membrane separation equipment constituting critical production inputs. Single-source vulnerability concentrates around integrated propylene oxide producers on the US Gulf Coast, where capacity clustering limits spot market liquidity. Distribution runs through railcar and tanker shipments for bulk industrial volumes, while pharmaceutical and food-grade material moves via drum and tote configurations with chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The propylene glycol sector sits in a feedstock-transition phase as glycerol-based bio-routes displace fossil propylene oxide pathways under EU Green Deal chemical sustainability mandates. Membrane separation automation and continuous processing technology are compressing batch cycle times while reshaping capital allocation toward modular retrofits rather than greenfield builds.
For Market Incumbents: Anticipate margin compression in industrial-grade segments by accelerating backward integration into agricultural feedstock corridors and securing pharmacopeial certification pipelines for inhalation-grade capacity. Dow and BASF SE demonstrate how captive propylene oxide access combined with glycerol-based bio-route optionality defends positioning against pure-play fermentation entrants. Prioritize carbon accounting integration to capture EU CSRD-driven premium tiers before certification saturation erodes differentiation.
For New Entrants and Emerging Players: Capture localized USP-grade demand growth in Indian pharmaceutical manufacturing clusters where CDSCO bulk drug park incentives and PLI scheme subsidies reduce incumbent cost advantages. Contract manufacturing for clean beauty brands represents the most penetrable white-space target, given Sephora and Ulta origin-disclosure mandates fragmenting procurement specifications. Lead with fermentation-derived carbon footprint certification as the go-to-market angle, bypassing fossil-route incumbents on sustainability credentials rather than unit cost.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap bio-route specialists with qualified glycerol hydrogenolysis capacity in European chemical parks, where EU Green Deal transition costs have compressed valuations without impairing long-term demand visibility. Over a five-to-ten-year window, feedstock cost convergence between agricultural and petrochemical pathways will determine regional manufacturing competitiveness and capital allocation priorities. Watch for ECHA substance evaluation protocol acceleration on glycol ether alternatives as the signal indicating bio-route demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycerol Feedstocks | BASF SE anchors European pharmaceutical-grade capacity through agricultural supply chain control. |
| Pharmacopeial Certification Pipeline Investment | 18-24 month USP monograph validation cycles lock downstream formulators into approved supplier relationships. |
| Membrane Separation Technology Deployment | Contract manufacturers serving inhalation drug delivery platforms automate purification to compress batch cycle times. |
| Carbon Accounting Integration | EU CSRD disclosure requirements create premium pricing tiers for certified bio-based propylene glycol. |
| Long-term Supply Agreement with Automotive OEMs | NHTSA toxicity guidelines accelerate ethylene glycol displacement in electric vehicle thermal management systems. |
Research Approach
Multi-period observation of propylene oxide-glycerol feedstock spreads, REACH authorization timelines, and CDSCO regulatory filings anchored the trend analysis, supplemented by interviews with plant managers at integrated petrochemical facilities, procurement leads at downstream pharmaceutical formulators, distribution channel partners serving cosmetic contract manufacturers, and technical R&D directors developing catalytic conversion pathways. Secondary validation drew from customs and trade data, SEC 10-K filings, ECHA substance evaluation protocols, and Cefic industry reports. Bottom-up capacity modeling and top-down demand segmentation were triangulated to cross-verify volume and value outputs.
Segment-weighting across grade tier, end-use industry, packaging format, and regional production hub dimensions structured the analytical framework. CAGRs were derived through exponential smoothing of historical consumption patterns projected across the analysis window, with pharmaceutical solvent and cosmetic ingredient segments receiving distinct growth coefficients reflecting clean-label formulation trends and inhalation drug delivery platform expansion. Industry-specific forecast inputs included propylene oxide capacity utilization rates and glycerol hydrogenolysis yield improvements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude oil price volatility, agricultural commodity cycles, and ECHA authorization sunset date acceleration. The modeling reflects documented assumptions regarding feedstock cost convergence and regulatory pathway timelines. A model refresh is warranted upon material change in EU Green Deal implementation speed or CDSCO bulk drug park incentive structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Ink Solvents Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Hydrosol Market
Solvents
Piperylene Market
Solvents
Reactive Diluents Market
Solvents
Mesitylene Market
Solvents
Global Chloroform Market
Solvents
Butyl Glycol Market
Solvents
Mixed Xylene Market
Solvents
Industrial Solvents Market
Solvents
North America Acetonitrile Market
Solvents
Hexylene Glycol Market
Solvents
Dimethyl Formamide Market
Solvents
Citrus Solvents Market
Solvents
Epoxy Thinner Market
Solvents
Pharmaceutical Solvent Market