
 Metallic Stearate Market | 2026-2036
Metallic Stearate Market Size, Share, and Industry Trends Forecast 2026-2036
Metallic Stearate Market Analysis
Buyer concentration across the plastics compounding sector is broadening as mid-sized PVC pipe and profile manufacturers in India, Vietnam, and Turkey expand direct procurement of metallic stearate blends. Baerlocher GmbH leverages its backward integration into fatty acid feedstocks to secure margin stability across European and Asian plants. Peter Greven GmbH & Co. KG anchors its position through specialized magnesium stearate grades that serve pharmaceutical tablet compression. Valtris Specialty Chemicals dominates North American supply through integrated manufacturing sites and long-term tolling agreements with polymer compounders.
Metallic stearates are salts formed from stearic acid and metal cations, typically produced via direct fusion or precipitation processes yielding particle sizes between 5 and 50 microns for lubricant and release applications. These compounds function primarily as internal and external lubricants in polymer processing, acid scavengers in polyolefins, and flow agents in pharmaceutical tablet manufacturing. Zinc stearate leads in volume across plastics applications where PVC thermal stabilization consumes the largest share, while magnesium stearate commands premium positioning in pharmaceutical excipient grades subject to stringent pharmacopeial standards. Calcium stearate maintains steady demand in food-grade packaging films where FDA compliance and low odor specifications determine supplier qualification.
REACH registration requirements administered by ECHA govern metallic stearate imports into Europe, while FDA food-contact notifications and USP-NF monographs shape product specifications for pharmaceutical and food additive applications in the United States. BIS certification under Indian standards increasingly determines market access for imported calcium and zinc stearate grades sold to domestic PVC processors and lubricant blenders. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards to anticipate reformulation costs and qualification timelines for multinational pharmaceutical supply contracts.
Market Dynamics
Polymer processors across Southeast Asia and India are absorbing metallic stearate volumes at rates that outpace local production capacity, forcing supply chain reconfiguration toward integrated fatty acid-to-stearate manufacturing hubs.
Growth Catalysts
- REACH registration thresholds:ECHA's tightened purity specifications for imported metallic stearates are accelerating qualification of high-grade calcium and zinc variants for European PVC compounding.
- Pharmaceutical tablet compression:Magnesium stearate demand from Indian and Chinese generic drug manufacturers is climbing as excipient localization policies reduce import dependency.
- Food-contact film specifications:FDA notification requirements for calcium stearate in packaging are driving specification upgrades among US-based blown film processors.
Market Restraints
- Palm and tallow fatty acid volatility:Feedstock price swings in Malaysian and Indonesian oleochemical markets compress margin predictability for precipitation-process stearate grades.
- European import concentration:REACH-registered supply channels for metallic stearates remain dominated by German and Benelux producers, limiting buyer negotiation leverage.
- Technical substitution pressure:Synthetic wax lubricants and polymer-modified release agents are displacing zinc stearate in select high-temperature PVC extrusion applications.
Strategic Opportunities
- Indian domestic capacity expansion:BIS certification requirements and PLI scheme incentives for specialty chemicals are creating opening for localized magnesium and calcium stearate production.
- Biopolymer processing compatibility:Metallic stearate formulations adapted for PLA and PHA thermal stabilization represent unaddressed white space as compostable packaging scales.
- Direct procurement platforms:Digital marketplaces connecting Indian and Vietnamese PVC pipe manufacturers with stearate producers are compressing distributor margins and enabling volume-based pricing.
Industry Challenges
- Pharmacopeial harmonization complexity:Divergent USP, EP, and IP monograph requirements for magnesium stearate particle size and moisture content extend qualification timelines for multinational pharmaceutical contracts.
- Capex intensity for precipitation-grade assets:Continuous-flow reactor systems producing sub-10-micron pharmaceutical-grade stearates require capital deployment that mid-scale Indian producers struggle to access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallic Stearate Market |
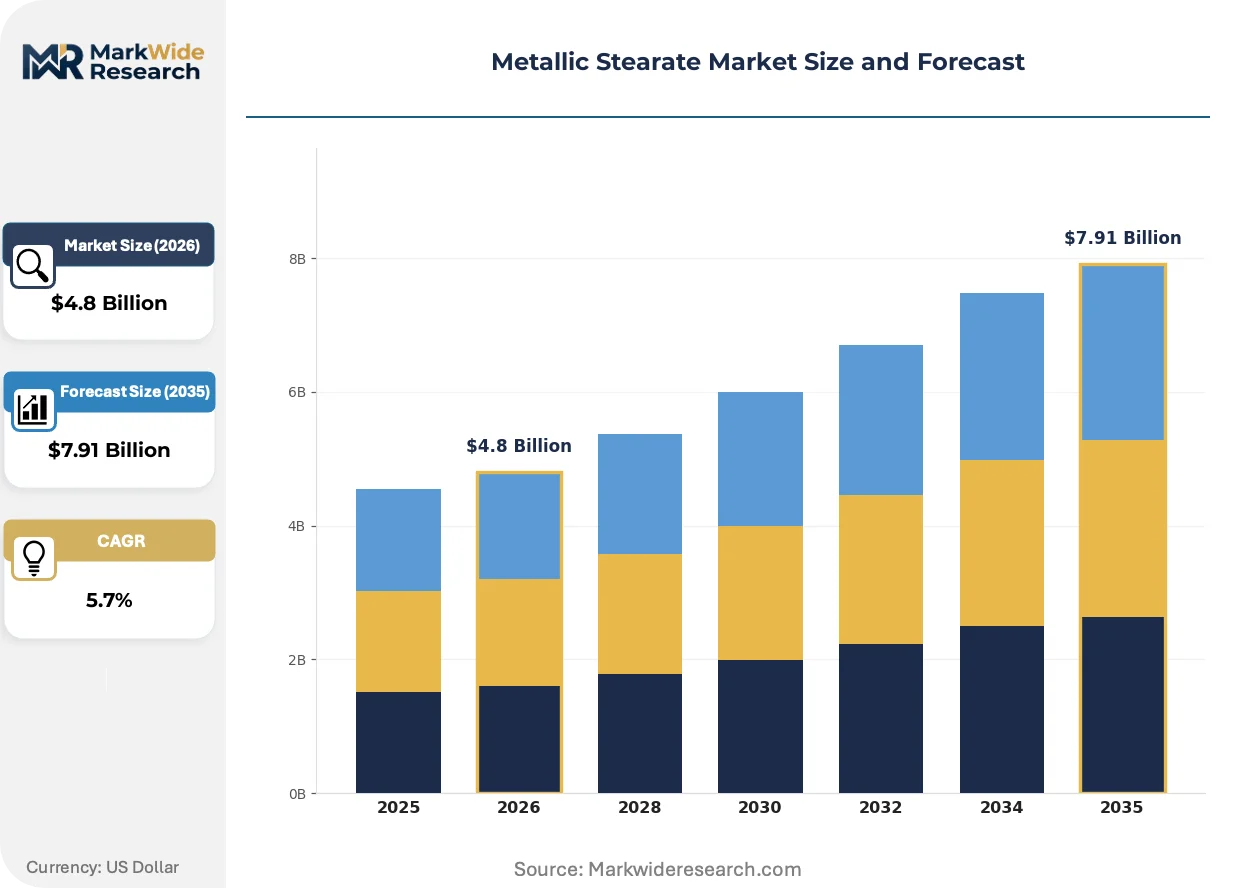
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnesium Stearate, Calcium Stearate, Zinc Stearate, Aluminium Stearate Application: Pharmaceuticals, Plastics, Cosmetics, Food Additives End User: Healthcare, Food Industry, Personal Care, Industrial Manufacturing Distribution Channel: Direct Sales, Distributors, E-Commerce, Retail |
| Companies Covered | Baerlocher GmbH, Dover Chemical Corporation, Faci S.p.A, Peter Greven GmbH & Co. KG, Valtris Specialty Chemicals, PMC Group Inc., Sun Ace Kakoh Pte Ltd, Norac Additives LLC, Nimbasia Stabilizers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallic Stearate Market Emerging Trajectories
Metallic stearate production is pivoting toward integrated manufacturing models that capture fatty acid feedstock security, while regulatory divergence between pharmacopeial standards and food-contact frameworks is fragmenting product grade specifications.
Continuous-flow precipitation technology is consolidating control over pharmaceutical-grade magnesium stearate particle size distribution. Indian and Chinese generic drug manufacturers are adopting these systems to meet USP-NF and EP monograph tolerances. The technology is consolidating supply positions among producers capable of sub-5-micron consistency, compressing margins for batch-process competitors.
REACH authorization requirements administered by ECHA are tightening impurity thresholds for metallic stearates used in food-contact and medical applications. Downstream PVC processors in Germany and France now face documentation burdens that favor pre-registered supply relationships over spot-market sourcing. Pharmaceutical compounders are responding by locking multi-year tolling agreements with REACH-compliant European producers.
Buyer concentration among mid-sized PVC pipe and profile manufacturers in Vietnam, Turkey, and India is compressing traditional distributor networks. These processors now procure blended calcium-zinc stabilizer packages directly from stearate producers, bypassing regional chemical distributors. The shift is most visible in Indian states Gujarat and Maharashtra, where domestic lubricant blenders have established direct supply corridors with polymer compounders.
Metallic Stearate Market Segmentation
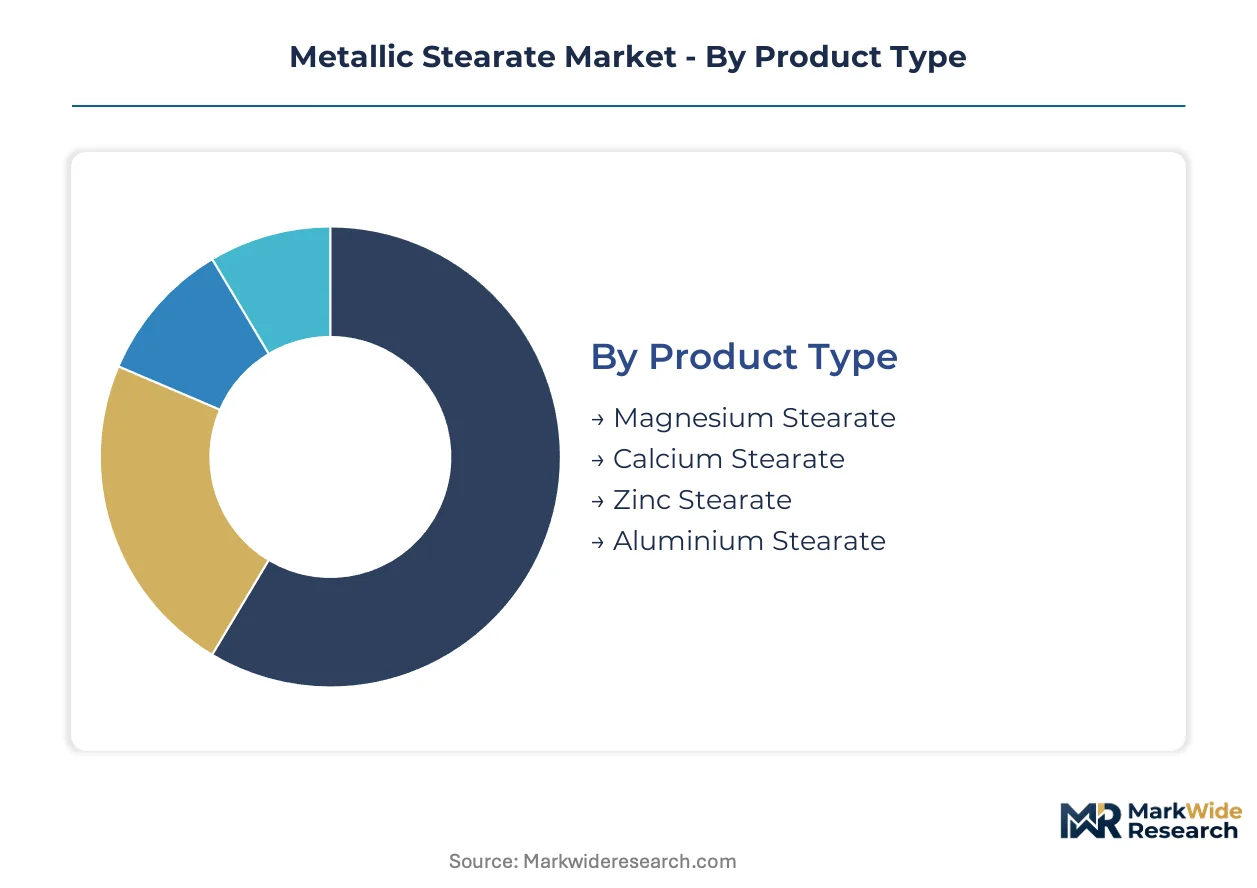
Metallic stearate specifications fragment sharply across pharmaceutical, polymer, and food-contact applications, with purity thresholds and particle size requirements determining supplier qualification. Segmentation by metal cation and end-use vertical reveals divergent margin structures and capital intensity requirements that reshape competitive positioning.
Product Type:
Integration depth varies substantially across metal stearate chemistries, with pharmaceutical-grade magnesium variants requiring standalone precipitation systems while calcium and zinc grades embed more readily into integrated fatty acid operations.
- Magnesium Stearate:Precipitation-processed salts with sub-10-micron particle size distribution serve pharmaceutical tablet compression as lubricants and flow agents. Demand concentrates in Indian generic drug manufacturing where CDSCO and USP-NF compliance requirements drive localization investments.
- Calcium Stearate:Fusion-processed grades with low odor specifications stabilize PVC thermal processing and food-contact films. FDA notification requirements for packaging applications in the United States are tightening impurity thresholds, compressing spot-market supply options.
- Zinc Stearate:Functions as acid scavenger in polyolefins and release agent in rubber molding.
- Aluminium Stearate:Niche applications in paint driers and waterproofing compounds with limited volume scale.
Volume placements concentrate in calcium stearate; the faster expansion belongs to magnesium stearate.
Application:
Cost tier stratification separates pharmaceutical excipient grades commanding premium pricing from commodity polymer lubricant applications with thinner margins.
- Pharmaceuticals:Magnesium stearate serves as essential excipient in tablet and capsule manufacturing, with pharmacopeial harmonization between USP, EP, and IP standards fragmenting specification requirements. Indian and Chinese generic producers are absorbing volumes as excipient localization policies reduce import dependency.
- Plastics:PVC thermal stabilization consumes the largest metallic stearate volumes across calcium-zinc stabilizer systems. Southeast Asian pipe and profile manufacturers in Vietnam and Indonesia are expanding direct procurement, bypassing traditional distributor networks.
- Cosmetics:Zinc and magnesium stearates function as emulsifiers and texture modifiers in color cosmetics.
- Food Additives:Calcium stearate serves as anticaking agent and emulsifier subject to FDA and EFSA purity specifications.
Revenue concentration sits with pharmaceuticals; plastics applications deliver the steepest volume expansion trajectory.
End User:
Customer type segmentation separates multinational pharmaceutical compounders with multi-year tolling agreements from fragmented industrial manufacturers purchasing on spot markets.
- Healthcare:Pharmaceutical manufacturers and contract development organizations drive magnesium stearate demand with stringent particle size and moisture content specifications. REACH-registered European supply relationships dominate procurement for firms serving EMA-regulated markets.
- Food Industry:Packaging film processors and food additive blenders require calcium stearate grades meeting FDA food-contact notifications and evolving purity thresholds.
- Personal Care:Cosmetic formulators source zinc and magnesium stearates for emulsion stability.
- Industrial Manufacturing:PVC compounders and rubber processors absorb commodity-grade calcium and zinc stearates.
Contract security concentrates in healthcare; industrial manufacturing delivers the fastest volume growth.
Distribution Channel:
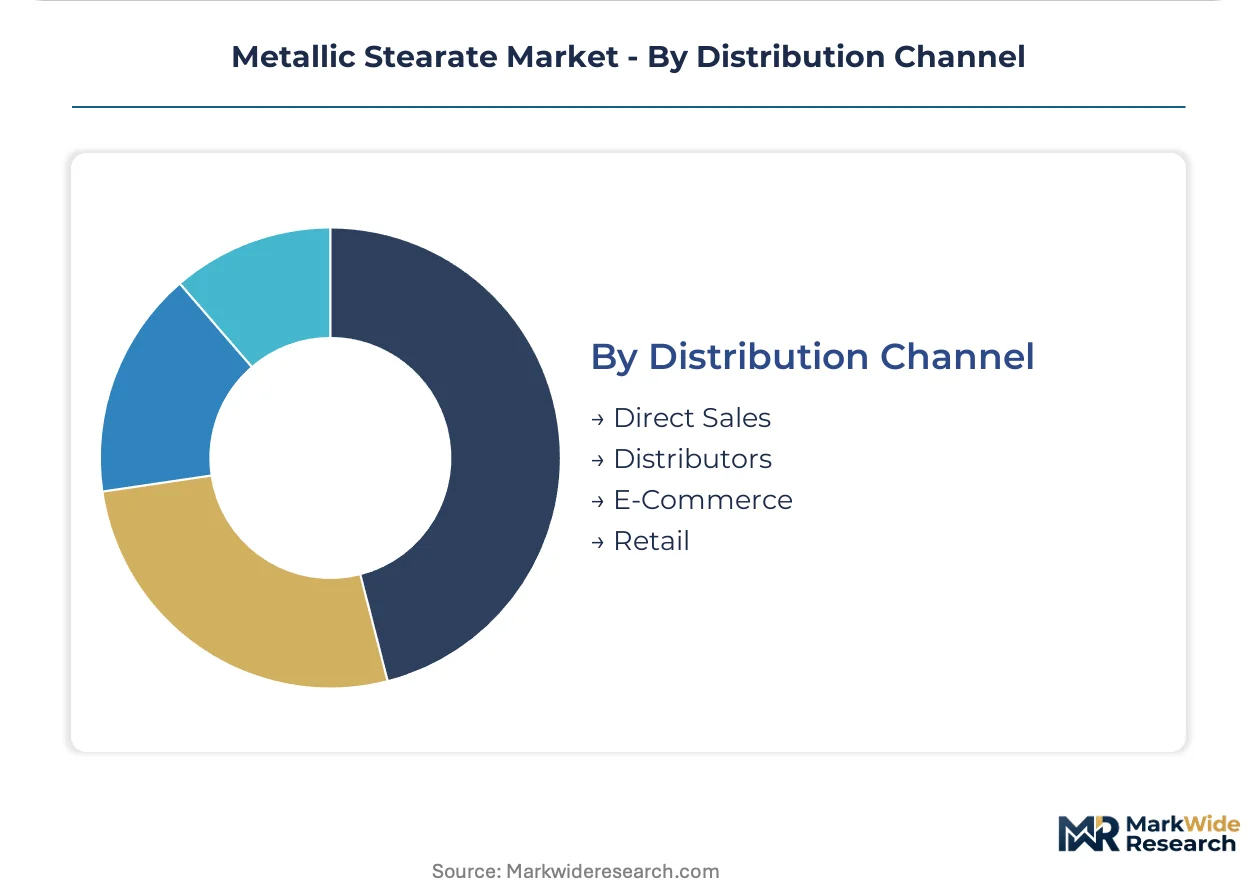
Supply concentration patterns favor direct sales relationships where technical qualification requirements and volume scale justify bypassing intermediaries.
- Direct Sales:Large-volume PVC compounders and pharmaceutical manufacturers procure metallic stearates through long-term supply agreements with integrated producers. Indian states Gujarat and Maharashtra have established direct supply corridors between domestic lubricant blenders and polymer processors.
- Distributors:Regional chemical distributors serve mid-sized processors with lower volume requirements and fragmented geographic footprints.
- E-Commerce:Digital marketplaces are emerging in India and Vietnam connecting PVC pipe manufacturers with producers, compressing distributor margins.
- Retail:Limited to small-scale cosmetic and food additive purchasers.
Channel leverage concentrates in direct sales; e-commerce platforms are gaining share fastest among mid-sized processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian and Indonesian palm oil plantations supply the fatty acid feedstocks that anchor metallic stearate production economics across Asia-Pacific and European manufacturing networks. Oleochemical processing clusters in Johor and Sumatra convert crude palm and tallow derivatives into stearic acid precursors. Regional demand patterns diverge sharply between REACH-governed European pharmaceutical markets and BIS-regulated Indian industrial expansion.
United States
FDA food-contact notifications for calcium stearate in packaging films are tightening impurity thresholds among blown film processors in the Midwest. The agency's evolving enforcement posture favors pre-qualified supply relationships over spot-market sourcing. Polymer compounders in Ohio and Illinois now lock multi-year tolling agreements with domestic producers to secure compliance documentation.
Germany
ECHA's REACH authorization requirements administer stringent purity specifications for metallic stearate imports serving PVC compounding and pharmaceutical applications. The regulator's documentation burdens favor established supply channels from Benelux producers over new market entrants. Industrial clusters in North Rhine-Westphalia host integrated fatty acid-to-stearate manufacturing hubs that capture backward integration advantages.
India
BIS certification under Indian standards increasingly determines market access for imported calcium and zinc stearate grades sold to domestic PVC processors. The PLI scheme for specialty chemicals creates fiscal incentives for localized magnesium and calcium stearate production. Gujarat and Maharashtra have established direct supply corridors between domestic lubricant blenders and polymer compounders, bypassing traditional distributor networks.
China
NMPA and evolving GB standards shape magnesium stearate specifications for pharmaceutical excipient exports to regulated markets. Generic drug manufacturers in Jiangsu and Zhejiang provinces are absorbing precipitation-processed volumes as excipient localization policies reduce import dependency. Continuous-flow reactor systems producing sub-5-micron grades are consolidating supply positions among domestic producers.
Vietnam
Mid-sized PVC pipe and profile manufacturers in Ho Chi Minh City and Binh Duong province are expanding direct procurement of calcium-zinc stabilizer packages. Digital marketplaces connecting these processors with regional stearate producers are compressing distributor margins and enabling volume-based pricing. The shift reflects broader Southeast Asian supply chain reconfiguration toward integrated manufacturing hubs.
Metallic Stearate Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade specialization and biopolymer-compatible formulations. The vendor base separates into three functional tiers: integrated oleochemical operators with captive fatty acid supply, precipitation-process specialists serving pharmacopeial markets, and regional compounders blending standard grades for industrial applications. Dominant competitive moves include backward integration into Malaysian and Indonesian feedstock networks, plus capacity expansion in Indian states offering PLI scheme incentives.
Among European-integrated operators, Baerlocher GmbH and Peter Greven GmbH & Co. KG exemplify divergent strategic archetypes. Baerlocher represents the backward-integrated model with control over fatty acid feedstocks, while Peter Greven occupies the pharmaceutical-specialist position. Valtris Specialty Chemicals anchors North American supply through integrated manufacturing presence. These three entities collectively illustrate how geographic footprint and integration depth determine margin stability across regulatory jurisdictions.
| Leading Market Players |
|---|
| Baerlocher GmbH |
| Dover Chemical Corporation |
| Faci S.p.A |
| Peter Greven GmbH & Co. KG |
| Valtris Specialty Chemicals |
| PMC Group Inc. |
| Sun Ace Kakoh Pte Ltd |
| Norac Additives LLC |
| Nimbasia Stabilizers |
| Others |
Supply Flow & Price Mechanics
Malaysian palm oil futures and Indonesian tallow price indices cascade through metallic stearate supply chains, compressing margins for precipitation-process grades while fusion-process calcium variants retain cost buffers through integrated fatty acid operations.
Pricing Analysis
Technical qualification documentation and REACH registration certificates bundle into premium pharmaceutical-grade magnesium stearate pricing, while commodity polymer lubricant grades trade unbundled on spot markets. Three-tier pricing structure across pharmacopeial-certified, food-contact-compliant, and industrial-standard levels separates buyers by compliance burden rather than volume scale. Pricing pressure stems from synthetic wax substitution in high-temperature PVC extrusion, forcing zinc stearate producers to absorb feedstock volatility. Mid-sized Indian and Vietnamese pipe manufacturers exhibit highest price sensitivity, locking annual contracts to hedge palm fatty acid swings.
Supply Chain Analysis
Skilled chemical process engineers concentrate in German North Rhine-Westphalia and Gujarat's specialty chemicals corridor, anchoring precipitation-grade capacity for pharmaceutical applications. Supply concentrates in Germany, India, and Malaysia, with Johor and Sumatra oleochemical clusters feeding stearic acid precursors to European and Asian conversion plants. Raw material dependencies rest on Malaysian palm oil derivatives, Indonesian tallow fractions, and Indian calcium feedstocks. Single-source vulnerability runs through REACH-registered import channels into Europe, where ECHA documentation burdens favor incumbent Benelux-German supply relationships. Distribution runs through direct sales agreements for large-volume PVC compounders, with digital marketplaces emerging for mid-tier Southeast Asian processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metallic stearate supply consolidation accelerates as REACH registration costs and pharmacopeial qualification timelines force sub-scale batch processors toward exit, leaving integrated oleochemical operators and continuous-flow specialists to capture margin recovery.
For Market Incumbents: Deploy backward integration into Malaysian and Indonesian fatty acid networks to secure feedstock cost predictability against palm oil volatility. Lock multi-year tolling agreements with Indian and Southeast Asian PVC compounders before digital procurement platforms commoditize distributor relationships. Counter synthetic wax substitution threat by co-developing biopolymer-compatible stabilizer formulations with PLA and PHA processors seeking thermal stabilization solutions. For New Entrants and Emerging Players: The gap between USP-NF-certified pharmaceutical-grade premiums and industrial-economy zinc stearate spot pricing creates entry space for mid-tier precipitation specialists. Capture BIS-certified calcium stearate demand from Gujarat and Maharashtra lubricant blenders scaling domestic PVC stabilization capacity. Lead with continuous-flow reactor technology producing sub-10-micron magnesium stearate to shortcut qualification timelines for Indian generic drug manufacturers reducing import dependency. For Investors and Strategic Acquirers: Distressed-cycle entries favor batch-process pharmaceutical-grade producers in India and China facing capex pressure to upgrade continuous-flow systems. Long-term viability centers on regulatory compliance infrastructure rather than commodity volume scale, positioning REACH-registered European assets and CDSCO-compliant Indian facilities for sustained margin capture. Watch pharmacopeial harmonization progress between USP, EP, and IP monograph standards as the signal for reformulation cost spikes that reshape multinational pharmaceutical supply contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Acid Feedstocks | Captures margin stability across Malaysian and Indonesian oleochemical supply networks. |
| Continuous-Flow Reactor Deployment | Consolidates pharmaceutical-grade magnesium stearate positions through sub-5-micron particle consistency. |
| Biopolymer-Compatible Formulation Development | Opens white space in PLA and PHA thermal stabilization as compostable packaging scales. |
| Direct Procurement Platform Launch | Compresses distributor margins by connecting Indian and Vietnamese PVC processors with producers. |
| Multi-Regulatory Certification Investment | Secures qualification for REACH, FDA, and CDSCO compliance across fragmented pharmacopeial standards. |
Methodological Framework
Document review covered customs trade data, SEC filings from listed chemical producers, ECHA registration databases, and USP-NF monograph updates, complemented by interviews with plant managers at integrated oleochemical facilities, procurement leads at Indian PVC compounders, pharmaceutical excipient sourcing directors, and distribution channel partners across Southeast Asia. Primary fieldwork validated secondary estimates through bottom-up capacity assessments and top-down demand triangulation across polymer, pharmaceutical, and food-contact end uses.
Output metrics span volume and value projections across the analysis window, with segmentation modeled by metal cation chemistry, grade tier, end-use vertical, and regional regulatory cluster. CAGRs derive from regression against oleochemical feedstock price indices, PVC compounding growth rates, and pharmaceutical excipient localization policy trajectories. Continuous-flow technology adoption curves and REACH registration completion timelines feed scenario-weighted forecast distributions.
Inputs from ECHA registration databases, Indian BIS certification records, and Malaysian palm oil futures were available through the study window; gaps in real-time Chinese NMPA pharmaceutical excipient approval data introduce uncertainty bands around magnesium stearate localization projections. Forecasts reflect documented assumptions regarding pharmacopeial harmonization progress and biopolymer processing adoption rates. Material deviation in REACH authorization stringency or sudden palm oil supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Plasticizer Concrete Admixtures Market
Additives
Cassia Gum Market
Additives
Plasticizers Market
Additives
High Performing Matting Agents Market
Additives
Europe UV Stabilizers Market
Additives
Competitive Inhibitors Market
Additives
Global Carboxylic Acids Based Esters Market
Additives
Butyrate Additives Market
Additives
Global Slip Additives Market
Additives
Anti-Creasing Agent Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Supplemental Coolant Additives Market
Additives
Printing Ink Additives Market
Additives
Tire Additives Market
Additives
Hydroxypropyl Distarch Phosphate Market