
 Antioxidant and Stabilizer Agents Market | 2026-2036
Antioxidant and Stabilizer Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Antioxidant and Stabilizer Agents Market Outlook
Specialized polymer chemist talent is bifurcating between commodity stabilizer production and high-performance additive formulation, tightening the labor pool for next-generation hindered amine light stabilizer development. BASF leverages its Ludwigshafen integrated site to sustain captive intermediates for antioxidant synthesis. Songwon Industrial anchors Asia-Pacific supply through its Busan manufacturing complex, while Evonik Industries differentiates via high-purity phosphite stabilizers for engineered plastics.
Antioxidant and stabilizer agents comprise synthetic and natural compounds—phenolics, phosphites, thioesters, and hindered amine light stabilizers (HALS)—that inhibit thermal oxidation and photo-degradation in organic materials by scavenging free radicals and decomposing hydroperoxides. These additives extend service life in polyolefins, polyurethanes, and lubricants where oxidative chain reactions degrade mechanical properties. Tocopherols and ascorbic acid segments command premium positioning in clean-label food preservation as manufacturers reformulate away from synthetic BHA and BHT. Plastics applications dominate volume consumption, with polymer producers absorbing the majority of hindered phenolic and phosphite blends for extrusion-grade resins.
REACH restrictions on substance authorization and the EU F-Gas Regulation shape product migration testing protocols for stabilizers used in refrigeration equipment plastics. FDA food-contact notifications and EPA chemical data reporting requirements govern antioxidant purity thresholds for U.S. packaging and coatings applications. Stakeholders must monitor regulatory divergence between European hazard-based assessments and U.S. risk-based frameworks when allocating R&D budgets across regional formulation portfolios.
Market Dynamics
Polymer producers are consolidating antioxidant procurement around integrated stabilizer packages as REACH authorization timelines and FDA food-contact notification requirements compress formulation cycles and force dual-track regulatory qualification.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Germany and the United States are expanding thermoplastic content in under-hood applications, pulling demand for heat-resistant phosphite and phenolic stabilizer blends that protect polyamide and polypropylene components during long-term thermal cycling.
- REACH substance authorization:ECHA's rolling review of existing antioxidant chemistries is accelerating replacement of legacy stabilizers with pre-registered alternatives, creating pull-through demand for reformulated additive packages that maintain performance while satisfying updated safety data requirements.
- China polymer capacity expansion:Domestic polyolefin and polyurethane production scale-up along the Yangtze River Delta is concentrating regional demand for hindered amine light stabilizers and thioester antioxidants, with local BHT manufacturing reducing import dependency for commodity grades.
Market Restraints
- Feedstock cost volatility:Propylene and phenol derivatives, core building blocks for phosphite and phenolic stabilizers, exhibit price sensitivity to crude oil fluctuations and refinery operating rates, compressing additive producer margins during upstream spikes.
- Supply concentration in Northeast Asia:Bulk antioxidant intermediates concentrate among integrated petrochemical complexes in South Korea and eastern China, exposing downstream formulators to single-source risk during regional logistics disruptions or trade policy shifts.
- Migration testing complexity:Divergent FDA food-contact notification requirements and EU plastic food contact material regulations create parallel compliance burdens, extending qualification timelines for stabilizers used in multi-jurisdiction packaging applications.
Strategic Opportunities
- India polymer downstream growth:Reliance Industries and Indian Oil Corporation are expanding polyolefin capacity under national petrochemical self-sufficiency targets, creating white space for localized stabilizer blending operations that bypass import tariffs and reduce working capital cycles.
- Biopolymer stabilization:PLA and PHA producers require novel antioxidant systems compatible with hydrolytically sensitive bio-based matrices, opening formulation partnerships between additive specialists and fermentation-derived polymer startups.
- EU F-Gas Regulation compliance:Refrigeration equipment manufacturers redesigning polymer seals and housings for low-GWP refrigerant compatibility need enhanced thermal stabilizer packages, creating specification pull for phosphite-phenolic synergistic blends in cold-chain infrastructure.
Industry Challenges
- Polymer chemist specialization gap:The bifurcation between commodity stabilizer production roles and high-performance additive formulation positions is tightening the labor pool for hindered amine light stabilizer development, with BASF and Songwon competing for the same specialized talent cohort.
- Dual-track regulatory qualification costs:Simultaneous FDA food-contact notification and EU REACH authorization processes require redundant toxicology studies and migration testing protocols, straining R&D budgets for mid-cap stabilizer producers without integrated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antioxidant and Stabilizer Agents Market |
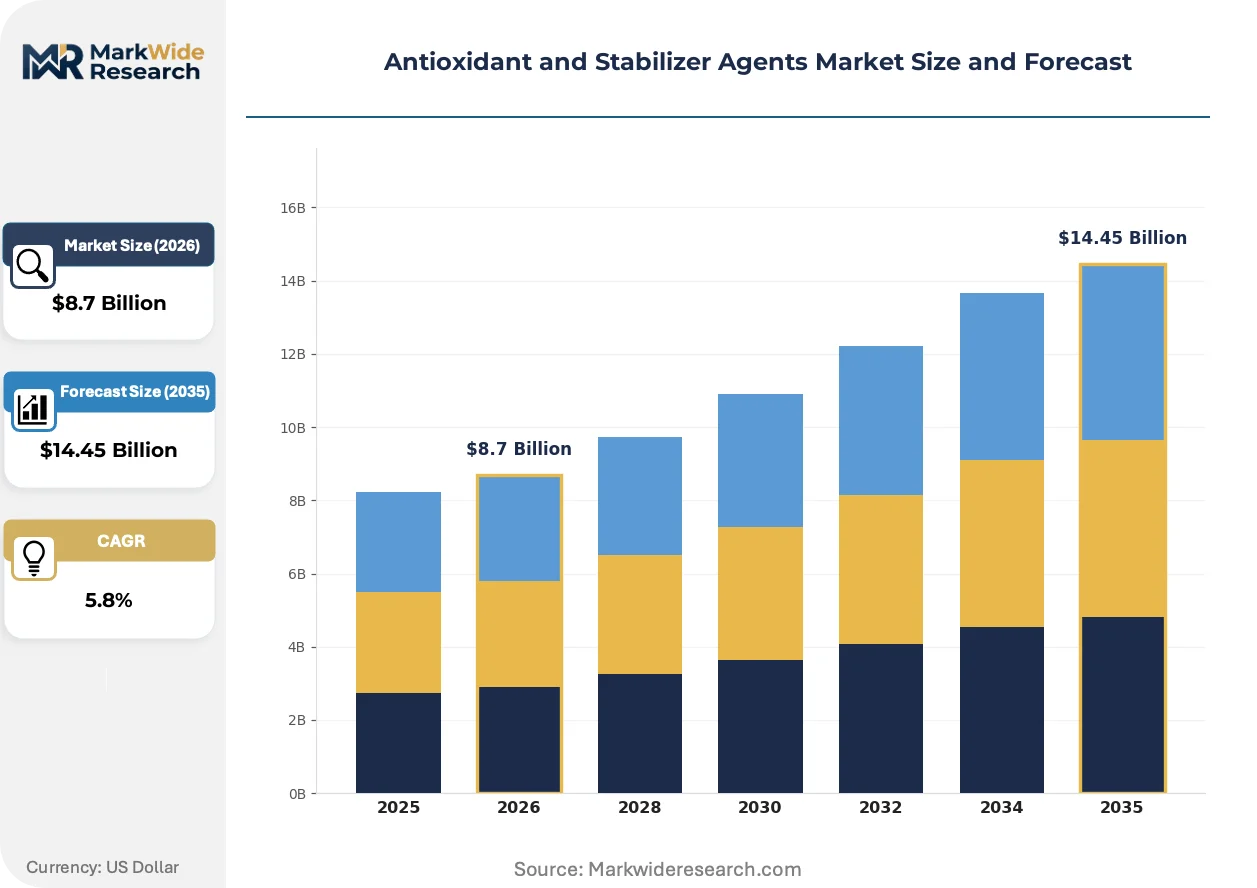
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BHA, BHT, Tocopherols, Ascorbic Acid Application: Food Preservation, Cosmetics, Pharmaceuticals, Plastics End User: Food Industry, Cosmetics Manufacturers, Pharmaceutical Firms, Polymer Producers Form: Liquid, Powder, Granular, Emulsion |
| Companies Covered | BASF, Clariant, Albemarle, Songwon Industrial, Adeka Corporation, SI Group, Solvay, Akzo Nobel, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antioxidant and Stabilizer Agents Market Strategic Shifts
Reactive antioxidant architectures and bio-derived stabilizer platforms are displacing conventional additive approaches as polymer producers seek permanence in high-extraction applications and clean-label positioning in food-contact segments.
Non-migrating reactive antioxidants with polymer-bound functional groups are supplanting conventional low-molecular-weight stabilizers in flexible packaging films and medical tubing where extraction and bloom concerns dominate specification discussions. European medical device manufacturers and U.S. food packaging converters are accelerating qualification timelines for these grafted architectures. The shift is compressing demand for traditional BHT and BHA grades in sensitive applications while expanding addressable market for additive suppliers with reactive chemistry capabilities.
ECHA's 2023-2027 rolling action plan for substance evaluation is forcing antioxidant producers to generate new mammalian toxicology data for legacy phenolic stabilizers previously grandfathered under REACH's 2010 registration deadline. The industrial consequence is a wave of read-across justifications and substance identity clarifications consuming technical resources. Polymer producers in automotive and construction sectors are most affected, responding by dual-sourcing stabilizer grades and accelerating validation of alternative chemistries with more favorable hazard profiles.
Long-term supply agreements with embedded volume commitments are displacing spot-market antioxidant purchasing as polyolefin producers seek price predictability amid feedstock volatility. The channel disruption concentrates procurement leverage among integrated petrochemical majors with captive additive capabilities. This pattern is most visible in China, where Sinopec and PetroChina are internalizing stabilizer blending operations to secure supply security for resin export contracts.
Antioxidant and Stabilizer Agents Market Segmentation
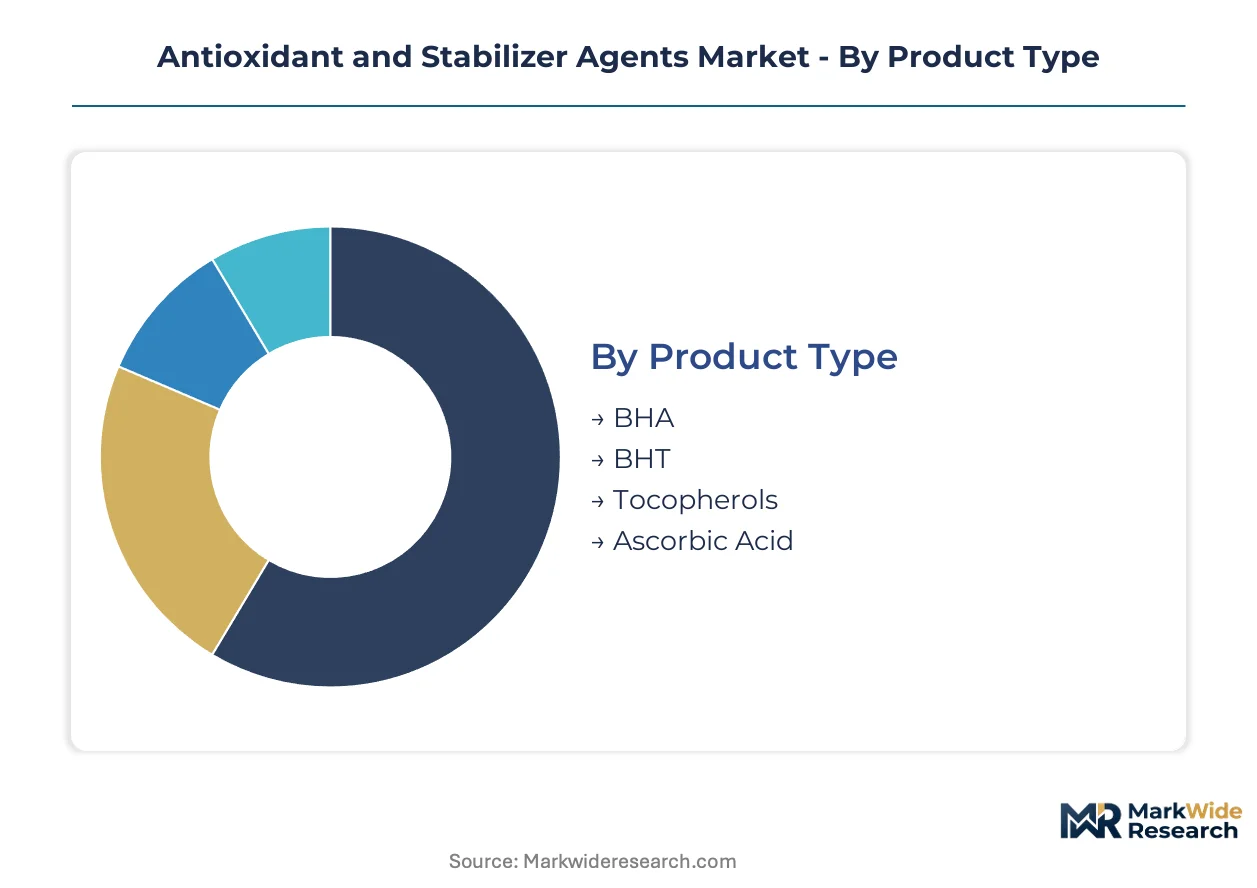
Antioxidant and stabilizer agents serve divergent performance requirements across food safety, polymer durability, and cosmetic shelf-life applications. Regulatory thresholds for migration limits and purity specifications fragment demand patterns by end-use, compelling suppliers to maintain parallel formulation portfolios.
Product Type:
FDA food-contact notifications and EFSA purity specifications create divergent qualification burdens for synthetic versus natural antioxidant chemistries, with REACH substance authorization timelines accelerating reformulation decisions.
- BHA:Synthetic phenolic compound with established efficacy in lipid oxidation prevention. Polymer producers in Germany and the United States specify BHA for under-hood automotive applications where thermal stability exceeds natural alternatives.
- BHT:Bulk commodity antioxidant manufactured at scale across China's Yangtze River Delta. Domestic polyolefin capacity expansion is absorbing regional BHT output, reducing import dependency for commodity-grade stabilizers.
- Tocopherols:Vitamin E-derived natural antioxidants commanding premium positioning in clean-label food preservation. EFSA-approved tocopherol concentrates are displacing synthetic alternatives in European organic packaged foods.
- Ascorbic Acid:Water-soluble antioxidant with dual functionality in food fortification and oxidative inhibition. Pharmaceutical-grade ascorbic acid meets USP specifications for parenteral formulation stability.
Established volume favors BHT; emerging adoption favors tocopherols.
Application:
Migration testing protocols and extraction limit requirements stratify demand intensity, with food-contact and medical applications absorbing the most stringent regulatory scrutiny.
- Food Preservation:Antioxidant systems prevent rancidity in edible oils and processed meats. FDA notification requirements for direct food additives compress formulation cycles for new product launches.
- Cosmetics:Personal care formulations require photostable antioxidants compatible with emulsion matrices. French and German cosmetics manufacturers prioritize tocopherol acetate for natural positioning claims.
- Pharmaceuticals:Excipient-grade stabilizers must meet ICH Q3D elemental impurity guidelines. Parenteral and inhalation dosage forms command the highest purity thresholds.
- Plastics:Hindered phenolic and phosphite blends protect polyolefins during extrusion and long-term thermal cycling. Automotive under-hood specifications in Germany and the United States drive heat-resistant stabilizer procurement.
Plastics applications dominate tonnage; food preservation commands the steepest expansion trajectory for natural alternatives.
End User:
Procurement consolidation patterns differ sharply between fragmented food processors and concentrated polymer producers with captive additive capabilities.
- Food Industry:Processors of edible oils, snack foods, and meat products specify antioxidants based on cost-performance ratios. Clean-label reformulation is accelerating tocopherol adoption in premium product lines.
- Cosmetics Manufacturers:Formulators prioritize photostability and skin compatibility in antioxidant selection. European natural cosmetics certification schemes restrict synthetic BHA and BHT usage.
- Pharmaceutical Firms:Drug developers require antioxidants with documented stability data across ICH storage conditions. USP and EP compliance documentation consumes qualification resources.
- Polymer Producers:Integrated petrochemical majors in China and South Korea are internalizing stabilizer blending to secure supply predictability for resin export contracts.
Polymer producers concentrate procurement leverage; pharmaceutical firms impose the most demanding documentation requirements.
Form:
Handling characteristics and dispersion uniformity requirements dictate form selection, with liquid and powder formats dominating distinct processing environments.
- Liquid:Preferred for high-throughput food oil processing and continuous polymer extrusion systems. Pumpable concentrates reduce dust exposure and improve dosing accuracy.
- Powder:Standard format for dry food premixes and powder cosmetic formulations. Flowability and caking resistance determine specification acceptance.
- Granular:Low-dust alternative for polymer compounding operations. Granular phosphite stabilizers disperse uniformly in polyolefin melt processing.
- Emulsion:Water-dispersible systems for beverage fortification and aqueous cosmetic formulations. Emulsion stability under thermal processing conditions governs shelf-life performance.
Powder formats retain volume dominance in dry processing; emulsion systems are gaining share fastest in beverage and aqueous cosmetic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH authorization timelines in Germany are compressing formulation cycles for antioxidant producers serving European polymer markets. Manufacturers must simultaneously satisfy ECHA substance evaluations and FDA food-contact notifications for cross-Atlantic supply contracts.
China
Domestic polyolefin capacity expansion along the Yangtze River Delta is absorbing regional BHT output from local manufacturers. MIIT industrial policy supports import substitution for commodity-grade stabilizers. Shanghai and Ningbo petrochemical clusters are internalizing phosphite blending operations to secure supply predictability for resin export contracts.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify heat-resistant phenolic-phosphite blends for under-hood thermoplastic applications. ECHA's rolling action plan demands new mammalian toxicology data for legacy stabilizers previously grandfathered under REACH. The Ludwigshafen chemical complex sustains captive intermediate production for integrated antioxidant synthesis.
United States
Packaging converters in the Midwest and Southeast are accelerating qualification of non-migrating reactive antioxidants for food-contact films. FDA notification requirements for direct food additives compress reformulation timelines. Texas and Louisiana petrochemical corridors concentrate phosphite intermediate production tied to refinery propylene streams.
South Korea
Busan-Ulsan manufacturing complexes anchor Asia-Pacific supply for hindered amine light stabilizers serving regional polymer producers. MFDS pharmaceutical-grade specifications govern antioxidant purity for excipient applications. Daegu-Gyeongbuk textile clusters demand photostable stabilizers for synthetic fiber production.
India
Reliance Industries and Indian Oil Corporation are expanding polyolefin capacity under national petrochemical self-sufficiency targets. FSSAI food additive regulations create parallel compliance burdens for tocopherol and synthetic antioxidant formulations. Gujarat and Maharashtra industrial corridors present white space for localized stabilizer blending operations.
Antioxidant and Stabilizer Agents Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the antioxidant and stabilizer agents market. The vendor base stratifies into integrated petrochemical majors with captive additive capabilities, mid-cap specialists with regulatory affairs depth, and regional blenders serving geographically concentrated polymer demand. Three archetypes dominate: German diversified chemical conglomerates leveraging integrated sites, Korean and Chinese scale producers feeding domestic polymer expansion, and formulation-focused specialists developing reactive antioxidant architectures. Competitive dynamics center on backward integration into phenol and propylene derivatives, alongside long-term supply agreements embedding volume commitments.
Among German-based diversified chemical producers, BASF exemplifies the integrated archetype through its Ludwigshafen manufacturing complex. Korean scale producers are represented by Songwon Industrial, which anchors Asia-Pacific supply from its Busan operations. Evonik Industries occupies a position within the high-purity specialty tier, differentiating through phosphite stabilizer grades for engineered plastics applications. These three companies represent distinct competitive vectors: integrated site economics, regional scale production, and performance-grade formulation specialization.
| Leading Market Players |
|---|
| BASF |
| Clariant |
| Albemarle |
| Songwon Industrial |
| Adeka Corporation |
| SI Group |
| Solvay |
| Akzo Nobel |
| Evonik Industries |
| Others |
Value Chain & Pricing Dynamics
Natural tocopherol substitution for synthetic BHT in European food-contact applications simultaneously redraws procurement geography toward Malaysian and Indonesian palm-derived feedstock zones and compresses price premiums for synthetic phenolic grades. This input shift concentrates margin pressure on legacy commodity producers while rewarding formulators with backward integration into natural antioxidant extraction.
Pricing Analysis
Geographic price spreads between South Korean phosphite stabilizer exports and Chinese domestic BHT contracts have widened as regional feedstock cost differentials intensify. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade specifications governs antioxidant transactions, with FDA notification compliance and REACH authorization status as primary price differentiation drivers. Pricing pressure stems from propylene derivative cost volatility eroding additive producer margins. Polymer producers exhibit lowest price sensitivity due to long-term supply agreements, while fragmented food processors remain most exposed to spot-market fluctuations.
Supply Chain Analysis
Inventory lead times for hindered amine light stabilizers have extended as polymer producers pre-position stocks ahead of ECHA substance evaluation deadlines. Supply concentrates in South Korea, China, and Germany, with Busan-Ulsan complexes and Ludwigshafen anchoring regional production. Raw material flows draw from phenol derivatives, propylene streams, and natural tocopherol concentrates. Single-source vulnerability persists for phosphite intermediates tied to Northeast Asian petrochemical complexes. Distribution runs through integrated petrochemical majors with captive blending operations and specialized distributors serving formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated polymer producers in China and South Korea, compressing negotiation leverage for mid-cap stabilizer suppliers without captive feedstock positions.
For Market Incumbents: Consolidate backward integration into phenol and propylene derivatives to defend margin structures against feedstock volatility. Expand high-purity phosphite capacity at Ludwigshafen or Busan-scale complexes to preempt regulatory-driven substitution. Lock in long-term offtake agreements with automotive OEMs specifying heat-resistant stabilizer blends for under-hood thermoplastic applications. For New Entrants and Emerging Players: Technical regulatory affairs support represents a service-layer gap where incumbents under-serve mid-cap polymer producers facing dual-track FDA and REACH qualification burdens. Target India polymer downstream growth in Gujarat and Maharashtra corridors where localized blending operations bypass import tariffs. Pursue formulation partnerships with PLA and PHA biopolymer startups requiring novel antioxidant systems compatible with hydrolytically sensitive matrices. For Investors and Strategic Acquirers: The market sits at a regulatory-qualification intensification phase that favors mid-cap specialists with embedded toxicology and migration testing capabilities. Long-term viability over the next decade hinges on positioning ahead of ECHA's rolling action plan completion and FDA food-contact notification backlog resolution. Acquisition target archetype: regional blenders with reactive antioxidant chemistry IP and established pharmaceutical-grade certification. Signal to watch: acceleration of non-migrating stabilizer qualification timelines at European medical device manufacturers and U.S. packaging converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Derivatives | Captive feedstock supply at Ludwigshafen-scale complexes insulates margin structures from propylene volatility. |
| Reactive Antioxidant Architecture Development | Polymer-bound functional groups address extraction concerns in FDA-regulated food-contact film applications. |
| Long-term Supply Agreement with Volume Commitments | Sinopec and PetroChina internalization patterns favor suppliers embedding price predictability clauses. |
| Regulatory Affairs Function Buildout | Dual-track REACH and FDA qualification capabilities reduce time-to-market for reformulated additive packages. |
| Biopolymer Stabilizer Formulation Partnership | PLA and PHA producers require antioxidant systems compatible with hydrolytically sensitive fermentation-derived matrices. |
Study Parameters
A spread of perspectives from polymer plant managers, antioxidant procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from listed chemical producers. Bottom-up demand modeling across polymer end-uses triangulated with top-down market sizing from production capacity disclosures.
Segmentation dimensions modeled include product type tier, application end-use, geographic production hub, and regulatory qualification status across the analysis window. CAGRs derive from slope analysis of normalized volume trends adjusted for feedstock cost pass-through assumptions. Industry-specific forecast inputs incorporate polyolefin capacity expansion timelines along the Yangtze River Delta and automotive lightweighting content-per-vehicle trajectories in German and U.S. markets.
Forecasts assume regulatory continuity in REACH authorization timelines and FDA food-contact notification processing; material policy shifts in ECHA substance evaluation priorities or FSSAI food additive regulations would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
North America Fuel Additives Market
Additives
Global Ester Gum Market
Additives
Plasticizers Market
Additives
South America Concrete Admixtures Market
Additives
Defoaming Coating Additives Market
Additives
Global Low-Profile Additive Market
Additives
Grease Additives Market
Additives
Trioctyldodecyl Citrate Market
Additives
Additives for Floor Coatings Market
Additives
Hydroxypropyl Distarch Phosphate Market
Additives
Foundry Additives Market
Additives
Asia Pacific Silage Additives Market
Additives
Liquid Silage Additive Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Sorbitan Esters Market
Additives
Pectin Market