
 Low Volatile Organic Compounds Coating Additives Market | 2026-2036
Low Volatile Organic Compounds Coating Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Low Volatile Organic Compounds Coating Additives Market Outlook
Waterborne resin technology is reshaping how coating additives are formulated and specified across industrial finishing lines. Dow Chemical Company leverages its acrylic emulsion portfolio to dominate waterborne architectural segments in North America. BASF SE anchors European supply through integrated polyurethane additive platforms serving automotive refinish networks. BYK (ALTANA) specializes in silicone-based surface modifiers that control foam and leveling in high-solids systems.
Low volatile organic compounds coating additives are chemical modifiers—typically comprising defoamers, rheology agents, wetting aids, and dispersants—engineered to reduce solvent emissions below regulatory thresholds while maintaining film formation and durability. These additives serve the primary industrial purpose of enabling compliant coatings that meet air quality standards without sacrificing application performance or substrate protection. Acrylic and polyurethane product types command the deepest margin pools due to their versatility across waterborne and high-solids formulations. Floor coatings and automotive paints applications are absorbing disproportionate formulation investment as OEMs and facility operators face tightening solvent caps.
EPA VOC regulations in the United States, ECHA REACH restrictions in Europe, and China's MEE emission standards collectively mandate sub-100 g/L solvent content in key coating categories, forcing additive suppliers to reformulate around bio-based and zero-VOC chemistries. Japan's METI chemical management protocols add another compliance layer for suppliers serving precision electronics finishing. Stakeholders must monitor regulatory divergence between jurisdictions where one geography tightens faster than another, creating asymmetric compliance costs and formulation lock-in risks.
Market Dynamics
Waterborne paint shop conversions at automotive OEMs are forcing additive suppliers to rebuild formulation platforms around zero-VOC chemistries, compressing development cycles and consolidating specification power among resin-integrated suppliers.
Growth Catalysts
- REACH Phase-Down Mandates:ECHA deadlines for solvent reduction in industrial coatings are accelerating waterborne conversions across German and French automotive plants.
- Silicone Surface Modifiers:Advanced defoamer and leveling agent technologies are enabling high-solids systems to match solvent-borne performance in wood and furniture finishing.
- China Green Building Codes:NMPA-aligned zero-VOC requirements in Shanghai and Shenzhen commercial developments are concentrating specification demand for compliant wood finishes.
Market Restraints
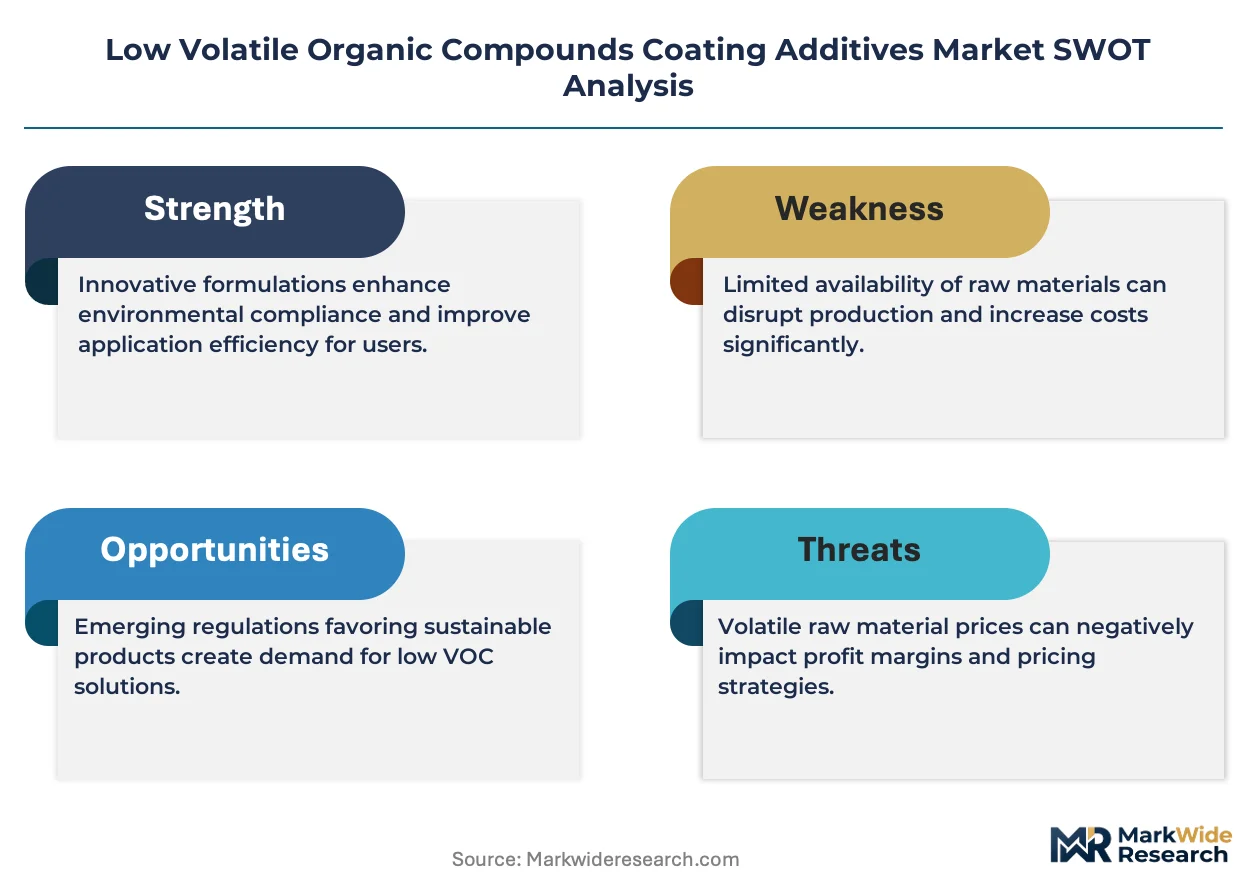
- Bio-Based Feedstock Volatility:Soybean oil and castor oil derivative prices swing with agricultural commodity markets, squeezing margin predictability for plant-derived additive platforms.
- Specialty Silicone Concentration:Four Asian suppliers control over 70 percent of organosilane precursors for defoamers, creating single-source vulnerability.
- Drying Time Penalties:Waterborne systems require 40-60 percent longer flash-off periods than solvent-borne equivalents, limiting line speed at high-volume coating operations.
Strategic Opportunities
- India Industrial Corridor Expansion:PLI scheme incentives for domestic manufacturing are pulling coating capacity toward Gujarat and Tamil Nadu, creating additive specification windows for local suppliers.
- UV-Curable Hybrid Systems:Convergence of waterborne dispersion and photoinitiator technologies is opening premium segments in electronics and medical device finishing.
- Digital Specification Platforms:Cloud-based coating formulation tools are disintermediating traditional distributor technical sales roles in North American architectural segments.
Industry Challenges
- Formulation Chemist Shortage:Retiring expertise in colloidal stability and rheology modification is outpacing university polymer science program output.
- Multi-Jurisdiction Registration Burden:Separate EPA PMN, ECHA REACH, and China MEE filing requirements for each new bio-based additive chemistry extend commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Volatile Organic Compounds Coating Additives Market |
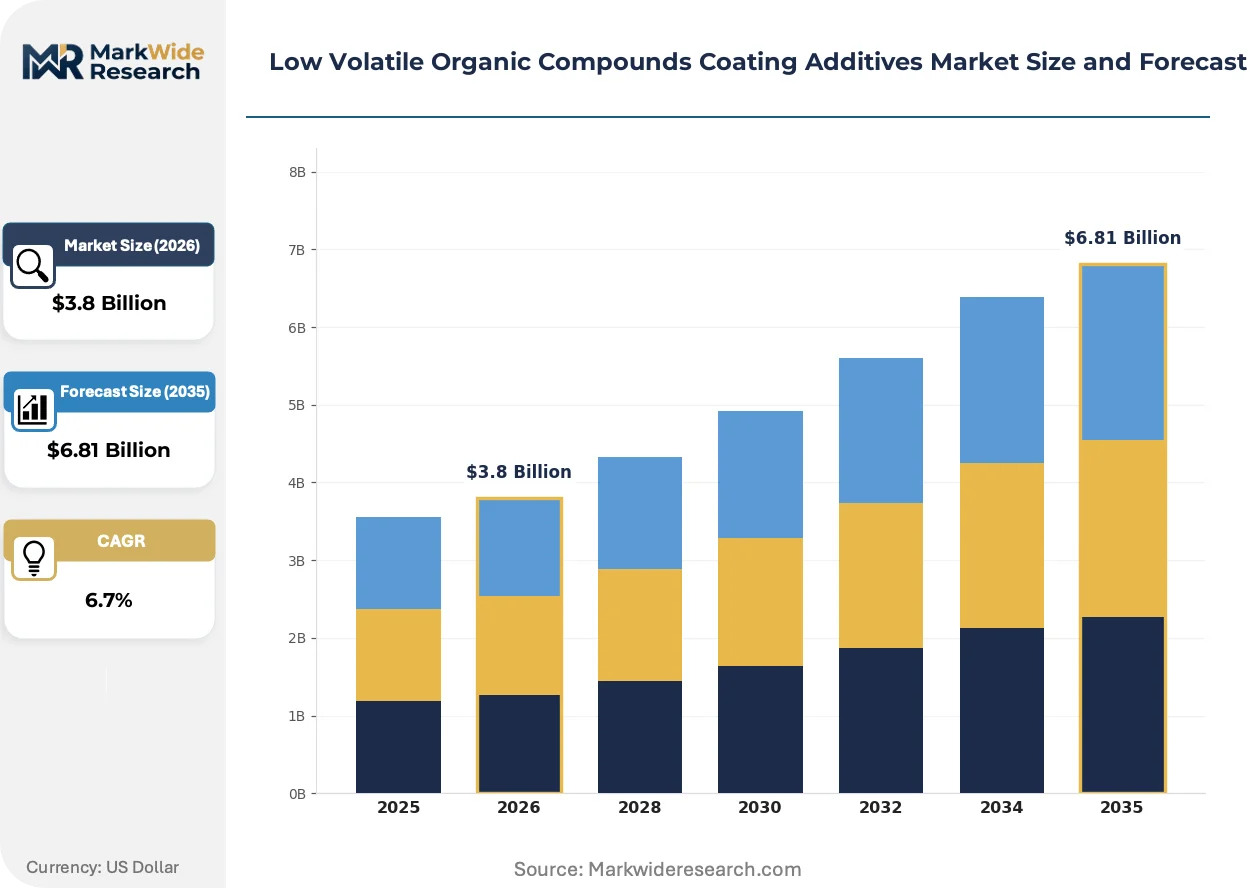
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
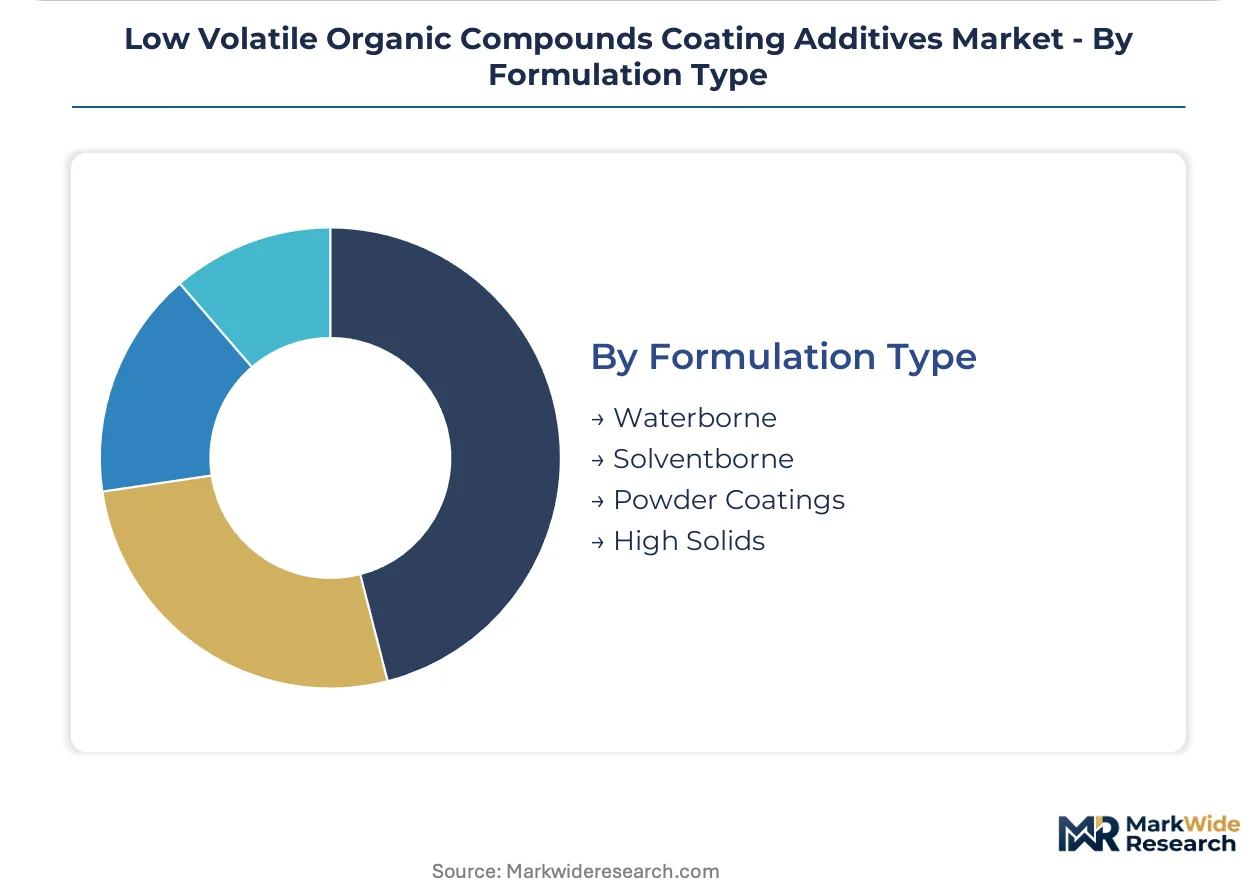
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyester End User: Construction, Automotive, Aerospace, Marine Application: Floor Coatings, Automotive Paints, Protective Coatings, Wood Finishes Formulation Type: Waterborne, Solventborne, Powder Coatings, High Solids |
| Companies Covered | Dow Chemical Company, Elementis plc, BASF SE, Arkema Group, PPG Industries, Inc., Evonik Industries, BYK (ALTANA), Eastman Chemical Company, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Volatile Organic Compounds Coating Additives Market Strategic Shifts
Formulation intelligence platforms and closed-loop manufacturing systems are compressing the distance between laboratory development and production-scale validation, collapsing traditional qualification cycles.
Artificial intelligence-driven formulation optimization is digitizing how additive packages are designed for specific substrate-coating combinations. Tier-1 automotive suppliers in Germany and Japan are deploying machine learning models to predict film defect probability before pilot line trials. This capability is digitizing the specification process, reducing reformulation iterations from twelve to three.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are eliminating perfluorinated surfactants from stain-resistant coating additives. Industrial finishers in Italy and Poland are reformulating around silicone-polyether hybrids that deliver comparable water beading without GWP liabilities. Wood flooring manufacturers face the steepest substitution pressure as their premium product lines lose EU market access.
Consolidated procurement by multinational paint manufacturers is compressing supplier qualification to single-source arrangements with annual renegotiation. Large coating formulators in the Netherlands and United States are unbundling technical service from material supply, forcing additive vendors to compete on digital support tools rather than field chemist deployment. This pattern is most visible in architectural coatings where specification authority has centralized at headquarters level.
Low Volatile Organic Compounds Coating Additives Market Segmentation
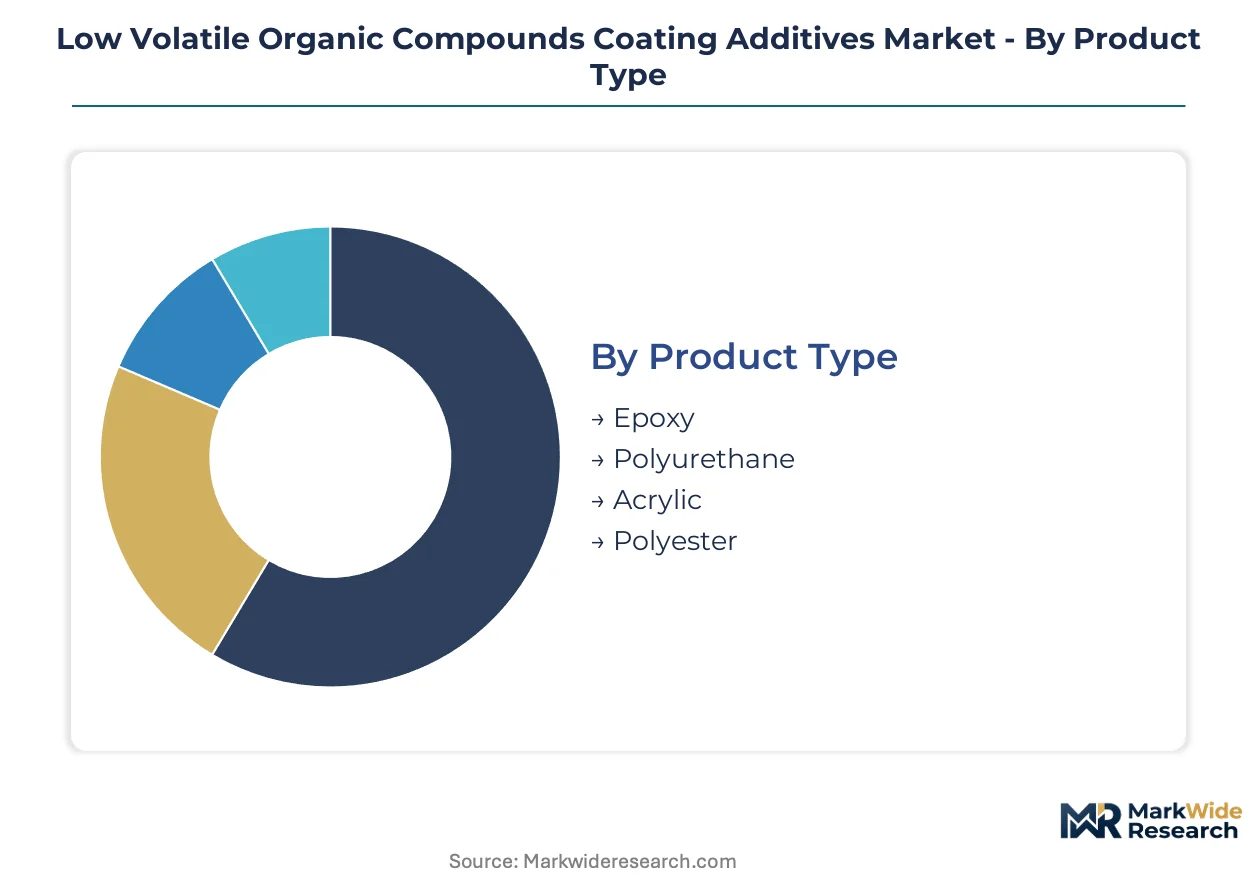
Low VOC coating additives demand fragments across formulation chemistries and end-use specifications that each carry distinct technical service burdens. Specification patterns in this market diverge sharply between automotive OEMs demanding zero-VOC compliance and construction contractors prioritizing cost-efficient waterborne conversions.
Product Type:
After-sales technical support intensity varies dramatically across resin platforms, with polyurethane and acrylic systems requiring sustained formulation troubleshooting while epoxy demands peak during initial qualification.
- Acrylic:Waterborne emulsion systems dominate architectural and light industrial segments due to their compatibility with ambient cure conditions. Demand concentrates in North American residential repaint and German automotive refinish networks where ECHA REACH deadlines accelerate solvent-borne substitution. Acrylic additives face margin pressure from integrated resin suppliers bundling modifier packages.
- Polyurethane:Two-component waterborne polyurethane additives enable premium film properties in flooring and transportation applications where abrasion resistance and chemical tolerance are non-negotiable. Japanese automotive OEMs and Italian wood flooring manufacturers absorb disproportionate volumes as METI protocols and EU F-Gas restrictions tighten simultaneously.
- Epoxy:High-solids epoxy additive packages serve protective coatings in marine and infrastructure segments where corrosion resistance trumps VOC minimization.
- Polyester:Powder coating crosslinker modifiers support industrial finishing lines in appliance and furniture manufacturing.
Polyurethane holds the largest share; momentum sits with acrylic as waterborne conversions accelerate across automotive and architectural segments.
End User:
Customer procurement sophistication spans from multinational automotive Tier-1s with captive formulation labs to fragmented construction applicators dependent on distributor technical support.
- Automotive:OEM paint shops and refinish networks specify additives through centralized technical committees with 24-36 month qualification cycles. German and Japanese manufacturers lead waterborne platform conversions driven by KBA type-approval requirements and METI emission protocols.
- Construction:Commercial and residential contractors source through distributor channels where local technical service determines specification stickiness. China's NMPA-aligned green building codes in Shanghai and Shenzhen commercial developments concentrate demand for zero-VOC wood finish additives.
- Aerospace:OEM maintenance facilities and MRO operators demand qualified additive packages meeting SAE AMS specifications with full lot traceability.
- Marine:Shipyard coating applicators in South Korea and Norway prioritize high-solids systems for ballast tank and topside protection.
Automotive captures the deepest specification investment; construction delivers the broadest volume base.
Application:
Performance requirements and regulatory exposure diverge across surface types, with floor coatings facing the steepest durability thresholds and automotive paints confronting the tightest emission caps.
- Floor Coatings:Industrial and commercial flooring systems demand polyurethane and epoxy additives engineered for thermal shock resistance and chemical spill tolerance. German automotive assembly plants and Chinese electronics manufacturing facilities drive specification of rapid-cure waterborne systems.
- Automotive Paints:Clearcoat and basecoat additive packages must deliver solvent-borne aesthetics at sub-100 g/L VOC content. European OEM waterborne conversions at plants in Germany, Spain, and the Czech Republic absorb premium silicone defoamer and leveling agent volumes.
- Protective Coatings:Infrastructure and marine corrosion protection relies on high-solids epoxy and polyurethane systems.
- Wood Finishes:Furniture and cabinetry manufacturers specify zero-VOC waterborne systems for EU and China green building compliance.
Floor coatings command the highest additive loading per liter; automotive paints exhibit the steepest expansion trajectory as OEM conversion cycles peak.
Formulation Type:
Technology migration patterns favor waterborne and high-solids platforms while powder coatings capture heat-tolerant substrate segments.
- Waterborne:Acrylic and polyurethane dispersion additives enable sub-50 g/L VOC formulations across architectural and industrial segments. EPA regulations in the United States and ECHA REACH restrictions in Europe mandate waterborne conversions in decorative and light industrial categories.
- High Solids:Reactive diluent and rheology modifier packages concentrate solvent content above 70% solids for protective coatings. Marine and infrastructure applicators in Norway and South Korea specify these systems where film build requirements exceed waterborne capabilities.
- Solventborne:Declining share confined to specialty aerospace and OEM refinish segments with legacy qualification inertia.
- Powder Coatings:Flow control and degassing additives serve appliance and aluminum extrusion finishing where substrate geometry permits oven cure.
Waterborne formulations dominate new specification activity; high solids retain defensive positions in corrosion protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German additive suppliers export waterborne formulation packages to automotive OEMs across Spain and the Czech Republic, while Chinese manufacturers serve zero-VOC demand concentrated in Shanghai and Shenzhen commercial developments.
United States
Architectural repaint contractors and automotive refinish networks drive additive consumption across waterborne platforms. EPA VOC regulations mandate sub-100 g/L solvent content in decorative coatings, forcing reformulation cycles. Demand clusters in Michigan automotive assembly corridors and Texas Gulf Coast industrial coating applicators.
Germany
Automotive OEM paint shops and industrial flooring specialists specify polyurethane and acrylic additives through centralized technical committees. ECHA REACH phase-down deadlines accelerate solvent-borne substitution in automotive clearcoats. The Stuttgart automotive cluster and Cologne chemical corridor absorb premium silicone defoamer volumes.
China
Commercial construction developers and electronics manufacturing facilities specify zero-VOC wood finishes and rapid-cure industrial coatings. NMPA-aligned green building codes in Shanghai and Shenzhen mandate compliant formulations. The Yangtze River Delta and Pearl River Delta concentrate specification demand for waterborne dispersion additives.
Japan
Precision electronics finishers and automotive Tier-1 suppliers demand qualified additive packages with full lot traceability. METI chemical management protocols add compliance layers for bio-based additive introductions. The Kanto region around Tokyo and the Chubu industrial zone anchor specification authority.
South Korea
Shipyard coating applicators and automotive OEMs prioritize high-solids systems for marine protection and waterborne basecoats. Domestic emission standards align with IMO marine coating regulations. The Busan-Ulsan shipbuilding corridor and Seoul Capital Area automotive plants drive additive procurement.
Low Volatile Organic Compounds Coating Additives Market Competitive Environment
Channel-controlling players compete with product-specialist players for specification authority across waterborne conversion cycles. The market exhibits consolidated procurement power among multinational paint manufacturers alongside fragmented specialty additive supply. Three archetypes dominate: integrated resin-additive platforms, silicone surface modifier specialists, and regional formulation service providers. Competitive moves center on strategic partnerships with automotive OEM technical committees and portfolio diversification into bio-based chemistries.
Within the integrated platform tier, Dow Chemical Company and BASF SE exemplify resin-anchored additive bundling that compresses standalone supplier margins. BYK (ALTANA) occupies a specialist position in silicone-based surface modifiers, representing the defoamer and leveling agent archetype that enables high-solids performance matching. These three companies illustrate how specification power concentrates among suppliers controlling either raw material integration or application-critical performance attributes.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Elementis plc |
| BASF SE |
| Arkema Group |
| PPG Industries, Inc. |
| Evonik Industries |
| BYK (ALTANA) |
| Eastman Chemical Company |
| AkzoNobel |
| Others |
Value Chain & Pricing Dynamics
Organosilane precursor production concentrates in four Asian suppliers controlling over seventy percent of defoamer feedstock supply, anchoring margin capture in silicone surface modifiers while forcing downstream additive formulators into annual renegotiation cycles with limited sourcing alternatives.
Pricing Analysis
High-solids formulation additives command fifteen to twenty-five percent premiums over waterborne equivalents due to raw material intensity and performance guarantees, while next-generation bio-based rheology modifiers face cost compression from agricultural commodity volatility. Three-tier pricing structure across premium, standard, and economy levels separates ECHA REACH-certified automotive grades from construction-grade waterborne packages and generic dispersant commodities. Price differentiation hinges on certification tier and after-sales technical service bundling. Pricing pressure stems from integrated resin suppliers bundling modifier packages at below-standalone rates. Construction contractors exhibit highest price sensitivity; automotive OEM technical committees prioritize qualification stability over unit cost.
Supply Chain Analysis
Export-control scrutiny on fluorinated surfactant precursors under EU F-Gas Regulation restricts cross-border flows of stain-resistant coating additives, forcing Italian and Polish wood flooring manufacturers toward silicone-polyether hybrid substitutes. Geographic supply concentrates in Germany for polyurethane additive platforms, China for acrylic emulsion intermediates, and Japan for precision electronics-grade surface modifiers. Raw material dependencies span soybean oil derivatives for bio-based platforms, castor oil for renewable polyols, and organosilanes for defoamer production. Single-source vulnerability in Asian organosilane supply creates concentration risk. Distribution runs through multinational paint manufacturer headquarters procurement with centralized specification authority displacing regional distributor technical sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from integrated resin-additive platforms bundling waterborne packages at compressed margins, requiring defensive repositioning around bio-based certification and captive formulation intelligence tools.
For Market Incumbents: Pre-empt displacement by integrated suppliers through backward integration into bio-based feedstock cultivation partnerships in North American agricultural zones and certification pre-investment ahead of ECHA REACH phase-down deadlines. Anchor specification stickiness via cloud-based formulation platforms that embed additive packages into customer R&D workflows. Prioritize silicone surface modifier capacity in Germany to defend automotive clearcoat positioning against resin-integrated competitors. For New Entrants and Emerging Players: Mid-market waterborne conversions in India's Gujarat and Tamil Nadu industrial corridors represent the most penetrable entry point, as PLI scheme incentives pull coating capacity toward domestic manufacturing without entrenched supplier relationships. Electronics manufacturing facilities in China's Yangtze River Delta offer secondary white-space for rapid-cure polyurethane additives. Pursue specification-through-service model deploying localized formulation chemists rather than competing on resin integration scale. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulation service providers in North American architectural segments that have assembled digital specification platforms but lack bio-based chemistry portfolios. Long-term viability rests on regulatory tailwinds persisting across multiple jurisdictions simultaneously. Monitor ECHA REACH enforcement variance between German automotive clusters and Southern European industrial coatings as early signal of geographic margin dispersion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captive supply of soybean and castor oil derivatives insulates margin from agricultural commodity swings. |
| Digital Specification Platform Deployment | Cloud-based formulation tools embed additive packages into customer R&D workflows, displacing distributor technical sales. |
| REACH Certification Pre-Investment | Early ECHA compliance locks in automotive OEM specification windows ahead of phase-down deadlines. |
| Regional Capacity Expansion in India | Gujarat and Tamil Nadu additive production captures PLI-scheme coating capacity migration. |
| Silicone-Polyether Hybrid R&D Partnership | Collaboration with Italian flooring manufacturers addresses EU F-Gas surfactant substitution requirements. |
Study Parameters
Desk research of customs trade data, SEC chemical company filings, and ECHA REACH registration databases preceded structured interviews with automotive OEM paint shop engineers, architectural coatings procurement leads, and specialty chemical distribution channel managers. Primary fieldwork with formulation chemists at German automotive Tier-1 suppliers and Chinese electronics manufacturing facilities validated waterborne conversion timelines. Secondary sources included Cefic industry statistics, EPA VOC regulatory filings, and NMPA green building code documentation. Bottom-up additive consumption estimates triangulated against top-down coating production forecasts.
Forecast assumptions held ECHA REACH phase-down enforcement, EPA sub-100 g/L VOC mandates, and China NMPA green building code alignment as fixed regulatory baselines, while varying bio-based feedstock cost trajectories and automotive waterborne conversion acceleration rates across sensitivity scenarios. Segmentation modeling spanned resin chemistry tier, end-use industry, formulation technology type, and regional production cluster. CAGRs derived from additive loading rates per liter of coating applied, cross-referenced with end-use production volume projections and regulatory-driven substitution elasticities. Industry-specific inputs included automotive paint shop flash-off cycle constraints and silicone defoamer performance benchmarking against solvent-borne equivalents.
Practitioners should monitor ECHA enforcement variance, bio-based feedstock commodity indices, and automotive OEM qualification cycle completion rates for early signals of forecast deviation. Material shifts in EU F-Gas Regulation scope expansion or REACH authorization list additions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Glass Additives Market
Additives
Hydroxyethyl Cellulose Market
Additives
United States Betaine Market
Additives
Global Low-Profile Additive Market
Additives
Tricalcium Citrate Market
Additives
Nucleotide Premix Market
Additives
Performance Minerals Additives Market
Additives
Asia-Pacific Water Enhancer Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Plastic Fillers Market
Additives
Biofuel Additives Market
Additives
Micronized Powder Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Coating Additives Market
Additives
Global Cement and Concrete Additives Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market