
 Fluid Loss Additives Market | 2026-2036
Fluid Loss Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Loss Additives Market Analysis
A shift from single-source to multi-source procurement is hardening across the fluid loss additives supply base. Halliburton leverages its integrated well services platform to bundle additive sales with drilling contracts. BASF SE anchors European supply through its specialty chemicals division, while Kemira competes on pulp-and-paper crossover chemistry adapted for oilfield brines.
Fluid loss additives are specialty chemicals—typically synthetic polymers, modified starches, or cellulose derivatives—that form a low-permeability filter cake on permeable formations to prevent liquid phase migration from drilling or cementing fluids. They function across temperature ranges exceeding 150°C and salinities above 250,000 ppm total dissolved solids. Synthetic polymers command premium positioning due to thermal stability in high-pressure high-temperature wells, while starch derivatives occupy cost-sensitive onshore applications where biodegradability satisfies discharge rules. The drilling application generates the largest volume pull, though cementing additives yield wider margins per kilogram because of lower price elasticity on critical well integrity jobs.
The EPA regulates drilling fluid discharge under the Clean Water Act and National Pollutant Discharge Elimination System permits, pushing operators toward less toxic additive packages. REACH registration requirements in Europe constrain import of unregistered polymeric additives, creating compliance barriers for non-EU manufacturers. Stakeholders must monitor how OSHA's updated silica exposure limits and emerging state-level PFAS restrictions reshape formulation choices before committing capital to new production lines.
Market Dynamics
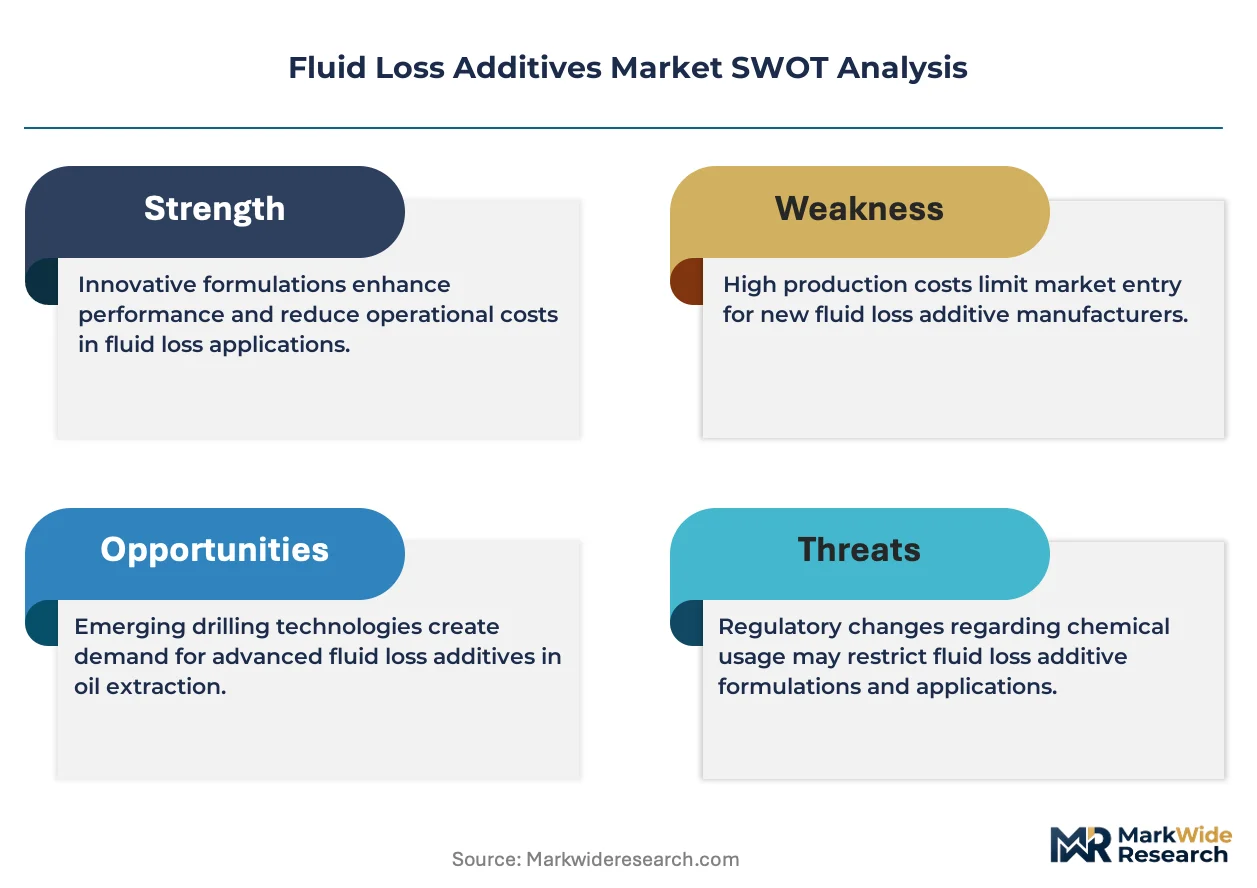
Deep well complexity is fragmenting additive specifications as operators push past 150°C bottom-hole temperatures and 250,000 ppm salinity thresholds, forcing polymer suppliers to abandon universal formulations for well-specific chemistry packages.
Growth Catalysts
- REACH chemical registration:European operators must document polymer safety profiles, creating certified supply lanes for compliant manufacturers and locking out unregistered imports.
- Permian Basin drilling intensity:Texas operators consume starch-based additives at scale where biodegradability satisfies discharge permits under EPA Clean Water Act oversight.
- Synthetic polymer thermal stability:HPHT well construction in Middle Eastern offshore fields requires thermal resistance above 200°C, pulling premium chemistry volumes.
Market Restraints
- Petrochemical feedstock volatility:Acrylamide and acrylic acid monomer costs swing with crude oil indices, compressing margin predictability for polymer manufacturers.
- Supplier concentration in Gulf Coast:Bulk starch derivative production clusters along Texas-Louisiana chemical corridors, exposing buyers to hurricane-related supply interruptions.
- Biodegradability-performance tradeoff:Cellulose derivatives degrade faster than synthetics but fail above 120°C, limiting deployment in deep gas wells.
Strategic Opportunities
- EPA drilling waste rules:Stricter cuttings discharge standards push operators toward water-based mud systems with certified biodegradable additives.
- Carbonate reservoir cementing:Middle Eastern sour gas fields require specialized fluid loss control for primary cement jobs, opening high-margin specialty chemical niches.
- Modular chemistry platforms:Suppliers can configure additive packages from standardized polymer building blocks, reducing inventory SKUs while accelerating well-specific formulation.
Industry Challenges
- Formulation chemist scarcity:Oilfield polymer expertise concentrates among aging specialists, constraining R&D velocity for next-generation thermal stabilizers.
- REACH registration timelines:Polymer substance dossiers require 18-24 month ECHA review cycles, delaying market entry for novel biodegradable chemistries.
- Legacy mud system integration:New additives must demonstrate compatibility with established barite-weighted formulations without requiring full fluid replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Loss Additives Market |
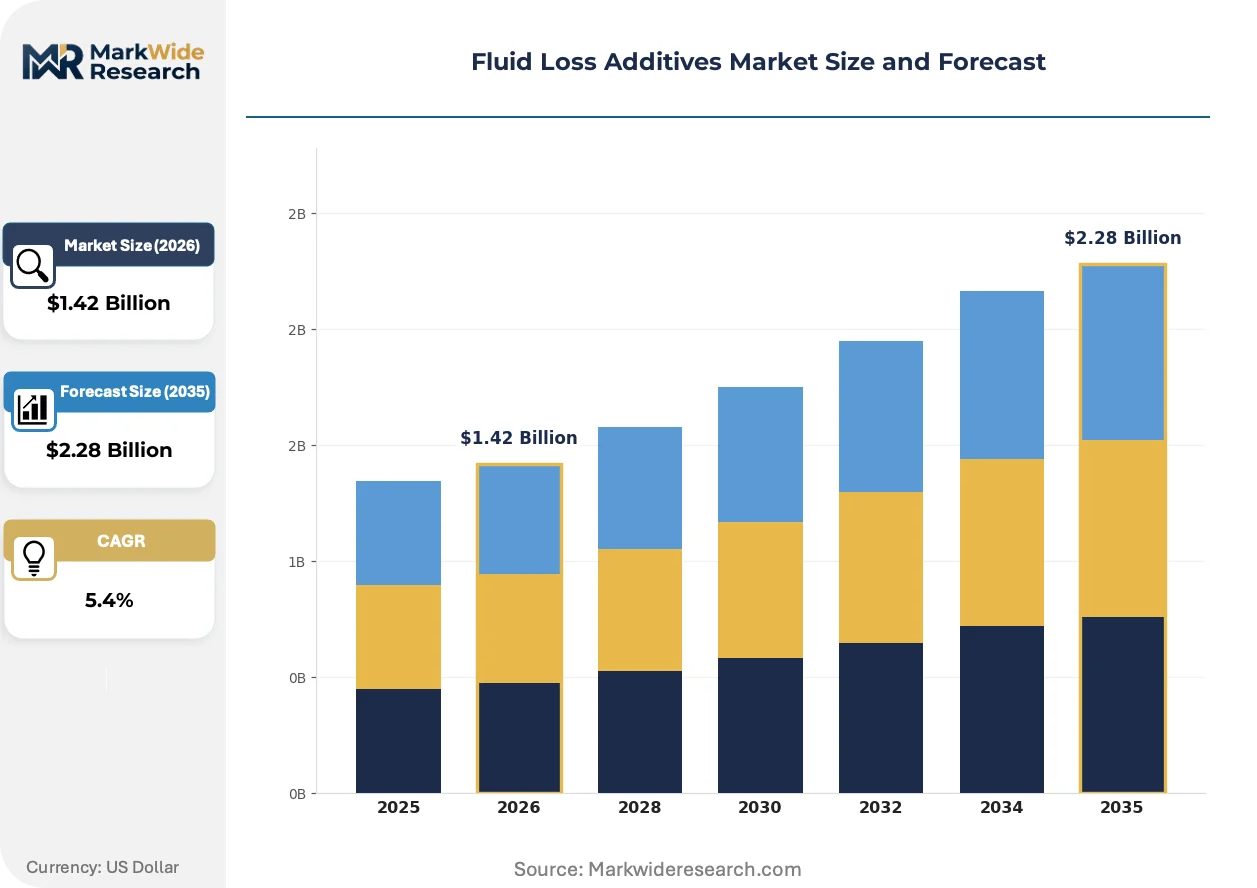
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Polymers, Starch Derivatives, Cellulose Derivatives, Natural Gums End User: Oil & Gas, Construction, Agriculture, Mining Form: Powder, Liquid, Emulsion, Granule Application: Cementing, Drilling, Grouting, Coating |
| Companies Covered | Solvay, Global Drilling Fluids and Chemicals Limited, Halliburton, Baker Hughes, Newpark Resources, Schlumberger Limited, BASF SE, Kemira, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Loss Additives Market Emerging Trajectories
Polymer architecture is evolving from single-function additives to multi-mechanism systems that simultaneously control fluid loss, viscosity, and shale inhibition, compressing the number of products operators must stock at remote well sites.
Crosslinked polyacrylamide microgels is absorbing formation damage risk in tight gas reservoirs by forming deformable filter cakes that fracture cleanup fluids can penetrate more readily than rigid conventional cakes. Appalachian shale operators are piloting these systems in Marcellus completions where formation permeability sits below 0.1 millidarcy. The technology is absorbing market share from traditional starch-cellulose blends in pressure-sensitive formations.
REACH authorization requirements are forcing reformulation of polyacrylamide-based additives as ECHA scrutinizes residual acrylamide monomer content in oilfield chemicals. European mud service companies are accelerating substitution with polyanionic cellulose and grafted starch alternatives to avoid authorization delays. The regulatory pressure is compressing synthetic polymer margins in EU-contracted drilling programs.
Integrated supply contracts are consolidating procurement decisions as operators bundle additive purchasing with directional drilling and logging services under single-vendor agreements. This model displaces spot purchasing through independent chemical distributors in North American land markets. The shift is most visible in Permian Basin operations where pad drilling economics favor simplified vendor management.
Fluid Loss Additives Market Segmentation
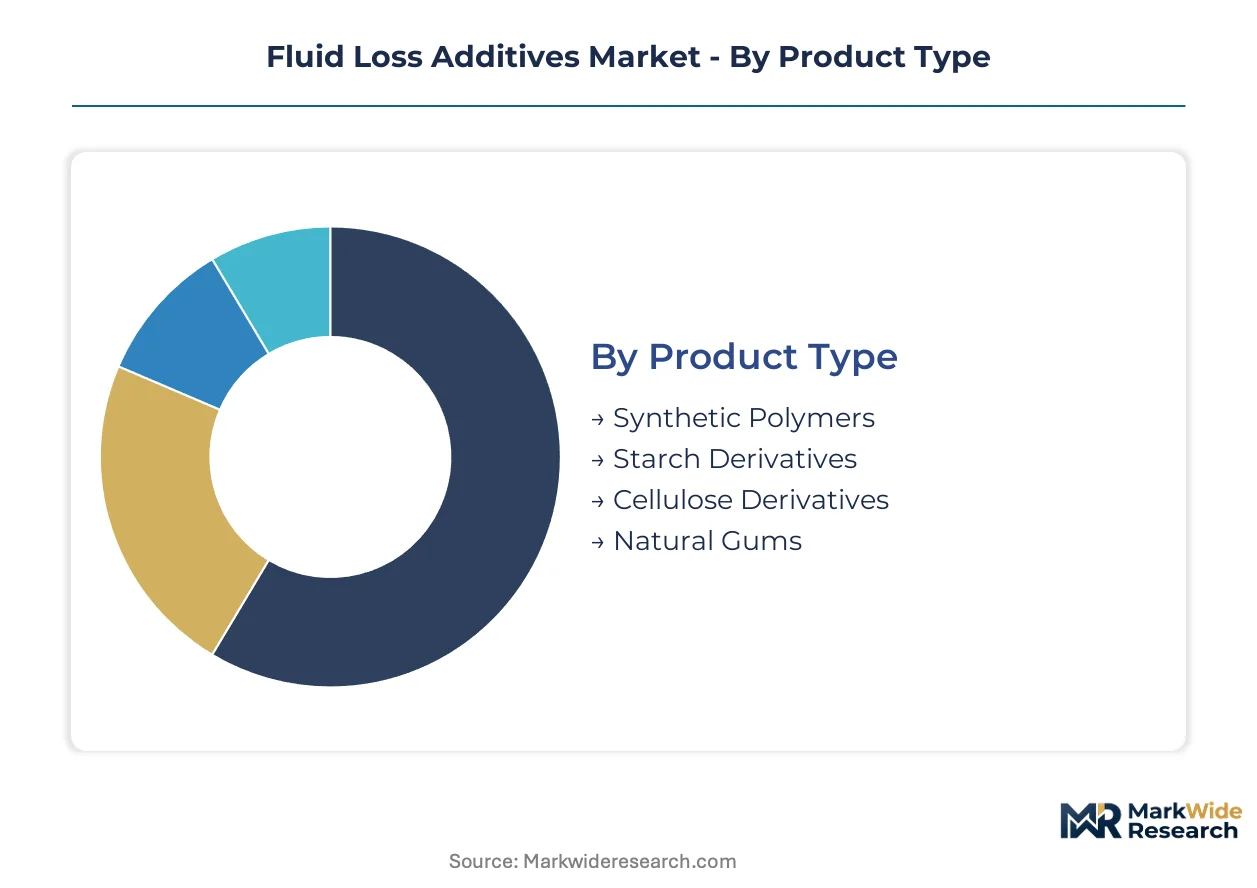
Fluid loss additives serve distinct performance requirements across well construction phases, driving suppliers to align product architectures with thermal stability thresholds and discharge compliance timelines. Segmentation reveals how polymer chemistry, physical form, and end-use specifications fragment procurement decisions across drilling and cementing operations.
Product Type:
Replacement cycles accelerate as operators abandon universal formulations for well-specific chemistry packages matched to bottom-hole temperature and salinity profiles.
- Synthetic Polymers:Crosslinked polyacrylamide microgels deliver thermal resistance above 200°C in Middle Eastern offshore HPHT wells. Premium positioning reflects acrylamide monomer costs and REACH registration compliance burdens for European supply.
- Starch Derivatives:Modified starches from corn and potato sources dominate Permian Basin onshore drilling where biodegradability satisfies EPA Clean Water Act discharge permits. Cost sensitivity limits deployment to formations below 150°C.
- Cellulose Derivatives:Polyanionic cellulose and carboxymethyl cellulose bridge mid-range thermal requirements up to 120°C.
- Natural Gums:Guar and xanthan gum formulations serve specialized grouting applications in construction and mining sectors.
Synthetic polymers sit at the top of the volume ranking, with starch derivatives climbing the fastest as biodegradability mandates expand.
End User:
Customer procurement scale varies sharply between integrated oilfield service companies and fragmented construction material distributors.
- Oil & Gas:Drilling contractors and mud service companies consume bulk volumes across shale plays and deepwater frontiers. Integrated supply contracts bundle additive purchasing with directional drilling services, displacing spot purchasing in North American land markets.
- Construction:Cement and concrete producers specify fluid loss control for grouting and coating applications where workability retention drives formulation choices.
- Agriculture:Irrigation system sealants and soil conditioning products absorb small specialty volumes.
- Mining:Tailings management and borehole stabilization in underground operations create niche demand for high-viscosity additive packages.
Oil & Gas anchors absolute consumption, with Construction expanding most quickly as infrastructure investment accelerates in Middle Eastern and Asian markets.
Form:
Physical state determines logistics economics and field blending compatibility with established barite-weighted mud systems.
- Powder:Dry granular formulations dominate bulk shipments to remote well sites where shelf stability and transport density reduce logistics costs. Dust exposure concerns are reshaping handling protocols under OSHA silica limits.
- Liquid:Pre-hydrated polymer solutions accelerate mixing at offshore platforms where deck space constraints favor pump-ready delivery.
- Emulsion:Oil-external dispersions serve specialized applications requiring delayed hydration in high-salinity brines.
- Granule:Low-dust agglomerated products address occupational health requirements in European-contracted drilling programs.
Powder maintains volume leadership, with Liquid gaining share fastest in offshore supply chains.
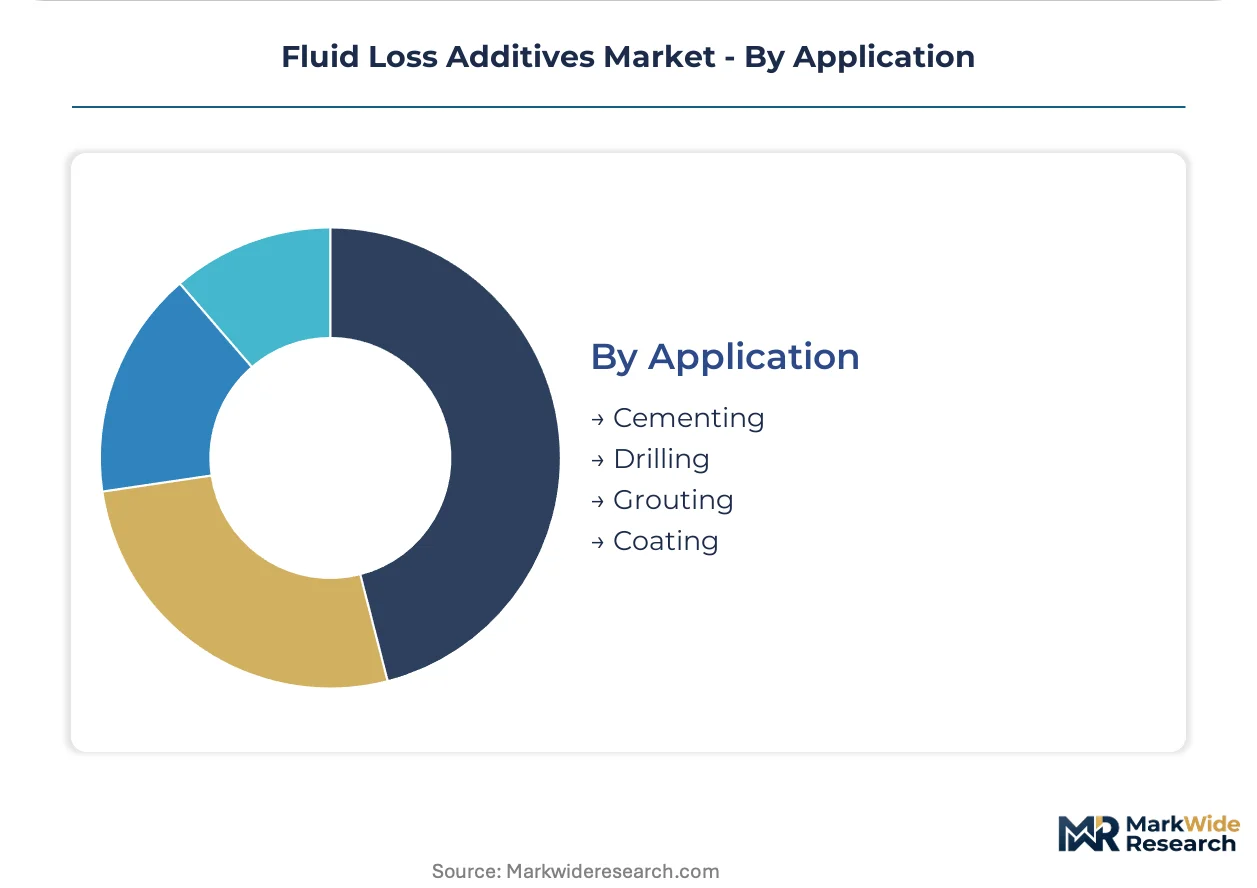
Application:
Performance specifications diverge between temporary filtration control in drilling and permanent barrier integrity in cementing.
- Cementing:Primary and remedial cement jobs demand specialized fluid loss control to prevent gas migration and zonal isolation failure. Sour gas fields in carbonate reservoirs command premium chemistry margins due to low price elasticity on critical well integrity.
- Drilling:Water-based and synthetic-based mud systems consume the largest additive volumes across temperature ranges exceeding 150°C and salinities above 250,000 ppm total dissolved solids.
- Grouting:Construction and mining applications require viscosity stability in pumped slurries for ground stabilization and tunnel support.
- Coating:Protective layer formulations in infrastructure projects absorb minor specialty volumes.
Drilling generates the largest volume pull, with Cementing yielding the widest margins per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers seek jurisdictions with streamlined chemical registration pathways. Compliance cost differentials between REACH-registered European supply and EPA-permitted US operations are redirecting capital toward Gulf Coast chemical corridors.
United States
Permian Basin drilling intensity consumes starch-based additives at scale, with Texas operators prioritizing biodegradable formulations to satisfy EPA Clean Water Act discharge permits. OSHA's updated silica exposure limits are reshaping handling protocols at bulk powder facilities. Houston anchors domestic supply chain concentration, with Louisiana chemical corridors providing captive monomer feedstock for synthetic polymer production.
Germany
REACH registration requirements constrain import of unregistered polymeric additives, creating certified supply lanes for compliant manufacturers. ECHA scrutiny of residual acrylamide monomer content is accelerating reformulation toward polyanionic cellulose alternatives. BASF SE's Ludwigshafen headquarters anchors European specialty chemicals distribution for oilfield applications.
Saudi Arabia
Middle Eastern offshore HPHT well construction demands thermal resistance above 200°C, pulling premium synthetic polymer volumes. SFDA chemical safety standards align with Gulf regulatory harmonization initiatives. Eastern Province industrial cities concentrate additive blending operations serving sour gas fields in carbonate reservoirs.
China
Domestic shale development in Sichuan Basin is expanding water-based mud consumption with locally sourced starch derivatives. MEE environmental discharge rules are tightening biodegradability requirements for drilling waste. Yangtze River Delta chemical parks host integrated polymer production serving both domestic oilfield demand and export markets.
Brazil
Pre-salt deepwater drilling programs require fluid loss control compatible with high-salinity formation brines. ANVISA chemical registration creates compliance barriers for unregistered imports, favoring established suppliers with local technical presence. Rio de Janeiro serves as procurement hub for offshore contractor fleets operating Campos and Santos basins.
Fluid Loss Additives Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular chemistry platforms and regional blending partnerships. The supply base exhibits moderate consolidation, with integrated oilfield service companies bundling additive sales with drilling contracts alongside independent specialty chemical manufacturers. Three archetypes dominate: vertically integrated energy service conglomerates, diversified chemical multinationals with oilfield divisions, and regional blenders with logistics advantages. Competitive moves center on REACH registration pre-positioning in Europe and hurricane-resilient supply chain diversification along Gulf Coast corridors.
Among diversified chemical multinationals, BASF SE and Kemira exemplify the pulp-and-paper crossover strategy, adapting established polymer chemistry for oilfield brine compatibility. Halliburton represents the integrated service model, leveraging well services platforms to bundle additive procurement with directional drilling contracts. These three anchors illustrate how competitive positioning diverges between chemistry-centric and service-centric value capture approaches.
| Leading Market Players |
|---|
| Solvay |
| Global Drilling Fluids and Chemicals Limited |
| Halliburton |
| Baker Hughes |
| Newpark Resources |
| Schlumberger Limited |
| BASF SE |
| Kemira |
| Clariant |
| Others |
Supply Flow & Price Mechanics
Integrated oilfield service companies concentrating procurement decisions through bundled drilling contracts enforce project-based pricing with volume-scaled discounts, compressing spot-market premiums for independent additive distributors serving smaller Permian Basin operators.
Pricing Analysis
Distributor margins absorb the primary pricing pressure as Halliburton and Schlumberger negotiate direct-to-OEM discounts that bypass independent chemical channels. Three-tier pricing structure across premium synthetic polymers, standard starch derivatives, and economy cellulose grades reflects thermal stability certification and REACH registration status. Cost compression in synthetic polymer tiers stems from acrylamide monomer volatility tracking crude indices. Spot purchasers in construction and mining segments exhibit highest price sensitivity, while cementing contractors for sour gas fields show lowest elasticity due to well integrity requirements.
Supply Chain Analysis
REACH registration and EPA discharge permitting create dual-certification gating that fragments qualified supplier pools between European and North American supply lanes. Production concentrates in the United States, Germany, and China, with Gulf Coast chemical corridors hosting captive acrylamide feedstock for synthetic polymer output. Raw material dependencies center on corn and potato starch for biodegradable grades, acrylic acid monomers for thermal-resistant synthetics, and specialty cellulose pulps for mid-range applications. Single-source vulnerability runs through Louisiana-Texas starch derivative clusters exposed to hurricane disruption. Distribution runs through integrated service company logistics networks for oilfield demand, with construction and mining sectors served by regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH registration timelines and EPA discharge compliance costs create divergent capital efficiency between European and North American production footprints.
For Market Incumbents: Acquire modular chemistry platform capabilities to compress formulation-to-delivery cycles for well-specific additive packages. Backward integration into acrylamide monomer production insulates margin compression from petrochemical feedstock volatility. Defensive positioning requires pre-positioning polymer substance dossiers with ECHA before authorization deadlines lock out reformulated alternatives. For New Entrants and Emerging Players: Launch via regional blending partnerships in Eastern Province industrial cities serving Saudi sour gas fields where premium cementing additive demand outpaces qualified supply. White-space targets include carbonate reservoir specialty formulations and low-dust granule formats for European-contracted drilling programs. Construction sector grouting applications in Middle Eastern infrastructure markets offer penetrable entry points with lower certification barriers than oilfield drilling. For Investors and Strategic Acquirers: Integrated oilfield service companies are the most active acquirer in this space, pursuing additive manufacturers to deepen well services bundling. Long-term viability hinges on biodegradable polymer R&D pipelines aligned with tightening discharge regulations across multiple geographies. Acquisition target archetypes include regional blenders with hurricane-resilient logistics and REACH-registered European specialty chemical divisions. Watch for ECHA authorization delays on residual acrylamide content as signal for accelerated substitution demand toward cellulose and starch alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Pre-Positioning | Locks in certified supply lanes before ECHA authorization deadlines constrain polymer import. |
| Backward Integration into Monomer Production | Captive acrylamide supply insulates synthetic polymer margins from crude index volatility. |
| Modular Chemistry Platform Development | Standardized polymer building blocks reduce inventory SKUs while accelerating well-specific formulation. |
| Regional Blending Partnership in Gulf States | Eastern Province facilities capture premium cementing volumes in Saudi sour gas fields. |
| Biodegradable Formulation R&D Investment | Polyanionic cellulose alternatives align with EPA Clean Water Act discharge permit tightening. |
Methodological Framework
Direct dialogue with drilling fluid engineers, mud service company procurement directors, polymer R&D chemists, and ECHA regulatory consultants grounded qualitative insights in operational realities. Secondary validation drew from EPA Clean Water Act discharge permit databases, ECHA substance dossier filings, SEC 10-K disclosures from integrated service companies, and customs trade data tracking acrylamide monomer flows. Bottom-up additive volume estimates triangulated against top-down oilfield chemical spending patterns.
Bottom-up modeling built product-type and application-level forecasts across the analysis window, with segmentation across synthetic polymer, starch derivative, and cellulose chemistry tiers. End-use splits between drilling, cementing, and construction applications incorporated thermal stability thresholds and biodegradability compliance timelines. CAGRs derived from well count projections in Permian Basin and Middle Eastern offshore plays, weighted by HPHT well penetration rates and water-based mud system adoption curves.
Several conditions sit outside the modeled scope, including abrupt REACH authorization revocations, hurricane-induced Gulf Coast supply disruptions, and breakthrough non-polymer fluid loss technologies. Forecasts reflect assumptions about regulatory enforcement continuity and petrochemical feedstock price band stability. A model refresh is warranted upon material change in EPA drilling waste rule stringency or ECHA polymer substance review timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Adjustive Agents Market
Additives
Hexyl Acetate Market
Additives
Tamarind Gum Derivatives Market
Additives
Maltitol Based on Corn Starch Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Global Feed Acidifiers Market
Additives
Metal Modifiers Market
Additives
Additives for Metalworking Fluids Market
Additives
Global Anti-Fog Additives Market
Additives
Feed Additives Market
Additives
Organic Friction Modifier Additives Market
Additives
Global Calcium Formate Market
Additives
North America Phosphate Esters Market
Additives
Isopropyl Acetate Market
Additives
Sorbitan Esters Market
Additives
Global Lubricating Oil Additives Market