
 Propylene Market | 2026-2036
Propylene Market Size, Share, and Industry Trends Forecast 2026-2036
Propylene Market Outlook
The split between polymer-grade and chemical-grade propylene is recalibrating contract structures and margin allocation across the value chain. SABIC leverages its fully integrated Saudi feedstock position to sustain cost leadership in Asian polypropylene deliveries. INEOS anchors European supply through its North Sea cracker network and pipeline connectivity to downstream derivatives.
Propylene is a three-carbon olefin hydrocarbon produced primarily via steam cracking of naphtha or fluid catalytic cracking of refinery gases, with polymer-grade material exceeding 99.5% purity for polypropylene synthesis. Its primary industrial purpose centers on conversion into plastics, synthetic rubbers, and chemical intermediates that underpin packaging, automotive, and construction end-uses. Polypropylene dominates product-type value capture due to its ubiquity in automotive parts and packaging films, while propylene oxide represents the fastest-expanding derivative segment driven by polyurethane feedstock demand. Application-level demand in plastics concentrates margin pools with converters serving consumer goods and electronics end users.
The EPA enforces air emissions standards for US olefin production facilities under the Clean Air Act, while REACH and the EU Green Deal impose carbon-intensity disclosure requirements on European propylene importers and derivative manufacturers. China's MEE enforces dual carbon compliance timelines that reshape investment priorities for new steam cracker capacity. Stakeholders must monitor regulatory divergence between carbon-border-adjustment regimes and domestic emissions-trading systems to anticipate cost pass-through mechanics and sourcing relocation.
Market Dynamics
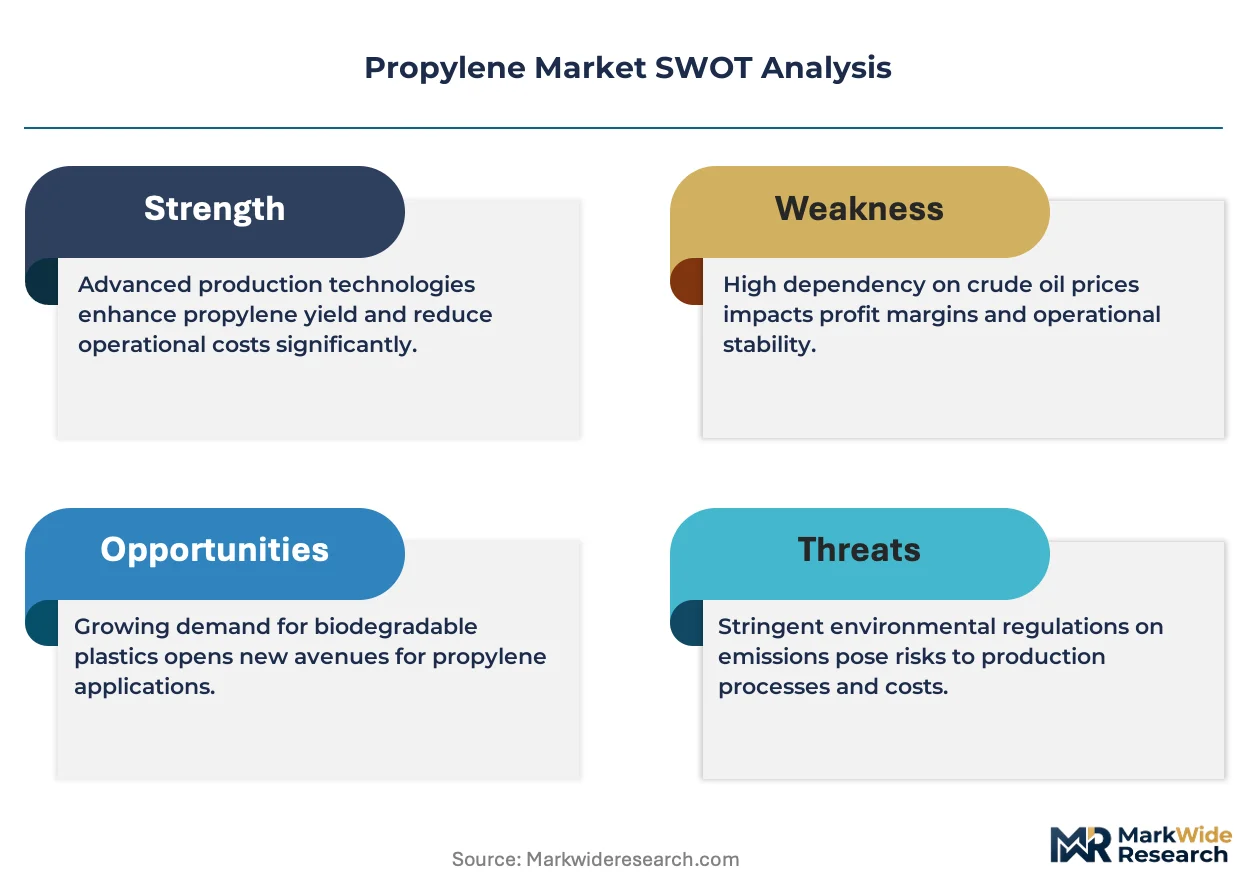
Steam cracker operators face mounting pressure from China's MEE dual carbon compliance timelines and the EU Green Deal carbon-intensity disclosure mandates, forcing capital reallocation toward lower-emission propylene production routes.
Growth Catalysts
- Automotive Lightweighting Mandates:Polypropylene demand from vehicle interior and exterior component programs is intensifying procurement volumes across integrated refining-petrochemical complexes.
- REACH Carbon-Intensity Disclosure:European importers and derivative manufacturers must document supply chain emissions, creating preferential sourcing for low-carbon propylene routes.
- Propylene Oxide Derivative Expansion:Polyurethane feedstock demand is accelerating chemical-grade propylene consumption in construction insulation and appliance manufacturing.
Market Restraints
- Naphtha Feedstock Volatility:Steam cracking economics remain exposed to crude oil price swings and refinery output fluctuations.
- Middle Eastern Supply Concentration:Fully integrated Saudi feedstock positions dominate Asian polypropylene deliveries, limiting pricing leverage for regional buyers.
- Propane Dehydrogenation Yield Limits:Technical constraints on catalyst selectivity cap conversion efficiency in on-purpose propylene production.
Strategic Opportunities
- India Petrochemical Investment Corridor:PLI scheme incentives and refining capacity expansions create greenfield opportunities for integrated propylene-polypropylene complexes.
- Bio-Based Propylene Routes:Renewable naphtha and bio-propane pathways align with EU Green Deal procurement preferences and brand sustainability commitments.
- Recycled Polypropylene Uptake:Mechanical and chemical recycling infrastructure investments open circular economy revenue streams for polymer-grade material.
Industry Challenges
- Process Control Engineering Shortage:Advanced automation and digital twin deployment for steam cracker optimization outpaces available specialist talent pools.
- EPA Clean Air Act Compliance:US olefin production facilities face continuous emissions monitoring upgrades and Best Available Control Technology retrofit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propylene Market |
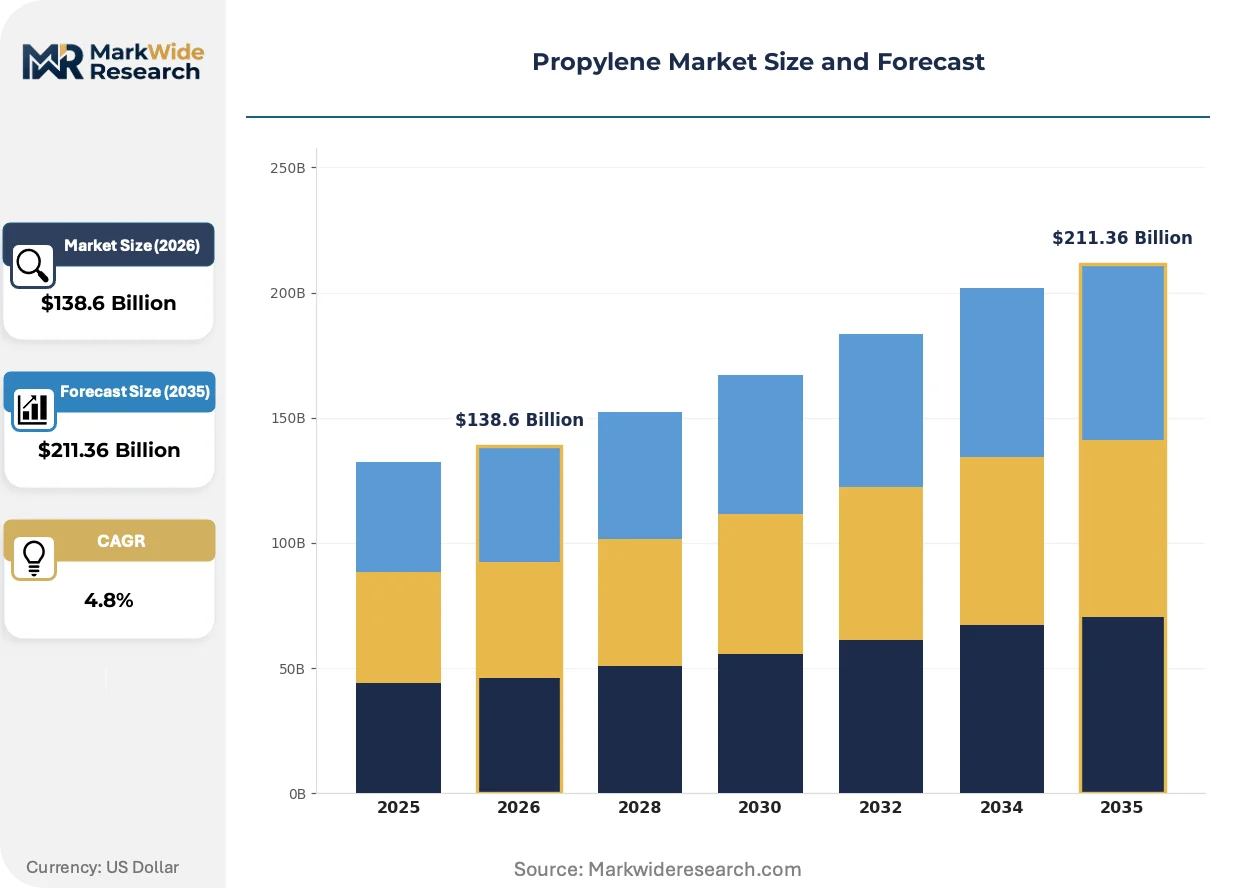
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $211.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Acrylonitrile, Propylene Oxide, Isopropanol Application: Textiles, Automotive Parts, Packaging, Plastics End User: Construction, Consumer Goods, Automotive, Electronics Manufacturing Stage: Upstream, Midstream, Downstream, Refining |
| Companies Covered | SABIC, INEOS, MOLGROUP, Braskem, Repsol, Formosa Plastics Corporation, Exxon Mobil Corporation, Borealis, LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propylene Market Strategic Shifts
Propylene production technology is bifurcating between conventional steam cracking optimization and on-purpose route commercialization, with regulatory carbon accounting driving investment toward lower-emission alternatives.
Electrified steam cracking is electrifying traditional naphtha pyrolysis by replacing fuel-fired furnaces with resistive heating elements. BASF and SABIC pilot installations demonstrate 90% CO2 reduction potential. Automotive suppliers sourcing polypropylene for electric vehicle battery housings are electrifying their material qualification priorities toward low-carbon certification tiers.
REACH and the EU Green Deal impose binding carbon-intensity disclosure requirements on European propylene importers and derivative manufacturers. Compliance costs are restructuring contract negotiations toward long-term offtake agreements with certified low-emission suppliers. Polypropylene converters serving packaging and consumer goods end-uses face the steepest documentation burdens.
Buyer concentration among integrated automotive tier-one suppliers is compressing polypropylene procurement cycles and demanding real-time inventory visibility. Direct mill relationships are displacing traditional distributor intermediaries in high-volume automotive programs. Eastern China's refining-petrochemical clusters exhibit the most pronounced channel consolidation.
Propylene Market Segmentation
Propylene market segmentation reveals how margin pools distribute across derivative chemistry, application durability requirements, and supply chain positioning. Buyers select grades based on purity specifications and conversion economics, while producers optimize output mix against regional demand concentration.
Product Type:
Cost tier determines procurement patterns, with converters weighing feedstock flexibility against specification rigidity.
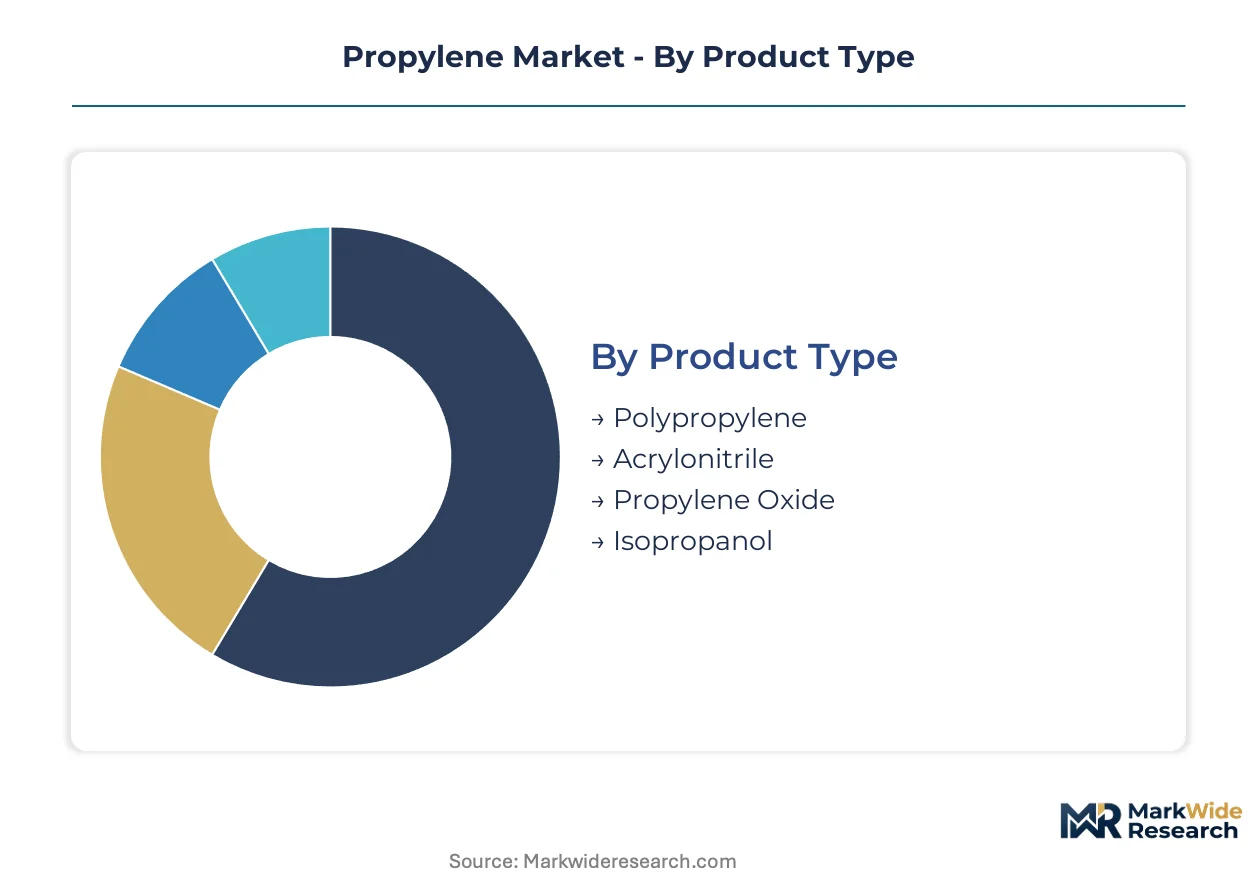
- Polypropylene:Polymer-grade propylene exceeding 99.5% purity yields isotactic polypropylene for injection-molded automotive interior panels and biaxially oriented packaging films. Demand concentrates in eastern China's integrated refining-petrochemical complexes serving automotive lightweighting programs.
- Propylene Oxide:Chemical-grade material feeds polyurethane precursor production for construction insulation and appliance foams. Consumption is climbing the fastest in Asia-Pacific manufacturing bases where polyurethane feedstock demand outpaces regional supply.
- Acrylonitrile:Acrylic fiber and ABS resin precursor serving textile and electronics applications.
- Isopropanol:Solvent and disinfectant intermediate with pharmaceutical and industrial cleaning end-uses.
Volume sits with Polypropylene; growth tilts toward Propylene Oxide.
Application:
Application durability requirements separate commodity procurement from performance-grade contracting.
- Automotive Parts:Interior trim, bumper fascias, and battery housings demand high-flow polypropylene grades with talc or glass reinforcement. Procurement is intensifying across tier-one supplier direct mill relationships in Germany and China.
- Packaging:Flexible films, rigid containers, and caps/closures utilize random and impact copolymer grades. Specifications tighten around EU Green Deal carbon-intensity disclosure requirements for imported material.
- Plastics:General-purpose molding and extrusion applications across consumer goods and industrial components.
- Textiles:Acrylic fiber production for apparel and industrial fabrics via acrylonitrile derivatives.
Automotive Parts commands premium contract structures; Packaging shows the steepest expansion trajectory on sustainability-driven material substitution.
End User:
Customer type dictates volume scale and technical service intensity.
- Automotive:OEM-directed polypropylene specifications for exterior and under-hood components require real-time inventory visibility and just-in-sequence delivery. Procurement cycles compress as electric vehicle platforms multiply material qualification requirements.
- Construction:Propylene oxide-derived polyurethane insulation dominates thermal envelope applications in EU energy efficiency retrofits and North American residential building.
- Consumer Goods:Packaging and durables manufacturers face REACH documentation burdens for supply chain emissions disclosure.
- Electronics:ABS resins and specialty polymers for device housings and components.
Construction anchors volume throughput; Electronics is gaining share fastest on miniaturization and 5G infrastructure material demand.
Manufacturing Stage:
Supply concentration varies by vertical position, with margin capture shifting downstream.
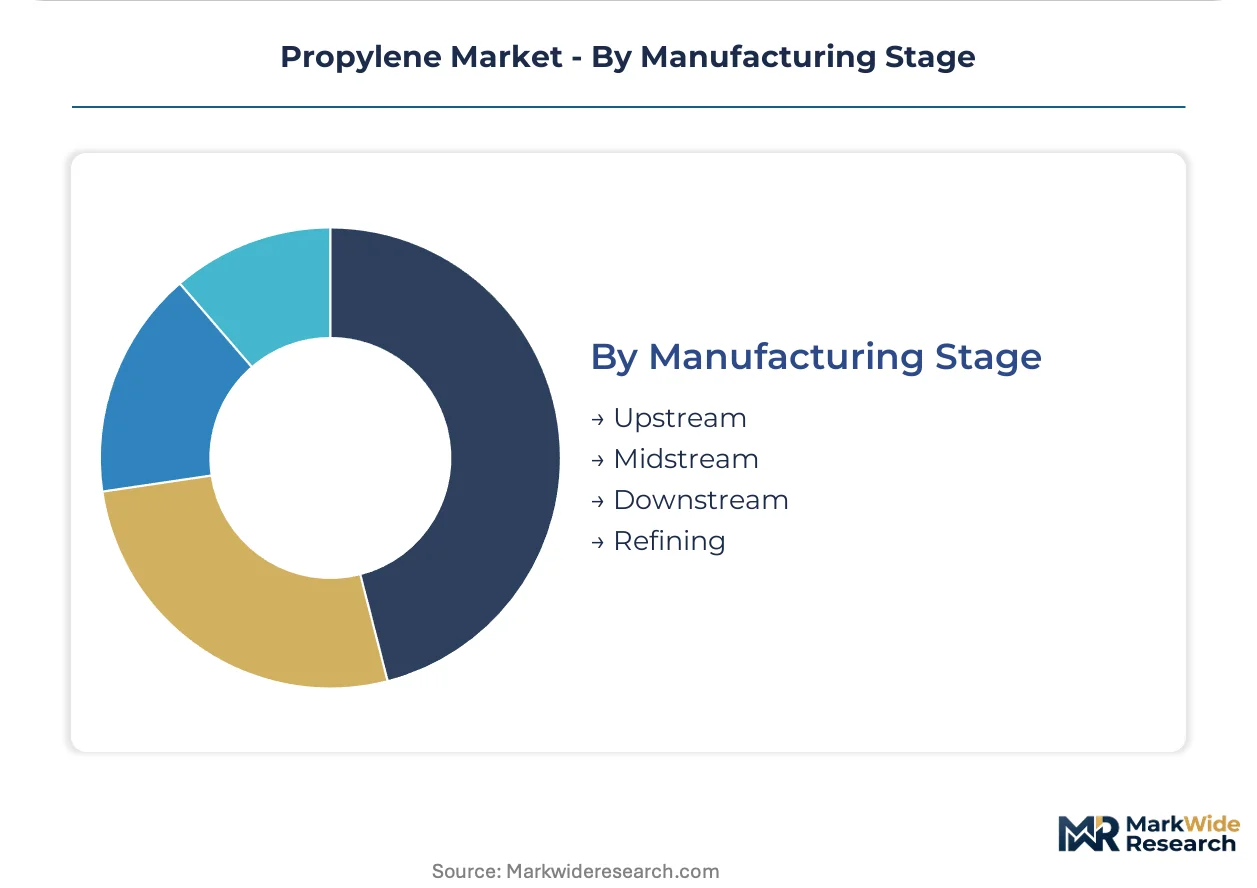
- Refining:Fluid catalytic cracking units at integrated complexes in Saudi Arabia and the US Gulf Coast produce refinery-grade propylene as byproduct. SABIC leverages captive feedstock for cost leadership in Asian polypropylene deliveries.
- Downstream:Polymerization and derivative conversion capture value-added margin pools with converters serving consumer goods and automotive end users.
- Upstream:Naphtha and propane feedstock production and logistics.
- Midstream:Pipeline distribution and storage infrastructure linking production to derivative facilities.
Refining concentrates upstream supply; Downstream claims expanding margin share on differentiation and certification services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo-Zhoushan anchors the world's densest propylene-polypropylene production corridor, with integrated refining-petrochemical complexes feeding automotive lightweighting programs across eastern China's manufacturing belt.
China
Dual carbon mandates from MEE are forcing steam cracker retrofits in Zhejiang and Jiangsu provinces. Yangzi Petrochemical's Nanjing complex exemplifies the shift toward electrified cracking pilots. Procurement from these clusters now requires documented carbon-intensity disclosures for EU-bound polypropylene exports.
United States
Gulf Coast propane dehydrogenation units are expanding to capture chemical-grade propylene demand from polyurethane insulation markets. EPA Clean Air Act enforcement is tightening emissions monitoring at Texas and Louisiana olefin facilities. The Houston Ship Channel corridor concentrates new PDH capacity announcements from 2024-2026.
Germany
REACH carbon-intensity disclosure requirements are restructuring contract negotiations for imported propylene derivatives. BASF's Ludwigshafen complex pilots electrified steam cracking with SABIC partnership backing. Automotive tier-one suppliers in Baden-Württemberg now mandate real-time inventory visibility from polypropylene converters.
Saudi Arabia
Fully integrated feedstock positions at Jubail Industrial City sustain cost leadership in Asian polypropylene deliveries. SABIC leverages captive ethane and naphtha supply to undercut regional competitors on delivered pricing. The kingdom's downstream expansion targets specialty chemicals to diversify beyond commodity polymer exports.
India
PLI scheme incentives are accelerating greenfield propylene-polypropylene complex development along the Gujarat-Maharashtra petrochemical corridor. Reliance Industries' Jamnagar refinery integration exemplifies the scale-driven investment pattern. Demand from automotive and packaging converters in Pune and Ahmedabad is outpacing domestic supply growth.
Propylene Market Competitive Environment
Premium-margin players sit above commodity-margin players across carbon-certification tiers, with low-emission route operators capturing contract premiums from EU automotive and packaging end-users. The vendor base stratifies between fully integrated Middle Eastern suppliers, European pipeline-anchored derivatives specialists, and Asian scale-focused polymer producers. Three archetypes dominate: feedstock-integrated cost leaders, regulation-compliant low-carbon specialists, and downstream-differentiated compounders. Competitive moves concentrate on electrified cracking technology licensing and strategic offtake partnerships for certified-low-carbon material.
Within the feedstock-integrated tier, SABIC anchors cost leadership through its Jubail-based captive supply position. INEOS occupies a pipeline-anchored role across European derivative markets. LyondellBasell Industries exemplifies the scale-focused polypropylene specialist competing on automotive program qualification speed. These three represent distinct strategic positioning vectors without implying specific market share claims.
| Leading Market Players |
|---|
| SABIC |
| INEOS |
| MOLGROUP |
| Braskem |
| Repsol |
| Formosa Plastics Corporation |
| Exxon Mobil Corporation |
| Borealis |
| LyondellBasell Industries |
| Others |
Value Chain & Pricing Dynamics
China's MEE dual carbon compliance timelines gate qualified supply access for steam cracker operators while simultaneously creating premium-tier pricing premiums for certified low-emission propylene routes serving EU automotive and packaging end-users.
Pricing Analysis
Contract-based long-term offtake agreements anchor value-based pricing tied to carbon-intensity certification tiers and polypropylene yield consistency. Price differentiation separates polymer-grade material with REACH documentation from standard refinery-grade supply, with volume scale and geographic delivery cost as secondary drivers. Cost compression in commodity-grade segments is intensifying because Middle Eastern integrated producers leverage captive feedstock positions. Tier-one automotive suppliers exhibit the least price sensitivity due to just-in-sequence qualification requirements, while general-purpose packaging converters face the steepest procurement pressure.
Supply Chain Analysis
Freight cost differentials between Middle Eastern export terminals and Asian manufacturing clusters amplify the competitive advantage of fully integrated Saudi supply positions. Production concentrates in Saudi Arabia, China, and the United States, with naphtha, propane, and refinery off-gas as primary feedstock dependencies. Single-source vulnerability runs through the Strait of Hormuz corridor for Asian-bound polypropylene deliveries. Distribution runs through direct mill relationships displacing traditional distributor intermediaries in high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH carbon-intensity disclosure requirements erect barrier-to-entry moats favoring incumbent operators with documented low-emission production routes.
For Market Incumbents: Lock in long-term offtake agreements with EU automotive tier-one suppliers before certification capacity scarcity tightens contract terms. Prioritize electrified cracking pilot investments in Zhejiang and Jiangsu provinces to defend margin position against emerging bio-based propylene routes. Channel control through direct mill relationships in eastern China limits pricing leverage for regional buyers. For New Entrants and Emerging Players: Automotive tier-two suppliers in India's Gujarat-Maharashtra corridor represent the most penetrable entry point given PLI scheme incentives and domestic supply-demand gaps. Target bio-based propylene qualification partnerships with EU packaging converters facing brand sustainability commitments. White-space exists in chemical recycling infrastructure for circular polypropylene streams serving consumer goods end-users. For Investors and Strategic Acquirers: BASF-SABIC electrified cracking partnership announcements are the leading indicator that technology licensing revenue streams will displace commodity margin capture. Long-term viability centers on operators with backward integration into low-carbon feedstock and certification infrastructure. Acquisition targets should demonstrate proven carbon-intensity documentation capabilities and established automotive qualification pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Cracking Technology Licensing | BASF and SABIC pilots demonstrate 90% CO2 reduction potential for EU-bound supply. |
| Backward Integration into Bio-Based Feedstock | Renewable naphtha pathways align with EU Green Deal procurement preferences. |
| Long-term Supply Agreement with Tier-One Automotive | Direct mill relationships capture just-in-sequence delivery premiums in Germany and China. |
| Joint Venture for Chemical Recycling Infrastructure | Mechanical and chemical recycling opens circular economy revenue streams for polymer-grade material. |
| Capacity Expansion in India's Petrochemical Corridor | PLI scheme incentives accelerate greenfield propylene-polypropylene complex development. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this propylene market assessment. Primary interviews with steam cracker plant managers, polypropylene procurement leads at automotive OEMs, petrochemical distribution channel partners, and technical R&D directors at derivative manufacturers combined with ACC, Cefic, and SEC 10-K validation. Bottom-up capacity modeling and top-down demand triangulation reconciled volume estimates across polymer-grade and chemical-grade segments.
Segment-level granularity modeled propylene by grade tier, end-use industry, regional production hub, and carbon-intensity certification status across the projection horizon. CAGRs derived from production capacity buildout schedules, automotive lightweighting program procurement timelines, and polyurethane feedstock demand trajectories. Forecast inputs incorporated MEE dual carbon compliance timelines and REACH disclosure implementation phases without year-specific assumptions.
Caveats apply where feedstock price volatility, regulatory enforcement delays, or electrified cracking technology scale-up failures could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Propane Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Military Propellants Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Pentaerythritol Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Light Olefins Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Oman Pyrolysis Gasoline Market
Petrochemicals
Aliphatic Hydrocarbon Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Global Perfluorocarbons Market
Petrochemicals
Alkylate Market