
 Rosin Ester Market | 2026-2036
Rosin Ester Market Size, Share, and Industry Trends Forecast 2026-2036
Rosin Ester Market Analytics
Packaging adhesive demand is realigning rosin ester consumption patterns as e-commerce fulfillment drives hot-melt formulation volumes. Eastman Chemical Company leverages backward integration into gum rosin supply chains to secure feedstock consistency across North American operations. Arakawa Chemical Industries Ltd. anchors its position through specialized hydrogenation capabilities that serve Japanese automotive tier-one suppliers. Wuzhou Pine Chemicals Ltd. dominates the upstream gum rosin segment, controlling extraction capacity across southern China's pine forest belt.
Rosin esters are thermoplastic resins produced by esterifying abietic acid and related diterpenoid acids from pine oleoresin, yielding products with softening points between 80°C and 120°C that function as tackifiers, binders, and film-formers across industrial formulations. Modified rosin variants command the widest formulation latitude in pressure-sensitive adhesives, while hydrogenated grades attract premium positioning in food-contact packaging applications governed by FDA and EU migration limits. Esterified rosin competes directly with hydrocarbon tackifiers in rubber compounding, though natural-origin labeling sustains niche preference in cosmetic and personal care emulsions.
EPA regulates rosin ester manufacturing under TSCA Section 5 for new chemical notifications, while REACH requires full SVHC disclosure for imported resin batches entering European adhesive and coatings value chains. China's SAMR enforces GB standards on rosin derivative purity that directly affect export eligibility for domestic refiners. Stakeholders must monitor evolving biobased content certification schemes, as these frameworks increasingly determine qualification for public procurement tenders and corporate sustainability mandates without explicit regulatory compulsion.
Market Dynamics
Hot-melt adhesive formulation demand from e-commerce packaging fulfillment is restructuring rosin ester procurement patterns, pulling hydrogenated grades into food-contact applications while modified variants retain dominance in pressure-sensitive tapes.
Growth Catalysts
- REACH SVHC disclosure mandates:European adhesive and coatings value chains now require full substance transparency for imported resin batches, accelerating supplier qualification programs among compliant refiners.
- GB standards enforcement by SAMR:China's purity thresholds on rosin derivatives directly determine export eligibility, filtering subscale domestic producers from international supply.
- Hot-melt packaging adhesives:Fulfillment center automation is driving specification volumes for rosin ester tackifiers in case-sealing and label-stock applications.
Market Restraints
- Gum rosin feedstock volatility:Pine oleoresin harvest cycles in southern China create input cost swings that compress margin predictability for esterification facilities.
- Hydrocarbon tackifier substitution:Petrochemical-derived C5 and C9 resins compete on price in rubber compounding applications, eroding natural-origin market share where labeling claims lack procurement weight.
- Upstream concentration risk:Wuzhou Pine Chemicals and regional peers control gum rosin extraction across Guangdong and Fujian provinces, creating single-source dependency for downstream ester producers.
Strategic Opportunities
- Biobased content certification:Emerging sustainability frameworks in public procurement and corporate mandates create qualification pathways for certified rosin esters without explicit regulatory compulsion.
- Food-contact hydrogenated grades:FDA and EU migration limit compliance positions hydrogenated rosin esters for premium packaging segments where safety documentation commands price premiums.
- Cosmetic emulsion labeling:Natural-origin positioning sustains niche preference in personal care formulations where consumer-facing ingredient transparency outweighs cost differentials against synthetic alternatives.
Industry Challenges
- Esterification process expertise scarcity:Hydrogenation and specialty modification capabilities require skilled chemical engineering talent that concentrates in Japanese and select European facilities.
- Multi-jurisdiction compliance synchronization:TSCA Section 5 notifications, REACH SVHC declarations, and evolving GB standards demand parallel regulatory tracking that strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rosin Ester Market |
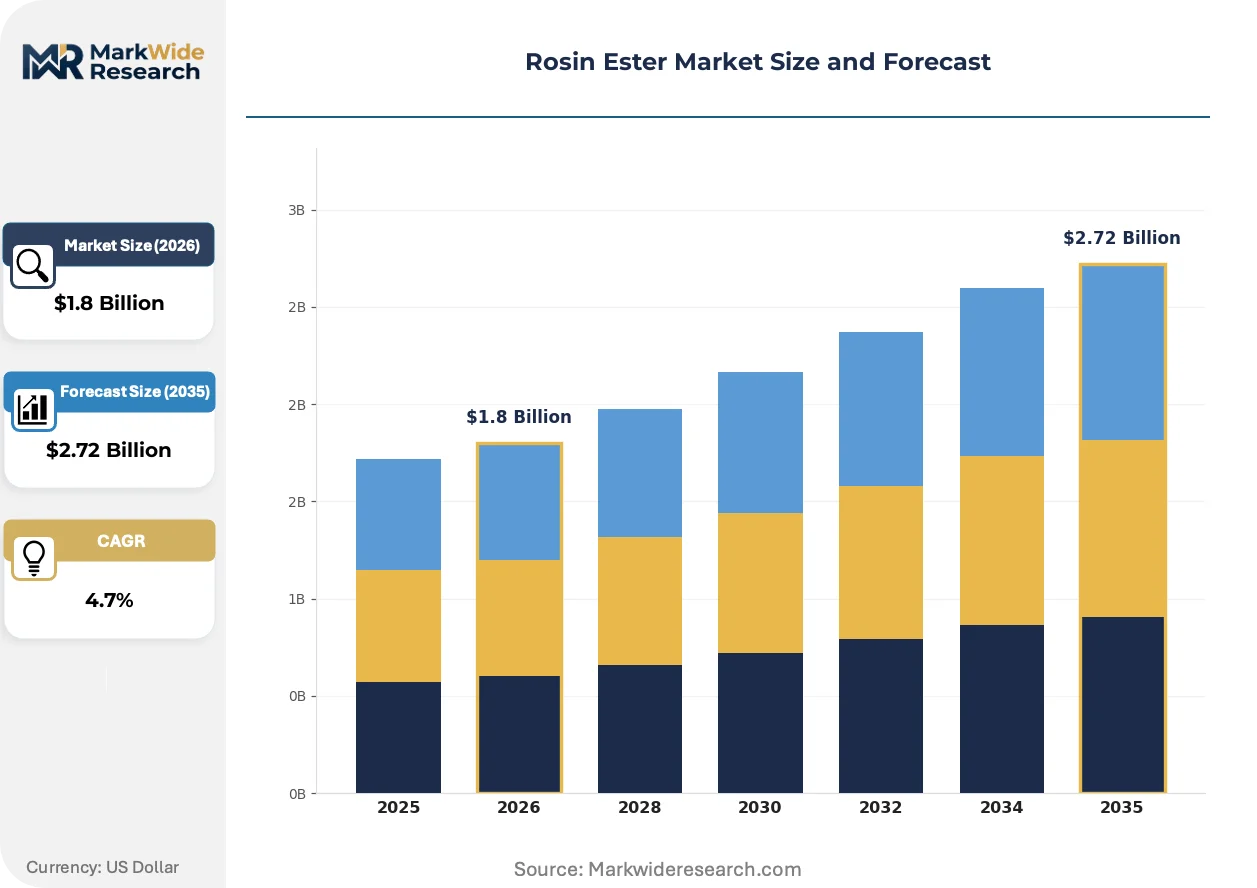
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rosin, Modified Rosin, Hydrogenated Rosin, Esterified Rosin Application: Adhesives, Coatings, Inks, Rubber Compounding End Use Industry: Packaging, Cosmetics, Automotive, Construction Form: Solid, Liquid, Powder, Emulsion |
| Companies Covered | Eastman Chemical Company, Lawter Inc., Kraton Corporation, Guangdong KOMO, Robert Kraemer, DRT, Arakawa Chemical Industries Ltd., Wuzhou Pine Chemicals Ltd., Ingevity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rosin Ester Market Evolving Landscape
Reactive modification chemistry and sustainability certification protocols are redefining competitive differentiation in rosin ester supply, compressing the advantage window for undifferentiated commodity grades.
Partially hydrogenated rosin ester technology is unifying color stability and oxidation resistance in a single resin platform. Pressure-sensitive adhesive compounders in North American tape manufacturing are adopting these grades at accelerating specification rates. The technology is unifying performance tiers that previously required separate inventory positions for standard and premium applications.
EU Green Deal biobased content thresholds are tightening eligibility for public infrastructure adhesives tenders. REACH-compliant rosin esters with verified renewable carbon content now qualify for preferential scoring in municipal procurement frameworks. German automotive tier-one suppliers are restructuring supplier scorecards to weight biobased certification alongside technical performance metrics.
Direct refiner-to-compounder contracting is displacing distributor intermediaries in high-volume hot-melt supply chains. Large packaging adhesive formulators in the United States are consolidating purchase orders through backward integration into gum rosin sourcing or exclusive offtake agreements with Chinese refiners. This channel compression is most visible in e-commerce fulfillment hub supply contracts where volume concentration justifies dedicated logistics arrangements.
Rosin Ester Market Segmentation
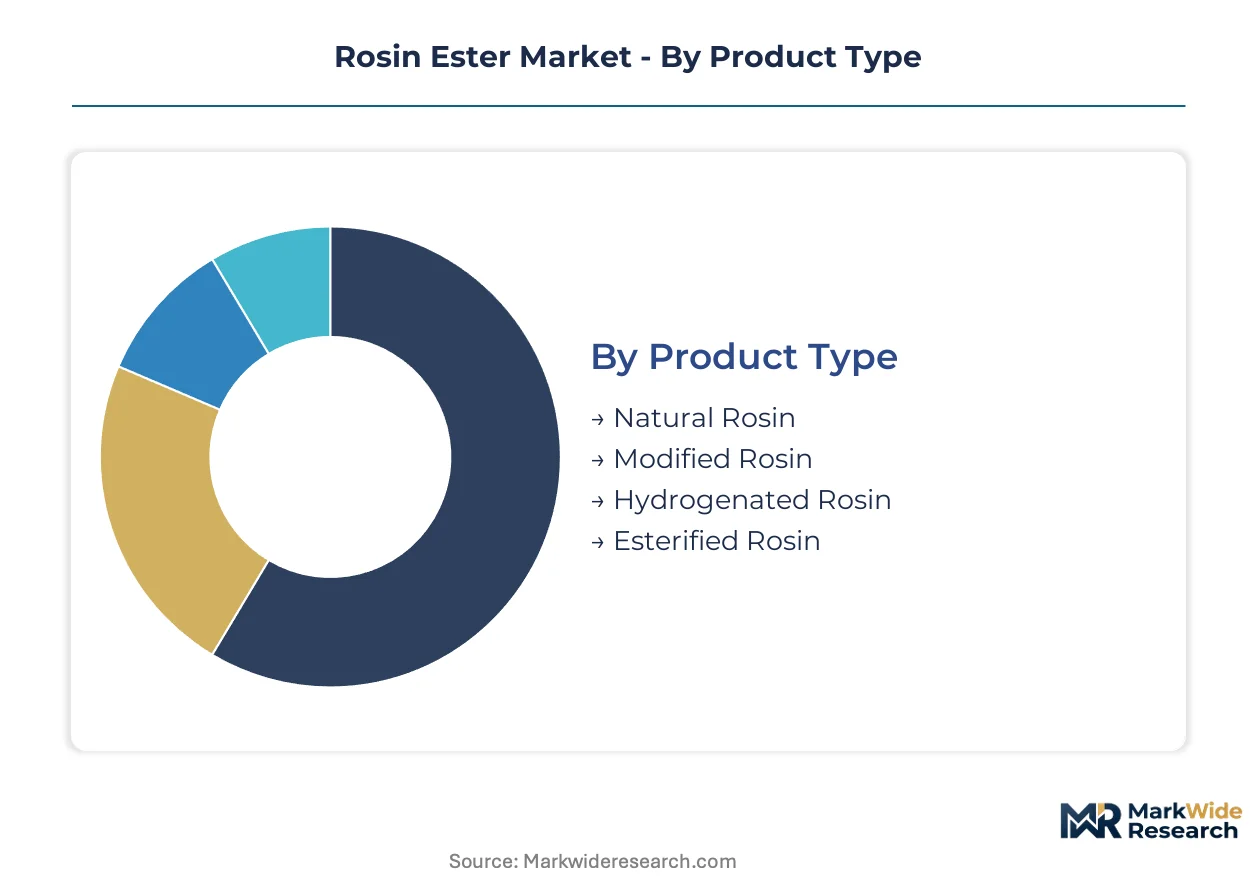
Rosin ester procurement patterns diverge sharply across product grades and application specifications, with hydrogenated variants commanding food-contact premiums while modified grades dominate pressure-sensitive adhesive volumes. Form factor selection directly determines logistics costs and processing equipment compatibility for downstream compounders.
Product Type:
Upgrading from standard to hydrogenated grades delivers color stability and oxidation resistance that extends formulation shelf life in demanding adhesive applications.
- Modified Rosin:Esterified and disproportionated variants achieve tailored softening points between 85°C and 115°C through controlled acid modification. Pressure-sensitive adhesive manufacturers in the United States and Germany specify these grades for tape and label stock where tack retention drives purchasing decisions.
- Hydrogenated Rosin:Partial or complete hydrogenation saturates double bonds in abietic acid structures, yielding pale color and enhanced thermal stability. FDA-compliant hydrogenated esters attract specification from food-contact packaging formulators facing migration limit scrutiny under EU and US regulations.
- Natural Rosin:Unmodified gum rosin retains higher acid numbers and darker coloration, limiting application to cost-sensitive industrial binders and intermediate processing feedstocks.
- Esterified Rosin:Glycerol or pentaerythritol esterification produces thermoplastic resins with defined viscosity profiles for hot-melt compounding.
Volume placements concentrate in Modified Rosin; the faster expansion belongs to Hydrogenated Rosin.
Application:
Cost tier stratification separates commodity rubber compounding from premium adhesive formulations where specification compliance commands price multiples.
- Adhesives:Hot-melt and pressure-sensitive formulations consume the majority of rosin ester tackifier volumes, with e-commerce packaging automation driving specification rates for low-odor, low-color grades in case-sealing applications.
- Coatings:Solvent-borne and water-borne industrial coatings employ rosin esters as film-forming binders and gloss modifiers, particularly in wood furniture finishes where natural-origin labeling supports marketing claims.
- Inks:Offset and gravure printing inks utilize rosin-modified phenolic resins for pigment wetting and vehicle compatibility, though digital printing displacement constrains segment trajectory in publication markets.
- Rubber Compounding:Tire and mechanical goods manufacturers specify rosin esters as processing aids and tackifiers, competing directly with hydrocarbon alternatives on price in non-labeled applications.
Adhesives captures the dominant share; Coatings demonstrates the steepest expansion trajectory.
End Use Industry:
Customer type segmentation distinguishes between procurement-heavy industrial formulators and specification-driven consumer goods manufacturers with divergent compliance requirements.
- Packaging:Corrugated case sealing, flexible packaging lamination, and label stock applications generate the largest volume demand, with fulfillment center automation accelerating hot-melt consumption across North American and European logistics networks.
- Cosmetics:Personal care emulsions and depilatory waxes specify pharmaceutical-grade rosin esters where natural-origin ingredient transparency supports premium positioning against synthetic alternatives.
- Automotive:Tier-one suppliers utilize hydrogenated rosin esters in interior adhesive applications, with German and Japanese manufacturers integrating biobased content metrics into supplier scorecards.
- Construction:Flooring adhesives, carpet backing, and sealant formulations employ cost-optimized modified rosin grades where performance specifications permit darker color and higher odor profiles.
Packaging anchors procurement volumes; Cosmetics climbs the fastest on natural-label premiumization.
Form:
Supply concentration in solid flake and pellet formats reflects hot-melt adhesive dominance, while liquid and emulsion alternatives serve water-borne formulation niches.
- Solid:Flake, pellet, and block forms dominate bulk shipments to hot-melt compounders, offering thermal stability in storage and compatibility with standard melting equipment across adhesive manufacturing facilities.
- Liquid:Solvent-cut or molten bulk deliveries serve high-volume coatings and ink manufacturers with dedicated storage and handling infrastructure, reducing solid-to-liquid conversion costs.
- Powder:Micronized rosin esters enable dry-blend compounding in rubber and certain powder coating applications where solvent elimination is prioritized.
- Emulsion:Water-dispersed rosin esters support water-borne adhesive and coating formulations facing VOC regulatory pressure from EPA and MEE enforcement.
Solid forms capture the volume concentration; Emulsion formats gain share fastest on water-borne formulation conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's bonded logistics zones in Guangdong and Fujian provinces concentrate gum rosin refining capacity. These special economic zones attract downstream esterification investment through tariff exemptions on pine oleoresin imports from Southeast Asia.
United States
Hot-melt adhesive formulators serving e-commerce fulfillment centers drive specification volumes for low-odor rosin ester grades. EPA regulates new chemical notifications under TSCA Section 5, creating compliance barriers for imported resin batches. Texas and Ohio host the largest packaging adhesive manufacturing clusters, with direct refiner-to-compounder contracting displacing traditional distributor channels.
Germany
Automotive tier-one suppliers integrate hydrogenated rosin esters into interior adhesive applications facing biobased content scoring. REACH SVHC disclosure mandates require full substance transparency for resin imports entering European coatings value chains. The Cologne-Düsseldorf industrial corridor concentrates formulation R&D for pressure-sensitive tape manufacturers.
China
Guangdong and Fujian provinces control upstream gum rosin extraction across the southern pine forest belt. SAMR enforces GB standards on rosin derivative purity that directly determine export eligibility for domestic refiners. Wuzhou Pine Chemicals anchors extraction capacity, creating single-source dependency for downstream ester producers.
Japan
Specialized hydrogenation capabilities serve automotive and electronics adhesive specifications requiring thermal stability. METI oversees chemical substance management under CSCL, with industry-specific guidelines for tackifier imports. The Osaka-Kobe manufacturing belt concentrates rosin ester modification expertise among mid-cap chemical specialists.
Rosin Ester Market Competitive Landscape
Top-tier vendors anchor hydrogenated and food-contact grade supply, while regional gum rosin refiners and commodity ester producers occupy the lower tier. The market exhibits tiered concentration: three to four integrated chemical majors control premium specification channels, while Chinese provincial refiners fragment the upstream gum rosin segment. Strategic archetypes include backward-integrated pine forest operators, hydrogenation specialists with pharmaceutical-grade certification, and toll-esterification service providers. Dominant competitive moves center on exclusive offtake agreements with Chinese gum rosin sources and capacity expansion into hydrogenated grades for food-contact compliance.
Within the integrated chemical major tier, Eastman Chemical Company and Arakawa Chemical Industries Ltd. exemplify divergent geographic anchoring strategies. Eastman leverages North American backward integration into gum rosin supply chains to secure feedstock consistency. Arakawa occupies a position as a hydrogenation specialist serving Japanese automotive tier-one suppliers. Wuzhou Pine Chemicals Ltd. represents the upstream concentration archetype, controlling extraction capacity that shapes downstream ester producer procurement economics.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Lawter Inc. |
| Kraton Corporation |
| Guangdong KOMO |
| Robert Kraemer |
| DRT |
| Arakawa Chemical Industries Ltd. |
| Wuzhou Pine Chemicals Ltd. |
| Ingevity |
| Others |
Value Network & Pricing Analysis
Gum rosin harvest volatility in Guangdong and Fujian provinces transmits directly into hydrogenated grade premiums, with spot buyers absorbing steeper differentials than contract holders while modified rosin trades on thinner margins in rubber compounding channels.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate emergency spot purchases from annual contract volumes in food-contact hydrogenated grades. Three-tier pricing structure across premium hydrogenated, standard modified, and economy natural rosin segments reflects certification burden and color stability differentials. Cost compression in modified rosin intensifies because hydrocarbon tackifiers erode share in unlabeled rubber applications. Packaging adhesive formulators exhibit lowest price sensitivity due to specification-locked formulations, while construction sector buyers drive hardest bargain on odor-tolerant industrial grades.
Supply Chain Analysis
Direct-to-compounder channels handle hyperscale packaging adhesive demand, displacing distributor intermediaries in North American and European hot-melt supply chains. Extraction concentrates in China, with Indonesian and Vietnamese pine oleoresin feeding bonded logistics zones. Esterification facilities draw from gum rosin, glycerol, and hydrogenation catalyst feedstocks. Single-source vulnerability concentrates in Wuzhou Pine Chemicals' grip on southern Chinese extraction capacity. Distribution runs through exclusive offtake agreements and backward-integrated refiner relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH SVHC disclosure mandates erect a cost-of-compliance moat that filters subscale refiners from European adhesive value chains, rewarding pre-qualified incumbents with pricing power and procurement lock-in.
For Market Incumbents: Extend hydrogenation capacity into pharmaceutical-grade certification to capture food-contact packaging premiums before hydrocarbon substitution accelerates in rubber compounding. Consolidate exclusive offtake agreements with Fujian and Guangdong extraction operators to defend against gum rosin feedstock volatility. Channel control through direct-to-compounder contracting represents the critical defensive lever against distributor disintermediation. For New Entrants and Emerging Players: Toll esterification service providers offer the most penetrable entry vector for mid-cap compounders seeking flexible capacity without capital intensity. Target cosmetic emulsion manufacturers in European and North American markets where natural-origin labeling commands price tolerance absent in industrial segments. White-space exists in biobased certification consulting bundled with resin supply, addressing sustainability procurement scoring requirements. For Investors and Strategic Acquirers: German automotive tier-one supplier scorecard restructuring is the leading indicator that biobased content metrics will propagate across adhesive procurement frameworks. Long-term viability favors hydrogenation specialists with FDA and EU migration limit documentation over commodity ester producers exposed to hydrocarbon substitution. Acquisition target archetype: mid-cap Japanese or European modifier with captive hydrogenation expertise and existing pharmaceutical-grade certification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gum Rosin Sourcing | Eastman Chemical's captive supply of pine oleoresin insulates margin predictability against Guangdong harvest volatility. |
| Hydrogenation Capacity Expansion | Arakawa Chemical's thermal stability expertise serves Japanese automotive interior specifications requiring migration compliance. |
| Biobased Certification Program | EU Green Deal scoring thresholds qualify certified rosin esters for preferential municipal infrastructure tender treatment. |
| Exclusive Offtake Agreement | Large packaging formulators secure dedicated logistics arrangements through direct Chinese refiner contracting. |
| Pharmaceutical-Grade Certification Investment | FDA-compliant hydrogenated grades command price multiples in food-contact lamination versus standard modified variants. |
Research Methodology
Document review covered customs trade databases, SEC 10-K filings, and ECHA SVHC registration lists, complemented by interviews with gum rosin extraction plant managers, hot-melt adhesive procurement leads, hydrogenation R&D directors, and coatings formulators at European automotive tier-one suppliers. Secondary validation drew from SAMR GB standard enforcement notices, REACH compliance disclosure registries, and American Chemistry Council resin trade statistics. Bottom-up volume modeling triangulated against top-down value chain sizing across the analysis window.
Historical shipment patterns cross-referenced against expert panel input on specification migration and substitution elasticity shaped the analytical framework. Segmentation dimensions modeled include product grade tier, end-use industry vertical, packaging form factor, and regional regulatory cluster. CAGRs derived from slope-log analysis of volume trajectories adjusted for feedstock cycle normalization. Industry-specific inputs incorporated pine oleoresin harvest yield variability and e-commerce fulfillment center automation deployment rates.
Caveats apply where gum rosin harvest failures, REACH scope expansions, or hydrocarbon tackifier price collapses could materially shift the outlook beyond modeled scenarios. Forecasts reflect documented assumptions on substitution thresholds and certification adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Octane Improver Fuel Additives Market
Additives
Lead Stearate Market
Additives
Sodium Stearyl Fumarate Market
Additives
Competitive Inhibitors Market
Additives
Plastic Additives Market
Additives
Global Butyric Acid Derivatives Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Refinery Fuel Additives Market
Additives
Saudi Arabia Feed Additives Market
Additives
Shortstop Inhibitor Market
Additives
Antiknock Agents Market
Additives
Dry-Mix Mortar Additives and Chemicals Market
Additives
Sodium Citrate Dihydrate Market
Additives
Anti Crystallizing Agents Market
Additives
Cassia Gum Market