
 Global Insight As a Service Market | 2026-2036
Global Insight As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insight As a Service Market Foresight
Cloud-native artificial intelligence architectures are reshaping how insight platforms are built and delivered. Microsoft leverages its Azure ecosystem to anchor enterprise-grade analytics pipelines across Fortune 500 accounts. IBM Corporation competes through Watson's specialized natural-language processing layers for regulated industries. Oracle Corporation controls database-to-insight workflows by extending its autonomous data warehouse into pre-configured analytics modules.
Insight as a Service denotes the externalized delivery of actionable intelligence through subscription-based platforms that ingest structured and unstructured data, apply machine-learning algorithms, and render decision-ready outputs via API or dashboard interfaces. Cloud-Based deployment dominates transaction volume due to elastic compute scaling and lower capital barriers, though Hybrid configurations are capturing margin pools in banking and telecommunications where data residency rules fragment workload placement. Predictive Modeling and Competitive Intelligence represent the fastest-growing service type categories as procurement teams shift from descriptive reporting to forward-looking scenario engines.
The EU AI Act, GDPR, and ISO 27001 collectively shape compliance costs and product architecture for vendors serving European enterprises. The US SEC and HIPAA impose parallel constraints on financial and healthcare insight applications, forcing multi-jurisdictional certification roadmaps. Stakeholders must monitor how divergent algorithmic accountability regimes fragment platform development priorities and inflate go-to-market timelines.
Market Dynamics
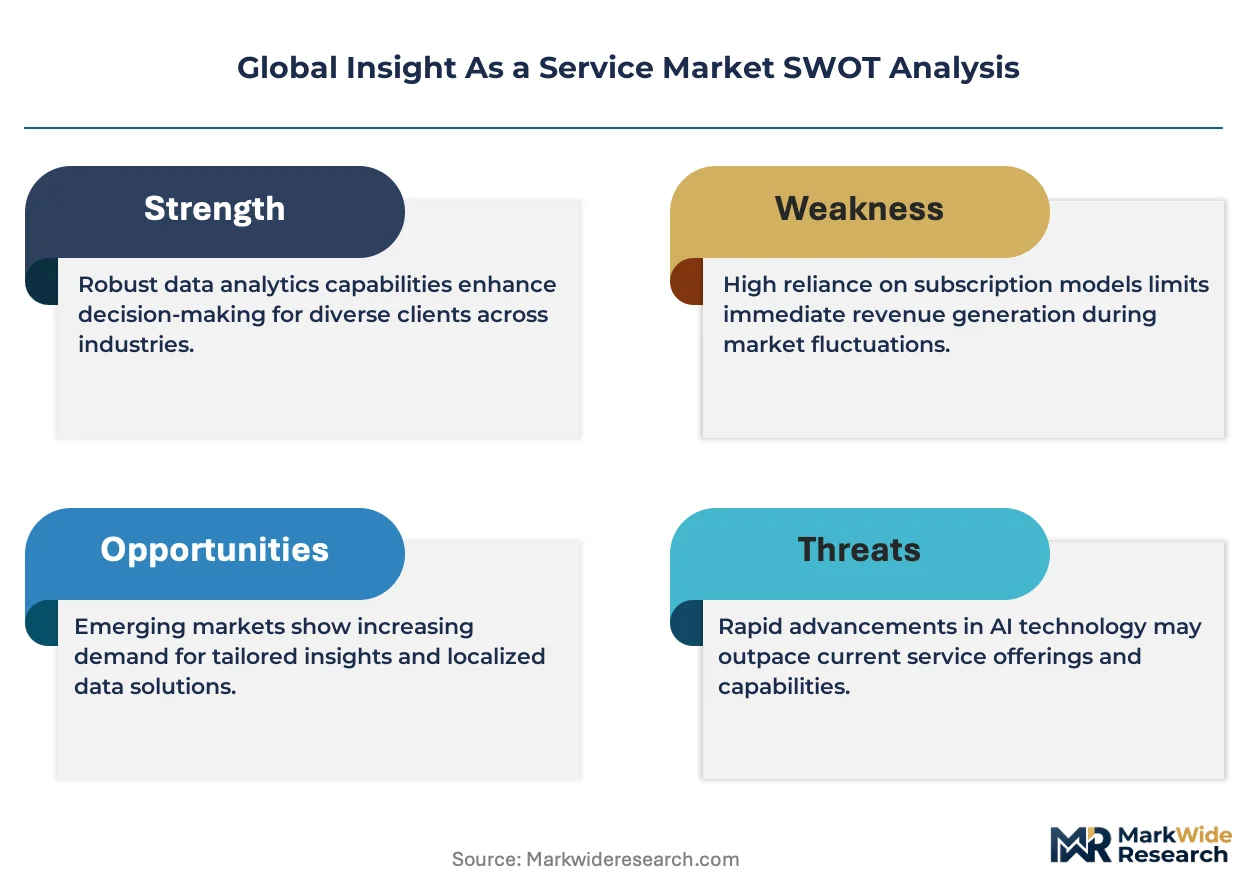
Algorithmic explainability mandates from the EU AI Act and SEC disclosure rules are forcing vendors to re-architect black-box models into interpretable pipelines, raising R&D burn rates while creating compliance moats for first movers.
Growth Catalysts
- EU AI Act transparency tiers:Mandatory documentation requirements for high-risk automated decision systems are generating subscription demand for audit-ready insight platforms in Frankfurt and Paris banking clusters.
- Healthcare predictive analytics:HIPAA-covered entities in the United States are externalizing clinical risk scoring to cloud-native vendors to avoid on-premise infrastructure liability.
- Elastic compute economics:GPU-as-a-service pricing models from hyperscalers are compressing capital barriers for mid-market enterprises entering predictive modeling.
Market Restraints
- Cross-border data localization:China's PIPL and Russia's data sovereignty rules fragment training dataset assembly, forcing redundant infrastructure in Beijing and Moscow metro zones.
- Specialized talent scarcity:MLOps engineers with production-grade model governance experience command premium compensation that squeezes vendor gross margins.
- Substitute internal build-outs:Capital-rich asset managers and pharmaceutical conglomerates are constructing captive insight units rather than subscribing to third-party platforms.
Strategic Opportunities
- India's digital public infrastructure:Account Aggregator framework and UPI data rails enable consent-based financial insight products for Mumbai and Bangalore fintech ecosystems.
- Convergence of graph neural networks with LLMs:Hybrid architectures for relationship-aware forecasting open white space in supply chain risk applications.
- Brazil's open banking mandate:Central Bank of Brazil's phased data-sharing requirements create embedded insight slots for credit decisioning APIs.
Industry Challenges
- Model drift monitoring at scale:Production environments require continuous validation pipelines that most vendors have not automated, creating operational reliability gaps.
- ISO 27001 and SOC 2 Type II certification timelines:Enterprise procurement gates impose 12-18 month compliance runway before contract execution, stretching vendor cash conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insight As a Service Market |
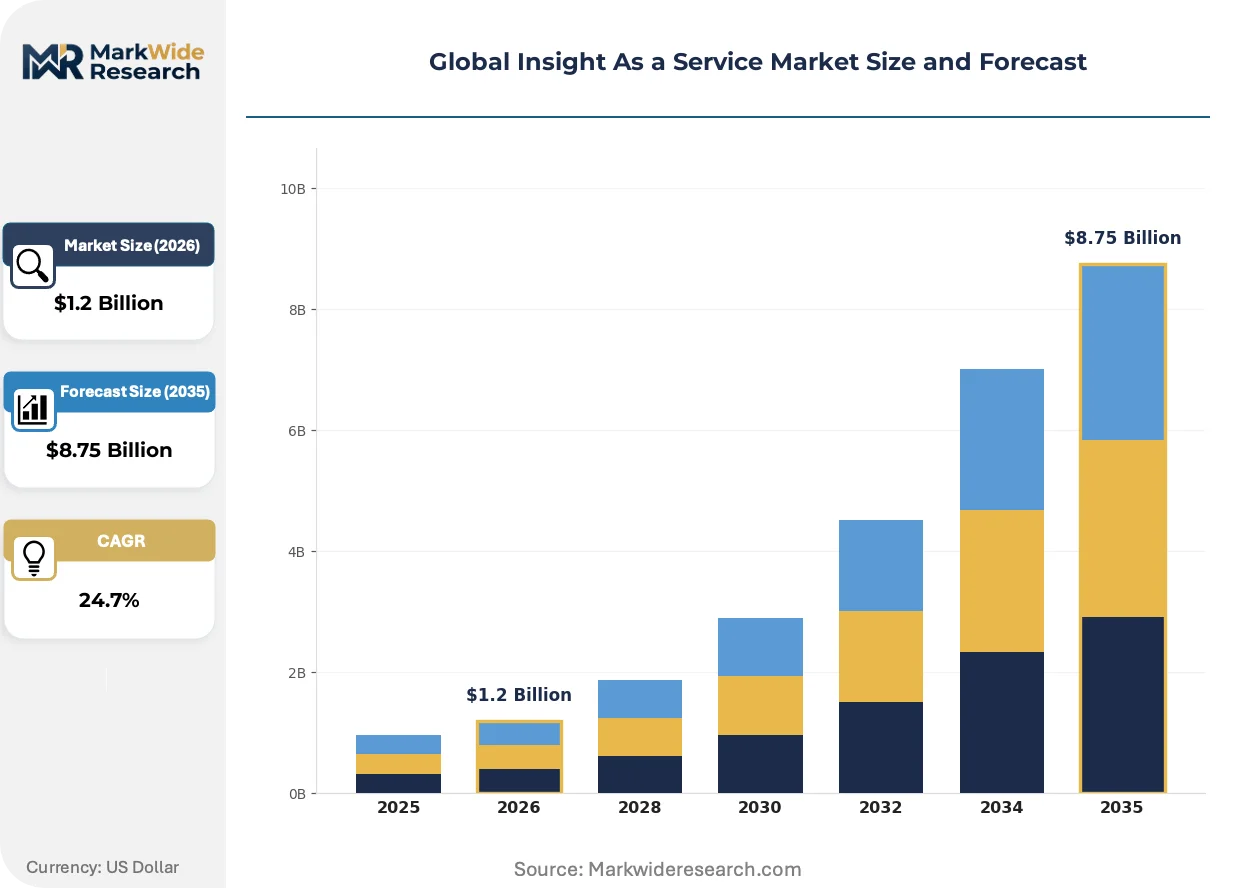
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $8.75 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Analytics, Predictive Modeling, Market Research, Sentiment Analysis, Competitive Intelligence Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Customer Insights, Risk Management, Fraud Detection, Product Development, Operational Efficiency End User Industry: Telecommunications, Banking, E-Commerce, Manufacturing, Media & Entertainment |
| Companies Covered | Accenture, Capgemini, Dell Technologies, GoodData Corporation, Microsoft, IBM Corporation, Oracle Corporation, Tata Consultancy Services, NTT DATA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insight As a Service Market Shifts & Advancements
Foundation-model architectures are compressing the traditional extract-transform-load pipeline into single-pass inference systems, collapsing vendor differentiation around raw data access rather than algorithmic sophistication.
Retrieval-augmented generation stacks are rendering obsolete static business intelligence dashboards that required pre-defined query schemas. Fortune 500 procurement teams in the United States are piloting natural-language insight interfaces that bypass SQL-dependent analyst intermediaries. This compression is eliminating seat-license pricing power for incumbent visualization platforms.
The EU AI Act's risk-classification framework is mandating human-in-the-loop documentation for high-stakes automated credit and hiring decisions. Vendors serving European financial institutions must now embed explainability modules that trace individual predictions to training data lineage. German and French regulators are already enforcing conformity assessments that delay product launches by six to nine months.
Enterprise buyers are unbundling descriptive reporting from predictive subscriptions, contracting insight-as-a-service only for forward-looking scenario engines while handling historical analytics in-house. This bifurcation concentrates vendor margins in specialized forecasting modules rather than platform-wide licenses. The pattern is most pronounced among North American private equity and insurance underwriters.
Global Insight As a Service Market Segmentation
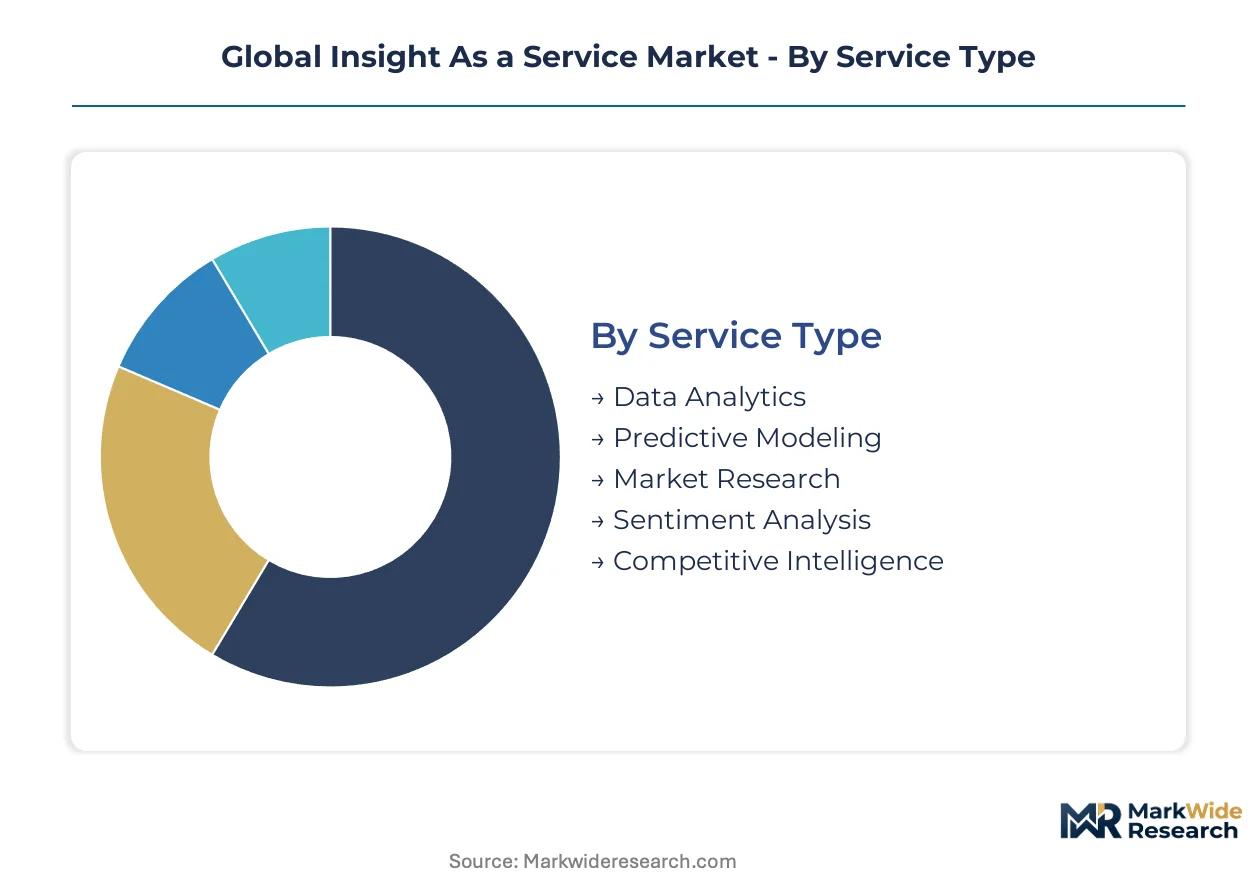
Insight as a Service platforms fragment across service layers, deployment architectures, and industry verticals. Procurement patterns diverge sharply between enterprises seeking turnkey predictive engines and those demanding bespoke on-premise implementations.
Service Type:
Predictive Modeling and Competitive Intelligence turn over fastest as procurement teams abandon descriptive reporting, while Market Research and Sentiment Analysis refresh cycles lag due to entrenched vendor relationships.
- Data Analytics:Structured and unstructured data processing pipelines delivering descriptive dashboards and diagnostic visualizations. Demand concentrates among mid-market manufacturers in Germany seeking ISO 27001-compliant operational dashboards without captive data science teams.
- Predictive Modeling:Machine-learning engines generating forward-looking scenario outputs for credit risk and demand forecasting. US financial institutions under SEC disclosure pressure are externalizing model development to avoid governance liability.
- Market Research:Traditional survey-based intelligence and panel data synthesis. Contract cycles extend 24-36 months among Japanese conglomerates with established agency relationships.
- Sentiment Analysis:Natural-language processing of social media, earnings calls, and customer feedback streams. Brazilian fintech clusters leverage Central Bank open banking data for real-time credit sentiment scoring.
- Competitive Intelligence:Relationship-aware forecasting combining patent filings, supply chain signals, and pricing telemetry. Telcos in India deploy graph neural networks to anticipate competitor tower rollouts.
Predictive Modeling anchors the volume base while Competitive Intelligence gains share at the steepest rate.
Deployment Model:
Cost tiers separate elastic cloud subscriptions from capital-intensive on-premise builds, with hybrid configurations capturing premium pricing in regulated jurisdictions.
- Cloud-Based:Multi-tenant SaaS architectures with API-delivered insights and consumption-based pricing. Elastic compute scaling from hyperscalers compresses entry barriers for Mumbai and Bangalore fintech ecosystems.
- On-Premises:Dedicated hardware installations behind client firewalls with full data sovereignty. China's PIPL localization mandates force redundant Beijing infrastructure for training dataset assembly.
- Hybrid:Split workloads with sensitive data on-premise and compute-intensive modeling in cloud zones. Frankfurt and Paris banking clusters demand this architecture for EU AI Act audit trails.
- Edge Computing:Distributed inference nodes minimizing latency for real-time operational decisions. Manufacturing plants in Stuttgart deploy edge insight modules for predictive maintenance on sensitive production lines.
Cloud-Based deployment commands the volume base while Hybrid configurations expand most quickly.
Application:
Customer-facing applications refresh faster than back-office functions as revenue teams demand real-time personalization engines.
- Customer Insights:Segmentation and lifetime-value modeling for acquisition and retention campaigns. E-commerce platforms in São Paulo leverage Brazil's open banking mandate for embedded credit decisioning.
- Risk Management:Credit, operational, and supply chain risk scoring with regulatory documentation. HIPAA-covered US healthcare entities externalize clinical risk scoring to avoid infrastructure liability.
- Fraud Detection:Real-time transaction monitoring and anomaly flagging across payment networks. Singapore-based payment processors deploy graph neural networks for relationship-aware fraud forecasting.
- Product Development:Demand sensing and feature prioritization from behavioral telemetry. Media conglomerates in Los Angeles pilot natural-language insight interfaces bypassing SQL-dependent analyst intermediaries.
- Operational Efficiency:Process mining and resource optimization across manufacturing and logistics. German automotive suppliers under CSRD pressure document supply chain emissions through audit-ready insight platforms.
Risk Management anchors the volume base while Fraud Detection climbs the fastest.
End User Industry:
Technology maturity separates cloud-native sectors from legacy verticals still migrating off mainframe analytics.
- Telecommunications:Network optimization, churn prediction, and tower deployment planning. Indian operators leverage Account Aggregator framework data for consent-based financial insight products.
- Banking:Credit decisioning, regulatory reporting, and algorithmic trading surveillance. EU AI Act transparency tiers generate subscription demand in Frankfurt and Paris for audit-ready platforms.
- E-Commerce:Dynamic pricing, inventory positioning, and personalization at scale. São Paulo and Bangalore marketplaces deploy retrieval-augmented generation stacks rendering static BI dashboards obsolete.
- Manufacturing:Predictive maintenance, quality control, and supply chain resilience. Stuttgart and Munich industrial clusters demand ISO 27001 certification before contract execution.
- Media & Entertainment:Content recommendation, audience forecasting, and rights valuation. Los Angeles and New York studios unbundle descriptive reporting from predictive subscriptions for scenario engines.
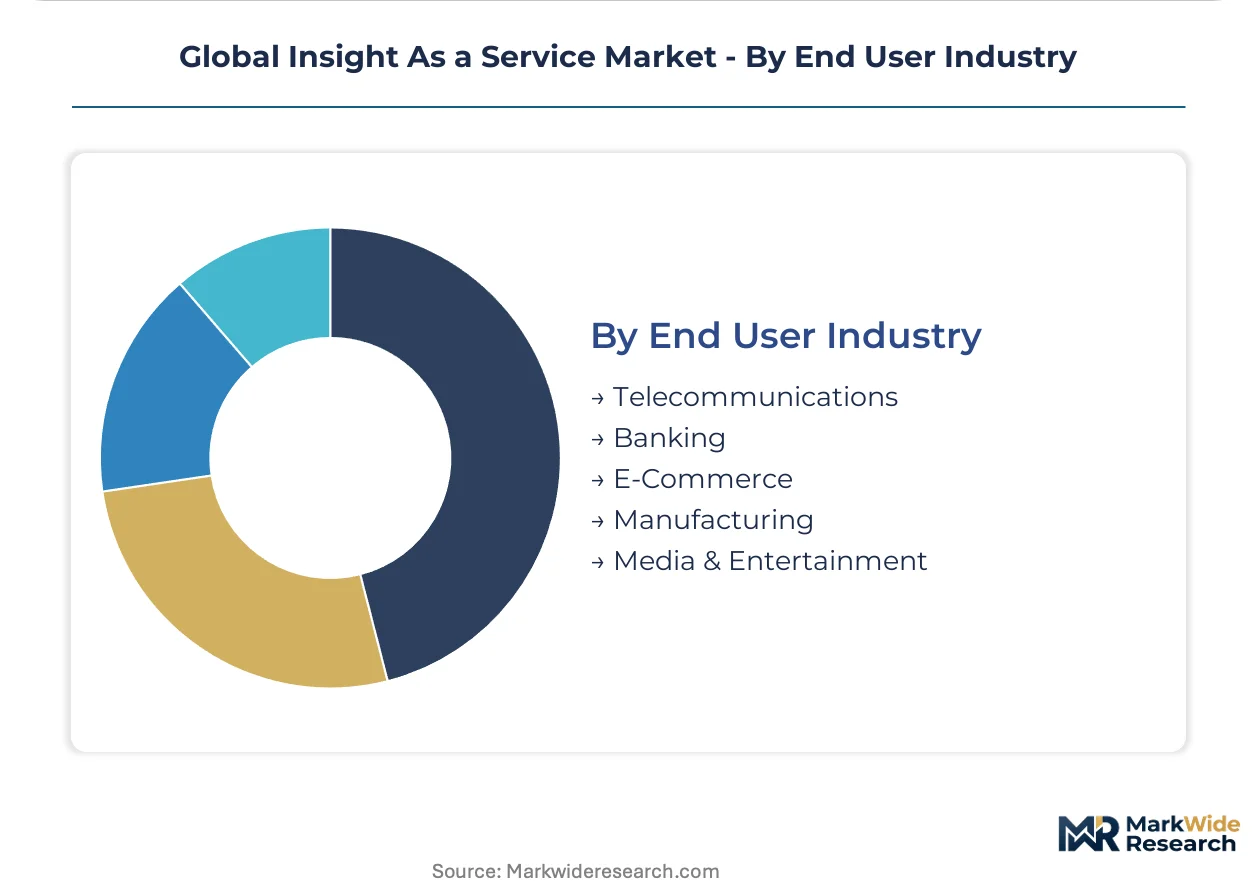
Banking anchors the volume base while E-Commerce gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in the United States and Germany command premium pricing for audit-ready insight platforms, while emerging clusters in India and Brazil exploit digital public infrastructure to compress deployment costs.
United States
SEC disclosure rules and HIPAA-covered entity outsourcing are accelerating predictive modeling adoption. Healthcare providers in Boston and New York externalize clinical risk scoring to avoid on-premise infrastructure liability. Silicon Valley hyperscalers anchor GPU-as-a-service pricing models that compress capital barriers for mid-market entrants.
Germany
EU AI Act conformity assessments and CSRD supply chain documentation requirements are reshaping procurement criteria. Stuttgart automotive suppliers demand ISO 27001-certified operational dashboards for emissions tracking. Frankfurt banking clusters drive subscription demand for explainability modules that trace predictions to training data lineage.
India
RBI-regulated Account Aggregator frameworks and UPI data rails enable consent-based financial insight products. Mumbai fintech ecosystems leverage elastic cloud scaling from hyperscaler partnerships. Bangalore technology parks host retrieval-augmented generation pilots that render static BI dashboards obsolete.
Brazil
Central Bank open banking mandates phase in data-sharing requirements that create embedded credit decisioning slots. São Paulo e-commerce platforms deploy real-time personalization engines powered by transaction telemetry. Local payment processors exploit graph neural networks for relationship-aware fraud forecasting.
China
PIPL data localization mandates force redundant Beijing infrastructure for training dataset assembly. State-affiliated telecommunications operators in Shenzhen pilot edge computing nodes for network optimization. Shanghai banking clusters demand hybrid architectures that split sensitive data on-premise from cloud-based modeling workloads.
Global Insight As a Service Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Hyperscale cloud providers anchor enterprise-grade analytics pipelines through elastic compute ecosystems. Legacy IT consultancies leverage vertical relationships to embed insight modules into broader transformation contracts. Pure-play analytics vendors defend margin pools through specialized natural-language processing layers for regulated industries. Competitive moves concentrate on strategic partnerships with hyperscalers and portfolio diversification into explainability tooling.
Among technology conglomerates with cloud ecosystems, Microsoft, IBM Corporation, and Oracle Corporation exemplify distinct competitive archetypes. Microsoft occupies a position anchored in Azure-native analytics pipelines serving Fortune 500 procurement teams. IBM Corporation sits within the specialized AI tier through Watson's regulatory-focused natural-language capabilities. Oracle Corporation represents database-to-insight workflow control via autonomous data warehouse extensions into pre-configured analytics modules.
| Leading Market Players |
|---|
| Accenture |
| Capgemini |
| Dell Technologies |
| GoodData Corporation |
| Microsoft |
| IBM Corporation |
| Oracle Corporation |
| Tata Consultancy Services |
| NTT DATA Corporation |
| Others |
Supply & Pricing Matrix
EU AI Act conformity assessment bottlenecks determine both tier spreads between audit-ready and standard platforms and vendor infrastructure placement decisions across Frankfurt, Paris, and London metro zones. Cloud hyperscalers leverage extended payment terms to compress mid-market entry barriers while ISO 27001 certification timelines inflate enterprise contract values by twelve to eighteen months.
Pricing Analysis
Cost-plus contracts indexed to GPU-as-a-service hyperscaler pricing anchor subscription tiers across cloud-native deployments. Pricing stratifies across premium, standard, and economy tiers based on explainability module depth and SOC 2 Type II certification status. Cost compression in standard tiers is intensifying because elastic compute economics democratize predictive modeling access. Mid-market manufacturers in Germany exhibit highest price sensitivity, while HIPAA-covered US healthcare entities demonstrate lowest sensitivity due to infrastructure liability avoidance.
Supply Chain Analysis
Supply-chain finance facilities extended by hyperscalers to certified vendors compress working capital cycles for model training infrastructure. Compute hardware concentrates in Taiwan, South Korea, and the United States, while MLOps talent pools center on India, Germany, and Singapore. Platform development draws from GPU clusters, proprietary training datasets, and regulatory documentation frameworks. Single-source vulnerability around NVIDIA H100 allocations threatens vendor scaling timelines. Distribution runs through API-first direct sales and systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across compliance regimes and deployment architectures creates specialist niche opportunities as enterprise buyers unbundle descriptive from predictive capabilities.
For Market Incumbents: Insulate margin pools by embedding explainability tooling into hybrid architectures for EU banking clusters and securing GPU allocation commitments through hyperscaler strategic partnerships. Counter captive build-out threats among capital-rich asset managers with outcome-based pricing tied to model accuracy benchmarks. For New Entrants and Emerging Players: Mid-market fintech ecosystems in Mumbai and São Paulo represent the most penetrable entry point given Account Aggregator framework and open banking mandate tailwinds. Target consent-based credit decisioning APIs with lightweight retrieval-augmented generation stacks that bypass incumbent visualization platform complexity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized natural-language processing layers with regulatory certification moats. Long-term viability hinges on human-in-the-loop documentation automation for EU AI Act high-risk tiers. Watch for conformity assessment backlog duration as inflection indicator for platform differentiation sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Explainability Module Development | EU AI Act audit trail requirements in Frankfurt banking clusters mandate traceable prediction lineage. |
| Hyperscaler Partnership | GPU-as-a-service pricing compression enables mid-market predictive modeling entry in Bangalore. |
| Hybrid Architecture Deployment | Data residency rules in Beijing and Moscow force split workload placement for compliance. |
| ISO 27001 Certification Investment | Stuttgart automotive suppliers gate procurement on twelve-month compliance runway completion. |
| Retrieval-Augmented Generation Launch | Natural-language interfaces displace SQL-dependent analyst intermediaries in Los Angeles media pilots. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings across the analysis window. CTOs, IT procurement officers, platform engineers, and integration specialists at Fortune 500 accounts, mid-market fintechs, and HIPAA-covered healthcare entities provided operational data. Secondary sources include SEC disclosure filings, EU AI Act conformity assessment registers, hyperscaler capex disclosures, and ISO certification databases. Bottom-up deployment volume estimates triangulate against top-down cloud infrastructure spend allocations.
Calibration against historical platform adoption curves and regulatory implementation timelines shapes the projection framework. Segmentation dimensions span service type, deployment model, application, and end-user industry vertical across the modeling period. CAGRs derive from elasticity-adjusted subscription pricing trajectories and GPU cost decline curves. Model governance automation rates and explainability module attach rates constitute industry-specific forecast inputs.
Practitioners should monitor EU AI Act enforcement consistency, hyperscaler GPU allocation policy shifts, and captive build-out announcements among capital-rich conglomerates for early signals. Forecasts reflect assumptions regarding regulatory timeline adherence and cloud infrastructure cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
North America Data Virtualization Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Poland ICT Market
Digital Solutions
Graphical Situational Display Market
Digital Solutions
Cloud Field Service Management (FSM) Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Australia ICT Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
Mobile Command and Control Solutions Market
Digital Solutions
Intelligent Virtual Store Design Solution Market
Digital Solutions
Cloud Manufacturing Execution System (MES) Market
Digital Solutions
Decision Management Applications Market