
 Ticketing Solution Market | 2026-2036
Ticketing Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Ticketing Solution Market Analytics
Developer talent with embedded systems and cryptography expertise is collapsing across the ticketing technology sector, constraining platform security roadmaps for incumbents and entrants alike. Ticketmaster leverages its venue control and exclusive promoter contracts to sustain North American dominance. Eventbrite anchors the small-to-mid event organizer segment through self-service onboarding tools. CTS Eventim competes across European live entertainment through integrated promotion and ticketing operations.
A ticketing solution comprises hardware and software systems that authenticate, issue, validate, and transfer admission rights for events and transportation, typically incorporating barcode generation, near-field communication protocols, and real-time inventory management with sub-second transaction processing. The primary commercial purpose centers on eliminating counterfeit entry credentials, optimizing venue capacity utilization, and capturing first-party customer data for event organizers. Mobile tickets now lead product type adoption as smartphone penetration and contactless entry requirements displace print-at-home alternatives, while RFID tickets command premium positioning in high-frequency festival environments where re-entry and cashless payments integrate. Online platforms dominate distribution channel value capture, though third-party resellers occupy a contested margin pool shaped by regulatory price-cap debates.
FDA guidelines on data privacy in consumer-facing applications, FCC rules governing short-range wireless transmission for NFC validation, and EU GDPR requirements on personal data retention all shape platform architecture decisions and vendor compliance costs. The EU AI Act introduces additional scrutiny for automated pricing and demand-forecasting algorithms deployed by major platforms. Stakeholders must monitor how jurisdictional fragmentation in digital ticket transferability rules affects secondary market participation and primary platform pricing power.
Market Dynamics
NFC validation protocols and blockchain credentialing are compressing fraud windows while forcing incumbent platforms to rebuild authentication stacks from hardware through cloud layers.
Growth Catalysts
- FCC Part 15 Rules:Short-range wireless certification for NFC readers accelerates venue deployment timelines across United States stadiums and transit terminals.
- EU AI Act:Algorithmic transparency mandates for dynamic pricing create competitive openings for compliant forecasting engines in European live entertainment.
- Festival Cashless Integration:RFID wristbands with embedded payment credentials drive hardware refresh cycles at multi-day music events in Germany and Japan.
Market Restraints
- Semiconductor Supply Concentration:NFC controller chip fabrication concentrates in Taiwan, exposing hardware vendors to single-source vulnerability.
- GDPR Data Retention Limits:EU-mandated deletion timelines compress first-party data monetization windows for cross-border event organizers.
- Print-at-Home Residual Demand:Demographic segments without smartphone penetration sustain legacy infrastructure costs that dilute platform margins.
Strategic Opportunities
- India Venue Digitization:Untapped sports stadium infrastructure and BIS certification pathways create greenfield deployment potential for mobile-first platforms.
- ISO 27001 Convergence:Information security certification becomes a procurement filter, rewarding vendors with pre-certified architecture in enterprise sales cycles.
- Secondary Market Smart Contracts:Blockchain-based resale royalties enable new revenue sharing models between artists and primary ticket issuers.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for secure element integration commands premium compensation that strains development budgets.
- Legacy POS Integration:Decades-old venue access control systems require custom API bridges that extend implementation timelines and inflate professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ticketing Solution Market |
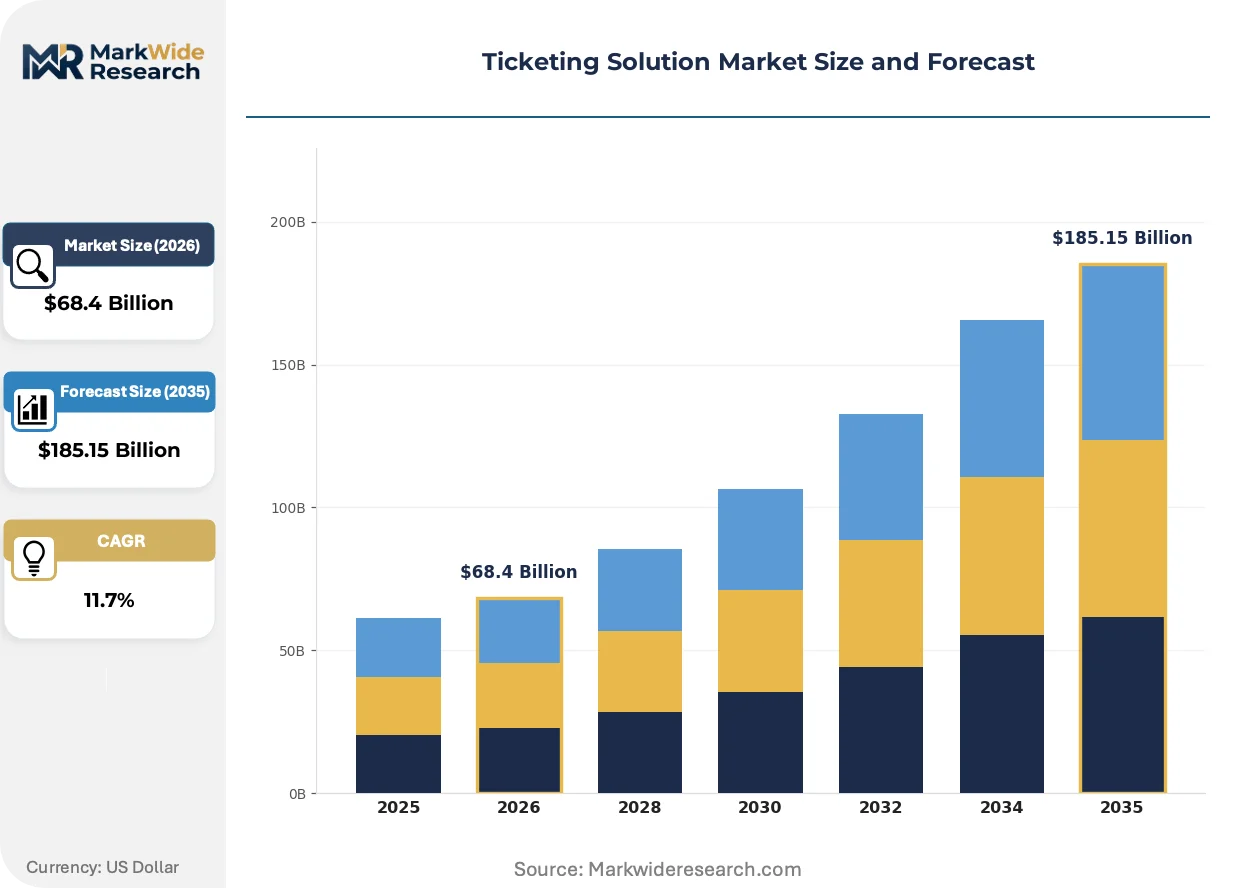
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Tickets, Print-at-Home, RFID Tickets, E-Tickets Distribution Channel: Online Platforms, Box Offices, Third-Party Resellers, Direct Sales Event Type: Concerts, Sports Events, Theatrical Shows, Festivals Customer Type: Individual Consumers, Corporate Clients, Event Organizers, Venues |
| Companies Covered | Ticketmaster, Eventbrite, StubHub, Live Nation Entertainment, CTS Eventim, See Tickets, Cubic Corporation, Infineon Technologies, HID Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ticketing Solution Market Evolving Landscape
Authentication technology is bifurcating between smartphone-native credentials and wearable form factors, each demanding distinct hardware investments and venue retrofit strategies.
Dynamic QR codes with rotating encryption seeds are supplanting static barcode generation in high-value event categories. Premier league football clubs and Broadway theaters have adopted these credentials for season ticket holders. This shift is compressing the window for credential replication fraud while forcing secondary market platforms to rebuild transfer verification protocols.
EU GDPR enforcement actions against excessive data collection are tightening consent architecture requirements for European ticketing platforms. Event organizers now face audit exposure for retention practices exceeding purpose limitations. Germany and France lead this compliance wave, with Dutch and Spanish regulators accelerating investigation timelines.
Subscription-based access memberships are displacing single-event purchases in metropolitan entertainment corridors. Young adult demographics in Tokyo, London, and New York demonstrate highest uptake for monthly venue passes. This model concentrates demand forecasting risk with platform operators while reducing per-transaction revenue visibility.
Ticketing Solution Market Segmentation
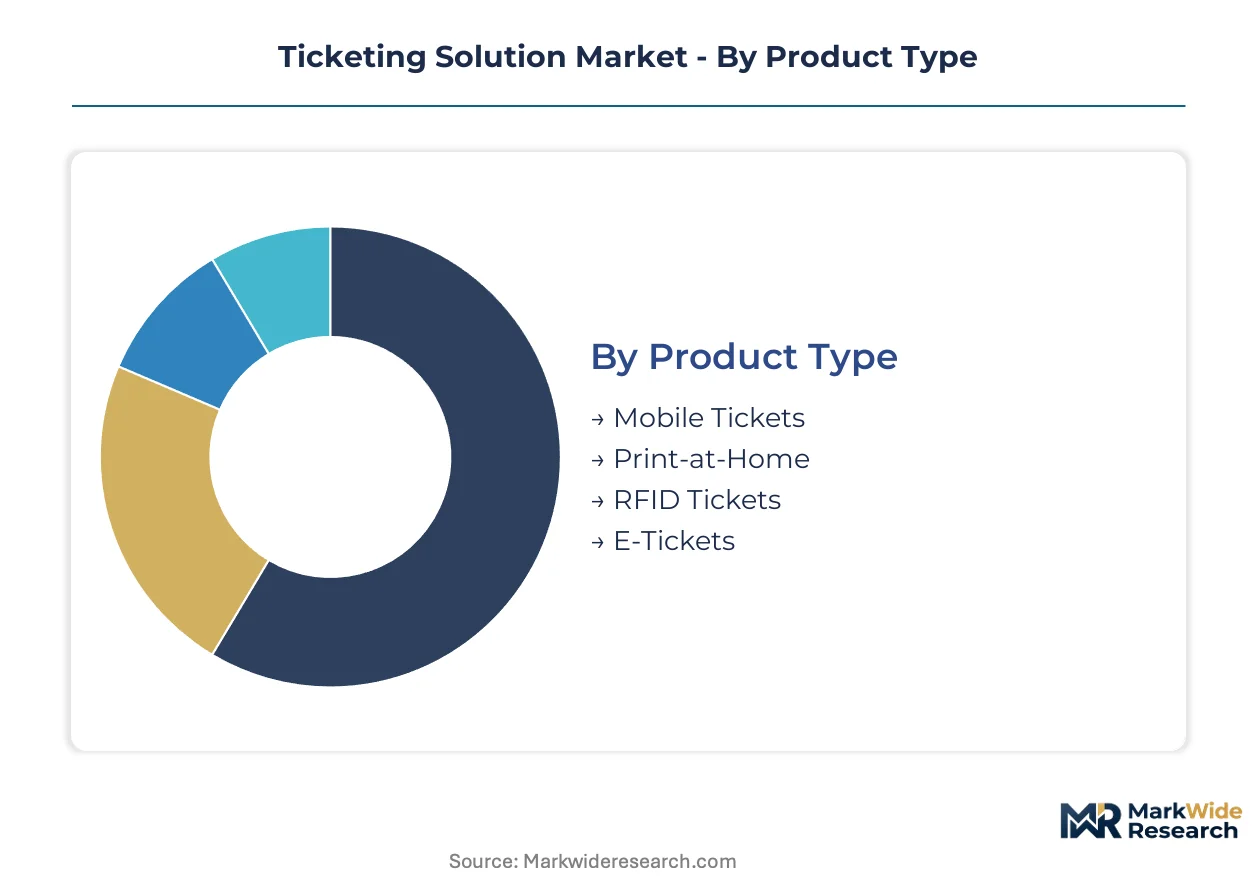
Ticketing solution architectures diverge sharply across credential formats, distribution pathways, and end-user procurement patterns. Segment boundaries determine fraud exposure, hardware refresh cycles, and platform monetization models. Vendors must align R&D allocation with substitution trajectories reshaping each category.
Product Type:
Print-at-Home credentials face the most acute substitution pressure as smartphone-native alternatives displace paper-based authentication across venue tiers.
- Mobile Tickets:Smartphone-native credentials leveraging NFC and dynamic QR encryption for contactless venue entry. Demand concentrates in United States sports stadiums and Japanese transit corridors where FCC Part 15 certification and METI contactless standards accelerate deployment timelines.
- RFID Tickets:Wearable form factors embedding secure element chips for re-entry authentication and cashless payments at multi-day festivals. German music events and Tokyo entertainment districts drive hardware refresh cycles through integrated payment credential requirements.
- Print-at-Home:Static barcode generation for demographic segments lacking smartphone penetration or venue legacy system compatibility.
- E-Tickets:PDF-based credentials delivered via email for low-frequency event attendance with minimal fraud risk profiles.
Mobile tickets retain volume leadership; RFID tickets hold the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates self-service digital platforms from high-touch professional sales requiring dedicated account management.
- Online Platforms:Direct-to-consumer portals with real-time inventory management and algorithmic dynamic pricing engines. United States and German live entertainment markets concentrate demand where EU AI Act transparency mandates create competitive openings for compliant forecasting systems.
- Third-Party Resellers:Secondary market intermediaries facilitating peer-to-peer transfers with blockchain-based royalty distribution. Regulatory fragmentation across state-level price-cap legislation in the United States and national transferability rules in Europe shapes margin capture.
- Box Offices:Venue-controlled physical sales points sustaining operations for walk-up demand and cash-preferred customer segments.
- Direct Sales:Enterprise procurement channels for corporate hospitality packages and season ticket blocks negotiated outside standard platform interfaces.
Online platforms dominate transaction velocity; third-party resellers face the most volatile regulatory headwinds.
Event Type:
Application-specific authentication requirements separate high-frequency re-entry environments from single-use credential scenarios.
- Festivals:Multi-day events requiring RFID wristbands with embedded payment and access control across camping, stage, and vendor zones. German and Japanese festival circuits drive integrated hardware procurement for cashless economy deployment.
- Sports Events:Season-long credential programs with rotating encryption for season ticket holders and dynamic single-game sales. United States professional leagues and European football clubs concentrate platform investment in anti-scalping verification protocols.
- Concerts:Single-night performances with high secondary market velocity and artist-controlled transfer restrictions.
- Theatrical Shows:Reserved seating environments with lower fraud risk and established subscription membership models in London and New York corridors.
Sports events sustain the largest credential issuance volumes; festivals command the highest per-attendee hardware spend.
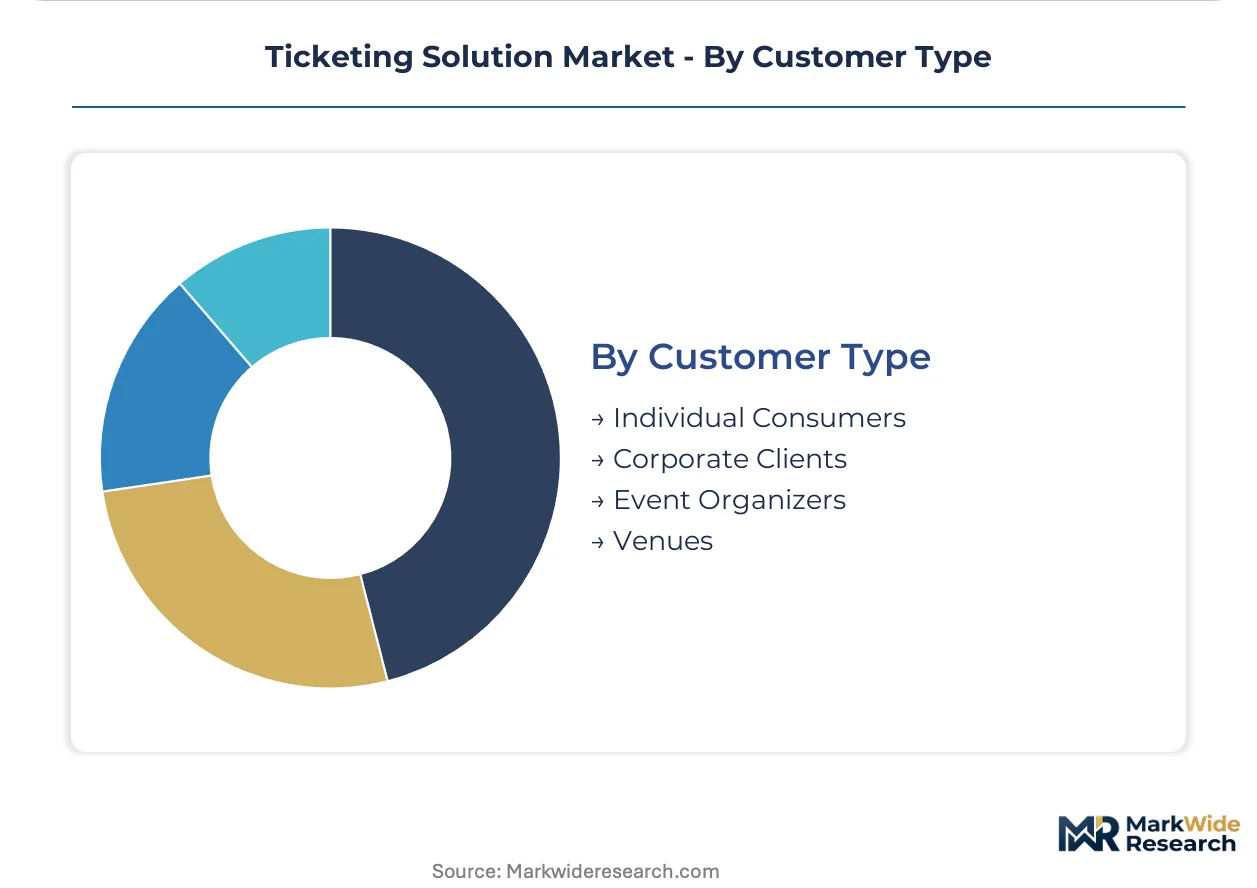
Customer Type:
Procurement pattern divergence separates individual transaction behavior from enterprise contract structures with negotiated service level agreements.
- Event Organizers:Primary demand aggregators requiring end-to-end platform solutions spanning issuance, validation, and first-party data capture. GDPR compliance costs and FCC wireless certification requirements shape vendor selection criteria in cross-border tour circuits.
- Venues:Infrastructure owners controlling access control system integration and hardware deployment decisions across legacy POS retrofits and greenfield NFC installations.
- Individual Consumers:End-users selecting credential formats based on smartphone compatibility and transfer flexibility preferences.
- Corporate Clients:Hospitality purchasers procuring block inventory through direct sales channels with customized reporting and attendee management requirements.
Event organizers control platform selection authority; venues determine hardware deployment feasibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 certification requirements for NFC readers anchor United States deployment timelines, while EU GDPR enforcement and Japan METI contactless standards shape compliance architectures across their respective markets.
United States
Sports stadium digitization and transit terminal upgrades drive hardware procurement cycles. FCC Part 15 Rules govern short-range wireless certification for NFC validation infrastructure. Los Angeles and New York entertainment corridors concentrate platform migration investments among major venue operators.
Germany
Festival cashless integration and integrated promotion operations sustain RFID wristband demand. EU AI Act algorithmic transparency mandates reshape dynamic pricing engine procurement. Berlin and Hamburg anchor live entertainment platform consolidation through CTS Eventim's vertical operations.
Japan
Smartphone penetration and contactless transit standards accelerate mobile ticket adoption. METI contactless authentication protocols govern secure element integration requirements. Tokyo entertainment districts lead subscription-based access membership uptake among young adult demographics.
India
Untapped sports stadium infrastructure and greenfield venue construction create deployment opportunities. BIS certification pathways for mobile-first platforms reduce market entry friction. Mumbai and Bangalore concentrate startup platform investments targeting digitization gaps in legacy access control systems.
United Kingdom
Theatrical subscription models and Premier League anti-scalping verification sustain credential innovation. GDPR consent architecture requirements tighten data retention compliance for cross-border tour circuits. London's West End and Manchester entertainment clusters drive dynamic QR code adoption for season ticket programs.
Ticketing Solution Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated venue operators commanding authentication stack control while self-service platforms capture mid-market organizer volumes. The market structures around three tiers: incumbent venue-integrated platforms, mid-market SaaS providers, and specialized hardware vendors. Dominant competitive moves include exclusive promoter contract negotiations and NFC reader hardware refresh cycles tied to festival cashless integration mandates.
Within the venue-integrated tier, Ticketmaster and Live Nation Entertainment occupy positions exemplifying control over North American stadium infrastructure and exclusive promoter relationships. Eventbrite represents the self-service platform archetype targeting small-to-mid event organizers through rapid onboarding tooling. CTS Eventim anchors European competitive positioning through combined promotion and ticketing operations across German-speaking markets.
| Leading Market Players |
|---|
| Ticketmaster |
| Eventbrite |
| StubHub |
| Live Nation Entertainment |
| CTS Eventim |
| See Tickets |
| Cubic Corporation |
| Infineon Technologies |
| HID Global |
| Others |
Value Network & Pricing Analysis
FCC Part 15 certification requirements for NFC reader hardware simultaneously gate supplier qualification and create three-tier pricing stratification across venue infrastructure procurement. Platform vendors bearing pre-certified architectures command premium positioning against uncertified competitors, while certification lag time compresses margins for late entrants racing deployment windows in United States stadiums and transit terminals.
Pricing Analysis
United States sports venues pay 15-25% premiums over German festival operators for equivalent NFC validation hardware due to FCC compliance overhead and domestic logistics costs. Pricing stratifies across ISO 27001-certified, FCC Part 15-compliant, and uncertified tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in the uncertified tier is intensifying because Taiwanese semiconductor foundries prioritize contracted volumes over spot-market orders. Small-to-mid event organizers exhibit highest price sensitivity; integrated venue operators with exclusive promoter contracts demonstrate lowest.
Supply Chain Analysis
Container availability constraints on the Taiwan-to-Long Beach trade lane inflate inbound logistics costs for NFC controller chip shipments by 8-12 weeks against pre-pandemic baselines. Hardware fabrication concentrates in Taiwan, South Korea, and China, with secure element manufacturing drawing from silicon wafer and embedded firmware dependencies. Single-source vulnerability in Taiwan-based NFC controller production exposes vendors to geopolitical disruption risk. Distribution runs through direct OEM relationships with venue operators and festival promoters, bypassing traditional distributor networks for high-volume deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where subscription-based access memberships and blockchain-based resale royalty layers expand faster than hardware credential issuance. Recurring revenue from cashless payment processing and dynamic pricing algorithm licensing now outpaces one-time NFC reader sales in margin contribution.
For Market Incumbents: Fortify control over venue access system integration through exclusive API partnerships with legacy POS operators, blocking entrant pathways into stadium infrastructure. Deepen backward integration into secure element firmware development to offset embedded systems talent scarcity squeezing development budgets. CTS Eventim's vertical promotion operations in Germany demonstrate how upstream control over artist relationships secures primary issuance volume against platform competitors. For New Entrants and Emerging Players: Differentiate on GDPR-compliant consent architecture as European enforcement actions against excessive data collection create procurement filters for cross-border tour circuits. Target India's greenfield sports stadium digitization where BIS certification pathways reduce incumbent advantage and legacy POS retrofit burdens are minimal. Lead with mobile-first platforms bypassing hardware-heavy RFID deployments to capture price-sensitive municipal venue operators in Mumbai and Bangalore. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape by elevating algorithmic transparency capabilities to due-diligence priority status for dynamic pricing engine targets. Long-term viability across the projection horizon hinges on recurring revenue attachment rates rather than hardware shipment volumes. ISO 27001 pre-certification serves as the critical signal to watch for platform vendors capable of accelerating enterprise sales cycles without compliance delay.| Strategic Initiative | Industry Significance |
|---|---|
| FCC Part 15 Certification Investment | Pre-certified NFC readers accelerate United States stadium deployment timelines against uncertified competitors. |
| GDPR Consent Architecture Development | Compliant data retention systems unlock European cross-border tour procurement for primary platform vendors. |
| Blockchain Resale Royalty Integration | Smart contract-enabled artist revenue sharing disrupts secondary market margin capture for incumbent resellers. |
| Festival Cashless Payment Partnership | RFID wristband-embedded credentials drive hardware refresh cycles at German and Japanese multi-day events. |
| Legacy POS API Bridge Development | Custom integration tooling reduces professional services costs and extends platform reach into aging venue infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with venue technology directors, festival operations managers, embedded systems engineers, and ticketing platform product leads. Secondary validation drew from FCC equipment authorization databases, EU GDPR enforcement action filings, METI contactless standard documentation, and SEC filings of publicly traded live entertainment conglomerates. Bottom-up credential volume estimates triangulated against top-down platform revenue disclosures to anchor market sizing.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning credential format, distribution channel, event type, and customer procurement pattern. CAGRs were derived from trend extrapolation of NFC deployment timelines, smartphone penetration curves, and regulatory compliance cost trajectories. Forecast inputs incorporated festival cashless integration mandates, EU AI Act algorithmic transparency implementation schedules, and India BIS certification pathway acceleration.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor supply from Taiwan, continued FCC Part 15 enforcement consistency, or accelerated India venue digitization would require recalibration. Forecasts reflect documented assumptions regarding NFC protocol standardization and blockchain credential adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Onboarding Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Game Engines Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market
Digital Solutions
Workspace As a Service Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Cloud Field Service Management (FSM) Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
United Kingdom ICT Market
Digital Solutions
Mobile Campaign Management Platform Market
Digital Solutions
Product Information Management Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Global Continuous Delivery Market