
 Global Cloud Infrastructure Service Market | 2026-2036
Global Cloud Infrastructure Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Infrastructure Service Market Foresight
Arm-based silicon is pivoting cloud compute economics away from x86 dominance in hyperscale data centers. Amazon Web Services leverages its Graviton processor family to reduce per-instance energy costs across its global fleet. Microsoft Azure sustains competitive pressure through custom Cobalt chips and deep integration with enterprise software stacks. Google Cloud differentiates via its Tensor Processing Unit roadmap for AI inference workloads.
Cloud infrastructure service denotes on-demand provisioning of compute, storage, and networking resources through virtualized or bare-metal abstraction layers, typically metered by consumption and delivered via API-driven orchestration. These services enable enterprises to replace capital-intensive data center ownership with operational expenditure models while maintaining workload portability across geographic zones. Infrastructure as a Service anchors current revenue pools as the foundational layer for enterprise migration, though Function as a Service captures the fastest expansion as event-driven architectures proliferate. Hybrid Cloud deployment models concentrate margin pools where regulated industries require on-premises control paired with burst capacity to public endpoints.
FDA guidelines on cloud-based healthcare data processing, EU GDPR data-localization mandates, and China's MEE dual carbon goals collectively shape facility siting and energy sourcing decisions across provider networks. India's BIS cloud security certification requirements and TRAI data-center localization rules further fragment compliance architectures for multinational operators. Stakeholders must monitor sovereign AI infrastructure investments in Saudi Arabia, Singapore, and Brazil as these reshape cross-border data flow assumptions and provider partnership structures.
Market Dynamics
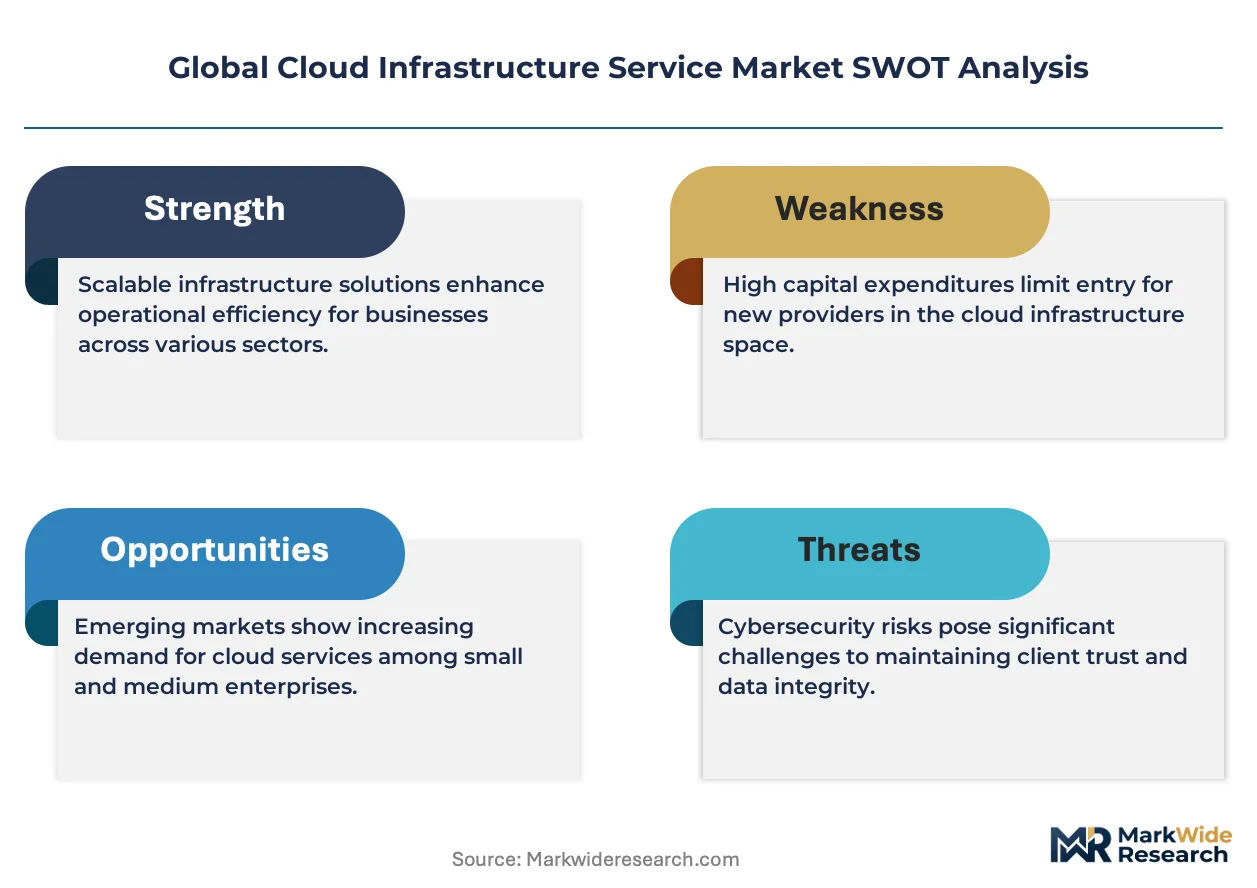
Arm-based silicon architectures are consolidating compute economics across hyperscale data centers, forcing infrastructure providers to redesign thermal and power distribution systems while sovereign data residency mandates fragment facility deployment strategies.
Growth Catalysts
- EU AI Act compliance deadlines:Financial services firms in Frankfurt and Paris are accelerating cloud-native migrations to meet algorithmic accountability requirements, expanding managed infrastructure contracts.
- India's domestic hyperscale buildout:TRAI data-center localization rules and BIS cloud security certifications are pulling AWS, Microsoft, and Google to establish Mumbai and Hyderabad availability zones.
- Function as a Service proliferation:Event-driven serverless architectures are displacing provisioned virtual machines in retail and logistics workloads, metering compute by actual execution time rather than reserved capacity.
Market Restraints
- Lithium-ion battery supply concentration:Uninterruptible power systems for hyperscale facilities depend on cathode materials from concentrated East Asian processing capacity, exposing providers to input cost volatility.
- GDPR data-localization friction:Cross-border workload portability faces structural barriers as EU member states implement divergent supervisory authority interpretations of lawful transfer mechanisms.
- Optical interconnect bandwidth limits:Electrical-to-optical conversion overhead in current generation silicon photonics constrains rack-scale disaggregation economics below 800G per lane thresholds.
Strategic Opportunities
- Saudi sovereign AI infrastructure:NEOM and SDAIA investments are creating greenfield demand for specialized GPU clusters and liquid-cooled facilities outside traditional demand centers.
- ISO 42001 AI management systems:Early certification against this emerging standard offers providers differentiation in enterprise procurement evaluations ahead of mandatory adoption curves.
- Edge-to-cloud orchestration convergence:Kubernetes federation across 5G multi-access edge computing nodes and centralized hyperscale pools enables new low-latency application categories in autonomous systems.
Industry Challenges
- Immersion cooling technician scarcity:Dielectric fluid handling and two-phase thermal management expertise remains concentrated among semiconductor fabrication veterans, constraining facility retrofit timelines.
- Legacy mainframe integration complexity:Financial institutions in London and Tokyo face operational risk when orchestrating COBOL workloads alongside containerized microservices across hybrid topologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Infrastructure Service Market |
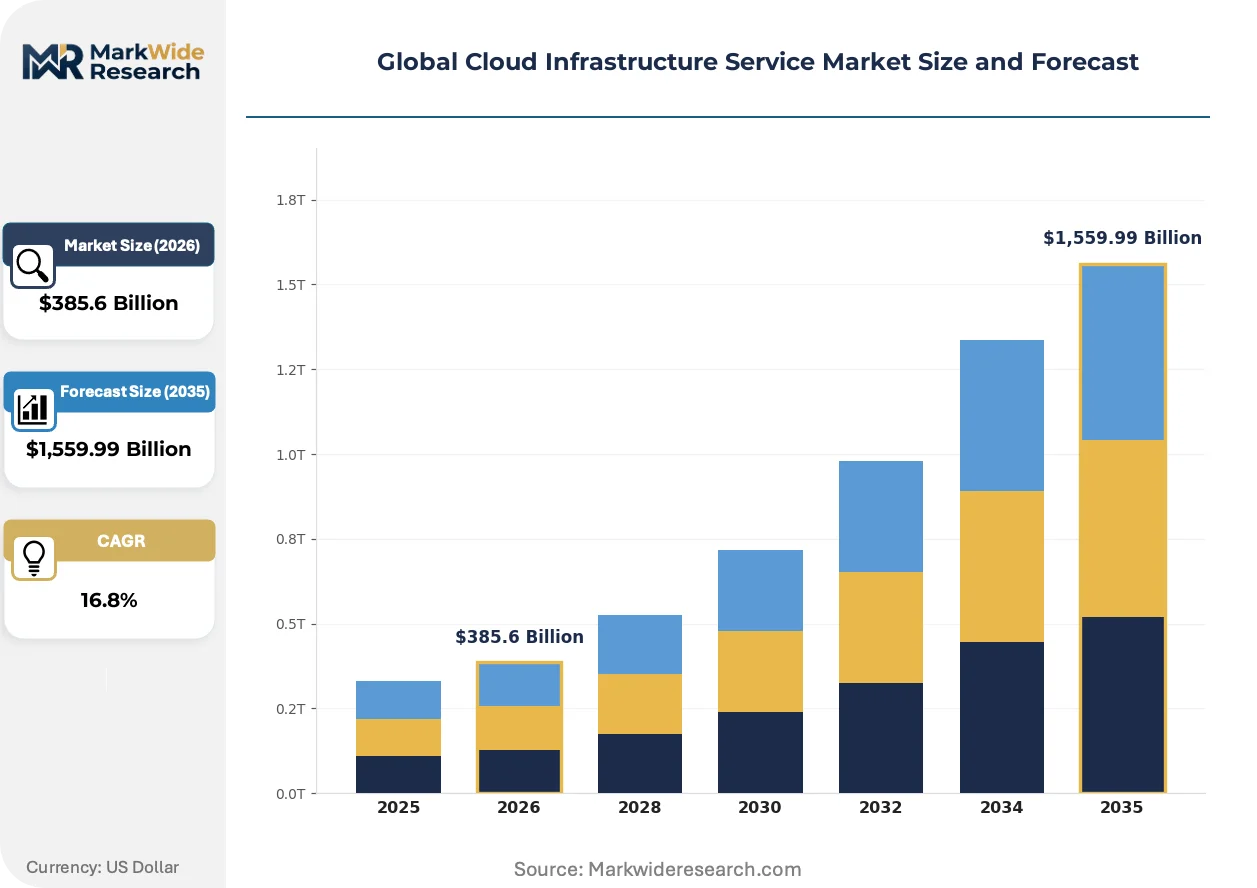
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $1,559.99 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service, Managed Cloud Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Application: Data Backup & Recovery, Big Data Analytics, Web Hosting, Content Delivery Networks, Machine Learning Platforms End User Industry: Information Technology Firms, Telecommunications Providers, Media & Entertainment, Manufacturing Enterprises, Government Agencies |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Alibaba Cloud, Oracle Cloud Infrastructure, IBM Cloud, Salesforce, CoreWeave, Crusoe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Infrastructure Service Market Shifts & Advancements
Silicon specialization and regulatory fragmentation are simultaneously compressing hardware margins and expanding service attach opportunities across the infrastructure stack.
Arm-based server processors are consolidating x86 dominance in general-purpose compute pools. Hyperscale operators in Oregon and Dublin are deploying Graviton and Cobalt instances for web serving and containerized workloads, reducing per-rack power draw by thirty to forty percent against comparable x86 configurations. This consolidation is enabling providers to defer data center expansion timelines while maintaining committed capacity growth rates.
The EU AI Act's risk-based classification system is reshaping facility siting decisions across provider networks. High-risk AI training workloads now require documented technical documentation and human oversight capabilities that influence control plane architecture design. German automotive manufacturers and French healthcare consortia are demanding contractual guarantees of EU-based model training infrastructure, accelerating Frankfurt and Paris region investments.
Consumption-based procurement models are displacing reserved instance commitments in enterprise buyer segments. Retail and media companies in São Paulo and Singapore are negotiating pure pay-per-use contracts with automatic scaling clauses rather than three-year capacity reservations. This shift concentrates margin risk with providers during demand troughs while transferring utilization optimization burden to vendor operations teams.
Global Cloud Infrastructure Service Market Segmentation
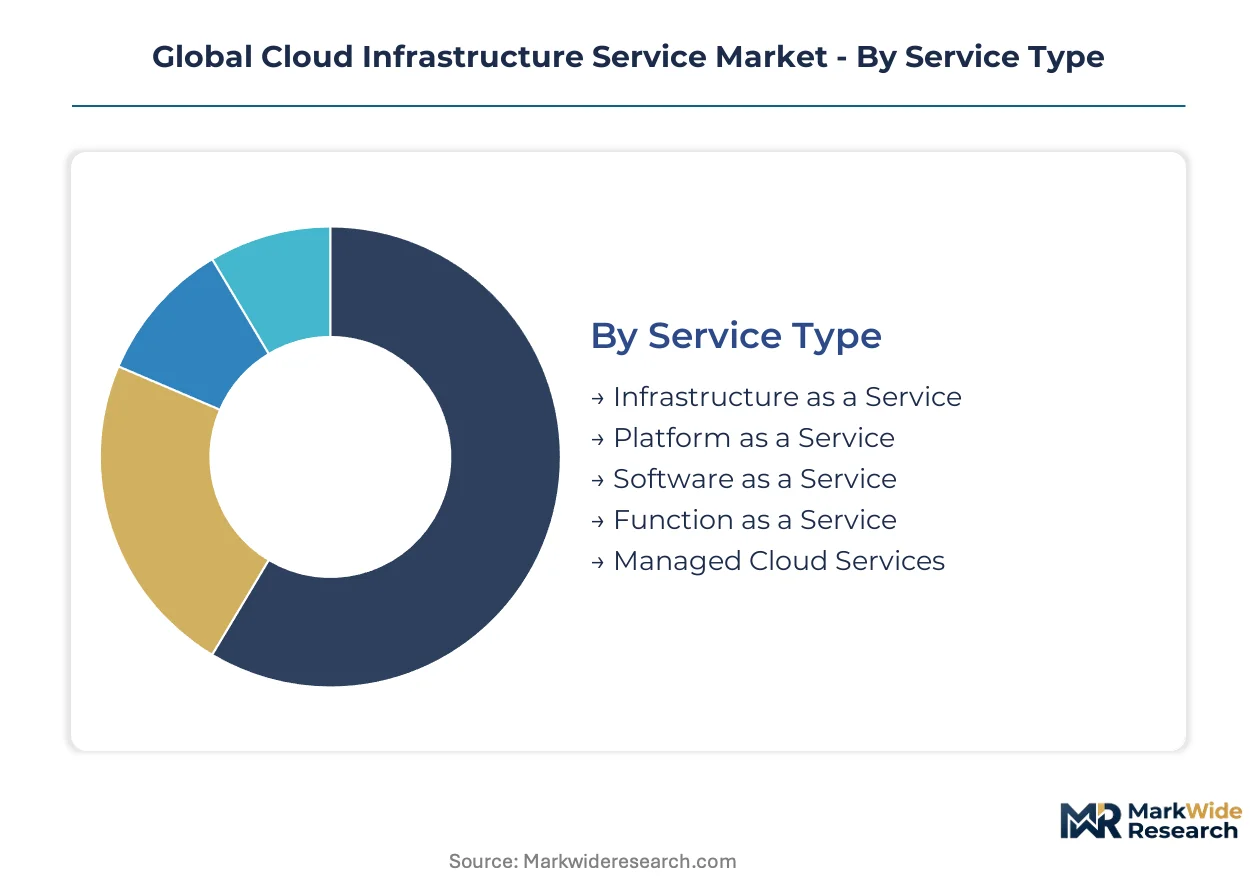
Cloud infrastructure segmentation reveals divergent compliance obligations across service tiers, with sovereign data residency rules and AI governance frameworks creating distinct certification burdens for each category. Procurement patterns in Frankfurt, Mumbai, and Riyadh demonstrate how regulatory fragmentation reshapes segment prioritization.
Service Type:
Infrastructure as a Service demands ISO 27001 and SOC 2 Type II certifications for enterprise procurement, while Function as a Service triggers additional scrutiny under EU AI Act algorithmic accountability requirements for event-driven workloads processing personal data.
- Infrastructure as a Service:Virtualized compute, storage, and networking resources provisioned through API-driven orchestration layers. German automotive manufacturers and French healthcare consortia in Frankfurt and Paris regions require contractual guarantees of EU-based infrastructure, accelerating managed IaaS contract expansions for high-risk AI training workloads.
- Function as a Service:Event-driven serverless execution environments metering compute by actual execution time rather than reserved capacity. Retail and logistics operators in São Paulo and Singapore negotiate pure pay-per-use contracts with automatic scaling clauses, displacing provisioned virtual machines in latency-sensitive applications.
- Platform as a Service:Managed runtime environments abstracting infrastructure management from application deployment.
- Software as a Service:Fully managed application delivery eliminating client-side infrastructure ownership.
- Managed Cloud Services:Outsourced operational responsibility for cloud environment optimization and security monitoring.
Infrastructure as a Service sits at the top of the volume ranking, with Function as a Service climbing the fastest.
Deployment Model:
Cost structures stratify sharply across deployment architectures, with hybrid configurations commanding premium pricing for orchestration complexity while public cloud delivers lowest unit economics at scale.
- Hybrid Cloud:Integrated orchestration across on-premises infrastructure and public cloud endpoints enabling workload portability. Regulated industries in London and Tokyo require on-premises control paired with burst capacity, concentrating margin pools where COBOL legacy systems interface with containerized microservices.
- Public Cloud:Shared multi-tenant infrastructure delivered through hyperscale provider networks. Oregon and Dublin facilities deploy Arm-based Graviton and Cobalt instances, reducing per-rack power draw by thirty to forty percent against x86 configurations while deferring expansion timelines.
- Private Cloud:Single-tenant dedicated infrastructure isolating compute and storage resources.
- Community Cloud:Shared infrastructure serving specific industry verticals or regulatory jurisdictions.
Public Cloud captures the largest revenue base, with Hybrid Cloud expanding most quickly among regulated enterprise adopters.
Application:
Application workloads exhibit divergent maturity curves, with established categories facing margin compression while AI-infused platforms attract infrastructure investment.
- Machine Learning Platforms:Specialized compute clusters optimized for model training and inference workloads. Saudi Arabia's NEOM and SDAIA investments create greenfield demand for GPU clusters and liquid-cooled facilities outside traditional demand centers, requiring ISO 42001 AI management system certifications ahead of mandatory adoption curves.
- Big Data Analytics:Distributed processing frameworks handling petabyte-scale dataset exploration. India's BIS cloud security certification requirements and TRAI data-center localization rules pull AWS, Microsoft, and Google to establish Mumbai and Hyderabad availability zones for analytics workloads.
- Data Backup & Recovery:Resilient storage architectures ensuring business continuity against infrastructure failures.
- Web Hosting:Scalable content delivery and application serving for internet-facing properties.
- Content Delivery Networks:Geographically distributed edge caching minimizing latency for media and software distribution.
Web Hosting maintains the broadest installed base, with Machine Learning Platforms gaining share fastest on sovereign AI infrastructure investments.
End User Industry:
Industry verticals present distinct procurement maturity profiles, with technology-native sectors driving standardization while legacy industries negotiate custom compliance architectures.
- Information Technology Firms:Technology-native organizations with sophisticated cloud-native development practices. Kubernetes federation across 5G multi-access edge computing nodes and centralized hyperscale pools enables new low-latency application categories in autonomous systems for software vendors.
- Government Agencies:Public sector entities with stringent sovereignty and security classification requirements. FDA guidelines on cloud-based healthcare data processing and China's MEE dual carbon goals shape facility siting and energy sourcing decisions across provider networks serving state-level contracts.
- Telecommunications Providers:Network operators integrating cloud infrastructure with 5G core and edge services.
- Media & Entertainment:Content creators and distributors requiring elastic capacity for production and streaming peaks.
- Manufacturing Enterprises:Industrial operators deploying cloud-connected IoT and predictive maintenance systems.
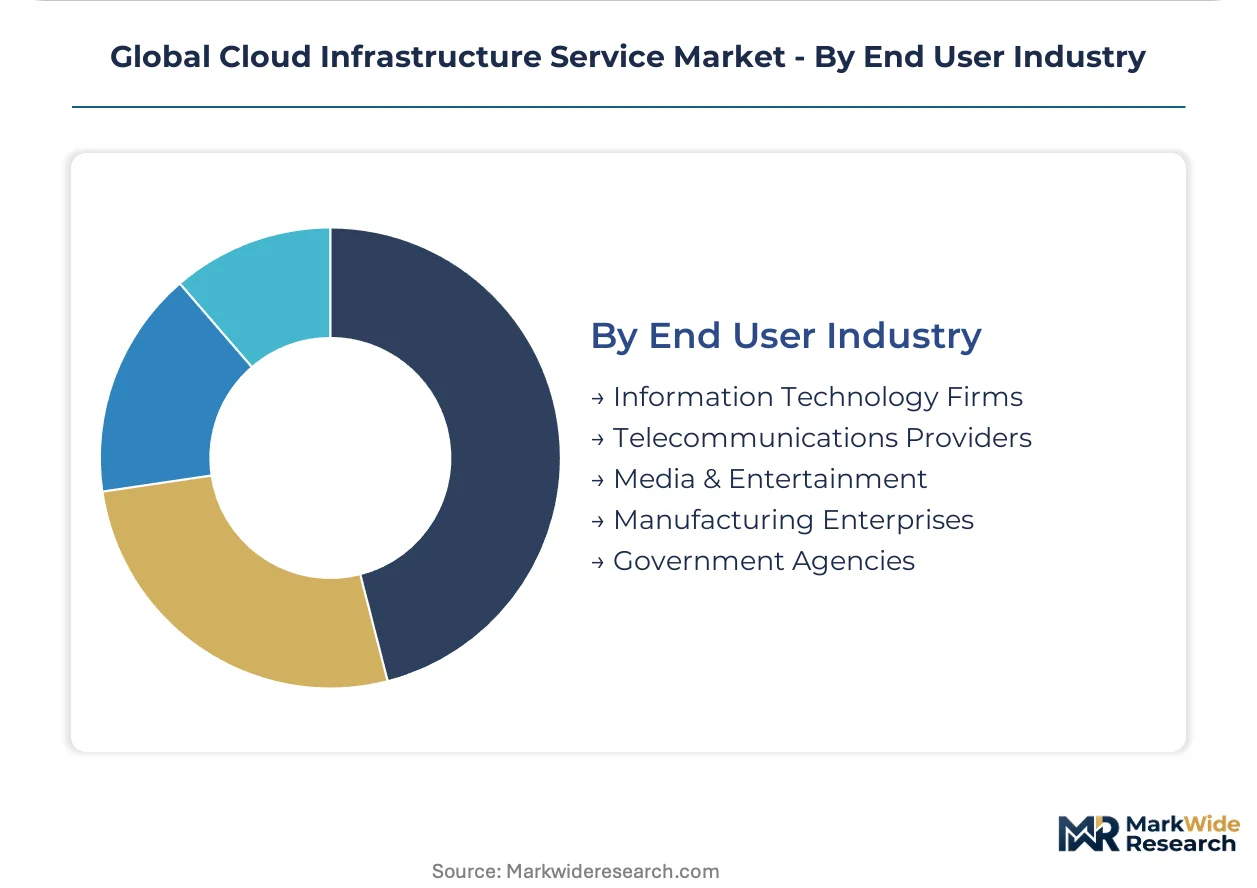
Information Technology Firms dominate current procurement volumes, with Government Agencies expanding most steeply on sovereign infrastructure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oregon's hyperscale cluster anchors infrastructure deployment economics, with Arm-based silicon retrofits deferring expansion timelines across the Pacific Northwest. Sovereign data mandates in Frankfurt, Mumbai, and Riyadh fragment facility siting strategies while concentrating compliance investment.
United States
Financial services firms in New York and Chicago accelerate cloud-native migrations to meet SEC cybersecurity disclosure rules. FDA guidelines on cloud-based healthcare data processing reshape facility siting for pharmaceutical analytics clusters. Oregon and Virginia data centers deploy Graviton and Cobalt instances, reducing per-rack power draw against x86 configurations.
Germany
Automotive manufacturers in Stuttgart and Munich demand contractual guarantees of EU-based model training infrastructure. EU AI Act risk-based classification systems influence control plane architecture design for high-risk AI workloads. Frankfurt region investments accelerate on algorithmic accountability requirements from BaFin supervisory guidance.
India
Domestic hyperscale buildout pulls AWS, Microsoft, and Google to establish Mumbai and Hyderabad availability zones. TRAI data-center localization rules and BIS cloud security certifications fragment compliance architectures for multinational operators. Bangalore's technology corridor drives Kubernetes federation across 5G multi-access edge computing nodes.
Saudi Arabia
NEOM and SDAIA investments create greenfield demand for specialized GPU clusters outside traditional demand centers. SFDA and national AI authority frameworks shape sovereign infrastructure procurement for healthcare and energy applications. Riyadh-based facilities require liquid-cooled architectures for thermal management in desert climates.
Singapore
Retail and media companies negotiate pure pay-per-use contracts with automatic scaling clauses rather than reserved capacity commitments. Maritime and logistics operators deploy edge-to-cloud orchestration for port automation and autonomous vessel coordination. The city-state's data sovereignty framework attracts regional headquarters for Asia-Pacific cloud operations.
Global Cloud Infrastructure Service Market Competitive Landscape
Strategic partnerships dominate the current landscape as hyperscale providers align with sovereign infrastructure mandates and specialized compute requirements. The vendor base concentrates around three operational archetypes: integrated platform operators with custom silicon roadmaps, vertical specialists serving regulated industries, and emerging GPU-focused challengers. Geographic expansion into secondary markets and technology licensing for Arm-based deployments represent the primary competitive vectors.
Within the integrated platform tier, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify divergent specialization strategies. AWS leverages its Graviton processor family to reduce per-instance energy costs across global fleet operations. Microsoft Azure sustains competitive pressure through custom Cobalt chips and enterprise software stack integration. Google Cloud occupies a position differentiated via its Tensor Processing Unit roadmap for AI inference workloads.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Alibaba Cloud |
| Oracle Cloud Infrastructure |
| IBM Cloud |
| Salesforce |
| CoreWeave |
| Crusoe |
| Others |
Supply & Pricing Matrix
Captive silicon design at AWS, Microsoft, and Google anchors both supply security and pricing power in compute infrastructure, insulating hyperscale providers from x86 vendor pricing cycles while creating proprietary cost structures competitors cannot replicate.
Pricing Analysis
Input-cost pass-through from lithium-ion battery cathode materials and Arm-based processor wafer economics shapes contract negotiations for hyperscale facility expansions. Three-tier pricing structure across reserved instances, on-demand compute, and spot capacity segments German automotive manufacturers as least price-sensitive given EU AI Act compliance mandates, while retail and media companies in São Paulo drive hardest bargain on pure pay-per-use terms. Cost compression in general-purpose compute is intensifying because Graviton and Cobalt deployments reduce per-rack power draw against legacy x86 configurations.
Supply Chain Analysis
Photoresist and advanced packaging materials supply rests on Japanese specialty chemical producers and Taiwanese foundry operations, creating concentrated dependency for custom silicon roadmaps. Lithium processing for facility UPS systems draws from Chilean and Australian mining operations with Chinese refining dominance. Single-source vulnerability in silicon photonics at 800G per lane thresholds constrains rack-scale disaggregation timelines. Distribution runs through direct hyperscale procurement teams rather than channel intermediaries, compressing margin capture for component vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between German compliance premiums and Indian operational costs creates structural margin expansion for providers mastering dual-certificate architectures across EU AI Act and BIS cloud security regimes.
For Market Incumbents: Cement sovereign data residency capabilities through Frankfurt and Mumbai zone expansions before regulatory deadlines harden competitive moats. Invest in liquid-cooled facility designs for Riyadh deployments where thermal management expertise scarcity blocks challenger entry. ISO 42001 certification investment anchors differentiation as algorithmic accountability mandates propagate across automotive and healthcare verticals. For New Entrants and Emerging Players: Mid-market financial institutions in London and Tokyo facing COBOL legacy integration complexity represent underserved buyer archetype demanding hybrid orchestration specialists. Sovereign AI infrastructure buildouts in Saudi Arabia and Singapore offer most penetrable geography given greenfield procurement patterns outside established hyperscale relationships. Lead with Kubernetes federation expertise across 5G edge nodes as differentiated go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for vertical specialists serving regulated industries because compliance certification burdens fragment procurement decisions away from generalist platforms. Five-to-ten year viability hinges on Arm-based silicon roadmap execution and sovereign facility deployment pace. Watch GPU cluster utilization rates in NEOM and SDAIA projects as inflection indicator for specialized infrastructure demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Roadmap Execution | Graviton and Cobalt deployments reduce energy costs across Oregon and Dublin hyperscale fleets. |
| Sovereign Facility Certification | EU AI Act and BIS compliance architectures capture German automotive and Indian analytics procurement. |
| Liquid-Cooled Infrastructure Buildout | Desert climate facilities in Riyadh require dielectric fluid expertise concentrated among semiconductor veterans. |
| Edge-to-Cloud Orchestration Platform | Kubernetes federation across 5G MEC nodes enables autonomous systems for Singapore maritime operators. |
| ISO 42001 Early Certification | AI management system credentials differentiate providers ahead of mandatory enterprise procurement curves. |
Research Methodology
Bottom-up enterprise workload modeling reconciled against top-down hyperscale capex tracking forms the analytical core of this study. Primary interviews with cloud infrastructure procurement officers, platform engineering directors, data center facility managers, and regulatory compliance leads combined with secondary validation from SEC filings, hyperscaler quarterly capex disclosures, and TRAI localization rule filings. Triangulation across deployment model segmentation, service type tiers, and geographic regulatory clusters ensures dimensional consistency.
Input-output matrix framing connects silicon wafer supply, lithium-ion battery procurement, and facility power contracting to compute instance pricing and availability zone expansion decisions across the analysis window. Segmentation dimensions modeled include service type, deployment architecture, end-user industry vertical, and regional sovereign compliance cluster. CAGRs derive from weighted capacity buildout schedules and consumption-based procurement adoption curves, with Arm-based server penetration and GPU cluster deployment pace as cloud-specific forecast inputs.
Inputs from hyperscaler capex disclosures and national regulator filings were available through the study window; gaps in sovereign AI infrastructure procurement timelines introduce uncertainty bands around Saudi Arabia and Singapore demand trajectories. Forecasts reflect documented assumptions regarding EU AI Act enforcement consistency and lithium supply chain stability. A small set of named triggers—immersion cooling technician availability, optical interconnect 800G lane economics, and GDPR supervisory authority divergence—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Norway Data Center Networking Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
India Data Center Power Market