
 Kuwait ICT Market | 2026-2036
Kuwait ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait ICT Market Outlook
Project finance for large-scale data center builds is reconfiguring competitive entry barriers in Kuwait's ICT landscape. Huawei Technologies Co. Ltd. leverages its integrated equipment-to-cloud portfolio to anchor infrastructure contracts across government and telecom verticals. Zain competes through aggressive 5G network densification that sustains its retail and enterprise subscriber base. Cisco Systems Inc. differentiates via security-centric enterprise networking architectures that dominate Kuwait's banking and oil sector procurement cycles.
Information and communications technology in Kuwait encompasses computing hardware, enterprise software, telecommunications networking equipment, and associated managed services that process, store, and transmit data across public and private infrastructures. The technology stack operates on fiber-optic backbone specifications exceeding 10 Gbps throughput in metro zones, with latency requirements under 20 milliseconds for financial trading applications. Services and software capture expanding margin pools as government and oil sector buyers shift from capital-intensive hardware procurement to subscription-based cloud and managed service arrangements. Hardware retains structural importance in networking and data center buildouts, though margin compression persists amid standardized server and storage commoditization.
The Central Bank of Kuwait enforces stringent data localization and cybersecurity protocols that shape enterprise architecture decisions across financial services. The Communications and Information Technology Regulatory Authority governs spectrum allocation, cloud service licensing, and cross-border data flow permissions that directly condition market access for foreign vendors. Stakeholders must monitor evolving national cloud sovereignty requirements and alignment between vendor certification programs and Kuwait's emerging critical infrastructure protection standards.
Market Dynamics
The Central Bank of Kuwait's data localization mandates are forcing wholesale replatforming of financial infrastructure, compressing procurement cycles and elevating cybersecurity architecture to the primary vendor selection criterion.
Growth Catalysts
- National E-Government Framework:Kuwait's digital transformation directives mandate cloud-first procurement across ministries, creating sustained demand for sovereign cloud infrastructure and managed services.
- Oil Sector Modernization:Kuwait Petroleum Corporation subsidiaries are deploying industrial IoT and predictive analytics across upstream operations, requiring high-throughput fiber connectivity and edge computing nodes.
- 5G Spectrum Allocation:The Communications and Information Technology Regulatory Authority's release of mid-band spectrum enables network densification that supports enterprise private wireless deployments.
Market Restraints
- Data Sovereignty Compliance Costs:The Central Bank of Kuwait's strict localization rules force foreign cloud providers to build in-country facilities, raising capital requirements and extending time-to-market.
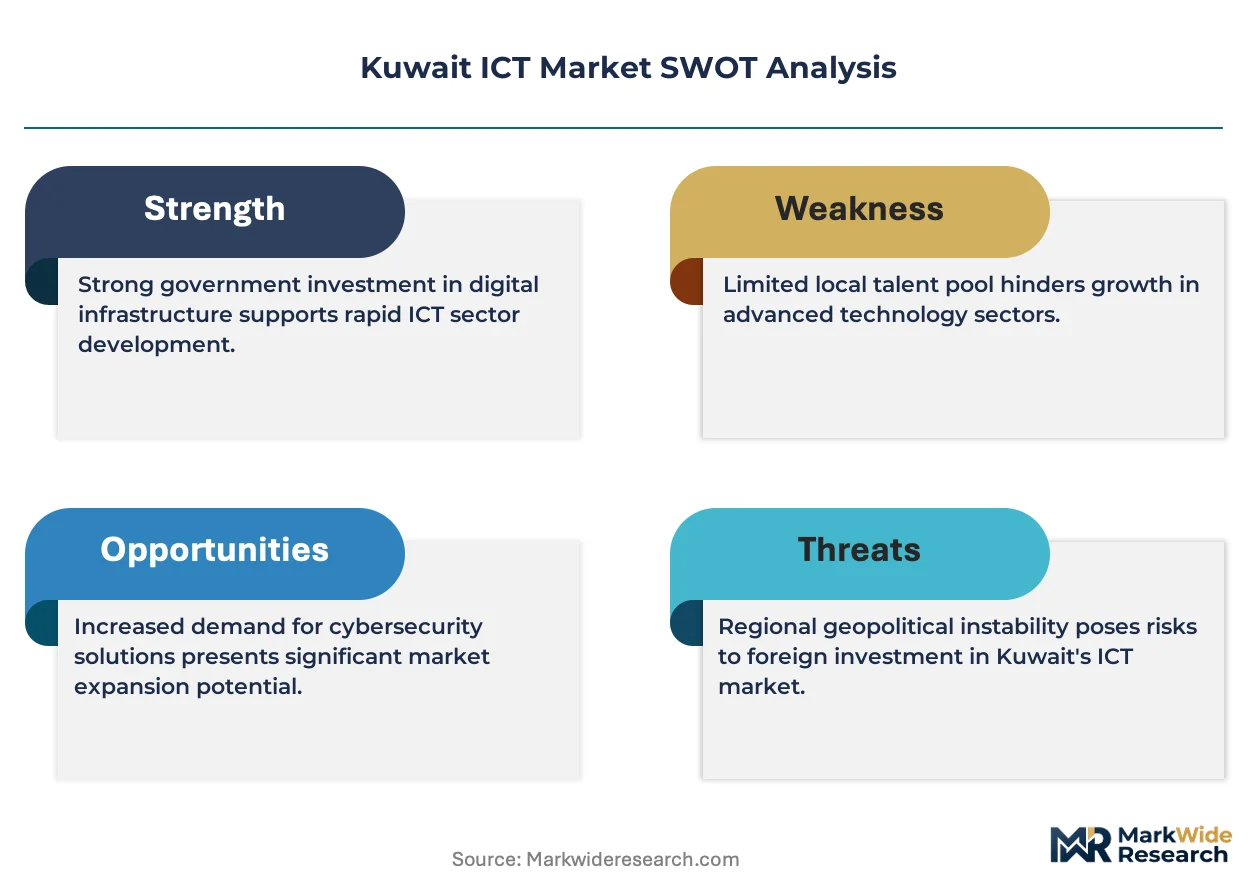
- Skilled Workforce Scarcity:Domestic supply of certified cybersecurity architects and cloud engineers falls short of demand, inflating labor costs and project timelines.
- Hardware Import Dependencies:Server and networking equipment relies on concentrated East Asian manufacturing bases, exposing buyers to shipping volatility and currency fluctuation risks.
Strategic Opportunities
- Financial Services Cybersecurity:The Central Bank of Kuwait's escalating audit frequency creates whitespace for managed security service providers offering continuous compliance monitoring.
- Smart City Infrastructure:Kuwait Municipality's integrated urban management platforms require converged IoT, AI, and edge computing stacks for traffic, utilities, and public safety coordination.
- SME Cloud Adoption:Underpenetrated mid-market segments present volume opportunities as subscription pricing models reduce upfront barriers for family-owned trading and logistics firms.
Industry Challenges
- Legacy System Integration:Oil ministry and banking core systems built on 1990s-era architectures resist API-based connectivity, forcing expensive middleware layers.
- Certification Bottlenecks:Vendor accreditation through the Communications and Information Technology Regulatory Authority involves multi-quarter security reviews that delay contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait ICT Market |
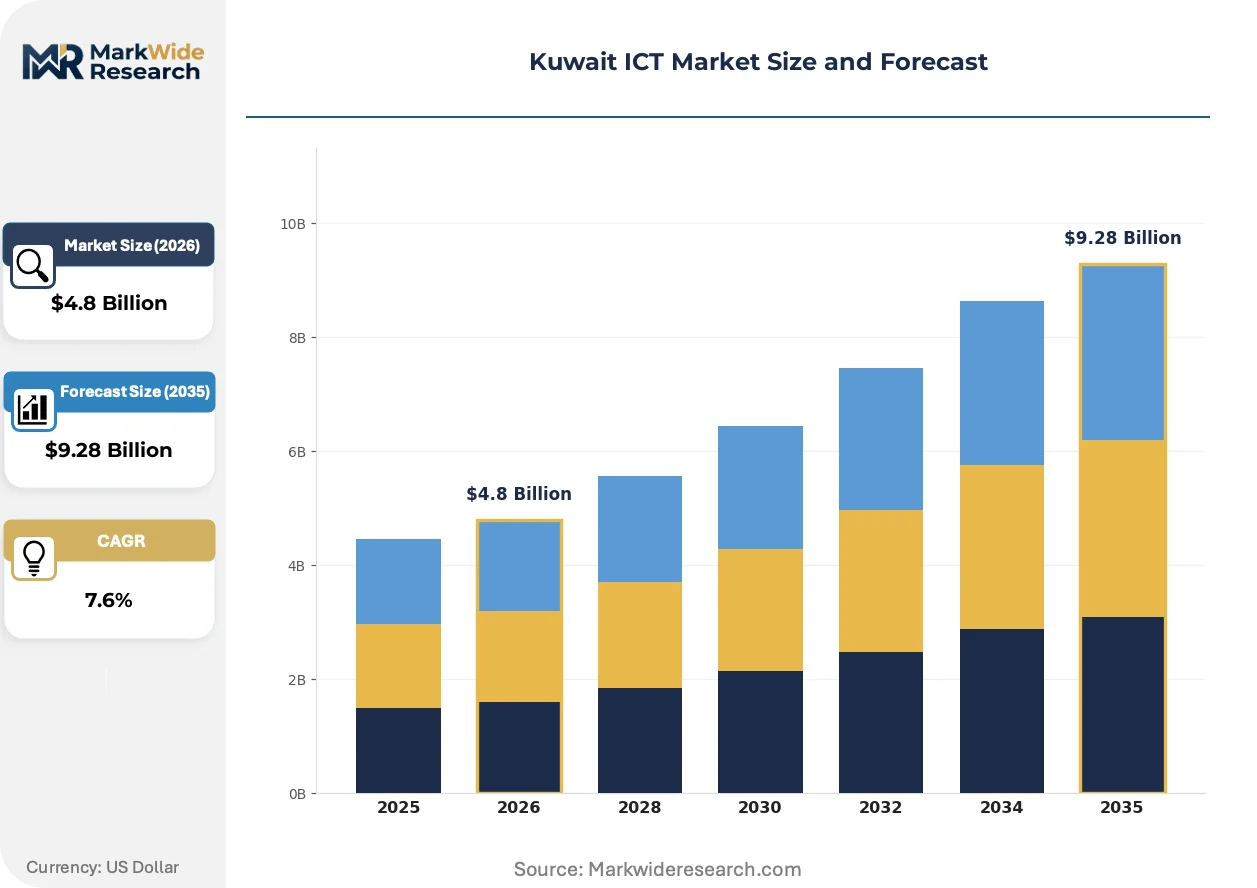
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Networking, Services End User: Government, Education, Healthcare, Retail Deployment: On-premises, Cloud, Hybrid, Managed Technology: AI, IoT, Cybersecurity, Big Data |
| Companies Covered | International Business Machines Corp., Huawei Technologies Co. Ltd., Zain, Gulfsat, Arabian Information Technology Solutions Company, Ooredoo, Cisco Systems Inc., International Turnkey Systems, stc Kuwait, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait ICT Market Strategic Shifts
Hyperconverged infrastructure is collapsing traditional three-tier data center architectures across Kuwait's enterprise landscape, while regulatory pressure on data residency accelerates localization investments.
Software-defined wide area networking is collapsing hardware-centric branch connectivity models. Kuwaiti banks and retail chains are adopting SD-WAN to aggregate MPLS, broadband, and 4G/5G links into unified transport fabrics. This collapse of router-centric architectures is compressing hardware refresh cycles and shifting margin pools to subscription-based orchestration platforms.
The Central Bank of Kuwait's circular on operational resilience mandates annual penetration testing and 24-hour incident reporting for all licensed financial institutions. This regulatory pressure is forcing CISOs to consolidate vendor relationships around integrated security platforms rather than point solutions. Tier-one banks are responding by procuring managed detection and response services under multi-year frameworks.
Enterprise buyers are unbundling hardware procurement from professional services, demanding itemized pricing transparency that exposes traditional integrator margins. Kuwait's oil sector joint ventures are leading this shift, separating infrastructure purchasing from implementation contracts to optimize capital allocation. This behavioral change is most visible in Ahmadi and Mina Al-Ahmadi industrial zones where operator procurement teams have adopted category-management approaches.
Kuwait ICT Market Segmentation
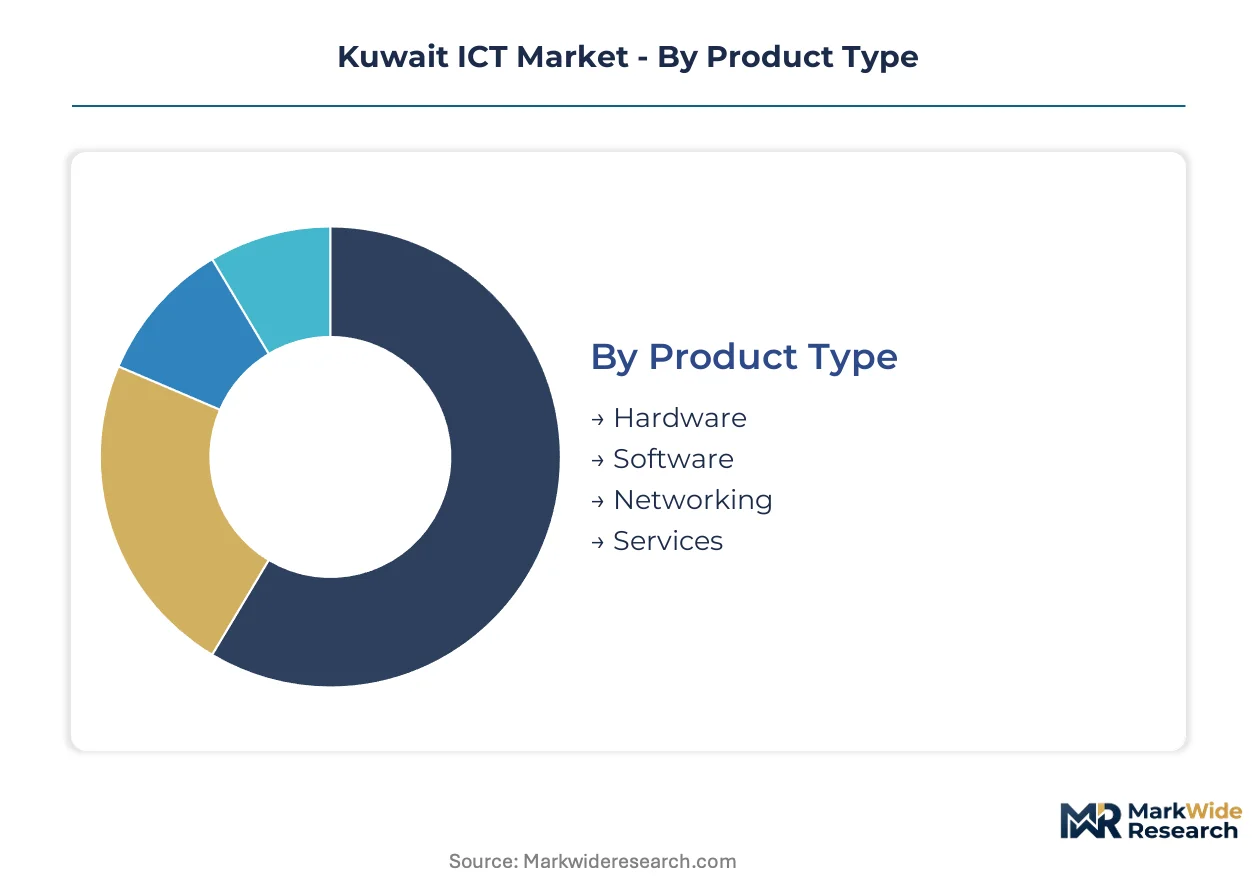
Kuwait's ICT market segments reflect procurement patterns shaped by the Central Bank's data localization mandates and the national e-government framework's cloud-first directives. Each dimension captures distinct buyer behaviors across sovereign infrastructure requirements and sector-specific compliance thresholds.
Product Type:
Cost tier differentiation separates capital-intensive infrastructure from recurring service expenditures across Kuwait's public and private procurement cycles.
- Hardware:Servers, storage arrays, and networking equipment form the physical foundation of data center builds. Kuwait Petroleum Corporation subsidiaries and government ministries drive demand for high-throughput fiber-optic infrastructure in Ahmadi and Mina Al-Ahmadi industrial zones, though margin compression persists amid standardized server commoditization.
- Services:Managed infrastructure, system integration, and professional consulting engagements capture expanding margin pools as buyers shift from capital expenditure to operational expenditure models. The Central Bank's tightening audit frequency elevates demand for continuous compliance monitoring and 24-hour incident response capabilities.
- Software:Enterprise applications, operating systems, and middleware layers enable core business process automation.
- Networking:Routers, switches, and wireless access points interconnect distributed computing resources.
Services commands the established base. The steepest expansion runs through Software.
End User:
Application context determines architectural requirements across Kuwait's sector-specific regulatory environments.
- Government:Ministry-level digital transformation mandates under the national e-government framework create sustained demand for sovereign cloud infrastructure. The Communications and Information Technology Regulatory Authority governs certification and procurement eligibility, compressing vendor selection timelines around compliance-verified solution stacks.
- Healthcare:Hospital information systems and telemedicine platforms require HIPAA-aligned data governance architectures. Kuwait's Ministry of Health modernization programs are deploying integrated electronic medical record systems with strict residency requirements for patient data.
- Education:K-12 and university digital learning platforms drive endpoint device and connectivity investments.
- Retail:Point-of-sale modernization and e-commerce backend infrastructure support omnichannel operations.
Government anchors procurement volume. Healthcare is gaining share fastest amid clinical system digitization timelines.
Deployment:
Customer type and internal capability maturity dictate infrastructure control preferences across Kuwait's enterprise landscape.
- Cloud:Public and private cloud instances deliver compute, storage, and application services via subscription models. Foreign providers face capital requirements for in-country facility builds under Central Bank localization rules, extending time-to-market for international entrants.
- Hybrid:Integrated on-premises and cloud environments balance legacy system retention with scalability needs. Kuwaiti banks are adopting hybrid architectures to maintain core banking system stability while deploying cloud-native customer-facing applications.
- On-premises:Self-managed data centers retain sensitive workloads under direct organizational control.
- Managed:Third-party operated infrastructure offloads operational burden to specialized service providers.
Hybrid deployments command the established base. Cloud is climbing the fastest as sovereign facility investments mature.
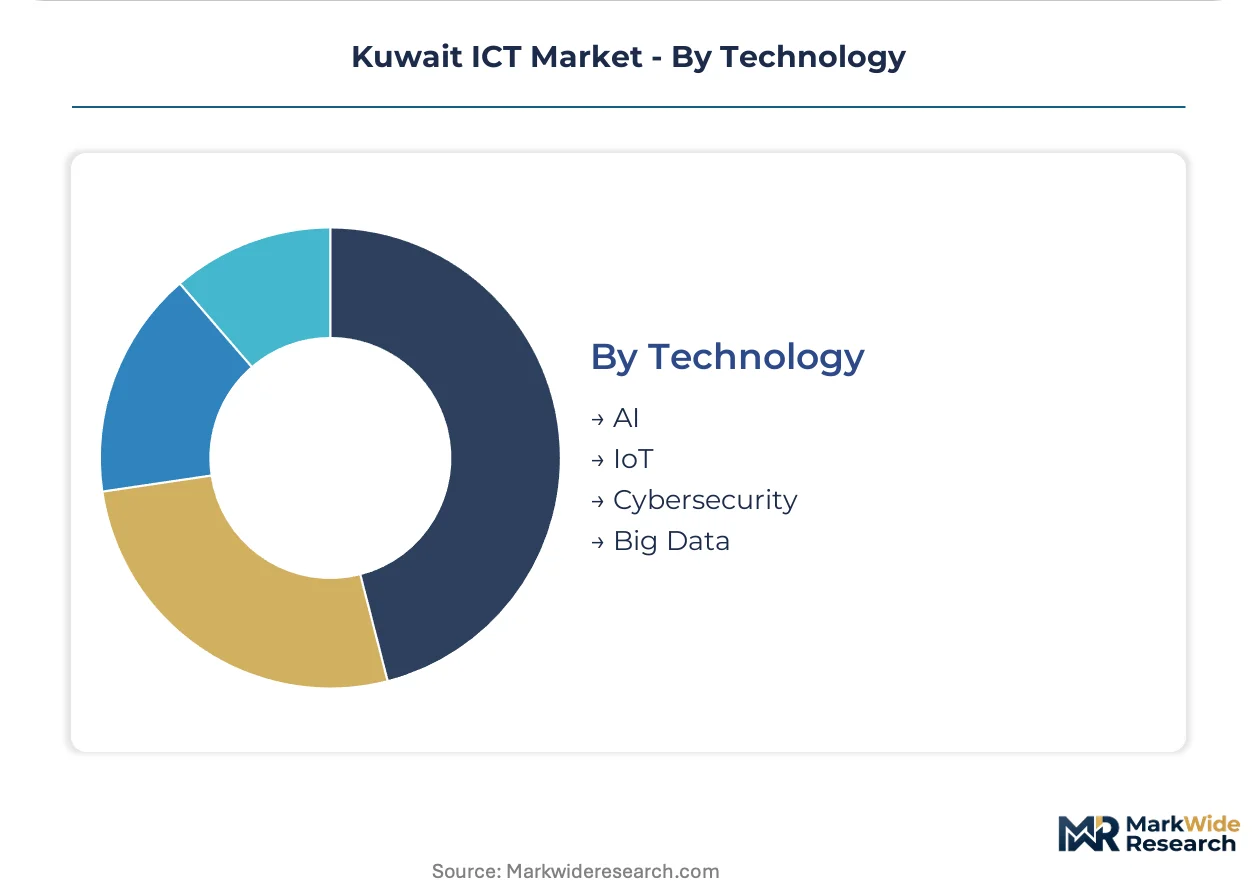
Technology:
Maturity curves and implementation complexity separate experimental adoption from scaled production deployment across Kuwait's technology stack.
- Cybersecurity:Identity management, threat detection, and incident response platforms address escalating audit frequency from the Central Bank. Tier-one financial institutions are consolidating vendor relationships around integrated security platforms rather than point solutions under operational resilience mandates.
- AI:Machine learning models and predictive analytics automate decision workflows. Kuwait Petroleum Corporation's upstream operations are deploying industrial AI for predictive maintenance across extraction and refining facilities.
- IoT:Sensor networks and connected device fleets enable real-time operational monitoring.
- Big Data:Distributed storage and analytics platforms process high-velocity information streams.
Cybersecurity commands the established base. AI is expanding most quickly through oil sector modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kuwait's ICT trade balance tilts toward service imports, with hardware sourcing concentrated through East Asian manufacturing corridors and software licensing flowing from US and European vendors. Domestic data center construction is narrowing this gap as sovereign cloud mandates localize infrastructure spending.
Capital Governorate
Kuwait City anchors public sector digital procurement, with ministry headquarters driving sovereign cloud infrastructure demand. The national e-government framework mandates centralized IT spending through the Central Agency for Information Technology. The Dasman and Sharq districts concentrate banking sector cybersecurity investments under Central Bank compliance timelines.
Hawalli Governorate
Retail and healthcare digitization concentrates demand in Salmiya and Hawalli commercial corridors. The Ministry of Health's hospital information system deployments require HIPAA-aligned data governance architectures. The Salem Al-Mubarak Street corridor hosts mid-market trading firms adopting subscription-based ERP platforms.
Ahmadi Governorate
Kuwait Petroleum Corporation subsidiaries deploy industrial IoT and predictive analytics across upstream operations. The Mina Al-Ahmadi refinery complex requires high-throughput fiber connectivity and edge computing nodes for real-time process monitoring. The Al-Ahmadi industrial zone leads procurement unbundling trends, separating hardware purchasing from implementation contracts.
Al Farwaniyah Governorate
Logistics and aviation technology investments cluster around Kuwait International Airport's cargo and passenger processing systems. The airport's smart infrastructure programs demand converged IoT and AI stacks for baggage handling and security screening. The Jleeb Al-Shuyoukh commercial district supports SME cloud adoption through managed service provider aggregation.
Jahra Governorate
Agricultural modernization and remote government service delivery drive connectivity investments in Kuwait's northwestern corridor. The Ministry of Interior's border security infrastructure requires ruggedized networking equipment and satellite backup links. The Jahra city administrative center anchors provincial e-government service rollout under national digital transformation directives.
Kuwait ICT Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base stratifies across three tiers: global technology conglomerates with end-to-end portfolios, regional telecom operators with captive infrastructure, and niche cybersecurity specialists. Competitive positioning depends on certification velocity through the Communications and Information Technology Regulatory Authority and alignment with Central Bank data localization mandates. M&A activity concentrates on managed security service capabilities, while strategic partnerships target sovereign cloud facility construction.
Among global platform providers, Huawei Technologies Co. Ltd. and Cisco Systems Inc. anchor infrastructure and enterprise networking procurement cycles respectively. Regional operators Zain and Ooredoo occupy positions bridging telecom infrastructure with enterprise service delivery. These entities exemplify the bifurcation between equipment-centric and service-centric competitive models shaping Kuwait's vendor selection criteria.
| Leading Market Players |
|---|
| International Business Machines Corp. |
| Huawei Technologies Co. Ltd. |
| Zain |
| Gulfsat |
| Arabian Information Technology Solutions Company |
| Ooredoo |
| Cisco Systems Inc. |
| International Turnkey Systems |
| stc Kuwait |
| Others |
Value Chain & Pricing Dynamics
East Asian manufacturing corridors anchor hardware cost structures, with Shenzhen and Taipei capacity dynamics transmitting directly into Kuwaiti enterprise procurement budgets. Central Bank localization mandates force premium pricing for sovereign cloud infrastructure, compressing margin elasticity across foreign vendor bids.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS-tiered pricing across managed infrastructure contracts. Price differentiation separates certified sovereign cloud deployments from uncertified offshore alternatives, with volume scale and after-sales service bundling as secondary tiering factors. Pricing pressure stems from standardized server commoditization eroding hardware margins. SME trading firms exhibit highest price sensitivity, while tier-one banks absorb premium tiers for compliance-verified security stacks.
Supply Chain Analysis
US export-control restrictions on advanced networking semiconductors limit component flows into Kuwaiti data center builds. Geographic supply concentration centers on China, Taiwan, and South Korea for server motherboards, fiber-optic transceivers, and enterprise storage arrays. Raw material dependencies include rare-earth magnets, high-purity silicon wafers, and copper cabling. Single-source vulnerability around specialized ASICs creates procurement risk. Distribution runs through Dubai-based regional logistics hubs with last-mile fulfillment via Kuwait City channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's ICT landscape rewards service-attach strategies as managed security and compliance monitoring expand faster than underlying hardware procurement. Recurring revenue layers around 24-hour incident response and continuous audit support capture margin pools that capital expenditure models cannot replicate.
For Market Incumbents: Entrench platform consolidation advantages by deepening certification velocity through the Communications and Information Technology Regulatory Authority. Acquire managed detection and response capabilities to counter emerging pure-play cybersecurity specialists. Expand sovereign cloud facility capacity in the Capital Governorate to preempt foreign entrant localization investments. For New Entrants and Emerging Players: Pursue SME cloud adoption whitespace in Al Farwaniyah's trading and logistics corridors where subscription pricing reduces upfront barriers. Target family-owned firms with vertical-specific ERP templates bypassing legacy system complexity. Lead with channel partner aggregation models rather than direct enterprise sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors managed security service providers with Central Bank compliance frameworks already embedded. Long-term viability hinges on recurring revenue density rather than project-based system integration. Watch for sovereign cloud facility completion as inflection signal for competitive pricing pressure release.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Security Service Acquisition | Consolidates vendor relationships under Central Bank operational resilience mandates. |
| Sovereign Cloud Facility Buildout | Satisfies data localization requirements for foreign providers entering Kuwait. |
| Hyperconverged Infrastructure Platform Launch | Collapses three-tier architectures across Kuwait Petroleum Corporation subsidiaries. |
| SD-WAN Orchestration Partnership | Unifies transport fabrics for retail chains aggregating MPLS and 5G links. |
| Industrial IoT Edge Computing Deployment | Enables predictive analytics across Mina Al-Ahmadi refinery operations. |
Study Parameters
A spread of perspectives from CTOs at tier-one banks, IT procurement officers at Kuwait Petroleum Corporation subsidiaries, platform engineers at telecom operators, and integration specialists at system integrators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, and Central Bank circulars. Bottom-up segment sizing and top-down macro anchoring were triangulated to constrain variance.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical sector, integration complexity, and regional adoption pattern. CAGRs were derived from fitted growth curves against historical procurement data. Forecast inputs incorporated 5G spectrum allocation timelines and sovereign cloud facility construction schedules.
Macroeconomic conditions sit as an overlay; deviation in oil revenue flows and currency peg stability would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement intensity and vendor certification velocity. Material shifts in Central Bank data residency requirements or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Transit Station Display Board Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
Defense IT Spending Market
Digital Solutions
Super Apps Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Global Cloud OSS BSS Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Price Optimization and Management Software Market