
 South America Data Center Server Market | 2026-2036
South America Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
South America Data Center Server Market Insights
Aftermarket service revenue is narrowing as original equipment manufacturers tighten maintenance contracts and cloud providers internalize server lifecycle management. Dell Inc. leverages its direct enterprise channel to sustain replacement-cycle visibility across Brazilian financial institutions. Huawei anchors hyperscale deployments through localized assembly partnerships that navigate import duty structures. Hewlett Packard Enterprise competes on liquid-cooled server architectures designed for tropical operating conditions.
A data center server is a high-availability computing system engineered with redundant power supplies, ECC memory, and enterprise-grade processors operating at 24/7 duty cycles, purpose-built to host virtualized workloads and distributed storage for commercial and institutional networks. Rack servers dominate volume shipments across South American colocation facilities due to density requirements in space-constrained São Paulo and Bogotá facilities. Edge Computing represents the fastest-expanding technology segment as telecommunications carriers deploy micro data centers for 5G latency reduction, while Blade Servers retain concentrated demand from financial services clusters requiring fault-tolerant transaction processing.
ANATEL certification requirements in Brazil and SUBTEL infrastructure standards in Chile dictate electromagnetic compatibility and energy efficiency thresholds for imported server equipment, effectively filtering non-compliant vendors from public-sector tenders. Argentina's national data localization directives and Peru's cybersecurity framework for critical infrastructure further segment procurement compliance obligations. Stakeholders must monitor how Mercosur digital economy harmonization negotiations reshape cross-border server deployment rules and duty classifications.
Market Dynamics
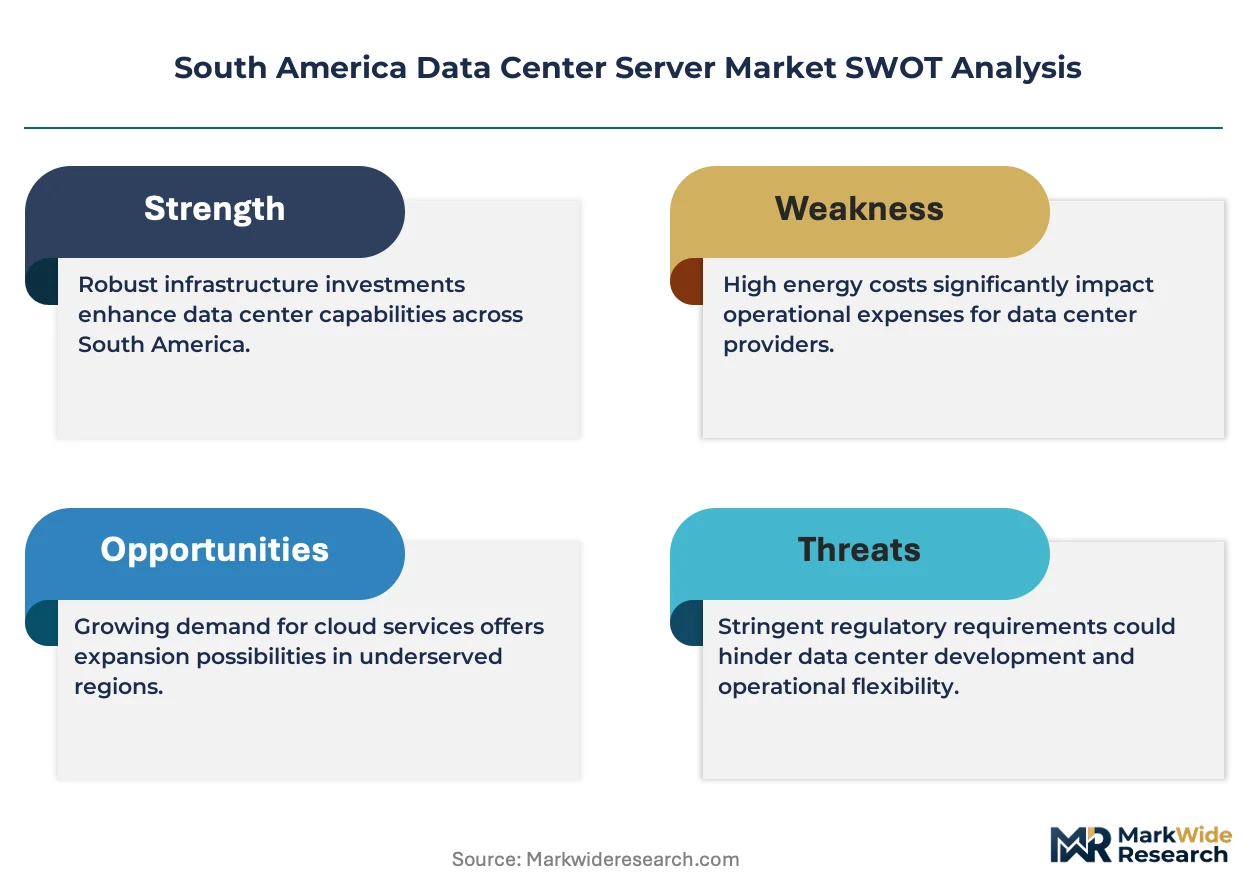
Data center server procurement across South America is reconfiguring around Brazil's LGPD data sovereignty mandates and Chile's renewable energy thresholds for facility certification. These dual regulatory currents are compressing supplier qualification timelines while elevating liquid-cooled architectures for tropical deployment.
Growth Catalysts
- AI Workload Expansion:Hyperscale cloud providers in São Paulo and Santiago are expanding GPU-intensive server clusters for generative AI inference, driving rack-density requirements above 30kW per cabinet.
- Edge Computing Mandates:Brazil's ANATEL spectrum allocations for 5G mid-band are compelling telecommunications carriers to deploy micro data centers in secondary cities, creating distributed server demand outside metropolitan fiber corridors.
- Renewable Energy Standards:Chile's SUBTEL efficiency thresholds and carbon-neutral facility certifications are accelerating procurement of energy-optimized server configurations with power usage effectiveness targets below 1.3.
Market Restraints
- Import Duty Structures:Brazil's industrialized goods tax and Mercosur common external tariff impose 14-18% landed cost premiums on fully assembled servers, disadvantaging vendors without localized assembly partnerships.
- Currency Volatility:Argentine peso depreciation and Chilean peso fluctuation against the US dollar are compressing procurement budgets and extending replacement cycles for enterprise buyers.
- Power Infrastructure Gaps:Grid instability in northeastern Brazil and capacity constraints in Bogotá's electrical distribution network are limiting data center expansion in otherwise attractive secondary markets.
Strategic Opportunities
- Free-Trade Zone Facilities:Santiago's Zona Franca installations offer duty-exempt server imports and renewable energy access, creating arbitrage opportunities for serving Argentine and Bolivian demand.
- Submarine Cable Landings:New fiber systems connecting Fortaleza to Europe and Africa are positioning Brazil's northeast as an emerging latency-competitive alternative to São Paulo for content delivery infrastructure.
- Financial Services Modernization:Brazilian open banking regulations and instant payment system expansion are forcing legacy transaction processing clusters toward blade server refresh cycles with fault-tolerant architectures.
Industry Challenges
- Certification Timeline Compression:ANATEL electromagnetic compatibility testing and SUBTEL energy efficiency validation now require 16-24 weeks, delaying revenue recognition for new product introductions.
- Thermal Engineering Talent Scarcity:Liquid-cooled server deployment in tropical conditions demands specialized HVAC integration skills that remain concentrated among São Paulo-based systems integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Data Center Server Market |
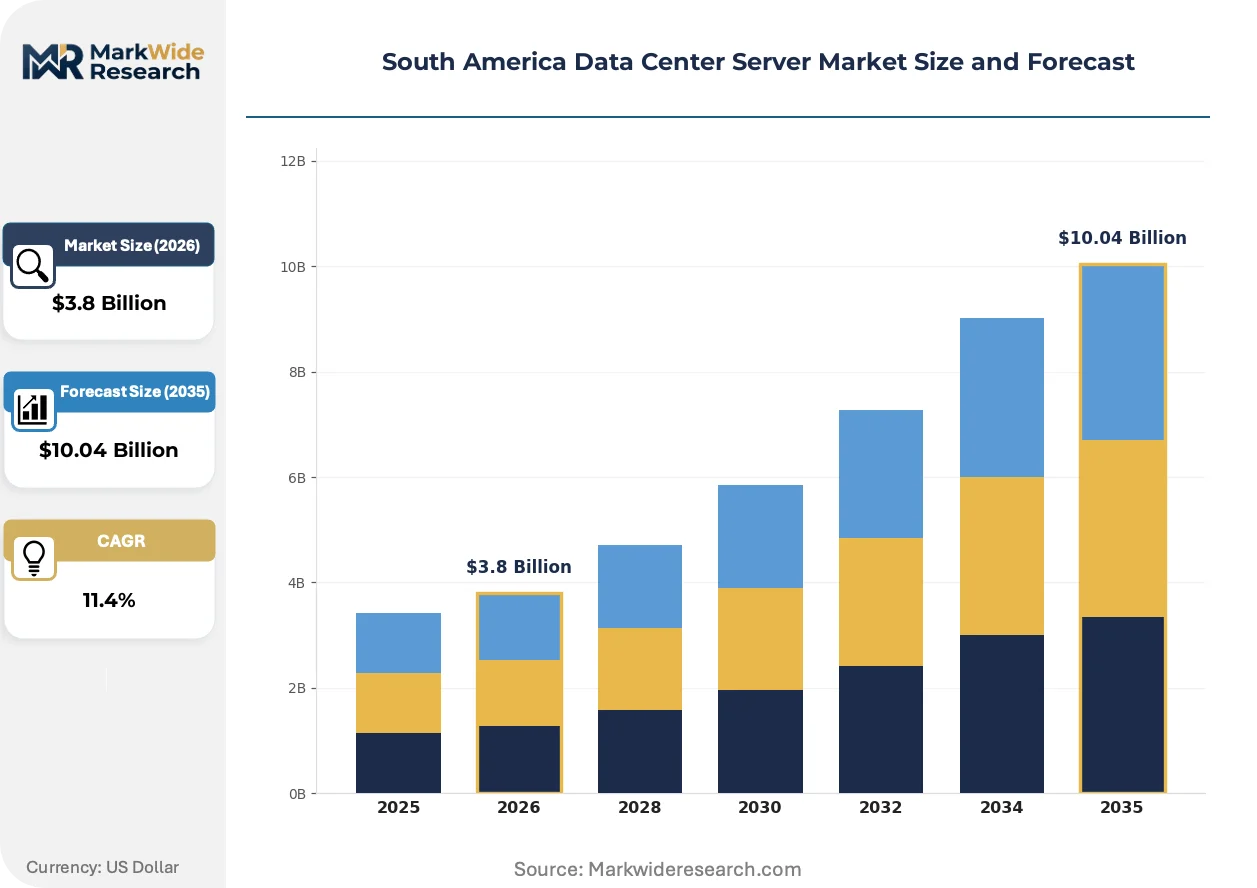
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Micro Servers End User: Cloud Providers, Telecommunications, Financial Services, Government Deployment: On-Premise, Colocation, Managed Services, Hybrid Solutions Technology: Virtualization, Hyperconverged Infrastructure, Edge Computing, AI Integration |
| Companies Covered | Cisco Systems Inc., Fujitsu, Dell Inc., Huawei, Supermicro, Hewlett Packard Enterprise, IBM Corporation, Intel Corporation, Lenovo Group Limited, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Data Center Server Market Trends and Innovations
Server architecture evolution across South American facilities is converging on density-optimized designs that reconcile tropical thermal constraints with sovereignty-driven data localization. Regulatory certification complexity and procurement model fragmentation are simultaneously reshaping vendor-go-to-market approaches.
Direct liquid cooling is collapsing the thermal design power ceiling that previously constrained AI server deployment in ambient temperatures exceeding 30°C. Brazilian financial institutions and Chilean mining conglomerates are adopting cold-plate and immersion systems at triple-digit annual growth rates. This thermal architecture shift is collapsing the geographic monopoly of temperate-climate data center locations, enabling high-performance computing clusters in previously excluded subtropical zones.
Brazil's LGPD enforcement mechanisms and data localization directives are mandating in-country processing for personal data categories, compelling multinational cloud providers to expand domestic server footprint regardless of cost differentials. Chile's SUBTEL infrastructure standards are extending electromagnetic compatibility requirements to edge computing nodes below 10kW capacity. These regulatory frameworks are fragmenting procurement specifications across national boundaries, forcing vendors to maintain parallel certification portfolios for Mercosur markets.
Enterprise buyers are consolidating server lifecycle management under captive facilities teams, displacing traditional OEM maintenance contracts with self-service parts logistics and third-party technical support. Argentine banks and Peruvian telecommunications operators are piloting this insourced model most aggressively. São Paulo's concentration of systems integrators and spare parts distributors is accelerating this behavioral shift in Brazil's southeast corridor.
South America Data Center Server Market Segmentation
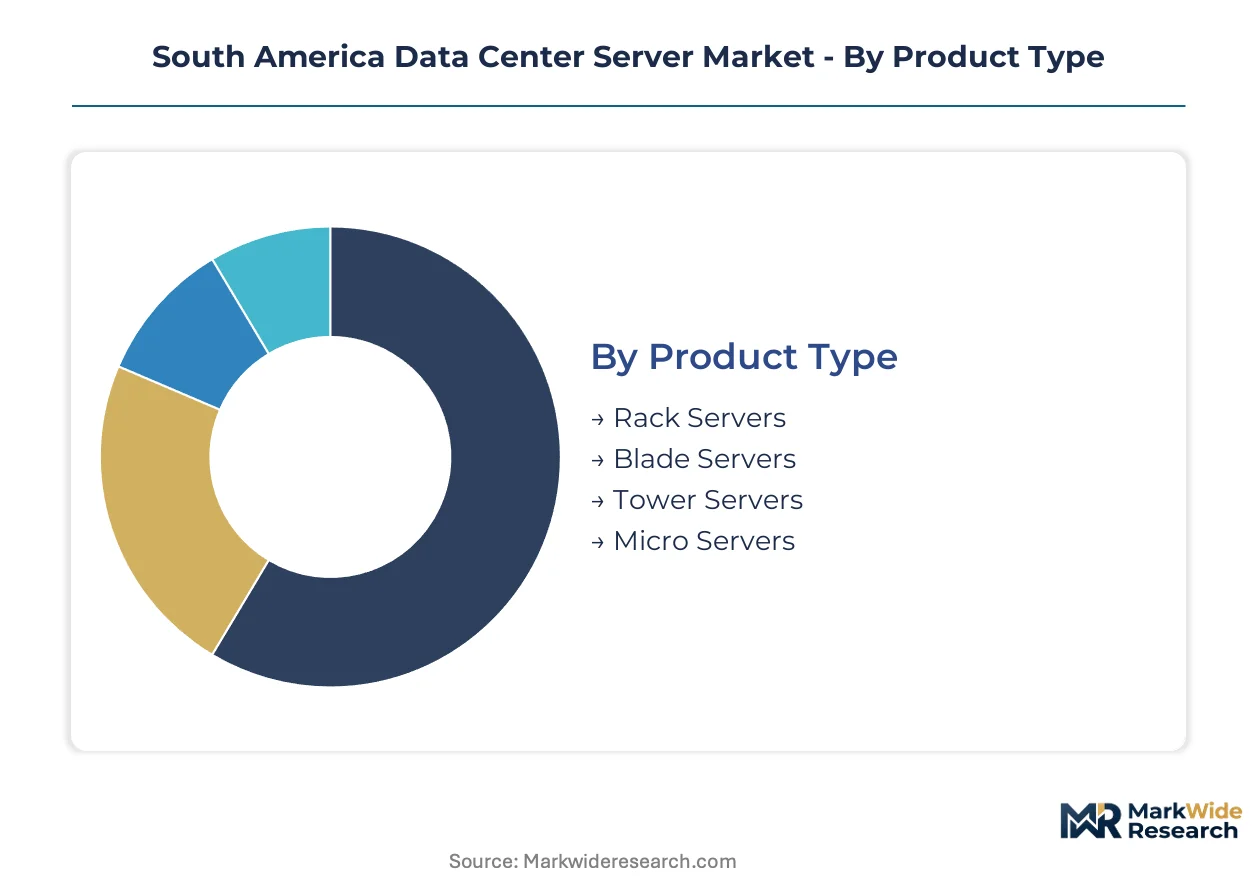
Server procurement across South America fragments across thermal constraints, sovereignty mandates, and workload specialization. Segmentation reveals where vendor margins concentrate versus where volume expansion accelerates.
Product Type:
Rack servers turn over fastest at hyperscale facilities, while blade architectures persist through extended refresh cycles in fault-tolerant environments.
- Rack Servers:High-density 1U-4U chassis dominate São Paulo and Bogotá colocation facilities where space premiums exceed hardware costs. Cloud providers in Brazil's metropolitan fiber corridor specify 30kW+ cabinets that demand rack-optimized airflow engineering.
- Blade Servers:Modular enclosures with shared power and cooling infrastructure serve Brazilian financial institutions requiring sub-5ms failover for instant payment processing. These architectures justify premium positioning through fault-tolerant redundancy that tower configurations cannot match.
- Tower Servers:Standalone vertical chassis persist in Argentine provincial government offices and Peruvian educational institutions with limited rack infrastructure.
- Micro Servers:Compact single-socket nodes address Chilean telecommunications edge deployments below 10kW SUBTEL certification thresholds.
Rack servers dominate installed base. Micro servers are where expansion concentrates.
End User:
Cloud providers drive volume procurement while financial services sustain margin premiums through specialized reliability requirements.
- Cloud Providers:Hyperscale operators in São Paulo and Santiago procure GPU-intensive clusters for generative AI inference, specifying liquid-cooled architectures that collapse thermal constraints in tropical ambient conditions.
- Telecommunications:Brazilian carriers deploying ANATEL-mandated 5G infrastructure source micro data centers for secondary cities outside metropolitan fiber corridors, creating distributed server demand.
- Financial Services:Blade server refresh cycles accelerate among Argentine banks and Brazilian payment processors modernizing legacy transaction infrastructure.
- Government:LGPD compliance drives Brazilian public-sector procurement toward domestic assembly partnerships that navigate import duty structures.
Cloud providers dominate installed base. Telecommunications is where expansion concentrates.
Deployment:
Capital intensity separates self-operated facilities from outsourced arrangements, with hybrid architectures capturing organizations navigating sovereignty transitions.
- On-Premise:Chilean mining conglomerates and Argentine banks retain captive data centers for latency-sensitive workloads, insourcing lifecycle management to displace OEM maintenance contracts.
- Colocation:São Paulo's space-constrained facilities and Santiago's Zona Franca installations concentrate rack server density for cloud providers and content delivery networks.
- Managed Services:Third-party operation appeals to Peruvian telecommunications operators and Colombian enterprises lacking specialized HVAC integration talent.
- Hybrid Solutions:Brazilian enterprises split workloads between domestic LGPD-compliant infrastructure and international cloud, creating dual procurement specifications.
Colocation dominates installed base. Hybrid solutions are climbing the fastest.
Technology:
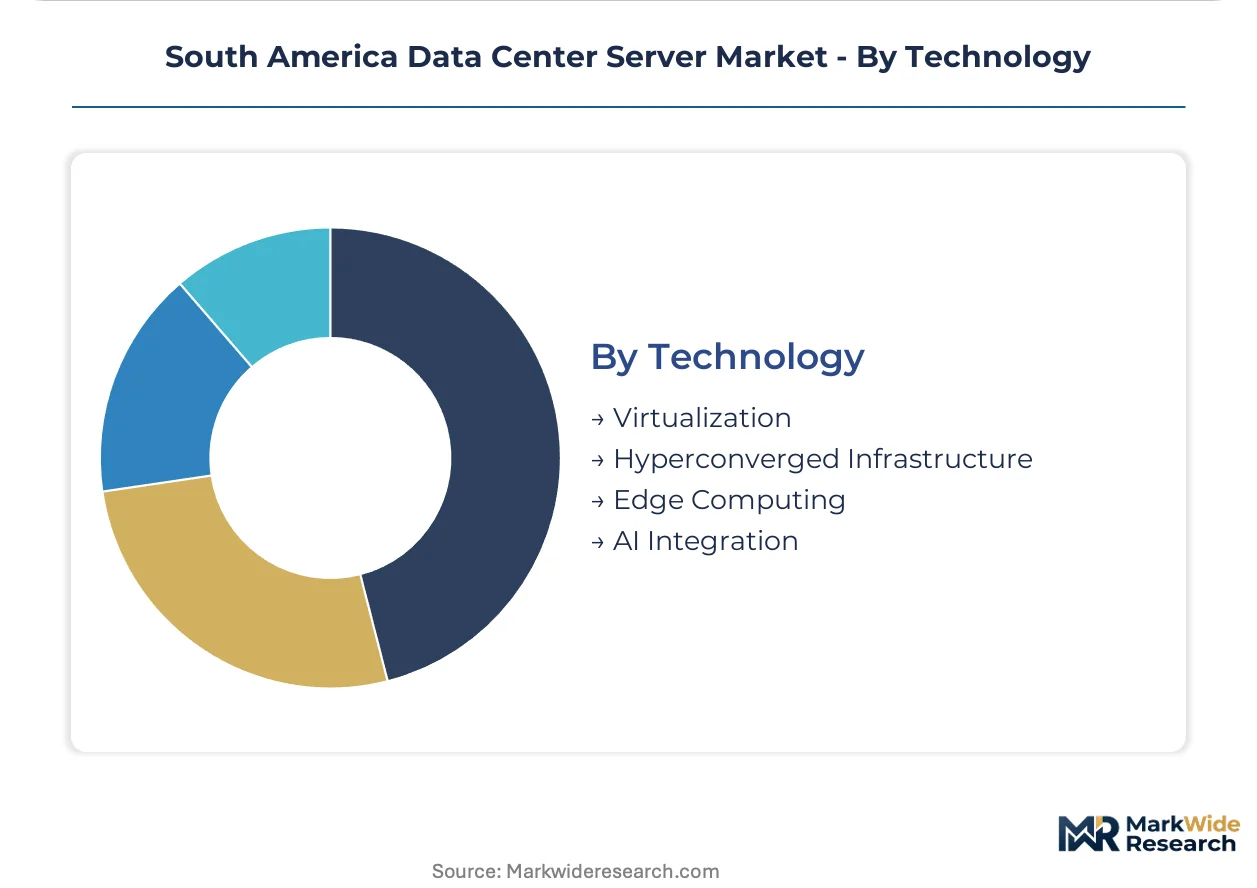
Virtualization commoditized server utilization while AI integration and edge computing create new hardware specialization requirements.
- Virtualization:Software-defined resource allocation remains baseline capability across all South American enterprise deployments, no longer a differentiating procurement criterion.
- Hyperconverged Infrastructure:Integrated compute-storage-networking stacks gain traction among Chilean mid-market enterprises seeking simplified procurement without specialized integration expertise.
- Edge Computing:Micro data center deployment accelerates fastest as Brazilian ANATEL 5G spectrum allocations compel distributed infrastructure in secondary cities.
- AI Integration:GPU-intensive server configurations with direct liquid cooling expand among São Paulo hyperscale operators and Santiago financial services clusters.
Virtualization dominates installed base. Edge computing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentine buyers exhibit extreme price sensitivity due to peso volatility, while Chilean mining conglomerates and Brazilian financial institutions absorb premium pricing for fault-tolerant architectures without procurement delays.
Brazil
Hyperscale cloud operators in São Paulo's metropolitan fiber corridor drive GPU-intensive server clusters for generative AI inference. ANATEL electromagnetic compatibility certification mandates 16-24 week validation timelines for imported equipment. Domestic assembly partnerships in Campinas and Sorocaba navigate industrialized goods tax structures that impose 14-18% landed cost premiums on fully assembled units.
Chile
Santiago's Zona Franca free-trade zone facilities concentrate rack server density for content delivery networks and regional cloud nodes. SUBTEL infrastructure standards extend energy efficiency thresholds to edge computing nodes below 10kW capacity. Renewable energy mandates in the Atacama Desert corridor position carbon-neutral data centers for serving Argentine and Bolivian cross-border demand.
Argentina
National data localization directives compel multinational cloud providers to expand domestic server footprint regardless of cost differentials. The central bank's foreign exchange restrictions compress enterprise procurement budgets and extend hardware replacement cycles. Buenos Aires province government offices and provincial banks in Córdoba retain tower server configurations due to limited rack infrastructure investment capacity.
Colombia
Bogotá's space-constrained colocation facilities prioritize high-density 1U-4U rack chassis where real estate premiums exceed hardware acquisition costs. The national cybersecurity framework for critical infrastructure segments procurement compliance obligations for telecommunications and financial sectors. Medellín's emerging fiber corridor attracts secondary data center investment from content delivery networks seeking Andean latency arbitrage.
Peru
Lima's telecommunications operators pilot insourced server lifecycle management models that displace traditional OEM maintenance contracts. The national cybersecurity framework mandates localized processing for government and banking workloads. Arequipa's secondary market grid stability limitations constrain data center expansion despite attractive Andean cooling conditions for tropical thermal management.
South America Data Center Server Market Competitive Landscape
Capability concentration sits with liquid-cooled architecture specialists; scale advantage sits with hyperscale assembly partnerships. The vendor base stratifies across three tiers: direct enterprise channel operators with replacement-cycle visibility, localized assembly partnerships navigating import duty structures, and hyperscale cloud integrators internalizing procurement decisions. Strategic moves center on thermal engineering talent acquisition in São Paulo and duty-exempt free-trade zone facility establishment in Santiago.
Within the direct enterprise tier, Dell Inc. and Hewlett Packard Enterprise occupy positions shaped by Brazilian financial institution relationships and tropical-condition server architectures respectively. Huawei anchors the localized assembly archetype through partnerships that navigate Mercosur tariff configurations. Among hyperscale cloud integrators, Cisco Systems Inc. exemplifies the vendor category facing compressed aftermarket service revenue as cloud providers internalize server lifecycle management.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Fujitsu |
| Dell Inc. |
| Huawei |
| Supermicro |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Intel Corporation |
| Lenovo Group Limited |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in liquid-cooled server engineering across São Paulo's systems integrator cluster drives premium pricing for tropical-deployment architectures while compressing margins for commodity rack configurations. This utilization asymmetry rewards vendors with captive thermal engineering talent and penalizes those dependent on third-party HVAC integration.
Pricing Analysis
Aftermarket service revenue streams, including extended maintenance contracts and spare parts logistics, sustain lifetime value for original equipment manufacturers. Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy refurbished tiers reflects certification grade and thermal engineering complexity. Cost compression in standard rack servers is intensifying because cloud providers internalize lifecycle management and displace OEM service contracts. Argentine provincial government offices exhibit extreme price sensitivity due to peso volatility, while Chilean mining conglomerates absorb premium positioning for fault-tolerant blade architectures without procurement delays.
Supply Chain Analysis
Tariff exposure between Brazil and Mercosur trading partners dominates supply chain risk planning for server vendors. Manufacturing concentration draws from China for GPU accelerators, Taiwan for advanced semiconductors, and domestic Campinas assembly for duty-optimized final configuration. Single-source vulnerability in specialized cooling components sourced from German engineering houses creates bottleneck exposure for liquid-cooled deployments. Distribution runs through São Paulo-based systems integrators with spare parts logistics capabilities, supplemented by Santiago Zona Franca free-trade zone facilities for cross-border Andean coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal engineering talent scarcity in tropical deployment conditions creates asymmetric returns for vendors with captive integration capabilities versus those outsourcing HVAC complexity. This capability gap concentrates margin capture among São Paulo-based specialists while fragmenting procurement outcomes elsewhere.
For Market Incumbents: Insulate replacement-cycle visibility through direct enterprise channel control in Brazilian financial institutions, where blade server refresh mandates accelerate. Deepen captive liquid-cooled architecture development to offset margin erosion from cloud provider internalization of lifecycle management. Prioritize SUBTEL certification maintenance in Chile to sustain positioning against emerging local assembly partnerships. For New Entrants and Emerging Players: Establish a beachhead in Argentine provincial government tower server replacement cycles, where foreign exchange restrictions disadvantage incumbent import-dependent vendors. Target micro server deployments for Brazilian telecommunications edge infrastructure below ANATEL certification thresholds, leveraging simplified electromagnetic compliance pathways. Pursue assembly partnership structures in Mercosur duty-advantaged zones to neutralize landed cost premiums. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among systems integrators with captive thermal engineering talent and spare parts logistics infrastructure. Long-term viability over the next decade favors vertically integrated vendors controlling both server assembly and tropical-deployment integration capabilities. Monitor SUBTEL and ANATEL certification timeline compression as an inflection indicator for vendor working capital stress and market exit vulnerability.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Assembly Partnership | Campinas facilities navigate Brazil's industrialized goods tax to neutralize 14-18% landed cost premiums on fully assembled units. |
| Liquid-Cooled Architecture Development | Direct cooling systems collapse thermal constraints in ambient temperatures exceeding 30°C across São Paulo hyperscale deployments. |
| Free-Trade Zone Facility Establishment | Santiago's Zona Franca installations offer duty-exempt imports and renewable energy access for Andean cross-border service. |
| Thermal Engineering Talent Acquisition | HVAC integration skills concentrated among São Paulo specialists enable premium positioning for tropical AI cluster deployment. |
| Certification Portfolio Parallel Maintenance | ANATEL and SUBTEL compliance fragmentation across Mercosur boundaries requires dual validation timelines for market access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, with data center facility managers, OEM channel directors, systems integrator technical leads, and telecommunications procurement officers providing operational perspective. Secondary validation drew from ANATEL certification databases, SUBTEL infrastructure standards filings, Mercosur customs trade records, and hyperscaler capital expenditure disclosures. Bottom-up shipment estimates by product configuration triangulated against top-down facility capacity buildout tracking across the analysis window.
Calibration against historical replacement cycle patterns and regulatory implementation timelines anchored the projection framework. Segmentation dimensions modeled include product type, end-user vertical, deployment architecture, and technology integration level, with thermal design power thresholds and sovereignty compliance status as industry-specific forecast inputs. CAGRs were derived from installed base evolution and workload growth assumptions throughout the forecast period.
Sensitivities concentrate around currency volatility in Argentina, certification timeline compression in Brazil, and grid stability constraints in secondary Andean markets. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and thermal engineering talent supply elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
Japan Data Center Construction Market
Data Center Infrastructure
Data Center in Japan Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
Brazil Data Center Rack Market