
 Remote Control Duplicators Market | 2026-2036
Remote Control Duplicators Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Control Duplicators Market Analytics
Shenzhen is tilting the competitive balance through concentrated PCB assembly and RF module production for duplicator OEMs. Chamberlain Group leverages its garage door ecosystem to sustain captive demand for compatible duplicator protocols. HBC-radiomatic GmbH anchors premium industrial remote duplication through German-engineered safety certifications. Nice S.p.A. competes across Mediterranean markets with integrated automation-to-duplicator product lines.
Remote control duplicators are electronic devices that clone transmission signatures from original remotes, typically operating at 315 MHz, 433 MHz, or 868 MHz frequencies using rolling code or fixed code capture methods, primarily serving aftermarket replacement and multi-device consolidation needs. Key fob duplicators lead product type revenue due to automotive aftermarket density, while radio frequency remotes extend the fastest growth trajectory as smart home interoperability demands proliferate. RFID technology segments capture premium margins through encrypted credential cloning, whereas infrared retains mature, price-pressured positioning in legacy consumer electronics.
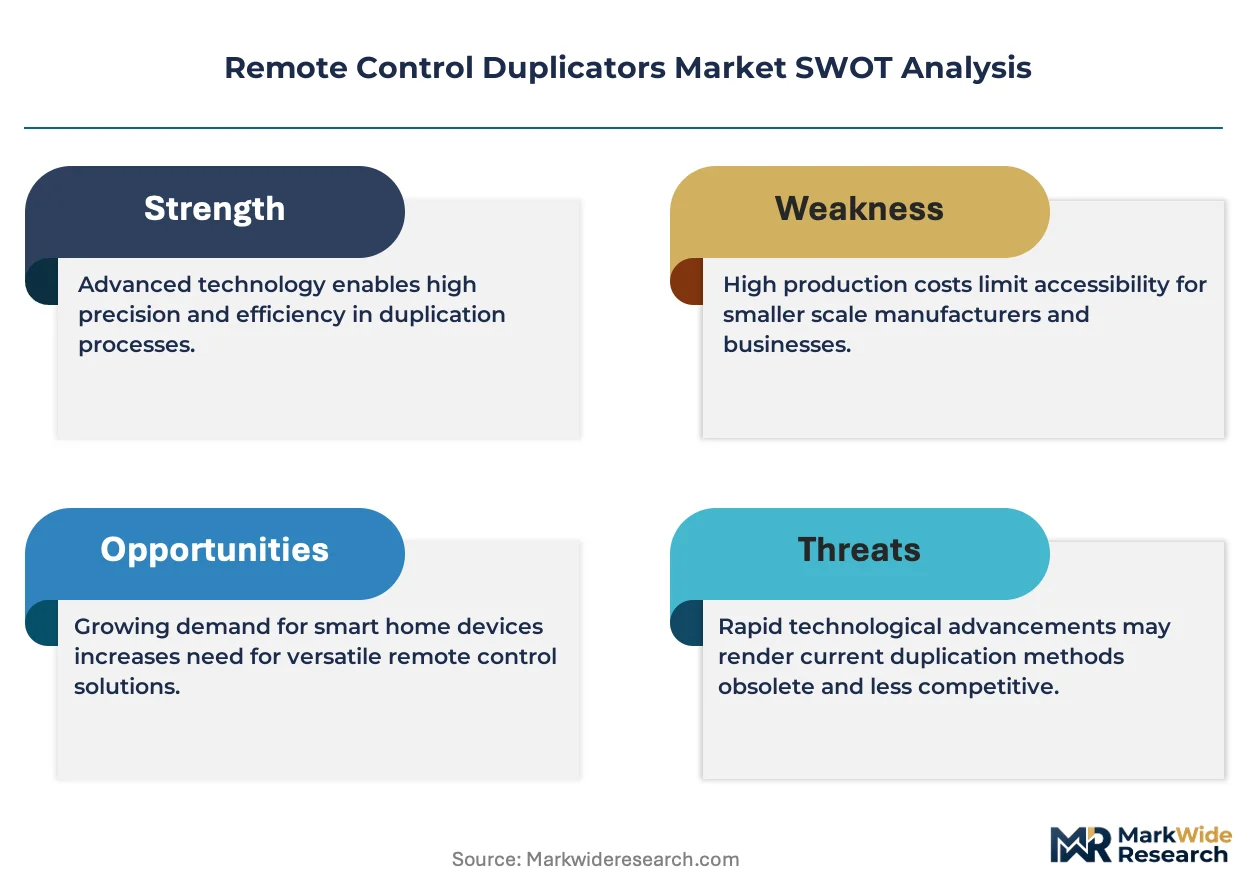
FCC Part 15 governs unlicensed RF emissions in the United States, compelling duplicator manufacturers to certify devices for specific frequency bands and power thresholds. CE marking under the EU Radio Equipment Directive mandates interoperability and spectrum efficiency testing for European market access. China's MIIT issues type approval certificates for radio transmission equipment, creating compliance layers for Shenzhen-based exporters. Stakeholders must monitor evolving encryption mandates from automotive OEMs that progressively block unauthorized cloning protocols.
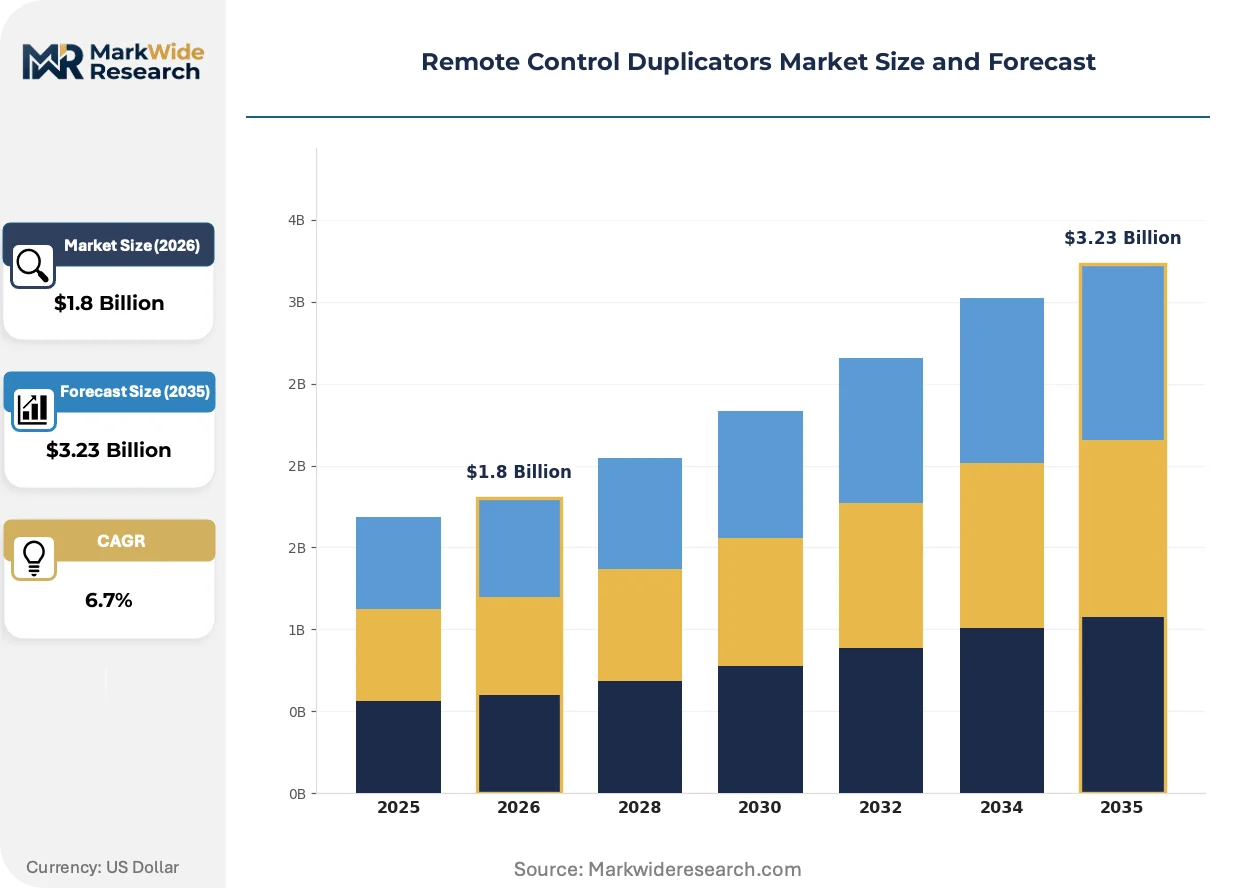
Market Dynamics
Automotive OEMs are progressively deploying encrypted rolling-code protocols that block unauthorized cloning, forcing duplicator manufacturers toward reverse-engineering partnerships and firmware licensing agreements with tier-1 suppliers.
Growth Catalysts
- Keyless Entry Proliferation:Aftermarket automotive service networks in China and Brazil are expanding duplication services to accommodate aging vehicle fleets with degraded original remotes.
- MIIT Type Approval Streamlining:China's Ministry of Industry and Information Technology has accelerated RF equipment certification timelines, reducing exporter lead times for Shenzhen-based manufacturers.
- Smart Home Interoperability:Radio frequency protocols are consolidating around 433 MHz and 868 MHz standards, enabling single duplicators to service multiple garage door and gate automation brands.
Market Restraints
- Semiconductor Supply Concentration:RF transceiver chips and SAW resonators depend heavily on TSMC and Samsung foundry allocation, creating input cost volatility for mid-tier duplicator assemblers.
- FCC Part 15 Certification Burden:Unintentional radiator testing for each frequency variant adds fixed compliance costs that disproportionately constrain small-batch manufacturers.
- Automotive Encryption Arms Race:AES-128 and proprietary hopping-code algorithms in premium vehicle segments are rendering passive signal-capture duplicators technically obsolete for newer models.
Strategic Opportunities
- India Aftermarket Penetration:The country's automotive parc exceeds 50 million passenger vehicles with minimal dealer-network key replacement coverage, creating whitespace for mobile duplication services.
- Industrial Safety Certification:SIL-rated and PL-d certified radio remote duplication for construction and material handling equipment commands premium positioning in German and Nordic markets.
- Bluetooth Low Energy Convergence:Hybrid duplicators combining RF capture with BLE credential provisioning are opening smartphone-integrated key management for multi-family residential properties.
Industry Challenges
- Firmware Reverse-Engineering Talent Scarcity:Rolling-code decryption and protocol analysis require embedded security expertise concentrated in Tel Aviv, Tallinn, and Shenzhen, limiting replication of technical teams.
- Multi-Jurisdiction Certification Timelines:Simultaneous FCC, CE marking, and MIIT approvals for a tri-band duplicator extend time-to-revenue by 8-14 months, straining working capital for product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Control Duplicators Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Remotes, Key Fob Duplicators, Infrared Remotes, Radio Frequency Remotes End User: Automotive, Electronics Retailers, Smart Home Users, Security Companies Technology: RFID, Infrared, Bluetooth, Wi-Fi Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Third-Party Retailers |
| Companies Covered | Universal Remote Control, HBC-radiomatic GmbH, Chamberlain Group, Tele Radio, Hetronic International, LiftMaster, Nice S.p.A., Scanreco, CAME S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Control Duplicators Market Evolving Landscape
Duplicator hardware is bifurcating between low-cost fixed-code devices for legacy installations and sophisticated protocol-analyzing units that negotiate with encrypted transceivers through manufacturer-authorized channels.
Software-defined radio architecture is hybridizing duplicator functionality. SDR platforms enable field-upgradable frequency coverage and protocol libraries through firmware over-the-air updates. Automotive locksmiths and facility maintenance contractors are adopting these flexible units to reduce inventory carrying costs across multiple vehicle makes and access control brands. The technology is hybridizing what were previously discrete product categories into unified service tools.
EU Radio Equipment Directive enforcement is tightening electromagnetic compatibility and spectrum efficiency verification. Notified bodies in Germany and the Netherlands are rejecting submissions with inadequate documentation of spurious emission mitigation. Garage door and gate automation OEMs serving European markets are responding by pre-certifying compatible duplicator protocols through formal partnership programs, creating a two-tier access structure.
Buyer preference is consolidating around certified-compatibility guarantees rather than lowest-unit-cost procurement. Facility managers and automotive service chains are demanding duplicator brands with documented protocol licensing from original equipment manufacturers. This specification tightening is most visible in German-speaking markets and Nordic countries, where liability exposure for unauthorized access incidents drives vendor qualification rigor.
Remote Control Duplicators Market Segmentation
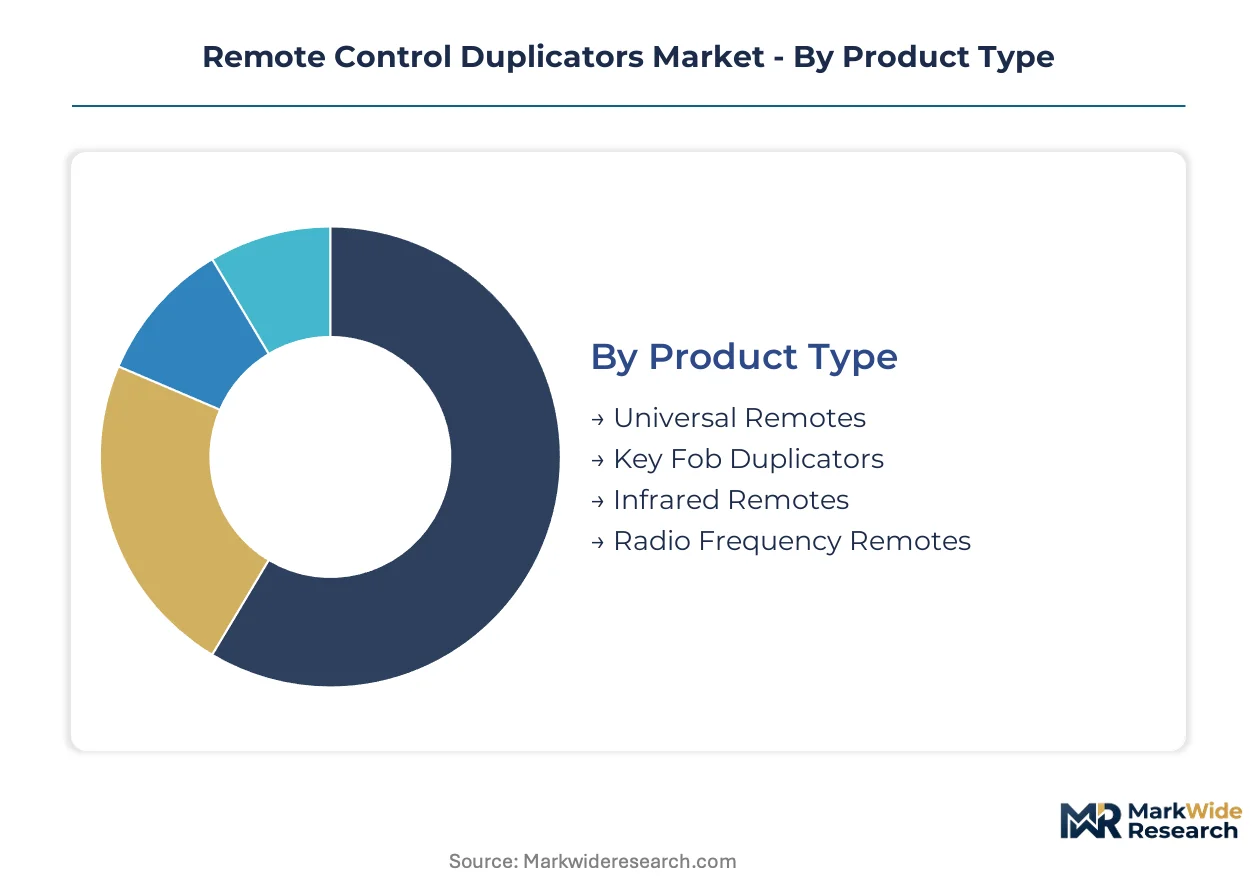
Remote control duplicators fragment across four distinct category axes, each reflecting different procurement rhythms and technical specifications. Product type segmentation reveals the sharpest contrast between high-velocity consumer replacements and long-cycle industrial certifications.
Product Type:
Inventory turns vary dramatically: universal remotes and infrared units move fastest through electronics retail, while key fob duplicators tied to automotive security protocols carry 18-24 month certification cycles.
- Key Fob Duplicators:These devices capture rolling-code and fixed-code transmissions from vehicle immobilizer systems, typically operating at 315 MHz or 433 MHz frequencies. Demand clusters in aftermarket automotive service networks across China and Brazil, where aging vehicle fleets require replacement credentials for degraded original remotes. FCC Part 15 and MIIT type approval requirements extend product development timelines for new frequency variants.
- Radio Frequency Remotes:Operating across 433 MHz and 868 MHz bands, these units clone garage door and gate automation signals. Smart home interoperability demands in German-speaking markets and Nordic countries are accelerating protocol consolidation, enabling single devices to service multiple automation brands. CE marking under the EU Radio Equipment Directive mandates rigorous electromagnetic compatibility verification.
- Universal Remotes:Multi-device consolidation tools supporting infrared and RF protocols for consumer electronics.
- Infrared Remotes:Legacy cloning devices for television and audio equipment, facing price compression in mature consumer markets.
Key fob duplicators anchor the volume base while radio frequency remotes gain share at the steepest rate.
End User:
Customer procurement patterns diverge sharply: automotive and security companies demand certified-compatibility documentation, while electronics retailers and smart home users prioritize unit cost and immediate availability.
- Automotive:Aftermarket service networks and mobile locksmiths performing on-site key replacement for passenger and commercial vehicles. Demand concentrates where dealer-network coverage is sparse, particularly in India's expanding vehicle parc. OEM encryption protocols are progressively restricting unauthorized cloning, forcing duplicator manufacturers toward firmware licensing agreements.
- Security Companies:Access control integrators and facility managers requiring SIL-rated or PL-d certified duplication for industrial equipment. German and Nordic markets command premium positioning through documented safety certifications and liability protection.
- Electronics Retailers:Consumer-facing channels stocking universal and infrared remotes for immediate replacement needs.
- Smart Home Users:Residential adopters of integrated garage door and gate automation systems.
Automotive anchors the volume base while security companies expand most quickly through safety-certified industrial applications.
Technology:
Technical architecture determines margin structure: RFID and Bluetooth command premium positioning through encryption layers, while infrared and basic RF face commoditization.
- RFID:Encrypted credential cloning for access control cards and keyless entry systems. Demand concentrates in corporate and multi-family residential properties requiring high-security credential management. Premium margins reflect cryptographic complexity and compliance with evolving encryption standards.
- Bluetooth:Low-energy protocols enabling smartphone-integrated key management and hybrid duplicator functionality. Multi-family residential properties in North American and European urban centers are adopting BLE credential provisioning for tenant access systems.
- Infrared:Legacy line-of-sight cloning for consumer electronics, operating in mature, price-pressured segments.
- Wi-Fi:Cloud-connected duplication platforms for remote credential management and firmware updates.
RFID anchors the volume base while Bluetooth climbs the fastest through smart home convergence.
Distribution Channel:
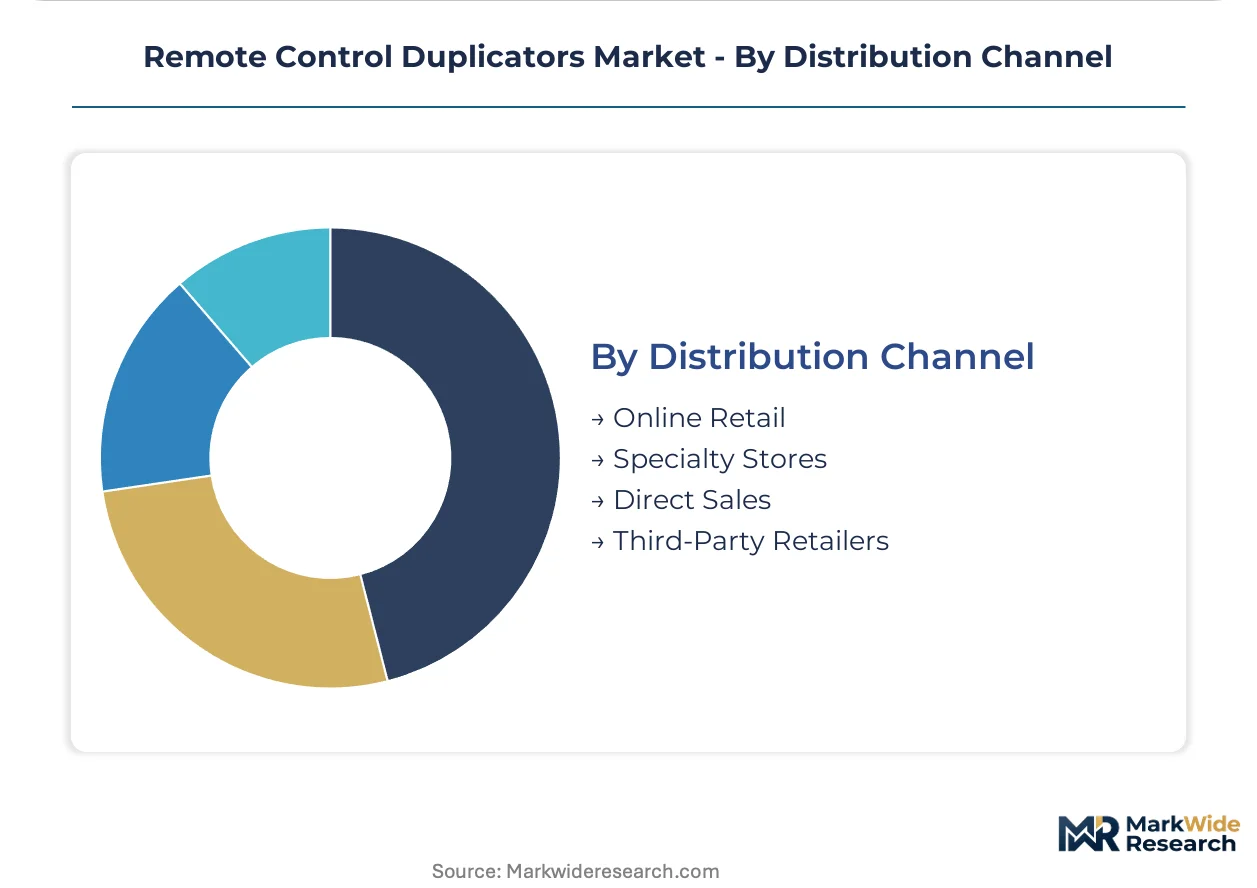
Channel economics reflect certification burden: direct sales and specialty stores absorb complex technical consultation, while online retail and third-party distributors compete on fulfillment speed.
- Specialty Stores:Automotive locksmith suppliers and industrial safety equipment distributors providing protocol consultation and certification documentation. German, Swiss, and Austrian markets demonstrate strongest penetration through qualified vendor programs.
- Direct Sales:Manufacturer-to-integrator relationships for high-volume security and automotive service chains. Shenzhen-based OEMs leverage direct channels to bypass distributor margins for European and North American system integrators.
- Online Retail:E-commerce platforms serving price-sensitive consumer segments with universal and infrared remotes.
- Third-Party Retailers:General electronics and hardware stores stocking entry-level duplication devices.
Specialty stores anchor the volume base while direct sales gains share fastest through integrated supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys duplicators primarily for automotive aftermarket key replacement, while Germany channels demand through industrial safety-certified radio remote systems for construction equipment. Brazil and India concentrate mobile duplication services where dealer-network coverage gaps persist.
China
Automotive parc expansion and aging vehicle fleets drive aftermarket key replacement demand across provincial service networks. MIIT type approval streamlining has compressed RF equipment certification timelines for Shenzhen-based exporters. Shenzhen's electronics manufacturing clusters supply PCB assemblies and RF modules to global duplicator OEMs, consolidating component sourcing.
Germany
Industrial automation and construction equipment operators demand SIL-rated and PL-d certified radio remote duplication. CE marking under the EU Radio Equipment Directive enforces electromagnetic compatibility and spectrum efficiency verification. Bavaria and North Rhine-Westphalia host notified bodies and industrial safety distributors that pre-qualify compatible duplicator protocols.
United States
Garage door ecosystem integration and smart home interoperability requirements shape procurement patterns for residential automation. FCC Part 15 governs unlicensed RF emissions, compelling manufacturers to certify devices for specific frequency bands and power thresholds. Midwest automotive service chains and Texas-based facility management contractors absorb multi-brand duplication tools.
Brazil
Aftermarket automotive service networks exploit minimal dealer-network key replacement coverage across São Paulo and Rio de Janeiro state vehicle parcs. ANVISA and national telecommunications regulator frameworks govern radio transmission equipment importation. Mobile locksmith services proliferate in urban corridors where fixed-location duplication infrastructure remains sparse.
India
Passenger vehicle parc exceeding 50 million units generates whitespace for mobile duplication services outside organized dealer networks. BIS certification requirements and central excise frameworks shape import and domestic manufacturing compliance. Maharashtra and Karnataka automotive clusters concentrate independent service providers performing on-site key replacement.
Remote Control Duplicators Market Competitive Landscape
Capability concentration sits with protocol-analysis specialists; scale advantage sits with Shenzhen-based component integrators. The vendor base stratifies across three tiers: premium industrial safety certifiers, mid-market automotive aftermarket suppliers, and price-driven consumer electronics assemblers. Dominant competitive moves include firmware licensing agreements with tier-1 automotive suppliers and pre-certification partnerships with European notified bodies for streamlined CE marking access.
Among German-engineered safety specialists, HBC-radiomatic GmbH exemplifies premium-tier positioning through documented industrial certifications. Chamberlain Group occupies a captive-demand position leveraging integrated garage door ecosystem protocols. Shenzhen-based production gravitates toward component supply relationships, with Nice S.p.A. representing Mediterranean-market automation-to-duplicator integration.
| Leading Market Players |
|---|
| Universal Remote Control |
| HBC-radiomatic GmbH |
| Chamberlain Group |
| Tele Radio |
| Hetronic International |
| LiftMaster |
| Nice S.p.A. |
| Scanreco |
| CAME S.p.A. |
| Others |
Value Network & Pricing Analysis
Shenzhen's concentrated PCB assembly and RF module production feeds directly into margin capture by tier-1 duplicator OEMs serving German and North American safety-certified markets. Component sourcing density in China's Pearl River Delta enables volume-scale producers to extract cost advantages while specialized protocol-analyzing units command premium positioning through firmware licensing overhead.
Pricing Analysis
Long-term offtake agreements between automotive aftermarket chains and Shenzhen-based manufacturers anchor volume-tier pricing, while spot procurement dominates small-batch industrial safety certifications. Three-tier pricing structure across premium, standard, and economy levels separates SIL-rated industrial units from automotive aftermarket devices and consumer-grade infrared clones. Pricing pressure stems from TSMC and Samsung foundry allocation constraints on RF transceiver chips. Electronics retailers exhibit highest price sensitivity; security companies purchasing PL-d certified equipment demonstrate lowest.
Supply Chain Analysis
RF transceiver chips and SAW resonators draw from Taiwan, South Korea, and China foundry networks, with PCB assemblies clustering in Shenzhen's manufacturing corridors. Raw material dependencies center on semiconductor-grade silicon substrates, copper-clad laminates, and lithium coin-cell power sources. Single-source vulnerability concentrates in advanced RF chip fabrication. Distribution runs through specialty automotive locksmith suppliers and industrial safety equipment distributors in German-speaking markets, with direct manufacturer-to-integrator channels bypassing traditional wholesale tiers for high-volume security and automotive service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth Low Energy convergence with legacy RF capture protocols is disrupting established duplicator hardware categories, creating expansion vectors for smartphone-integrated credential management across multi-family residential and commercial access control deployments.
For Market Incumbents: Harden firmware licensing partnerships with tier-1 automotive suppliers against AES-128 encryption proliferation that threatens passive signal-capture obsolescence. Deepen backward integration into Shenzhen component sourcing to defend margin position against foundry allocation volatility affecting RF transceiver supply.
For New Entrants and Emerging Players: Pursue India's 50-million-unit passenger vehicle parc where dealer-network key replacement coverage remains sparse, deploying mobile duplication services through Maharashtra and Karnataka automotive clusters. Leverage MIIT type approval streamlining to compress certification timelines for Shenzhen-exported hardware targeting provincial service networks.
For Investors and Strategic Acquirers: Capital is best deployed toward protocol-analysis specialists with embedded security expertise concentrated in Tel Aviv, Tallinn, and Shenzhen, given multi-year viability of rolling-code decryption capabilities against automotive OEM encryption arms races. Monitor firmware reverse-engineering talent scarcity as inflection signal for competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Licensing Agreement | Secures authorized protocol access from Chamberlain Group and Nice S.p.A. for compatible duplication. |
| CE Marking Pre-Certification Partnership | Streamlines EU Radio Equipment Directive compliance through German and Dutch notified body relationships. |
| Software-Defined Radio Platform Launch | Enables field-upgradable frequency coverage through over-the-air protocol library updates. |
| Industrial Safety Certification Investment | Unlocks premium positioning in German and Nordic markets through SIL-rated and PL-d credentials. |
| Bluetooth Low Energy Hybrid Development | Captures smartphone-integrated key management demand in North American multi-family residential properties. |
Research Methodology
Desk research of FCC equipment authorization databases, MIIT type approval registries, and EU Radio Equipment Directive notified body submissions preceded structured interviews with automotive aftermarket service directors, industrial safety equipment procurement managers, and Shenzhen-based OEM export specialists. Secondary validation drew from customs trade data, semiconductor foundry allocation disclosures, and garage door automation OEM technical documentation. Bottom-up unit demand modeling triangulated against top-down market size estimates from frequency-band shipment analysis.
Assumptions held fixed include regulatory certification timeline structures and automotive OEM encryption protocol deployment schedules, while variables encompassed RF chip foundry capacity allocation and smart home interoperability standard convergence. Segmentation dimensions spanned product type, end user category, technology protocol, and distribution channel, with geographic production cluster effects layered across the projection horizon. CAGRs derived from logistic growth curve fitting against historical adoption inflection points in comparable access control technology markets, incorporating BLE credential provisioning penetration rates and industrial safety certification velocity as industry-specific inputs.
Sensitivities concentrate around automotive OEM encryption mandate acceleration and MIIT certification timeline reversals. Cross-checking against IHS Markit vehicle registration data and Shenzhen customs export statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Virtual Hiring Tools Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
IT Operations Management Market
Digital Solutions
China Cloud OSS BSS Market
Digital Solutions
Digital Clothing Market
Digital Solutions
Legal Technology Market
Digital Solutions
Data Extraction Market
Digital Solutions
Game Engines Market
Digital Solutions
Product Information Management Market