
 Nigeria E-Commerce Market | 2026-2036
Nigeria E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria E-Commerce Market Outlook
Subscription-based delivery memberships is repositioning unit economics for Nigerian e-commerce platforms. Cokodeal leverages its B2B marketplace focus to sustain merchant lock-in across regional trade corridors. Autochek anchors vehicle financing and inspection services within its auto-commerce vertical. Metro Africa Xpress competes through last-mile logistics control in dense urban corridors.
Nigeria e-commerce comprises digital retail transactions conducted via web and mobile platforms, relying on payment gateways, inventory management systems, and fulfillment networks to connect buyers with sellers across fragmented physical infrastructure. Fashion and electronics dominate product category volume, with groceries representing the fastest-growing segment as cold-chain logistics mature. Mobile payment methods lead transaction flow, while cash on delivery retains structural importance in peri-urban zones where banking penetration lags; same-day delivery models concentrate margin pools in Lagos and Abuja.
The Central Bank of Nigeria governs electronic payment standards and mobile money licensing, while the Nigerian Communications Commission regulates data infrastructure and platform access; both bodies shape market entry costs and consumer trust thresholds. The country's national consumer protection regulator enforces product authenticity and dispute resolution frameworks that influence cross-border seller participation. Stakeholders must monitor regulatory clarity on digital taxation and data localization requirements as enforcement capacity evolves.
Market Dynamics
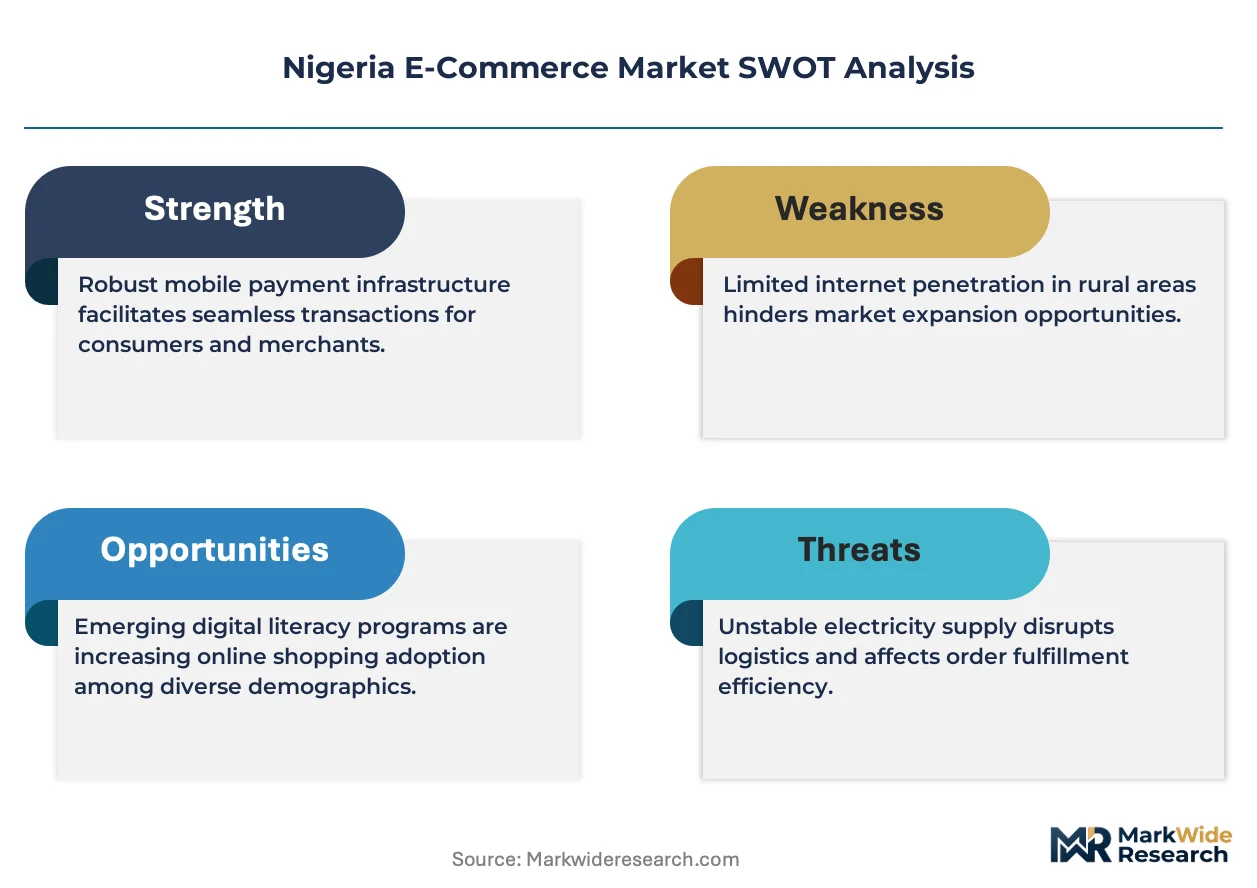
The Central Bank of Nigeria's cashless policy mandate is compressing payment friction across digital retail channels, forcing platform operators to rebuild checkout flows around mobile wallet infrastructure rather than traditional card rails.
Growth Catalysts
- Mobile Money Licensing:The Central Bank of Nigeria's tiered licensing framework for Payment Service Banks expands deposit-taking capabilities for non-bank operators, deepening financial inclusion in peri-urban corridors.
- Cold-Chain Infrastructure:Temperature-controlled logistics investment from Lagos-based fulfillment operators unlocks grocery and pharmaceutical verticals previously excluded from digital retail.
- Urban Millennial Density:Concentrated smartphone penetration in Lagos and Abuja creates addressable demand pools with above-average order frequency in fashion and electronics categories.
Market Restraints
- Diesel Price Volatility:Last-mile delivery fleets depend on petroleum-based fuel inputs subject to federal subsidy removal shocks, compressing unit economics for same-day services.
- Single-City Fulfillment Concentration:Over 70% of bonded warehouse capacity sits within Lagos State, exposing national delivery promises to localized grid congestion and port delays.
- Interbank Settlement Latency:NIBSS instant payment rails experience peak-hour throughput constraints, creating checkout abandonment during high-traffic promotional windows.
Strategic Opportunities
- Abuja-Nasarawa Logistics Corridor:Underdeveloped fulfillment infrastructure in the Federal Capital Territory periphery offers first-mover positioning for regional distribution hubs.
- BNPL Integration:Embedded consumer credit products within checkout flows address purchasing power constraints among salary-cyclical urban demographics.
- State-Level Digital Tax Clarity:Anticipated harmonization of e-commerce levies across Nigerian states would reduce compliance fragmentation for cross-state merchants.
Industry Challenges
- Warehouse Automation Talent:Scarcity of robotics integration specialists delays deployment of automated picking systems in existing Lagos facilities.
- Legacy ERP Migration:Merchant onboarding friction persists where sellers operate offline inventory management systems incompatible with real-time API synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria E-Commerce Market |
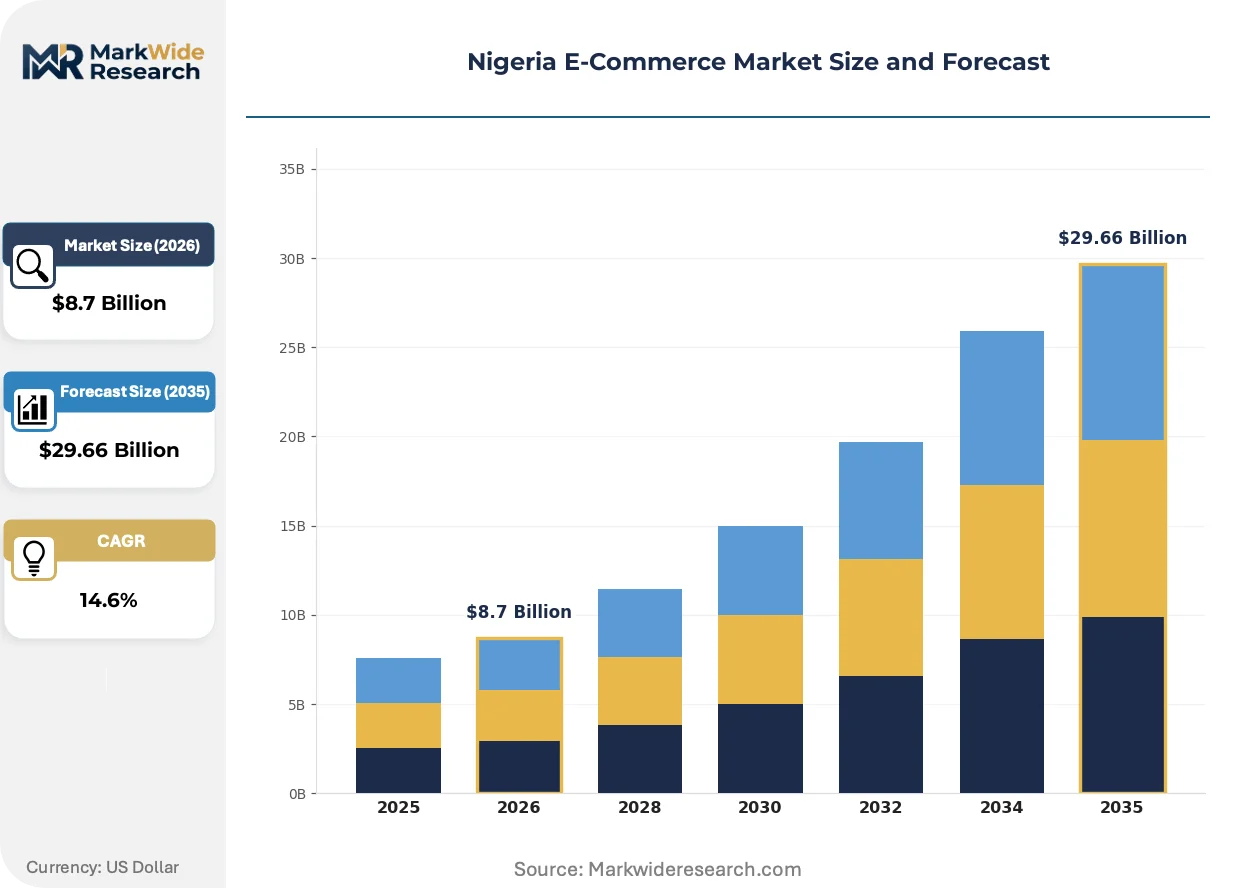
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Home Goods, Groceries Payment Method: Credit Card, Mobile Payment, Bank Transfer, Cash on Delivery Delivery Model: Same-Day Delivery, Standard Shipping, Click & Collect, International Shipping Customer Segment: Millennials, Gen Z, Professionals, Small Business Owners |
| Companies Covered | Cokodeal, Ripples, Metro Africa Xpress, DAYDONE, Poddin, Autochek, Atoovis, Injina Nigeria Limited, Wenamart, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria E-Commerce Market Strategic Shifts
Platform architecture decisions are converging on composable commerce stacks that decouple frontend presentation from backend fulfillment logic, enabling faster vertical specialization without core system rebuilds.
Headless commerce architecture is modularizing storefront development for Nigerian fashion retailers, allowing direct-to-consumer brands to deploy progressive web applications without monolithic platform dependencies. Mid-market merchants in Lagos and Port Harcourt are adopting micro-frontend approaches at accelerating pace. This modularity compresses time-to-market for seasonal collection launches from months to weeks.
The Central Bank of Nigeria's revised Card Scheme Guidelines mandate interoperability standards for domestic payment switches, reducing acquirer lock-in for platform operators. Industrial consequence includes downward pressure on merchant discount rates for local card transactions. Marketplace operators serving cross-border sellers are reconfiguring settlement flows to prioritize Naira-denominated rails over international card networks.
Subscription-based delivery memberships are displacing per-order shipping fees among Abuja-based grocery platforms, locking in predictable demand patterns and improving route density for last-mile providers. This model concentrates customer lifetime value metrics for platforms willing to absorb upfront fulfillment subsidies. Urban corridor density in Lagos Island and Ikeja GRA makes this approach economically viable before wider geographic rollout.
Nigeria E-Commerce Market Segmentation
Platform operators in Nigeria face divergent fulfillment economics across product categories and customer cohorts. Payment behavior and delivery expectations fragment sharply between Lagos urban corridors and peri-urban zones, requiring modular infrastructure investments.
Product Category:
Purchase frequency and margin profiles separate electronics buyers from grocery shoppers in ways that reshape warehouse configuration decisions.
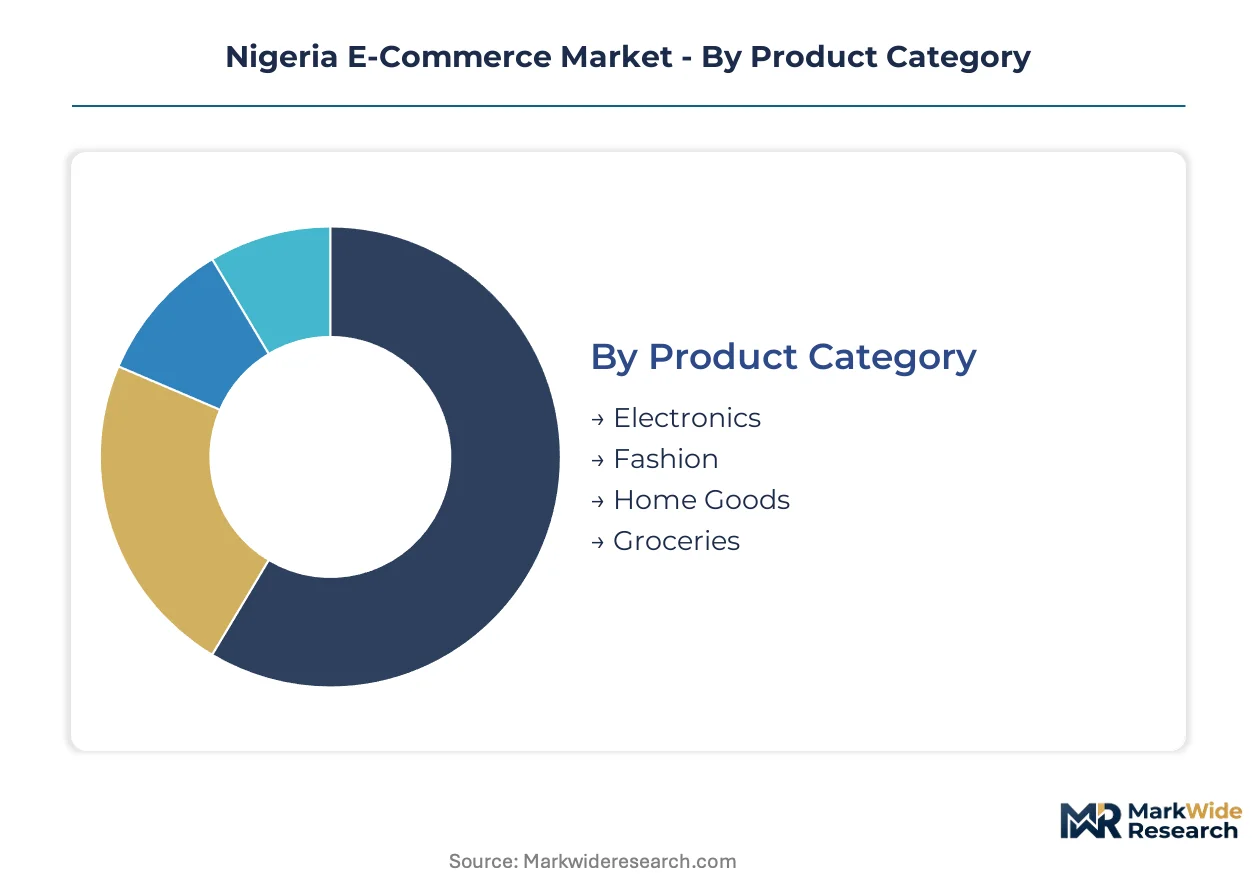
- Electronics:High-value transactions with extended consideration cycles dominate this segment. Lagos Island and Ikeja GRA concentrate demand for smartphones and computing equipment, where warranty authenticity concerns drive platform selection.
- Fashion:Rapid inventory turnover and seasonal collection velocity characterize this segment. Urban millennials in Lagos and Abuja generate above-average order frequency, though return rates compress net margins.
- Home Goods:Bulky logistics requirements favor platforms with bonded warehouse partnerships in Lagos State. Delivery cost absorption remains the primary customer acquisition lever.
- Groceries:Cold-chain infrastructure unlocks this segment. Temperature-controlled fulfillment investment from Lagos-based operators is expanding addressable demand in pharmaceutical-adjacent categories.
Volume sits with Electronics; growth tilts toward Groceries.
Payment Method:
Banking penetration gaps and Central Bank of Nigeria policy mandates create stark payment preference divides across Nigerian geographies.
- Credit Card:Limited issuer penetration restricts this segment to upper-income Lagos and Abuja demographics. Domestic card scheme interoperability requirements are compressing merchant discount rates.
- Mobile Payment:Payment Service Bank licensing expansion is deepening deposit-taking capabilities for non-bank operators. Peri-urban corridors in Ogun and Oyo states show accelerating adoption velocity.
- Bank Transfer:NIBSS instant payment rails experience peak-hour throughput constraints. Checkout abandonment spikes during promotional windows create platform reliability risks.
- Cash on Delivery:Structural importance persists in northern and eastern zones where mobile wallet penetration lags. Last-mile collection costs erode unit economics for same-day services.
Transaction volume concentrates in Mobile Payment; Cash on Delivery retains defensive positioning in underbanked corridors.
Delivery Model:
Route density and diesel price exposure determine which fulfillment modes achieve sustainable unit economics across Nigerian urban corridors.
- Same-Day Delivery:Subscription membership models are displacing per-order fees in Lagos Island and Ikeja GRA. Route density requirements limit geographic scalability outside Abuja's central districts.
- Standard Shipping:National coverage depends on Lagos State warehouse concentration. Port delays and grid congestion propagate delivery promise failures to northern destinations.
- Click & Collect:Locker network deployment remains sparse outside Lagos and Abuja. Partner retail footprint expansion would unlock cost advantages for peri-urban fulfillment.
- International Shipping:Cross-border settlement flows face Naira volatility exposure. Customs clearance friction at Lagos ports compresses delivery predictability.
Margin pools concentrate in Same-Day Delivery; Click & Collect offers expansion leverage for capital-constrained operators.
Customer Segment:
Digital literacy and purchasing power cycles segment Nigerian e-commerce demand across generational and occupational boundaries.
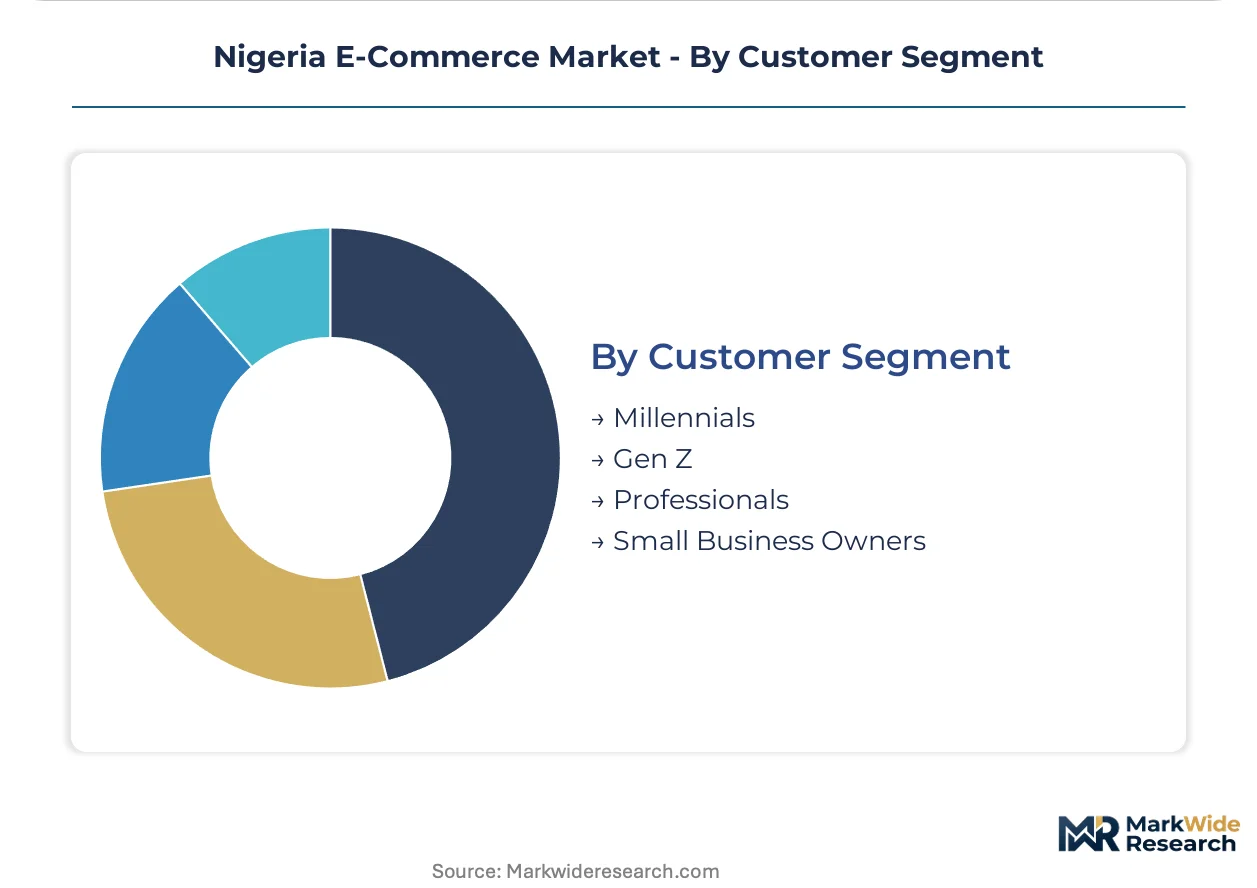
- Millennials:Smartphone-native behavior drives fashion and electronics category dominance. Salary-cyclical spending patterns create demand troughs in final weeks of payment cycles.
- Gen Z:Social commerce discovery channels and peer recommendation dependency distinguish this cohort. Platform loyalty remains undeveloped, with price sensitivity exceeding service quality prioritization.
- Professionals:Time-scarcity and convenience premium willingness support subscription delivery adoption. Lagos and Abuja corporate corridor density enables targeted acquisition.
- Small Business Owners:B2B marketplace participation concentrates in regional trade corridor merchants. Inventory procurement cycles differ from consumer purchase patterns, requiring distinct platform architecture.
Revenue concentration rests with Millennials; Gen Z represents the steepest expansion trajectory for platform lifetime value investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption clusters in Lagos State while fulfillment infrastructure concentrates in the same corridor, creating geographic imbalance between demand generation and supply-side capacity deployment across Nigerian sub-regions.
Lagos State
Urban millennial density and smartphone penetration drive fashion and electronics transaction volume in Lagos Island and Ikeja GRA. The Central Bank of Nigeria's cashless policy mandates reshape payment gateway configurations for platforms serving this corridor. Bonded warehouse capacity concentrates in Lagos State, exposing national delivery promises to localized port congestion and grid delays.
Federal Capital Territory
Professional cohorts in Abuja's corporate districts sustain subscription-based grocery delivery adoption with above-average convenience premiums. The Central Bank of Nigeria's Payment Service Bank licensing expands mobile wallet deposit-taking capabilities for non-bank operators serving peri-urban Nasarawa periphery. Underdeveloped fulfillment infrastructure in the FCT periphery offers first-mover positioning for regional distribution hubs.
Ogun State
Peri-urban corridors between Lagos and Abeokuta show accelerating mobile payment adoption velocity as Payment Service Bank licensing deepens financial inclusion. The Central Bank of Nigeria's tiered licensing framework enables non-bank operators to extend deposit-taking services beyond traditional banking infrastructure. Logistics operators leverage Ogun's position along the Lagos-Ibadan expressway to establish intermediate staging facilities.
Rivers State
Port Harcourt's mid-market merchants adopt micro-frontend approaches for fashion retail storefront development at accelerating pace. The Nigerian Communications Commission regulates data infrastructure access that shapes platform reliability thresholds for this corridor. Industrial clusters around Onne and Trans Amadi layout attract fulfillment operators seeking alternatives to Lagos State concentration.
Kano State
Cash on delivery retains structural importance in northern zones where mobile wallet penetration lags behind southern corridors. The country's national consumer protection regulator enforces product authenticity frameworks that influence cross-border seller participation in this market. Trade corridor merchants in Kano's Dawanau grain market and Sabon Gari commercial district participate in B2B marketplace procurement cycles distinct from consumer purchase patterns.
Nigeria E-Commerce Market Competitive Environment
Capital-heavy logistics operators compete with asset-light marketplace platforms for margin capture in Nigerian e-commerce. The vendor base stratifies across three tiers: integrated vertical specialists controlling last-mile fleets, horizontal marketplaces aggregating merchant supply, and niche B2B platforms serving regional trade corridors. Dominant competitive moves include subscription-based delivery membership deployment and cold-chain infrastructure investment for grocery vertical expansion.
Within the B2B marketplace tier, Cokodeal exemplifies merchant lock-in strategies across regional trade corridors. Autochek anchors vehicle financing and inspection services within auto-commerce vertical specialization. Metro Africa Xpress occupies a position emphasizing last-mile logistics control in dense urban corridors. These three entities represent divergent archetypes: horizontal B2B aggregation, vertical auto-commerce integration, and logistics-native platform development.
| Leading Market Players |
|---|
| Cokodeal |
| Ripples |
| Metro Africa Xpress |
| DAYDONE |
| Poddin |
| Autochek |
| Atoovis |
| Injina Nigeria Limited |
| Wenamart |
| Others |
Value Chain & Pricing Dynamics
Headless commerce architecture adoption by Lagos and Port Harcourt fashion retailers compresses storefront development costs while concentrating margin capture among platforms with modular backend systems. This technology shift simultaneously reduces merchant onboarding friction and reinforces pricing power for fulfillment operators controlling bonded warehouse capacity.
Pricing Analysis
Price erosion across standard delivery tiers traces to diesel subsidy removal shocks compressing last-mile operator margins. Three-tier pricing structure across premium same-day, standard 2-3 day, and economy 5-7 day levels differentiates urban corridor density and fuel cost absorption. Cost compression in same-day services accelerates because subscription membership models displace per-order fees. Small business owners in B2B marketplace procurement show lowest price sensitivity; Gen Z consumers exhibit highest.
Supply Chain Analysis
Freight cost volatility from petroleum-based fuel inputs exposes last-mile delivery economics to federal pricing policy shifts. Fulfillment infrastructure draws from China for warehouse automation equipment, India for enterprise software licensing, and South Africa for cold-chain refrigeration units. Bonded warehouse capacity concentrates in Lagos State, creating single-city vulnerability to port congestion and grid delays. Distribution runs through Lagos-based fulfillment operators to national destinations, with intermediate staging in Ogun State along the Lagos-Ibadan expressway.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigerian e-commerce platforms compete through vertical-integration races into last-mile logistics and cold-chain infrastructure. Players pursue downstream control over delivery networks as the decisive margin lever.
For Market Incumbents: Deepen merchant lock-in through embedded financing products and subscription delivery memberships that raise switching costs. Expand bonded warehouse automation in Lagos State to defend against diesel price volatility eroding same-day unit economics. Prioritize Payment Service Bank licensing partnerships to secure deposit-taking capabilities ahead of regulatory tightening. For New Entrants and Emerging Players: Capture the Abuja-Nasarawa logistics corridor where fulfillment infrastructure remains underdeveloped and professional cohorts sustain convenience premiums. Target grocery verticals in temperature-controlled categories where cold-chain investment barriers exclude asset-light competitors. Deploy micro-frontend storefront approaches to compress time-to-market for seasonal fashion launches. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated logistics operators seeking last-mile control and horizontal marketplaces pursuing vertical category depth. Long-term viability favors platforms with captive warehouse capacity and mobile wallet settlement infrastructure. Watch Payment Service Bank license issuance velocity as inflection signal for financial inclusion depth and deposit-taking competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | Temperature-controlled fulfillment unlocks grocery and pharmaceutical verticals previously excluded from digital retail. |
| Subscription Delivery Membership Launch | Predictable demand patterns improve route density and concentrate customer lifetime value for Lagos-based operators. |
| Payment Service Bank Licensing Pursuit | Central Bank of Nigeria tiered framework enables non-bank deposit-taking capabilities deepening financial inclusion. |
| Micro-Frontend Architecture Adoption | Modular storefront development compresses seasonal collection launch timelines for Port Harcourt fashion merchants. |
| Regional Distribution Hub Establishment | Abuja-Nasarawa corridor positioning captures professional cohort convenience premiums in underdeveloped fulfillment zones. |
Study Parameters
Independent corroboration across platform operations executives, logistics fleet managers, and merchant onboarding specialists underwrites the qualitative findings in this study. Primary interviews with Payment Service Bank license applicants, warehouse automation integrators, and grocery vertical operators combined with secondary validation from Central Bank of Nigeria policy circulars, Nigerian Communications Commission infrastructure reports, and customs trade data. Bottom-up transaction volume modeling and top-down macroeconomic anchoring provided cross-verification.
Comparable-period anchoring to historical mobile wallet adoption curves and e-commerce penetration trajectories established the forecast baseline across the projection horizon. Segmentation dimensions modeled include product category velocity, payment method infrastructure maturity, delivery model route density, and customer segment digital literacy tiers. CAGRs derived from logistic diffusion curves fitted to smartphone penetration and cashless policy compliance data, with diesel price volatility and interbank settlement latency as scenario inputs.
The model holds under continued Central Bank cashless policy enforcement and mobile wallet interoperability standards; deviation in diesel subsidy restoration or port clearance delays would shift fulfillment cost assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
South America E-Commerce Apparel Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
Global Ecommerce Platform Market
E-Commerce Solutions
Oman E-Commerce Market
E-Commerce Solutions
Automotive E-Commerce Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
India E-Commerce Warehousing Market
E-Commerce Solutions
E-Commerce Software Market
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Global Healthcare E-Commerce Market
E-Commerce Solutions
E-Commerce in Nigeria Market