
 Digital User Experience Solutions Market | 2026-2036
Digital User Experience Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Digital User Experience Solutions Market Outlook
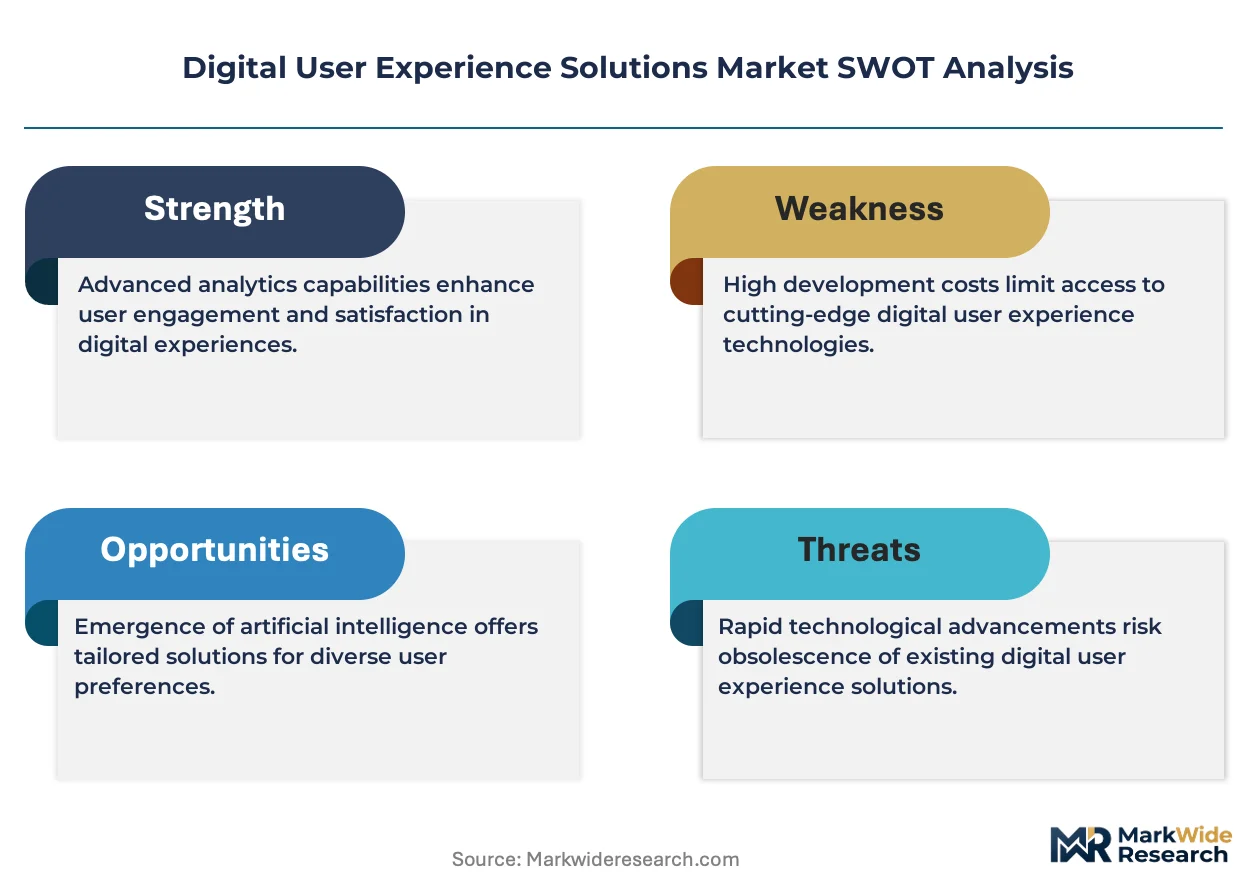
Generative AI integration into design workflows is rewriting how digital experiences are conceived, prototyped, and deployed at scale. Adobe Inc. leverages its creative software heritage to anchor enterprise design operations, while Salesforce.com, Inc. competes through embedded UX capabilities within its CRM ecosystem. Microsoft Corporation extends its position by weaving user experience tools into Azure cloud services, creating captive demand among existing enterprise subscribers.
Digital User Experience Solutions encompass the research, design, testing, and optimization services that shape how users interact with software interfaces, typically incorporating interaction design patterns, accessibility compliance protocols, and performance metrics such as task completion rates and System Usability Scale scores. These solutions serve commercial and industrial purposes by reducing friction in digital transactions, improving customer retention, and lowering support costs across touchpoints. Cloud Computing deployment models now dominate enterprise procurement by offering elastic infrastructure for real-time experience personalization, while AI-powered service layers represent the fastest-expanding margin pool as vendors automate research synthesis and predictive usability scoring. Interaction Design remains the most mature service category, though Usability Testing is gaining structural importance as regulatory compliance tightens.
The EU AI Act and GDPR establish binding requirements for explainable algorithms and consent-driven data processing in European digital experiences, directly shaping vendor qualification and procurement timelines. ISO 9241 ergonomics standards and WCAG accessibility guidelines further constrain product design choices, creating compliance-driven demand for specialized UX consultancies. Stakeholders must weigh whether to build captive AI design capabilities or rely on external platforms as regulatory scrutiny intensifies and liability frameworks mature.
Market Dynamics
Generative AI integration into design workflows is compressing research-to-deployment cycles from months to weeks, forcing incumbent vendors to restructure service delivery models around automated synthesis and predictive usability scoring rather than traditional labor-intensive methods.
Growth Catalysts
- EU AI Act compliance mandates:Binding requirements for explainable algorithms in financial interfaces are accelerating procurement of audit-ready UX platforms across German, French, and British retail banking operations.
- Cloud-native personalization engines:Elastic infrastructure for real-time experience adaptation is capturing enterprise budgets previously allocated to on-premise design tool licenses.
- Germany:Stricter digital accessibility enforcement under the BFSG (Barrierefreiheitsstärkungsgesetz) is generating specialized demand for WCAG 2.1 AAA-compliant design consultancies.
Market Restraints
- Specialized talent scarcity:Shortage of designers proficient in both interaction design patterns and AI model interpretability is inflating project staffing costs by 40-60% above baseline UX rates.
- Regulatory fragmentation:Divergent GDPR implementation across EU member states creates compliance overhead for vendors serving multi-jurisdictional financial institutions.
- Legacy system entrenchment:Core banking infrastructure predating API-first architectures constrains seamless integration of modern UX layers without costly middleware development.
Strategic Opportunities
- France:Underpenetrated SME banking segment presents whitespace for standardized, compliance-embedded UX solution packages priced below enterprise tiers.
- Voice and multimodal interfaces:Convergence of conversational AI with biometric authentication is opening new design service categories for accessible banking experiences.
- CSRD reporting requirements:Mandatory sustainability disclosures are creating demand for UX solutions that visualize ESG data within customer-facing dashboards.
Industry Challenges
- Cross-functional alignment friction:Bridging design systems, data science, and legal compliance teams extends procurement timelines and inflates stakeholder management overhead.
- WCAG certification bottlenecks:Limited accredited testing bodies in the United Kingdom are creating 8-12 week delays for accessibility validation required by public sector contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital User Experience Solutions Market |
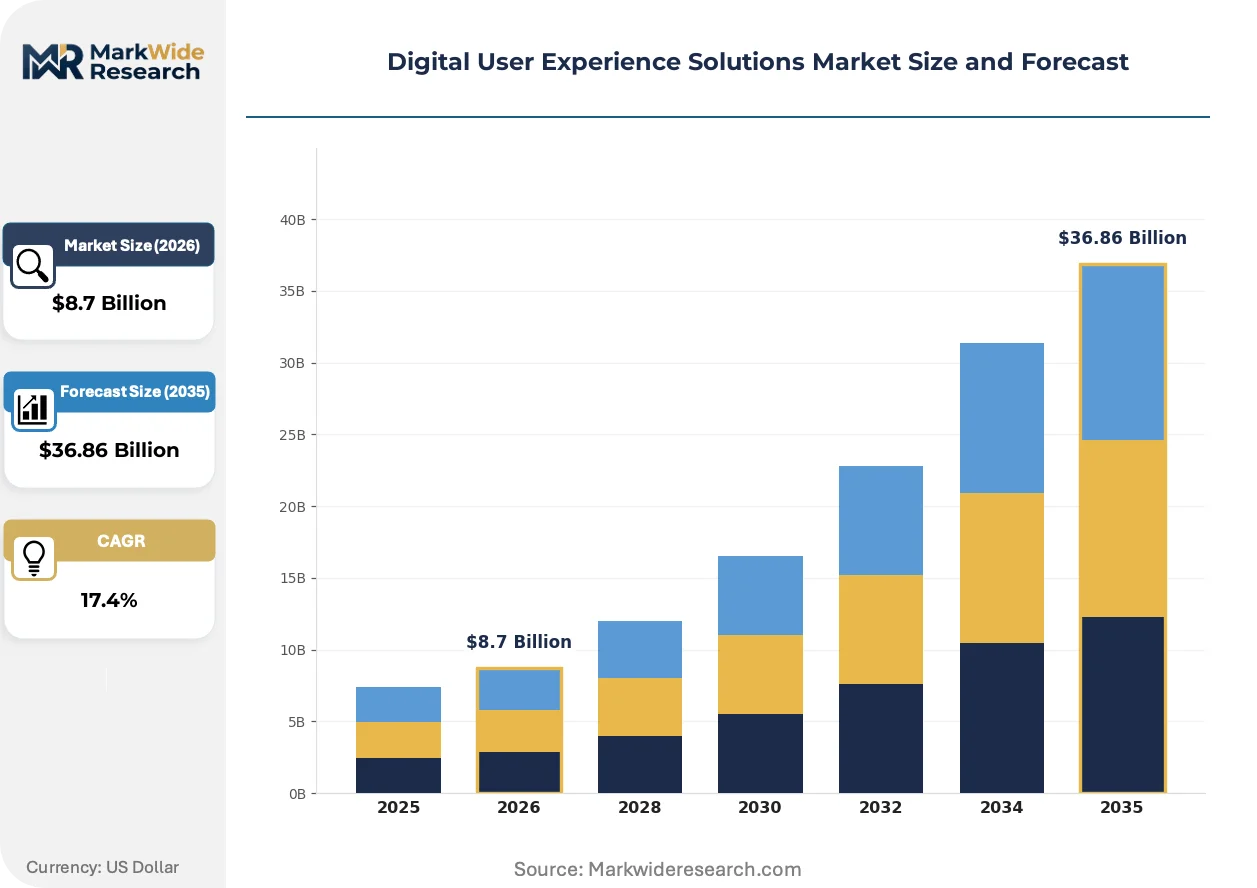
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: User Research, Interaction Design, Usability Testing, Content Strategy Industry Vertical: Retail, Finance, Healthcare, Education Technology: AR, VR, AI, Cloud Computing Customer Type: SMEs, Enterprises, Startups, Nonprofits |
| Companies Covered | Accenture plc, Adobe Inc., Salesforce.com, Inc., International Business Machines Corporation, Deloitte Digital, Cognizant Technology Solutions Corp., Capgemini SE, Oracle Corporation, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital User Experience Solutions Market Strategic Shifts
Automation of research synthesis and predictive design is redistributing value capture from labor-intensive agencies toward platform vendors with embedded AI capabilities.
Generative design copilots trained on interaction pattern libraries are rendering obsolete the traditional wireframing and prototyping specialist roles that dominated UX team structures. Mid-market financial institutions are adopting these tools at twice the rate of Fortune 500 banks due to leaner in-house design functions. The shift is compressing agency revenue per project while expanding addressable volume for self-service platforms.
GDPR Article 22 provisions on automated decision-making are forcing explainability layers into personalization engines. Vendors must now architect "why" disclosures directly into interface components rather than treating transparency as post-hoc documentation. British retail banks face the steepest compliance curve given the Financial Conduct Authority's concurrent focus on consumer duty obligations.
Enterprise buyers are unbundling research, design, and testing contracts previously awarded to full-service agencies. Procurement teams at German insurers now source usability testing through specialized SaaS platforms while retaining strategic design relationships with boutique consultancies. This bifurcation is most pronounced in regulated verticals where compliance documentation requirements favor audit-trail-rich software over opaque creative processes.
Digital User Experience Solutions Market Segmentation
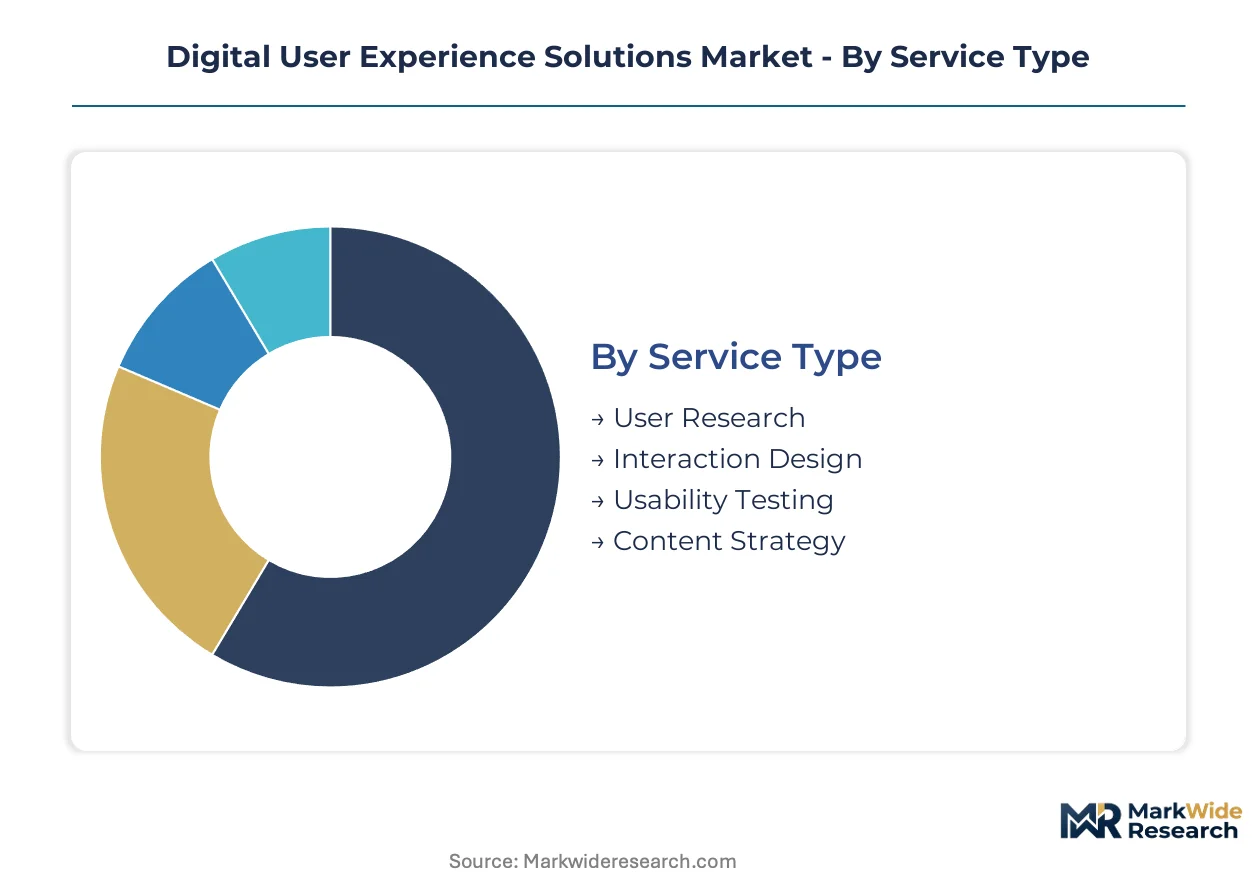
Segmentation in digital user experience solutions reveals how procurement patterns diverge across service maturity, compliance requirements, and infrastructure sophistication. Vendors must align delivery models with distinct buyer capabilities and regulatory exposure.
Service Type:
Mature disciplines dominate revenue concentration while emerging automation layers capture margin expansion.
- Interaction Design:Established practice encompassing wireframing, prototyping, and design system architecture. German retail banking interfaces under BFSG mandates drive specialized demand for WCAG 2.1 AAA-compliant pattern libraries.
- Usability Testing:Validation protocols measuring task completion rates, SUS scores, and accessibility conformance. United Kingdom public sector contracts face 8-12 week bottlenecks at accredited testing bodies.
- User Research:Behavioral analysis and journey mapping informing design decisions.
- Content Strategy:Information architecture and microcopy optimization for conversion.
Interaction Design handles the majority of throughput; Usability Testing is gaining share fastest on regulatory tailwinds.
Industry Vertical:
Regulatory intensity creates tiered pricing power across buyer categories.
- Finance:Retail banking, insurance, and wealth management interfaces subject to EU AI Act explainability requirements and GDPR Article 22 automated decision-making disclosures. French SME banking segment shows whitespace for standardized compliance-embedded packages.
- Healthcare:Patient portals and clinical decision support systems requiring HIPAA-aligned privacy architectures in US markets.
- Retail:E-commerce personalization engines and omnichannel experience orchestration.
- Education:Learning management systems and student-facing administrative platforms.
Finance commands premium pricing; Healthcare presents the steepest expansion trajectory on digital health acceleration.
Technology:
Infrastructure deployment models determine scalability and integration complexity.
- Cloud Computing:Elastic infrastructure for real-time personalization and experience adaptation. Enterprise budgets shift from on-premise design tool licenses toward consumption-based service layers.
- AI:Predictive usability scoring, automated research synthesis, and generative design copilots trained on interaction pattern libraries. Mid-market financial institutions adopt at twice the rate of Fortune 500 banks.
- AR:Spatial interface prototyping and immersive product visualization.
- VR:Full-environment simulation for accessibility testing and training scenarios.
Cloud Computing anchors procurement volume; AI is climbing the fastest on automation ROI.
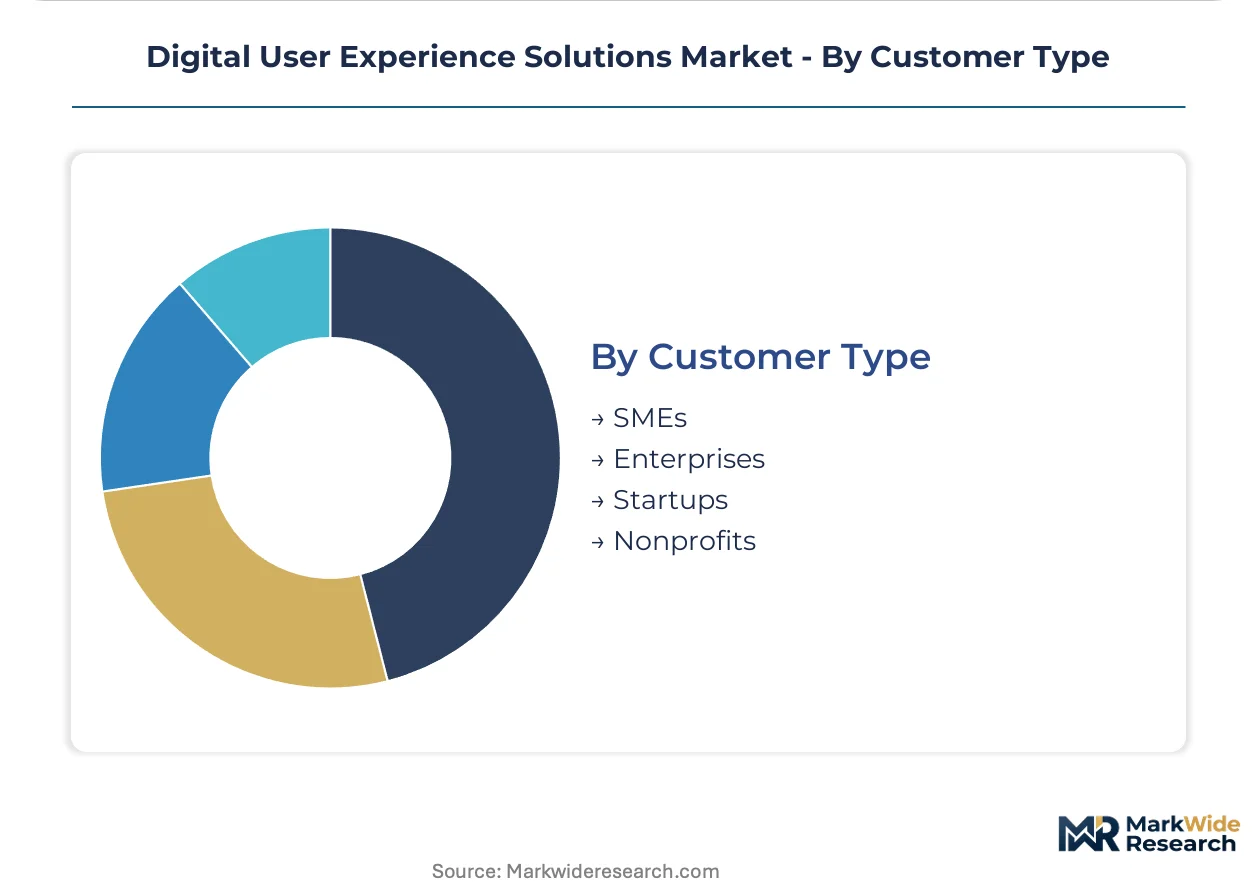
Customer Type:
Organizational scale dictates build-versus-buy calculus and platform sophistication requirements.
- Enterprises:Fortune 500 institutions with captive design operations and complex multi-jurisdictional compliance obligations. Procurement teams unbundle research, design, and testing contracts across specialized vendors.
- SMEs:Mid-market institutions with leaner in-house functions driving self-service platform adoption. French SME banking segment shows particular concentration.
- Startups:Venture-backed companies prioritizing speed-to-market over comprehensive accessibility conformance.
- Nonprofits:Mission-driven organizations with constrained budgets and public sector grant requirements.
Enterprises dominate absolute spend; SMEs are expanding most quickly on platform accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in financial services concentrate procurement budgets in jurisdictions with mature regulatory frameworks and established design talent pools. Germany, the United Kingdom, France, and the United States anchor demand concentration, while India emerges as a delivery hub for offshore UX engineering capacity.
Germany
Retail banking interfaces drive specialized demand for WCAG 2.1 AAA-compliant pattern libraries under BFSG enforcement. The Barrierefreiheitsstärkungsgesetz mandates full digital accessibility compliance by 2025, accelerating vendor qualification timelines. Frankfurt's financial cluster hosts captive design operations at Commerzbank and Deutsche Bank, while Berlin's startup ecosystem feeds mid-market SaaS platform adoption.
United Kingdom
Public sector contracts face 8-12 week bottlenecks at accredited WCAG testing bodies, constraining procurement velocity. The Financial Conduct Authority's consumer duty obligations compound GDPR Article 22 explainability requirements for British retail banks. London's fintech corridor concentrates demand for audit-trail-rich usability testing platforms, with Manchester and Edinburgh emerging as secondary delivery centers.
France
The underpenetrated SME banking segment presents whitespace for standardized compliance-embedded UX packages priced below enterprise tiers. CNIL enforcement of GDPR automated decision-making provisions forces explainability layers into personalization engines. Paris anchors financial institution headquarters demand, while Lyon and Toulouse house specialized accessibility consultancies serving provincial banking networks.
United States
Fortune 500 technology and financial services firms drive premium demand for AI-powered personalization engines with predictive usability scoring. HIPAA-aligned privacy architectures constrain healthcare UX design choices, creating specialized vendor requirements. San Francisco and New York anchor enterprise procurement, with Austin and Seattle emerging as centers for generative design tool development.
India
Global capability centers in Bangalore and Hyderabad deliver offshore UX engineering and research synthesis at compressed cost structures. RBI guidelines on digital payment interface usability create domestic compliance demand alongside export-oriented services. Mumbai's financial services cluster and Delhi-NCR's IT services corridor concentrate both delivery capacity and emerging local enterprise demand.
Digital User Experience Solutions Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Consolidated enterprise consultancies anchor high-value transformation contracts, while vertical SaaS platforms capture mid-market volume through self-service accessibility tools. Boutique design studios occupy regulatory specialization niches, particularly in German BFSG compliance and British public sector WCAG certification. Dominant competitive moves include strategic partnerships between cloud infrastructure providers and specialized testing platforms, alongside portfolio diversification into generative AI design copilots.
Within the enterprise consultancy tier, Accenture plc and Deloitte Digital exemplify channel-controlling archetypes that bundle UX capabilities into broader digital transformation mandates. Adobe Inc. occupies a distinct position as a product heritage player extending creative software dominance into enterprise design operations. Microsoft Corporation anchors the platform-integrated archetype, weaving user experience tools into Azure cloud services to capture captive demand among existing enterprise subscribers. These three patterns—consultancy-led transformation, creative software extension, and cloud platform embedding—define the competitive structure without implying specific strategic actions or market share claims by any named entity.
| Leading Market Players |
|---|
| Accenture plc |
| Adobe Inc. |
| Salesforce.com, Inc. |
| International Business Machines Corporation |
| Deloitte Digital |
| Cognizant Technology Solutions Corp. |
| Capgemini SE |
| Oracle Corporation |
| Microsoft Corporation |
| Others |
Value Chain & Pricing Dynamics
EU AI Act compliance mandates on algorithmic explainability compress both pricing tier spreads and supply chain configuration, forcing vendors to absorb specialized audit-ready development costs while tiering delivery models around regulatory risk exposure rather than pure capability differentiation.
Pricing Analysis
Cost-plus contracts indexed to specialized AI talent rates dominate enterprise procurement, with price differentiation anchored in WCAG certification grade and vertical integration depth. Three-tier pricing structure across premium audit-ready platforms, standard compliance-embedded tools, and economy self-service tiers is narrowing as mid-market buyers consolidate around middle-tier offerings. Pricing pressure stems from generative AI automation compressing research-to-deployment cycles, with SME banking segments in France exhibiting highest price sensitivity and Fortune 500 institutions with captive design operations showing lowest.
Supply Chain Analysis
Tariff exposure between the United States and China on cloud infrastructure hardware dominates supply chain risk assessment for UX platform vendors. Delivery capacity concentrates in India, Germany, and the United Kingdom, with raw material dependencies spanning GPU compute clusters, accessibility testing accreditation, and specialized design pattern libraries. Single-source vulnerability around accredited WCAG testing bodies in the United Kingdom creates procurement bottlenecks. Distribution runs through direct enterprise sales teams for Fortune 500 accounts and self-service SaaS platforms for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is pronounced as enterprise buyers unbundle research, design, and testing contracts across specialized vendors, creating niches for regulatory-specialist boutiques alongside platform-scale players.
For Market Incumbents: Harden audit-trail capabilities in usability testing platforms to defend against specialized SaaS entrants capturing German BFSG compliance demand. Deepen vertical integration into generative AI design copilots to offset margin compression from automated research synthesis. Channel control through cloud platform embedding remains the priority defensive lever against creative software heritage players. For New Entrants and Emerging Players: Mid-market SME banking segments in France represent the most penetrable entry point, with standardized compliance-embedded UX packages priced below enterprise tiers offering immediate addressable volume. Voice and multimodal interface design services for accessible banking experiences present adjacent whitespace. A direct-to-bank procurement team go-to-market angle bypasses entrenched consultancy relationships. For Investors and Strategic Acquirers: EU AI Act enforcement milestones reshape the acquisition landscape, elevating vendors with pre-built explainability layer architectures. Long-term viability across the analysis window favors platforms with embedded AI capabilities over labor-intensive agency models. Acquisition target archetype: specialized accessibility consultancies with WCAG 2.1 AAA certification pipelines. The signal to watch is accreditation body capacity expansion in the United Kingdom as inflection indicator for testing platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Design Copilot Launch | Automated research synthesis displaces traditional wireframing specialist roles at mid-market financial institutions. |
| WCAG 2.1 AAA Certification Investment | BFSG enforcement in Germany creates captive demand for audit-ready accessibility pattern libraries. |
| Cloud Platform Integration Partnership | Azure-embedded UX tools capture subscription revenue from existing enterprise Microsoft relationships. |
| Specialized Accessibility Consultancy Acquisition | Accredited testing body relationships in the United Kingdom unlock public sector contract access. |
| Explainability Layer Architecture Development | GDPR Article 22 compliance embeds transparency directly into personalization engine interfaces. |
Study Parameters
Operator-level perspectives from UX design directors, regulatory compliance officers at European financial institutions, procurement leads at German insurers, and platform engineering heads anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings of listed software vendors, EU AI Act implementation guidance documents, WCAG accreditation body records, and cloud hyperscaler capex disclosures. Bottom-up service line sizing and top-down macro constraint triangulation ensured cross-verification.
Scenario-bracketing around regulatory enforcement intensity and AI adoption velocity framed the analytical approach across the analysis window. Segmentation dimensions modeled encompass service type maturity, industry vertical regulatory intensity, deployment infrastructure, and organizational scale. CAGRs derived from elasticity-adjusted adoption curves and compliance-driven replacement cycles. Industry-specific forecast inputs include BFSG deadline proximity and accredited testing body capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in enterprise software spending cycles or cloud infrastructure investment pauses would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement consistency and generative AI capability advancement rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Transport Management System Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Microservices Architecture Market
Digital Solutions
Utility Cases Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
South Africa ICT Market
Digital Solutions
Web Performance Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
Global E-Filing Platforms Market
Digital Solutions
Japan E-Invoicing Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
United States ICT Market
Digital Solutions
Asia-Pacific Digital Pen Market