
 Middle East Data Center Rack Market | 2026-2036
Middle East Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Data Center Rack Market Insights
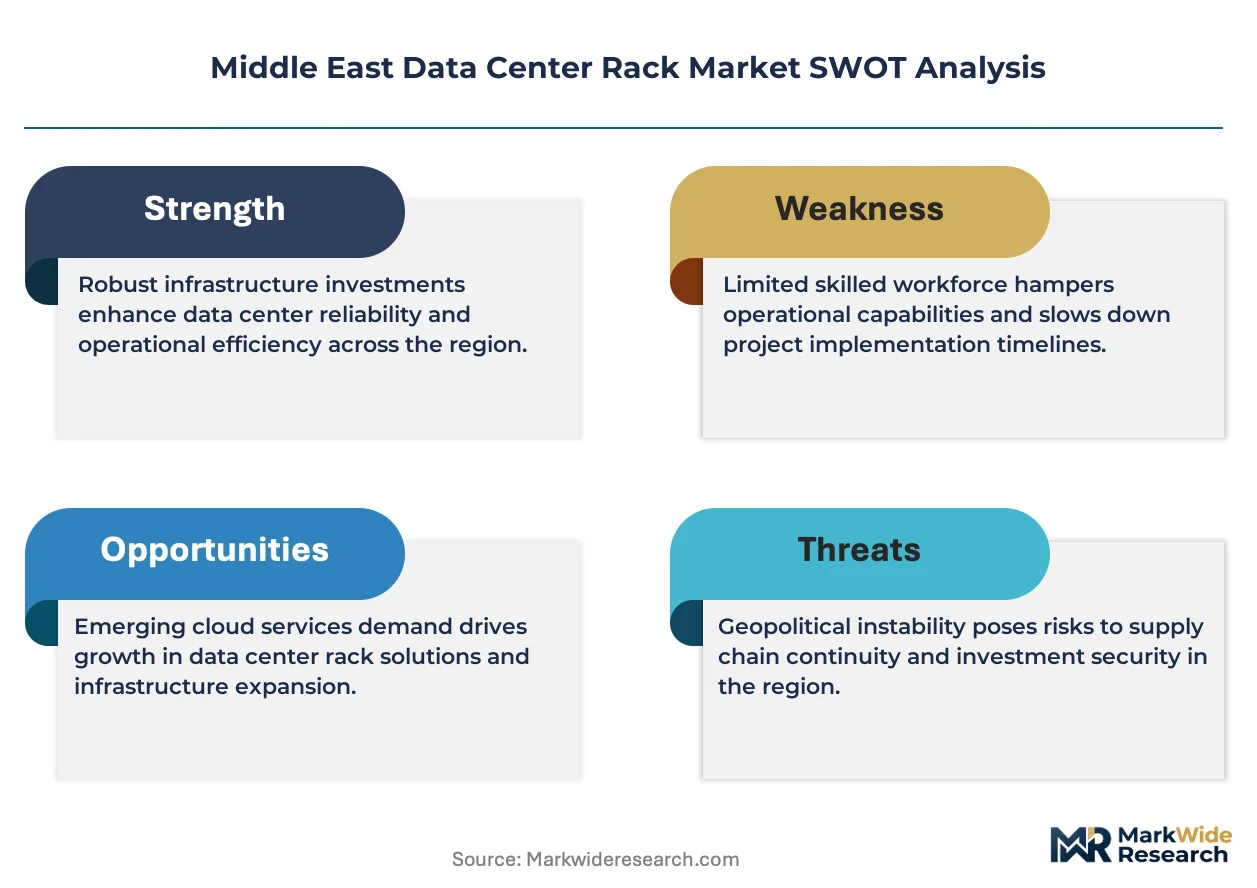
Saudi Arabia's domestic metal fabrication sector is consolidating around data center infrastructure supply. Schneider Electric SE leverages its regional manufacturing partnerships to anchor rack distribution across Gulf markets. Vertiv Group Corp. competes through thermal-integrated rack systems designed for desert climate operations. Rittal GmbH & Co. KG specializes in modular enclosure architectures that sustain deployment velocity for colocation operators.
A data center rack is a standardized metal frame engineered to house servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA width specifications and load ratings between 1,000 and 3,000 pounds. Its primary purpose is to organize IT hardware vertically, optimize airflow management, and enable scalable infrastructure expansion in controlled environments. Server rack configurations dominate current procurement volumes as cloud providers and telecommunications operators prioritize high-density computing enclosures. Edge computing installations represent the fastest-growing installation type, driven by latency-sensitive applications requiring distributed processing nodes across urban corridors. Enclosed rack variants command premium positioning where dust filtration and thermal isolation prove critical for Gulf climate resilience.
The UAE's Telecommunications and Digital Government Regulatory Authority enforces facility certification standards that dictate rack-level power redundancy and fire suppression integration. Saudi Arabia's Communications, Space and Technology Commission mandates local content requirements influencing supplier qualification and manufacturing location decisions. Stakeholders must monitor evolving national data sovereignty frameworks that will determine rack specification compliance thresholds and cross-border equipment certification pathways.
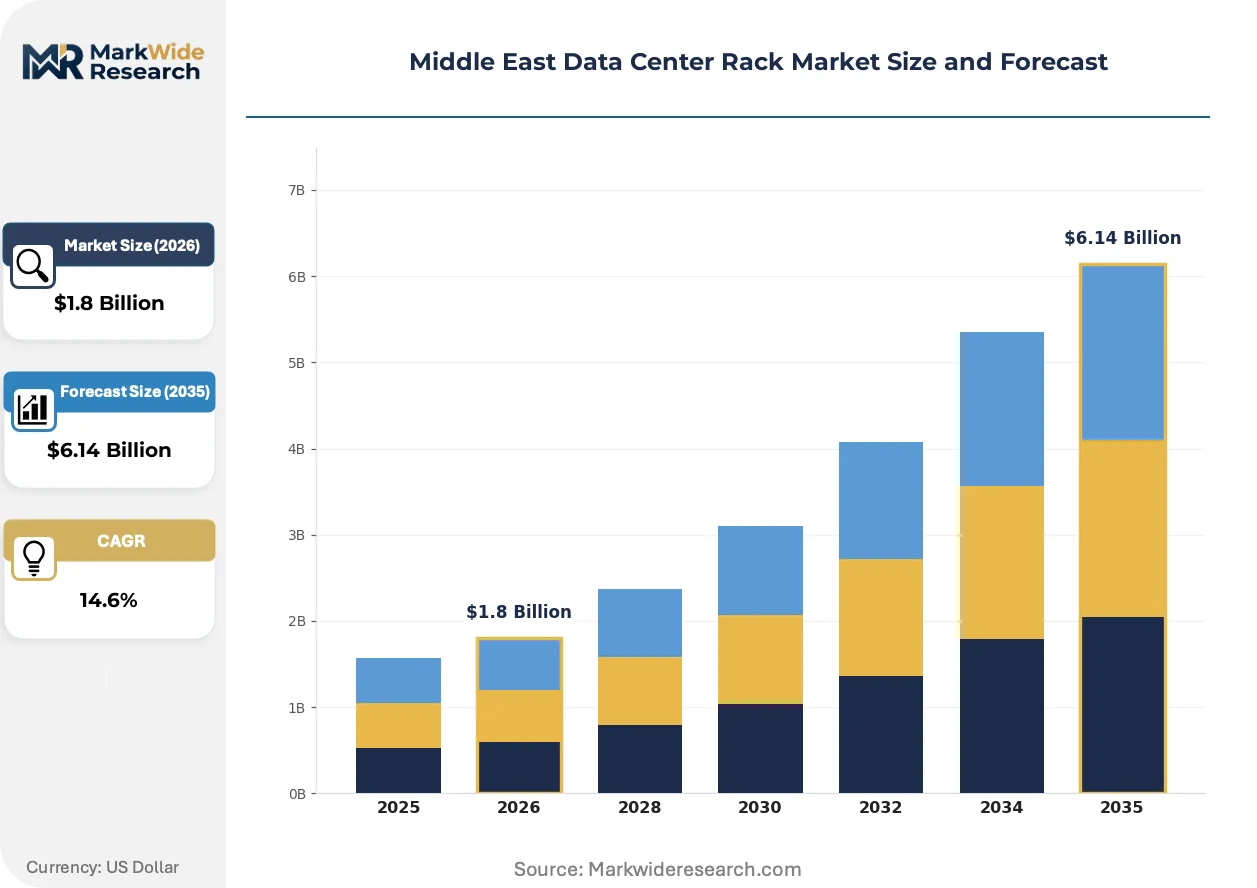
Market Dynamics
Hyperscale cloud deployment across Gulf Cooperation Council states is compressing procurement cycles and forcing rack suppliers to localize manufacturing capacity. Saudi Arabia's domestic content mandates and the UAE's certification requirements are restructuring supplier qualification pathways.
Growth Catalysts
- Vision 2030 infrastructure mandates:Saudi Arabia's national transformation program requires sovereign data hosting capacity, driving rack procurement specifications across government and enterprise verticals.
- Edge computing latency requirements:Financial services and autonomous systems in Dubai and Riyadh demand distributed micro-data centers, expanding addressable rack volume beyond traditional hyperscale facilities.
- TDRA facility certification standards:The UAE's telecommunications regulator enforces redundant power and fire suppression integration, elevating technical specifications and average selling prices for compliant enclosures.
Market Restraints
- Steel and aluminum input volatility:Regional metal fabrication depends on imported raw materials, exposing rack manufacturers to shipping cost fluctuations and currency hedge requirements.
- Supplier concentration in East Asian component sourcing:Power distribution units and precision cooling subsystems flow through limited channel partners, creating single-source vulnerability for Gulf assemblers.
- Desert climate thermal engineering:Ambient temperatures exceeding 50°C impose derating requirements on standard rack designs, limiting off-the-shelf product applicability without modification.
Strategic Opportunities
- Neom and Red Sea Project greenfield sites:Saudi Arabia's planned megaprojects incorporate data center zones from inception, enabling rack-integrated facility design rather than retrofit specifications.
- Liquid cooling convergence with high-density compute:GPU clusters for artificial intelligence training exceed air-cooled thermal limits, creating retrofit and new-build demand for liquid-ready rack architectures.
- Direct procurement by hyperscale operators:Cloud providers are bypassing systems integrators for rack-level contracts, compressing channel margins while expanding volume commitments to qualified manufacturers.
Industry Challenges
- Thermal and mechanical engineering talent scarcity:Gulf universities produce limited graduates in computational fluid dynamics and heat transfer, forcing reliance on expatriate specialists and knowledge transfer delays.
- Multi-certification timeline compression:Rack systems must simultaneously satisfy TDRA, CST, and IEC standards for cross-border deployment, extending validation cycles and pre-revenue engineering investment.
- Legacy facility retrofit integration:Existing raised-floor data centers in Dubai Internet City and Riyadh Tech Valley use non-standard dimensions, complicating rack replacement and capacity expansion workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Data Center Rack Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Server Rack, Open Frame Rack, Wall-Mount Rack, Enclosed Rack End User: Telecommunications, Cloud Providers, Enterprises, Government Installation Type: On-Premises, Colocation, Modular, Edge Computing Power Rating: Low Power, Medium Power, High Power, Others |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., Rittal GmbH & Co. KG, Legrand SA, Hewlett Packard Enterprise, Dell Technologies, Eaton Corporation plc, Chatsworth Products, Black Box Corporation, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Data Center Rack Market Trends and Innovations
Modular prefabrication is displacing on-site rack assembly across Middle East data center construction. Suppliers are embedding power and cooling distribution into factory-integrated enclosures, compressing deployment timelines and reducing field labor dependencies.
Immersion cooling infrastructure is integrating directly into rack floor plans as GPU density requirements exceed 50 kilowatts per enclosure. Colocation operators in Dubai and Riyadh are specifying dielectric fluid-ready frames from initial procurement, avoiding costly retrofit cycles. This technology is integrating thermal management responsibility upward into rack supplier scope, compressing the traditional mechanical-electrical-contractor value chain.
CST local content requirements are mandating domestic manufacturing presence for government contract eligibility. Saudi Arabia's communications regulator now requires assembly or fabrication within the Kingdom for public sector rack procurement, forcing international suppliers to establish Jeddah or Riyadh production partnerships. Enterprise and hyperscale segments are responding by dual-sourcing across UAE and Saudi manufacturing footprints to maintain bid flexibility.
Power usage effectiveness guarantees are reshaping buyer-supplier contracting structures. Colocation tenants in Masdar City and King Abdullah Economic City now require rack-level energy efficiency warranties with financial penalties, transferring operational risk to enclosure manufacturers. This pattern is most visible in UAE and Saudi markets where sustainability-linked financing instruments reward demonstrated carbon intensity reductions.
Middle East Data Center Rack Market Segmentation
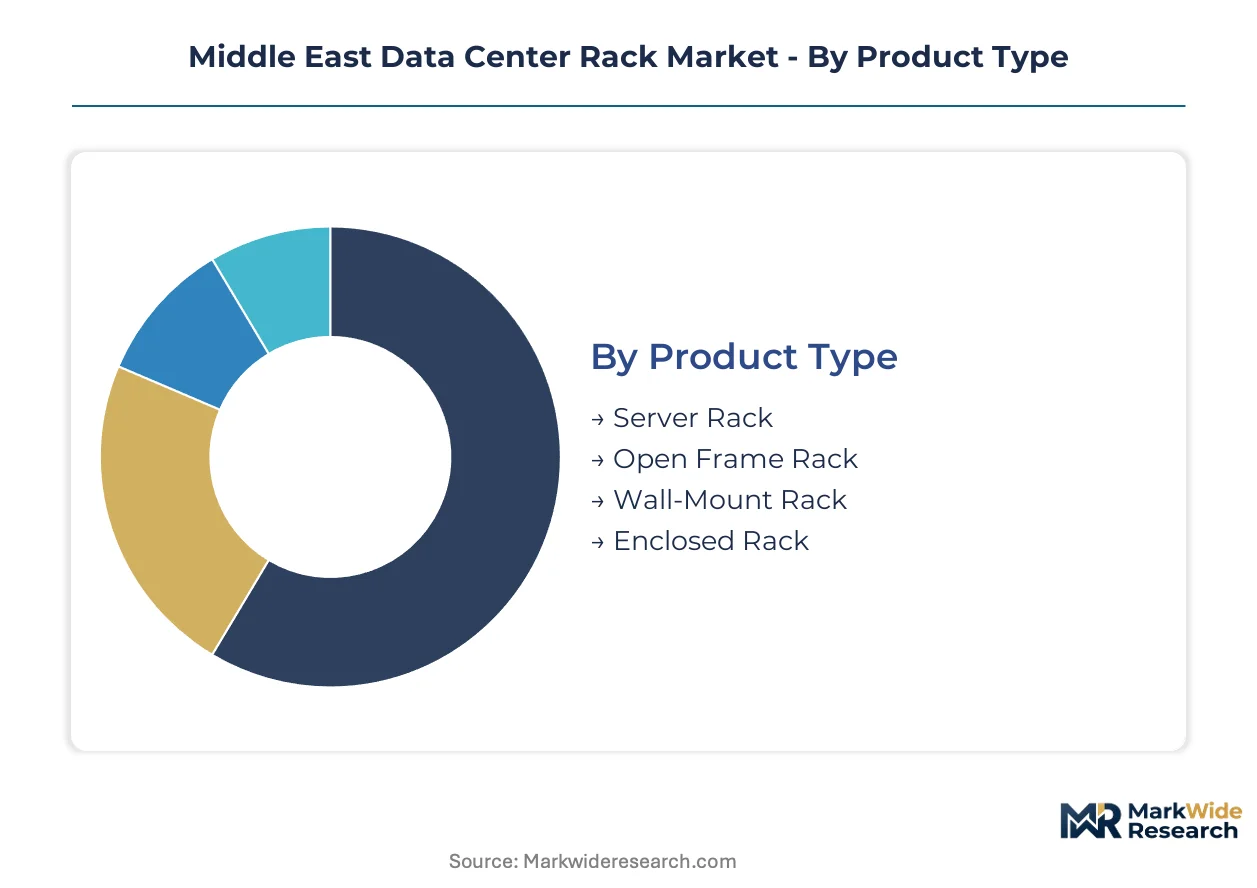
Data center rack segmentation in the Middle East reflects divergent infrastructure upgrade cycles across hyperscale, colocation, and enterprise deployments. Procurement patterns cluster around thermal specifications and power density thresholds that vary sharply by end-user vertical and installation environment.
Product Type:
Rack replacement cycles accelerate where hyperscale operators demand higher load ratings and integrated cooling compatibility, compressing standard product lifecycles.
- Server Rack:Standardized 19-inch EIA frames dominate procurement volumes across UAE and Saudi hyperscale facilities. Cloud providers in Dubai and Riyadh specify dynamic load ratings above 1,500 pounds to accommodate GPU-intensive compute nodes.
- Enclosed Rack:Dust-sealed architectures with integrated filtration systems address Gulf ambient conditions exceeding 50°C. Saudi government data centers under CST mandates prioritize these variants for sovereign hosting facilities.
- Open Frame Rack:Cost-optimized frames serve enterprise retrofit projects in legacy Dubai Internet City facilities.
- Wall-Mount Rack:Compact enclosures support distributed edge nodes in urban Riyadh and Jeddah corridors.
Server rack configurations sit at the top of the volume ranking, with enclosed rack variants climbing the fastest.
End User:
Customer procurement authority determines specification complexity, with direct hyperscale purchasing displacing traditional systems integrator channels.
- Cloud Providers:Hyperscale operators bypass distribution channels for direct manufacturer contracts, compressing margins while expanding volume commitments. AWS, Google, and Azure deployments across Masdar City and King Abdullah Economic City specify liquid-cooling-ready frames from initial procurement.
- Telecommunications:Etisalat and stc Group drive rack demand for 5G core infrastructure and edge aggregation points. These operators prioritize NEBS-compliant thermal specifications for outdoor cabinet integration.
- Enterprises:Banking and healthcare verticals in Dubai International Financial Centre specify TDRA-certified redundant power integration.
- Government:Saudi Vision 2030 mandates require domestic assembly qualification under CST local content rules.
Cloud providers command the largest addressable spend, with telecommunications expanding most quickly through 5G infrastructure rollout.
Installation Type:
Deployment architecture dictates rack modularity requirements, with prefabricated solutions displacing field-assembly for greenfield construction timelines.
- Colocation:Multi-tenant facilities in Dubai Silicon Oasis and Riyadh Tech Valley specify standardized 42U and 48U configurations with hot-aisle containment compatibility. Operators like Khazna and Mobily Data Center mandate factory-integrated power distribution to compress commissioning schedules.
- Edge Computing:Latency-sensitive financial trading and autonomous vehicle infrastructure in Dubai and Riyadh urban corridors drives micro-data center rack demand. These installations require shock-mounted frames for non-traditional building environments.
- On-Premises:Enterprise captive facilities in Abu Dhabi Global Market maintain legacy raised-floor specifications.
- Modular:Prefabricated all-in-one enclosures support rapid deployment at Neom and Red Sea Project greenfield sites.
Colocation installations hold the dominant volume position, with edge computing gaining share fastest through distributed infrastructure mandates.
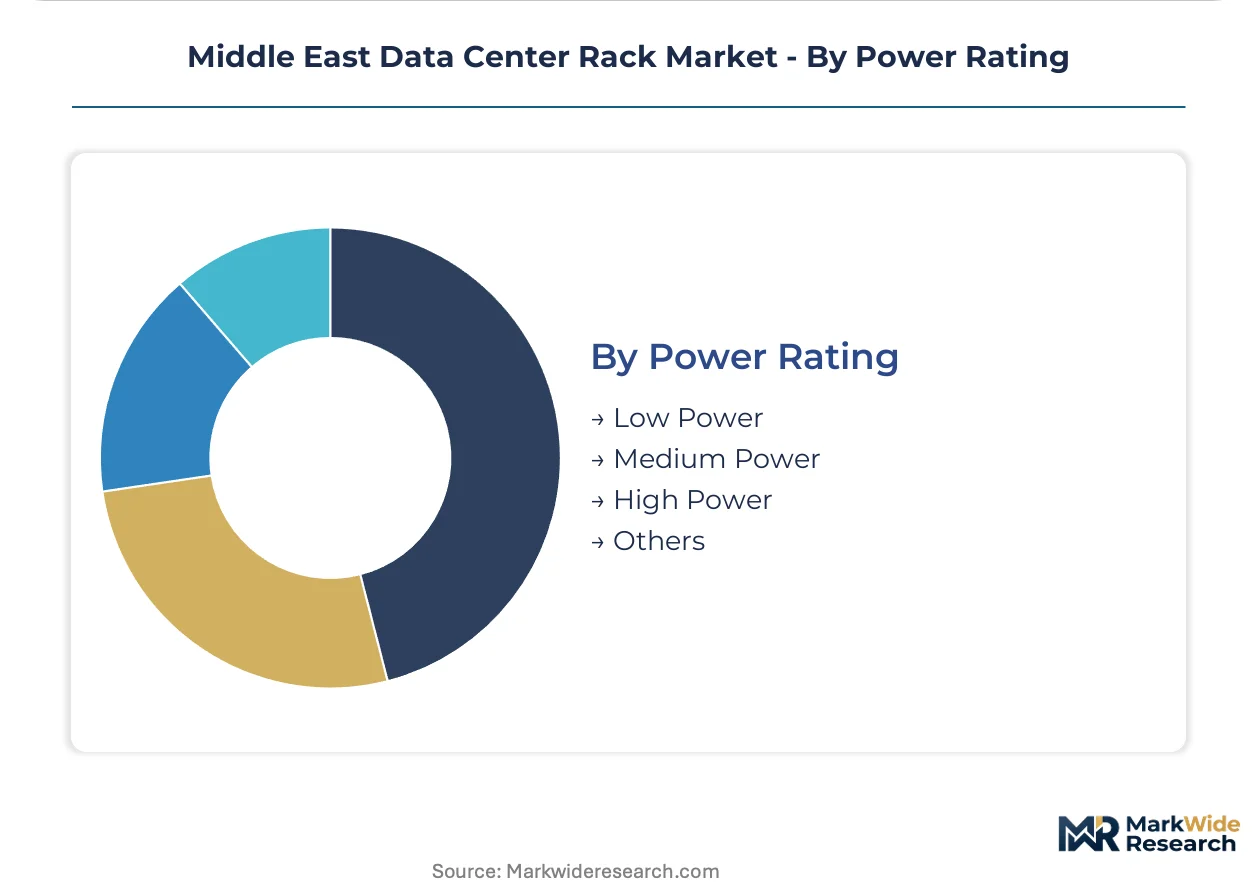
Power Rating:
Density gradients separate commodity procurement from premium specification tiers, with AI training clusters forcing rack-level thermal engineering upgrades.
- High Power:Enclosures rated above 30 kilowatts per rack serve GPU clusters for artificial intelligence training exceeding air-cooled limits. Saudi Aramco and ADNOC digital transformation programs specify these for reservoir simulation workloads.
- Medium Power:10-20 kilowatt ratings align with standard cloud compute node densities in UAE and Saudi hyperscale halls. This tier captures the broadest addressable market across enterprise and colocation verticals.
- Low Power:Sub-10 kilowatt frames support network equipment and storage arrays in telecommunications edge facilities.
- Others:Custom density configurations address specialized industrial control and research computing requirements.
Medium power ratings anchor current procurement volumes, with high power specifications tracing the steepest expansion trajectory through AI infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing cost-of-compliance gaps are driving rack assembly migration toward Gulf states with domestic content incentives. Suppliers now face divergent certification burdens across national regulators, reshaping regional production footprints.
United Arab Emirates
Dubai Internet City and Masdar City hyperscale campuses anchor rack procurement volumes. The Telecommunications and Digital Government Regulatory Authority enforces facility certification standards that mandate redundant power integration. Abu Dhabi Global Market colocation operators specify TDRA-compliant enclosures for financial services tenants.
Saudi Arabia
Neom and Red Sea Project greenfield data center zones incorporate rack-integrated facility design from inception. The Communications, Space and Technology Commission mandates local assembly qualification for government contract eligibility. Riyadh Tech Valley and King Abdullah Economic City concentrate domestic manufacturing partnerships.
Qatar
Lusail Smart City infrastructure and Qatar National Vision 2030 digital transformation programs expand addressable rack demand. The country's communications regulator enforces cyber-physical security standards for critical infrastructure enclosures. Doha Education City research computing clusters specify high-density thermal-ready frames.
Kuwait
South Surra and Subhan data center development zones drive procurement for cloud and enterprise verticals. The national telecom regulator imposes facility resilience standards affecting rack-level redundancy specifications. Kuwait City financial district colocation operators prioritize TIA-942 compliant enclosure architectures.
Bahrain
Bahrain FinTech Bay and cloud-first government digitization initiatives stimulate edge computing rack deployments. The national telecommunications regulatory authority aligns with GCC certification harmonization efforts. Manama Technology Park concentrates micro-data center installations for latency-sensitive trading infrastructure.
Middle East Data Center Rack Market Competitive Landscape
European electrical infrastructure conglomerates anchor one tier; North American thermal management specialists hold differentiated positions through climate-adapted engineering. The supplier base concentrates around integrated power-cooling-enclosure portfolios rather than pure-play metal fabrication. Three archetypes dominate: full-stack infrastructure providers, thermal-integrated rack specialists, and modular enclosure architects. Capacity localization and domestic manufacturing partnerships represent the primary competitive vectors as Gulf content mandates tighten.
Among the integrated infrastructure tier, Schneider Electric SE exemplifies the European conglomerate archetype with regional manufacturing scale. Vertiv Group Corp. occupies a position among North American specialists emphasizing thermal engineering for extreme climate operations. Rittal GmbH & Co. KG represents the modular enclosure archetype with standardized architectures for rapid deployment velocity. These three anchors illustrate how supplier qualification pathways increasingly hinge on in-country assembly presence rather than pure product specification.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| Rittal GmbH & Co. KG |
| Legrand SA |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Eaton Corporation plc |
| Chatsworth Products |
| Black Box Corporation |
| Others |
Pricing and Supply Chain Analysis
Liquid-cooling-ready rack architectures are compressing manufacturing cost curves while concentrating supplier qualification around thermal-integrated portfolios. This technology transition simultaneously elevates engineering investment thresholds and rewards Gulf-based assembly partnerships under CST and TDRA domestic content frameworks.
Pricing Analysis
Distributor margins in legacy channel structures face compression as hyperscale cloud providers in Masdar City and King Abdullah Economic City pursue direct manufacturer contracts. Pricing stratifies across TDRA-certified premium tiers, CST-compliant domestic assembly mid-tiers, and non-certified economy imports. Cost compression in standard server rack tiers is intensifying because Saudi and UAE buyers now bundle power distribution and cooling into single-source procurement. Government verticals under Vision 2030 mandates exhibit lowest price sensitivity; enterprise retrofit projects in Dubai Internet City legacy facilities show highest sensitivity.
Supply Chain Analysis
Workforce availability constraints in Saudi Arabia and the UAE are accelerating automated fabrication investments at Jeddah and Riyadh production partnerships. Component sourcing draws from China for power distribution units, Germany for precision cooling subsystems, and South Korea for specialized steel alloys. Single-source vulnerability pervades East Asian power distribution channels, exposing Gulf assemblers to logistics chokepoint risk. Distribution runs through systems integrators for enterprise segments while hyperscale operators bypass intermediaries entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East data center rack market functions as a geographic-arbitrage play where Saudi Arabia's CST local content mandates create cost-of-compliance premiums against UAE's established TDRA certification infrastructure.
For Market Incumbents: Hedge against hyperscale direct procurement by deepening captive manufacturing partnerships in Riyadh Tech Valley and Dubai Silicon Oasis. Anchor defensive positioning through dual-certification investment spanning TDRA facility standards and CST assembly qualifications. Vertical integration into precision cooling subsystems offsets margin erosion from disintermediated rack sales. For New Entrants and Emerging Players: Digital channel routes through colocation operator procurement platforms offer lowest barrier-to-entry penetration. Target edge computing micro-data center deployments in urban Riyadh and Jeddah corridors where specification complexity remains below hyperscale thresholds. Pursue go-to-market positioning around liquid-cooling retrofit expertise for existing Dubai Internet City facilities. For Investors and Strategic Acquirers: Valuations sit cheapest among modular enclosure specialists lacking Gulf manufacturing footprints. Long-term viability favors suppliers with demonstrated thermal engineering capabilities for ambient conditions exceeding 50°C. Acquisition target archetype: European enclosure architects with established Middle East distribution seeking Saudi assembly partnerships. Signal to watch: CST enforcement intensity on government contract eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Partnership | CST qualification unlocks Saudi government procurement under Vision 2030 mandates. |
| Liquid Cooling Integration | GPU density requirements above 50kW per enclosure reshape rack thermal specifications. |
| Dual Certification Investment | Simultaneous TDRA and CST compliance expands addressable contract universe across UAE-Saudi border. |
| Direct Hyperscale Contracting | Bypassing systems integrators compresses channel margins while securing volume commitments. |
| Prefabricated Modular Deployment | Factory-integrated power and cooling compression accelerates Neom and Red Sea Project timelines. |
Research Methodology
Coverage spans the United Arab Emirates, Saudi Arabia, Qatar, Kuwait, and Bahrain, with primary inputs from each national market. Primary interviews with data center facility operators, rack procurement managers at hyperscale cloud providers, thermal engineering specialists, and regulatory compliance officers combined with secondary validation from SEC filings of listed infrastructure suppliers, TDRA facility certification registries, CST procurement bulletins, and customs trade data. Bottom-up rack shipment estimates triangulated against top-down data center construction pipeline values.
Granularity-level modeling addressed product type at the enclosure architecture level, end user at the procurement authority tier, installation type at the deployment velocity segment, and power rating at the thermal density threshold. CAGRs derived from segmented growth rate reconciliation across hyperscale, colocation, and enterprise verticals. Forecast inputs incorporated AI training cluster deployment schedules and 5G edge aggregation point rollout timelines.
The model assumes a particular technology adoption path; alternative pathways for immersion cooling infrastructure would alter the outlook if dielectric fluid compatibility standards fragment across Gulf regulators. Forecasts reflect assumptions about CST enforcement consistency and TDRA certification harmonization. Material deviation in hyperscale capex commitment levels or domestic content mandate intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
Singapore Data Center Power Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Nigeria Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
Colocation Edge Data Center Market