
 Cloud Based Manufacturing Market | 2026-2036
Cloud Based Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Based Manufacturing Market Analysis
The Cloud Based Manufacturing Market is restructuring around a sharp divergence between premium enterprise suites with embedded AI analytics and commodity ERP modules sold on per-user pricing. SAP S/4HANA dominates the high-end segment through deep manufacturing vertical functionality. Plex Systems specializes in multi-tenant cloud architectures for mid-market discrete manufacturers. Oracle Cloud ERP extends its position via aggressive database-layer integration with shop-floor IoT data streams.
Cloud based manufacturing denotes the delivery of production management, supply chain orchestration, and quality systems through remote server infrastructure accessible via internet protocols, typically employing containerized microservices architectures with sub-100-millisecond latency requirements for real-time machine control. Its primary purpose is to replace on-premise MES and ERP installations with elastic compute resources that scale with order volatility. Hybrid cloud deployments are capturing the fastest expansion as manufacturers retain sensitive process data on private nodes while bursting analytics workloads to public infrastructure. IoT-enabled technology layers anchor the highest-margin subscription tiers by converting sensor telemetry into predictive maintenance revenue streams. Supply chain management applications remain the most mature functional area, though inventory optimization modules are displacing legacy WMS investments at the fastest clip among Tier-1 suppliers.
The EU AI Act and REACH chemical traceability requirements are reshaping product standards for cloud platforms serving European process industries, while FDA 21 CFR Part 11 compliance remains mandatory for pharmaceutical manufacturers deploying cloud quality systems in the United States. China's GB standards for industrial data security and SAMR cloud service classifications are creating parallel certification pathways that fragment vendor go-to-market strategies. Stakeholders must monitor how diverging data sovereignty regimes will force architecture decisions that either unify or Balkanize their platform deployments across manufacturing footprints.
Market Dynamics
Hybrid cloud deployments are forcing architectural bifurcation as manufacturers isolate sensitive process data on private nodes while bursting analytics workloads to public infrastructure, creating dual-certification burdens for platform vendors.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Smart factory systems in Germany's Industrie 4.0 corridor require explainable AI modules, pulling demand for compliant cloud-native production planning platforms.
- Automotive OEM cloud-native migration:Vehicle manufacturers are consolidating multi-site MES instances into single-tenant cloud architectures to synchronize EV battery production across distributed supplier networks.
- IoT-enabled predictive maintenance monetization:Sensor telemetry conversion into subscription revenue streams anchors the highest-margin tiers, with real-time machine control demands driving sub-100-millisecond latency specifications.
Market Restraints
- Data sovereignty fragmentation:China's GB standards for industrial data security and SAMR cloud service classifications force parallel certification pathways that Balkanize vendor deployment strategies.
- REACH chemical traceability compliance costs:European process industries face elevated platform certification expenses for cloud quality systems managing hazardous substance documentation.
- Legacy ERP sunk-cost entrenchment:On-premise MES installations in mature manufacturing bases create switching friction that delays elastic compute adoption.
Strategic Opportunities
- Mid-market discrete manufacturing penetration:Multi-tenant cloud architectures targeting sub-$500M revenue manufacturers remain underpenetrated relative to enterprise deployments.
- Inventory optimization module displacement:Cloud WMS functionality is capturing legacy warehouse management investments among Tier-1 automotive suppliers faster than adjacent categories.
- FDA 21 CFR Part 11 pharmaceutical compliance:Cloud quality system deployments for US drug manufacturers create a regulated vertical with high switching costs and recurring audit requirements.
Industry Challenges
- OT-IT convergence skill scarcity:Manufacturing engineers with simultaneous shop-floor operational technology and cloud infrastructure expertise command premium compensation that constrains rollout velocity.
- Containerized microservices integration complexity:Real-time machine control requirements demand specialized edge-to-cloud orchestration that exceeds standard DevOps competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Based Manufacturing Market |
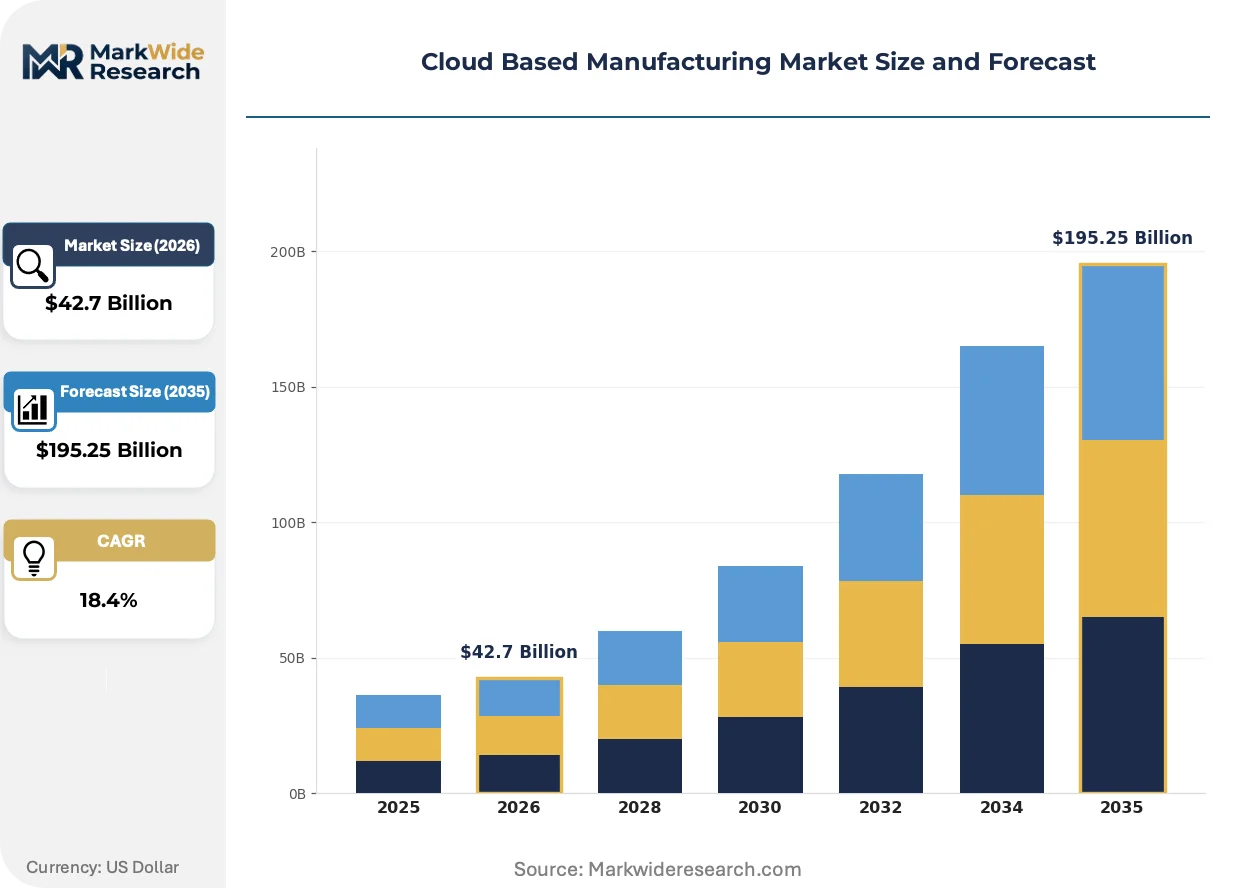
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $195.25 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Technology: IoT, AI, Machine Learning, Big Data End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors Application: Supply Chain Management, Product Lifecycle Management, Quality Control, Inventory Optimization |
| Companies Covered | Infor (Godlan), Acumatica Cloud ERP, SAP S/4HANA, Rootstock Software, Plex Systems, Oracle Cloud ERP, IFS Cloud, Protolabs, Microsoft Dynamics 365, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Based Manufacturing Market Emerging Trajectories
Cloud manufacturing platforms are absorbing edge computing capabilities that compress latency boundaries while regulatory jurisdictions harden data localization requirements that fragment deployment architectures.
Digital twin implementations are absorbing physics-based simulation workloads that previously ran on dedicated HPC clusters. Automotive powertrain manufacturers deploy these twins for virtual commissioning of assembly lines before physical installation. The technology is absorbing capital expenditure that once flowed to on-site simulation hardware, redirecting it toward cloud subscription commitments.
REACH chemical traceability extensions are mandating blockchain-anchored substance declarations for cloud platforms serving European process industries. The regulation forces vendors to embed immutable ledger layers for hazardous material lineage tracking. Specialty chemical manufacturers in Germany's Ruhr industrial cluster face the steepest compliance ramps as they retrofit legacy batch records.
Buyer procurement patterns are compressing contract cycles from annual to quarterly renegotiation as manufacturers demand elasticity clauses matching order volatility. Cloud ERP vendors are unbundling implementation services from subscription fees to accommodate this preference. The shift is most visible among contract electronics manufacturers in Mexico's Baja California assembly corridor serving North American OEMs.
Cloud Based Manufacturing Market Segmentation
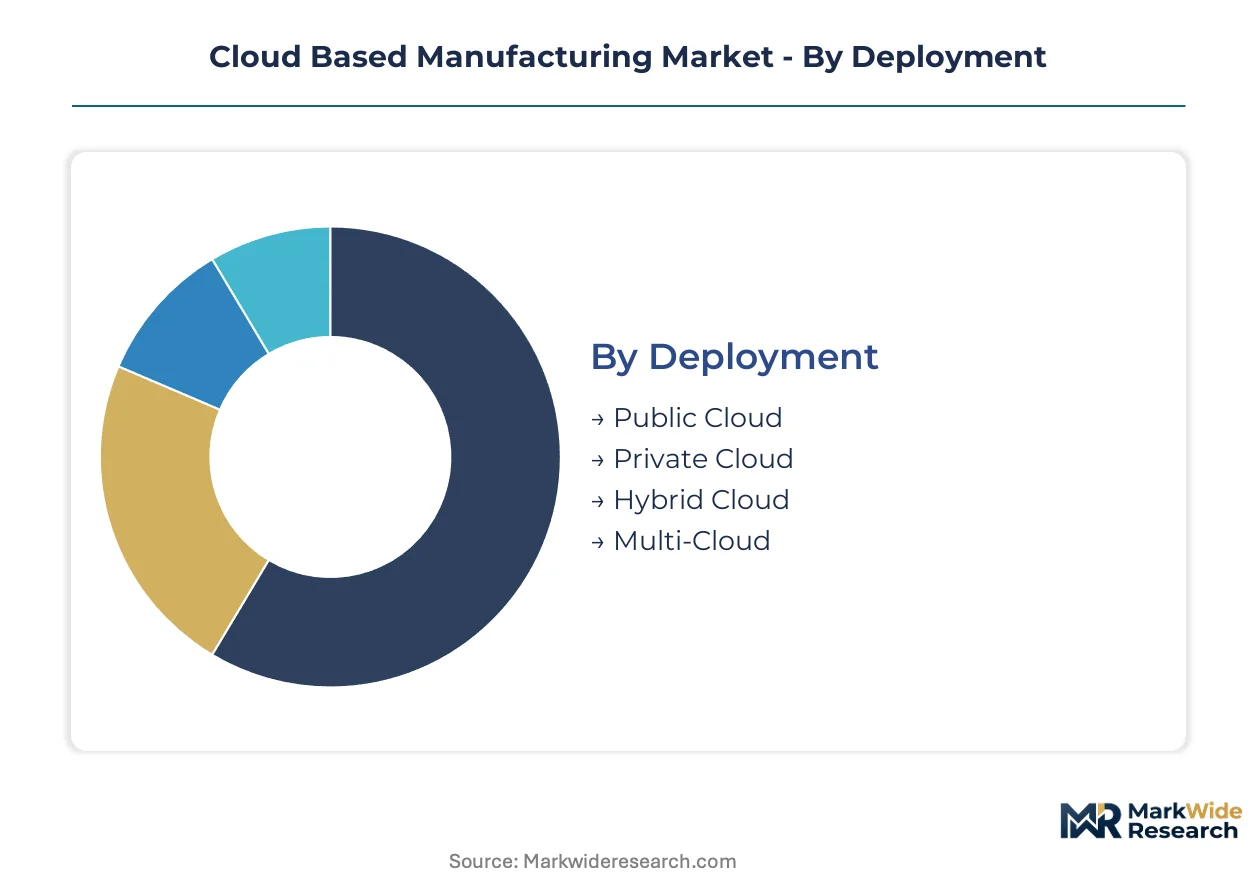
Cloud manufacturing platforms diverge sharply across deployment architectures, technology stacks, and buyer sophistication levels. Segmentation reveals where elastic compute investments concentrate versus where legacy on-premise entrenchment persists.
Deployment:
Customization demands intensify from fully managed public infrastructure through sovereign private nodes, with hybrid architectures occupying the contested middle ground.
- Hybrid Cloud:Manufacturers isolate sensitive process data on private nodes while bursting analytics workloads to public infrastructure. German automotive OEMs in Stuttgart and Wolfsburg drive this pattern for EV battery production synchronization across distributed supplier networks.
- Public Cloud:Multi-tenant architectures deliver elastic compute without capital overhead. Mexico's Baja California contract electronics manufacturers favor quarterly renegotiation cycles here to match order volatility clauses.
- Private Cloud:Single-tenant deployments satisfy data sovereignty requirements for pharmaceutical quality systems under FDA 21 CFR Part 11.
- Multi-Cloud:Workload distribution across competing hyperscalers reduces vendor lock-in for Tier-1 suppliers with complex global footprints.
Leading the category by volume: Public Cloud. Growing fastest: Hybrid Cloud.
Technology:
Functional maturity separates embedded analytics from emerging orchestration layers, with integration complexity rising alongside capability depth.
- IoT:Sensor telemetry conversion into predictive maintenance revenue anchors the highest-margin subscription tiers. Real-time machine control demands sub-100-millisecond latency specifications that strain standard DevOps competencies.
- AI:Explainable modules satisfy EU AI Act algorithmic transparency mandates for smart factory systems in Germany's Industrie 4.0 corridor.
- Machine Learning:Pattern recognition workloads optimize inventory positioning among automotive Tier-1 suppliers faster than legacy WMS displacement.
- Big Data:Physics-based simulation absorption from dedicated HPC clusters redirects capital expenditure toward cloud subscription commitments for powertrain virtual commissioning.
Dominant by revenue concentration: IoT-enabled platforms. Steepest expansion trajectory: AI compliance layers.
End User:
Buyer scale determines implementation complexity, from enterprise suite consolidation through mid-market multi-tenant penetration.
- OEMs:Vehicle manufacturers consolidate multi-site MES instances into single-tenant cloud architectures. Cloud-native production planning platforms synchronize production across supplier networks.
- Tier-1 Suppliers:Sub-$500M revenue discrete manufacturers remain underpenetrated relative to enterprise deployments, creating whitespace for multi-tenant architectures.
- Aftermarket Providers:Spare parts inventory optimization demands elasticity clauses matching demand volatility patterns.
- Distributors:Warehouse management functionality captures legacy investments through unbundled implementation service structures.
Primary volume anchor: OEMs. Fastest adoption velocity: Tier-1 Suppliers.
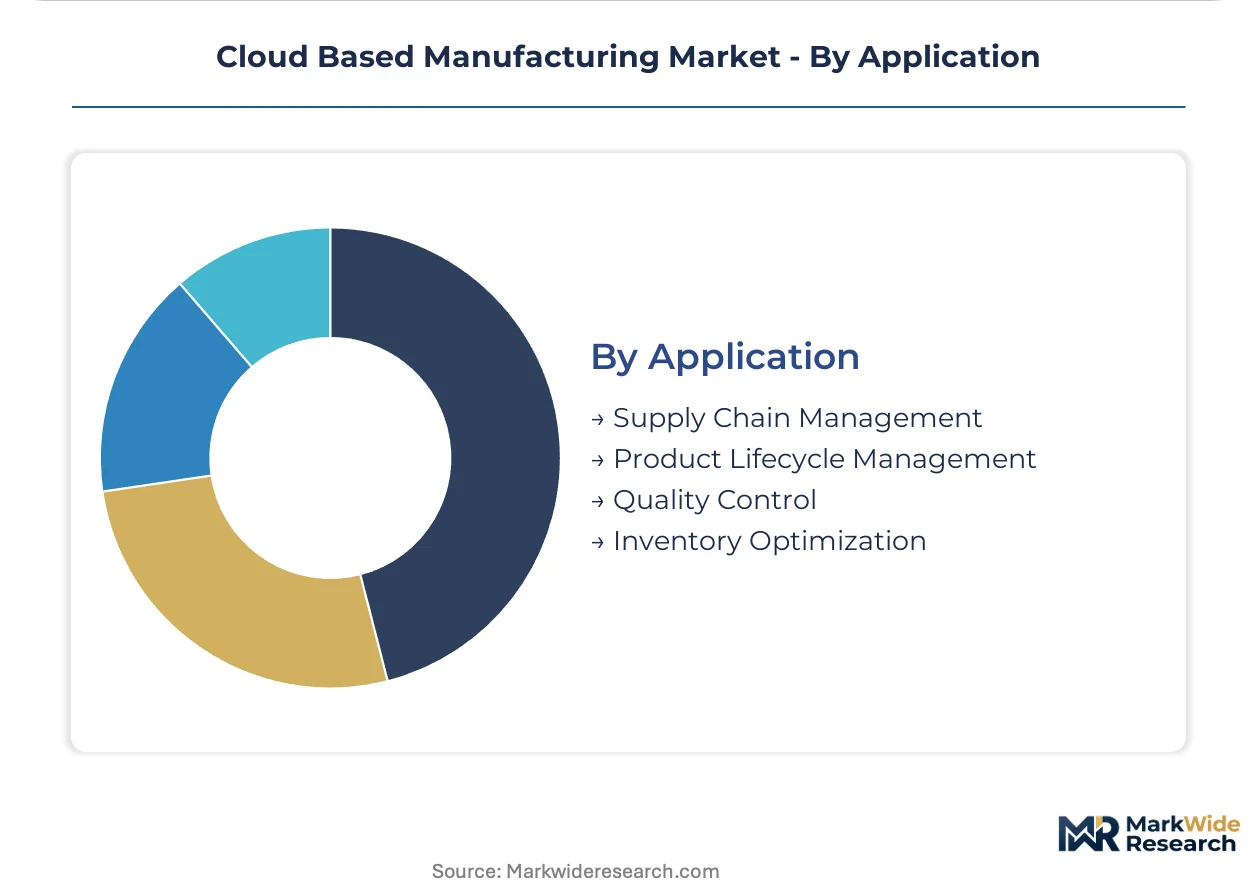
Application:
Functional maturity varies from established supply chain orchestration through emerging quality system compliance verticals.
- Supply Chain Management:The most mature functional area with established cloud migration patterns. Inventory optimization modules displace legacy WMS investments at the fastest clip among automotive suppliers.
- Quality Control:REACH chemical traceability requirements mandate blockchain-anchored substance declarations. Specialty chemical manufacturers in Germany's Ruhr industrial cluster face steep compliance ramps retrofitting legacy batch records.
- Product Lifecycle Management:Digital twin implementations absorb physics-based simulation workloads for virtual assembly line commissioning before physical installation.
- Inventory Optimization:Cloud WMS functionality captures legacy warehouse management investments among Tier-1 automotive suppliers with unbundled service pricing.
Maturity leader: Supply Chain Management. Gaining share fastest: Quality Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors cloud manufacturing adoption through German automotive OEMs consolidating multi-site MES instances into single-tenant architectures for EV battery synchronization.
United States
FDA 21 CFR Part 11 compliance drives pharmaceutical quality system deployments in New Jersey's pharma corridor. The regulation mandates electronic records and signatures for cloud-based manufacturing execution. Boston's biotech cluster absorbs predictive maintenance modules for continuous processing equipment.
Germany
EU AI Act algorithmic transparency requirements pull demand for explainable AI modules in Wolfsburg's automotive production networks. ECHA REACH chemical traceability mandates blockchain-anchored substance declarations for Ruhr industrial cluster specialty chemical manufacturers retrofitting legacy batch records.
China
GB standards for industrial data security and SAMR cloud service classifications force parallel certification pathways for foreign platform vendors. MIIT dual carbon goals accelerate energy-intensive sector migration to elastic compute in Yangtze River Delta manufacturing zones.
Japan
METI supply chain resilience initiatives promote cloud-native production planning for Nagoya's automotive component suppliers. JIS standards for industrial data interoperability create domestic certification requirements that fragment vendor deployment strategies in Kansai manufacturing belts.
Mexico
Nearshoring momentum concentrates contract electronics manufacturing in Baja California's assembly corridor serving North American OEMs. Quarterly renegotiation cycles replace annual contracts as manufacturers demand elasticity clauses matching order volatility patterns.
Cloud Based Manufacturing Market Vendor Landscape
Capital-heavy infrastructure providers compete with asset-light software specialists across deployment architectures, creating a tiered competitive structure. Consolidation pressures intensify as enterprise suites absorb mid-market capabilities through vertical functionality expansion. Three archetypes dominate: hyperscaler-integrated platforms, manufacturing-native specialists, and ERP incumbents with database-layer advantages. Competitive moves center on M&A for IoT telemetry capabilities and strategic partnerships for edge-to-cloud orchestration.
Within the ERP incumbent tier, SAP S/4HANA and Oracle Cloud ERP exemplify database-layer integration strategies, while Plex Systems occupies a position among manufacturing-native specialists with multi-tenant architectures. These three anchors demonstrate how competitive positioning splits between vertical depth and horizontal scale.
| Leading Market Players |
|---|
| Infor (Godlan) |
| Acumatica Cloud ERP |
| SAP S/4HANA |
| Rootstock Software |
| Plex Systems |
| Oracle Cloud ERP |
| IFS Cloud |
| Protolabs |
| Microsoft Dynamics 365 |
| Others |
Supply Flow & Price Mechanics
OT-IT convergence specialists concentrated in Germany's Industrie 4.0 manufacturing corridor command premium compensation that widens pricing-tier spreads between enterprise suites and mid-market multi-tenant deployments. Labor-cost differentials between Stuttgart's automotive engineering hubs and Mexico's Baja California assembly zones directly map to subscription pricing stratification across hybrid and public cloud architectures.
Pricing Analysis
Outcome-based pricing tied to production uptime percentages anchors enterprise subscription tiers for automotive OEMs synchronizing EV battery production. Three-tier pricing structure across premium compliance-certified, standard integration-ready, and economy self-service levels separates FDA 21 CFR Part 11 validated deployments from commodity ERP modules. Cost compression in mid-market discrete manufacturing intensifies as Plex Systems and Acumatica Cloud ERP compete on per-user rates. Tier-1 suppliers with sub-$500M revenue demonstrate highest price sensitivity, while pharmaceutical quality system buyers accept premium pricing for audit-ready compliance layers.
Supply Chain Analysis
Edge-to-cloud orchestration hardware rests on semiconductor fabrication concentrated in Taiwan, South Korea, and the United States, with specialized industrial IoT sensors drawing from German precision engineering and Japanese automation component producers. Containerized microservices architectures depend on hyperscaler compute infrastructure, open-source orchestration frameworks, and proprietary manufacturing vertical functionality. Single-source vulnerability in EU-certified AI explainability modules creates procurement risk for vendors serving Germany's automotive production networks. Distribution runs through direct enterprise sales forces for complex hybrid deployments and channel partners for standardized public cloud subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
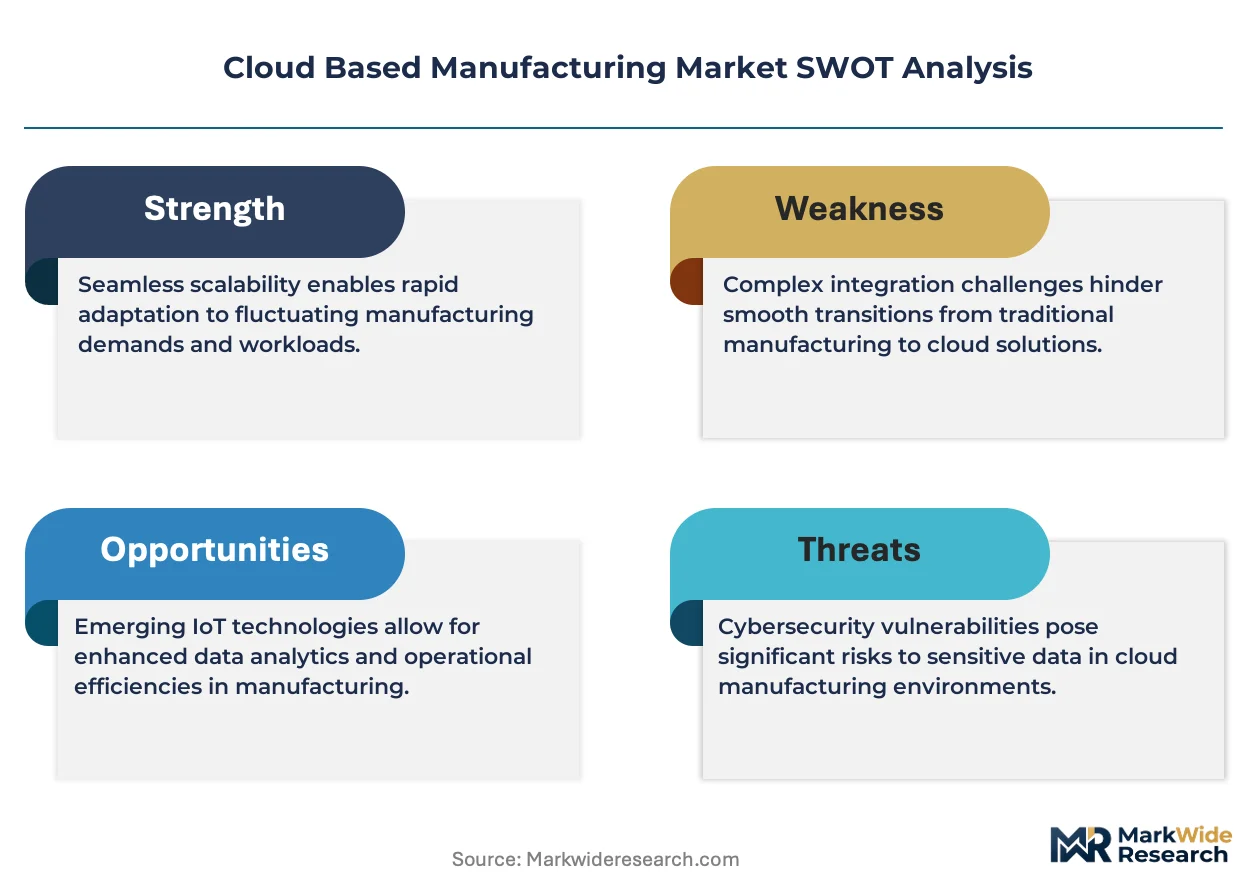
Cloud manufacturing platforms are replacing legacy on-premise MES installations through containerized microservices architectures that compress deployment timelines and elastic compute resources that absorb order volatility.
For Market Incumbents: Deepen database-layer integration with shop-floor IoT data streams to defend against Oracle Cloud ERP and SAP S/4HANA's manufacturing vertical functionality expansion. Incumbent vendors must accelerate FDA 21 CFR Part 11 certification investments to capture pharmaceutical quality system switching costs before mid-market specialists achieve compliance parity. Vertical integration into edge computing hardware reduces hyperscaler dependency and secures sub-100-millisecond latency specifications for real-time machine control tiers. For New Entrants and Emerging Players: Enter via multi-tenant architectures targeting sub-$500M revenue discrete manufacturers in Mexico's Baja California corridor and Germany's Ruhr industrial cluster, where legacy ERP sunk-cost entrenchment remains weakest. White-space concentration in inventory optimization modules for Tier-1 automotive suppliers offers faster penetration than saturated supply chain management applications. Go-to-market execution should emphasize quarterly renegotiation cycles and unbundled implementation services to match buyer procurement pattern shifts. For Investors and Strategic Acquirers: Re-rating potential sits with manufacturing-native specialists possessing IoT telemetry capabilities given EU AI Act algorithmic transparency mandates pulling demand for explainable AI modules. Long-term viability favors platforms with dual-certification pathways for China's GB standards and SAMR classifications alongside Western regulatory compliance. Acquisition target archetype: mid-market cloud ERP vendors with automotive vertical depth and existing edge-to-cloud orchestration partnerships. Watch FDA enforcement patterns on 21 CFR Part 11 cloud quality system audits as inflection indicator for pharmaceutical vertical pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Database-layer connectivity with shop-floor IoT data streams differentiates SAP S/4HANA from commodity ERP modules. |
| Acquisition of Specialist Firm | IoT telemetry capabilities from industrial sensor vendors anchor highest-margin predictive maintenance subscription tiers. |
| Strategic Partnership | Edge-to-cloud orchestration alliances with hyperscalers satisfy sub-100-millisecond latency for real-time machine control. |
| Geographic Expansion | Dual-certification investments for China's GB standards and SAMR classifications unlock Yangtze River Delta manufacturing zones. |
| Product Launch | Explainable AI modules satisfy EU AI Act mandates for Wolfsburg automotive production networks and Stuttgart OEMs. |
Methodological Framework
Independent corroboration across primary interviews with manufacturing engineers, cloud infrastructure architects, procurement officers at Tier-1 automotive suppliers, and regulatory compliance leads, combined with secondary validation through SEC filings of ERP vendors, hyperscaler capex disclosures, ECHA REACH substance databases, and FDA 21 CFR Part 11 guidance documents, underwrites the qualitative findings. Bottom-up triangulation aggregates deployment data across hybrid, public, private, and multi-cloud architectures, while top-down validation cross-checks against aggregate subscription revenue patterns reported by manufacturing-native specialists and ERP incumbents.
Rate-of-change decomposition separates volume expansion from pricing migration across the analysis window, modeling deployment architecture shifts, technology stack absorption, end-user scale transitions, and application functional maturity as independent dimensions. Segmentation dimensions include deployment model, technology layer, buyer revenue tier, and regulatory compliance vertical. CAGRs derive from elasticity-adjusted adoption curves weighted by order volatility patterns in contract electronics and automotive supplier networks. Forecast inputs incorporate EU AI Act implementation timelines and MIIT dual carbon goal acceleration in Chinese energy-intensive sectors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under data sovereignty fragmentation scenarios where China's GB standards and SAMR classifications diverge further from Western regulatory frameworks. Assumptions reflect sustained automotive OEM cloud-native migration momentum and REACH chemical traceability extension to blockchain-anchored declarations. A small set of named triggers warrants ongoing watch: FDA enforcement intensity on pharmaceutical cloud quality systems, EU AI Act penalty structures for non-compliant algorithmic transparency, and hyperscaler pricing volatility for compute-intensive physics-based simulation workloads.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Mobility in Energy Sector Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Context Rich Systems Market
Digital Solutions
Digital Pen Market
Digital Solutions
US Customer Communication Management (CCM) Market
Digital Solutions
US Digital Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Supply Side Platform (SSP) Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Online Home Service Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Global Intelligent Document Processing Market