
 Global Advanced Distribution Management System (ADMS) Market | 2026-2036
Global Advanced Distribution Management System (ADMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Distribution Management System (ADMS) Market Foresight
Utility engineering talent is rotating toward distributed energy resource integration competencies, constraining deployment timelines for smaller municipal operators. Siemens AG leverages its digital grid software portfolio to anchor European utility modernization programs. Hitachi Energy Ltd. sustains technology leadership in renewable integration modules through intensive R&D spending on real-time network optimization algorithms. Schneider Electric SE competes aggressively in hybrid deployment architectures across North American electric cooperatives.
An Advanced Distribution Management System constitutes an integrated software platform that unifies supervisory control and data acquisition, outage management, and distribution network analysis functions through real-time digital twin modeling of feeder topology and load flows. Its primary industrial purpose centers on enabling electric utilities to monitor, control, and optimize distribution grid operations while accommodating bidirectional power flows from distributed solar, battery storage, and electric vehicle charging infrastructure. Cloud-based deployment architectures represent the fastest-expanding segment as utilities abandon capital-intensive on-premises infrastructure for subscription-based operational expenditure models. Fault detection and outage management solution types command the deepest margin pools due to their direct linkage to regulatory reliability metrics and customer satisfaction benchmarks. Smart grid automation applications lead absolute demand volume as transmission operators modernize legacy supervisory systems.
FERC Order 2222 in the United States, the EU Green Deal framework, and Australia's CER grid reliability standards collectively reshape ADMS procurement specifications by mandating interoperability standards for distributed energy resource aggregation. The EPA's evolving power sector emissions guidelines further accelerate software refresh cycles as utilities model compliance pathways through dynamic load forecasting engines. Stakeholders must monitor evolving cybersecurity certification requirements from IEC and national regulators as attack surface expansion from cloud-connected grid infrastructure outpaces current utility security governance frameworks.
Market Dynamics
Cloud-native architectures are compressing deployment timelines as utilities abandon multi-year on-premises implementations for modular software-as-a-service stacks that scale with distributed energy resource penetration.
Growth Catalysts
- FERC Order 2222:This US mandate requires regional transmission organizations to enable distributed energy resource aggregation, forcing utilities to procure interoperable ADMS platforms for bidirectional grid management.
- EU Green Deal framework:Binding decarbonization targets across member states are accelerating software refresh cycles as distribution operators model dynamic load flows from proliferating solar and battery assets.
- Edge computing integration:Real-time processing at substation level reduces latency for fault detection algorithms, enabling faster outage response than centralized cloud architectures alone.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate advanced chip fabrication for grid hardware, creating vulnerability in IED and RTU procurement timelines.
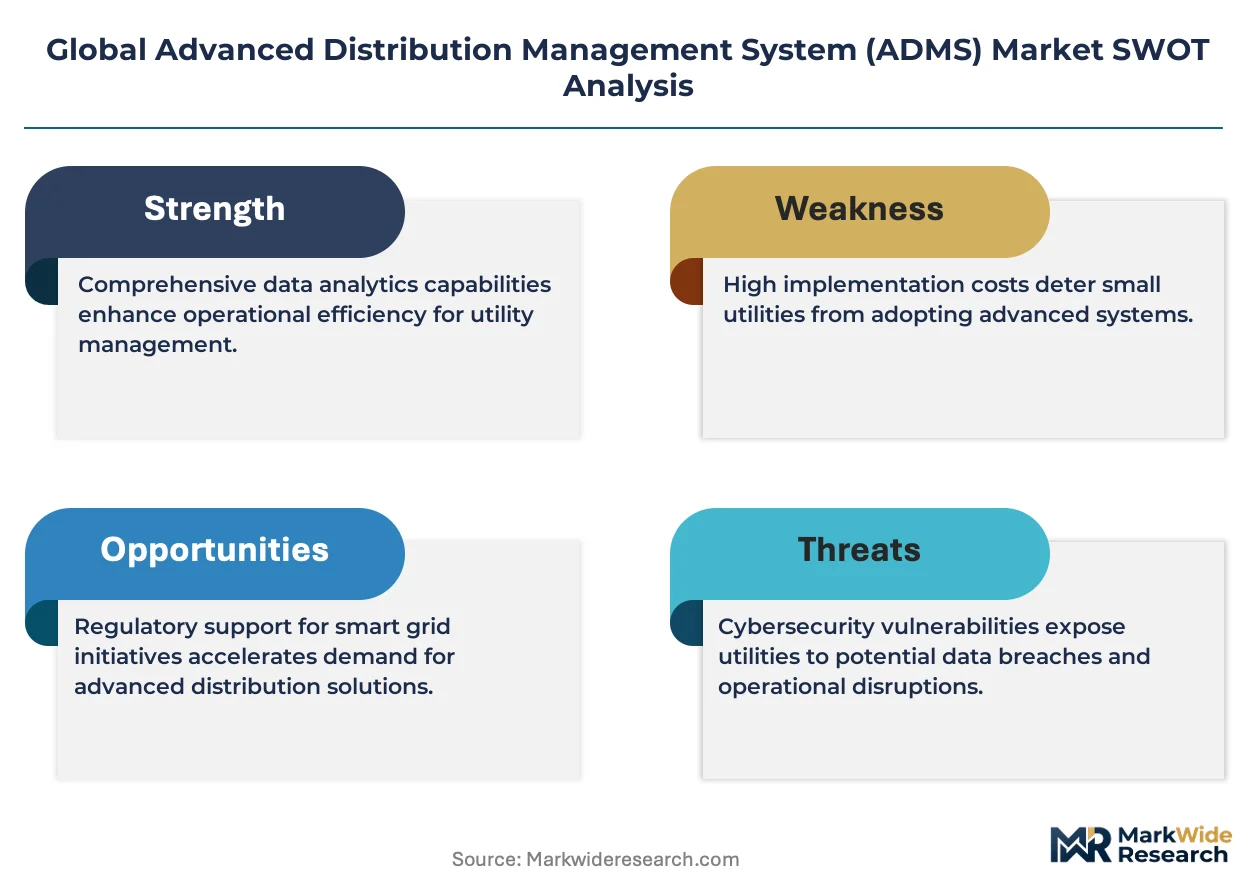
- Cybersecurity certification friction:IEC 62351 compliance timelines stretch 18-24 months, delaying go-live dates for cloud-connected deployments.
- Legacy SCADA substitution economics:Sunk costs in decade-old proprietary protocols deter municipal utilities from full-platform replacements despite functional obsolescence.
Strategic Opportunities
- India's rural electrification gaps:Microgrid operators in Bihar and Uttar Pradesh seek lightweight ADMS modules for decentralized village-level distribution control.
- Vehicle-to-grid convergence:Bidirectional charging protocols from ISO 15118 create new revenue streams for utilities managing EV fleet dispatch as mobile storage assets.
- Subscription pricing models:Operational expenditure structures reduce upfront capital barriers for electric cooperatives in Australia and Germany.
Industry Challenges
- Distribution engineering talent scarcity:Power systems expertise is migrating to DER integration roles, leaving legacy network analysis understaffed at smaller municipal utilities.
- Multi-vendor integration complexity:SCADA, OMS, and DMS modules from different suppliers require costly custom middleware for unified data models.
- Cybersecurity governance gaps:Utility security frameworks lag cloud attack surface expansion from API-connected grid infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Distribution Management System (ADMS) Market |
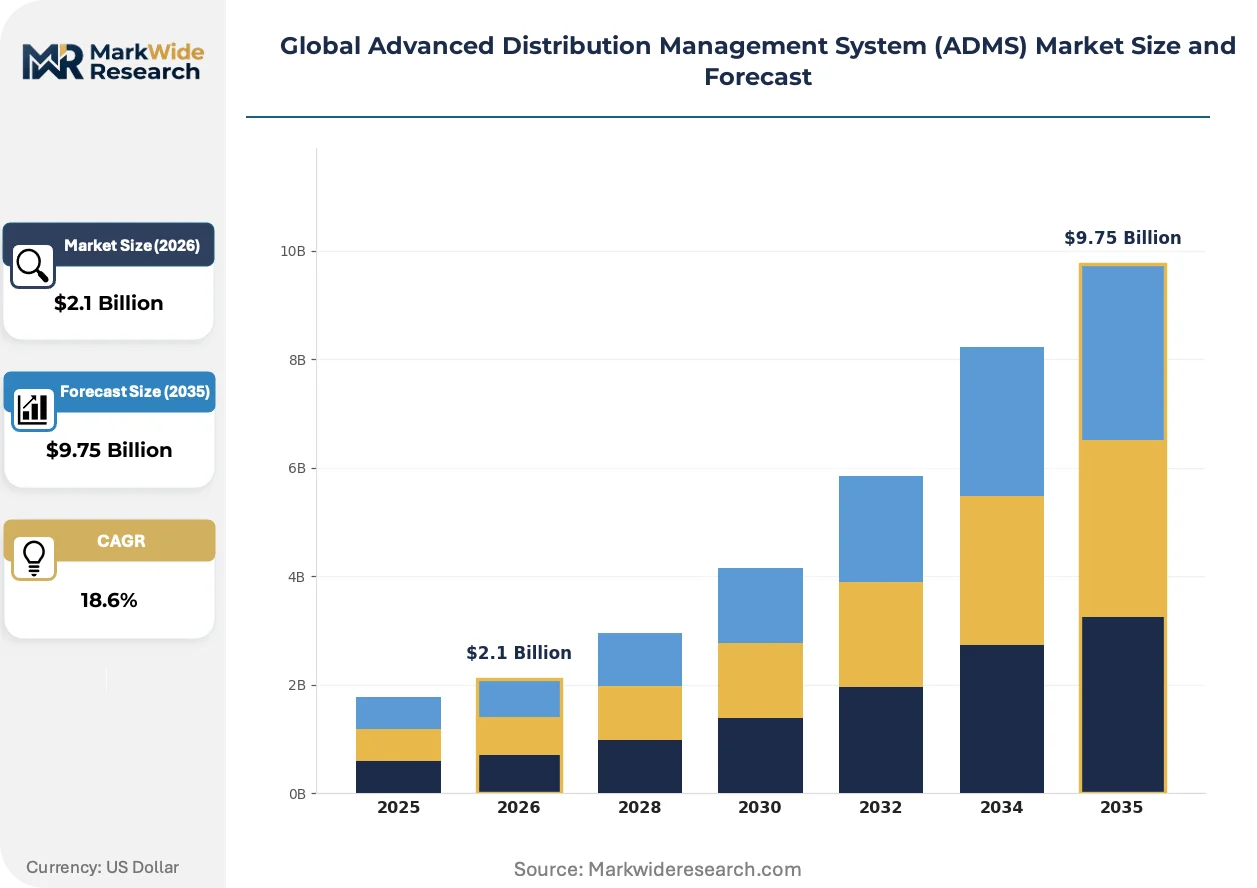
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.75 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution Type: Fault Detection, Volt/Var Optimization, Outage Management, Demand Response Management Application: Smart Grid Automation, Renewable Integration, Distribution Optimization, Load Forecasting End User: Electric Cooperatives, Municipal Utilities, Transmission Operators, Independent System Operators |
| Companies Covered | Eaton Corporation, Honeywell International Inc., Hitachi Energy Ltd., ETAP, Mitsubishi Electric Corporation, Siemens AG, GE Vernova, Oracle Utilities, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Distribution Management System (ADMS) Market Shifts & Advancements
Digital twin fidelity is advancing from static feeder models to real-time physics-based simulations that predict thermal loading and voltage instability before physical manifestation.
Containerized microservices architecture is miniaturizing ADMS deployment units. Electric cooperatives in the United States are adopting these modular stacks to replace monolithic legacy platforms incrementally. This fragmentation is compressing vendor lock-in and enabling best-of-breed component selection.
The EU AI Act's risk classification framework is reshaping algorithmic transparency requirements for automated switching decisions. European distribution system operators must now document training data provenance and decision logic for ML-based fault location. German utilities are responding by establishing internal AI governance boards ahead of enforcement deadlines.
Cooperative procurement consortia are displacing individual utility RFP processes. Aggregated buying pools across state borders in the United States are consolidating vendor negotiations and standardizing technical specifications. This concentration is most visible among rural electric cooperatives in the Midwest and Southeast seeking cloud outage management capabilities.
Global Advanced Distribution Management System (ADMS) Market Segmentation
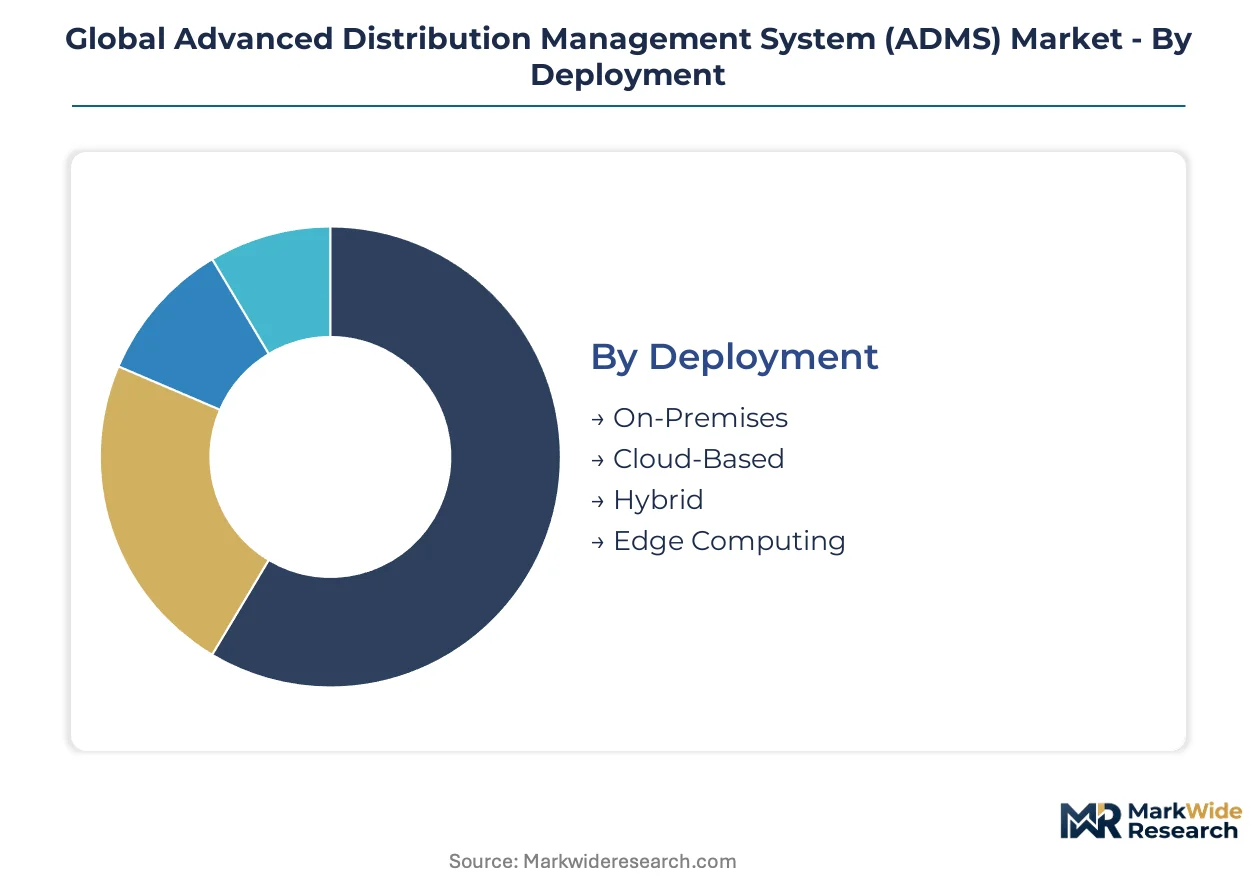
ADMS procurement patterns diverge sharply across deployment architectures and utility ownership structures. Segment-specific requirements from FERC Order 2222 compliance to rural electrification mandates in India reshape vendor product roadmaps and pricing strategies.
Deployment:
Cloud-based architectures dominate procurement in Germany and Australia where utilities prioritize operational expenditure flexibility, while on-premises systems retain preference among US municipal utilities with legacy cybersecurity governance frameworks.
- On-Premises:Capital-intensive infrastructure requiring dedicated server farms and localized data centers. US municipal utilities in California and Texas sustain demand despite longer deployment timelines, constrained by stringent state-level cybersecurity audit requirements and sunk costs in decade-old SCADA integrations.
- Cloud-Based:Subscription software-as-a-service models with API-connected grid infrastructure. Australian utilities in Victoria and New South Wales accelerate procurement to achieve scalable outage management without capital-heavy hardware refresh cycles, though IEC 62351 compliance stretches implementation timelines.
- Hybrid:Mixed architecture combining on-premises critical control with cloud analytics layers. European transmission operators deploy these configurations to satisfy GDPR data residency mandates while accessing machine learning-based load forecasting engines.
- Edge Computing:Real-time processing at substation level reducing latency for fault detection algorithms. German distribution system operators in Bavaria pilot these deployments to enable millisecond-scale switching decisions for distributed solar integration.
On-Premises holds the largest share; momentum sits with Cloud-Based.
Solution Type:
Margin pools concentrate in modules directly linked to regulatory reliability metrics, with outage management commanding premium pricing due to customer satisfaction benchmarking requirements.
- Fault Detection:Algorithmic identification of feeder anomalies through real-time digital twin modeling. US electric cooperatives in the Midwest prioritize these investments to reduce SAIDI metrics and avoid regulatory penalty structures tied to interruption frequency.
- Volt/Var Optimization:Reactive power management for voltage stability across distributed generation nodes. Indian utilities in Maharashtra and Gujarat deploy lightweight versions for rural microgrid stabilization where centralized control infrastructure remains uneconomical.
- Outage Management:Integrated crew dispatch and customer communication platforms. Australian CER grid reliability standards mandate these capabilities for metropolitan distribution operators, creating concentrated demand in Sydney and Melbourne.
- Demand Response Management:Automated load curtailment and price signal transmission to commercial consumers. German utilities leverage these modules to manage bidirectional flows from rooftop solar clusters under EU Green Deal flexibility requirements.
Outage Management generates the deepest margins; Fault Detection is climbing the fastest.
Application:
Volume leadership sits with smart grid automation as transmission operators modernize legacy supervisory systems, while renewable integration accelerates most quickly under decarbonization mandates.
- Smart Grid Automation:Unified SCADA-DMS-OMS platforms replacing siloed legacy architectures. US transmission operators in PJM and ERCOT territories drive replacement cycles as FERC Order 2222 interoperability deadlines approach.
- Renewable Integration:Dynamic hosting capacity analysis and inverter-based resource dispatch. Spanish distribution system operators under EU Green Deal binding targets model these capabilities for Iberian solar penetration scenarios.
- Distribution Optimization:Network reconfiguration and loss minimization algorithms. Japanese utilities in Tokyo and Osaka deploy these for aging infrastructure efficiency gains under METI carbon neutrality roadmaps.
- Load Forecasting:Machine learning engines predicting demand patterns from EV charging and heat pump electrification. UK distribution network operators utilize these for winter peak management under Ofgem price control frameworks.
Smart Grid Automation leads absolute volume; Renewable Integration shows steepest expansion trajectory.
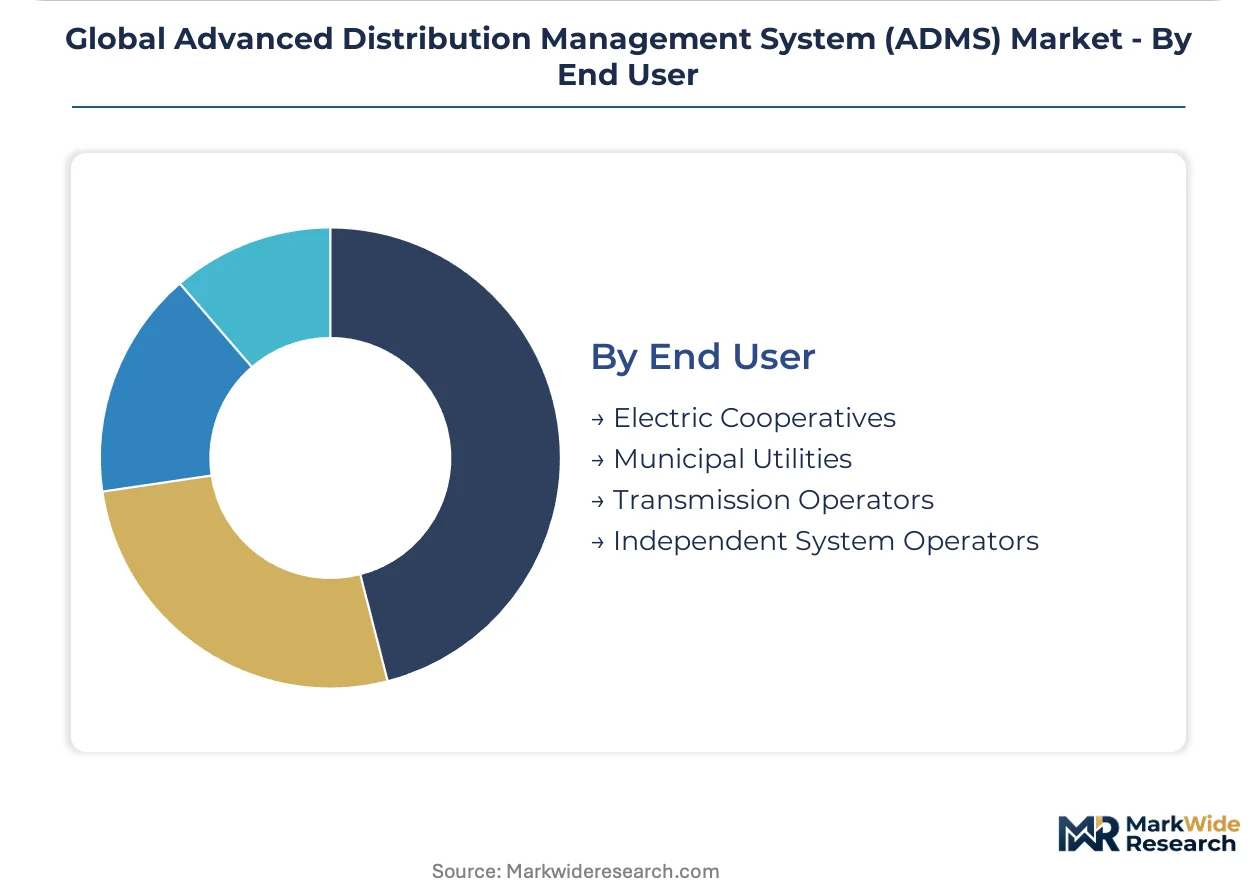
End User:
Procurement authority fragments across ownership structures, with electric cooperatives aggregating through multi-state consortia to overcome individual scale disadvantages.
- Electric Cooperatives:Member-owned utilities serving rural territories. Midwest and Southeast US cooperatives form aggregated buying pools spanning Iowa, Nebraska, and Georgia to standardize cloud outage management specifications and compress vendor negotiations.
- Municipal Utilities:City-owned distribution operators with localized governance. German Stadtwerke in Munich and Hamburg pursue hybrid deployments balancing EU AI Act algorithmic transparency requirements with operational autonomy preferences.
- Transmission Operators:Regional grid coordinators managing bulk power flows. Australian AEMO and US ISOs procure ADMS modules for distributed energy resource aggregation visibility under FERC Order 2222 and CER standards.
- Independent System Operators:Non-profit grid coordinators ensuring wholesale market reliability. Texas ERCOT and California CAISO drive interoperability specification development for bidirectional resource participation protocols.
Electric Cooperatives represent the fastest-expanding customer category; Transmission Operators retain the largest procurement budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ADMS deployment patterns diverge sharply by geography, with United States utilities prioritizing DER aggregation compliance while German operators emphasize AI governance and Australian networks favor cloud-native outage scalability.
United States
Electric cooperatives across Iowa and Nebraska aggregate procurement through multi-state consortia to overcome scale disadvantages in cloud outage management adoption. FERC Order 2222 mandates interoperability standards for distributed energy resource participation, compressing procurement timelines for regional transmission organizations. ERCOT in Texas and CAISO in California anchor interoperability specification development for bidirectional resource protocols.
Germany
Distribution system operators in Bavaria pilot edge computing deployments to enable millisecond-scale switching decisions for distributed solar integration. The EU AI Act's risk classification framework forces algorithmic transparency documentation for automated switching decisions ahead of enforcement deadlines. Stadtwerke in Munich and Hamburg pursue hybrid architectures balancing GDPR data residency with machine learning access.
Australia
Utilities in Victoria and New South Wales accelerate cloud-based procurement to achieve scalable outage management without capital-heavy hardware refresh cycles. The CER grid reliability standards mandate integrated crew dispatch capabilities for metropolitan distribution operators. Sydney and Melbourne distribution networks concentrate demand response management investments under these regulatory benchmarks.
India
Microgrid operators in Bihar and Uttar Pradesh seek lightweight ADMS modules for decentralized village-level distribution control where centralized infrastructure remains uneconomical. The CEA rural electrification mandates create procurement specifications for scalable outage management in low-density territories. Maharashtra and Gujarat utilities deploy volt/var optimization for rural microgrid stabilization.
Japan
Utilities in Tokyo and Osaka deploy distribution optimization algorithms for aging infrastructure efficiency gains under METI carbon neutrality roadmaps. The country's national energy regulator accelerates software refresh cycles through binding decarbonization compliance pathways. Kansai and Chubu regional operators model dynamic load flows from proliferating rooftop solar clusters.
Global Advanced Distribution Management System (ADMS) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-platform vendors controlling interoperability specification development while modular specialists capture niche DER integration segments. The vendor base organizes around three strategic archetypes: integrated industrial conglomerates with digital grid portfolios, pure-play software vendors with cloud-native architectures, and hardware-originated suppliers extending into analytics layers. Dominant competitive moves include strategic partnerships between software vendors and transmission operators for FERC Order 2222 compliance, plus portfolio diversification into edge computing modules for substation-level deployment.
Among integrated industrial conglomerates, Siemens AG and Hitachi Energy Ltd. exemplify the full-platform archetype with anchored positions in European and Asia-Pacific utility modernization programs respectively. Schneider Electric SE occupies a hybrid-deployment specialization, particularly visible across North American electric cooperative procurement. These three companies represent distinct geographic anchoring strategies—German engineering depth, Japanese R&D intensity, and French multi-regional execution—while converging on cloud-edge hybrid architectures as the dominant competitive vector.
| Leading Market Players |
|---|
| Eaton Corporation |
| Honeywell International Inc. |
| Hitachi Energy Ltd. |
| ETAP |
| Mitsubishi Electric Corporation |
| Siemens AG |
| GE Vernova |
| Oracle Utilities |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month IEC 62351 certification timelines compress vendor pricing power while amplifying buyer leverage in cloud-connected deployments across Australian and German utilities. This lead-time band concentrates procurement authority with transmission operators who can absorb extended validation cycles, forcing modular specialists to accept deferred revenue recognition and subscription-heavy contract structures.
Pricing Analysis
Long-term offtake agreements dominate cloud-native ADMS procurement, with Australian utilities in Victoria and New South Wales locking in five-year SaaS subscriptions to avoid capital-heavy hardware refresh cycles. Pricing stratifies across premium, standard, and economy tiers based on DER aggregation capacity limits and FERC Order 2222 interoperability certification levels. Cost compression in the economy tier intensifies because municipal utilities with sunk SCADA investments demand steep discounts for incremental module adoption. Electric cooperatives in the US Midwest exhibit the highest price sensitivity, while German Stadtwerke in Munich and Hamburg demonstrate lowest sensitivity due to EU AI Act compliance budgets.
Supply Chain Analysis
Taiwan and South Korea semiconductor fabrication chokepoints constrain IED and RTU procurement timelines for edge computing deployments in German Bavarian substations. Advanced chip supply draws from concentrated foundry capacity, with grid hardware sourcing anchored in Japanese precision components and Chinese enclosure manufacturing. Single-source vulnerability in 7nm and 5nm process nodes threatens millisecond-scale switching decision hardware for distributed solar integration. Distribution runs through transmission operator specification consortia and electric cooperative buying pools rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent ADMS vendors face substitution pressure from cloud-native software specialists offering containerized microservices that fragment historically monolithic platform markets. This threat demands defensive repositioning around interoperability specification control and edge computing module integration.
For Market Incumbents: Fortify FERC Order 2222 specification leadership by embedding proprietary protocols into regional transmission organization procurement templates. Deepen backward integration into substation-level edge hardware to capture latency-critical switching decisions currently ceded to semiconductor vendors. Defend against modular specialists by bundling outage management with DER aggregation visibility under unified data models. For New Entrants and Emerging Players: Anchor in India's rural electrification gaps where lightweight ADMS modules for Bihar and Uttar Pradesh microgrids escape incumbent platform economics. Target cooperative procurement consortia across US Midwest and Southeast electric utilities with standardized cloud outage management specifications. Pursue ISO 15118 vehicle-to-grid protocol integration as a wedge capability absent from legacy SCADA-DMS architectures. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance infrastructure play because FERC Order 2222, EU Green Deal binding targets, and Australia's CER standards create irreversible software refresh cycles. Acquisition candidates with IEC 62351 pre-certification and edge computing pilot deployments in Germany or Australia command structural scarcity premiums. Monitor DER penetration rates exceeding distribution hosting capacity thresholds as the signal indicating accelerated ADMS replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Module Development | Millisecond-scale switching decisions in German Bavarian substations capture DER integration premiums. |
| Cloud-Native Platform Migration | Subscription models reduce capital barriers for Australian Victoria and New South Wales utilities. |
| FERC Order 2222 Interoperability Certification | Pre-certified platforms lock in US transmission operator procurement specifications ahead of deadlines. |
| AI Governance Board Establishment | German Stadtwerke compliance with EU AI Act transparency requirements defends algorithmic switching revenue. |
| Cooperative Procurement Consortium Participation | Aggregated buying pools across Iowa and Nebraska compress vendor negotiation leverage for incumbents. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, ADMS platform engineers, grid operators, and electric cooperative procurement managers; and secondary validation through FERC filings, EIA power sector data, IEA grid modernization reports, and project development databases tracking DER aggregation deployments. Bottom-up utility procurement tracking triangulated against top-down transmission operator capital expenditure disclosures to anchor market sizing.
Across the projection horizon, the analytical framework modeled deployment architecture, solution type, application, and end-user ownership structure dimensions. CAGRs derived from utility procurement pipeline analysis weighted by regulatory deadline proximity, with FERC Order 2222 compliance timelines and EU Green Deal binding targets serving as demand acceleration inputs. Edge computing penetration rates and cloud-native adoption curves informed technology transition assumptions.
Material uncertainties — semiconductor supply concentration disruptions, IEC 62351 certification timeline extensions, and cybersecurity governance framework evolution — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and utility capital allocation priorities. Revision becomes warranted when DER penetration rates exceed distribution hosting capacity thresholds in PJM or ERCOT territories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
China Digital Twin Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Digital Certificates Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
IT Service Management Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Data Analytics in the Smart Home Market