
 North America API Management Market | 2026-2036
North America API Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America API Management Market Insights
Containerized microservices architecture is realigning how enterprises deploy API gateways and developer portals. Google leverages its Kubernetes heritage to dominate cloud-native API orchestration for North American enterprises. Microsoft sustains competitive pressure through deep Azure integration and enterprise distribution channels. IBM anchors its position with hybrid cloud API management tailored to regulated industries.
API management encompasses the lifecycle governance of application programming interfaces, including design, security, traffic control, and analytics through centralized platforms that enforce rate limiting, authentication protocols, and version control. Cloud-based deployment leads segment expansion as enterprises migrate from on-premises infrastructure, while security solutions command premium pricing due to zero-trust architecture mandates. Healthcare end users represent the fastest-growing adoption vertical as HIPAA-compliant data exchange requirements intensify.
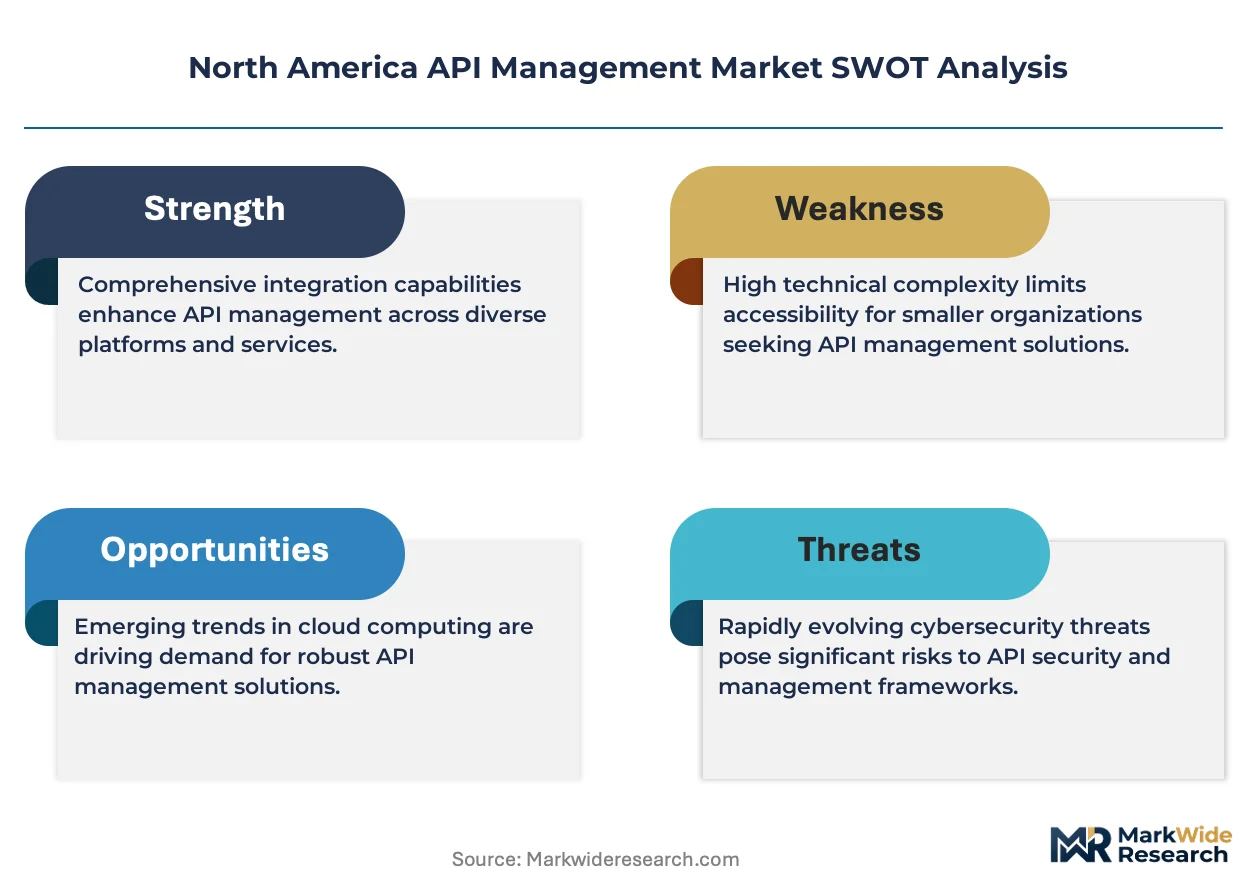
The US Securities and Exchange Commission, the Consumer Financial Protection Bureau, and Canada's Office of the Superintendent of Financial Institutions shape compliance obligations for financial APIs through open banking and consumer data privacy frameworks. The Federal Trade Commission's evolving data broker rules and state-level privacy statutes in California and New York create fragmented regulatory terrain that elevates demand for governance-ready platforms. Stakeholders must monitor how artificial intelligence inference APIs trigger novel liability and disclosure obligations across federal and provincial jurisdictions.
Market Dynamics
Containerized microservices deployment is forcing enterprises to rearchitect legacy API infrastructure around Kubernetes-orchestrated service meshes, compressing procurement cycles for cloud-native gateway solutions.
Growth Catalysts
- Open banking mandates:The US Consumer Financial Protection Bureau's Section 1033 rule and Canada's Consumer-Driven Banking Framework compel financial institutions to expose transactional APIs, creating immediate governance demand.
- Healthcare data exchange:HIPAA-compliant interoperability requirements under the 21st Century Cures Act accelerate API adoption for clinical data sharing between hospital systems and payers.
- Silicon Valley cluster effects:California's concentration of SaaS vendors and fintech incubators generates dense API ecosystem development, pulling adjacent enterprise demand.
Market Restraints
- Specialized talent scarcity:Shortage of platform engineers with Kubernetes and service mesh expertise inflates implementation timelines and consulting costs.
- Cloud concentration risk:Hyperscaler dominance in North American cloud infrastructure creates vendor lock-in exposure for API gateway deployments.
- State privacy fragmentation:Divergent data broker rules across California, New York, and Texas multiply compliance engineering overhead for multi-state API operators.
Strategic Opportunities
- AI inference API governance:The FTC's emerging algorithmic accountability guidance creates white space for platforms managing machine learning model endpoints and audit trails.
- Mid-market financial services:Regional banks and credit unions outside major tech hubs remain underpenetrated for full-lifecycle API management suites.
- Edge API orchestration:Convergence of 5G network slicing and distributed cloud architectures enables low-latency gateway deployment for industrial IoT use cases.
Industry Challenges
- Legacy system integration:Mainframe and monolithic application environments in established enterprises resist seamless API abstraction, extending migration timelines.
- Zero-trust architecture complexity:Continuous verification requirements across microservices architectures strain security engineering capacity and certificate management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America API Management Market |
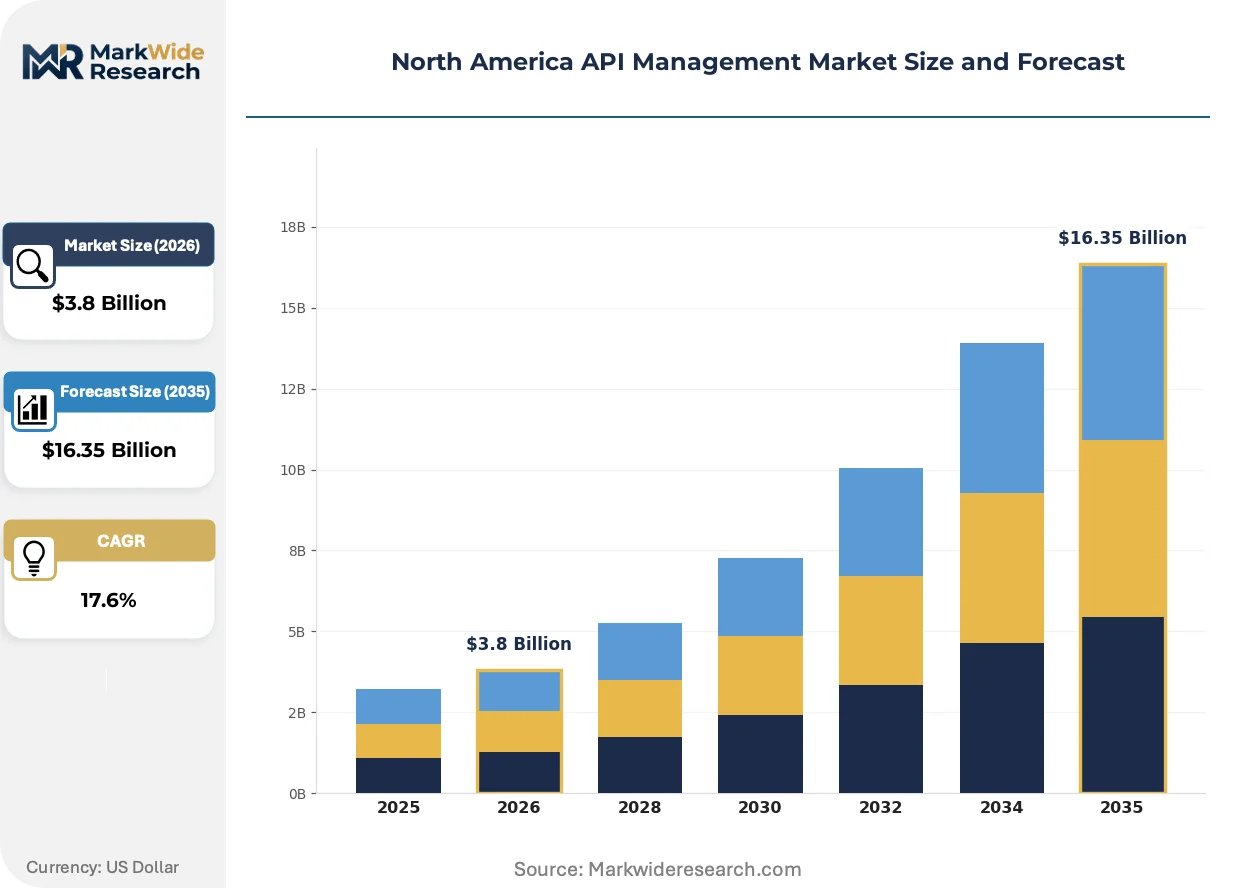
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Retail, Healthcare, Financial Services, Telecommunications Service Type: Consulting, Integration, Support, Training Solution: Management, Security, Analytics, Monetization |
| Companies Covered | Google, Microsoft, IBM, Amazon Web Services, MuleSoft, Broadcom, Akamai Technologies, Oracle, Software AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America API Management Market Trends and Innovations
API management platforms are absorbing adjacent security and analytics functions, blurring traditional category boundaries as buyers consolidate vendor relationships.
GraphQL query languages are expanding into enterprise API portfolios, enabling precise data fetching that reduces payload overhead for mobile and IoT clients. Retail and logistics operators in Texas and Illinois are piloting GraphQL federation across distributed microservices. This consolidation is compressing standalone API analytics vendor margins as functionality migrates into integrated suites.
The SEC's cybersecurity disclosure rules now mandate incident reporting for material API breaches, elevating governance platforms to board-level procurement priorities. Financial services compliance teams are embedding automated policy enforcement into CI/CD pipelines to satisfy audit requirements. Asset managers and broker-dealers in New York are reallocating budget from perimeter security toward API-centric zero-trust implementations.
Developer portal self-service models are displacing traditional ticket-based API provisioning, compressing time-to-production from weeks to hours. Healthcare technology vendors in Massachusetts and Minnesota are prioritizing platforms with embedded sandbox environments and interactive documentation. This behavioral shift favors vendors with native developer experience tooling over pure infrastructure plays.
North America API Management Market Segmentation
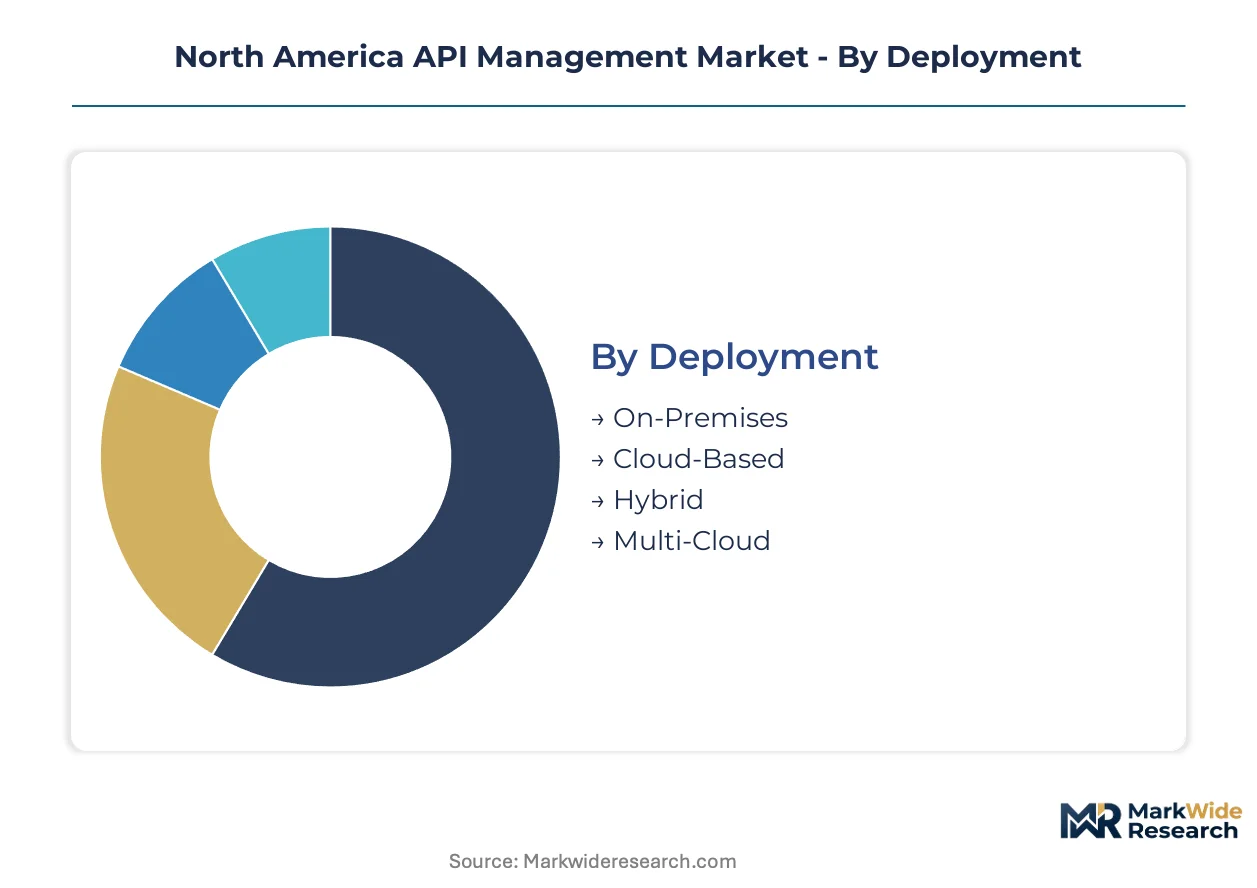
API management procurement patterns diverge sharply across deployment architectures and regulatory exposure levels. Financial institutions and healthcare systems impose distinct compliance burdens that reshape segment prioritization and vendor selection criteria across North American markets.
Deployment:
FedRAMP authorization and HIPAA Business Associate Agreements determine which deployment modes qualify for federal and healthcare contracts. SOC 2 Type II certification separates enterprise-grade from mid-market offerings.
- On-Premises:Hardware-resident gateway infrastructure deployed within client data centers. Demand concentrates among defense contractors and federal agencies in Virginia and Maryland corridors where air-gapped requirements persist. The Department of Defense's CMMC 2.0 mandates sustain this segment despite cloud migration pressure.
- Cloud-Based:Fully managed SaaS delivery through hyperscaler marketplaces. Texas energy trading platforms and California SaaS vendors drive consumption where elastic scaling outweighs sovereignty concerns. The FTC's data broker oversight rules create compliance engineering demand for audit-log retention capabilities.
- Hybrid:Split architecture with sensitive workloads on-premises and public-facing APIs in cloud environments. Regional banks across the Midwest deploy this model to satisfy state banking commissioners while enabling digital channel expansion.
- Multi-Cloud:Gateway federation across AWS, Azure, and GCP to prevent vendor lock-in. Fintech clusters in New York and Toronto prioritize this architecture for disaster recovery and rate negotiation leverage.
Leading the category by volume: Cloud-Based. Growing fastest: Multi-Cloud.
End User:
Vertical-specific data governance frameworks fragment procurement requirements across regulated industries. Customer acquisition costs and implementation complexity vary substantially by sector maturity.
- Retail:Omnichannel commerce platforms and marketplace operators. California and Illinois distribution centers deploy edge-optimized gateways for inventory API latency reduction. PCI-DSS Level 1 certification gates access to tier-one merchant processing volumes.
- Healthcare:Hospital systems, payers, and health information exchanges. The 21st Century Cures Act's information blocking provisions compel API adoption for clinical data portability. Massachusetts and Minnesota health technology corridors generate concentrated demand for HIPAA-compliant sandbox environments.
- Financial Services:Banks, credit unions, asset managers, and insurance carriers. The CFPB's Section 1033 rule and Canada's Consumer-Driven Banking Framework mandate transactional data sharing APIs. New York's broker-dealer density and Toronto's fintech incubation sustain premium pricing for governance-ready platforms.
- Telecommunications:5G network operators and communications platform providers. Edge computing initiatives in Texas and Arizona drive low-latency API orchestration for network slicing applications.
Healthcare claims the steepest expansion trajectory. Financial Services retains the largest revenue concentration.
Service Type:
Professional services intensity correlates with legacy system complexity and internal platform engineering maturity. Procurement patterns split between retained consulting relationships and project-based implementation.
- Consulting:Architecture assessment and governance framework design. Federal contractors and Fortune 500 enterprises in Chicago and Atlanta sustain demand for API strategy roadmapping.
- Integration:Legacy system abstraction and microservices migration. Mainframe-dependent insurance carriers in Hartford and Hartford-equivalent markets require extended engagement timelines.
- Support:24/7 operational assistance and incident response. Mid-market SaaS vendors in Denver and Salt Lake City prioritize this service tier over internal platform engineering hires.
- Training:Developer certification and platform administration education. Kubernetes and service mesh skill scarcity elevates corporate training contract values.
Integration commands the highest per-engagement value. Support generates the most recurring revenue.
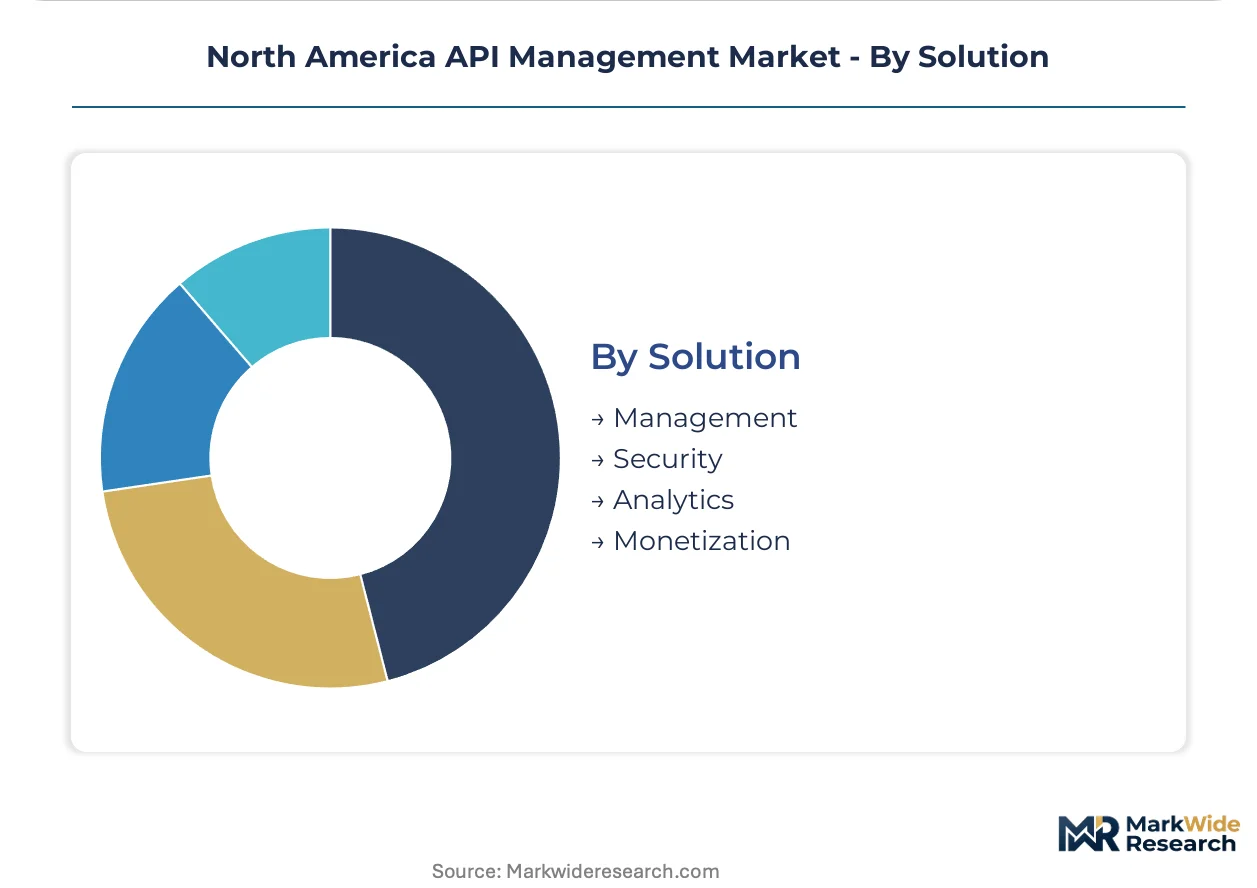
Solution:
Functional bundling decisions reflect buyer consolidation preferences and security engineering capacity. Standalone point solutions face margin compression as integrated suites absorb adjacent capabilities.
- Management:Gateway provisioning, lifecycle governance, and developer portal administration. Core platform functionality embedded in virtually every deployment.
- Security:Authentication, authorization, threat detection, and encryption. Zero-trust architecture mandates elevate this solution to board-level procurement priority. The SEC's cybersecurity disclosure rules now require material API breach reporting.
- Analytics:Traffic monitoring, consumption metering, and business intelligence dashboards. Revenue leakage detection for monetized APIs drives adoption among platform economy operators.
- Monetization:Billing, rate plan configuration, and partner revenue sharing. API product managers in fintech and logistics verticals deploy these tools for external developer ecosystem economics.
Security solutions command premium pricing. Analytics is gaining share fastest as buyers consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for API management concentrates in coastal technology corridors where financial services density and cloud infrastructure investment overlap. The United States dominates regional procurement volume, though Canada and Mexico present distinct regulatory and sectoral opportunities. Sub-regional variation reflects industry clustering patterns and compliance environment fragmentation.
United States
Financial institutions in New York and fintech incubators in California drive enterprise gateway procurement. The SEC's cybersecurity disclosure rules and CFPB Section 1033 mandate transactional API governance for broker-dealers and retail banks. Silicon Valley SaaS vendors and Manhattan asset managers sustain premium pricing for zero-trust architectures.
Canada
Toronto's fintech corridor and Vancouver cloud infrastructure hubs anchor national demand. The Office of the Superintendent of Financial Institutions and Consumer-Driven Banking Framework compel open banking API exposure. Ontario credit unions and British Columbia health information exchanges prioritize hybrid deployment for data sovereignty.
Mexico
Mexico City financial services and Monterrey manufacturing clusters generate emerging API adoption. The central bank's fintech licensing regime and open finance regulations reshape compliance obligations for digital lenders. Guadalajara technology parks attract nearshore SaaS development requiring gateway federation.
North America API Management Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscaler cloud platforms and enterprise software incumbents dividing the North American market. Google, Microsoft, and Amazon Web Services leverage infrastructure scale to capture cloud-native workloads, while IBM and Oracle retain regulated industry accounts through hybrid deployment expertise. Three strategic archetypes dominate: hyperscaler-integrated suites, legacy enterprise extenders, and API-native specialists. Competitive intensity centers on Kubernetes-orchestrated service mesh capabilities and FedRAMP authorization attainment.
Within the hyperscaler tier, Google exemplifies cloud-native API orchestration through Kubernetes heritage, while Microsoft anchors enterprise distribution through Azure integration. IBM occupies a distinct position serving hybrid cloud requirements for financial services and healthcare compliance. These three entities represent the structural fault lines of competitive positioning: infrastructure-native velocity versus enterprise relationship depth versus regulated industry specialization.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Amazon Web Services |
| MuleSoft |
| Broadcom |
| Akamai Technologies |
| Oracle |
| Software AG |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FedRAMP-authorized suites and mid-market SaaS offerings manifests in both subscription pricing and cloud infrastructure sourcing strategies. Premium tiers command threefold rate differentials over economy deployments while hyperscaler concentration in US West and East Coast regions shapes procurement geography.
Pricing Analysis
Volume concentration in cloud-native SaaS tiers compresses margins while security-heavy hybrid deployments sustain premium realization. Pricing stratifies across enterprise governance suites, mid-market integrated platforms, and developer-centric point solutions based on FedRAMP authorization and HIPAA Business Associate Agreement status. Cost compression in economy tiers intensifies as Kubernetes expertise commoditizes, though zero-trust architecture mandates prop security module premiums. Regional banks and credit unions exhibit acute price sensitivity; defense contractors and Manhattan asset managers demonstrate inelastic demand for air-gapped configurations.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler infrastructure concentration across AWS, Azure, and GCP for cloud-based gateway delivery. Component dependencies span Kubernetes distributions, service mesh fabrics, and hardware security modules sourced from US, Taiwan, and Israel manufacturing bases. Tariff exposure on semiconductor-based encryption accelerators elevates supply risk for on-premises appliance vendors. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with systems integrators handling hybrid deployment complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering talent scarcity props pricing power for vendors with embedded Kubernetes and service mesh expertise, creating durable margin pools amid cloud infrastructure commoditization.
For Market Incumbents: Lock in hybrid cloud positioning through CMMC 2.0 and FedRAMP authorization investments that federal contractors and defense agencies mandate. Deepen upstream control over service mesh and certificate management components to offset hyperscaler gateway commoditization. Prioritize developer portal self-service capabilities as ticket-based provisioning loses share to sandbox-native competitors. For New Entrants and Emerging Players: Hyperscaler marketplace routes offer lowest-friction customer acquisition for API-native specialists targeting mid-market SaaS vendors in Denver and Salt Lake City. Regional banks across the Midwest present underpenetrated demand for governance-ready platforms with state banking commissioner pre-certification. Lead with AI inference API governance capabilities as FTC algorithmic accountability guidance creates compliance white space. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid-deployment specialists given CFPB Section 1033 and Canadian Consumer-Driven Banking Framework implementation timelines. Long-term viability favors vendors with FedRAMP authorization and healthcare HIPAA BAA infrastructure spanning federal and clinical data exchange use cases. Monitor Kubernetes certification completion rates among platform engineering talent as inflection signal for implementation capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Unlocks federal agency procurement pipelines in Virginia and Maryland corridors. |
| Service Mesh Integration | Captures Kubernetes-orchestrated microservices demand from Silicon Valley SaaS vendors. |
| Developer Portal Self-Service | Compresses time-to-production for Massachusetts and Minnesota health technology vendors. |
| AI Inference API Governance | Addresses FTC emerging algorithmic accountability guidance for machine learning endpoints. |
| Multi-Cloud Gateway Federation | Prevents vendor lock-in for New York and Toronto fintech disaster recovery requirements. |
Research Methodology
Document review covered hyperscaler capex disclosures, SEC cybersecurity filings, and federal procurement databases, complemented by interviews with platform engineering directors, API product managers, and healthcare IT compliance officers. Secondary validation drew from CFPB rulemaking dockets, CMMC 2.0 implementation guidance, and Canadian OSFI open banking frameworks. Bottom-up deployment volume estimates triangulated against top-down enterprise software spending analysis.
Cross-referencing historical adoption curves against panel input from CTOs and cloud architects shaped the analytical framework across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user vertical, solution functional bundle, and regional regulatory cluster. CAGR derivation incorporated open banking mandate implementation timelines, HIPAA Cures Act compliance deadlines, and 5G network slicing deployment schedules as industry-specific forecast inputs.
The model holds under steady regulatory enforcement and hyperscaler infrastructure investment continuity; deviation in federal procurement freezes or state privacy law fragmentation would shift trajectory. Forecasts reflect assumptions about talent supply elasticity and certification pipeline throughput. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Australia System Integration Market
Digital Solutions
Database Management Platform Market
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Equipment Tracking Software Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Electrical Digital Twins Market
Digital Solutions
Service Lifecycle Management Application Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Global Website Builders Market
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Europe ICT Market
Digital Solutions
Express Digitizer Market