
 Inventory Management Market | 2026-2036
Inventory Management Market Size, Share, and Industry Trends Forecast 2026-2036
Inventory Management Market Outlook
Enterprise-grade cloud-native architecture is redrawing competitive boundaries in inventory technology. SAP SE leverages deep ERP integration to anchor large manufacturer deployments across Europe. Oracle Corporation sustains dominance in database-driven inventory analytics for wholesale distribution networks. Manhattan Associates specializes in warehouse-centric optimization, competing aggressively with point solutions in North American retail logistics.
Inventory management encompasses the systematic oversight of stock levels, order fulfillment, and supply chain synchronization through software platforms that process real-time SKU data, demand signals, and replenishment algorithms. Cloud-based deployment leads structural momentum as retailers and e-commerce businesses prioritize elastic scalability over fixed on-premise infrastructure; software solutions capture the deepest margin pools while automated systems represent the fastest expansion vector among product categories. Hybrid solutions retain relevance in regulated manufacturing environments where data residency requirements constrain full cloud migration.
FDA traceability mandates for pharmaceutical supply chains and EU GDPR data-localization standards shape platform architecture decisions across healthcare and retail verticals. India's BIS certification requirements for IoT-enabled tracking hardware create compliance gates for barcoding systems entering that market. Stakeholders must weigh regulatory fragmentation against the operational efficiency gains of unified global inventory platforms.
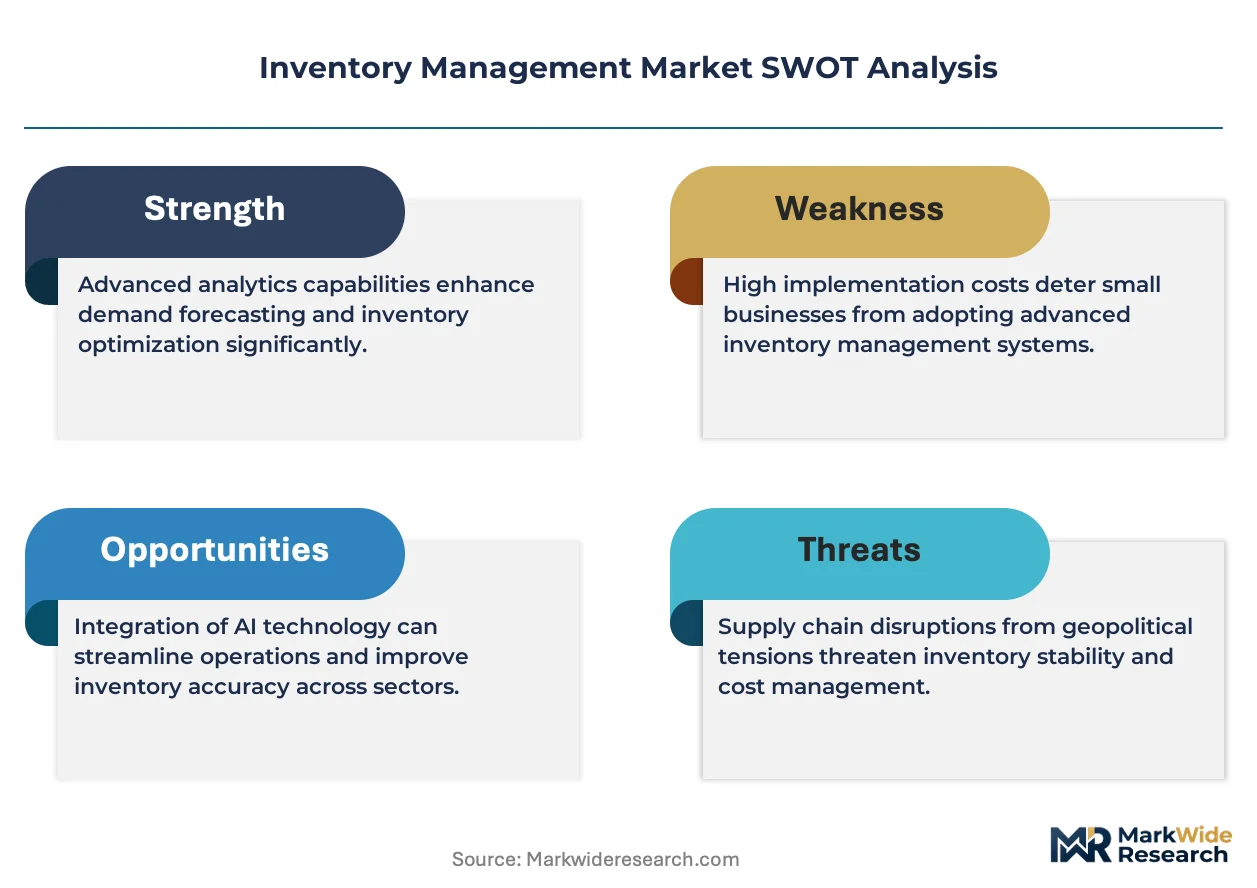
Market Dynamics
Cloud-native architecture is compressing deployment timelines for inventory platforms while fragmenting vendor competitive boundaries. Real-time SKU synchronization across omnichannel touchpoints now determines fulfillment economics, forcing legacy ERP-dependent operators into costly middleware investments.
Growth Catalysts
- EU AI Act:Automated demand-forecasting algorithms face new compliance requirements that favor established platform providers with audit-ready architectures, accelerating consolidation among European retailers.
- India's PLI scheme:Manufacturing corridor beneficiaries building localized supply chain visibility are mandating IoT-enabled tracking infrastructure, creating concentrated procurement windows for hardware-software bundles.
- Elastic cloud scalability:E-commerce peak-load volatility drives retailers toward consumption-based pricing models that align technology spend with transaction volume rather than fixed capacity.
Market Restraints
- Data residency mandates:EU GDPR localization standards and India's BIS certification requirements for IoT hardware fragment platform architectures, raising compliance engineering costs for unified global deployments.
- Semiconductor supply concentration:RFID and sensor module production concentrates in East Asian foundries, exposing hardware-dependent tracking systems to input volatility and extended lead times.
- Legacy system entrenchment:Pharmaceutical manufacturers bound to FDA-validated on-premise environments face technical debt barriers that slow cloud migration despite operational pressure.
Strategic Opportunities
- Brazilian retail modernization:ANVISA pharmaceutical traceability mandates and wholesale distribution digitization create entry points for cloud-native platforms in Latin America's largest consumer market.
- Edge-AI convergence:Warehouse robotics and computer vision for real-time inventory counting are merging, opening bundled solution architectures that capture automation budgets.
- Saudi Vision 2030 logistics hubs:SFDA pharmaceutical serialization requirements and bonded zone infrastructure investments concentrate demand for temperature-controlled tracking systems in Gulf distribution corridors.
Industry Challenges
- Cloud-to-legacy integration complexity:Hybrid deployments require specialized middleware talent scarce in manufacturing regions outside established technology clusters, inflating implementation timelines.
- Multi-jurisdiction certification sequencing:FDA, EMA, and CDSCO validation protocols for pharmaceutical inventory systems often conflict, forcing redundant documentation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inventory Management Market |
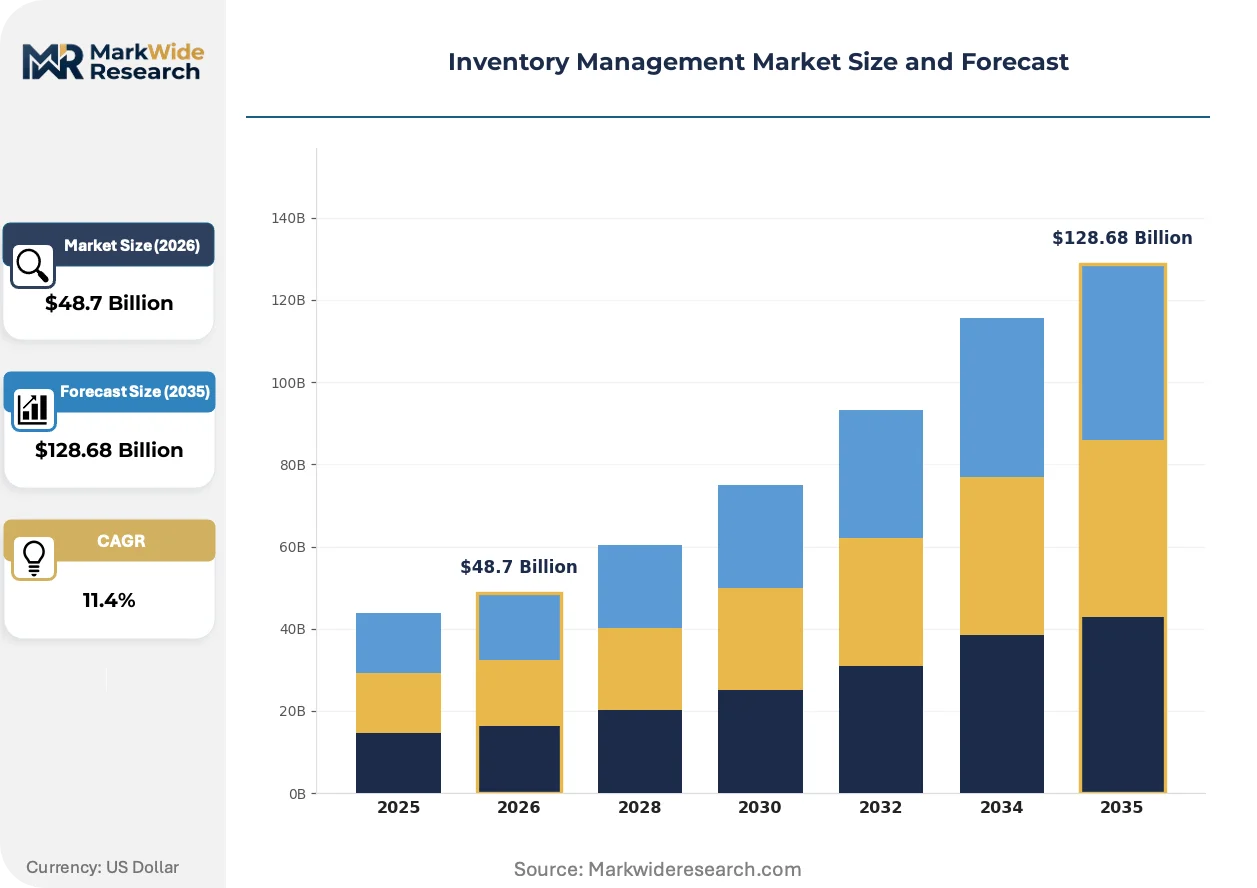
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Automated Systems, Inventory Tracking Tools, Barcoding Systems Service Type: Consulting Services, Implementation Services, Maintenance Services, Support Services Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Mobile Platforms End User: Retailers, Manufacturers, Wholesalers, E-Commerce Businesses |
| Companies Covered | SAP SE, Oracle Corporation, Microsoft Corporation, IBM Corporation, Manhattan Associates, Zoho Corporation, Fishbowl Inventory, Intuit Inc., Infor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inventory Management Market Strategic Shifts
Artificial intelligence is embedding into inventory decision layers faster than organizational readiness can absorb, compressing the window for competitive differentiation through algorithmic sophistication alone.
Computer vision systems for automated stock counting are displacing handheld barcode scanners in high-velocity fulfillment centers. Third-party logistics operators in North American retail corridors are deploying camera-based verification at receiving docks, eliminating manual reconciliation delays. This displacement is compressing labor cost structures while raising capital intensity for facility retrofits.
The EU AI Act's risk-classification framework for automated forecasting tools is forcing algorithmic transparency disclosures from European wholesale distributors. High-risk inventory prediction systems now require human-in-the-loop validation, adding operational friction that favors simpler heuristic models in medium-complexity environments. German automotive parts distributors are restructuring procurement workflows to accommodate these intervention requirements.
Subscription-based platform licensing is replacing perpetual software purchases among mid-market retailers. Buyers in India's tier-two manufacturing cities prefer operational expenditure models that preserve working capital for inventory holding rather than technology ownership. This preference shift is pressuring incumbent vendors to restructure revenue recognition and customer success functions.
Inventory Management Market Segmentation
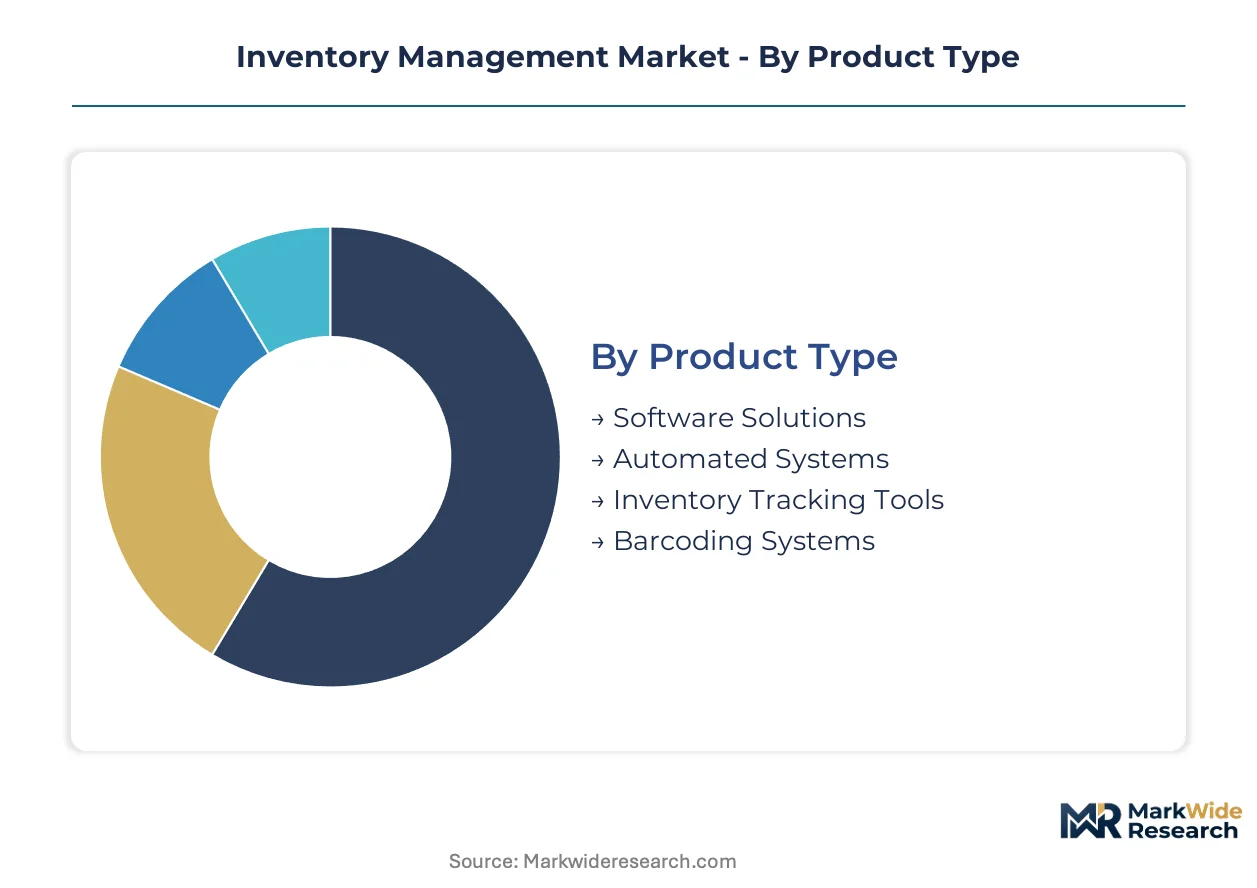
Inventory management platforms fragment across technology layers and consumption models that determine vendor margin structures and customer switching costs. Deployment architecture and end-use verticals drive the deepest competitive moats, while service attach rates separate platform economics from pure software licensing.
Product Type:
Software solutions flow through direct enterprise sales and cloud marketplaces, while automated systems and tracking hardware move via systems integrators and industrial distributors.
- Software Solutions:Cloud-native platforms with embedded AI forecasting modules process real-time SKU data across omnichannel touchpoints. Retailers in India's tier-two manufacturing cities favor subscription pricing that preserves working capital for inventory holding rather than technology ownership.
- Automated Systems:Warehouse robotics, automated storage and retrieval systems, and conveyor networks integrate with WMS platforms through standardized APIs. North American third-party logistics operators deploy these at receiving docks to eliminate manual reconciliation delays, compressing labor cost structures while raising facility retrofit capital intensity.
- Inventory Tracking Tools:RFID readers, IoT sensors, and GPS-enabled asset tags provide location visibility across distributed supply chains. India's BIS certification requirements for IoT-enabled hardware create compliance gates for equipment entering that market.
- Barcoding Systems:Handheld scanners, label printers, and mobile data collection terminals remain entrenched in pharmaceutical manufacturing where FDA validation protocols constrain rapid technology refresh cycles.
Software solutions dominate installed base. Automated systems are where expansion concentrates.
Service Type:
Service margins concentrate in implementation and ongoing support, with cost tiers separating enterprise transformation programs from mid-market quick deployments.
- Consulting Services:Supply chain network design, demand forecasting model selection, and inventory policy optimization delivered by specialized practices. German automotive parts distributors restructure procurement workflows to accommodate EU AI Act human-in-the-loop validation requirements, driving specialized consulting demand.
- Implementation Services:System configuration, data migration, and integration with legacy ERP environments. Hybrid deployments require middleware talent scarce in manufacturing regions outside established technology clusters, inflating timelines and day rates.
- Maintenance Services:Preventive hardware servicing, software patch management, and uptime guarantees for automated warehouse equipment.
- Support Services:Help desk operations, user training programs, and incident resolution for cloud platform subscribers.
Implementation services capture the highest per-customer revenue. Support services scale most efficiently across expanding cloud subscriber bases.
Deployment:
Deployment mode determines customer acquisition economics and platform architecture constraints, with hybrid configurations commanding premium pricing for complexity management.
- On-Premise:Perpetual-licensed software running on customer-managed infrastructure with direct database access. Pharmaceutical manufacturers bound to FDA-validated environments face technical debt barriers that slow migration despite operational pressure for cloud elasticity.
- Cloud-Based:Multi-tenant SaaS platforms with consumption-based pricing aligned to transaction volume rather than fixed capacity. E-commerce peak-load volatility drives retailers toward this model across North American omnichannel fulfillment networks.
- Hybrid Solutions:Split architectures with sensitive planning data on-premise and elastic compute in public cloud. EU GDPR data-localization standards and India's data residency mandates fragment platform architectures, raising compliance engineering costs for unified global deployments.
- Mobile Platforms:Native applications and progressive web apps for warehouse floor operations and field inventory counts.
Cloud-based deployment is climbing the fastest. Hybrid solutions retain relevance in regulated manufacturing verticals where data sovereignty requirements constrain full migration.
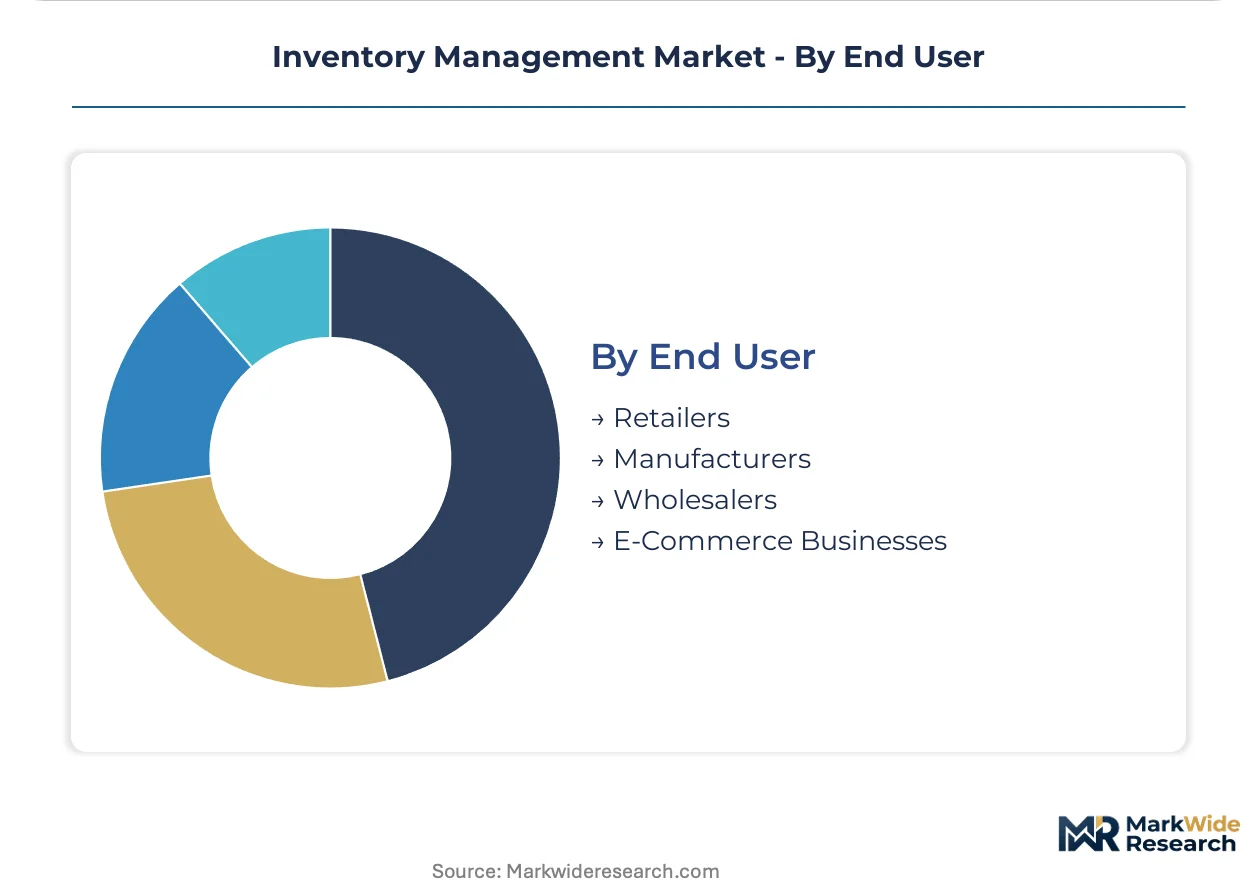
End User:
End-use concentration shapes feature roadmaps, with retailer demand for real-time synchronization pulling platform development ahead of manufacturing-centric lot-traceability requirements.
- Retailers:Department stores, specialty chains, and grocery operators managing omnichannel inventory visibility across storefronts, dark stores, and fulfillment centers. Real-time SKU synchronization now determines fulfillment economics, forcing legacy ERP-dependent operators into costly middleware investments.
- Manufacturers:Discrete and process industries managing raw material, work-in-process, and finished goods visibility. India's PLI scheme beneficiaries building localized supply chain visibility mandate IoT-enabled tracking infrastructure, creating concentrated procurement windows.
- Wholesalers:Distribution intermediaries managing cross-dock operations and vendor-managed inventory programs for downstream retail accounts.
- E-Commerce Businesses:Direct-to-consumer operators and marketplace sellers with high-velocity, long-tail SKU portfolios requiring algorithmic replenishment.
Retailers anchor current platform revenue. Manufacturers represent the steepest expansion trajectory as industrial digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure concentrates in the United States and Germany, while manufacturing demand clusters in India and China. Regulatory divergence across FDA, EMA, and BIS jurisdictions fragments platform architectures. Tier-two cities in emerging economies now outpace metro adoption for IoT-enabled tracking systems.
United States
E-commerce peak-load volatility drives retailers toward consumption-based pricing models. FDA traceability mandates for pharmaceutical supply chains constrain rapid cloud migration despite operational pressure. Third-party logistics operators in the Chicago-Memphis corridor deploy computer vision systems at receiving docks to eliminate manual reconciliation delays.
Germany
Automotive parts distributors restructure procurement workflows to accommodate EU AI Act human-in-the-loop validation requirements. EMA pharmaceutical serialization standards intersect with GDPR data-localization rules, raising compliance engineering costs. The Stuttgart-Munich industrial belt concentrates demand for warehouse-centric optimization platforms with embedded forecasting modules.
India
PLI scheme beneficiaries building localized supply chain visibility mandate IoT-enabled tracking infrastructure, creating concentrated procurement windows. BIS certification requirements for IoT hardware create compliance gates for equipment entering the market. Manufacturing corridors in Gujarat and Tamil Nadu outpace metro adoption for subscription-based platform licensing among tier-two cities.
China
Dual carbon goals accelerate warehouse robotics deployment to compress labor cost structures and energy intensity. NMPA pharmaceutical traceability mandates shape platform architecture decisions for domestic and export-oriented manufacturers. The Yangtze River Delta anchors demand for automated storage and retrieval systems integrated with WMS platforms through standardized APIs.
Brazil
ANVISA pharmaceutical traceability mandates and wholesale distribution digitization create entry points for cloud-native platforms. Retail modernization programs in São Paulo and Rio de Janeiro pull real-time SKU synchronization investments. The Southeast industrial corridor concentrates procurement for temperature-controlled tracking systems serving domestic pharmaceutical distribution networks.
Inventory Management Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the inventory management ecosystem. The vendor base separates into three tiers: deep ERP-integrated platforms commanding enterprise manufacturing accounts, cloud-native specialists capturing mid-market retail velocity, and point solutions defending warehouse-centric niches. Dominant competitive moves include M&A to absorb middleware capabilities and strategic partnerships to bridge cloud-to-legacy integration gaps.
Within the ERP-integrated tier, SAP SE and Oracle Corporation anchor large manufacturer deployments across European and North American markets. Manhattan Associates occupies a position in warehouse-centric optimization, competing aggressively with point solutions in retail logistics corridors. Zoho Corporation exemplifies the subscription-based model gaining traction among India's tier-two manufacturing cities, where operational expenditure preferences preserve working capital for inventory holding.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| IBM Corporation |
| Manhattan Associates |
| Zoho Corporation |
| Fishbowl Inventory |
| Intuit Inc. |
| Infor |
| Others |
Value Chain & Pricing Dynamics
RFID tag substitution for barcode infrastructure is redrawing procurement economics across inventory platforms, compressing hardware margins in East Asian foundries while elevating software attach rates for North American integrators.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for automated forecasting modules, separating audit-ready enterprise platforms from heuristic-based mid-market alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FDA-validated pharmaceutical deployments commanding substantial premiums over retail SaaS tiers. Cost compression in cloud-native subscription models is intensifying because consumption-based pricing aligns vendor revenue directly with transaction volatility. Tier-two manufacturing cities in India exhibit the sharpest price sensitivity, while German automotive distributors prioritize compliance-grade forecasting over cost minimization.
Supply Chain Analysis
Strategic stockpile preferences dominate semiconductor-dependent hardware procurement, with inventory management vendors buffering RFID reader and sensor module inventories against East Asian foundry lead-time volatility. Component sourcing draws heavily from Taiwan, South Korea, and China for sensor modules and processing chips. Raw material dependencies span rare earth elements for magnetics, silicon wafers for chip fabrication, and lithium compounds for battery-powered mobile terminals. Single-source vulnerability in advanced RFID chip fabrication exposes hardware vendors to input cost spikes. Distribution runs through systems integrators and industrial distributors for automated systems, while cloud software flows direct or through hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in inventory management hinge on API interoperability standards that determine whether point solutions capture automation budgets or ERP-integrated suites absorb middleware spend.
For Market Incumbents: Compound defensive positioning through backward integration into IoT sensor hardware and captive cloud infrastructure. Acquire middleware specialists in manufacturing corridors outside established technology clusters to neutralize integration-timeline advantages held by cloud-native entrants. The EU AI Act's audit requirements favor established providers with compliance-ready architectures.
For New Entrants and Emerging Players: Cloud-to-legacy integration services represent the most penetrable white-space, as pharmaceutical manufacturers bound to FDA-validated environments face technical debt barriers that slow pure-cloud migration. Target tier-two manufacturing cities in India's Gujarat and Tamil Nadu corridors with subscription-based platforms that preserve working capital for inventory holding. Lead with implementation partnerships rather than direct platform sales.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed warehouse robotics specialists lacking SaaS revenue streams and cloud-native inventory platforms with narrow vertical focus. Five-to-ten-year viability favors vendors with embedded AI forecasting and cross-vertical regulatory certification. Watch for inflection when ANVISA pharmaceutical traceability mandates in Brazil concentrate procurement for temperature-controlled tracking systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API standardization with SAP and Oracle ERP systems anchors enterprise manufacturing accounts in Stuttgart-Munich belt. |
| Acquisition of Specialist Firm | Middleware capabilities from systems integrators compress cloud-to-legacy deployment timelines for FDA-validated environments. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure accelerate consumption-based pricing adoption among North American retailers. |
| Geographic Expansion | Localized supply chain visibility platforms capture PLI scheme procurement windows in India's manufacturing corridors. |
| Product Launch | Edge-AI warehouse robotics bundled with computer vision displace handheld scanners in Chicago-Memphis logistics corridor. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with supply chain executives, warehouse operations directors, and pharmaceutical compliance officers; and secondary validation through SEC 10-K filings, EU regulatory submissions, and hyperscaler capex disclosures. Bottom-up triangulation across deployment model, organization size, vertical, and regional adoption pattern intersected with top-down market sizing. Conversations with third-party logistics operators and systems integrators in North American retail corridors provided ground-truth on computer vision deployment timelines.
Across the projection horizon, value outputs reflect segmented modeling across software solutions, automated systems, tracking hardware, and barcoding equipment, with further granularity by cloud, on-premise, hybrid, and mobile deployment architectures. CAGRs derive from elasticity-adjusted adoption curves and regulatory mandate sequencing. Forecast inputs incorporate EU AI Act compliance timelines, India's BIS certification throughput, and FDA pharmaceutical traceability phase-in schedules.
Forecasts assume regulatory continuity in EU AI Act implementation, FDA traceability mandates, and India's PLI scheme extensions; material policy shifts would require re-modeling adoption velocity and vendor competitive positioning. Practitioners should keep alternative scenarios live as semiconductor supply concentration and data residency mandate fragmentation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Dating Services Market
Digital Solutions
Database Management Platform Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Agriculture Software Market
Digital Solutions
Digital Workplace Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Global Data Historian Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
P2P Rental Apps Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
E-Ink E-Reader Market