
 Europe Digital Marketing Software Market | 2026-2036
Europe Digital Marketing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Marketing Software Market Analytics
Digital marketing talent scarcity across continental Europe is rotating demand toward platforms that reduce manual campaign complexity. Adobe Inc. leverages its Creative Cloud integration to anchor workflows for creative agencies in France and the UK. Salesforce Inc. competes through its Customer Data Platform specialization, sustaining enterprise loyalty among retail conglomerates. HubSpot Inc. dominates the mid-market with inbound methodology tooling, extending its partner channel across Nordic markets.
Europe Digital Marketing Software encompasses cloud-native and on-premises applications for audience segmentation, campaign orchestration, performance analytics, and marketing resource management, typically deployed via API-first architectures that integrate with CRM and e-commerce stacks. The primary commercial purpose is to automate multi-channel customer engagement while measuring return on ad spend across programmatic, social, and owned-media touchpoints. Cloud-Based and SaaS deployment models now capture the bulk of new bookings as IT procurement teams prioritize subscription flexibility over capital-intensive on-premises installations. Analytics and Social Media Management solution types are absorbing disproportionate R&D investment as advertisers demand real-time attribution across privacy-restricted data environments.
The EU AI Act, GDPR, and ePrivacy Directive collectively mandate algorithmic transparency, consent management, and cross-border data governance that shape product roadmaps and vendor liability exposure. ECHA and national data protection authorities in Germany, France, and Spain enforce these frameworks through periodic audits and penalty regimes that redirect procurement toward certified compliance-ready platforms. Stakeholders must weigh the trade-off between AI-powered personalization depth and regulatory risk exposure when selecting vendor stacks for the next investment cycle.
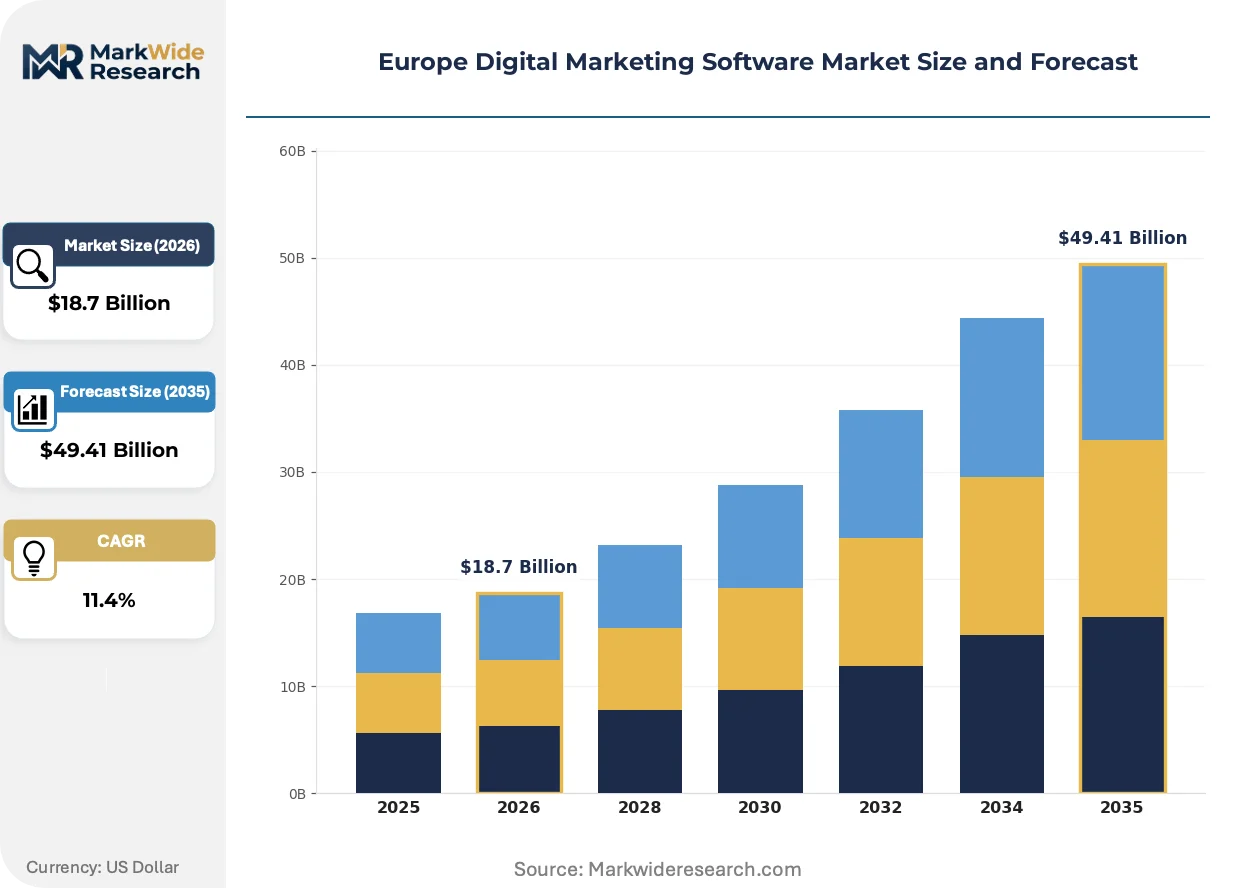
Market Dynamics
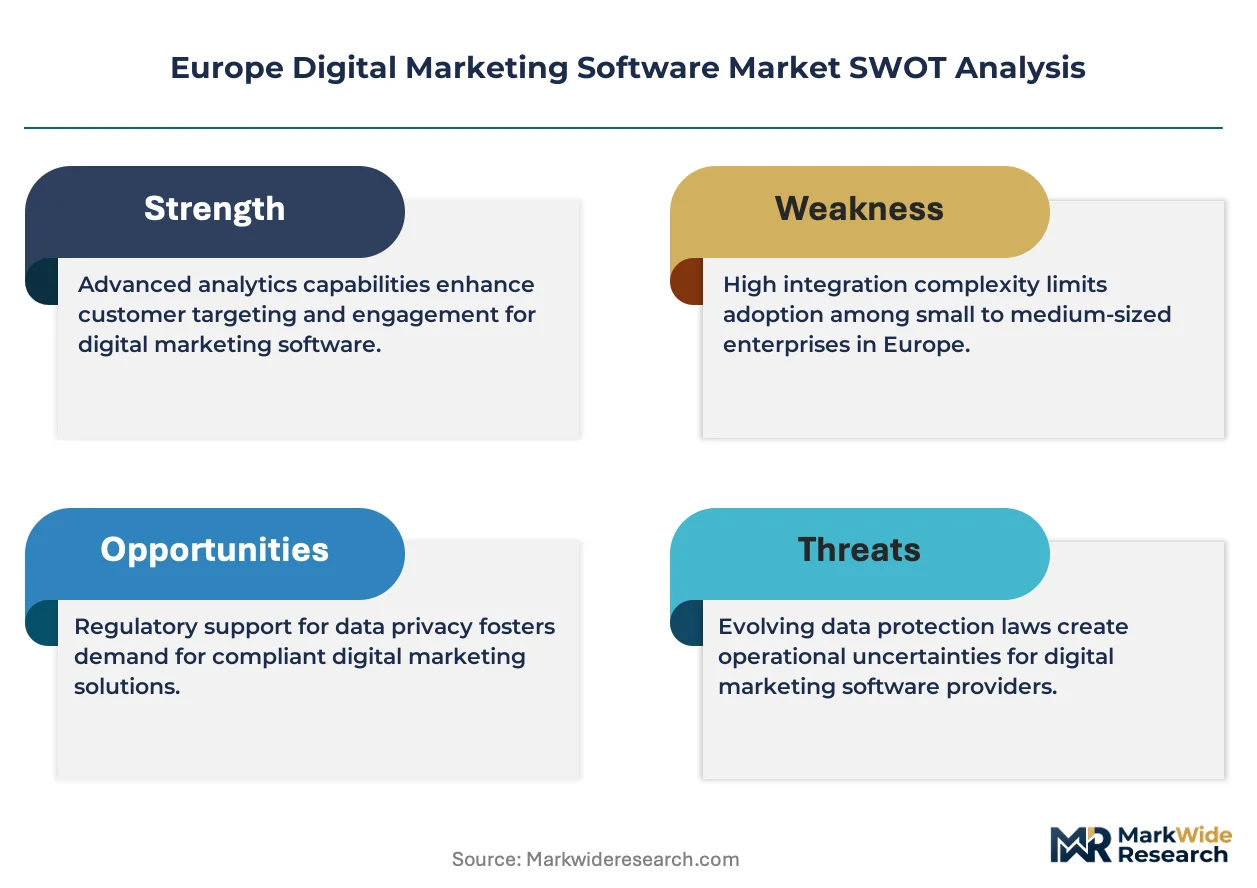
GDPR enforcement intensity and the EU AI Act's algorithmic transparency mandates are compressing vendor margins while forcing architectural redesigns of campaign orchestration engines across the continent.
Growth Catalysts
- Retail automation demand:German and French e-commerce conglomerates are consolidating martech stacks to unify customer data across owned and paid media channels.
- GDPR compliance architecture:Privacy-by-design requirements embedded in the ePrivacy Directive are accelerating replacement cycles for legacy consent management platforms.
- Cloud migration tailwinds:Nordic mid-market enterprises are abandoning on-premises marketing resource management systems for API-first SaaS alternatives.
Market Restraints
- Cross-border data friction:Schrems II rulings and divergent national interpretations of GDPR adequacy decisions are fragmenting pan-European campaign execution.
- Specialized talent scarcity:Düsseldorf-Cologne and Paris agency corridors face acute shortages of machine-learning engineers with marketing domain expertise.
- First-party data deprecation:Browser-level cookie elimination by Apple Safari and Mozilla Firefox is degrading attribution accuracy for programmatic advertisers.
Strategic Opportunities
- Spanish market underpenetration:Madrid and Barcelona brand headquarters remain underserved by localized customer data platform implementations relative to Northern Europe.
- AI Act certification services:Algorithmic audit and bias-testing tooling represents emergent white space as high-risk system designations expand.
- Edge computing convergence:Real-time personalization engines combining 5G latency reduction with on-device inference are opening retail and automotive applications.
Industry Challenges
- Legacy CRM integration complexity:SAP and Oracle on-premises installations at German industrial conglomerates resist API-native marketing automation connectivity.
- CSRD reporting alignment:Sustainability disclosure mandates are forcing martech vendors to reconstruct carbon accounting for cloud infrastructure and data center operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Marketing Software Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Content Marketing, Email Marketing, Social Media Management, Analytics End User: SMEs, Large Enterprises, E-commerce, Agencies Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS Marketing Channel: SEO, PPC, Affiliate Marketing, Social Media Ads |
| Companies Covered | Adobe Inc., Salesforce Inc., HubSpot Inc., Oracle Corporation, SAP SE, Microsoft Corporation, IBM Corporation, SAS Institute Inc., Brevo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Marketing Software Market Evolving Landscape
Privacy-preserving computation techniques and federated learning architectures are displacing centralized data lakes as the dominant technical paradigm for audience intelligence across European advertisers.
Edge-deployed inference engines for real-time bidding and dynamic creative optimization are miniaturizing hardware requirements for programmatic infrastructure. Retail media networks in the UK and Germany are adopting these lightweight models to reduce cloud egress costs. The shift is compressing vendor margins on high-volume data processing contracts while opening subscription tiers for mid-market advertisers previously priced out of enterprise platforms.
The EU AI Act's risk-based classification system is mandating conformity assessments for automated decision-making in credit, insurance, and employment-related marketing. Vendors serving financial services must now document training data provenance and algorithmic explainability. German and French banks are prioritizing certified providers, creating procurement friction for uncertified challengers.
Brand procurement teams are unbundling agency-of-record relationships into specialized contracts for data clean rooms, identity resolution, and creative production. Retail conglomerates in the UK are leading this decomposition, directly contracting technology vendors while retaining agencies for execution-only scopes. The pattern concentrates most visibly among grocery and fashion verticals with mature in-house analytics functions.
Europe Digital Marketing Software Market Segmentation
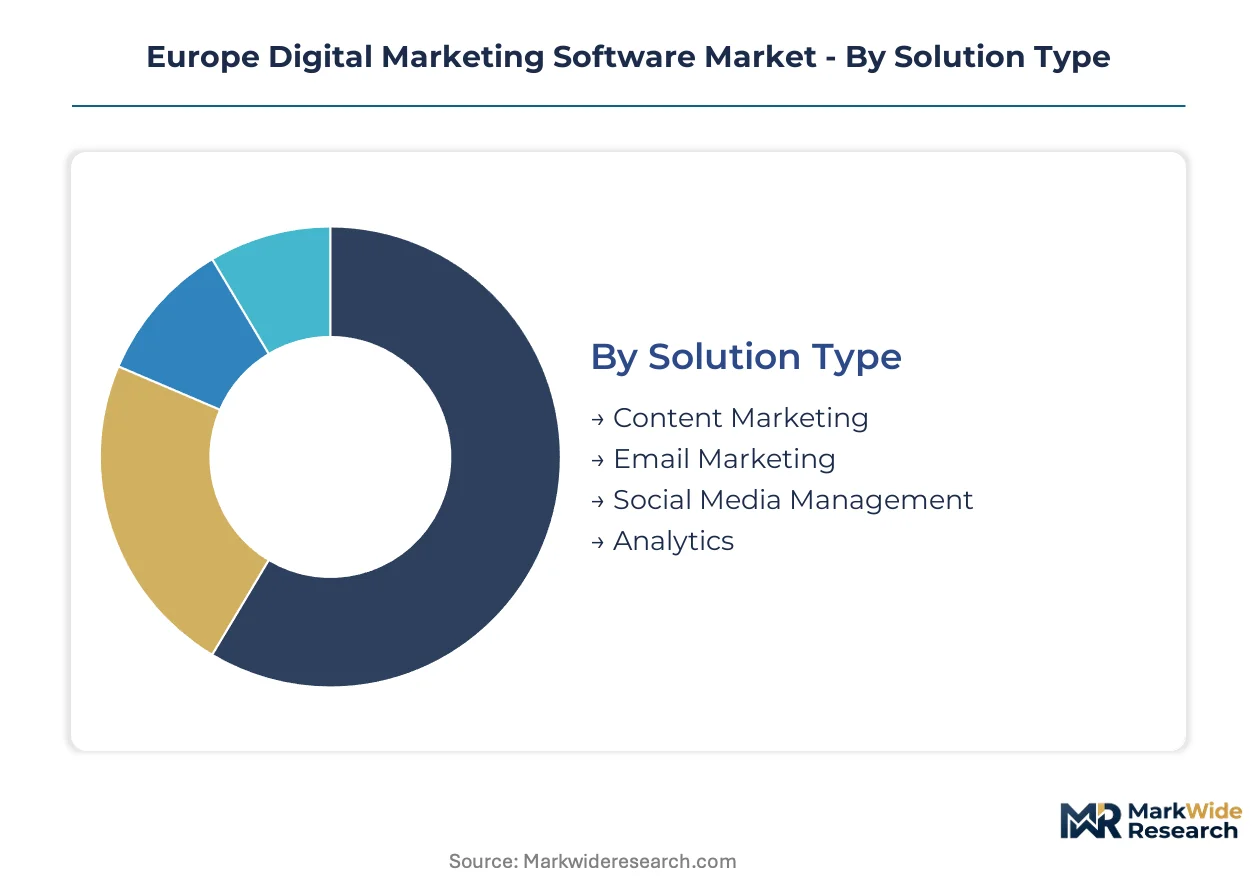
Segmentation in the Europe Digital Marketing Software Market reveals how procurement priorities diverge between compliance-heavy enterprises and agility-driven mid-market players. Vendors must architect distinct delivery models for each cluster, as GDPR enforcement intensity and cloud migration readiness vary sharply across organizational scale and sector.
Solution Type:
Substitution pressure from adjacent software categories is fragmenting the traditional marketing stack, with standalone point solutions facing displacement from integrated suites.
- Content Marketing:Modular platforms for editorial workflow, asset management, and personalized content delivery now embed AI-assisted generation tools. German automotive and B2B industrial advertisers in Stuttgart and Munich drive demand for multilingual content orchestration that satisfies EU AI Act documentation requirements.
- Social Media Management:Unified publishing, listening, and community engagement tools with native compliance logging for regulatory audit trails. UK retail conglomerates and French luxury houses concentrate investment here, prioritizing real-time reputation management across Instagram, TikTok, and emerging channels.
- Email Marketing:Automation platforms with consent management and deliverability optimization.
- Analytics:Attribution and predictive modeling engines with privacy-preserving computation.
Analytics anchors the volume base while Social Media Management gains share at the steepest rate.
End User:
Cost-tier stratification separates procurement patterns, with enterprise buyers prioritizing compliance certification and mid-market buyers emphasizing subscription flexibility.
- Large Enterprises:Multi-tenant deployments with dedicated data residency, custom SLA terms, and enterprise-grade consent management. German industrial conglomerates in the Rhine-Ruhr corridor and French CAC 40 headquarters dominate this tier, consolidating fragmented legacy stacks into unified customer data platforms.
- SMEs:Self-service onboarding, template-driven campaign builders, and transparent per-seat pricing. Nordic mid-market enterprises and UK regional retail chains are migrating fastest from on-premises marketing resource management to API-first SaaS alternatives.
- E-commerce:Conversion-optimized tooling with native marketplace and payment integrations.
- Agencies:Multi-account management, white-label reporting, and client isolation architectures.
Large Enterprises anchor the volume base while SMEs expand most quickly as cloud-native alternatives democratize access.
Deployment Model:
Application requirements dictate infrastructure choices, with real-time personalization engines demanding edge proximity while batch analytics tolerate centralized processing.
- Cloud-Based:Fully managed infrastructure with automatic scaling and regional data center selection. French and UK retail media networks favor this model for programmatic campaign execution, leveraging AWS, Azure, and Google Cloud's EU sovereign cloud offerings to satisfy data localization mandates.
- SaaS:Subscription-native delivery with continuous feature deployment and zero-touch maintenance. Nordic enterprises and Spanish mid-market brands are abandoning perpetual licenses for this model, prioritizing operational expenditure predictability over capital deployment.
- Hybrid:Sensitive data on-premises with burst compute in cloud.
- On-Premises:Air-gapped installations for defense and critical infrastructure sectors.
SaaS anchors the volume base while Hybrid climbs the fastest as regulated sectors seek architectural compromise.
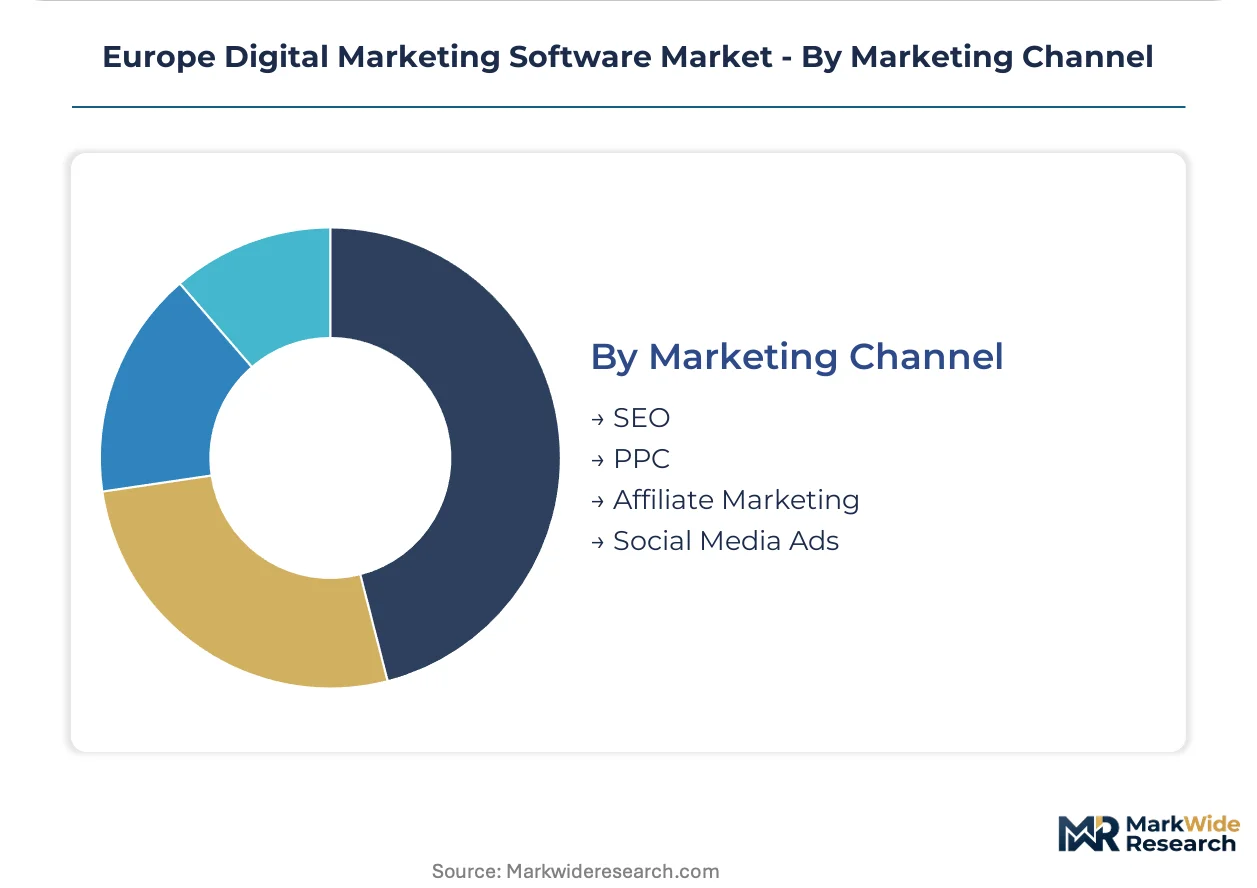
Marketing Channel:
Customer-type concentration shapes channel investment, with direct-to-consumer brands over-indexing on paid social while B2B industrials sustain search and affiliate spend.
- Social Media Ads:Programmatic buying across Meta, TikTok, and emerging platforms with automated creative optimization. UK grocery and fashion verticals with mature in-house analytics functions lead unbundling of agency relationships, contracting technology vendors directly for this channel.
- PPC:Search engine marketing with automated bidding and quality score optimization. German B2B technology and industrial advertisers in Berlin and Hamburg maintain substantial investment here, prioritizing lead quality metrics over volume.
- SEO:Technical audit, content optimization, and rank tracking tooling.
- Affiliate Marketing:Partner tracking, commission management, and fraud detection.
PPC anchors the volume base while Social Media Ads shows the steepest expansion trajectory as retail media networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR enforcement by CNIL and BfDI anchors the regulatory gravity across the continent. The EU AI Act's risk-based classification system now mandates conformity assessments for automated decision-making in marketing stacks.
Germany
Industrial conglomerates in the Rhine-Ruhr corridor are consolidating fragmented martech stacks into unified customer data platforms. BfDI audits and Schrems II adequacy rulings are accelerating replacement cycles for legacy consent management systems. Düsseldorf-Cologne advertising technology clusters concentrate agency networks and brand headquarters demanding privacy-by-design architectures.
United Kingdom
Retail media networks and grocery conglomerates are unbundling agency-of-record relationships into specialized contracts for data clean rooms and identity resolution. The UK Information Commissioner's Office enforces GDPR-derived standards through penalty regimes that redirect procurement toward certified compliance-ready platforms. London's in-house analytics functions lead direct contracting with technology vendors for social media advertising execution.
France
Luxury houses and CAC 40 headquarters prioritize real-time reputation management across Instagram and TikTok with native compliance logging for regulatory audit trails. CNIL enforces algorithmic transparency mandates that compress vendor margins while forcing architectural redesigns of campaign orchestration engines. Paris agency corridors face acute shortages of machine-learning engineers with marketing domain expertise.
Spain
Madrid and Barcelona brand headquarters remain underserved by localized customer data platform implementations relative to Northern Europe. Spanish data protection authority enforcement of GDPR and ePrivacy Directive provisions is pushing mid-market brands toward API-first SaaS alternatives. Barcelona's retail and fashion verticals are migrating fastest from on-premises marketing resource management to subscription-native delivery models.
Netherlands
Randstad enterprises and Eindhoven Region technology advertisers are adopting edge-deployed inference engines for real-time bidding to reduce cloud egress costs. The Dutch Data Protection Authority enforces cross-border data governance that fragments pan-European campaign execution. Amsterdam's programmatic infrastructure clusters are miniaturizing hardware requirements for retail media network applications.
Europe Digital Marketing Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European digital marketing software landscape. The vendor base separates into enterprise-grade suite providers, mid-market inbound specialists, and regional compliance-focused challengers. Three strategic archetypes dominate: Creative Cloud-integrated workflow anchors, Customer Data Platform specialists, and API-first SaaS democratizers. Competitive moves concentrate on M&A for consent management capabilities and strategic partnerships for sovereign cloud data residency.
Within the enterprise suite tier, Adobe Inc. and Salesforce Inc. occupy positions shaped by creative workflow integration and customer data platform specialization respectively. HubSpot Inc. exemplifies the mid-market inbound methodology archetype extending across Nordic markets. These three anchors represent divergent approaches to GDPR compliance architecture and AI Act certification requirements.
| Leading Market Players |
|---|
| Adobe Inc. |
| Salesforce Inc. |
| HubSpot Inc. |
| Oracle Corporation |
| SAP SE |
| Microsoft Corporation |
| IBM Corporation |
| SAS Institute Inc. |
| Brevo |
| Others |
Value Network & Pricing Analysis
Capacity-reservation contracts with sovereign cloud providers lock in both data residency compliance and subscription price visibility for European enterprise procurement teams navigating GDPR localization mandates.
Pricing Analysis
German enterprise buyers face subscription premiums of 15-25% over Nordic mid-market counterparts for equivalent customer data platform functionality. Three-tier pricing structure across premium, standard, and economy levels separates dedicated data residency deployments from multi-tenant SaaS and self-serve alternatives. Pricing pressure stems from cloud infrastructure cost compression as AWS, Azure, and Google Cloud compete for EU sovereign cloud certifications. Mid-market retailers in Spain and Italy exhibit highest price sensitivity, while Rhine-Ruhr industrial conglomerates prioritize compliance certification over cost optimization.
Supply Chain Analysis
Just-in-time feature deployment dominates software delivery, with continuous integration pipelines replacing traditional release cycles across European vendor operations. Development resources concentrate in Germany, Ireland, and Poland, with machine-learning engineering talent scarcity in Paris and Amsterdam forcing compensation premiums. Cloud compute and API infrastructure dependencies draw from hyperscaler data centers in Frankfurt, Dublin, and Amsterdam. Single-source vulnerability in consent-management module supply creates procurement risk. Distribution runs through direct enterprise sales teams and partner channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine-learning engineering talent gaps in Düsseldorf-Cologne and Paris corridors are constraining campaign orchestration innovation velocity, redirecting competitive advantage toward vendors with captive technical training pipelines.
For Market Incumbents: Fortify market position by deepening backward integration into consent-management technology and acquiring specialized AI Act certification capabilities. Adobe and Salesforce must defend against API-first challengers by embedding privacy-by-design architectures deeper into creative workflow and customer data platform stacks. Channel control through certified implementation partner networks represents the critical defensive lever. For New Entrants and Emerging Players: Differentiate on localized Spanish and Italian customer data platform implementations where Northern European vendors remain underrepresented. White-space concentration in Madrid and Barcelona brand headquarters offers the most penetrable geography. Go-to-market execution should emphasize transparent per-seat pricing and rapid self-service onboarding to capture mid-market retailers abandoning legacy on-premises systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API-first SaaS vendors with demonstrated GDPR compliance certification and established partner channel networks. Long-term viability across the analysis window favors platforms with embedded AI Act conformity assessment capabilities. Acquisition targets should demonstrate algorithmic audit tooling and bias-testing infrastructure. The signal to watch is enforcement intensity from CNIL and BfDI accelerating replacement cycles for non-compliant legacy stacks.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Creative Cloud and CRM connectivity anchors agency retention in France and the UK. |
| Strategic Partnership | Sovereign cloud alliances with AWS, Azure, and Google Cloud satisfy EU data localization mandates. |
| Acquisition of Specialist Firm | Consent-management and algorithmic audit capabilities address AI Act certification requirements. |
| Product Launch | Edge-deployed inference engines reduce latency for retail media network real-time bidding. |
| Geographic Expansion | Localized Madrid and Barcelona deployments capture underserved Spanish mid-market demand. |
Research Methodology
Cross-validation between primary interviews with marketing technology executives and secondary analysis of vendor SEC filings anchors the qualitative findings. Chief technology officers, IT procurement officers at German retail conglomerates, platform engineers, and integration specialists across the Düsseldorf-Cologne and Paris agency corridors provided operational perspective. Secondary sources include hyperscaler capex disclosures, CNIL and BfDI enforcement bulletins, and EU AI Act implementation guidance. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates.
Sensitivity analysis across deployment model, organization size, vertical industry, and integration complexity dimensions shapes the analytical framework over the projection horizon. CAGRs derive from trend extrapolation and adoption curve modeling. Forecast inputs incorporate cloud migration velocity among Nordic mid-market enterprises and GDPR replacement cycle timing for legacy consent management platforms.
Material uncertainties — regulatory enforcement intensity, cross-border data adequacy rulings, and browser-level cookie deprecation pace — sit outside the modeled envelope. Forecasts reflect assumptions about vendor certification timelines and sovereign cloud availability. Revision becomes warranted when AI Act high-risk system designations expand beyond financial services marketing applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Pipeline Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Self-Service Kiosk Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Equipment Tracking Software Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Weather App Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Data Pipeline Tools Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Cloud Monetization Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Predictive Maintenance Software Market