
 North America Digital Signage Market | 2026-2036
North America Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital Signage Market Analytics
The direct-to-end-user channel is narrowing as manufacturers build captive service networks. Samsung Electronics leverages vertical integration across panel production and content management platforms. LG Electronics sustains manufacturing scale through dedicated display fabs serving North American commercial buyers. Daktronics specializes in outdoor LED systems for sports venues and transportation hubs across the United States and Canada.
North America digital signage encompasses networked electronic display systems ranging from small-format LCD screens to large-scale LED video walls, typically operating on content management software with remote scheduling capabilities and brightness ratings between 500 and 10,000 nits for varied ambient light conditions. These systems serve commercial and institutional communicators by replacing static media with dynamically updatable visual content. LED display systems command premium positioning in outdoor and high-ambient installations where luminance requirements exceed standard LCD capabilities. Retail application demand outpaces other verticals as brick-and-mortar operators deploy interactive wayfinding and promotional networks. Indoor installation types dominate volume, though outdoor segments carry higher per-unit margins due to weatherproofing and thermal management specifications.
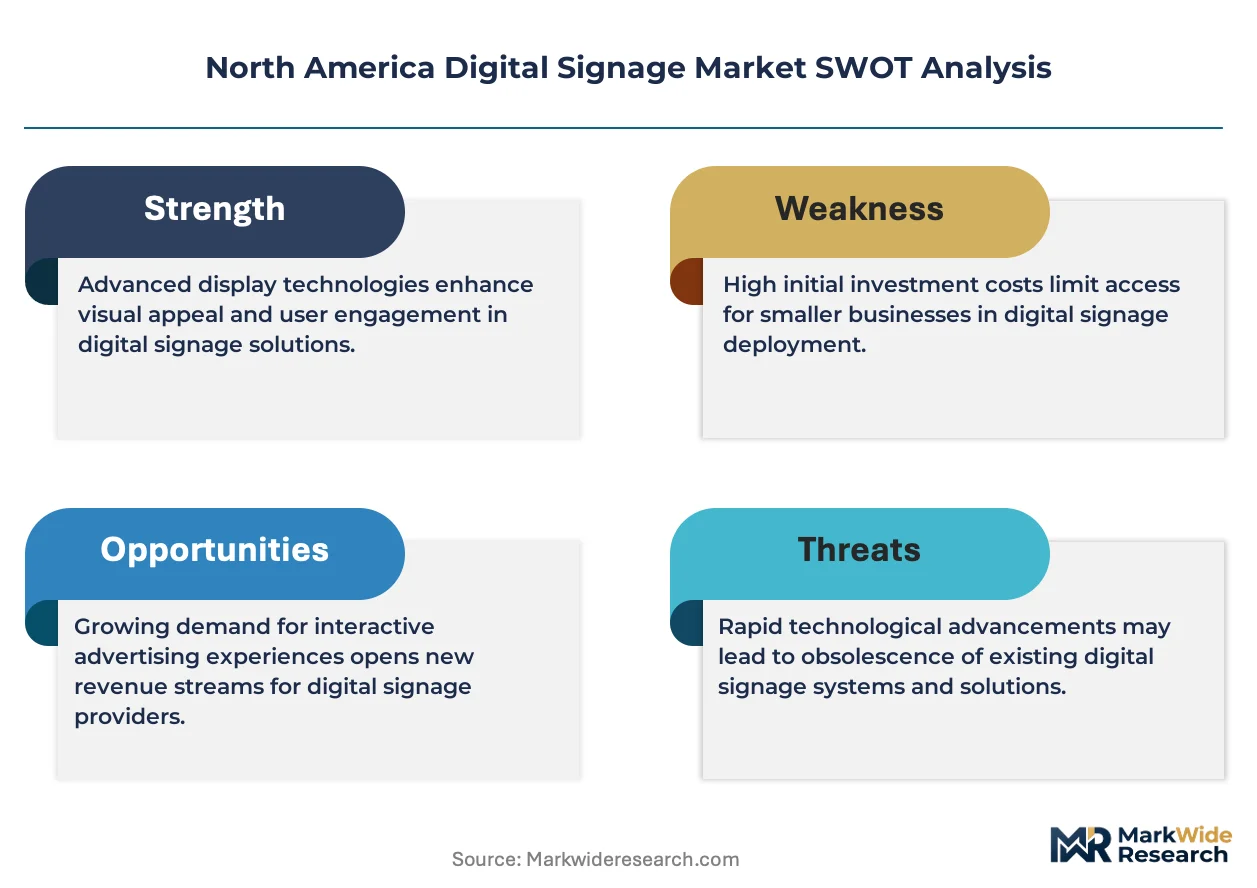
FCC equipment authorization processes govern radio-enabled signage modules, while Energy Star certification shapes municipal and corporate procurement criteria across the United States. State-level building codes in California and New York impose additional electrical efficiency and safety standards for permanent display installations. CSA Group standards apply to Canadian deployments, creating a dual-compliance environment for vendors operating across the region. Stakeholders must monitor evolving state energy mandates and procurement preference shifts between ownership models and subscription-based display-as-a-service arrangements.
Market Dynamics
FCC equipment authorization requirements and Energy Star efficiency standards are compressing vendor margins while forcing rapid product refresh cycles across the United States and Canada. Manufacturers must now certify radio-enabled signage modules and meet escalating municipal procurement criteria simultaneously.
Growth Catalysts
- Transit infrastructure modernization:Transit authorities across the United States Northeast corridor are deploying large-format LED networks for real-time passenger information. Federal infrastructure allocations accelerate these procurement timelines.
- Energy Star certification mandates:Corporate and municipal buyers now require certified displays for new installations. This creates specification lock-in for compliant vendors.
- Brick-and-mortar retail reinvestment:Retail chains are expanding interactive wayfinding and promotional screen networks to compete with e-commerce. Customer engagement metrics drive deployment decisions.
Market Restraints
- Panel supply concentration:Display panel production concentrates among Asian semiconductor foundries, exposing North American integrators to shipping volatility and currency fluctuation.
- Weatherproofing cost escalation:Outdoor LED systems require thermal management and ingress protection rated at IP65 or higher, adding substantial per-unit manufacturing overhead.
- CSA Group dual-compliance burden:Vendors serving both the United States and Canada must maintain parallel certification tracks, extending product launch timelines.
Strategic Opportunities
- Display-as-a-service models:Subscription-based arrangements are displacing capital purchase cycles. Managed service providers capture recurring revenue from corporate campus networks.
- Canadian transit digitization:Toronto and Vancouver transit authorities lag U.S. counterparts in network density, presenting first-mover expansion potential.
- AI-driven content optimization:Machine learning analytics are converging with digital signage platforms to enable real-time audience measurement and dynamic creative adjustment.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for brightness calibration and thermal management exceeds available talent pools in North American labor markets.
- Legacy AV infrastructure integration:Corporate buyers require seamless interoperability with existing control rooms and scheduling systems, complicating deployment architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital Signage Market |
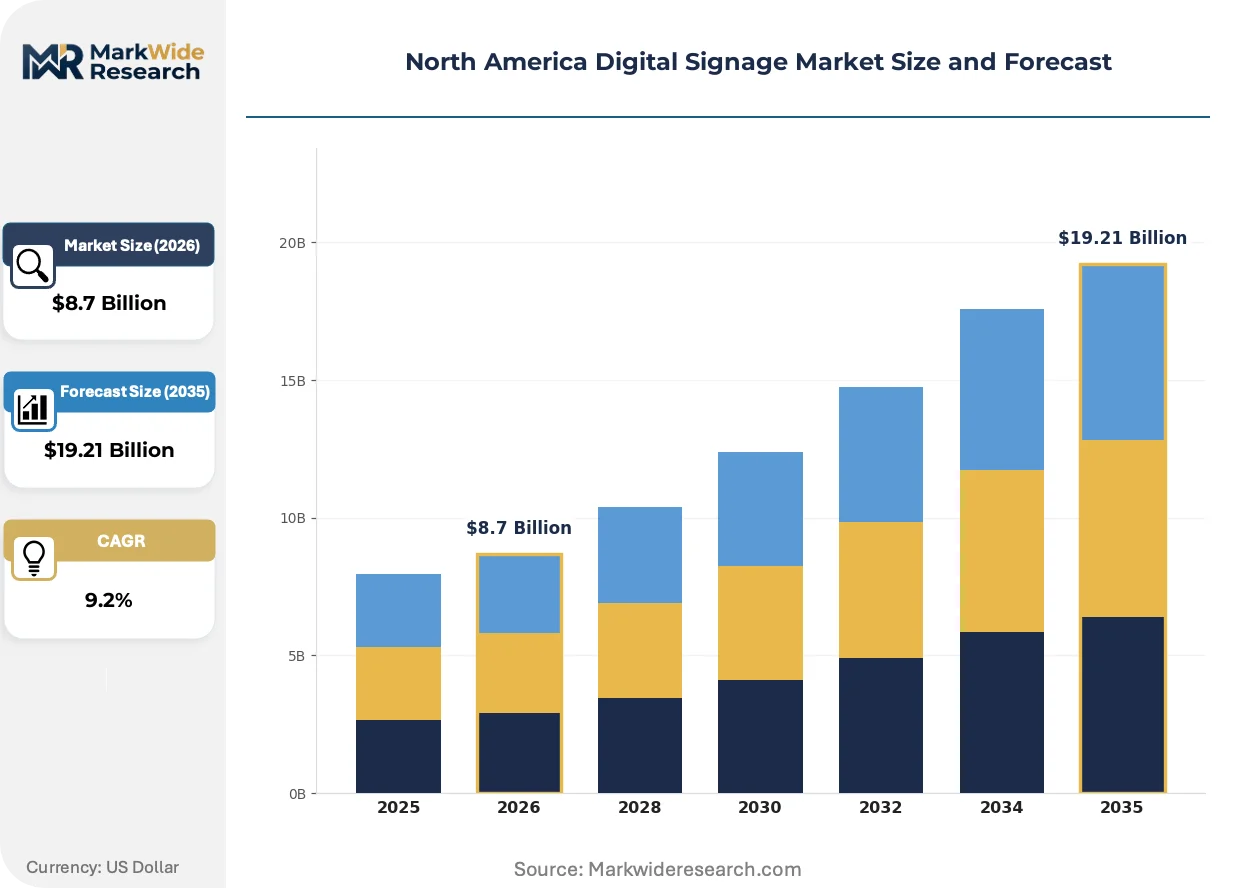
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Display, LCD Display, Projection, OLED Display Application: Retail, Transportation, Education, Entertainment End User: Corporate, Healthcare, Government, Hospitality Installation Type: Indoor, Outdoor, Portable, Wall-Mounted |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics, SHARP NEC Display Solutions, Ltd., Panasonic Corporation, Sony Corporation, Cisco Systems, Inc., Planar Systems, Inc., Barco NV, Daktronics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital Signage Market Evolving Landscape
Cloud-native content management platforms are displacing on-premise servers across enterprise deployments. This architectural shift compresses total cost of ownership while enabling centralized creative control.
MicroLED display technology is virtualizing the boundary between indoor and outdoor installation specifications. Transit authorities and sports venue operators are piloting sub-1mm pixel pitch systems for close-viewing applications previously dominated by LCD. The technology is virtualizing traditional category distinctions between high-brightness outdoor and precision indoor formats.
California Title 24 building energy codes now mandate automated daylight dimming for permanent display installations exceeding specified wattage thresholds. Retail and corporate campus developers must integrate photocell sensors and programmable drivers into new construction specifications. Compliance costs are accelerating specification consolidation toward vertically integrated platform vendors.
Buyers are unbundling hardware procurement from creative services and technical support. Large retail chains now source displays through direct manufacturer relationships while contracting specialized agencies for content production. This bifurcation is most visible in the United States, where Fortune 500 campus deployments increasingly separate capital equipment budgeting from operating expenditure for managed services.
North America Digital Signage Market Segmentation
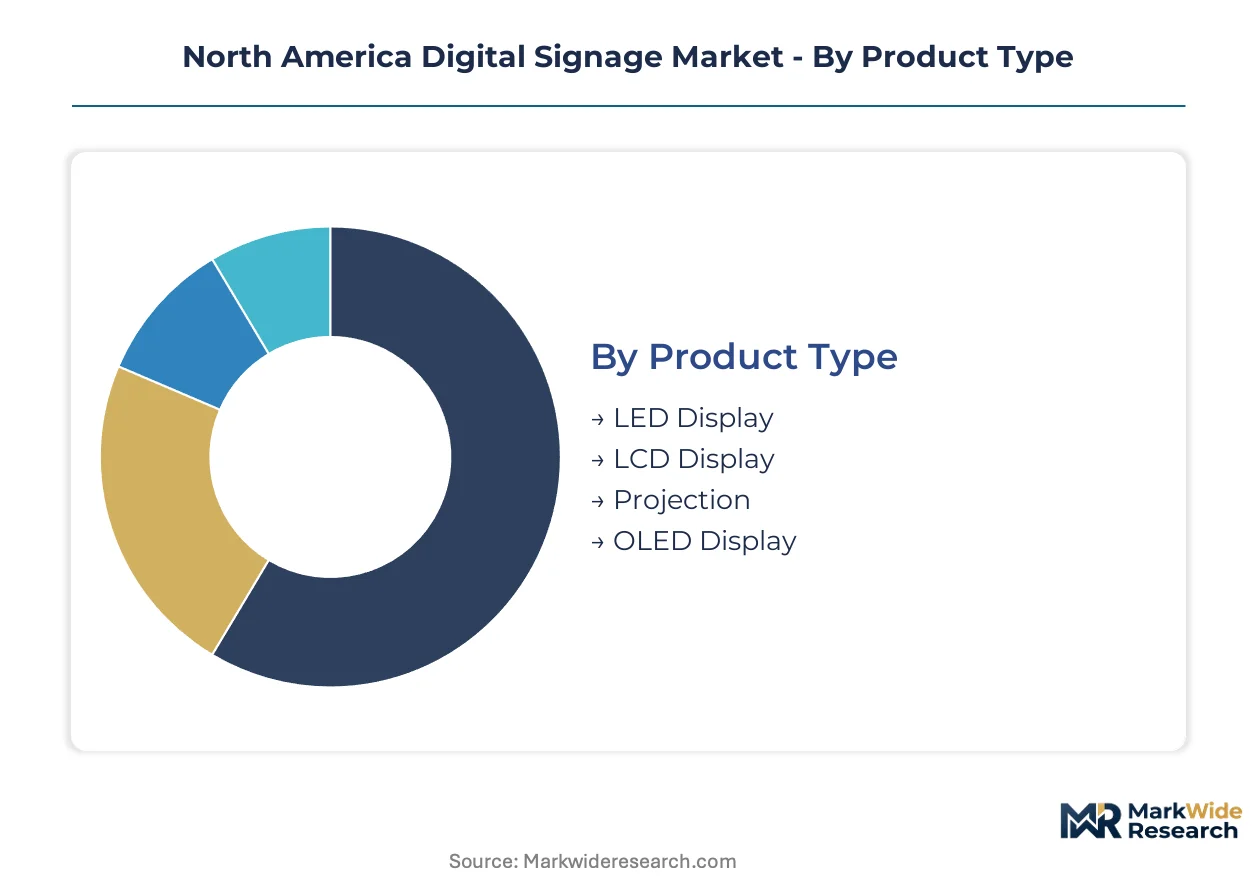
North American digital signage procurement varies sharply by ambient light requirements, content refresh cycles, and regulatory exposure. Buyers select product architectures based on whether displays face direct sunlight, require touchscreen interactivity, or operate within climate-controlled interiors. These technical boundaries create four distinct category hierarchies that vendors must address simultaneously.
Product Type:
Display technologies span a luminance spectrum from 500-nit indoor LCD panels to 10,000-nit outdoor LED arrays, each commanding different margin profiles and installation expertise.
- LED Display:Direct-view LED modules with pixel pitches from 0.9mm to 16mm deliver brightness levels exceeding standard LCD capabilities by an order of magnitude. Sports venues across Texas and Florida deploy these for daylight-visible video walls, though thermal management engineering adds manufacturing overhead.
- LCD Display:Thin-film transistor liquid crystal panels dominate volume through standardized 32-inch to 98-inch formats, with in-plane switching technology improving off-angle viewing for retail aisle endcaps. Corporate campus networks in Illinois and Ohio specify these for conference room scheduling and wayfinding.
- Projection:Laser phosphor and solid-state illumination systems enable temporary large-format surfaces without permanent structural mounting.
- OLED Display:Organic light-emitting diode panels offer self-emissive pixels with true black levels and sub-2mm bezel configurations.
The dominant share belongs to LED Display for high-margin outdoor and transit applications, while OLED Display is closing the gap fastest through premium retail flagship installations.
Application:
End-use contexts determine content management complexity, network uptime requirements, and integration with legacy building systems.
- Retail:Point-of-sale networks and fitting room mirrors drive the highest screen density per square foot, with interactive kiosks capturing shopper dwell-time analytics. Grocery chains in California and Arizona deploy refrigerated case-edge displays with IP54-rated enclosures.
- Transportation:Real-time passenger information systems require 99.9% uptime guarantees and redundant connectivity through cellular and hardwired Ethernet. Metropolitan Transportation Authority contracts in New York and Port Authority of New York and New Jersey specifications set regional procurement standards.
- Education:Campus-wide digital bulletin boards and lecture hall collaboration displays serve K-12 and higher education institutions.
- Entertainment:Cinema lobbies, casino floor directories, and stadium concourse networks prioritize high-dynamic-range content playback.
Transportation commands the steepest expansion trajectory through federal infrastructure allocations, though Retail maintains volume leadership across the United States and Canada.
End User:
Budget authority and procurement compliance requirements fragment buyer profiles across capital expenditure and operating lease models.
- Corporate:Fortune 500 headquarters and regional office campuses favor cloud-managed networks with centralized creative control, often separating hardware procurement from managed service subscriptions. Technology and financial services firms in Massachusetts and Washington state lead deployment density.
- Healthcare:Hospital systems require HIPAA-compliant content distribution and antimicrobial surface treatments for patient-facing displays. Kaiser Permanente and Mayo Clinic network standards influence vendor qualification processes.
- Government:Municipal buildings and federal facilities mandate Energy Star certification and Section 508 accessibility compliance.
- Hospitality:Hotel lobbies and convention centers prioritize seamless integration with property management systems for meeting room signage.
Corporate buyers generate the highest revenue per deployment, while Healthcare is expanding most quickly through hospital consolidation and campus modernization programs.
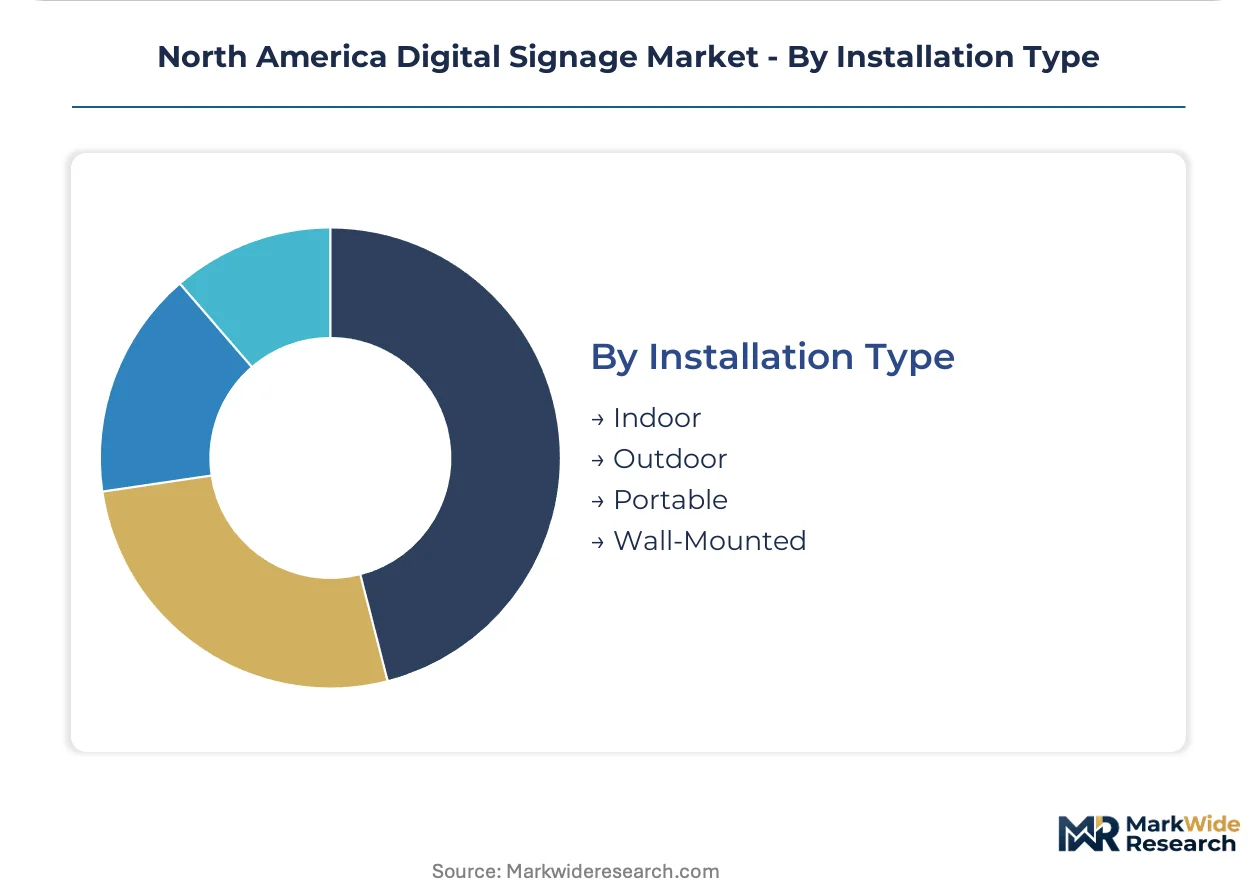
Installation Type:
Physical mounting constraints determine weatherproofing specifications, electrical load calculations, and structural engineering requirements.
- Indoor:Climate-controlled environments allow standard thermal management without IP-rated enclosures, reducing per-unit cost by 40-60% versus outdoor equivalents. Office towers in Manhattan and Chicago drive volume through lobby video walls and elevator directory systems.
- Outdoor:Permanent exterior installations require NEMA 3R or IP65 ingress protection, automatic brightness sensors, and heating elements for cold-weather markets. Canadian deployments face additional CSA Group certification for temperature cycling durability.
- Portable:Tradeshow and event rental applications prioritize rapid assembly and flight-case transportability.
- Wall-Mounted:Flush architectural integration demands shallow-depth chassis designs and concealed cable routing.
Indoor installations account for the majority of unit shipments, though Outdoor configurations deliver the highest per-unit margins and are gaining share fastest through transit and stadium digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian transit authorities command premium pricing for CSA-certified outdoor installations, while Mexican retail chains absorb cost-sensitive LCD volume through duty-advantaged distribution corridors. This asymmetry concentrates vendor margin capture in the northern tier of the region.
United States
Federal infrastructure allocations accelerate transit digitization across the Northeast corridor, with Metropolitan Transportation Authority specifications setting procurement benchmarks nationwide. FCC equipment authorization requirements govern radio-enabled signage modules for commercial deployment. Chicago and Manhattan office towers drive indoor volume through lobby video walls and elevator directory networks.
Canada
Toronto and Vancouver transit authorities lag U.S. counterparts in network density, presenting expansion potential for real-time passenger information systems. CSA Group standards apply to all permanent display installations, creating dual-compliance complexity for cross-border vendors. Montreal corporate campuses favor cloud-managed networks with centralized creative control.
Mexico
Retail chains in Mexico City and Guadalajara deploy cost-optimized LCD networks for promotional content and wayfinding applications. NAFTA-origin tariff advantages attract display assembly operations for re-export to U.S. border states. Northern border manufacturing clusters serve duty-advantaged distribution into Texas and California markets.
North America Digital Signage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying panels, drivers, and thermal management subsystems to branded assemblers. The vendor base stratifies across three tiers: vertically integrated electronics conglomerates with captive display fabs, dedicated commercial display specialists with regional service networks, and systems integrators bundling third-party hardware with proprietary content management software. Dominant competitive moves include backward integration into panel sourcing and geographic expansion through local service partnerships.
Within the conglomerate tier, Samsung Electronics Co., Ltd. and LG Electronics exemplify scale-driven platform strategies spanning manufacturing through software layers. Daktronics, Inc. occupies a specialist position focused on outdoor LED systems for sports and transportation applications. These three anchors represent divergent archetypes: Korean electronics groups leverage upstream control over semiconductor and panel production, while the Brookings-based fabricator concentrates engineering resources on high-brightness environmental durability.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics |
| SHARP NEC Display Solutions, Ltd. |
| Panasonic Corporation |
| Sony Corporation |
| Cisco Systems, Inc. |
| Planar Systems, Inc. |
| Barco NV |
| Daktronics, Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Asian display panel foundries is compressing spot pricing for LCD modules while forcing North American integrators toward longer-term offtake commitments to secure allocation priority. This utilization imbalance rewards vendors with captive semiconductor supply while squeezing margins for pure-play assemblers dependent on merchant markets.
Pricing Analysis
The customization-premium spread between configured-to-order outdoor LED systems and standard indoor LCD panels now exceeds 300% at the project level. Project-based pricing dominates large-format transit and stadium deployments, while subscription SaaS-tiered models capture recurring revenue from corporate campus networks. Price differentiation hinges on Energy Star certification tier and IP65 weatherproofing grade. Pricing pressure stems from panel oversupply in South Korea and Taiwan, with municipal buyers showing highest price sensitivity and Fortune 500 corporate buyers least sensitive due to total-cost-of-ownership framing.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for supply-chain finance facilities offered by Korean electronics conglomerates to North American integrators. Display panel production concentrates in South Korea, Taiwan, and China, with driver ICs and thermal management subsystems sourced from Japanese and German specialists. The supply chain draws from gallium nitride substrates, aluminum heat sinks, and optical-grade polycarbonate. Single-source vulnerability around advanced LED chip architectures threatens allocation security. Distribution runs through manufacturer-direct channels for enterprise accounts and specialized AV integrators for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cloud-native content management interoperability is displacing on-premise server architectures, rewarding vendors who control both hardware and software layers.
For Market Incumbents: Harden defensive moats by deepening backward integration into LED chip packaging and securing exclusive content management platform partnerships with transit authorities. FCC certification investment creates specification lock-in against Asian competitors lacking U.S. regulatory expertise. Priority lever rests on captive service network density across the Northeast corridor. For New Entrants and Emerging Players: Pursue white-space expansion in Canadian transit digitization where Toronto and Vancouver lag U.S. network density by 40-60%. AI-driven content optimization represents the most penetrable application layer, with machine learning analytics enabling real-time audience measurement. Go-to-market angle should emphasize display-as-a-service subscription models displacing capital purchase cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers bundling hardware procurement with creative services and technical support. Long-term viability favors vendors with cloud-native platform control and vertical integration into panel sourcing. Acquisition target archetype: mid-scale integrators with exclusive transit authority relationships. Signal to watch is subscription revenue share crossing 50% of total bookings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Packaging | Captive supply of high-brightness modules insulates Samsung and LG from foundry allocation volatility. |
| Cloud-Native Platform Migration | Content management software displacement of on-premise servers compresses total cost of ownership for corporate buyers. |
| CSA Group Certification Investment | Dual-compliance capability for U.S.-Canada cross-border vendors accelerates Toronto and Vancouver transit procurement timelines. |
| Display-as-a-Service Launch | Subscription models capture recurring revenue from hospital campus networks and Fortune 500 headquarters. |
| MicroLED Pilot Deployment | Sub-1mm pixel pitch systems enable transit authorities to virtualize indoor-outdoor category distinctions. |
Research Methodology
Initial hypotheses were tested against primary input from display procurement managers at transit authorities, AV integration specialists, corporate facilities directors, and LED module manufacturing engineers, then refined through secondary validation. Primary fieldwork encompassed structured interviews with stakeholders responsible for FCC certification compliance and Energy Star procurement specifications. Secondary sources included FCC equipment authorization databases, Energy Star certified product listings, Metropolitan Transportation Authority contract disclosures, and CSA Group standards documentation. Bottom-up unit economics triangulated against top-down market sizing across product type, application, and installation type segments.
Demand-supply-balance framing anchored the forecast framework, with installation volume projections cross-referenced against panel foundry capacity utilization reported by Korean and Taiwanese manufacturers. Segmentation dimensions modeled span display technology, ambient light requirement, content refresh cycle intensity, and regulatory compliance tier. CAGRs were derived from slope analysis of historical procurement trajectories and forward-looking infrastructure allocation schedules. Industry-specific inputs included federal transit infrastructure spending flows and state-level building code evolution in California and New York.
Sensitivities concentrate around panel supply disruption from Taiwan Strait logistics volatility and accelerated Energy Star efficiency mandate adoption. Forecasts reflect assumptions about transit authority procurement timelines and retail chain reinvestment cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America API Management Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Web Content Management Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Cloud Logistics Software Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Dating Services Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Global E-Signature Platform Market
Digital Solutions
Marketing Automation Market
Digital Solutions
Green IT Services Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Predictive Maintenance Software Market