
 Infrared Sensors Market | 2026-2036
Infrared Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Sensors Market Analysis
Automotive safety is decoupling from surveillance as the dominant end-use vertical for infrared sensors, with advanced driver-assistance systems and night-vision modules now commanding disproportionate engineering resources. Teledyne Technologies leverages its vertically integrated detector fabrication to anchor high-reliability aerospace contracts. Texas Instruments Incorporated sustains cost leadership in thermopile arrays for consumer electronics through its mature MEMS infrastructure. FLIR Systems differentiates via thermal imaging software stacks that extend hardware margins into recurring analytics revenue.
Infrared sensors detect electromagnetic radiation in wavelengths from approximately 0.75 to 1000 micrometers, converting thermal energy into electrical signals through thermoelectric, pyroelectric, or photonic transduction mechanisms; microbolometer arrays operate at ambient temperature without cryogenic cooling, enabling compact thermal cameras for commercial deployment. Image sensors lead the product type hierarchy in revenue contribution, while motion sensors represent the fastest-expanding application layer as smart building automation proliferates. Quantum well technology occupies the premium tier for military and scientific instrumentation where cooled performance remains non-negotiable.
The US FDA regulates infrared thermography devices for medical screening under 21 CFR standards, while the EU RoHS directive restricts hazardous substances in sensor electronics, and Japan's METI enforces energy efficiency benchmarks that thermopile manufacturers must satisfy for consumer product certification. These frameworks collectively elevate compliance costs for new entrants but protect incumbent suppliers with established testing infrastructure. Stakeholders must monitor evolving export control classifications for focal plane arrays as geopolitical friction intensifies around dual-use thermal imaging capabilities.
Market Dynamics
Automotive OEMs are diverting engineering resources from traditional surveillance applications toward thermal imaging for pedestrian detection and cabin monitoring, restructuring demand patterns across detector suppliers.
Growth Catalysts
- Mercury-free detector mandates:European REACH regulations on hazardous substances are accelerating indium gallium arsenide adoption for medical and industrial spectroscopy, forcing material transitions across foundries.
- ADAS thermal integration:Night-vision modules for advanced driver-assistance systems are pulling uncooled microbolometer volumes into automotive qualification pipelines.
- Smart building automation:Occupancy sensing and HVAC optimization in commercial real estate are expanding thermopile array deployments for energy management.
Market Restraints
- Indium supply concentration:Detector-grade indium refining concentrates in Chinese smelters, exposing Western fabricators to export restriction risk.
- Cryogenic cooling cost floor:Quantum well infrared photodetectors require liquid nitrogen or Stirling cycle cooling, pricing them out of commercial volume markets.
- Silicon photonics substitution:Short-wave infrared imaging below 1.6 micrometers faces displacement from advanced CMOS image sensors with extended spectral response.
Strategic Opportunities
- India industrial automation:BIS certification requirements for process control equipment are creating localized assembly demand for non-contact temperature sensors.
- EU F-Gas Regulation phase-down:Leak detection mandates for hydrofluorocarbon refrigeration systems are mandating infrared absorption analyzers across service networks.
- Edge AI thermal fusion:On-chip neural processing integration with microbolometer arrays enables real-time threat classification without cloud dependency.
Industry Challenges
- Cleanroom lithography talent scarcity:Focal plane array fabrication requires specialized MEMS process engineers concentrated in Germany and Japan.
- ITAR/EAR classification complexity:Dual-use thermal imaging export controls create licensing friction for products crossing technical performance thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Sensors Market |
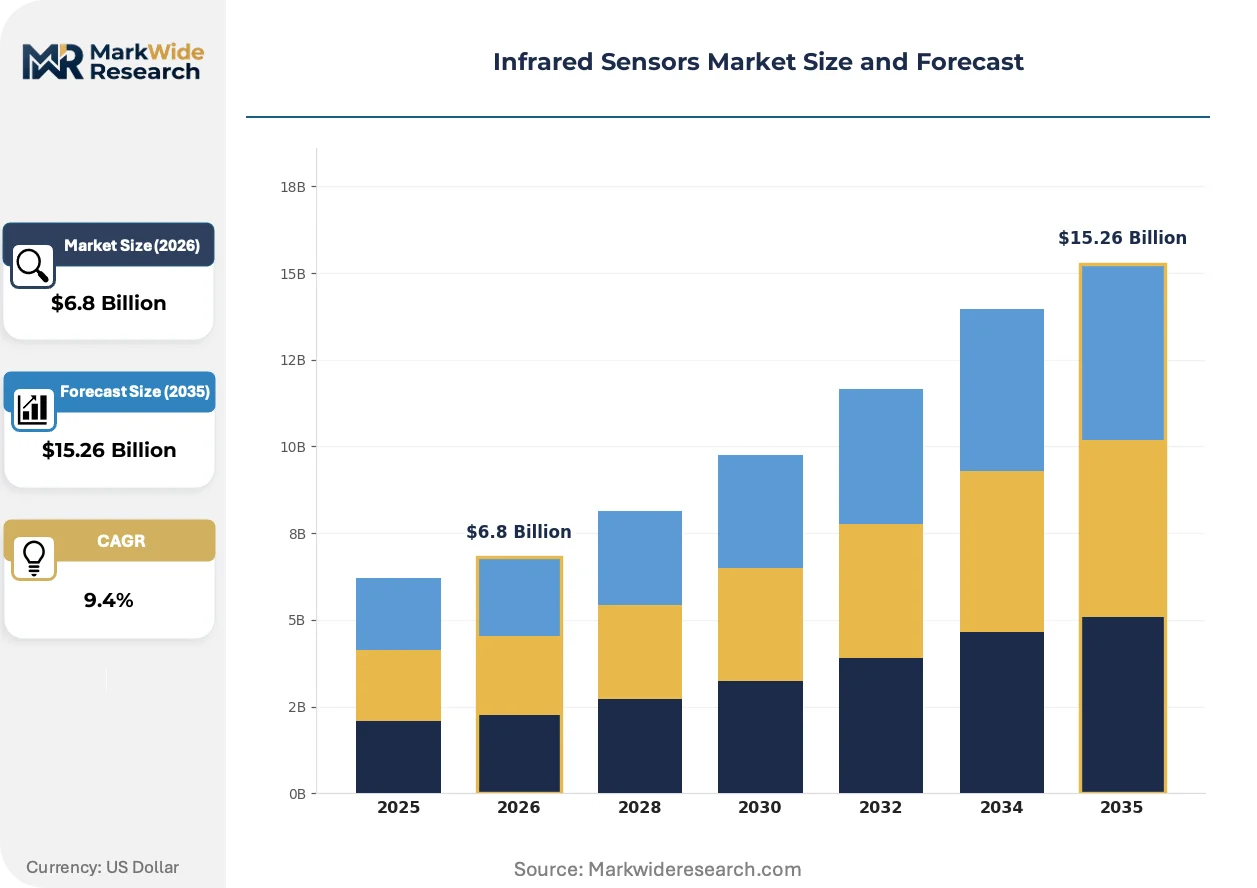
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Sensors, Proximity Sensors, Image Sensors, Motion Sensors Application: Heating, Surveillance, Automotive Safety, Consumer Electronics End User: Manufacturing, Healthcare, Aerospace, Security Technology: Active Infrared, Passive Infrared, Quantum Well, Microbolometer |
| Companies Covered | Teledyne Technologies, Texas Instruments Incorporated, Murata Manufacturing Co., Ltd., Honeywell International Inc., Excelitas Technologies Corp., Lynred, Raytheon Technologies Corporation, Hamamatsu Photonics K.K., FLIR Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Sensors Market Emerging Trajectories
Detector architectures are fragmenting between cost-optimized uncooled arrays for volume applications and performance-optimized cooled sensors for scientific instrumentation, with software-defined imaging gaining hardware margin capture.
Microbolometer pixel pitch is converging with wafer-level optics integration. Automotive Tier-1 suppliers are qualifying 12-micron pixel arrays for night-vision modules at production scales. This convergence is compressing the cost gap between thermal and visible-light camera modules for driver monitoring.
Japan's METI energy efficiency benchmarks are tightening standby power requirements for consumer electronics thermopiles. Manufacturers must redesign analog front-end circuits to meet sub-milliwatt thresholds. Consumer appliance OEMs in Osaka and Nagoya are qualifying redesigned sensor modules ahead of 2027 enforcement.
Building automation procurement is consolidating around integrated sensor-to-cloud platforms. Facility managers are rejecting discrete component sourcing in favor of bundled hardware-software-service contracts. This pattern is most pronounced in German commercial real estate, where CSRD reporting obligations drive unified energy and occupancy data collection.
Infrared Sensors Market Segmentation
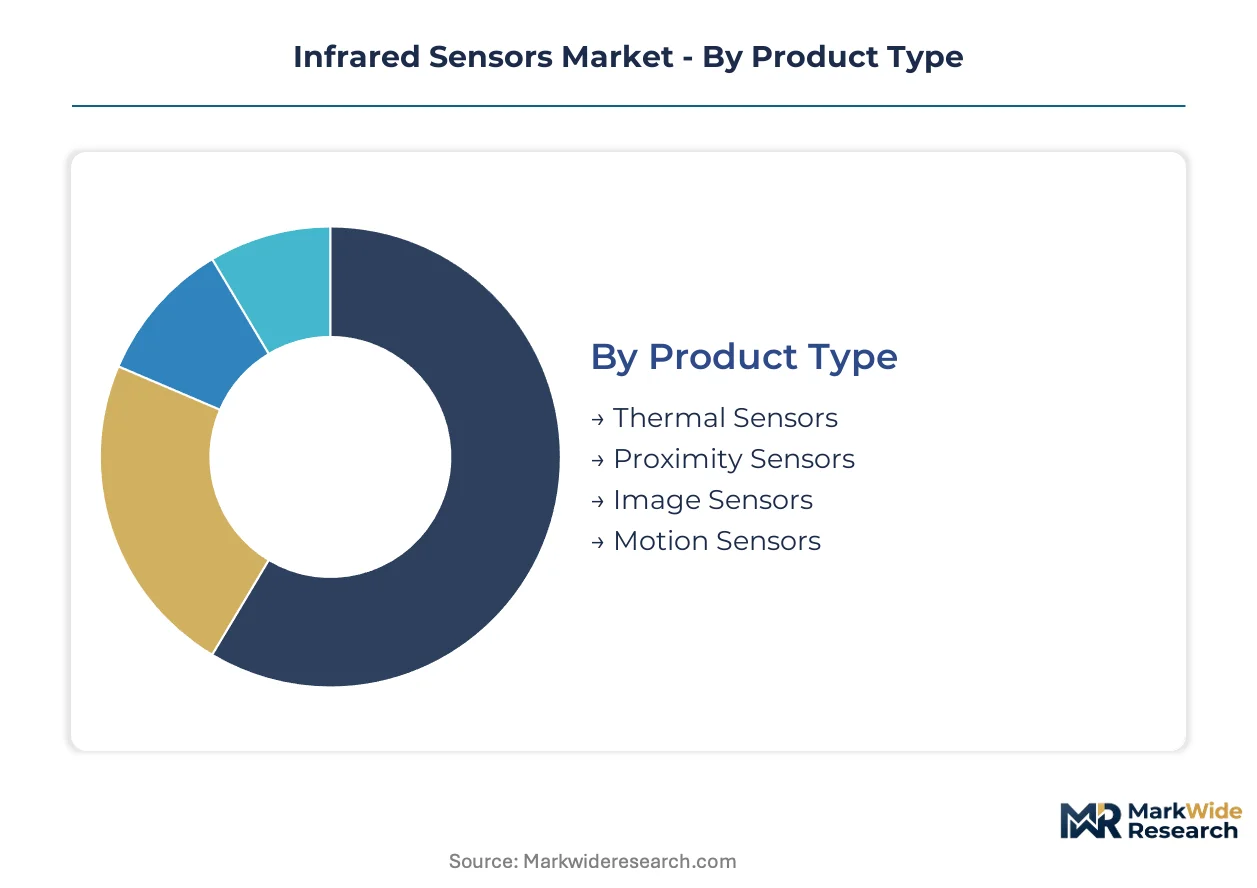
Infrared sensor architectures fragment sharply between cost-optimized volume applications and performance-critical instrumentation. Detector cooling requirements, pixel pitch specifications, and integration complexity create distinct procurement patterns across each segment boundary.
Product Type:
Volume concentration clusters in uncooled arrays for commercial deployment, while premium tiers demand cooled photon detectors for scientific and military specifications.
- Thermal Sensors:Thermopile and pyroelectric elements measure absolute temperature through Seebeck effect voltage generation. German industrial process control and Japanese appliance OEMs anchor procurement for non-contact pyrometry.
- Proximity Sensors:Active infrared emitters paired with photodiodes detect object presence through reflected signal modulation. Automotive gesture recognition and smartphone near-field detection are pulling emitter-detector module volumes from Taiwanese packaging houses.
- Image Sensors:Microbolometer focal plane arrays convert thermal radiation into electrical resistance changes without cryogenic cooling. Surveillance camera OEMs in Shenzhen and security integrators across the US Southwest dominate deployment.
- Motion Sensors:Passive infrared pyroelectric detectors sense differential thermal signatures from moving bodies. Smart building automation in German commercial real estate and Indian residential security installations are expanding multisensor node deployment.
Mature deployment sits with thermal sensors. Newer deployment is concentrated in motion sensors.
Application:
Customer procurement patterns diverge between regulated safety systems and discretionary consumer electronics, with automotive qualification timelines creating the steepest entry barriers.
- Heating:Temperature feedback loops in industrial furnaces and residential HVAC systems rely on thermopile arrays for flame monitoring and thermal efficiency optimization. European boiler manufacturers under Ecodesign directives are mandating precision infrared control modules.
- Surveillance:Perimeter security and border monitoring deploy cooled long-wave infrared imagers for detection through obscurants. US-Mexico border infrastructure and critical facility protection in Saudi Arabia sustain demand for high-resolution thermal cameras.
- Automotive Safety:Night-vision modules and cabin occupancy monitors integrate microbolometer arrays behind germanium optics. German Tier-1 suppliers and Japanese OEMs are qualifying 12-micron pixel pitch arrays for production vehicle integration.
- Consumer Electronics:Thermopile arrays enable ear-worn temperature monitoring and smartphone thermal cameras. Osaka-based appliance brands and Shenzhen wearable manufacturers are driving sub-milliwatt power specification requirements.
Procurement maturity centers on heating applications. Steepest expansion trajectory belongs to automotive safety.
End User:
Specification intensity escalates from commercial quality thresholds through aerospace reliability certification, with healthcare and security demanding intermediate validation rigor.
- Manufacturing:Process control, predictive maintenance, and quality inspection deploy infrared thermography for non-destructive testing. German automotive stamping operations and Chinese steel mills are standardizing thermal monitoring for equipment failure prevention.
- Healthcare:Medical thermography and spectroscopic diagnostic instruments require FDA 510(k) clearance or CE-MDR certification. US dermatology clinics and Japanese fever screening deployments are expanding clinical-grade infrared device procurement.
- Aerospace:Satellite earth observation and aircraft engine monitoring demand hermetically sealed cooled detectors with decade-plus operational lifetimes. European Space Agency programs and NASA earth science missions concentrate qualification-tested focal plane array procurement.
- Security:Force protection and critical infrastructure monitoring integrate multispectral imaging with radar and visible-light fusion. Israeli border technology providers and Australian mining site operators are deploying integrated threat detection platforms.
Established procurement patterns define manufacturing. Security applications are gaining share fastest.
Technology:
Cost structure stratification separates ambient-temperature microbolometers from cryogenically cooled quantum well architectures, with active infrared occupying the lowest unit-cost tier.
- Active Infrared:Near-infrared LED emitters paired with silicon photodetectors enable short-range proximity and communication functions. Chinese smartphone assembly lines and Korean automotive interior suppliers consume the highest emitter-detector pair volumes.
- Passive Infrared:Pyroelectric and thermopile detectors sense thermal radiation without emitted energy, minimizing power consumption and detection signature. Indian residential security installers and Brazilian commercial building automation integrators are expanding PIR node deployment.
- Quantum Well:Inter-subband absorption in gallium arsenide heterostructures enables high-speed mid-wave infrared detection with liquid nitrogen cooling. US military reconnaissance platforms and European scientific instrumentation manufacturers specify these for performance-critical applications.
- Microbolometer:Vanadium oxide or amorphous silicon resistor arrays operate at ambient temperature with MEMS-fabricated thermal isolation structures. Chinese thermal camera OEMs and US firefighting equipment suppliers are driving wafer-scale packaging cost reduction.
Technology maturity resides with active infrared. Microbolometer architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhongguancun Science Park and other high-technology zones in Beijing concentrate microbolometer design houses serving domestic thermal camera manufacturers. National policy support for semiconductor self-sufficiency is accelerating local foundry investments.
China
Domestic automotive OEMs in Shanghai and Shenzhen are qualifying 12-micron pixel microbolometers for night-vision modules. MIIT industrial standards for automotive electronics are tightening electromagnetic compatibility requirements. Wuhan and Xi'an host the principal indium refining and detector-grade material processing facilities.
Germany
Industrial automation integrators in Munich and Stuttgart are deploying thermopile arrays for predictive maintenance in automotive stamping operations. The EU F-Gas Regulation phase-down is mandating infrared absorption analyzers for hydrofluorocarbon leak detection. Dresden and Freiburg concentrate MEMS foundry capacity for automotive-qualified sensors.
Japan
Osaka-based appliance OEMs are redesigning thermopile modules to meet METI's sub-milliwatt standby power requirements ahead of 2027 enforcement. JIS standards for consumer electronics certification are elevating testing documentation burdens. Nagoya and Kyoto host the principal packaging houses for emitter-detector pairs.
United States
Border infrastructure contractors in Texas and Arizona are procuring cooled long-wave infrared imagers for perimeter security applications. FDA 21 CFR standards regulate medical thermography devices for clinical screening deployments. Greater Boston and the Pacific Northwest concentrate aerospace focal plane array qualification facilities.
India
Commercial building automation installers in Mumbai and Bangalore are expanding passive infrared node deployment for smart HVAC systems. BIS certification requirements for process control equipment are creating localized assembly demand. Gujarat and Tamil Nadu are emerging as contract manufacturing hubs for non-contact temperature sensors.
Infrared Sensors Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated detector fabricators commanding premium pricing in aerospace and military applications while MEMS foundry partners capture volume in consumer electronics. The vendor base organizes into three tiers: established defense contractors with captive cleanroom facilities, mid-scale industrial specialists with regional qualification expertise, and fabless design houses leveraging Taiwanese packaging capacity. Strategic moves center on backward integration into indium gallium arsenide epitaxy and geographic expansion into Indian industrial automation markets.
Among Japanese photonics specialists, Hamamatsu Photonics K.K. exemplifies the precision instrumentation archetype with decades of detector manufacturing heritage. Texas Instruments Incorporated represents the scale-driven MEMS integration model, leveraging mature semiconductor infrastructure for cost-optimized thermopile production. Teledyne Technologies occupies a position within the vertically integrated tier, anchoring high-reliability aerospace contracts through captive fabrication capabilities.
| Leading Market Players |
|---|
| Teledyne Technologies |
| Texas Instruments Incorporated |
| Murata Manufacturing Co., Ltd. |
| Honeywell International Inc. |
| Excelitas Technologies Corp. |
| Lynred |
| Raytheon Technologies Corporation |
| Hamamatsu Photonics K.K. |
| FLIR Systems |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between ITAR-restricted focal plane arrays and commercial uncooled microbolometers manifests in both pricing premiums and supply chain fragmentation, with aerospace-qualified detectors commanding order-of-magnitude markups while commodity thermopiles flow through Taiwanese packaging houses. European REACH mercury-free mandates and US EPA energy efficiency benchmarks further stratify procurement, as compliant suppliers capture pricing power while non-compliant fabricators face exclusion from regulated end markets.
Pricing Analysis
Lead-time compression premiums dominate aerospace and defense procurement, with ITAR-classified focal plane arrays priced at substantial premiums for sub-quarter delivery against standard 12-month qualification timelines. Pricing stratifies across military-grade cryogenic detectors, automotive-qualified microbolometers, and consumer thermopiles, with differentiation anchored in pixel pitch specifications and hermetic sealing standards. Cost compression in consumer-grade thermopiles is intensifying because Osaka-based appliance OEMs are consolidating supplier bases around sub-milliwatt power specifications. Commercial building automation integrators exhibit highest price sensitivity, while satellite earth observation programs demonstrate minimal elasticity given decade-long mission requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese indium refining, where detector-grade material processing concentrates in Wuhan and Xi'an smelters exposing Western fabricators to export restriction risk. German MEMS foundries in Dresden and Freiburg, Japanese packaging houses in Nagoya and Kyoto, and Taiwanese emitter-detector assembly lines feed downstream integration. Raw material dependencies center on high-purity indium, germanium optics substrates, and vanadium oxide thin-film deposition precursors. Tariff exposure runs through US-China technology trade classifications for dual-use thermal imaging components. Distribution runs through authorized distributors for ITAR-controlled products and direct OEM relationships for commercial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance cost escalation under European REACH, US ITAR/EAR, and Japanese METI standards has erected formidable barrier-to-entry moats, positioning certified incumbents to capture margin expansion as regulatory stringency intensifies across detector material and energy efficiency mandates.
For Market Incumbents: Lock in aerospace qualification pipelines through captive indium gallium arsenide epitaxy capacity, insulating against Chinese supply disruption while securing decade-long satellite mission contracts. Deepen backward integration into mercury-free detector materials ahead of European enforcement timelines, converting regulatory compliance into pricing power over unprepared rivals.
For New Entrants and Emerging Players: Launch via modular thermopile arrays targeting Indian industrial automation, where BIS certification requirements favor localized assembly partnerships over established import channels. Penetrate German commercial building automation through bundled sensor-to-cloud platforms, exploiting CSRD reporting obligations that favor unified energy and occupancy data procurement over discrete component sourcing.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to defense contractors seeking MEMS fabrication capabilities, with IPO viability tethered to demonstrated automotive qualification pipeline conversion. Acquisition target archetypes include fabless microbolometer design houses with 12-micron pixel pitch roadmaps and established Tier-1 supplier relationships. Monitor ITAR/EAR classification threshold adjustments as the signal for strategic repositioning around dual-use thermal imaging restrictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Materials | Captive indium gallium arsenide epitaxy secures supply continuity against Chinese export restrictions. |
| Automotive Qualification Pipeline | 12-micron pixel microbolometer certification with German Tier-1 suppliers opens production vehicle integration. |
| Mercury-Free Material Transition | European REACH compliance conversion protects market access while disqualifying non-compliant competitors. |
| Edge AI Thermal Fusion Development | On-chip neural processing integration with microbolometer arrays enables real-time threat classification without cloud dependency. |
| Indian Localization Partnership | BIS certification-aligned assembly in Gujarat and Tamil Nadu satisfies process control equipment mandates. |
Methodological Framework
Multi-period observation of automotive qualification timelines, regulatory enforcement trajectories, and foundry capacity utilization anchored the trend analysis, supplemented by interviews with MEMS process engineers, automotive Tier-1 procurement directors, satellite mission assurance officers, and building automation integrators. Secondary validation drew from MIIT industrial standards filings, EU REACH substance restriction updates, FDA 510(k) clearance databases, and SEC supplier disclosure filings. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches distributed value projections across detector cooling requirements, pixel pitch specifications, and integration complexity tiers, with technology adoption curves modeled for microbolometer, quantum well, thermopile, and active infrared architectures. CAGRs were derived from fitted growth trajectories against historical qualification cycle data and OEM platform deployment schedules. Forecast inputs incorporated indium price volatility assumptions and automotive night-vision module penetration sensitivity.
The model assumes a particular technology adoption path; alternative pathways for silicon photonics substitution in short-wave infrared imaging would alter the outlook through accelerated CMOS displacement. Forecasts reflect assumptions regarding regulatory enforcement consistency, automotive platform standardization timelines, and export control classification stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
Pressure Transducer Market