
 Inline Viscosity Sensor Market | 2026-2036
Inline Viscosity Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Inline Viscosity Sensor Market Intelligence
The application mix for inline viscosity sensors is hardening toward high-value sectors like polymer production and cosmetics manufacturing. Hydramotion leverages its specialization in vibrational sensor technology to serve these demanding process environments. Brookfield Engineering sustains its market position through a broad product portfolio catering to both laboratory and process applications. Emerson Electric integrates these sensors into larger process automation and control systems for major industrial clients.
An inline viscosity sensor is a device installed directly into a process pipeline to continuously measure the flow resistance of a fluid. It provides real-time data without sample extraction, enabling automated control to maintain product quality and optimize material usage. Vibrational and rotational technologies are the leading product types, valued for their reliability across diverse operating conditions. The paints & coatings application segment offers high-margin opportunities for sensors that handle abrasive or high-temperature fluids.
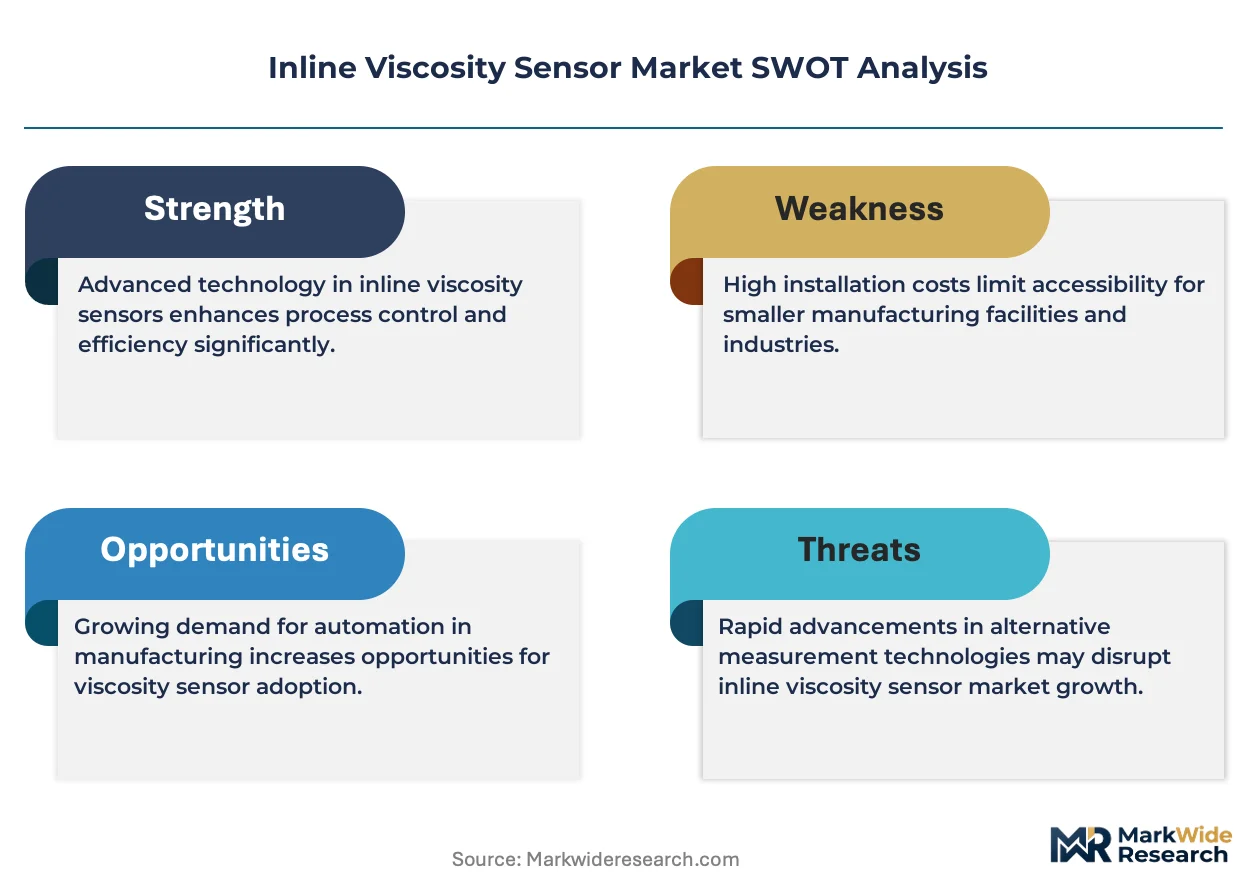
Process control requirements under regulations like the US FDA's rules for pharmaceuticals and Europe's REACH directive for chemicals influence sensor design and material selection. Adherence to ISO 9001 quality management systems in manufacturing facilities often necessitates the documented, continuous process monitoring that these sensors provide. Sensor manufacturers must decide whether to focus on standardized, high-volume products or develop specialized, high-margin solutions for niche process challenges.
Market Dynamics
The intensification of quality control mandates in pharmaceutical and food processing is the central force shaping sensor development. Regulations from bodies like the FDA and EFSA demand real-time monitoring, directly driving sensor design and adoption.
Growth Catalysts
- Stringent Quality Mandates:
Regulations from the FDA and EFSA require documented process control in food and pharma, necessitating real-time viscosity monitoring.
- High-Value Sector Expansion:
Growth in polymer and cosmetics manufacturing, which depend on precise fluid properties, drives adoption of specialized, high-performance sensors.
- Process Automation:
Integrating sensors into automated control systems to optimize material usage and ensure consistent quality is a primary catalyst in industrial settings.
Market Restraints
- High Initial Capital Outlay:
The significant upfront cost of high-precision sensors is a barrier for smaller manufacturers in the food and beverage industry.
- Abrasive Fluid Measurement:
Sensors suffer accelerated wear when measuring abrasive materials like paints, leading to higher maintenance costs and downtime.
- Competition from Offline Methods:
Lower-cost laboratory viscometers for batch testing remain a substitute in non-critical processes, limiting inline adoption.
Strategic Opportunities
- Biopharmaceutical Processing:
The biologics sector requires sterile, single-use sensors for monitoring cell culture media, creating a high-value niche.
- Food Sector in Southeast Asia:
Rising quality standards in Vietnam and Indonesia create an underpenetrated market for process control instruments in food manufacturing.
- AI-Enabled Predictive Analytics:
Integrating sensor data with machine learning enables predictive maintenance and process optimization, offering new value-added services.
Industry Challenges
- Legacy System Integration:
Integrating modern digital sensors with older analog plant control infrastructure poses significant technical and cost challenges for established facilities.
- Complex Certification Pathways:
Obtaining certifications for hazardous environments like ATEX or hygienic applications under EHEDG guidelines is a complex and costly process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inline Viscosity Sensor Market |
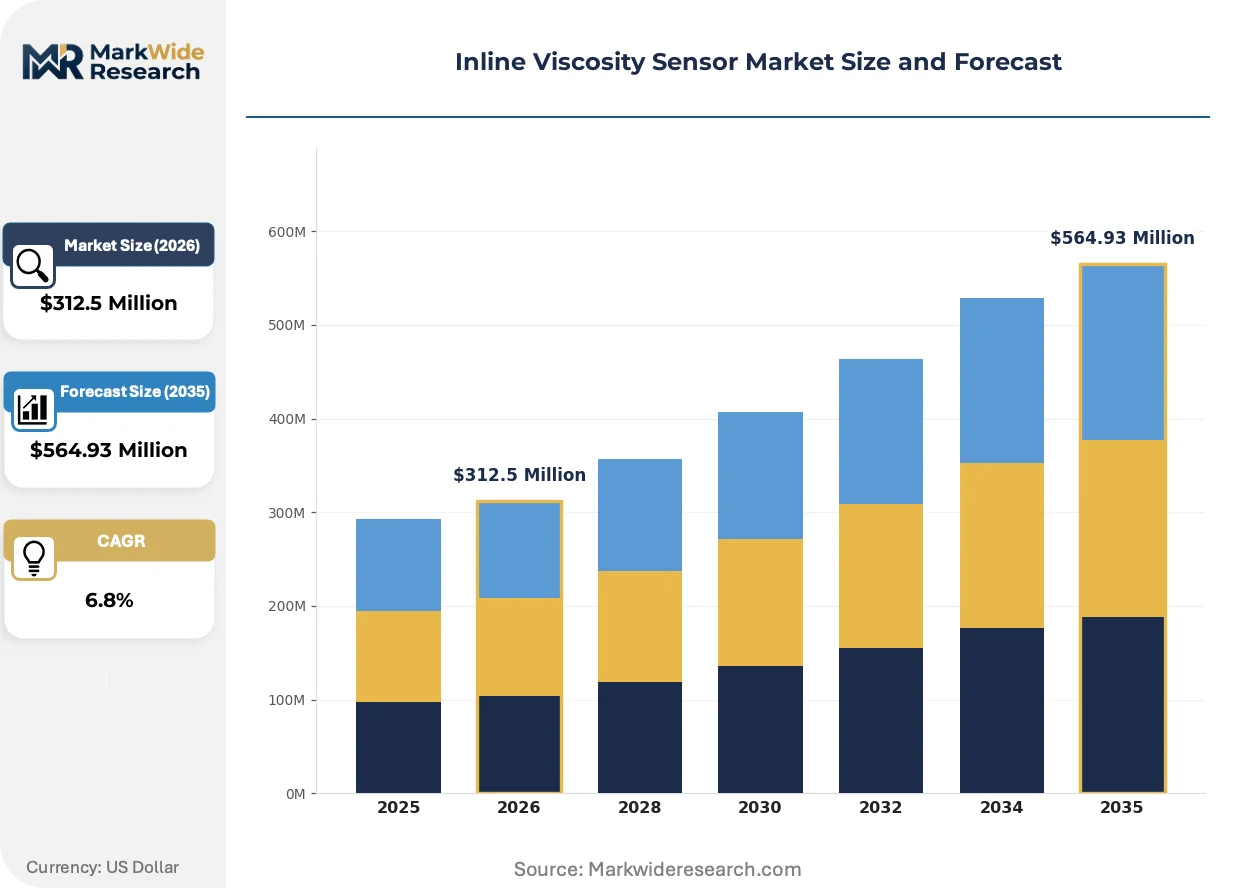
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotational, Vibrational, Capillary, Microfluidic, Ultraviolet Technology: Electromagnetic, Optical, Piezoelectric, Ultrasonic, Thermal Application: Petrochemical Processing, Food & Beverage, Paints & Coatings, Cosmetics Manufacturing, Polymer Production End User: Chemical Producers, Beverage Manufacturers, Paint Plants, Cosmetics Companies, Polymer Fabricators |
| Companies Covered | Hydramotion, VAF Instruments, Brookfield Engineering, AVENISENSE, Parker Hannifin, Emerson Electric, Cambridge Viscosity, Martechnic GmbH, Anton Paar GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inline Viscosity Sensor Market Strategic Shifts & Innovations
Sensor design is evolving toward greater specialization for extreme process environments. This shift is accompanied by deeper integration of sensor data into plant-wide digital ecosystems for advanced analytics.
Micro-electro-mechanical systems (MEMS) technology enables miniaturized, low-power viscosity sensors. The biopharmaceutical and medical device sectors are early adopters, valuing their small footprint for lab-on-a-chip devices. This miniaturization is converging with the need for disposable sensors, reducing cross-contamination risks in sterile applications.
Europe's REACH directive imposes strict documentation requirements on chemical manufacturers. This regulation necessitates continuous process verification to ensure products consistently meet viscosity specifications. Consequently, chemical producers in the EU are retrofitting lines with inline sensors to automate compliance reporting and reduce manual sampling.
A preference is emerging for service-based models where customers pay for process data and uptime instead of owning the hardware. This model disrupts traditional sales channels, replacing them with long-term monitoring contracts. The shift is most prominent among large chemical clients in Germany and the United States converting capex to opex.
Inline Viscosity Sensor Market Segmentation
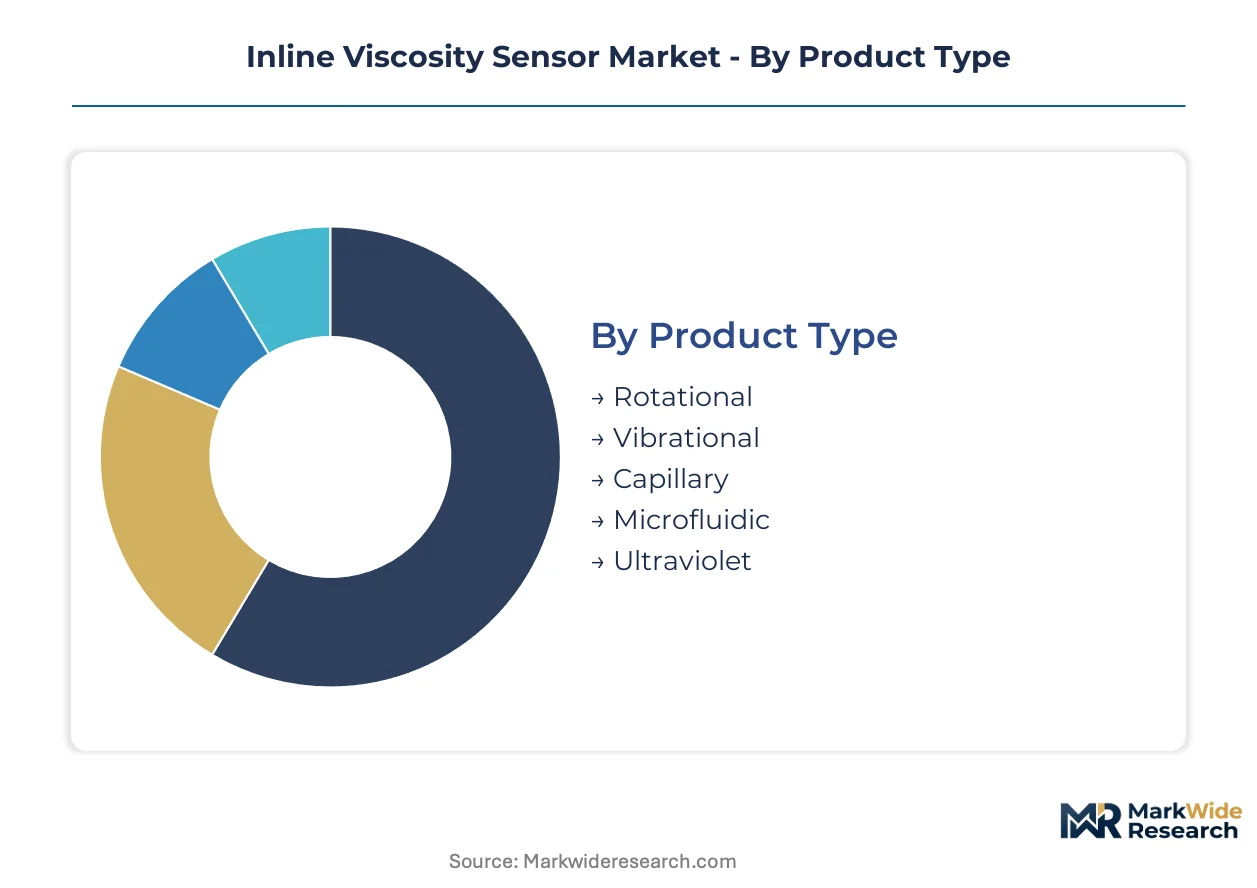
The inline viscosity sensor market is segmented to reflect the diverse requirements of industrial processes. Understanding these distinct categories helps in identifying specific demand patterns and technological preferences across various end-use sectors. This segmentation highlights the critical role of continuous fluid property monitoring in modern manufacturing.
Product Type:
Buyers in the inline viscosity sensor market differentiate their choices primarily based on the physical principle employed for measurement.
- Vibrational:These sensors determine viscosity by measuring the damping of an oscillating element immersed in the fluid. They are highly valued in polymer production and cosmetics manufacturing for their precision in demanding process environments.
- Rotational:This product type measures the torque required to rotate a spindle within the fluid, providing direct viscosity readings. Rotational sensors maintain a strong market position due to their broad applicability across general process control.
- Capillary:Capillary sensors measure the flow rate of a fluid through a narrow tube under a defined pressure. These are often used for Newtonian fluids in laboratory settings.
- Microfluidic:This miniaturized sensor type is designed for extremely small sample volumes and integrated into lab-on-a-chip devices. The biopharmaceutical sector increasingly adopts microfluidic sensors for sterile applications.
- Ultraviolet:While less common for direct viscosity measurement, ultraviolet sensors are sometimes integrated to monitor specific material properties that correlate with fluid resistance.
Volume sits with Rotational sensors; growth tilts toward Microfluidic solutions.
Technology:
Cost tiers for inline viscosity sensors often correlate with the underlying measurement technology utilized.
- Piezoelectric:This technology converts mechanical stress into electrical signals, enabling the creation of miniaturized MEMS sensors. Biopharmaceutical processing leverages piezoelectric sensors for sterile, single-use applications.
- Ultrasonic:Ultrasonic sensors use sound waves to measure fluid properties, offering non-invasive and wear-resistant solutions. They find utility in handling abrasive materials within the paints and coatings segment.
- Electromagnetic:Electromagnetic sensors detect changes in electromagnetic fields as fluid passes, often applied in conductive liquid measurements.
- Optical:Optical technology employs light interaction with the fluid to determine viscosity, suitable for transparent or translucent process streams.
- Thermal:Thermal sensors infer viscosity by measuring heat transfer properties within the fluid, particularly effective in high-temperature applications.
The integration of advanced technologies like piezoelectric elements drives sensor innovation.
Application:
The specific application dictates the required sensor robustness and precision, influencing material selection and design.
- Food & Beverage:This segment requires sensors with hygienic design and compliance with regulations from bodies like the US FDA and EFSA. They are essential for process control in dairy and confectionery applications.
- Polymer Production:Demands for high-precision sensors are pronounced in polymer production to control melt viscosity and ensure consistent material properties. This is a high-value sector for advanced sensor solutions.
- Petrochemical Processing:Sensors in petrochemical processing monitor crude oil and refined products, ensuring quality and optimizing refining efficiency.
- Paints & Coatings:This segment presents high-margin opportunities for sensors capable of handling abrasive or high-temperature fluids without accelerated wear.
- Cosmetics Manufacturing:Inline viscosity sensors ensure consistent texture, stability, and quality for various cosmetic products, from creams to lotions.
High-margin opportunities emerge from specialized applications like paints and coatings.
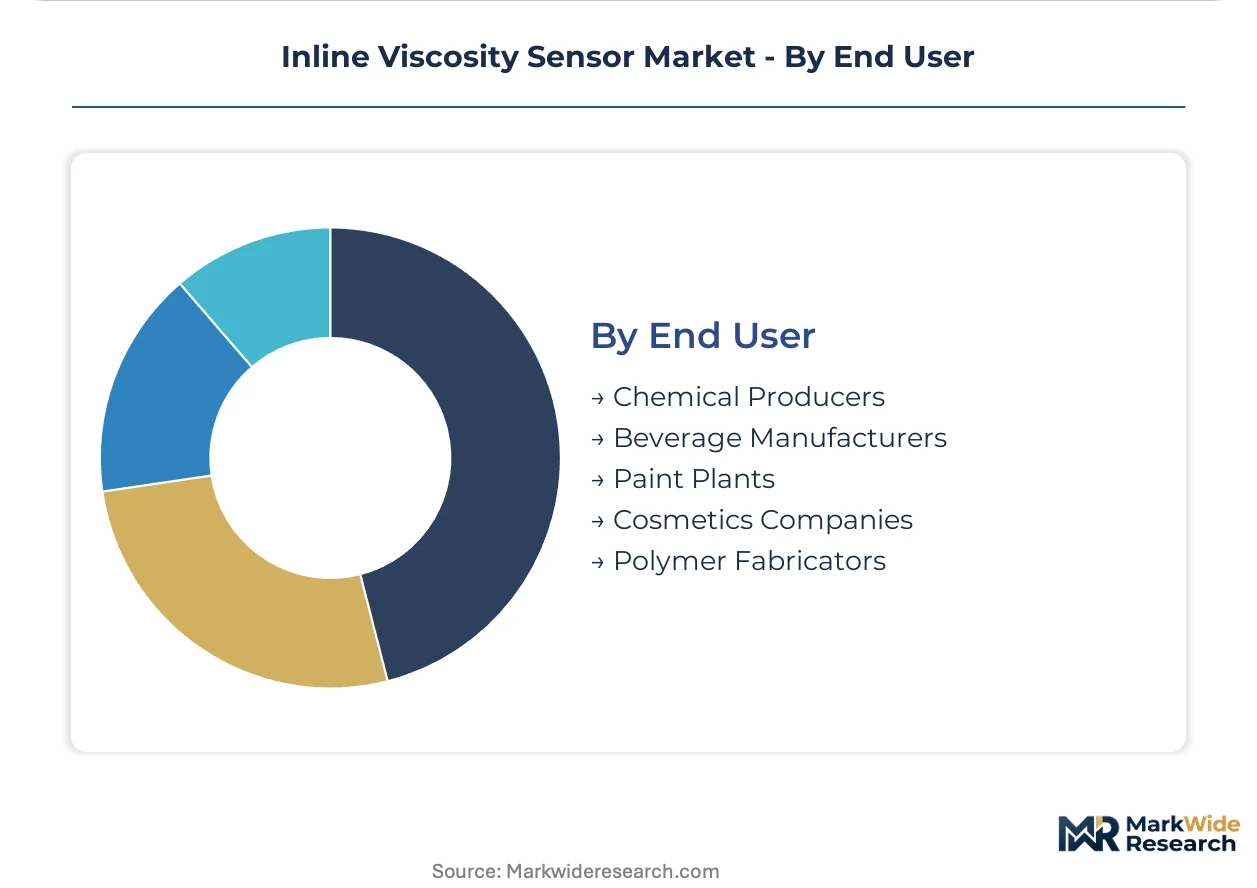
End User:
Customer type often defines the scale of deployment and the level of integration required for inline viscosity sensors.
- Chemical Producers:These users integrate sensors for compliance with directives such as Europe's REACH, necessitating continuous process verification. Large chemical clients often seek integration into broader automation systems.
- Beverage Manufacturers:They implement real-time monitoring for product consistency and adherence to food safety standards mandated by regulators like the US FDA. This ensures consistent quality in drinks production.
- Paint Plants:Paint plants utilize inline sensors to maintain desired product consistency, reduce rework, and optimize material usage during production.
- Cosmetics Companies:These companies rely on sensors for precise control of product texture, stability, and batch-to-batch consistency in their manufacturing processes.
- Polymer Fabricators:Polymer fabricators deploy sensors to optimize material properties, control polymerization reactions, and ensure the final product meets specifications.
The demand from polymer fabricators for high-performance sensors is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for inline viscosity sensors is concentrating within established industrial hubs, driven by process optimization needs and regulatory compliance. These regions benefit from robust manufacturing infrastructure and stringent quality control mandates. Strategic investments in advanced manufacturing zones further accelerate sensor adoption.
United States
United States manufacturers require inline viscosity sensors for precise control in polymer production and biopharmaceutical processing. US FDA regulations for pharmaceuticals mandate continuous process monitoring to ensure product quality and safety. Chemical processing hubs in Texas and Louisiana are retrofitting facilities with advanced sensors for improved operational efficiency.
Germany
German chemical producers and automotive manufacturers integrate inline viscosity sensors for compliance and product consistency. Europe's REACH directive imposes strict documentation requirements on chemical manufacturers, necessitating continuous process verification. Industrial centers in North Rhine-Westphalia are adopting service-based sensor models to convert capital expenditure to operational expenditure.
China
China's expanding chemical manufacturing and food processing sectors increasingly adopt inline viscosity sensors for quality control. The country's GB standards for industrial products and food safety regulations drive the need for real-time fluid property monitoring. The Yangtze River Delta region sees significant sensor deployment in large-scale industrial plants.
Japan
Japanese industries, particularly in high-tech materials and precision manufacturing, demand advanced inline viscosity sensors. JIS standards for industrial equipment and quality management systems encourage continuous process improvement across various sectors. The Kanto region, including Tokyo, is a hub for sensor innovation and integration into automated production lines.
India
Indian pharmaceutical production and the rapidly modernizing food & beverage industry are driving sensor adoption. CDSCO guidelines for pharmaceuticals necessitate robust process control, including real-time viscosity measurement. Pharmaceutical clusters in Gujarat and Hyderabad are investing in inline sensors for enhanced quality assurance and regulatory adherence.
Inline Viscosity Sensor Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied customer needs and integration complexities. The market exhibits a tiered structure, with established industrial players alongside specialized technology providers catering to specific process environments. Strategic archetypes include broad portfolio providers, niche technology experts focusing on advanced measurement principles, and system integrators embedding sensors into larger automation platforms. Portfolio diversification and strategic partnerships represent dominant competitive moves among these participants.
Within the broad portfolio provider archetype, Brookfield Engineering maintains a significant presence across diverse applications, serving both laboratory and process measurement needs. Hydramotion exemplifies a specialized approach, leveraging its vibrational sensor technology to address demanding process environments where precision is paramount. Emerson Electric, a major industrial automation firm, represents the system integrator archetype, embedding inline viscosity sensors into comprehensive control solutions for major industrial clients globally. These companies collectively shape the competitive dynamics through their distinct market strategies and technological focuses, catering to varied customer requirements.
| Leading Market Players |
|---|
| Hydramotion |
| VAF Instruments |
| Brookfield Engineering |
| AVENISENSE |
| Parker Hannifin |
| Emerson Electric |
| Cambridge Viscosity |
| Martechnic GmbH |
| Anton Paar GmbH |
| Others |
Cost & Logistics Intelligence
Precision engineering workforces concentrated in Germany and the United States influence the pricing tiers for advanced inline viscosity sensors, creating distinct spreads based on manufacturing location and expertise. This labor-cost differential impacts the final price points for high-performance units versus more standardized offerings.
Pricing Analysis
Lead-time-driven pricing for specialized inline viscosity sensors commands a premium, while readily available standard units often see discounts for spot inventory. The dominant pricing model remains per-unit transactional, though service-based models are emerging for large industrial clients. Price differentiation stems from certification levels, such as ATEX for hazardous environments, and the degree of customization for specific process integration. Pricing pressure intensifies on standard rotational sensors due to broader competition. Smaller food and beverage manufacturers exhibit higher price sensitivity compared to biopharmaceutical companies seeking validated, high-precision solutions.
Supply Chain Analysis
Reverse-logistics pathways for inline viscosity sensors include refurbishment programs for high-value units and proper disposal protocols for single-use microfluidic sensors. Geographic supply concentration for critical components rests in countries like Germany, Japan, and the United States for advanced piezoelectric elements and micro-electro-mechanical systems (MEMS). Raw material dependencies include specialized alloys for sensor probes and advanced polymers for hygienic designs. Single-source vulnerability for proprietary sensor technologies presents a structural supply chain risk. Distribution for inline viscosity sensors primarily runs through direct sales channels for major industrial clients and specialized technical distributors for smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently navigating a technology-transition phase, with miniaturized MEMS sensors gradually replacing bulkier, traditional inline viscosity measurement devices across specialized applications.
For Market Incumbents:
Hedge against the disruptive potential of microfluidic and AI-enabled sensor technologies by acquiring niche start-ups specializing in these areas. Invest heavily in R&D for new materials capable of withstanding extreme process environments and abrasive fluids, mitigating the threat of accelerated wear. Reinforce channel control in established industrial hubs like Germany and the United States through long-term service contracts. Deepen integration capabilities with existing plant automation systems to maintain competitive advantage.
For New Entrants and Emerging Players:
Price-point gaps between premium and economy tiers offer a clear entry opportunity for modular, cost-effective inline viscosity sensors. Target the underpenetrated food processing sector in Southeast Asia, where rising quality standards create demand for basic real-time monitoring solutions. Focus on developing disposable sensor solutions for the biopharmaceutical sector, leveraging the increasing need for sterile, single-use devices. A service-based go-to-market angle, offering data and uptime rather than hardware ownership, can attract capital-averse customers.
For Investors and Strategic Acquirers:
Re-rating potential sits with specialized sensor technology firms given the accelerating demand for high-precision process control and regulatory compliance. The long-term viability of this market is anchored in continuous industrial automation and stringent quality mandates. Target acquisition profiles include developers of MEMS-based sensors, companies with strong intellectual property in advanced material science, and firms offering AI-enabled predictive analytics platforms. Practitioners should monitor adoption rates of single-use sensors in biopharmaceutical manufacturing as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of specialized MEMS sensor developers | Expands product portfolio into miniaturized, high-growth applications, particularly in biopharma. |
| Investment in advanced material science R&D | Enhances sensor durability and performance in harsh, abrasive, or high-temperature industrial environments. |
| Development of service-based monitoring contracts | Shifts revenue model from CapEx to OpEx, attracting large industrial clients seeking long-term value. |
| Strategic partnerships with automation system integrators | Embeds sensors into broader industrial control platforms, expanding market reach and utility. |
| Expansion into Southeast Asian food processing markets | Captures early adoption in an underpenetrated region driven by evolving quality standards and regulations. |
Research Approach
Document review covered industry reports, regulatory guidelines from bodies like the FDA and EFSA, and patent databases, complemented by interviews with process engineers and R&D directors. Primary research involved conversations with procurement managers at chemical producers and regulatory compliance officers in the biopharmaceutical sector. This approach allowed for robust bottom-up and top-down triangulation of market data and trends.
Volume and value outputs were generated through a quantitative model that projects market dynamics across the analysis window. Segmentation dimensions modeled included product type, technology, application, end user, and regional regulatory stringency. Compound annual growth rates were derived from historical trends, projected industrial capital expenditures, and anticipated regulatory impacts. Key forecast inputs included global industrial production indices and biopharmaceutical R&D investment trends.
Inputs from company annual reports, industry associations, and regulatory bodies were available through the study window; gaps in emerging market adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Practitioners should monitor shifts in global manufacturing investment and new material science breakthroughs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Aspiration Control Systems Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Time of Flight (Tof) Sensor Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market