
 Machine Control System Market | 2026-2036
Machine Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Control System Market Intelligence
The ISO 15143-3 telematics standard is collapsing the data silos between different equipment brands and software platforms. This interoperability challenge is a key battleground where Trimble Inc. leverages its extensive software and hardware portfolio. Hexagon AB differentiates through its focus on sensor fusion and reality capture technologies for construction and mining. Caterpillar Inc. sustains its market position by integrating proprietary machine control systems directly into its heavy equipment fleet.
A machine control system integrates positioning data and onboard sensors to automate the operation of heavy machinery, achieving sub-centimeter accuracy for tasks like grading or excavation. Its primary purpose is to increase efficiency, reduce material waste, and improve safety on job sites. The construction application segment remains the largest volume driver, fueled by infrastructure development. Within technology, GNSS-based systems represent the fastest-growing segment due to their versatility and declining component costs compared to older laser guidance methods.
Regulations like the EU's Machinery Directive and safety standards from bodies like OSHA in the United States mandate features that drive system adoption. In parallel, initiatives from the U.S. Federal Highway Administration and China's promotion of digital construction under GB standards encourage the use of data-rich control systems. The critical decision for heavy equipment operators now centers on choosing between factory-integrated OEM systems and more flexible, multi-brand aftermarket solutions.
Market Dynamics
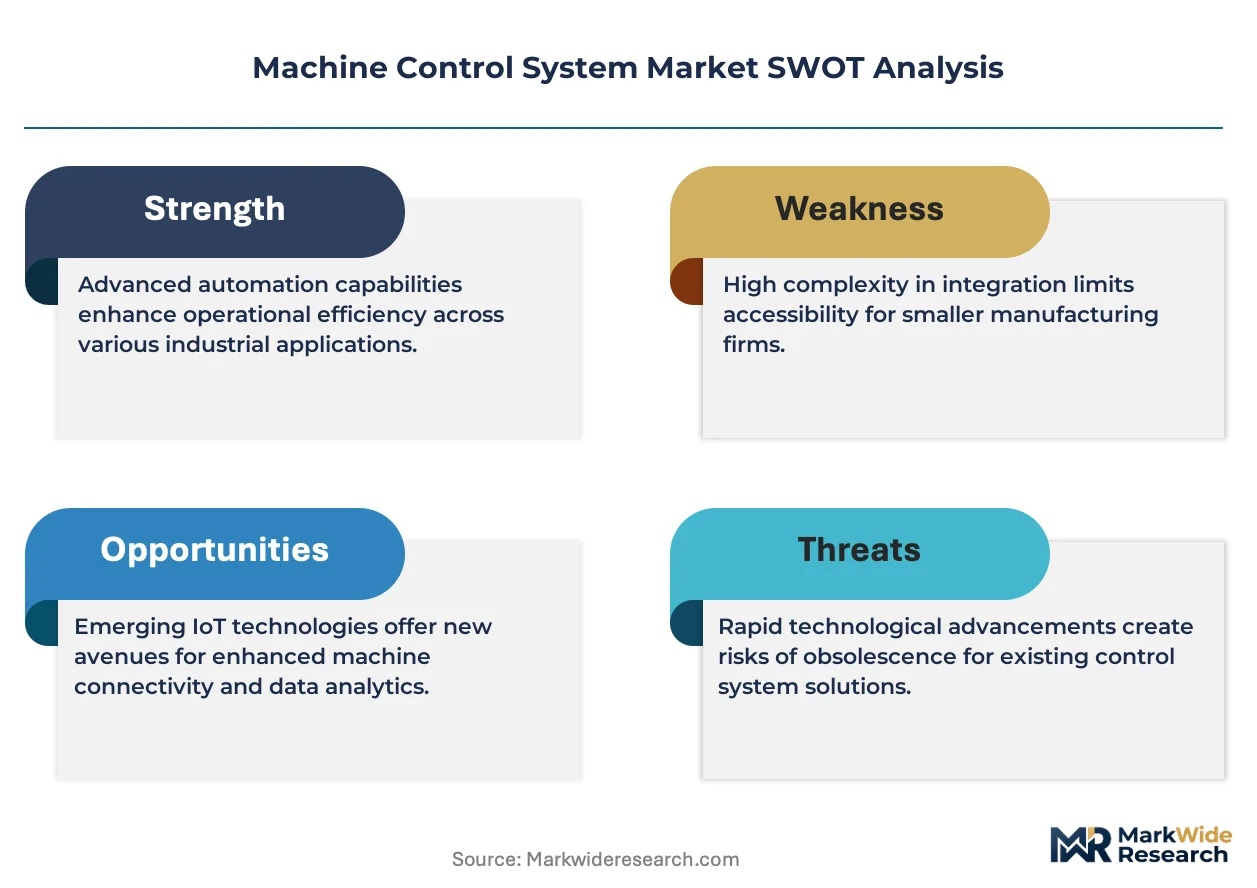
The market's central tension arises from the equipment operator's choice between proprietary, factory-integrated systems from a single OEM and more flexible, multi-brand aftermarket solutions. This decision is increasingly shaped by data interoperability standards like ISO 15143-3, which directly influence fleet management strategies and total cost of ownership.
Growth Catalysts
- Infrastructure Mandates:Government-funded projects, such as India's national highway development program, mandate advanced construction techniques, directly stimulating system adoption for efficiency and quality control.
- GNSS Accuracy:The increasing precision and falling cost of Global Navigation Satellite System (GNSS) components enable sub-centimeter accuracy, expanding applications in high-precision grading and excavation tasks.
- Large-Scale Construction:The construction sector's need for accelerated project timelines and reduced material waste on large-scale infrastructure like airports and dams serves as a primary catalyst for adoption.
Market Restraints
- High Initial Capital Outlay:The substantial upfront investment required for both hardware and software components presents a significant barrier for small to medium-sized contractors and rental companies.
- Data Interoperability Gaps:Despite standards like ISO 15143-3, achieving seamless data exchange between different OEM equipment and third-party software platforms remains a persistent technical hurdle.
- Legacy System Persistence:The continued use of simpler, less expensive laser-based guidance systems for certain grading applications slows the transition to more advanced GNSS-based solutions.
Strategic Opportunities
- Mining Sector Expansion:Applying machine control for autonomous hauling, drilling, and precise extraction in open-pit mining operations offers a significant avenue for growth beyond traditional construction.
- UAV and System Integration:Integrating drone-based survey data with machine control systems for real-time cut-and-fill calculations creates new workflows and improves overall job site management efficiency.
- Southeast Asian Infrastructure:Underpenetration in developing Southeast Asian economies presents a long-term opportunity as infrastructure investment in countries like Vietnam and Indonesia increases.
Industry Challenges
- Skilled Operator Scarcity:A shortage of technicians and operators proficient in managing and maintaining complex GNSS-based systems and associated software creates an operational bottleneck for contractors.
- Retrofitting Complexity:The technical difficulty and cost associated with retrofitting older heavy equipment fleets with modern aftermarket machine control systems challenge widespread adoption across existing assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Control System Market |
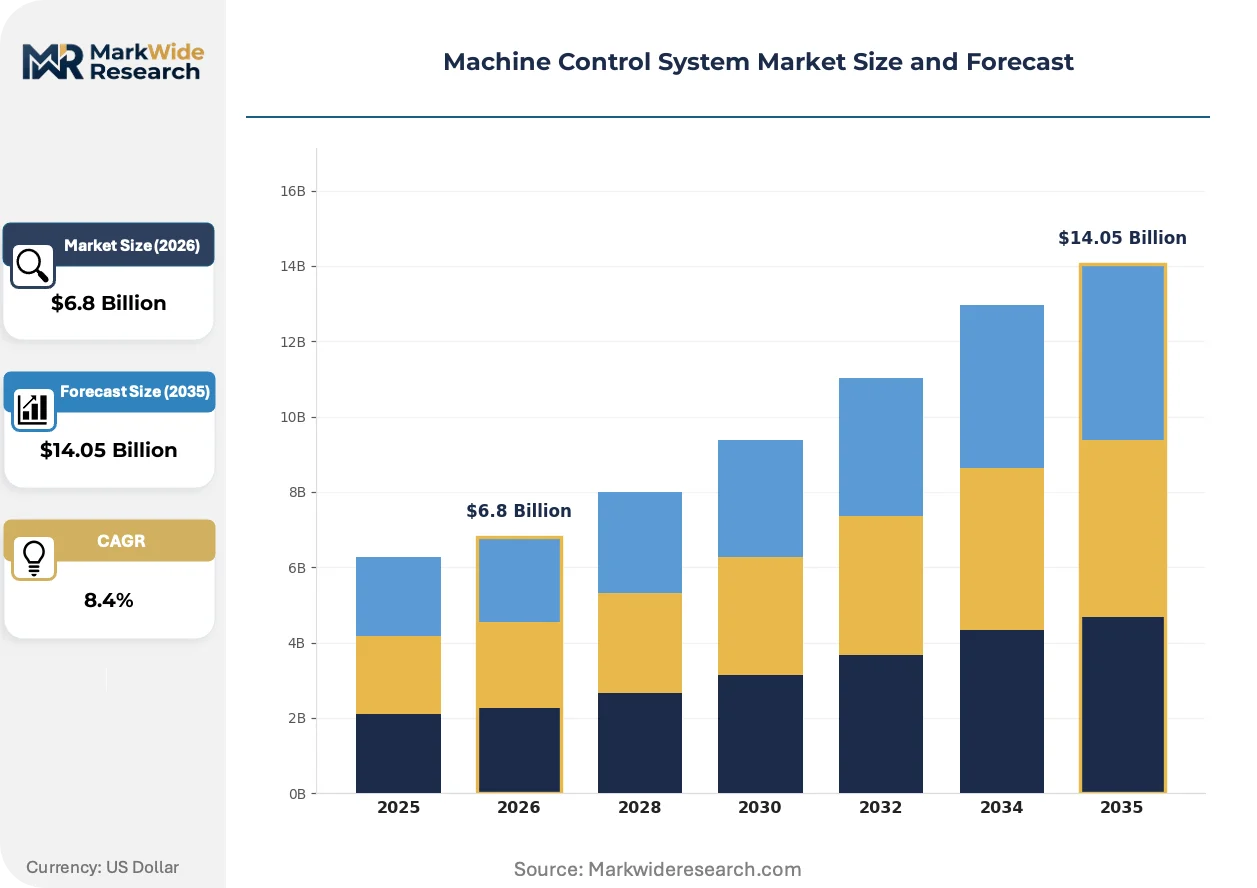
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Controller, Sensors, GPS Modules, Display Units, Data Collectors Technology: Laser Guidance, GNSS, Radar Systems, Inertial Measurement Units, Ultrasonic Sensors Application: Construction, Mining, Agriculture, Surveying, Forestry End User: Heavy Equipment Operators, Surveying Firms, Mining Companies, Agricultural Contractors |
| Companies Covered | MOBA Mobile Automation AG, Rockwell Automation, Trimble Inc., Caterpillar Inc., Deere & Company, Topcon Corporation, Hemisphere GNSS, Volvo Group, Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Control System Market Strategic Shifts & Innovations
The convergence of sensor fusion and telematics is elevating machine control from a simple guidance tool to a central nervous system for job site automation. This evolution emphasizes real-time data processing and interoperability across mixed equipment fleets, fundamentally altering site-level workflows.
Sensor fusion combines data from GNSS, inertial measurement units (IMUs), and vision cameras to provide continuous and accurate machine positioning, even during satellite signal loss. Heavy civil construction and mining operations are rapidly adopting these multi-sensor systems for critical tasks. This technology is bifurcating the market between basic GNSS guidance and premium, all-conditions automation solutions that command a higher price point.
Safety mandates, including the EU's Machinery Directive and OSHA standards in the United States, are compelling the integration of features like object detection and operator alerts. This regulatory pressure drives system complexity and requires vendors to meet stringent certification requirements for software and hardware. The earthmoving equipment segment is most affected, with manufacturers embedding these safety functions directly into factory-fit control systems.
Equipment owners are increasingly selecting systems based on software platform capabilities and data ownership policies, rather than solely on the hardware brand. This preference disrupts the traditional model of bundling proprietary hardware and software, creating an opening for open-architecture aftermarket providers. This behavioral shift is most visible in North American and European markets with large, mixed-fleet contractors seeking maximum flexibility.
Machine Control System Market Segmentation
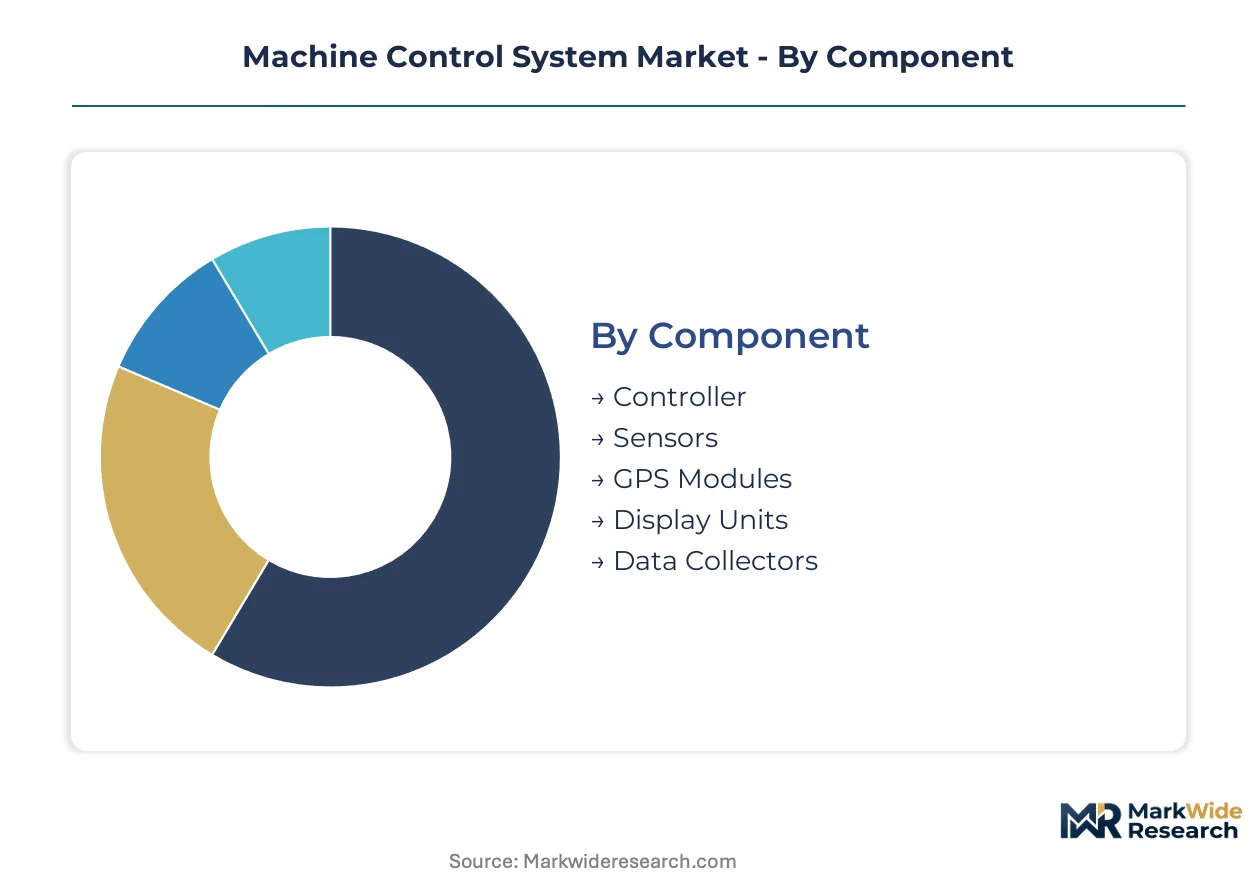
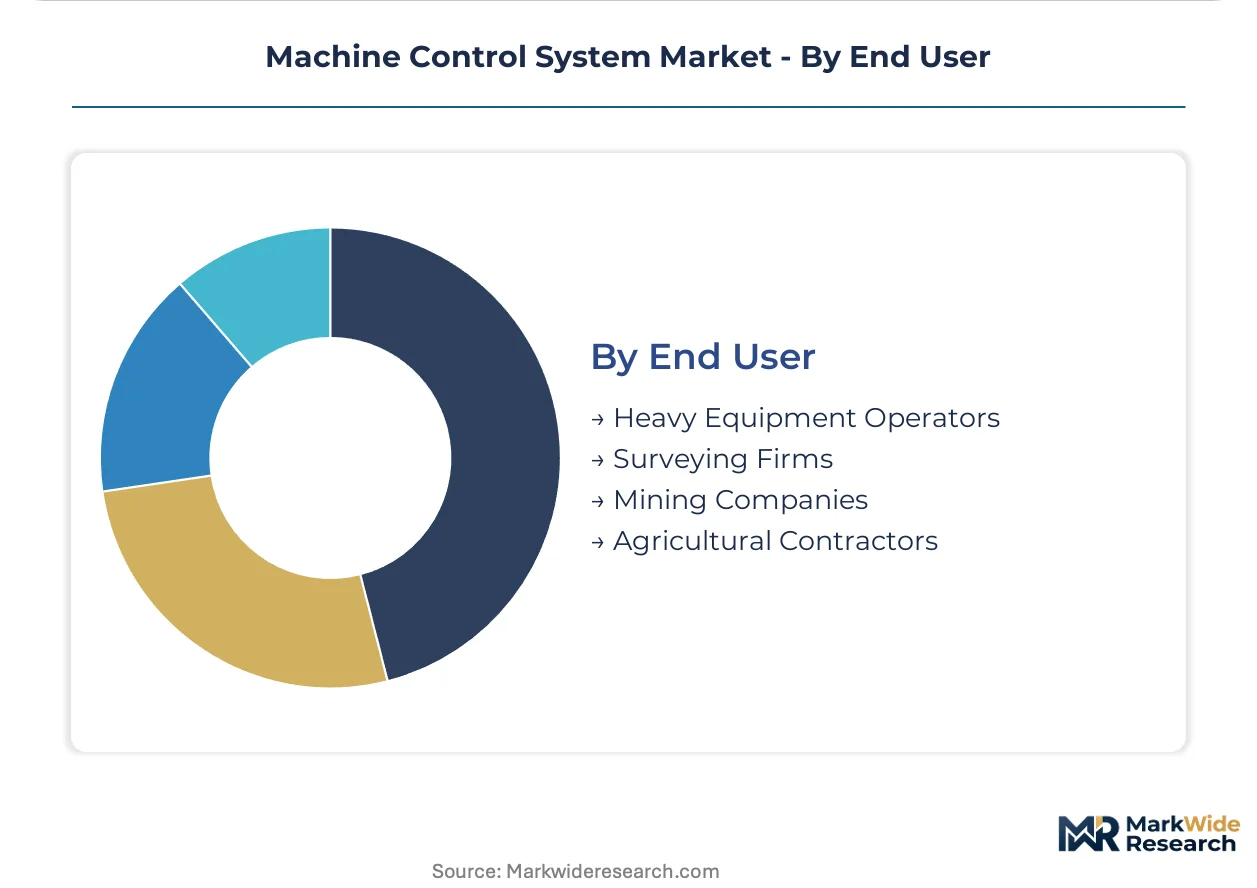
The Machine Control System Market is segmented across key dimensions, revealing distinct value propositions and growth trajectories. Understanding these categories helps clarify how different technologies and components address specific needs within diverse applications and end-user segments. This detailed breakdown highlights the varied demands driving innovation and adoption.
Component:
Margin pools within the component category often concentrate around the most sophisticated and data-intensive parts of the system.
- Controller:These central processing units integrate sensor inputs and execute machine commands, forming the intelligence core of any machine control system. Demand concentrates in advanced construction projects requiring complex automation and real-time data processing.
- GPS Modules:High-precision Global Navigation Satellite System (GNSS) modules provide sub-centimeter positioning data essential for accurate grading and excavation. Their declining component costs drive broader adoption in large-scale infrastructure development across India.
- Sensors:Various sensors, including IMUs and ultrasonic devices, provide real-time data on machine orientation, tilt, and proximity.
- Display Units:These human-machine interfaces present critical operational data and design plans to equipment operators in an intuitive format.
- Data Collectors:Handheld or vehicle-mounted devices gather and transmit project data, facilitating site management and progress tracking.
The dominant share belongs to Controller units, while GPS Modules are closing the gap fastest.
Technology:
Volume drivers within machine control technology are heavily influenced by the balance between precision requirements and overall system cost.
- GNSS:Global Navigation Satellite System technology provides highly accurate, real-time positioning for heavy equipment, crucial for achieving sub-centimeter precision in complex earthmoving tasks. Its versatility makes it the primary choice for modern infrastructure projects.
- Laser Guidance:This traditional technology uses rotating lasers and receivers to provide elevation and slope control, offering a cost-effective solution for simpler grading applications. It remains relevant for basic site preparation where extreme precision is not always required.
- Radar Systems:Radar systems enhance safety by detecting obstacles and monitoring proximity in challenging environments like mining operations.
- Inertial Measurement Units:IMUs complement GNSS by providing continuous orientation and motion data, crucial for maintaining accuracy during satellite signal loss.
- Ultrasonic Sensors:These sensors are used for short-range object detection and precise height control in specific applications, such as asphalt paving.
GNSS technology currently holds the largest market share, with Inertial Measurement Units experiencing the steepest expansion trajectory due to sensor fusion trends.
Application:
The maturity of machine control system adoption varies significantly across different application segments, reflecting distinct operational needs and investment cycles.
- Construction:This segment represents the largest application area, utilizing machine control for tasks like grading, excavation, and paving in large-scale infrastructure projects. Government-funded initiatives in highway development and smart cities drive sustained demand.
- Mining:Machine control systems are critical in mining for autonomous hauling, precise drilling, and ore extraction, enhancing safety and operational efficiency in harsh environments. Open-pit mining operations in particular benefit from advanced automation.
- Agriculture:Precision agriculture uses these systems for accurate planting, spraying, and harvesting, optimizing resource use and crop yields.
- Surveying:Machine control aids surveying firms in detailed site mapping, topographic analysis, and construction layout with high accuracy.
- Forestry:These systems assist in efficient logging operations, including precise felling and timber extraction, minimizing waste.
The Construction sector remains the largest volume driver, while the Mining sector is gaining market share most quickly.
End User:
Cost tiers for machine control systems often align with the scale and complexity of operations undertaken by different end-user types.
- Heavy Equipment Operators:These users, primarily large and small contractors, adopt systems to enhance the efficiency and precision of their machinery on job sites. The choice between OEM and aftermarket solutions is a critical decision point for this group.
- Mining Companies:Large mining corporations deploy integrated machine control systems for fleet management, autonomous operations, and safety compliance in their extensive operations. These companies prioritize robust, all-weather solutions.
- Surveying Firms:These firms leverage machine control for data collection accuracy and to streamline their site analysis and mapping processes.
- Agricultural Contractors:These users implement machine control for precision farming, optimizing field operations and improving productivity.
Heavy Equipment Operators constitute the largest end-user group, with Mining Companies demonstrating substantial investment in advanced systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-funded infrastructure mandates, such as India's national highway development program, directly stimulate machine control system adoption. These initiatives prioritize advanced construction techniques, driving demand for efficiency and quality control across diverse project types. The focus on large-scale development accelerates market penetration.
United States
The United States market demonstrates robust demand for machine control systems, driven by extensive infrastructure development and a focus on job site safety. Initiatives from the U.S. Federal Highway Administration encourage data-rich control systems for highway projects. Major construction hubs in states like Texas are integrating these advanced solutions into large-scale civil engineering works.
India
India's machine control system market expands rapidly, propelled by ambitious national highway development and smart city initiatives. Government mandates for advanced construction techniques stimulate system adoption for quality control. Urban infrastructure projects across the Delhi-NCR region increasingly rely on precision grading and excavation technologies.
China
China's market for machine control systems is significantly influenced by its promotion of digital construction under GB standards. Large-scale infrastructure projects and a push for operational efficiency drive demand for automated heavy machinery. The Yangtze River Delta region, a hub for major construction, sees widespread deployment of GNSS-based systems.
Germany
Germany exhibits strong demand for high-precision machine control systems, supported by stringent quality requirements in civil engineering. The EU's Machinery Directive compels the integration of advanced safety features into heavy equipment. Bavaria, a region known for its advanced manufacturing, integrates sensor fusion technologies into complex construction projects.
Australia
Australia's machine control system market benefits from significant investment in mining and large-scale civil infrastructure projects. National safety standards for heavy equipment operations encourage the adoption of advanced control technologies. Western Australia's extensive mining operations are rapidly deploying autonomous hauling and drilling systems.
Machine Control System Market Key Industry Players
Listed leaders compete with private specialists across the machine control system market, creating a hybrid structure. The market combines established heavy equipment manufacturers with dedicated software and sensor technology providers. Archetypes include full-stack solution providers, sensor fusion innovators, and integrated OEM system developers. Companies pursue strategic partnerships and technology licensing to expand their market reach.
Full-stack solution providers, such as Trimble Inc., offer extensive software and hardware portfolios, catering to diverse construction needs. These entities provide end-to-end solutions, from positioning data to machine execution, enhancing overall job site management. Hexagon AB exemplifies a focus on sensor fusion and reality capture technologies, differentiating through advanced data integration for construction and mining applications. This specialization allows for high-precision reality modeling and complex environmental analysis. Caterpillar Inc. anchors the integrated OEM segment, embedding proprietary machine control systems directly into its heavy equipment fleet, ensuring seamless operational compatibility and single-vendor support for its machinery users.
| Leading Market Players |
|---|
| MOBA Mobile Automation AG |
| Rockwell Automation |
| Trimble Inc. |
| Caterpillar Inc. |
| Deere & Company |
| Topcon Corporation |
| Hemisphere GNSS |
| Volvo Group |
| Hexagon AB |
| Others |
Cost & Logistics Intelligence
ISO 15143-3 interoperability standards gate component supply qualification and influence pricing models for compatible machine control systems. These standards drive differentiation between proprietary OEM solutions and flexible aftermarket offerings.
Pricing Analysis
Certification levels, such as those mandated by the EU's Machinery Directive, create the primary pricing spread for machine control systems. Project-based pricing dominates for large-scale infrastructure, reflecting custom integration costs. High-precision GNSS capabilities and robust sensor fusion drive premium pricing, contrasting with more economical laser-based systems. Pricing softness stems from the availability of basic, less-featured systems, making heavy equipment operators highly price-sensitive for initial capital outlay.
Supply Chain Analysis
Component manufacturing concentration in China and other Asian economies underwrites the supply chain for GPS modules and specialized sensors. The machine control system supply chain draws heavily from advanced semiconductor components and precision optics, critical for sub-centimeter accuracy. Single-source vulnerability for advanced GNSS chipsets represents a structural risk for system manufacturers. Distribution runs through a dual network of OEM factory-fit channels and independent aftermarket integrators, serving diverse end-user needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The machine control system market is undergoing a platform-economics inflection, driven by the ISO 15143-3 telematics standard. This standard enables a more open ecosystem, shifting value from proprietary hardware to integrated software solutions.
For Market Incumbents:Secure long-term software licensing agreements with large fleet operators to counter the threat of open-architecture aftermarket solutions. Invest heavily in sensor fusion R&D, particularly integrating vision cameras, to maintain a technological lead over emerging specialists. Extend OEM integration capabilities to offer bundled service contracts, mitigating margin pressure from component commoditization.
For New Entrants and Emerging Players:Lead with specialized software platforms offering superior data analytics and interoperability for mixed equipment fleets, targeting North American and European markets. Focus on retrofit solutions for legacy equipment, addressing the complexity challenge for smaller contractors. A go-to-market angle emphasizing ease of integration and lower total cost of ownership will penetrate under-served segments.
For Investors and Strategic Acquirers:OSHA safety standards reshape the acquisition landscape, favoring firms with proven object detection and operator alert technologies. Long-term viability for machine control systems hinges on integration with broader digital construction ecosystems over the next decade. Target specialist software developers with strong telematics and data analytics capabilities. The signal to watch is the increasing mandate for autonomous machine safety features in new infrastructure projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating third-party software enhances data exchange across mixed equipment fleets. |
| Sensor Fusion R&D | Developing multi-sensor systems enables all-conditions automation and continuous positioning. |
| Aftermarket Retrofit Solutions | Offering modular systems addresses the challenge of upgrading older heavy equipment fleets. |
| Geographic Expansion | Targeting Southeast Asian infrastructure development capitalizes on underpenetrated markets. |
| Talent Development Programs | Training skilled operators mitigates the scarcity of technicians proficient in complex GNSS systems. |
Research Approach
Cross-validation between primary interviews and extensive secondary data anchors the qualitative findings of this market analysis. Industry stakeholders, including heavy equipment operators, mining company engineers, and system integrators, provided critical insights. Secondary sources like national infrastructure reports, regulatory body publications (e.g., U.S. Federal Highway Administration), and technology patent databases informed the baseline. Bottom-up and top-down triangulation refined market size and growth projections.
Sensitivity analysis informed the forecast framework, assessing market responses to varying infrastructure spending and regulatory shifts over the projection horizon. Segmentation dimensions modeled include component type, technology, application, and end-user, alongside regional adoption patterns. Compound Annual Growth Rates were derived through a regression-based approach. Key forecast inputs include infrastructure project pipelines and GNSS component cost trajectories.
The analysis sits within stated boundaries; outcomes outside significant shifts in global infrastructure investment or rapid technological disruption would require recalibration. Forecasts reflect assumptions regarding regulatory stability. Practitioners should keep alternative scenarios live as government funding priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
RET Controller Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
North America MEMS and Sensors Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
Battery Free Wireless Sensor Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Cryogenic Temperature Controller Market