
 US Occupancy Sensors Market | 2026-2036
US Occupancy Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
US Occupancy Sensors Market Analytics
Modular sensor-to-gateway bundling is recalibrating procurement patterns across commercial and industrial verticals. Johnson Controls Inc leverages its building automation platform to anchor large-scale retrofit contracts in the healthcare and education sectors. Schneider Electric SE competes through its EcoStruxure architecture, which extends wired and wireless occupancy sensing into integrated energy management systems. Leviton Manufacturing Co Inc specializes in contractor-grade passive infrared and dual-technology units for residential and light commercial installations.
Occupancy sensors are electromechanical or solid-state detection devices that register human presence through passive infrared heat signatures, ultrasonic Doppler shifts, acoustic pattern recognition, or fused multi-modal inputs, typically outputting binary or dimming-level signals to lighting, HVAC, or security controllers. Their primary commercial purpose is to eliminate energy waste in conditioned spaces by triggering load reductions during unoccupied intervals. Passive infrared units still occupy the largest installed base due to lower per-node cost and simpler commissioning, yet dual-technology products are gaining fastest in high-bay industrial and precision healthcare environments where false-off events carry operational penalties. Wired deployments sustain margin pools in new construction, while wireless and Bluetooth segments are expanding in tenant improvement and historic building retrofit applications where pulling low-voltage cable is prohibitively expensive.
The Department of Energy enforces minimum efficacy and standby power requirements under federal appliance standards, while California's Title 24 mandates automatic daylighting and occupancy-responsive controls in commercial buildings over defined floor-area thresholds. The EPA's ENERGY STAR certification program and the FCC's Part 15 rules for unlicensed radio devices further constrain product design and market access for non-compliant hardware. Stakeholders must monitor evolving state-level stretch codes and utility incentive structures to anticipate where specification requirements will outpace baseline federal standards.
Market Dynamics
Utility rebate programs across Texas, California, and New York metro corridors are compressing payback periods for smart lighting retrofits, pulling forward replacement cycles that previously stretched across decades.
Growth Catalysts
- California Title 24 mandates:Automatic daylighting and occupancy-responsive controls now apply to commercial buildings above defined floor-area thresholds, forcing hardware upgrades across aging office and hospitality stock.
- Bluetooth Low Energy mesh:Wireless commissioning slashes installation labor in historic buildings where pulling low-voltage cable faces preservation restrictions.
- Healthcare precision requirements:Surgical suites and patient monitoring zones demand dual-technology sensors to eliminate false-off events that disrupt critical workflows.
Market Restraints
- Passive infrared price floors:Mature manufacturing in Mexico and Southeast Asia has compressed margins to levels that deter R&D investment in incremental improvements.
- FCC Part 15 certification delays:Unlicensed radio device approvals for new wireless sensor variants stretch 8-14 months, freezing product launch timelines.
- LED driver compatibility gaps:Legacy fluorescent ballast infrastructure in pre-2010 commercial buildings requires costly electrical rewiring to accept 0-10V dimming outputs.
Strategic Opportunities
- Texas ERCOT grid stress:Demand response programs now compensate commercial buildings for automated load curtailment, creating attach rates for sensors bundled with utility-controlled lighting.
- Acoustic pattern recognition:Fusion of PIR with sound-based presence detection opens installation in glass-walled conference rooms where thermal signatures dissipate.
- Industrial high-bay verticals:Warehousing and distribution centers above 25 feet ceiling heights remain underpenetrated by ultrasonic alternatives due to signal attenuation challenges.
Industry Challenges
- Commissioning technician shortages:Proper sensor placement, sensitivity calibration, and time-delay programming require trained low-voltage electricians in markets where vocational pipeline output lags retrofit demand.
- Interoperability fragmentation:BACnet, Zigbee, Z-Wave, and proprietary wireless protocols force integrators to maintain multiple gateway ecosystems, inflating project complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Occupancy Sensors Market |
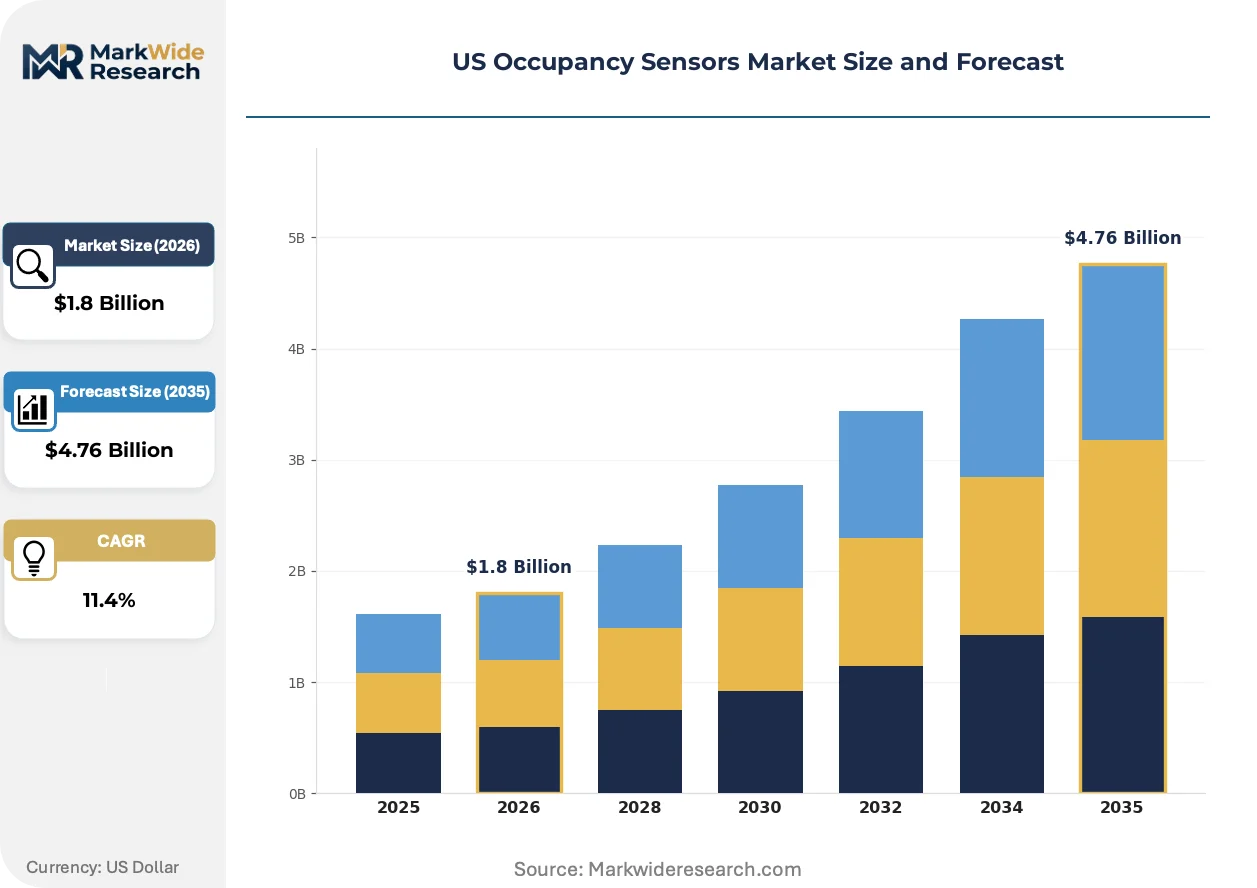
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Passive Infrared, Dual Technology, Microphonic Application: Residential, Commercial, Industrial, Automotive Technology: Wired, Wireless, Hybrid, Bluetooth End User: Facility Managers, Homeowners, Contractors, OEMs |
| Companies Covered | Johnson Controls Inc, Legrand SA, Honeywell International Inc, Schneider Electric SE, Eaton Corp PLC, Signify Holding BV, Lutron Electronics Co Inc, Leviton Manufacturing Co Inc, Acuity Brands Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Occupancy Sensors Market Evolving Landscape
Sensor-to-gateway architectures are shedding dedicated wiring infrastructure, while multi-modal detection stacks erode the dominance of single-technology units. Procurement patterns now favor bundled hardware-software contracts over component sourcing.
Machine learning inference at the edge is integrating occupancy pattern recognition directly into sensor firmware, eliminating cloud latency for real-time HVAC adjustments. Large commercial real estate portfolios in Manhattan and San Francisco are piloting these units to reduce false-positive rates in densely populated open-plan floors. The technology is compressing differentiation between premium and mid-tier hardware tiers as algorithmic performance supersedes sensor component quality.
The Department of Energy's appliance efficiency standards are tightening standby power limits for connected lighting controls, forcing redesigns of always-on wireless radios. Manufacturers must now sacrifice signal range or implement aggressive sleep-cycling to maintain compliance. California's Title 24 2025 amendments will extend these requirements to battery-powered sensors, accelerating chip-level power management investment.
Facility managers are consolidating vendor relationships around building automation platforms that bundle sensors with analytics dashboards, displacing standalone hardware procurement through electrical distributors. This concentration favors suppliers with software development capabilities over pure-play sensor manufacturers. The shift is most visible in healthcare and education verticals where capital budgets now flow through master service agreements rather than project-by-project bids.
US Occupancy Sensors Market Segmentation
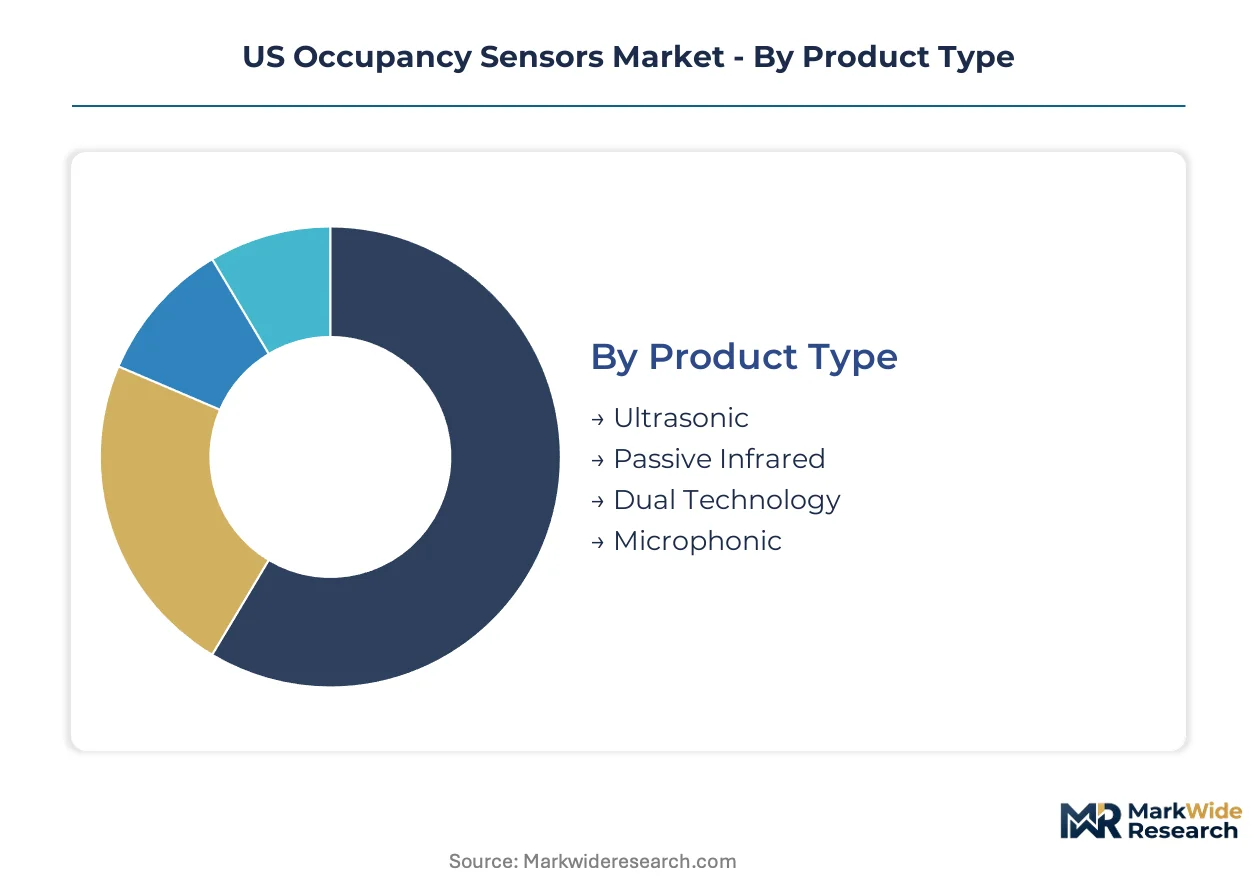
Technology diversity across detection modalities and connectivity architectures creates distinct procurement channels for US building automation integrators. Each segment carries unique commissioning requirements and margin profiles that shape vendor positioning.
Product Type:
Passive infrared units dominate volume shipments while dual-technology products command premium pricing in precision environments.
- Passive Infrared:Detects body heat through pyroelectric sensors measuring infrared radiation changes within a defined detection cone. Texas and California utility rebate programs prioritize PIR retrofits in aging office stock where per-node cost sensitivity dominates procurement decisions.
- Dual Technology:Fuses PIR with ultrasonic Doppler shift detection to eliminate false-off events through algorithmic cross-verification. New York metro healthcare facilities specify these units for surgical suites and patient monitoring zones where occupancy misreads disrupt critical workflows.
- Ultrasonic:Emits high-frequency sound waves and measures reflection patterns to detect motion in enclosed spaces.
- Microphonic:Employs acoustic pattern recognition to register presence through ambient sound signatures, enabling installation in glass-walled conference rooms where thermal signatures dissipate.
Today's leader: Passive Infrared. Tomorrow's challenger: Dual Technology.
Application:
Commercial buildings generate the deepest retrofit pipelines while industrial verticals remain underpenetrated by advanced detection stacks.
- Commercial:Encompasses office, hospitality, retail, and institutional buildings where Title 24 mandates automatic controls above defined floor-area thresholds. California's 2025 code amendments are forcing hardware upgrades across aging office and hospitality stock in Los Angeles and San Francisco corridors.
- Industrial:Covers warehousing, manufacturing, and distribution facilities where high-bay ceiling heights exceed 25 feet. Signal attenuation challenges have limited ultrasonic penetration, creating attach opportunities for PIR-ultrasonic fusion products in Texas logistics hubs.
- Residential:Single-family and multifamily installations driven by smart home integration and utility demand response programs.
- Automotive:Cabin occupancy detection for climate control optimization and child safety alert systems.
Commercial applications anchor current revenue; industrial verticals offer the steepest expansion trajectory as warehousing automation accelerates.
Technology:
Wired deployments sustain margin pools in new construction while wireless segments capture tenant improvement and historic retrofit demand.
- Wired:Delivers hardwired 0-10V or DALI control signals through low-voltage infrastructure, preferred in ground-up construction where cable pulling costs amortize across full building systems. New York and California new commercial permits specify wired controls for reliability guarantees in Class A office towers.
- Bluetooth:Implements Bluetooth Low Energy mesh networking for battery-powered or line-voltage sensors with wireless commissioning. Historic building retrofits in Boston and Philadelphia corridors adopt these units where preservation restrictions prohibit cable penetration.
- Wireless:Proprietary RF protocols operating in unlicensed bands, subject to FCC Part 15 certification timelines.
- Hybrid:Combines wired power with wireless signal transmission for flexibility in mixed renovation scenarios.
Wired technology holds installed base dominance; Bluetooth mesh is gaining share fastest in constrained retrofit environments.
End User:
Facility managers consolidate procurement through building automation platforms while contractors drive spot-market transactions.
- Facility Managers:Oversee corporate and institutional real estate portfolios, increasingly routing capital through master service agreements with bundled hardware-software contracts. Manhattan and San Francisco commercial real estate operators pilot edge-inference sensors to reduce false-positive rates in open-plan floors.
- Contractors:Execute project-based installations for electrical distributors and direct owner relationships, favoring contractor-grade PIR units with simplified commissioning. Vocational pipeline shortages in Texas and California markets are compressing available technician hours for calibration-intensive dual-technology deployments.
- Homeowners:Direct purchasers through retail and integrator channels for residential smart lighting and security applications.
- OEMs:Original equipment manufacturers integrating sensors into luminaires, HVAC units, and security systems at factory level.
Facility managers control premium segment specification; contractors mediate volume throughput in light commercial and residential tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US occupancy sensors industry traces its commercial roots to California's early building energy codes in the 1970s, where Title 24 first mandated automatic lighting controls for large commercial structures. Texas and New York subsequently developed parallel regulatory frameworks that institutionalized sensor deployment across their substantial building stocks.
California
California's Title 24 2025 amendments extend standby power limits to battery-powered sensors, forcing chip-level redesigns across supplier portfolios. The California Energy Commission enforces these standards through mandatory acceptance testing for commercial permits above 10,000 square feet. Los Angeles and San Francisco corridors host the densest concentration of edge-inference pilot programs in open-plan commercial towers.
Texas
ERCOT grid stress events have activated demand response programs that compensate commercial buildings for automated load curtailment, creating attach rates for sensor-utility integration. The Public Utility Commission of Texas oversees these incentive structures. Dallas-Fort Worth and Houston logistics hubs drive industrial high-bay sensor specification for warehousing above 25-foot ceiling heights.
New York Metro
Class A office towers in Manhattan specify wired controls for reliability guarantees, while historic districts in Brooklyn and Queens adopt Bluetooth mesh where preservation restrictions prohibit cable penetration. The New York State Energy Research and Development Authority administers rebate programs compressing retrofit payback periods. Healthcare facilities across the metro specify dual-technology units for surgical suites.
Greater Boston
Historic building stock in Cambridge and downtown Boston drives wireless sensor adoption where National Park Service preservation guidelines restrict structural modifications. Massachusetts Stretch Energy Code amendments align with California's trajectory on automatic controls. The Route 128 corridor hosts pilot deployments of acoustic pattern recognition sensors in glass-walled corporate facilities.
Pacific Northwest
Seattle and Portland utilities offer aggressive rebates for smart lighting controls tied to regional carbon reduction mandates. The Northwest Energy Efficiency Alliance coordinates specification standards across Oregon and Washington. Data center construction in Hillsboro, Oregon, creates specialized demand for precision occupancy detection in mission-critical facilities.
US Occupancy Sensors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with building automation platforms commanding service-annuity multiples against hardware-only suppliers. The market exhibits tiered concentration: diversified electrical conglomerates anchor the premium segment, specialized lighting controls firms occupy the mid-tier, and contractor-grade manufacturers serve volume retrofit channels. Three archetypes dominate: platform-integrated building automation suppliers, standalone sensor specialists, and electrical distribution-aligned commodity producers. Competitive moves center on software capability acquisition and utility partnership structures for demand response bundling.
Within the platform-integrated tier, Johnson Controls Inc and Schneider Electric SE exemplify the building automation anchor archetype, while Leviton Manufacturing Co Inc represents the distribution-aligned commodity producer model. These three companies illustrate the strategic divergence between software-integrated service contracts and hardware-volume throughput models that defines competitive positioning across California, Texas, and New York metro corridors.
| Leading Market Players |
|---|
| Johnson Controls Inc |
| Legrand SA |
| Honeywell International Inc |
| Schneider Electric SE |
| Eaton Corp PLC |
| Signify Holding BV |
| Lutron Electronics Co Inc |
| Leviton Manufacturing Co Inc |
| Acuity Brands Inc |
| Others |
Value Network & Pricing Analysis
Low-voltage electrician workforce concentration in Texas and California metro corridors feeds directly into pricing-tier spreads, as vocational pipeline shortages inflate commissioning labor costs for dual-technology sensor deployments while passive infrared units absorb margin compression through standardized installation protocols.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates building automation platform bundles from contractor-grade hardware and commodity passive infrared nodes. Price differentiation rests on FCC Part 15 certification tier and after-sales software integration depth. Cost compression in the economy tier is intensifying because Mexican and Southeast Asian manufacturing has standardized pyroelectric sensor production. Facility managers purchasing bundled analytics contracts show the least price sensitivity, while electrical contractors bidding spot-market retrofits drive aggressive per-node negotiations.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific sensor component origins has amplified working capital requirements for US distributors managing Bluetooth mesh and proprietary wireless inventory. Pyroelectric sensor elements draw from Japan and Germany, while microcontroller fabrication centers on Taiwan and South Korea. Single-source vulnerability in BLE system-on-chip supply creates exposure to foundry allocation shifts. Distribution runs through electrical wholesale channels serving contractor-grade volume, with direct OEM relationships capturing premium platform-integrated contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on algorithmic differentiation compressing hardware tier premiums, as edge-inference firmware reduces sensor component quality requirements while software-annuity contracts displace transactional hardware procurement.
For Market Incumbents: Hedge against Bluetooth Low Energy commoditization by deepening software development capabilities around building automation platform integration. Acquire acoustic pattern recognition sensor specialists before niche entrants consolidate glass-walled conference room specification. Vertical integration into edge-inference chip design protects margin pools as standby power regulations tighten.
For New Entrants and Emerging Players: Industrial high-bay warehousing above 25-foot ceiling heights in Texas logistics corridors represents the most penetrable white-space target, as ultrasonic signal attenuation has stalled incumbent penetration. Target healthcare precision environments with dual-technology units priced below Johnson Controls and Schneider Electric service-annuity bundles. Pursue utility demand response partnership structures as the primary go-to-market anchor.
For Investors and Strategic Acquirers: Building automation platform conglomerates are the most active acquirer in this space, seeking sensor-to-analytics software capabilities to defend master service agreement positions. Five-to-ten year viability favors targets with FCC Part 15 pre-certified wireless portfolios and Title 24 compliance documentation. Monitor California Energy Commission 2025 amendment enforcement velocity as the signal for chip-level power management investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Inference Firmware Development | Machine learning at the sensor compresses differentiation between premium and mid-tier hardware tiers. |
| Utility Demand Response Partnership | ERCOT grid stress programs create attach rates for sensor-utility controlled lighting bundles. |
| Acoustic Pattern Recognition Launch | Sound-based detection opens installation in glass-walled conference rooms where thermal signatures dissipate. |
| Bluetooth Mesh Certification Acceleration | FCC Part 15 approval timelines freeze product launches; pre-certified modules compress time-to-revenue. |
| Title 24 Compliance Documentation | California Energy Commission acceptance testing mandates position compliant suppliers for commercial permit flows. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with building automation platform engineers, electrical contractor procurement leads, facility management directors, and utility demand response program officers with secondary validation against DOE appliance efficiency standards, FCC Part 15 equipment authorization databases, California Energy Commission Title 24 compliance documentation, and utility rebate program filings. Bottom-up sensor shipment estimates and top-down building automation system spend analysis were triangulated to anchor market sizing.
Historical reference periods spanning installed base replacement cycles and retrofit wave timing anchored the projection horizon across technology, application, and connectivity architecture dimensions. CAGRs were derived from segment-level growth rate convergence analysis incorporating utility incentive program budget trajectories, commercial construction permit velocity, and Title 24 amendment enforcement schedules. Edge-inference adoption curves and Bluetooth mesh penetration rates in historic building retrofits served as industry-specific forecast inputs.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time utility rebate program redemption data and contractor-grade spot-market transaction pricing introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions about Title 24 amendment implementation timing and FCC certification backlog resolution; stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Predictive Touch Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Signal Calibrators Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Battery Monitor Market