
 Asia-Pacific Smart Glove Market | 2026-2036
Asia-Pacific Smart Glove Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Glove Market Insights
Shenzhen's electronics manufacturing base is pivoting toward smart glove component fabrication, drawing contract assembly from Guangdong province. Ansell leverages its Malaysian rubber expertise to sustain industrial-grade haptic glove production. Hartalega Holdings Berhad anchors its position through advanced nitrile formulations for health monitoring applications. Shenzhen Seekas Technology Co., Ltd. competes on Bluetooth-integrated gesture modules for gaming peripherals.
Asia-Pacific smart gloves integrate flexible sensors, conductive textiles, and wireless transceivers into wearable hand coverings that capture biomechanical data or deliver tactile feedback for remote manipulation. Typical units embed IMU arrays with sub-degree orientation accuracy and pressure-sensitive polymer layers spanning 10-15 sensing zones per digit. Health monitoring applications lead current revenue contribution, while gesture recognition systems for augmented reality training simulations represent the fastest-expanding margin pool. RFID-enabled industrial use segments remain nascent in Southeast Asian manufacturing facilities.
Japan's METI enforces JIS standards for wearable haptic devices, while China's MIIT governs Bluetooth and NFC protocol certifications for domestic market access. South Korea's MFDS regulates health monitoring wearables as quasi-medical devices, creating tiered compliance pathways. India's BIS mandates electromagnetic compatibility testing for imported wireless gloves under its compulsory registration scheme. Stakeholders must track evolving cross-border data localization rules affecting cloud-connected rehabilitation platforms.
Market Dynamics
Japan's METI haptic device standards and China's MIIT interoperability mandates are compressing certification timelines while fragmenting compliance pathways across the Asia-Pacific smart glove ecosystem.
Growth Catalysts
- MIIT Wearable Interoperability Guidelines:China's framework accelerates Bluetooth and NFC protocol clearances for domestic market entry, reducing time-to-certification for Shenzhen hardware clusters.
- Gesture Recognition in Telemedicine:Healthcare providers in South Korea deploy haptic gloves for remote rehabilitation, creating pull-through demand for pressure-sensitive polymer sensor arrays.
- Shenzhen Component Fabrication:The electronics manufacturing base pivots toward flexible sensor and conductive textile production, drawing contract assembly from Guangdong province suppliers.
Market Restraints
- Conductive Polymer Input Volatility:Silver nanowire and PEDOT:PSS supply chains concentrate in Chinese chemical processors, exposing margins to raw material price swings.
- MFDS Quasi-Medical Classification:South Korea's tiered compliance pathways for health monitoring wearables extend regulatory friction for rehabilitation platform developers.
- IMU Array Technical Ceiling:Sub-degree orientation accuracy requirements strain MEMS fabrication yields, limiting cost-down trajectories for consumer-tier gesture modules.
Strategic Opportunities
- India's BIS Wireless Import Gap:Electromagnetic compatibility testing mandates under compulsory registration schemes create first-mover advantage for certified industrial RFID glove entrants.
- AR Training Simulation Convergence:Integration of IMU arrays with edge AI processors opens margin pools in Japan's manufacturing skills transfer programs.
- Cloud-Connected Rehabilitation Platforms:Cross-border data localization rules in ASEAN markets favor localized server architectures for telemedicine deployments.
Industry Challenges
- Multi-Protocol Firmware Integration:Simultaneous Bluetooth, NFC, and proprietary haptic feedback stack development stretches embedded systems engineering capacity in Seoul-Incheon medtech corridors.
- JIS-MIIT-MFDS Certification Parallelism:Divergent electromagnetic and biocompatibility testing requirements force redundant validation cycles for multi-market product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Glove Market |
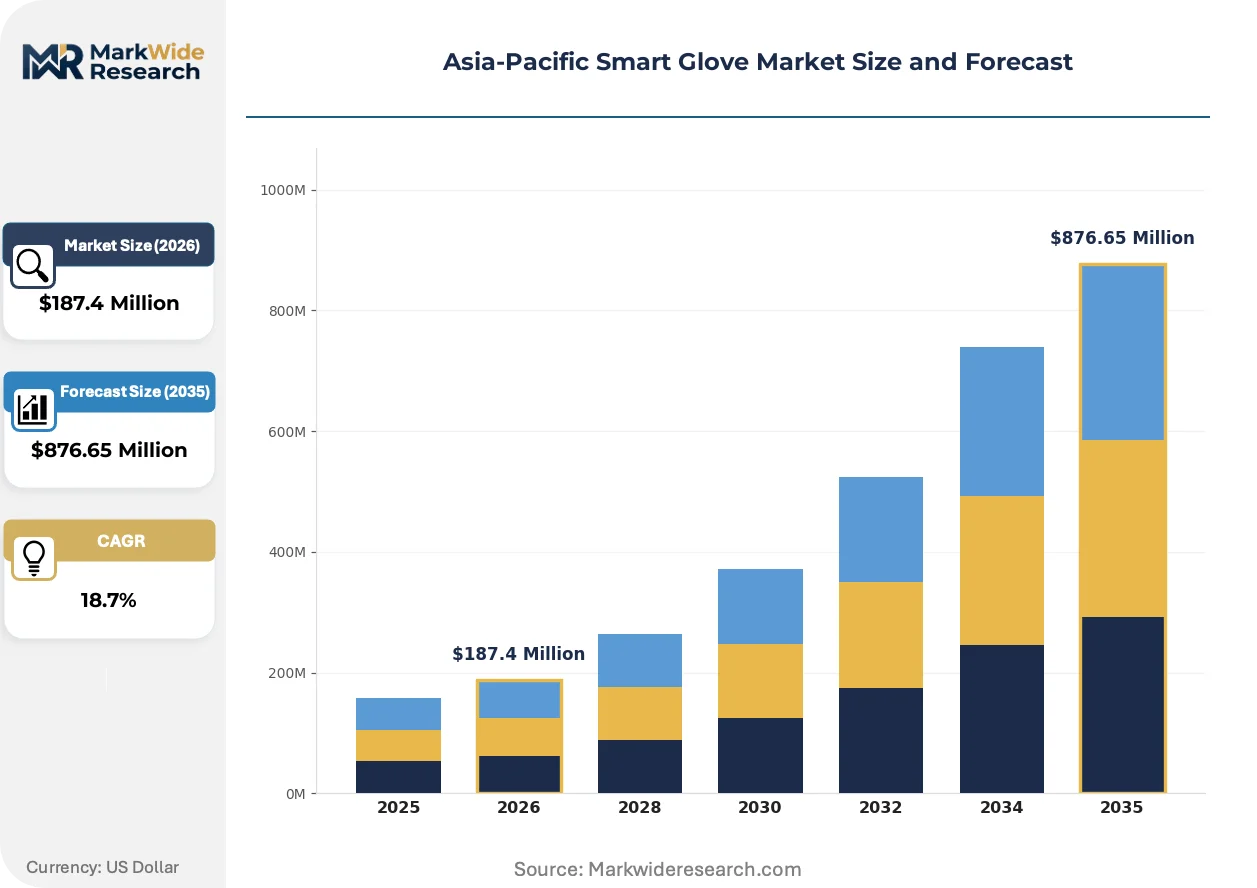
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Monitoring, Gesture Recognition, Gaming, Industrial Use Technology: Bluetooth, RFID, NFC, Haptic Feedback End User: Healthcare Providers, Gaming Companies, Manufacturing, Research Institutions Application: Telemedicine, Training Simulations, Rehabilitation, Augmented Reality |
| Companies Covered | Ansell, Top Glove Corporation Berhad, Hartalega Holdings Berhad, Supermax Corporation Berhad, Kossan Rubber Industries Bhd, Showa Group, Sri Trang Gloves Public Company Limited, Smart Glove, Shenzhen Seekas Technology Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Glove Market Trends and Innovations
Flexible sensor fusion and edge computing migration are compressing latency thresholds while expanding real-time biomechanical capture applications across Asia-Pacific industrial and clinical settings.
Machine learning inference at the glove edge is automating gesture classification without cloud dependency. Japanese automotive assemblers pilot these systems for assembly-line quality verification, compressing response times from 200ms to sub-50ms. The shift is automating tier-1 supplier qualification processes that previously required dedicated IT infrastructure.
China's MIIT revised radio equipment type-approval rules now mandate pre-certification interoperability testing with domestic cloud platforms. Industrial glove vendors must redesign wireless stacks to satisfy both international BLE standards and localized data routing protocols. South Korean health monitoring wearable exporters face the steepest redesign burden under these bifurcated requirements.
Hospital procurement committees in Japan and Australia now unbundle hardware acquisition from software subscription fees, reversing prior bundled service contracts. Rehabilitation platform vendors must price sensor hardware and analytics tiers separately, squeezing upfront equipment margins. This disaggregation is most visible in Tokyo metropolitan hospital district tenders, where five-year total cost of ownership calculations dominate vendor selection.
Asia-Pacific Smart Glove Market Segmentation
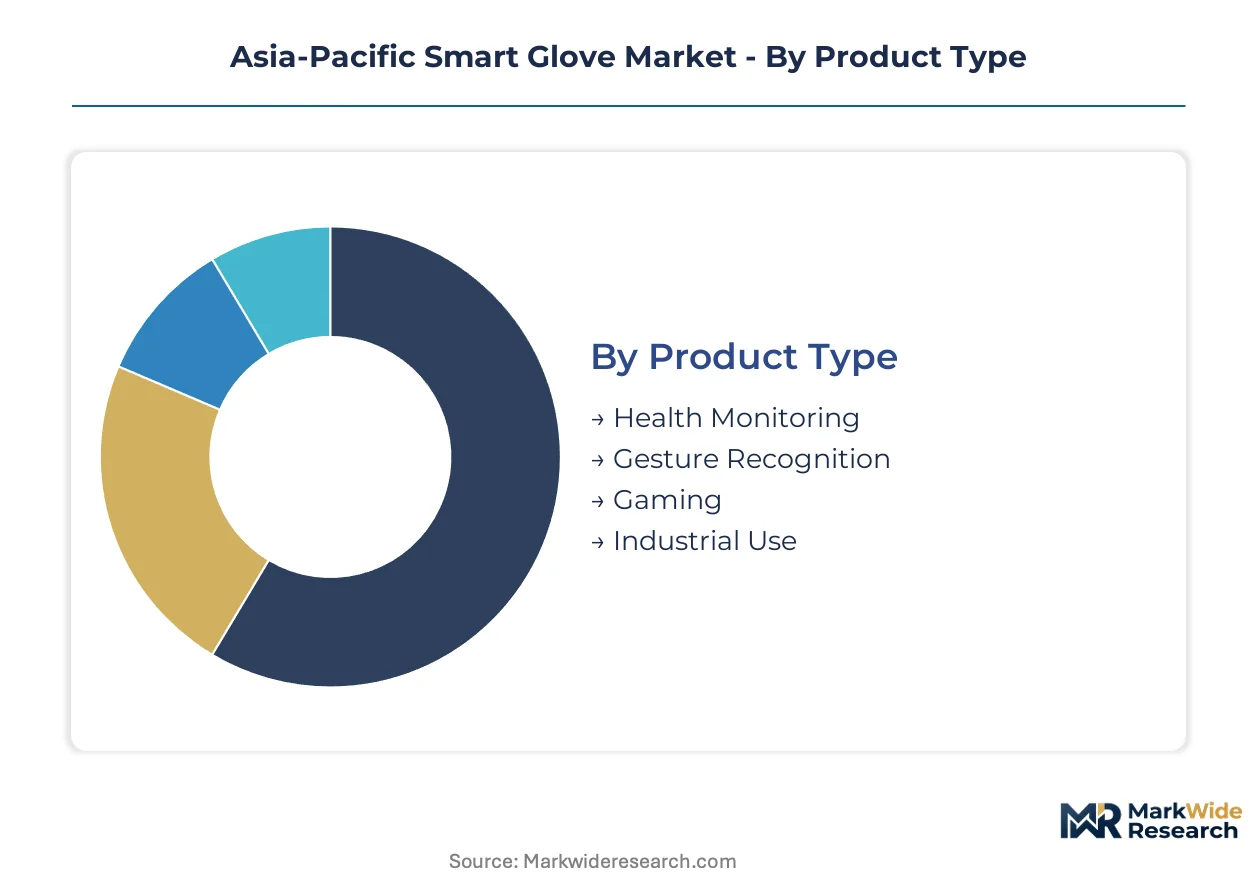
Segmentation in the Asia-Pacific smart glove market reveals how technical specifications align with distinct procurement budgets and regulatory pathways across Japan, South Korea, and China. Upgrade cycles vary dramatically: healthcare providers replace sensor arrays every 3-4 years, while gaming peripheral manufacturers refresh Bluetooth modules annually.
Product Type:
Replacement cycles drive purchasing patterns, with health monitoring gloves commanding extended service contracts and gesture recognition units facing accelerated obsolescence from IMU precision improvements.
- Health Monitoring:Units embed photoplethysmography sensors and conductive polymer electrodes for continuous vital sign capture. Hospitals in Tokyo and Seoul prioritize these for remote patient monitoring, though MFDS quasi-medical classification in South Korea extends procurement approval timelines.
- Gesture Recognition:IMU arrays with sub-degree orientation accuracy enable precise hand tracking for telemedicine applications. China's Shenzhen hardware clusters dominate component supply, drawing contract assembly from Guangdong province suppliers facing silver nanowire price volatility.
- Gaming:Bluetooth-integrated modules target latency-sensitive input for VR peripherals.
- Industrial Use:RFID-enabled gloves track assembly-line workflows in Japanese automotive plants.
Health Monitoring sits at the top of the volume ranking, with Gesture Recognition climbing the fastest.
Technology:
Cost tiers separate premium haptic feedback stacks from commodity Bluetooth implementations, with proprietary protocols commanding 3-4x firmware development investment.
- Bluetooth:BLE 5.3 transceivers dominate consumer-tier connectivity, with MIIT interoperability mandates forcing redesigns for China market entry. South Korean health monitoring exporters face the steepest compliance burden under bifurcated domestic-international protocol requirements.
- Haptic Feedback:Electromagnetic and piezoelectric actuators deliver tactile response for remote rehabilitation. METI JIS standards govern device certification in Japan, while China's GB standards create parallel testing obligations for multi-market launches.
- RFID:Industrial tagging applications concentrate in Japanese manufacturing facilities.
- NFC:Short-range pairing protocols see limited adoption outside payment-integrated healthcare workflows.
Haptic Feedback captures the highest margin tier, with Bluetooth expanding most quickly across price-sensitive segments.
End User:
Customer type determines specification rigor, with healthcare providers demanding biocompatibility certifications that gaming companies bypass entirely.
- Healthcare Providers:Hospital procurement committees in Japan and Australia now unbundle hardware from software subscriptions, squeezing upfront equipment margins. Five-year total cost of ownership calculations dominate vendor selection in Tokyo metropolitan tenders.
- Manufacturing:Japanese automotive assemblers pilot edge-AI gesture classification for assembly-line quality verification, compressing response times from 200ms to sub-50ms without cloud dependency.
- Gaming Companies:Peripheral manufacturers source from Shenzhen Seekas Technology and comparable module integrators.
- Research Institutions:Academic buyers prioritize open firmware architectures for biomechanical study applications.
Healthcare Providers anchor procurement volume, with Manufacturing gaining share fastest through industrial automation programs.
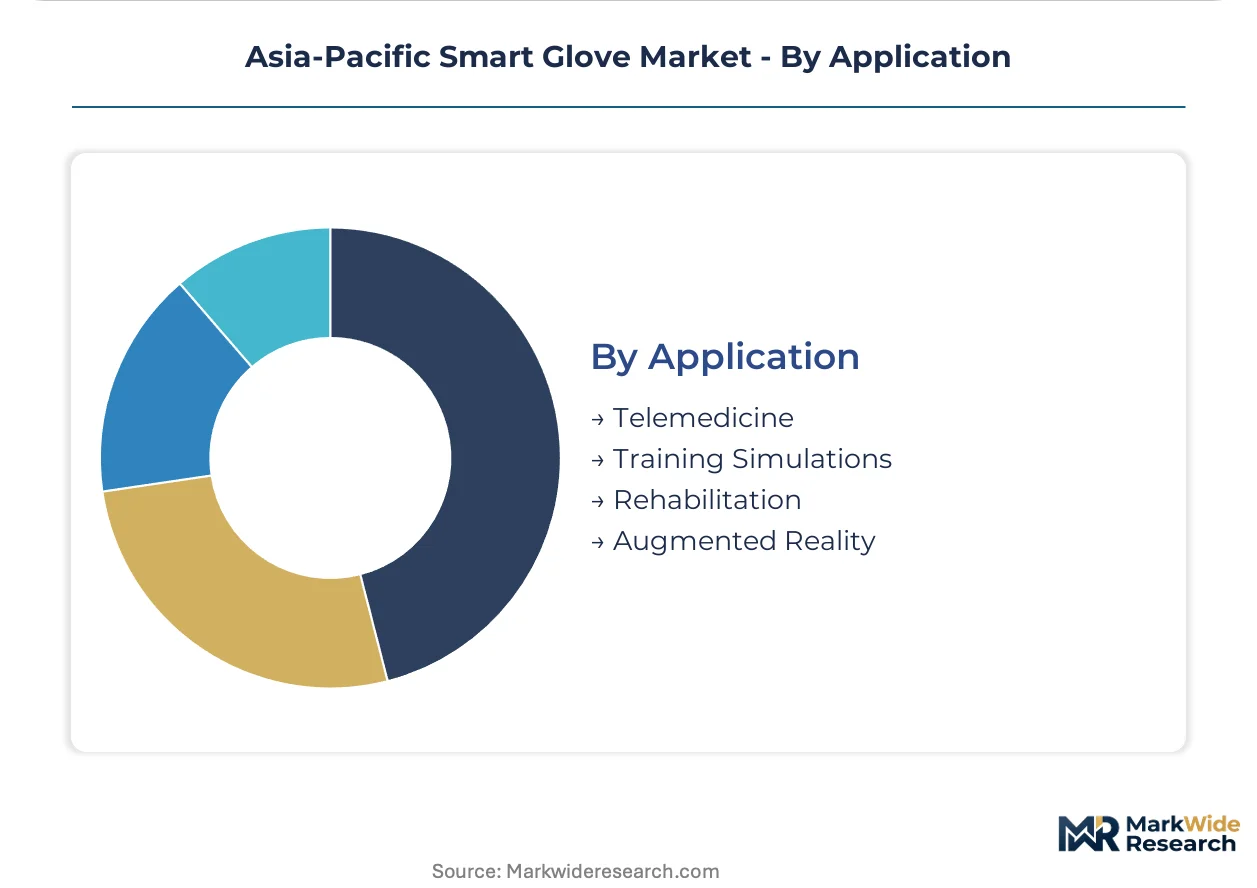
Application:
Application maturity separates established telemedicine deployments from nascent augmented reality training systems still seeking standardized content pipelines.
- Telemedicine:Cloud-connected rehabilitation platforms face cross-border data localization requirements across ASEAN markets, favoring localized server architectures. South Korean providers deploy haptic gloves for remote physical therapy, creating pull-through demand for pressure-sensitive polymer arrays.
- Rehabilitation:Post-stroke and orthopedic recovery protocols integrate gesture tracking for progress quantification. Japan's aging demographic concentrates demand in Kanto and Kansi hospital districts, with METI standards accelerating product certification timelines.
- Training Simulations:Skills transfer programs in Japanese manufacturing pilot AR-integrated glove systems.
- Augmented Reality:Enterprise training content pipelines remain underdeveloped outside pilot deployments.
Telemedicine leads current revenue contribution, with Rehabilitation expanding most quickly through aging-population demand drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with streamlined certification pathways as divergent haptic device standards across Northeast Asia fragment compliance costs. Malaysia and Thailand capture contract assembly flows from Chinese hardware clusters seeking tariff arbitrage and regulatory hedging.
China
Shenzhen's electronics manufacturing base pivots toward flexible sensor fabrication for gesture recognition modules. MIIT interoperability mandates for Bluetooth and NFC protocols compress domestic certification timelines while forcing redesigns for bifurcated export requirements. Guangdong province suppliers concentrate contract assembly for gaming peripheral integrators facing silver nanowire input volatility.
Japan
Hospital procurement committees in Tokyo metropolitan districts unbundle hardware from software subscriptions for rehabilitation platforms. METI enforces JIS standards for wearable haptic devices, accelerating product certification timelines for telemedicine deployments. Kanto and Kansai hospital districts drive demand for post-stroke recovery protocols with integrated gesture tracking.
South Korea
Healthcare providers deploy haptic gloves for remote physical therapy, creating pull-through demand for pressure-sensitive polymer sensor arrays. MFDS quasi-medical classification extends regulatory friction for health monitoring wearables through tiered compliance pathways. Seoul-Incheon medtech corridors stretch embedded systems engineering capacity for multi-protocol firmware integration.
Malaysia
Ansell leverages domestic rubber expertise to sustain industrial-grade haptic glove production for regional export markets. The country's central medical device regulator maintains alignment with ASEAN harmonized standards, reducing redundant validation cycles. Penang and Selangor manufacturing zones capture component assembly migrating from higher-cost Northeast Asian jurisdictions.
Australia
Hospital procurement committees in Sydney and Melbourne adopt five-year total cost of ownership calculations for vendor selection. TGA regulates health monitoring wearables with pathways converging toward ISO standards, simplifying multi-market launches. Research institutions prioritize open firmware architectures for biomechanical study applications in academic medical centers.
Asia-Pacific Smart Glove Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue gesture recognition specialization and cloud-connected rehabilitation platforms. The vendor base stratifies across industrial rubber conglomerates, Shenzhen hardware integrators, and Seoul-Incheon medtech specialists. Three archetypes dominate: Malaysian rubber-based industrial fabricators, Chinese Bluetooth module assemblers, and Japanese haptic device certifiers. Competitive moves concentrate on geographic expansion into ASEAN tariff-advantaged zones and backward integration into conductive polymer supply chains.
Among Malaysian rubber-based producers, Ansell, Hartalega Holdings Berhad, and Top Glove Corporation Berhad exemplify the industrial-grade fabrication archetype. These entities leverage captive nitrile formulation expertise to anchor health monitoring applications. Shenzhen Seekas Technology Co., Ltd. occupies a position within the hardware integration tier, representing Chinese contract assembly specialization for gesture recognition modules. The competitive dynamic pits scale-driven rubber conglomerates against nimble Shenzhen electronics clusters, with certification capacity emerging as the scarce resource separating viable multi-market entrants from single-jurisdiction players.
| Leading Market Players |
|---|
| Ansell |
| Top Glove Corporation Berhad |
| Hartalega Holdings Berhad |
| Supermax Corporation Berhad |
| Kossan Rubber Industries Bhd |
| Showa Group |
| Sri Trang Gloves Public Company Limited |
| Smart Glove |
| Shenzhen Seekas Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement committees across Tokyo and Sydney now mandate unbundled hardware-software contracts for rehabilitation platforms, forcing vendors to absorb upfront equipment costs while recovering margin through multi-year analytics subscriptions. This purchasing shift compresses sensor array margins and accelerates contract assembly migration toward tariff-advantaged ASEAN zones.
Pricing Analysis
Distributor margins in the Seoul-Incheon medtech corridor typically capture 18-25 percent of final equipment value, though direct-to-hospital tenders in Japan bypass intermediaries entirely. Three-tier pricing structure across premium haptic feedback systems, standard Bluetooth gesture modules, and economy RFID industrial gloves separates METI-certified rehabilitation units from Shenzhen-assembled gaming peripherals. Price differentiation hinges on JIS-MIIT-MFDS certification parallelism and captive conductive polymer formulation. Cost compression in consumer-tier gesture modules intensifies as MEMS fabrication yields strain under sub-degree accuracy requirements. Gaming peripheral manufacturers exhibit highest price sensitivity, while Japanese hospital systems prioritize five-year total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Workforce availability constraints in Guangdong province electronics clusters are accelerating component assembly migration toward Penang and Selangor manufacturing zones. Supply concentrates in China's Shenzhen hardware corridor for flexible sensor fabrication, Malaysia's rubber belt for nitrile formulation, and South Korea's Seoul-Incheon corridor for multi-protocol firmware integration. Silver nanowire and PEDOT:PSS conductive polymers draw from Chinese chemical processors, while IMU arrays rest on Taiwanese MEMS foundry output. Single-source vulnerability in silver nanowire supply chains exposes margins to raw material price swings. Distribution runs through regional medical device distributors in Japan, direct hospital procurement in Australia, and OEM contract channels for industrial RFID deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific smart glove market functions as a stable compounder, with aging demographics across Japan and South Korea generating durable demand for telemedicine and rehabilitation applications. Regulatory fragmentation creates defendable moats for certified multi-market players.
For Market Incumbents: Acquire conductive polymer formulation capabilities to secure input cost stability against silver nanowire price volatility. Malaysian rubber conglomerates should expand JIS certification capacity to capture Tokyo metropolitan hospital tenders, while Shenzhen hardware integrators must backward integrate into MEMS sensor design to escape commodity Bluetooth module pricing. Threat substitution from camera-based hand tracking systems pressures gesture recognition margins, making proprietary haptic feedback IP the critical defensive lever. For New Entrants and Emerging Players: The gap between premium METI-certified rehabilitation gloves and economy RFID industrial units offers entry space for mid-tier telemedicine specialists. India's BIS wireless import gap presents the most penetrable geography, with electromagnetic compatibility testing mandates creating first-mover advantage for certified entrants. Target cloud-connected rehabilitation platforms with localized server architectures for ASEAN data localization compliance, using hospital system partnerships as the primary go-to-market channel. For Investors and Strategic Acquirers: Asymmetric upside sits with Seoul-Incheon medtech specialists possessing multi-protocol firmware integration capabilities and existing MFDS quasi-medical device clearances. Long-term viability over the projection horizon favors vendors with demonstrated cross-certification throughput across JIS, MIIT, and MFDS pathways. Watch for inflection in ASEAN data localization rule harmonization, which would signal scalable telemedicine platform expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Regulatory Certification Investment | Parallel JIS-MIIT-MFDS clearances unlock Tokyo, Shenzhen, and Seoul hospital procurement simultaneously. |
| Backward Integration into Conductive Polymers | Captive PEDOT:PSS formulation insulates margins from Chinese chemical processor price volatility. |
| Localized Cloud Architecture Deployment | ASEAN data localization rules favor regional server infrastructure for telemedicine platform scalability. |
| Edge AI Processor Integration | Sub-50ms gesture classification without cloud dependency opens Japanese automotive quality verification applications. |
| Hospital System Direct Partnership | Unbundled procurement contracts in Tokyo metropolitan districts require separate hardware and analytics tier pricing. |
Research Methodology
Coverage spans Northeast Asia and Southeast Asia, with primary inputs from each regional cluster combined with secondary validation. Interviews with hospital procurement managers, biomedical engineers at rehabilitation centers, GPO contracts specialists, and embedded systems engineers in Seoul-Incheon medtech corridors informed demand-side and technical assessments. Secondary sources include MIIT radio equipment type-approval filings, METI JIS standard documentation, MFDS quasi-medical device registration databases, and ASEAN harmonized medical device regulatory frameworks. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window. Segmentation dimensions modeled include product type, connectivity technology, end-user category, and application, with regulatory certification tier as an additional industry-specific stratifier. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-checks against hospital capital expenditure cycles and gaming peripheral refresh rates. Industry-specific forecast inputs incorporate MEMS fabrication yield trajectories and conductive polymer price indices.
Caveats apply where silver nanowire supply disruptions, abrupt ASEAN data localization rule changes, or MEMS yield collapses could materially shift the outlook. Forecasts reflect modeling assumptions about regulatory certification parallelism and hospital procurement unbundling persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Global Battery Free RFID Sensor Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Europe Gas Sensors Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Europe Machine Control System Market