
 Rain Sensors Market | 2026-2036
Rain Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Rain Sensors Market Analytics
Automotive aftermarket distribution is fragmenting as tier-one suppliers bypass traditional distributors to sell rain sensors directly to repair chains and OEM service networks. Valeo SA leverages its integrated optics manufacturing to control premium optical sensor supply to European automakers. Robert Bosch GmbH anchors its position through captive semiconductor fabrication for capacitive sensing elements. HELLA GmbH & Co. KGaA competes by specializing in compact resistive designs for Asian compact vehicle platforms.
Rain sensors are electro-optical or capacitive devices that detect water droplets on a glass or exposed surface, typically operating through infrared light reflection changes or dielectric variation measured in picofarads, to trigger automated wiper activation or irrigation cutoff. Their primary commercial purpose is to reduce human intervention in environmental response systems while conserving energy and mechanical wear. Digital sensors and smart sensors are capturing margin pools as firmware-enabled units command pricing premiums over analog alternatives in automotive and smart home channels. Optical technology leads in automotive applications due to precision requirements, while capacitive designs sustain growth in agricultural irrigation where cost sensitivity dominates.
The EU Green Deal and F-Gas Regulation shape product design by mandating energy-efficient climate control systems that integrate rain-sensing wiper automation to reduce HVAC load. EPA fuel economy standards in the United States propel OEM adoption of rain sensors as part of aerodynamic optimization packages that eliminate unnecessary wiper drag. China's MIIT enforces GB standards for automotive electronics reliability that dictate sensor durability testing protocols for domestic market access. Stakeholders must monitor diverging regional certification timelines and decide whether to maintain separate product SKUs or pursue unified designs that satisfy multiple regulatory frameworks simultaneously.
Market Dynamics
The EU Green Deal's energy-efficiency mandates are compressing adoption timelines for automated wiper systems, forcing sensor integration into vehicle climate control architectures that were previously standalone. This regulatory pressure is redrawing competitive boundaries between optical and capacitive technology suppliers.
Growth Catalysts
- EU F-Gas Regulation:Mandates for reduced HVAC energy consumption are accelerating rain-sensing wiper automation as a load-reduction mechanism in passenger vehicles.
- Optical sensor precision:Infrared light reflection technology is capturing share in advanced driver-assistance systems where picofarad-level capacitive sensitivity proves inadequate.
- China's eastern manufacturing corridor:Domestic EV brands are consolidating smart sensor procurement with local suppliers, creating captive demand pools for firmware-enabled units.
Market Restraints
- Semiconductor input volatility:Capacitive sensing elements require specialized dielectric substrates whose foundry capacity concentrates in East Asian fabrication networks.
- Optical component supply concentration:Premium infrared emitter supply chains anchor in German and Japanese integrated optics manufacturers, creating single-source vulnerability.
- Dielectric measurement limitations:Capacitive designs face precision ceilings in heavy precipitation conditions where surface water films saturate picofarad detection ranges.
Strategic Opportunities
- Smart home irrigation:Agricultural automation platforms are integrating rain-sensing cutoff mechanisms as water conservation mandates tighten in drought-prone regions.
- China MIIT GB standards:Domestic reliability testing protocols for automotive electronics are creating certification barriers that favor established suppliers with in-house durability laboratories.
- Firmware-enabled premium tier:Digital sensors with embedded calibration algorithms command pricing separation from analog alternatives in aftermarket channels.
Industry Challenges
- Multi-regional certification timelines:Divergent EPA fuel economy verification protocols and EU type-approval procedures force parallel testing tracks for unified product designs.
- Legacy vehicle integration:Retrofit sensor installation requires windshield glass replacement, compressing aftermarket penetration in aging vehicle populations.
- Optics-electronics convergence:Cross-functional engineering teams combining infrared physics with semiconductor design remain scarce in tier-two supplier organizations.
Report Scope
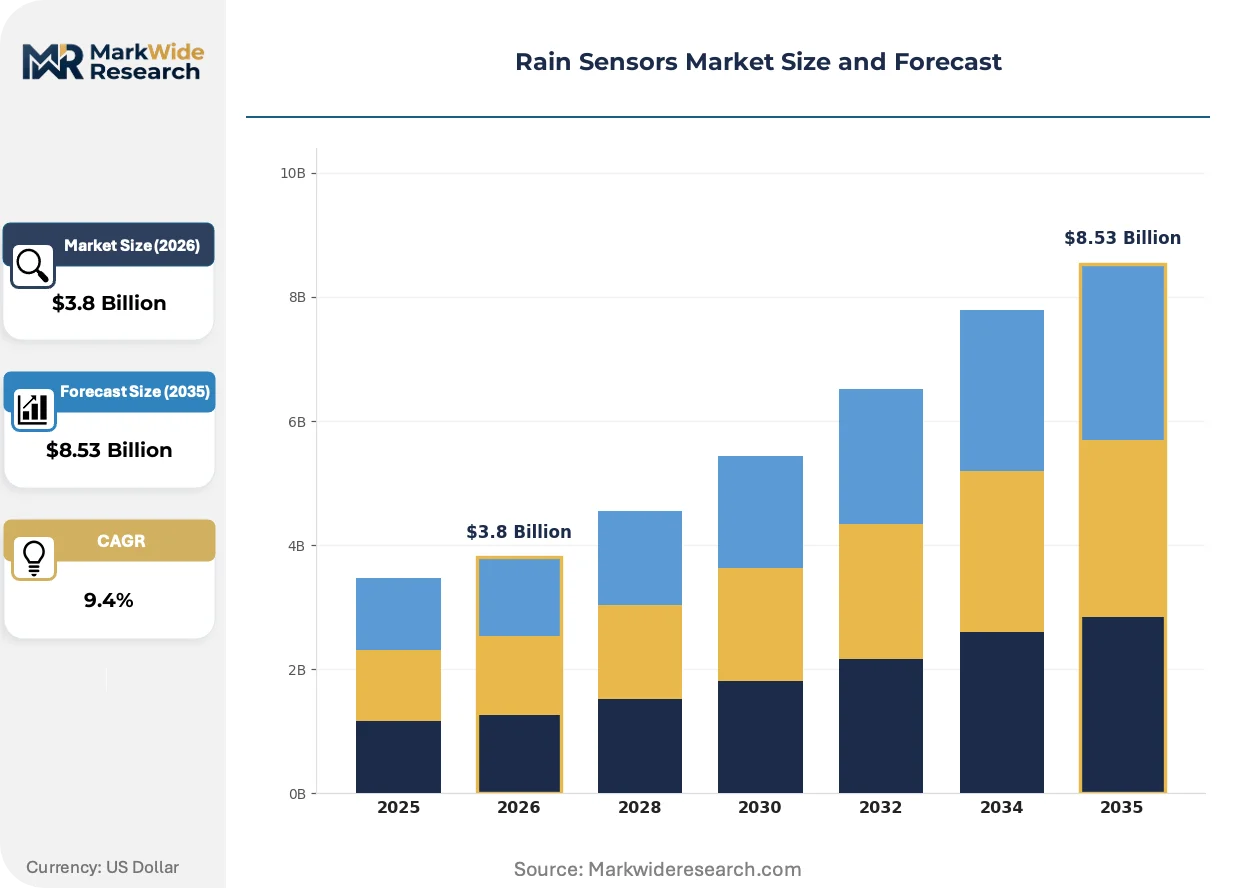
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rain Sensors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Sensors, Digital Sensors, Wireless Sensors, Smart Sensors Technology: Capacitive, Resistive, Optical, Mechanical Application: Irrigation Management, Automotive Systems, Weather Monitoring, Smart Home Devices End User: Agriculture, Automotive, Residential, Industrial |
| Companies Covered | Valeo SA, HELLA GmbH & Co. KGaA, Robert Bosch GmbH, DENSO Corporation, Continental AG, ZF Friedrichshafen AG, Melexis NV, Sensata Technologies, Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rain Sensors Market Evolving Landscape
Sensor architecture is bifurcating between precision-optical platforms for automotive safety systems and cost-optimized capacitive designs for agricultural automation. This divergence is fragmenting R&D investment patterns and reshaping supplier specialization boundaries.
Multispectral infrared arrays with embedded machine-learning inference are rendering obsolete single-wavelength optical detectors that rely on fixed-threshold reflection algorithms. European premium OEMs are adopting these adaptive units for highway-speed wiper activation. The technology is compressing margins for analog sensor producers locked into legacy emitter-detector pair designs.
The EU Green Deal's climate control efficiency mandates are forcing HVAC-wiper system integration that was architecturally separate in previous vehicle generations. Automakers must now certify combined energy consumption profiles rather than isolated subsystem performance. German and French OEMs are responding with unified sensor-controller modules that report to central vehicle energy management computers.
Aftermarket procurement is consolidating around direct repair-chain relationships that bypass traditional tier-one distribution networks. Independent service centers in the United States and Western Europe are establishing captive supplier agreements for sensor-wiper bundle replacements. This channel compression is most visible in collision repair networks where cycle-time pressure favors single-source parts procurement over multi-vendor sourcing.
Rain Sensors Market Segmentation
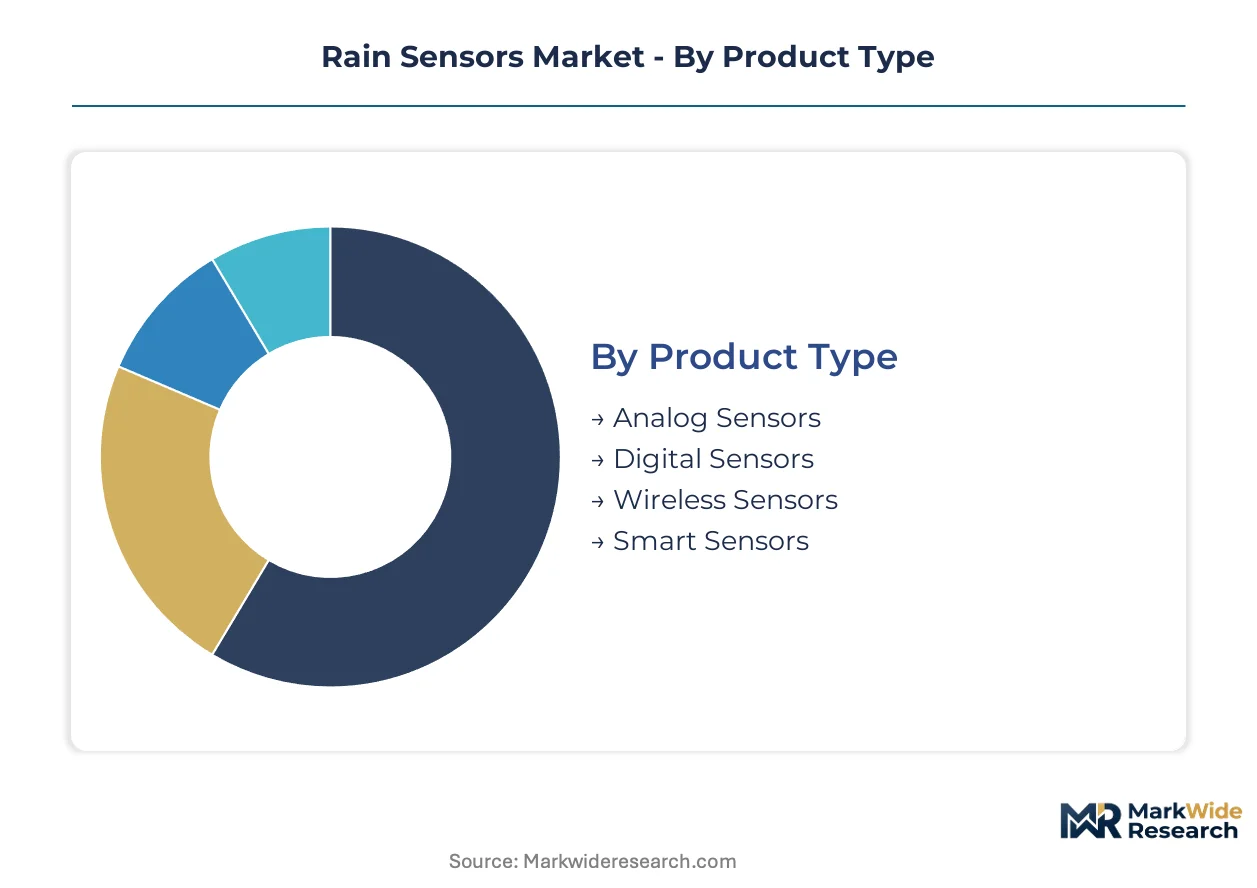
Segmentation in rain sensors reveals how technical specifications map to diverging value pools across automotive safety systems and cost-sensitive agricultural automation. Product architecture choices directly determine addressable margin tiers and regulatory compliance pathways.
Product Type:
Cost tier differentiation separates legacy analog units from firmware-enabled digital platforms commanding premium positioning in automotive channels.
- Analog Sensors:Continuous voltage-output designs rely on discrete emitter-detector pairs without embedded processing. Demand concentrates in aftermarket replacement channels serving aging vehicle populations where cost minimization overrides feature requirements.
- Digital Sensors:Microcontroller-integrated units with SPI or LIN bus interfaces enable calibration algorithms and diagnostic feedback. Procurement from German and Japanese OEMs is accelerating as EU Green Deal mandates force HVAC-wiper system integration requiring digital communication protocols.
- Wireless Sensors:Low-power RF or Bluetooth Low Energy modules eliminate harness complexity for retrofit agricultural installations. These units address irrigation automation in remote field deployments where cabling costs dominate project economics.
- Smart Sensors:Edge-computing platforms with embedded machine-learning inference for adaptive threshold adjustment. China's eastern manufacturing corridor is consolidating procurement with domestic EV brands seeking firmware differentiation.
Analog sensors command the established base. The steepest expansion runs through smart sensors.
Technology:
Application requirements dictate technology selection between precision-optical platforms and cost-optimized capacitive designs.
- Capacitive:Dielectric variation measurement in picofarad ranges detects water film presence through electrode arrays printed on flexible substrates. Agricultural irrigation in drought-prone regions sustains demand where cost sensitivity dominates precision requirements.
- Resistive:Conductive grid patterns on glass surfaces measure resistance changes from water bridging. Asian compact vehicle platforms favor these designs for packaging efficiency in crowded cowl architectures.
- Optical:Infrared light reflection systems with multispectral emitter arrays achieve highway-speed detection reliability. Advanced driver-assistance systems in European premium vehicles require this precision where picofarad-level capacitive sensitivity proves inadequate.
- Mechanical:Physical water-collection mechanisms with micro-switch activation persist in legacy industrial equipment. These units serve replacement markets for installed machinery with decades-long operational lifecycles.
Mechanical technology anchors legacy industrial maintenance. Optical platforms are climbing the fastest in revenue contribution.
Application:
End-use concentration patterns fragment between climate-control integration mandates and standalone automation systems.
- Irrigation Management:Soil-moisture-correlated cutoff systems with wireless telemetry backhaul. Water conservation mandates in drought-affected agricultural regions are tightening compliance requirements for automated suspension.
- Automotive Systems:Windshield-integrated wiper activation with LIN bus integration to central energy management computers. EPA fuel economy standards in the United States propel adoption as aerodynamic optimization packages eliminate unnecessary wiper drag.
- Weather Monitoring:Meteorological station precipitation detection with data logging for climatological databases. National weather services maintain steady procurement for ground-truth calibration of radar systems.
- Smart Home Devices:Skylight and window automation with home-automation hub integration. Residential construction in water-scarce municipalities is incorporating these units into building code compliance for runoff management.
Automotive systems command the revenue base. Irrigation management is gaining share fastest as agricultural water restrictions tighten.
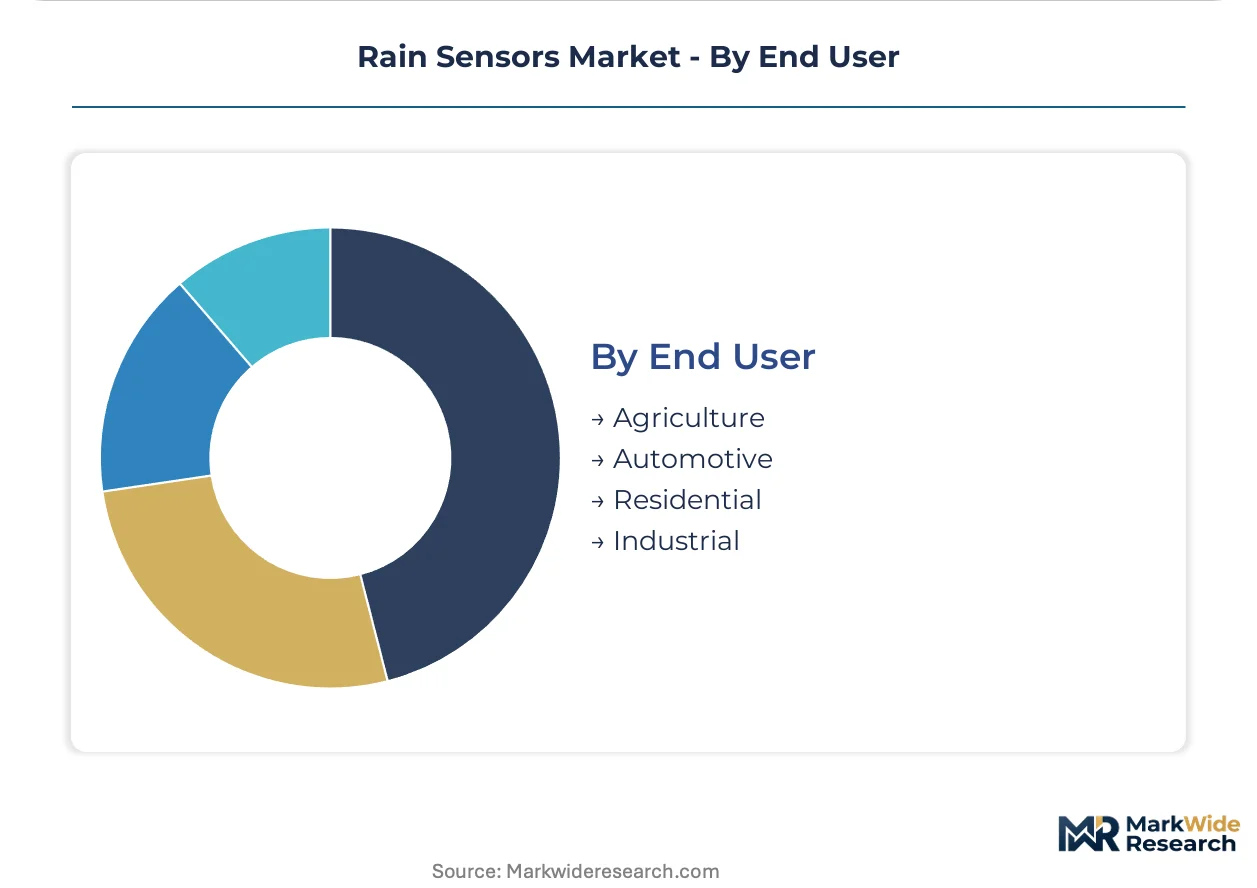
End User:
Customer type determines procurement channel structure and pricing power distribution between captive OEM supply and fragmented aftermarket.
- Agriculture:Large-scale farming operations and irrigation districts with centralized procurement of wireless sensor networks. These buyers prioritize total cost of ownership over unit price, favoring multi-year service contracts.
- Automotive:OEMs and tier-one suppliers with qualification requirements spanning durability testing under MIIT GB standards. Direct repair-chain relationships are bypassing traditional distribution networks in collision repair channels.
- Residential:Homeowners and small contractors through retail and e-commerce channels. Smart home integration compatibility with Alexa, Google Home, and Apple HomeKit drives purchase decisions.
- Industrial:Manufacturing facilities and logistics centers with rooftop monitoring for loading dock weather protection. These deployments emphasize reliability metrics and multi-year mean-time-between-failure guarantees.
Automotive customers anchor premium pricing. Residential adoption is expanding most quickly as smart home penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese integrated optics manufacturers while Chinese domestic suppliers compress margins in firmware-enabled smart sensor tiers. The EU Green Deal's energy-efficiency mandates accelerate premium optical adoption in European automotive channels. China's eastern manufacturing corridor consolidates procurement for local EV brands seeking cost-optimized digital alternatives.
Germany
Automotive OEMs in Stuttgart and Munich scale purchases of multispectral infrared arrays for highway-speed wiper activation. The EU F-Gas Regulation mandates HVAC-wiper system integration that forces unified sensor-controller module certification. Baden-Württemberg's precision optics cluster anchors premium emitter supply chains serving European premium vehicle platforms.
China
Domestic EV brands in Shanghai and Shenzhen consolidate smart sensor procurement with local firmware-enabled suppliers. MIIT enforces GB standards for automotive electronics reliability that dictate durability testing protocols for market access. The Yangtze River Delta manufacturing corridor captures contracts from emerging EV manufacturers seeking integrated digital solutions.
Japan
Tier-one suppliers in Aichi Prefecture advance optical sensor integration for advanced driver-assistance systems requiring picofarad-level precision. METI promotes domestic semiconductor fabrication capacity for capacitive sensing element production. The Chubu region's integrated optics manufacturers control infrared emitter supply to Asian and European automotive channels.
United States
Collision repair networks establish direct supplier agreements for sensor-wiper bundle replacements bypassing traditional distribution. EPA fuel economy standards propel OEM adoption as aerodynamic optimization packages eliminate unnecessary wiper drag. The Midwest automotive belt concentrates aftermarket procurement consolidation among independent service centers.
India
Irrigation districts in Maharashtra and Gujarat deploy wireless sensor networks for soil-moisture-correlated cutoff systems under tightening water conservation mandates. The central government's agricultural automation subsidies accelerate procurement of cost-optimized capacitive designs. Domestic fabrication capacity for flexible substrate electrode arrays concentrates in Pune and Ahmedabad industrial zones.
Rain Sensors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying dielectric substrates and infrared emitters. The vendor base concentrates around three structural tiers: captive semiconductor fabricators, integrated optics manufacturers, and compact design specialists. Two strategic archetypes dominate competitive positioning—vertically integrated technology conglomerates controlling emitter supply chains, and regional specialists optimizing packaging efficiency for specific vehicle architectures. Competitive moves center on backward integration into semiconductor fabrication and direct repair-chain relationship building that bypasses traditional tier-one distribution networks.
Among European automotive suppliers, Valeo SA and Robert Bosch GmbH exemplify the vertically integrated archetype through captive control over critical sensing element production. HELLA GmbH & Co. KGaA occupies a position within the compact design specialist tier, representing regional optimization strategies for crowded vehicle architectures. These three entities anchor the competitive structure through differentiated approaches to technology control and customer channel access.
| Leading Market Players |
|---|
| Valeo SA |
| HELLA GmbH & Co. KGaA |
| Robert Bosch GmbH |
| DENSO Corporation |
| Continental AG |
| ZF Friedrichshafen AG |
| Melexis NV |
| Sensata Technologies |
| Hyundai Mobis |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor's volatile container rates amplify cost differentials between German infrared emitter supply and Chinese capacitive substrate production, concentrating pricing power with integrated optics manufacturers while compressing margins for assembly-only suppliers serving cost-sensitive agricultural buyers.
Pricing Analysis
The configured-to-order premium spread separates firmware-enabled smart sensors with embedded calibration algorithms from analog units with fixed-threshold designs. Automotive OEM procurement runs through contract-based long-term offtake agreements where MIIT GB certification tier and LIN bus integration capability drive price differentiation. Pricing pressure stems from domestic Chinese suppliers capturing smart sensor contracts from local EV brands. Agricultural irrigation districts exhibit highest price sensitivity, while European premium automakers tolerate premium positioning for multispectral infrared arrays.
Supply Chain Analysis
Export-control regimes on advanced semiconductor fabrication equipment constrain capacitive sensing element production expansion outside established East Asian networks. Infrared emitter supply concentrates in Germany and Japan, while flexible substrate electrode arrays source from China and India. Specialized dielectric substrates and multispectral emitter arrays constitute critical input dependencies. Single-source vulnerability pervades premium optical component tiers. Distribution runs through direct repair-chain relationships that bypass traditional tier-one distribution networks in collision repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as automotive OEMs consolidate sensor procurement with tier-one suppliers possessing in-house durability laboratories, fragmenting aftermarket channel access for component specialists lacking certification infrastructure.
For Market Incumbents: Entrench position through captive semiconductor fabrication for capacitive sensing elements and backward integration into infrared emitter production. Valeo SA's integrated optics manufacturing model demonstrates how upstream control over premium optical supply insulates against price erosion from Chinese digital sensor competitors. Prioritize GB standards certification investment to defend access to domestic EV procurement in China's eastern manufacturing corridor. For New Entrants and Emerging Players: Pursue white-space opportunities in wireless sensor modules for agricultural irrigation automation, where cost-optimized capacitive designs face less entrenched incumbent control than automotive optical tiers. India's Maharashtra and Gujarat irrigation districts present penetrable demand pools under tightening water conservation mandates. Establish direct service contracts with farming cooperatives rather than competing through traditional distribution. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with in-house emitter fabrication or firmware-enabled edge-computing capabilities over pure-play assembly operations. The long-term viability window favors suppliers controlling both optical physics and semiconductor design competencies. Watch for inflection signals in EU F-Gas Regulation enforcement intensity, which would accelerate HVAC-wiper system integration mandates and expand addressable market for unified sensor-controller modules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Fabrication | Captive production of capacitive sensing elements reduces exposure to East Asian foundry capacity constraints. |
| GB Standards Certification Investment | MIIT durability testing protocols create market access barriers favoring established laboratory infrastructure. |
| Direct Repair-Chain Relationship Building | Collision repair network procurement consolidation bypasses traditional tier-one distribution intermediaries. |
| Firmware-Enabled Smart Sensor Development | Embedded machine-learning inference commands pricing separation from analog alternatives in EV channels. |
| Multispectral Infrared Array Platform Launch | Adaptive threshold algorithms displace fixed-threshold optical detectors in European premium OEM specifications. |
Research Methodology
A spread of perspectives from automotive platform engineers, tier-one supplier procurement leads, agricultural irrigation district managers, and aftermarket collision repair operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, customs records of infrared emitter trade flows, and MIIT regulatory filing disclosures. Bottom-up sensor shipment estimates triangulated against top-down automotive production and agricultural automation capex projections.
Demand-supply balance dynamics across optical and capacitive technology tiers anchored the analytical framework throughout the projection horizon. Segmentation modeling incorporated product architecture, technology type, application end-use, and regional production cluster dimensions. CAGRs derived from fitted growth curves calibrated to OEM procurement cycle visibility and agricultural water mandate implementation timelines. Forecast inputs included EV platform rollout schedules and EU Green Deal enforcement intensity assumptions.
Sensitivities concentrate around semiconductor foundry capacity allocation shifts and EU F-Gas Regulation verification protocol changes. Forecasts reflect documented assumptions regarding MIIT GB standards adoption velocity and infrared emitter supply expansion. Material shifts in export-control regime stringency or EPA fuel economy standard stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Microsensor Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Thermistor Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Vision Sensor Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Motion Control Encoders Market