
 Doppler Lidar Market | 2026-2036
Doppler Lidar Market Size, Share, and Industry Trends Forecast 2026-2036
Doppler Lidar Market Insights
F-Gas Regulation is broadening the cost-of-entry calculus for Doppler lidar manufacturers selling into European wind energy markets. Mitsubishi Electric leverages its fiber optic laser expertise to sustain premium positioning in coherent systems. NRG Systems anchors North American demand through deep channel relationships with utility-scale wind developers. HALO Photonics differentiates via compact platform designs suited for distributed meteorological networks.
Doppler lidar is a remote sensing instrument that transmits laser pulses and detects frequency shifts in backscattered light to measure wind velocity, aerosol density, and atmospheric boundary layer dynamics with range resolutions typically spanning 10 meters to several kilometers. The device serves meteorological agencies, wind farm operators, and aviation authorities requiring precise, real-time wind field characterization for safety and efficiency optimization. Scanning Doppler Lidar dominates commercial revenue due to its three-dimensional wind mapping capability across large rotor diameters, while Coherent Doppler Lidar captures the fastest expansion trajectory as turbine OEMs demand higher spatial resolution at hub heights exceeding 150 meters. Fiber Optic technology leads installed base because of its proven reliability in offshore salt environments, though Photonic Integrated Circuit architectures are emerging as the margin pool of interest for next-generation miniaturized units.
The US Federal Aviation Administration enforces wake vortex and wind shear detection standards that mandate lidar performance benchmarks at commercial airports, while the EPA integrates Doppler lidar into air quality monitoring protocols for particulate dispersion modeling. China's Ministry of Ecology and Environment deploys GB-standardized lidar networks for regional haze tracking, creating dual-use procurement channels that blend meteorological and environmental compliance functions. Stakeholders must weigh capital intensity against regulatory tailwinds when calibrating manufacturing scale and geographic prioritization.
Market Dynamics
Offshore wind turbine hub heights climbing past 150 meters are forcing wind farm operators to abandon cup anemometers in favor of remote sensing systems that capture full rotor disk wind profiles without tower-mounted infrastructure.
Growth Catalysts
- China's offshore wind deployment:The Ministry of Ecology and Environment's GB-standardized lidar networks for regional haze tracking create dual-use procurement channels blending meteorological and environmental compliance functions.
- F-Gas Regulation compliance pressure:Europe's tightening requirements for laser cooling systems are broadening the cost-of-entry calculus and favoring manufacturers with advanced thermal management architectures.
- Fiber optic reliability in salt environments:Proven performance in offshore installations is driving replacement cycles at aging North Sea and Baltic wind farms.
Market Restraints
- Rare earth element supply concentration:Neodymium and erbium doping materials for fiber lasers concentrate in Chinese processing facilities, creating input cost volatility and geopolitical exposure.
- Photonic Integrated Circuit yield limitations:Semiconductor foundry capacity for indium phosphide substrates remains constrained below commercial scale for miniaturized coherent systems.
- Aviation certification timelines:FAA wake vortex detection standards mandate multi-year validation protocols that compress manufacturer cash conversion cycles.
Strategic Opportunities
- Urban air quality monitoring convergence:EPA particulate dispersion modeling protocols and municipal climate action plans are opening non-wind revenue streams for atmospheric boundary layer characterization.
- Photonic Integrated Circuit miniaturization:Convergence of silicon photonics with coherent detection architectures enables palm-sized units for distributed meteorological networks previously served by radar.
- India's renewable energy corridor:The CEA's wind resource assessment mandates for new project financing are creating first-mover advantages for lidar suppliers establishing local calibration facilities.
Industry Challenges
- Atmospheric optics modeling expertise scarcity:The intersection of laser physics, signal processing, and boundary layer meteorology limits qualified field application engineering talent pools.
- Multi-jurisdiction type certification complexity:IEC 61400-12-1 power performance measurement standards require country-specific adaptations that fragment product platform economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Doppler Lidar Market |
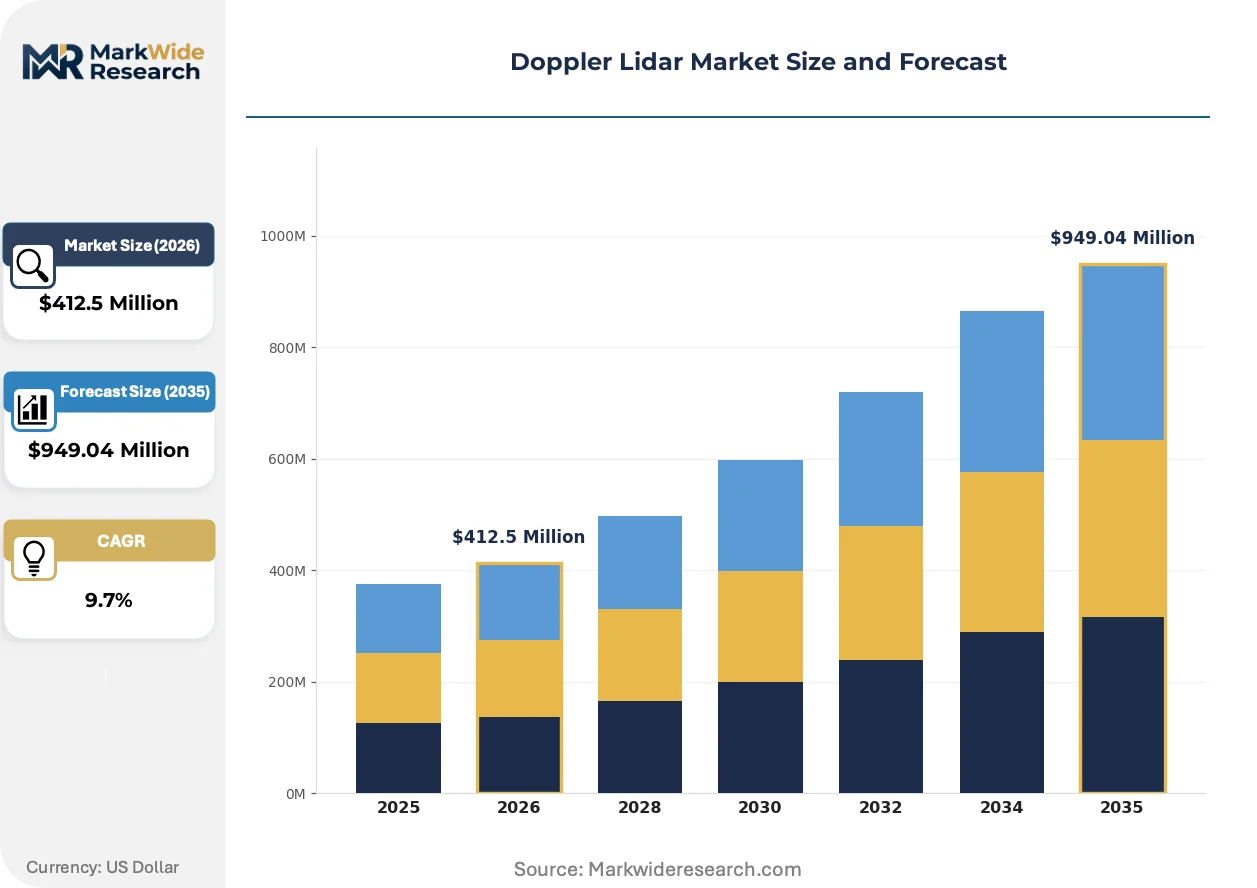
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $949.04 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scanning Doppler Lidar, Non-Scanning Doppler Lidar, Frequency Modulated Doppler Lidar, Coherent Doppler Lidar Technology: Laser Diode, Fiber Optic, Solid State, Microelectromechanical Systems, Photonic Integrated Circuit Application: Weather Observation, Traffic Management, Wind Resource Assessment, Aerospace Surveillance, Environmental Monitoring End User: Metrology Institutes, Telecommunication Providers, Aviation Authorities, Renewable Energy Companies |
| Companies Covered | Leosphere, Mitsubishi Electric, NRG Systems, HALO Photonics, ZX Lidars, Windar Photonics, Vaisala, Deutsche WindGuard, Platform Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Doppler Lidar Market Trends and Innovations
Hardware miniaturization and software-defined signal processing are compressing the traditional separation between research-grade atmospheric science instruments and operational wind farm control systems.
Photonic Integrated Circuit architectures are consolidating the optical bench functions of coherent Doppler lidar onto single substrates. Turbine OEMs demanding hub-height wind characterization at spatial resolutions below 10 meters are accelerating adoption of these chip-scale systems. The technology is consolidating vendor margins away from discrete component suppliers toward integrated photonics foundries with captive packaging capabilities.
Europe's F-Gas Regulation is tightening compliance requirements for laser cooling systems used in high-power coherent transmitters. Manufacturers serving wind energy markets must redesign thermal management subsystems or absorb refrigerant phase-out costs. German and Danish project developers are prioritizing suppliers with documented lifecycle refrigerant management protocols in procurement specifications.
Wind farm operators are unbundling measurement campaigns from turbine supply agreements and contracting directly with lidar service providers. This disintermediation of OEM-controlled wind resource assessment is compressing equipment sales cycles while expanding recurring calibration and data validation revenue streams. The pattern is most visible in Spanish and Portuguese auction rounds where independent power producers face stricter lender verification requirements.
Doppler Lidar Market Segmentation
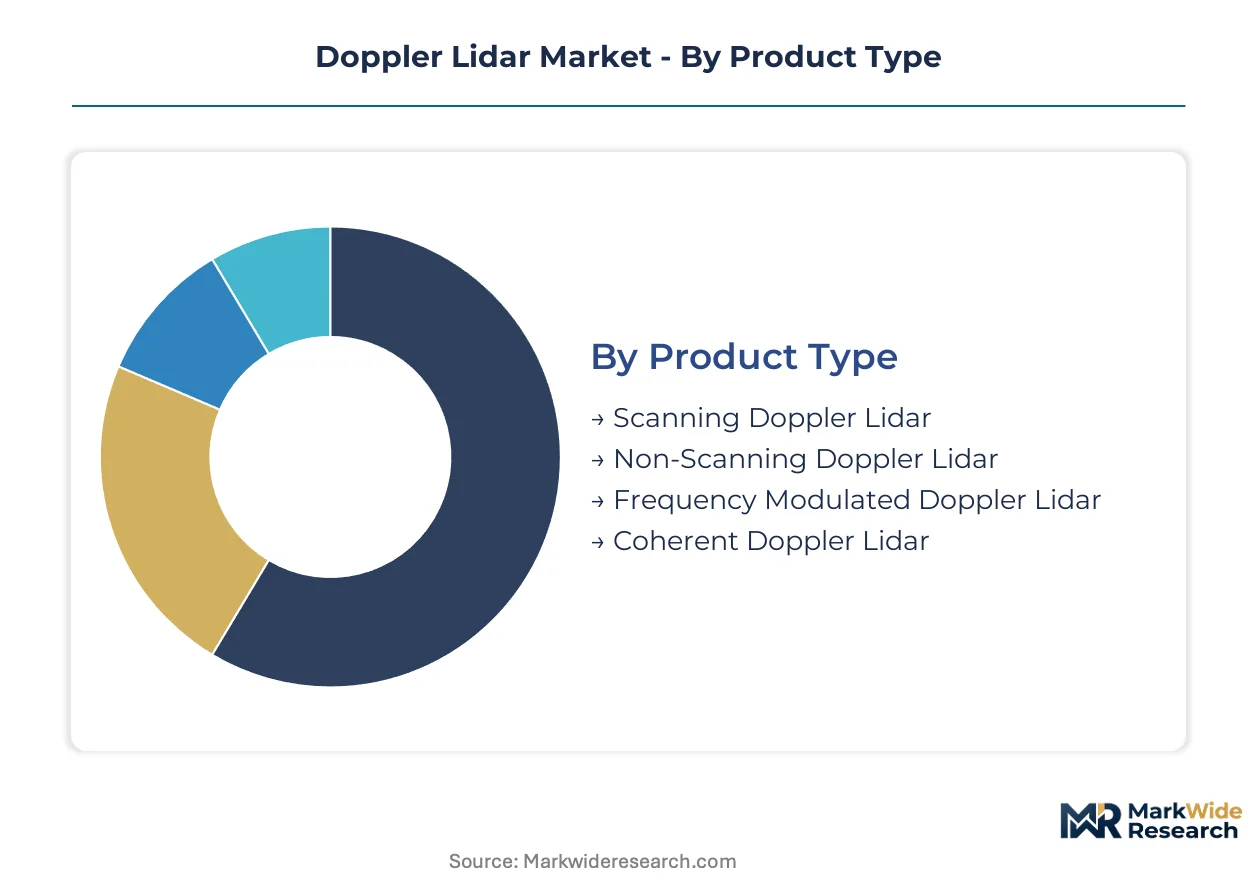
Doppler lidar segmentation reflects divergent integration depths across atmospheric sensing applications. Standalone scanning systems dominate utility-scale wind farms while chip-scale coherent modules embed directly into turbine nacelles for real-time pitch control.
Product Type:
Scanning systems operate as capital equipment with discrete installation protocols, whereas non-scanning and frequency-modulated variants embed into larger sensor networks with minimal field calibration.
- Scanning Doppler Lidar:Rotating optical heads capture three-dimensional wind fields across full rotor diameters exceeding 150 meters. Offshore wind developers in China and the North Sea specify these systems for bankable power curve verification under IEC 61400-12-1 standards.
- Coherent Doppler Lidar:Heterodyne detection architectures achieve Doppler-shift resolution below 0.1 meters per second through optical mixing of transmitted and backscattered signals. Turbine OEMs embed these for hub-height wind preview at spatial resolutions under 10 meters.
- Non-Scanning Doppler Lidar:Fixed-beam configurations serve aviation wake vortex monitoring at major hub airports.
- Frequency Modulated Doppler Lidar:Chirped pulse compression enables range-resolved aerosol profiling for urban air quality networks.
Volume placements concentrate in Scanning Doppler Lidar; the faster expansion belongs to Coherent Doppler Lidar.
Technology:
Cost tiers separate proven fiber optic platforms from emerging photonic integrated circuits still scaling through semiconductor foundries.
- Fiber Optic:Erbium-doped fiber amplifiers deliver kilowatt-class peak powers with demonstrated mean-time-between-failures exceeding 50,000 hours in North Sea salt environments. Danish and German project developers prioritize these platforms for 25-year asset lifecycles.
- Photonic Integrated Circuit:Indium phosphide substrates consolidate lasers, modulators, and detectors onto single chips. Silicon photonics foundries in Taiwan and the United States are ramping volume production for palm-sized meteorological nodes.
- Laser Diode:Direct-detection architectures serve cost-sensitive traffic management installations.
- Solid State:Diode-pumped bulk crystal designs persist in research-grade atmospheric boundary layer studies.
- Microelectromechanical Systems:MEMS beam-steering chips enable compact scanning without mechanical rotation.
Installed base tilts toward Fiber Optic; Photonic Integrated Circuit architectures are climbing the fastest.
Application:
Customer maturity varies sharply between regulated aviation mandates and discretionary environmental monitoring budgets.
- Wind Resource Assessment:Bankable energy yield calculations require 12-month measurement campaigns with uncertainty budgets below 3 percent. India's Central Electricity Authority mandates lidar validation for new project financing, creating calibration service demand.
- Weather Observation:National meteorological agencies operate networks for severe weather nowcasting and numerical model assimilation. China's Ministry of Ecology and Environment deploys GB-standardized lidar for regional haze tracking alongside meteorological functions.
- Traffic Management:Highway agencies deploy visibility sensors for fog detection and speed advisory systems.
- Aerospace Surveillance:FAA wake vortex detection standards mandate multi-year validation protocols at commercial airports.
- Environmental Monitoring:EPA particulate dispersion protocols open municipal procurement channels for atmospheric boundary layer characterization.
Revenue concentrates in Wind Resource Assessment; Weather Observation is gaining share fastest.
End User:
Procurement authority is fragmenting as renewable energy companies bypass turbine OEMs to contract directly with lidar service providers.
- Renewable Energy Companies:Independent power producers in Spain and Portugal now unbundle measurement campaigns from turbine supply agreements. Direct contracting compresses equipment sales cycles while expanding recurring calibration revenue.
- Aviation Authorities:FAA mandates enforce wake vortex and wind shear detection standards with specific lidar performance benchmarks.
- Metrology Institutes:National standards bodies maintain reference-grade systems for instrument intercomparison campaigns.
- Telecommunication Providers:Free-space optical link planners use boundary layer profiles to predict atmospheric scintillation.
Contract volume concentrates in Renewable Energy Companies; Aviation Authorities are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's offshore wind special economic zones concentrate manufacturing capacity and drive procurement concentration for remote sensing systems. Denmark's Esbjerg cluster anchors European supply chains for turbine installation vessels and associated meteorological equipment.
China
Offshore wind deployment in Jiangsu and Guangdong provinces accelerates demand for hub-height wind measurement systems. The Ministry of Ecology and Environment's GB-standardized lidar networks for regional haze tracking create dual-use procurement channels blending meteorological and environmental compliance functions. Yangtze River Delta manufacturers integrate photonic components into compact coherent detection platforms.
United States
Utility-scale wind developers in Texas and Iowa deploy scanning systems for power curve verification under evolving grid interconnection standards. The FAA enforces wake vortex and wind shear detection benchmarks at commercial airports that mandate specific lidar performance thresholds. Greater Boston hosts atmospheric research institutions driving coherent detection algorithm development.
Germany
North Sea wind farm operators prioritize fiber optic platforms with documented lifecycle refrigerant management under tightening F-Gas Regulation requirements. The country's national meteorological service operates reference-grade networks for instrument intercomparison campaigns. Hamburg and Bremerhaven industrial clusters specialize in offshore logistics and associated sensor calibration services.
India
The Central Electricity Authority's wind resource assessment mandates for new project financing create calibration service demand across Gujarat and Tamil Nadu renewable energy corridors. State-level renewable purchase obligations accelerate procurement of bankable measurement systems. Karnataka's technology hubs incubate local assembly partnerships for distributed meteorological networks.
United Kingdom
Scottish offshore lease rounds require multi-year measurement campaigns with uncertainty budgets below three percent for lender verification. The national meteorological agency integrates Doppler lidar into severe weather nowcasting infrastructure. Aberdeen's energy transition cluster repurposes oilfield service capabilities toward floating wind sensor deployment.
Doppler Lidar Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. Market structure tilts toward consolidation at the high-performance coherent detection segment while fragmentation persists in cost-sensitive direct-detection applications. Three archetypes dominate: integrated photonics foundries with captive packaging capabilities, fiber optic subsystem specialists leveraging offshore reliability records, and atmospheric science instrumentation houses with research-grade calibration protocols. Competitive moves center on semiconductor foundry partnerships for photonic integrated circuit volume production and thermal management subsystem redesigns addressing refrigerant phase-out timelines.
Within the coherent detection tier, Mitsubishi Electric and HALO Photonics occupy positions reflecting divergent scale strategies. NRG Systems anchors North American demand relationships through utility-scale wind developer channels. These three exemplify how geographic proximity to major offshore wind clusters and aviation authority procurement offices shapes competitive positioning.
| Leading Market Players |
|---|
| Leosphere |
| Mitsubishi Electric |
| NRG Systems |
| HALO Photonics |
| ZX Lidars |
| Windar Photonics |
| Vaisala |
| Deutsche WindGuard |
| Platform Aerospace |
| Others |
Pricing and Supply Chain Analysis
Erbium-doped fiber amplifier costs cascade through three pricing tiers as procurement contracts lengthen from spot purchases to decade-long offshore wind service agreements. Chinese rare earth processing concentration amplifies input volatility for manufacturers serving European and North American project developers facing F-Gas Regulation compliance deadlines.
Pricing Analysis
Lead-time premiums of 30-40 percent apply to scanning systems required within six months for offshore installation windows, while spot inventory of coherent modules trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61400-12-1 certified units from uncertified meteorological nodes and refurbished North Sea equipment. Cost compression in the standard tier is intensifying because Taiwanese photonic foundries are scaling indium phosphide wafer output. Independent power producers in Iberian auction rounds exhibit highest price sensitivity; aviation authorities mandated by FAA standards show least.
Supply Chain Analysis
Freight costs from Yangtze River Delta manufacturing clusters to North Sea ports add 8-12 percent to landed equipment costs, compressing margins on compact coherent systems. Component supply draws from Chinese rare earth processing for erbium and neodymium doping, Taiwanese semiconductor foundries for photonic integrated circuits, and German precision optics houses for scanning head assemblies. Single-source vulnerability concentrates in indium phosphide substrate supply below commercial scale. Distribution runs through turbine OEM channel partnerships, direct IPP contracting, and atmospheric research institution procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as F-Gas Regulation compliance costs force subscale manufacturers toward exit or acquisition. Photonic integrated circuit yield limitations and multi-year aviation certification timelines favor players with captive foundry partnerships and regulatory affairs depth.
For Market Incumbents: To counter photonic integrated circuit foundry capacity constraints, secure multi-year wafer allocation agreements with Taiwanese semiconductor houses and backward integration into erbium-doped fiber amplifier production. Channel control through direct IPP contracting relationships in Spain and Portugal insulates against turbine OEM disintermediation.
For New Entrants and Emerging Players: Enter via India's CEA-mandated wind resource assessment calibration services, where local facility establishment creates first-mover positioning before international competitors deploy. Urban air quality monitoring networks in EPA-regulated US municipalities offer penetrable white space with shorter sales cycles than aviation certification pathways. Partner with municipal climate action offices for atmospheric boundary layer characterization pilots.
For Investors and Strategic Acquirers: FAA issuance of wake vortex detection system approvals to non-incumbent manufacturers is the leading indicator that certification bottlenecks are easing and acquisition multiples will compress. Five-to-ten year viability favors vertically integrated specialists with captive photonic packaging capabilities over discrete component assemblers. Monitor German and Danish project developer procurement specifications for lifecycle refrigerant management protocol requirements as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Foundry Partnership | Captive wafer allocation with TSMC or GlobalFoundries secures indium phosphide supply for coherent miniaturization. |
| Thermal Management Redesign | F-Gas Regulation-compliant refrigerant architectures unlock German and Danish offshore wind procurement eligibility. |
| Calibration Facility Localization | India CEA-mandated service hubs in Gujarat and Tamil Nadu capture renewable energy corridor financing workflows. |
| Aviation Certification Investment | FAA wake vortex system validation creates multi-year revenue visibility at commercial airport installations. |
| Direct IPP Channel Development | Unbundled measurement campaign contracting in Iberian markets compresses sales cycles and expands recurring revenue. |
Research Methodology
Multi-period observation of turbine hub height trajectories, F-Gas Regulation implementation phases, and photonic integrated circuit foundry capacity announcements anchored the trend analysis, supplemented by interviews with wind farm project developers, turbine OEM procurement officers, atmospheric research scientists, and aviation authority certification engineers. Secondary validation drew from IEC standards documentation, EPA air quality monitoring protocols, FAA wake vortex detection guidelines, and customs trade data for erbium-doped fiber amplifier imports. Bottom-up unit economics for scanning and coherent system deployments were triangulated against top-down market sizing from national meteorological agency procurement budgets and renewable energy auction measurement requirements.
Segment-weighting across product type, technology architecture, application function, and end-user procurement authority shaped the analytical framework. Coherent Doppler lidar adoption curves at hub heights exceeding 150 meters, photonic integrated circuit yield progression at Taiwanese foundries, and India's CEA mandate expansion timelines served as industry-specific forecast inputs. CAGRs were derived from installed base replacement cycles, offshore wind deployment pipelines, and regulatory compliance deadline clustering.
Revisions become necessary when indium phosphide foundry yield breakthroughs accelerate, FAA certification timelines compress, or rare earth export restrictions from Chinese processing facilities materialize. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
Europe Fingerprint Sensor Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
Torque Transducer Market
Sensors and Controls
Asia-Pacific Current Transducer Market