

High Purity Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Flow Meter Market Insights
Stainless steel is shifting toward high-performance fluoropolymer wetted surfaces in next-generation high purity flow meters, reducing ionic contamination risk in aggressive chemical streams. Endress+Hauser leverages its Swiss manufacturing base to dominate Coriolis meter precision for bioprocessing applications. Emerson Electric anchors North American demand through its Rosemount instrumentation platform calibrated for semiconductor wet-bench environments. Bronkhorst High-Tech specializes in thermal mass designs for ultra-low-flow dosing in pharmaceutical formulation.
A high purity flow meter measures fluid flow rates in processes demanding extreme cleanliness, typically achieving surface roughness below 0.25 micrometers Ra and employing electropolished 316L stainless steel or PFA linings to eliminate particle shedding. These instruments serve primarily to safeguard batch integrity in sterile manufacturing and to protect billion-dollar wafer yields from chemical contamination. Coriolis technology commands the premium tier due to its direct mass measurement capability and immunity to fluid property variations, while electromagnetic designs occupy the volume tier in large-diameter ultrapure water distribution. IoT-enabled architectures represent the fastest-expanding technology slice as fabs and drug plants pursue predictive calibration drift detection.
The FDA enforces process analytical technology guidelines that mandate validated inline flow measurement for real-time release testing in pharmaceutical operations. The EU's MDR and Annex 1 GMP revision impose escalating documentation burdens on meter suppliers serving sterile facilities. Semiconductor fabs in Taiwan, South Korea, and Germany now require SEMI F57-compliant materials and NIST-traceable calibration certificates as baseline procurement criteria. Stakeholders must weigh capital intensity against the operational risk of unplanned calibration failures in continuous bioprocessing campaigns.
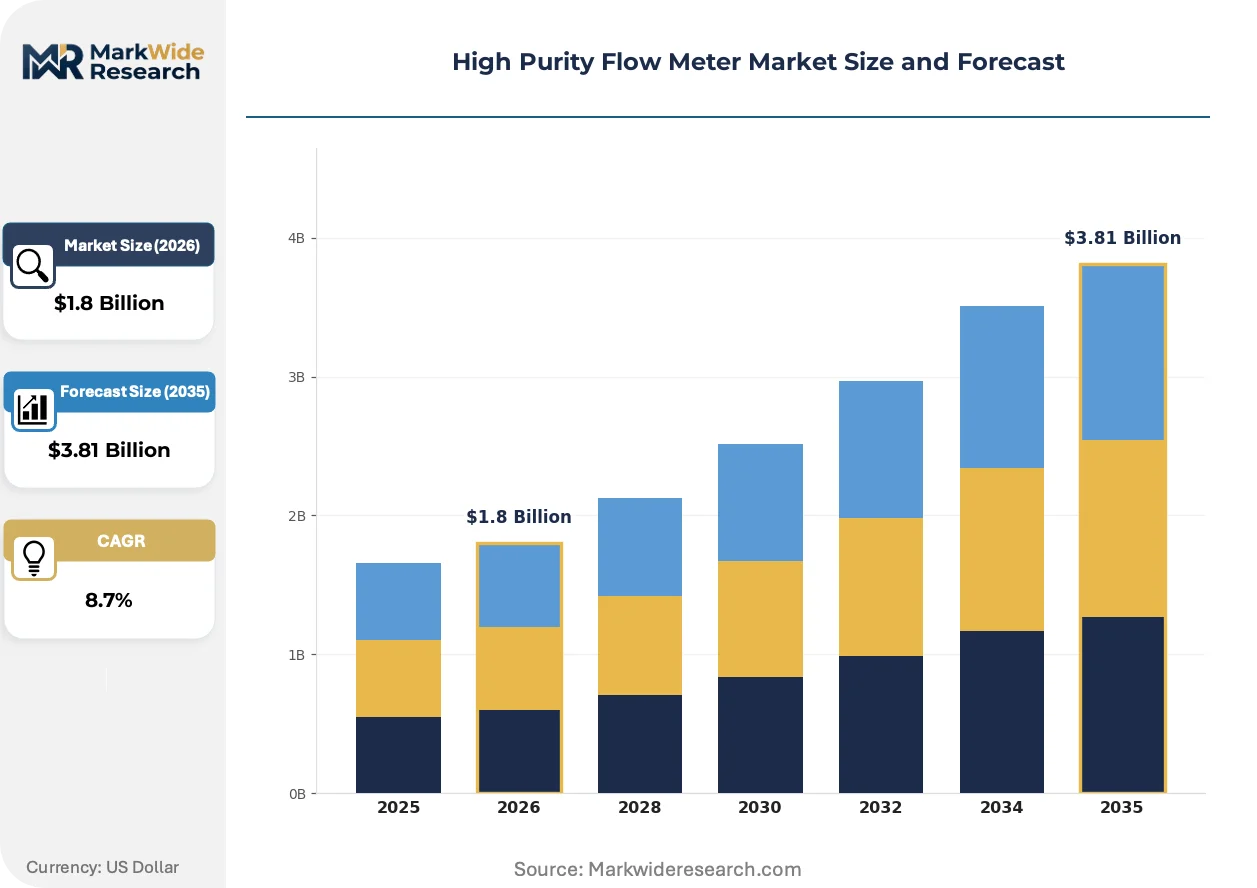
Market Dynamics
Wafer fabrication facilities in Taiwan and South Korea are driving a structural shift toward sub-1% measurement uncertainty requirements, forcing instrument suppliers to recalibrate around NIST-traceable standards and SEMI F57 material compliance as non-negotiable procurement criteria.
Growth Catalysts
- EU GMP Annex 1 Revision:The sterile manufacturing mandate tightens validation requirements for inline flow measurement, compelling pharmaceutical facilities to upgrade legacy instrumentation with electropolished 316L stainless steel meters.
- Semiconductor Cluster Expansion:Taiwan and South Korea fabs are scaling cleanroom infrastructure for advanced node production, generating acute demand for ultrapure chemical delivery systems with fluoropolymer wetted surfaces.
- FDA Process Analytical Technology:Real-time release testing requirements in bioprocessing operations mandate validated inline flow measurement, accelerating replacement cycles in sterile formulation facilities.
Market Restraints
- High-Performance Material Costs:PFA linings and electropolished 316L stainless steel command significant raw material premiums, compressing margins for volume-tier electromagnetic meter suppliers.
- Calibration Infrastructure Concentration:NIST-traceable calibration capabilities concentrate in Swiss and German metrology centers, creating geographic dependency for East Asian semiconductor fabs.
- Coriolis Technical Limitations:Direct mass measurement technology faces size constraints above six-inch diameters, ceding large-diameter ultrapure water distribution to electromagnetic alternatives.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO alignment with ICH Q12 guidelines creates demand for validated inline instrumentation in sterile API facilities, an underpenetrated geography for premium Coriolis meters.
- IoT Predictive Maintenance Convergence:Wireless sensor networks combined with edge computing enable calibration drift detection before batch failure, opening service revenue streams in continuous bioprocessing.
- China Dual Carbon Goals:NMPA green manufacturing incentives reward facilities with real-time process monitoring, accelerating electromagnetic meter adoption in domestic pharmaceutical plants.
Industry Challenges
- SEMI F57 Certification Timelines:Material qualification protocols for semiconductor-grade instruments extend product development cycles by twelve to eighteen months, delaying revenue recognition.
- Legacy System Integration Complexity:Brownfield pharmaceutical facilities operate proprietary SCADA architectures that resist seamless integration with IoT-enabled flow meters, requiring costly middleware development.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Flow Meter Market Trends and Innovations
Three distinct forces are reshaping instrument architecture: fluoropolymer materials are displacing stainless steel in aggressive chemical streams, regulatory documentation burdens are escalating across sterile manufacturing jurisdictions, and buyer procurement patterns are compressing supplier qualification timelines.
Multi-variable Coriolis transmitters are unifying density, temperature, and mass flow measurement in single instruments. Bioprocessing facilities in Switzerland and Germany are adopting these consolidated platforms to reduce instrument count in cleanroom environments. This unification is compressing the addressable market for standalone temperature and density sensors while elevating meter complexity requirements.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of PFA lining chemistries used in high purity flow meters. The industrial consequence is a qualification bottleneck as suppliers resubmit material safety dossiers to ECHA. Semiconductor wet-bench equipment manufacturers in Germany are responding by accelerating alternative fluoropolymer evaluations to maintain SEMI F57 compliance.
Contract manufacturing organizations are consolidating supplier panels from twelve vendors to three preferred instrumentation partners. This concentration is displacing fragmented procurement through distributor networks with direct manufacturer relationships. The shift is most visible in North American sterile injectables facilities, where Emerson and Endress+Hauser are capturing multi-year framework agreements.
High Purity Flow Meter Market Segmentation
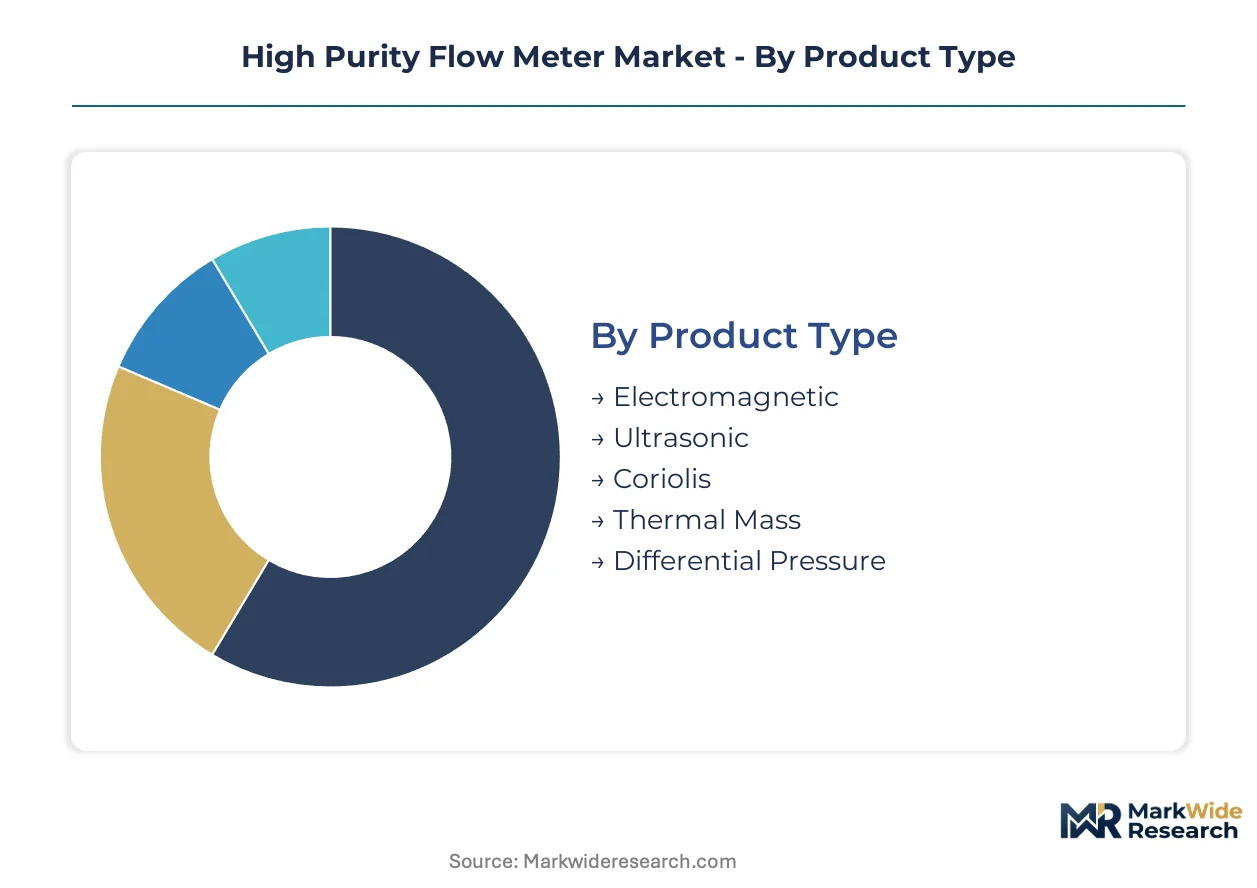
High purity flow meter procurement decisions hinge on matching measurement technology to contamination risk profiles. Semiconductor fabs and sterile drug plants impose divergent material and calibration requirements that reshape supplier margins across each segment category.
Product Type:
Capital intensity varies sharply across measurement principles, with Coriolis systems demanding precision machining and multi-variable calibration infrastructure while electromagnetic designs leverage simpler coil architectures.
- Coriolis:Direct mass measurement through vibrating tube mechanics achieves sub-1% uncertainty required for advanced node chemical delivery in Taiwan and South Korean fabs. NIST-traceable calibration and SEMI F57 material compliance inflate upfront costs threefold over electromagnetic alternatives.
- Electromagnetic:Coil-induced magnetic field measurement dominates large-diameter ultrapure water distribution with no moving parts and minimal maintenance. Demand concentrates in municipal semiconductor plant utilities where six-inch-plus line sizes exceed Coriolis technical limits.
- Ultrasonic:Transit-time or Doppler principles enable non-invasive clamp-on installation for retrofit pharmaceutical lines.
- Thermal Mass:Heated sensor elements excel at ultra-low-flow dosing in sterile API formulation suites.
- Differential Pressure:Orifice plate and venturi designs persist in legacy chemical processing installations with established maintenance protocols.
Most installed capacity flows through Electromagnetic. Expansion is steepest in Coriolis.
Application:
Regulatory stringency creates tiered margin structures, with sterile manufacturing mandates imposing documentation burdens that commodity chemical processing avoids entirely.
- Semiconductor Fabrication:Wafer throughput protection drives specification for electropolished 316L stainless steel or PFA wetted surfaces with surface roughness below 0.25 micrometers Ra. Taiwan and South Korean cleanroom expansion generates acute demand for fluoropolymer-lined meters in aggressive acid and solvent streams.
- Pharmaceutical Manufacturing:FDA process analytical technology guidelines and EU GMP Annex 1 revisions mandate validated inline measurement for real-time release testing. Electropolished 316L stainless steel with full material traceability commands procurement priority in sterile injectables facilities.
- Biotech Production:Continuous processing campaigns require predictive calibration drift detection through IoT-enabled architectures.
- Chemical Processing:Bulk ultrapure chemical distribution tolerates broader uncertainty bands than semiconductor or pharmaceutical applications.
- Food & Beverage:Hygienic design standards align with pharmaceutical specifications but relax material documentation requirements.
Semiconductor Fabrication captures the highest average selling prices. Pharmaceutical Manufacturing is climbing the fastest.
Technology:
Signal processing sophistication determines service revenue potential, with digital platforms enabling predictive maintenance contracts that analog systems cannot support.
- IoT Enabled:Edge computing architectures transmit calibration drift alerts before batch failure in continuous bioprocessing. Wireless sensor networks eliminate conduit costs in cleanroom environments where penetration points risk contamination.
- Digital Signal:Microprocessor-based filtering and diagnostic capabilities support multi-variable measurement consolidation in Coriolis transmitters.
- WirelessHART:IEC 62591 standard protocol ensures interoperability with Emerson and Endress+Hauser host systems in brownfield pharmaceutical SCADA integrations.
- Wireless:Proprietary radio protocols serve niche applications lacking WirelessHART infrastructure.
- Analog Signal:4-20mA outputs persist in legacy installations resisting digital migration.
Digital Signal dominates current installations. IoT Enabled is gaining share fastest.
End User Industry:
Facility scale and validation burden split the market between high-volume manufacturing plants and smaller quality assurance operations with sporadic procurement patterns.
- Manufacturing Plants:Continuous production lines in semiconductor and pharmaceutical operations demand redundant meter configurations with automated failover. Multi-year framework agreements with preferred suppliers displace fragmented distributor purchasing.
- Quality Assurance Facilities:Metrology laboratories require NIST-traceable reference standards for in-house calibration verification of production instruments.
- Laboratories:R&D environments prioritize flexibility over certification completeness.
- Research Institutes:Grant-funded procurement cycles create lumpy demand with extended qualification timelines.
Manufacturing Plants absorb the majority of unit volume. Quality Assurance Facilities show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park anchors global demand for high purity flow meters, with wafer fabrication facilities driving sub-1% measurement uncertainty specifications. Semiconductor clusters in South Korea and Germany follow closely, while pharmaceutical manufacturing in the United States and India generates parallel demand streams for sterile process instrumentation.
United States
FDA process analytical technology guidelines mandate validated inline flow measurement for real-time release testing in bioprocessing operations. The agency's sterile manufacturing enforcement compels pharmaceutical facilities to upgrade legacy instrumentation with full material traceability. Boston's biotech corridor and North Carolina's Research Triangle host continuous processing campaigns requiring predictive calibration architectures.
Taiwan
TSMC and United Microelectronics Corporation are expanding 3-nanometer fabrication capacity, generating acute demand for fluoropolymer-lined meters in aggressive chemical delivery systems. The island's Industrial Development Bureau enforces SEMI F57 compliance as baseline procurement criteria for all science park facilities. Hsinchu Science Park fabs now require NIST-traceable calibration certificates with twelve-month validation cycles.
South Korea
Samsung Electronics and SK Hynix are scaling Pyeongtaek and Yongin cleanroom infrastructure for advanced memory production. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative channels investment into ultrapure chemical distribution systems. Seoul Capital Area fabs specify electropolished 316L stainless steel with surface roughness below 0.25 micrometers Ra for all wet-bench environments.
Germany
BASF and Merck KGaA are expanding pharmaceutical-grade chemical production for export to Asian semiconductor markets. The EU's MDR and Annex 1 GMP revision impose escalating documentation burdens on meter suppliers serving sterile facilities. Bavaria's chemical corridor and Baden-Württemberg's precision engineering clusters host metrology centers providing NIST-traceable calibration services.
India
CDSCO alignment with ICH Q12 guidelines creates demand for validated inline instrumentation in sterile API facilities across Maharashtra and Gujarat. The country's national pharmaceutical regulator is tightening good manufacturing practice enforcement for export-oriented formulation plants. Hyderabad's Genome Valley and Ahmedabad's injectables corridor represent underpenetrated geographies for premium Coriolis meter deployment.
High Purity Flow Meter Market Competitive Landscape
Global majors compete with regional champions across calibration infrastructure and material certification capabilities. The vendor base stratifies into three tiers: precision metrology specialists with Swiss and German manufacturing heritage, diversified industrial conglomerates with broad instrumentation portfolios, and regional fabricators serving price-sensitive utility applications. Consolidation pressure is intensifying as contract manufacturing organizations reduce supplier panels from twelve vendors to three preferred partners. Multi-year framework agreements are displacing fragmented procurement through distributor networks.
Within the precision metrology tier, Endress+Hauser and Bronkhorst High-Tech occupy positions defined by NIST-traceable calibration capabilities and SEMI F57 material compliance. Among diversified industrial groups, Emerson Electric exemplifies scale-driven instrumentation platforms calibrated for semiconductor wet-bench environments. Siemens and ABB represent European conglomerates with broad automation portfolios spanning pharmaceutical and chemical processing applications. These archetypes reflect divergent strategic postures: specialization versus diversification, premium positioning versus volume tier penetration.
| Leading Market Players |
|---|
| Endress+Hauser |
| Emerson Electric |
| Siemens |
| ABB |
| Yokogawa Electric Corporation |
| KROHNE |
| Honeywell International |
| Badger Meter |
| Bronkhorst High-Tech |
| Others |
Pricing and Supply Chain Analysis
NIST-traceable calibration service premiums in Switzerland and Germany cascade through three distinct pricing tiers, with semiconductor fabs absorbing the steepest markups while municipal utilities negotiate volume discounts on electromagnetic alternatives.
Pricing Analysis
Input-cost pass-through from electropolished 316L stainless steel and PFA lining raw materials drives pricing stratification across certification grades. Premium Coriolis systems command threefold multiples over electromagnetic equivalents due to SEMI F57 compliance burdens and NIST-traceable calibration certificates. Cost compression in the volume-tier electromagnetic segment intensifies as Chinese suppliers expand fluoropolymer lining capacity. Pharmaceutical manufacturing plants exhibit lowest price sensitivity given batch failure risks, while municipal semiconductor utilities drive hardest bargain on large-diameter water distribution contracts.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and German metrology centers for NIST-traceable calibration certificates, creating geographic dependency for East Asian semiconductor fabs. Precision machining capacity concentrates in Germany, Switzerland, and Japan, while PFA lining feedstock draws from Chinese and American chemical producers. Tariff exposure on fluoropolymer imports threatens margin stability for European meter assemblers. Distribution runs through direct manufacturer relationships with fabs and pharmaceutical CMOs, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high purity flow meter market functions as a stable compounder, with regulatory ratcheting in sterile manufacturing and semiconductor fabrication creating durable replacement demand.
For Market Incumbents: Anchor calibration infrastructure investments in Taiwan and South Korea to reduce geographic dependency risks. Defend margin position by accelerating SEMI F57 certification timelines ahead of REACH fluoropolymer restrictions. Prioritize backward integration into PFA lining production to capture raw material premiums currently flowing to chemical suppliers.
For New Entrants and Emerging Players: CDSCO alignment with ICH Q12 guidelines in India opens a window for validated inline instrumentation in sterile API facilities. Target underpenetrated pharmaceutical manufacturing clusters in Maharashtra and Gujarat with Coriolis platforms priced below Endress+Hauser and Emerson tiers. Pursue direct sales relationships with contract manufacturing organizations consolidating supplier panels.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision metrology specialists possessing SEMI F57 certification capabilities and Swiss manufacturing heritage. Long-term viability rests on regulatory compliance moats widening through EU GMP Annex 1 and FDA process analytical technology enforcement. Monitor CDSCO inspection intensity in India as inflection indicator for geographic demand shift.
| Strategic Initiative | Industry Significance |
|---|---|
| SEMI F57 Certification Acceleration | Shortens product development cycles for semiconductor-grade instruments by preempting REACH fluoropolymer bottlenecks. |
| Calibration Infrastructure Regionalization | Reduces geographic dependency for East Asian fabs by establishing NIST-traceable centers in Taiwan and South Korea. |
| IoT Predictive Maintenance Platform Launch | Captures service revenue streams in continuous bioprocessing through calibration drift detection algorithms. |
| Backward Integration into PFA Lining | Secures fluoropolymer supply chains against ECHA reformulation delays and raw material cost volatility. |
| Direct Manufacturer Relationship Expansion | Displaces fragmented distributor networks as CMOs consolidate supplier panels from twelve vendors to three preferred partners. |
Research Methodology
Multiple input streams — executive interviews with semiconductor fab operations directors, pharmaceutical quality assurance leads, and metrology laboratory managers; secondary validation through FDA warning letters, EMA inspection observations, and SEMI standards documentation; plus customs data on fluoropolymer lining imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, application, technology, and end-user industry dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base depreciation schedules and replacement cycle acceleration factors tied to regulatory enforcement intensity. Forecast inputs incorporated wafer throughput expansion timelines from TSMC and Samsung disclosures alongside CDSCO inspection cadence projections.
Revisions become necessary when REACH fluoropolymer restrictions accelerate, NIST calibration center capacity constraints materialize, or semiconductor capital expenditure cycles inflect. Forecasts reflect documented assumptions about regulatory enforcement continuity and cleanroom infrastructure buildout pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.