
 Current Transducer Market | 2026-2036
Current Transducer Market Size, Share, and Industry Trends Forecast 2026-2036
Current Transducer Market Intelligence
Software-defined calibration and remote diagnostics subscription is consolidating recurring revenue alongside hardware shipments. LEM leverages its Geneva-based R&D footprint to sustain precision-magnetic-sensor leadership across EV traction inverters. Siemens anchors European industrial automation demand through integrated drive-and-sensor architectures. Texas Instruments competes by extending semiconductor-level signal-conditioning integration into module-level transducer designs.
A current transducer is an electromagnetic or solid-state device that measures electric current and produces a proportional output signal, typically specified by parameters such as galvanic isolation voltage, bandwidth, and linearity error below one percent. Its primary purpose is to enable safe, accurate current monitoring in power electronics, motor drives, and energy distribution systems. Hall-effect transducers dominate EV and industrial motor-drive applications where non-contact measurement and wide dynamic range matter. Transformer-based designs occupy mature utility-metering segments with stable margin pools but slower expansion. Shunt resistor technology is displacing legacy magnetic solutions in cost-sensitive automotive battery-management systems.
The US market responds to NHTSA functional-safety mandates and FCC electromagnetic-compatibility rules that dictate sensor certification for automotive and telecommunications equipment. Europe's CE-marking framework and IEC 61869 metering standards shape product design cycles and market-access timelines. China's GB standards and MIIT directives on new-energy vehicles enforce domestic testing protocols that influence transducer specification. Stakeholders must monitor how silicon-carbide power electronics and wireless sensor networks alter accuracy requirements and form-factor expectations.
Market Dynamics
Silicon-carbide power electronics is compressing switching frequencies and demanding higher-bandwidth current sensing, forcing transducer architectures to migrate from magnetic cores to solid-state designs with integrated signal conditioning.
Growth Catalysts
- EV powertrain electrification:Traction inverters and onboard chargers in battery-electric vehicles require galvanically isolated current measurement at megahertz sampling rates, pulling Hall-effect and fluxgate transducers into high-volume automotive supply chains.
- IEC 61869 metering standards:Accuracy class tightening across industrial energy management is mandating 0.2S-grade transducers for revenue-grade monitoring in smart grid deployments.
- Grid modernization programs:China State Grid and provincial distribution operators are retrofitting substations with digital instrument transformers, creating sustained demand for optical and Rogowski-coil current sensors.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings disrupt Hall-effect transducer bill-of-materials stability, compressing margins for magnetic-core-dependent suppliers.
- Shunt resistor substitution:Low-cost manganese-copper shunts with integrated isolation amplifiers are displacing magnetic solutions in cost-sensitive automotive battery management systems.
- Domestic content requirements:China's MIIT directives on new-energy vehicle components enforce local testing protocols that create non-tariff barriers for foreign transducer vendors.
Strategic Opportunities
- Wireless sensor networks:Industrial IoT architectures are creating openings for battery-free, energy-harvesting current transducers with embedded RF transmission in predictive maintenance applications.
- India PLI scheme:Production-linked incentives for domestic solar inverter and EV component manufacturing are attracting transducer localization investments from multinational suppliers.
- Software-defined calibration:Cloud-based accuracy drift monitoring and over-the-air recalibration subscriptions are generating recurring revenue streams alongside hardware shipments.
Industry Challenges
- Magnetic sensor design expertise scarcity:The talent pool for precision fluxgate and Hall-effect core design is concentrated among retiring specialists in Central Europe and Japan, constraining R&D velocity.
- Functional safety certification timelines:ISO 26262 ASIL-D compliance for automotive traction inverter sensors extends qualification cycles to 24-36 months, locking working capital in pre-revenue development.
- Legacy system integration friction:Digital output transducers face adoption resistance from industrial automation customers with entrenched 4-20mA analog infrastructure and control system retrofit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Current Transducer Market |
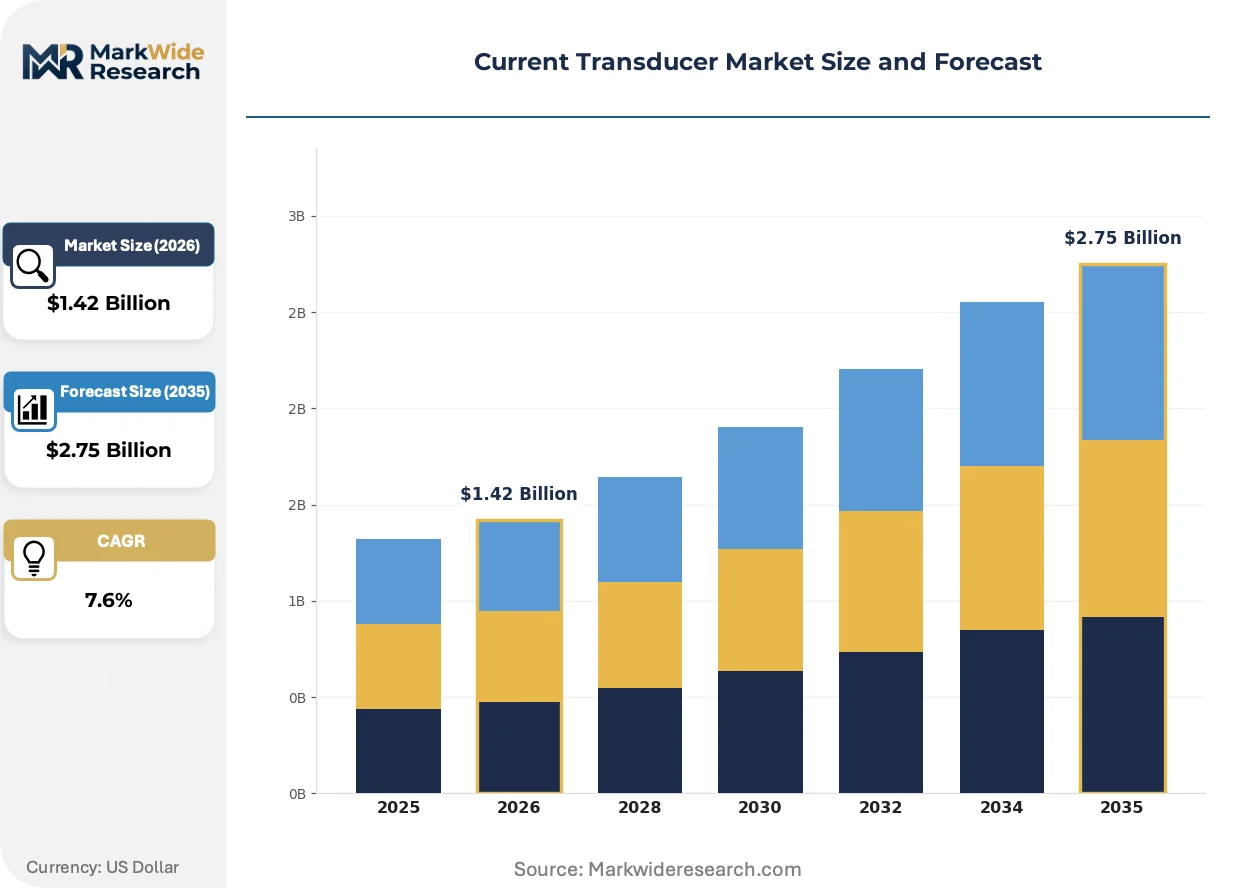
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hall Effect, Transformer-Based, Shunt Resistor, Rogowski Coil Application: Industrial Automation, Electric Vehicles, Power Generation, Renewable Energy Systems End User: Manufacturing, Utilities, Automotive, Telecommunications Technology: Analog, Digital, Wireless, Smart Sensors |
| Companies Covered | Honeywell, NK Technologies, LEM, Phoenix Contact, CR Magnetics, ABB, Texas Instruments, Veris Industries, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Current Transducer Market Strategic Shifts & Innovations
Current transducer technology is bifurcating between ultra-precision magnetic sensing for safety-critical applications and cost-optimized solid-state integration for volume automotive electronics.
Integrated shunt-and-isolation amplifier modules are absorbing the sub-100A measurement range in battery management systems and auxiliary power converters. Tier 1 automotive electronics suppliers are qualifying these semiconductor-packaged solutions for 800V architectures. This integration is absorbing the traditional discrete transducer market in low-current, cost-sensitive nodes.
Europe's F-Gas Regulation and accompanying REACH restrictions on fluorinated greenhouse gases are pressuring manufacturers to eliminate SF6 insulation in high-voltage instrument transformers. Industrial sensor vendors are accelerating dry-type and vacuum-insulated designs for 145kV+ substation applications. German TSOs and French distribution operators are piloting these alternatives under national grid decarbonization roadmaps.
Buyers in data center power distribution are unbundling hardware procurement from calibration and lifecycle service contracts. Colocation operators in Northern Virginia and Frankfurt are contracting directly with third-party metrology firms for annual accuracy verification, bypassing traditional OEM service channels. This disintermediation is compressing aftermarket revenue for established transducer manufacturers.
Current Transducer Market Segmentation
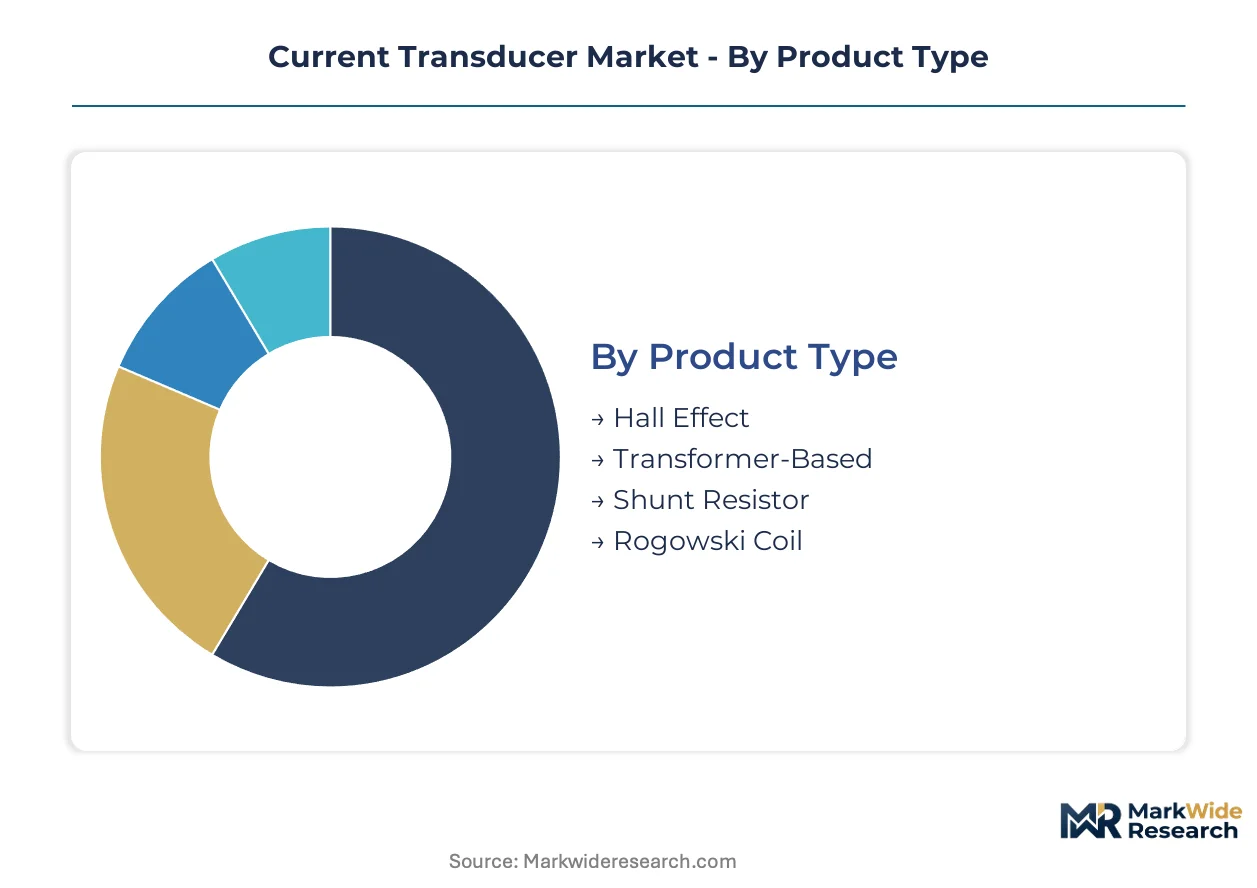
Current transducer procurement decisions hinge on balancing accuracy requirements against total cost of ownership across divergent upgrade cycles. Industrial customers face 15-20 year asset replacement timelines, while automotive programs refresh sensor specifications every 3-4 years with each EV platform generation.
Product Type:
Upgrade cycles vary sharply by magnetic content and semiconductor integration levels, with solid-state designs enabling faster refresh rates than core-dependent architectures.
- Hall Effect:Non-contact magnetic sensing using semiconductor Hall elements delivers galvanic isolation and wide dynamic range. Traction inverter demand in China's NEV production lines pulls high volumes of closed-loop and open-loop variants.
- Transformer-Based:Iron-core instrument transformers maintain dominance in utility revenue metering where IEC 61869-2 accuracy classes mandate stable, drift-free performance over decades. European grid operators specify these for 0.2S-grade substation installations.
- Shunt Resistor:Manganese-copper alloy elements with integrated isolation amplifiers are displacing magnetic solutions in automotive BMS cost optimization.
- Rogowski Coil:Air-core flexible windings enable retrofit current measurement without primary conductor interruption, finding niche adoption in switchgear modernization.
Volume placements concentrate in Hall Effect; the faster expansion belongs to Shunt Resistor.
Application:
Cost tier stratification separates premium safety-critical sensing from commodity monitoring, with certification requirements driving tier assignment.
- Industrial Automation:Motor drive and servo systems demand 0.5% accuracy with 100kHz bandwidth for closed-loop torque control. Siemens and ABB integrated drive architectures in Germany specify transducer modules with embedded temperature compensation.
- Electric Vehicles:Traction inverters, onboard chargers, and DC-DC converters require ASIL-D functional safety and 800V isolation. China's MIIT certification protocols enforce domestic testing for NEV program eligibility.
- Power Generation:Gas turbine and steam plant instrumentation favors transformer-based designs for generator monitoring.
- Renewable Energy Systems:Solar inverters and wind turbine converters need wide operating temperature ranges.
Revenue concentrates in Industrial Automation; steepest expansion trajectory sits with Electric Vehicles.
End User:
Customer type determines procurement modality, with utilities favoring lifecycle service contracts against automotive spot purchasing.
- Manufacturing:Discrete and process automation lines in automotive parts production and semiconductor fabrication deploy Hall-effect transducers for VFD current feedback. German machine builders specify LEM components for predictive maintenance integration.
- Utilities:Transmission and distribution operators in China State Grid retrofit programs drive optical and digital instrument transformer demand. Revenue-grade metering mandates 0.2S accuracy with 20-year calibration stability.
- Automotive:Tier 1 electronics suppliers qualify transducers against AEC-Q100 and ISO 26262.
- Telecommunications:Data center power distribution units specify compact Hall sensors for busbar monitoring.
Procurement volume centers on Manufacturing; share gains flow fastest to Utilities.
Technology:
Signal processing architecture determines margin structure, with analog legacy systems yielding to digital and connected variants.
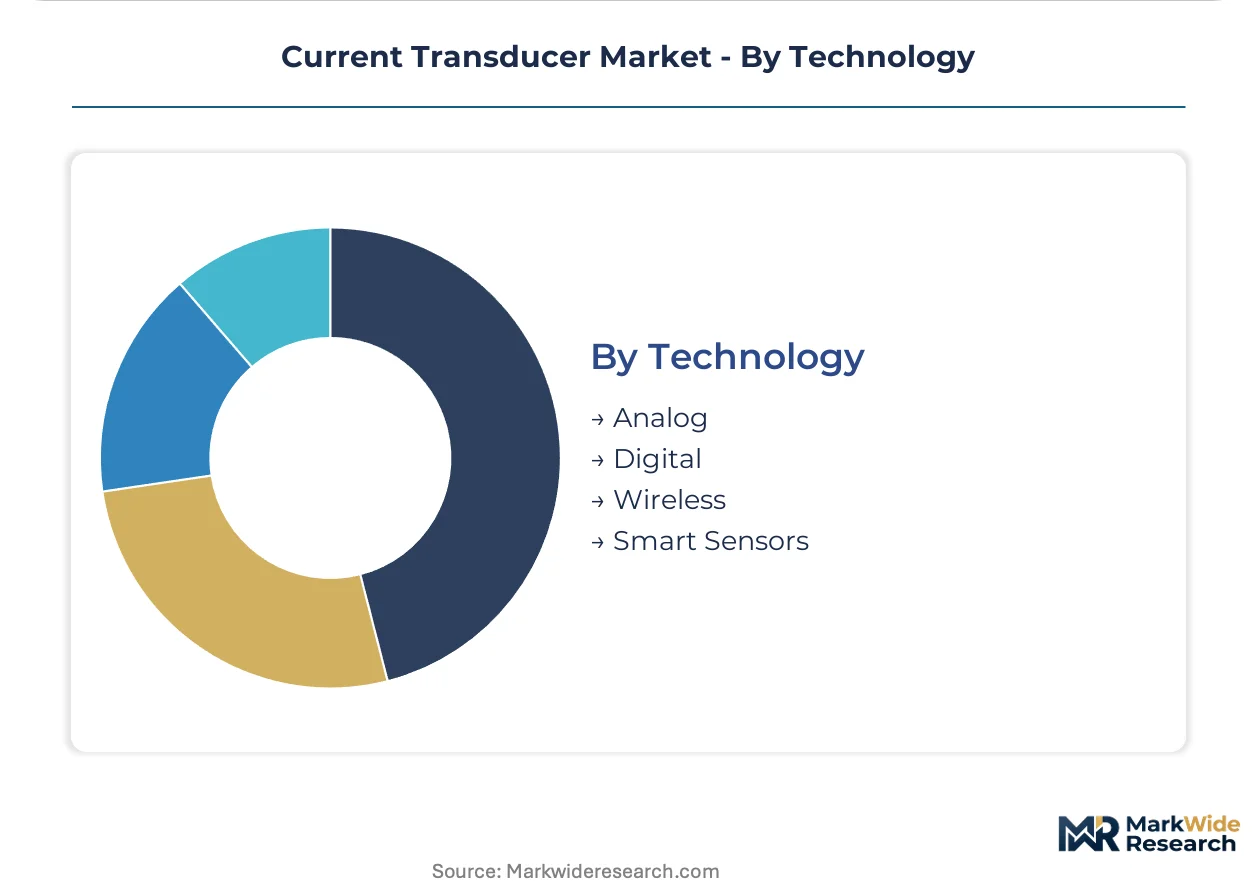
- Analog:4-20mA and voltage output transducers dominate installed base in process industries with entrenched DCS infrastructure. Migration resistance stems from control system retrofit costs and technician retraining requirements.
- Digital:Modbus, CAN, and SPI output formats enable direct microcontroller integration. Texas Instruments and STMicroelectronics supply integrated signal-conditioning ASICs that absorb discrete transducer functions.
- Wireless:Energy-harvesting RF transducers eliminate cabling in rotating machinery and remote substations.
- Smart Sensors:Edge-processing capabilities enable local fault detection and predictive algorithms.
Installed base concentrates in Analog; adoption velocity peaks with Digital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of Hall-effect and shunt-based transducers, yet Germany and the United States absorb premium precision-magnetic-sensor volumes for industrial automation and EV traction systems. Consumption clusters concentrate where grid modernization programs and automotive electrification mandates intersect.
China
Domestic EV production lines at BYD and CATL consume high volumes of closed-loop Hall-effect transducers for traction inverters. MIIT directives on new-energy vehicle components enforce GB standards testing protocols that favor local suppliers. Shenzhen and Shanghai host concentrated transducer manufacturing corridors serving both automotive and State Grid substation retrofit programs.
Germany
Siemens and ABB integrated drive architectures specify precision transducer modules with embedded temperature compensation for motor control systems. CE-marking frameworks and IEC 61869 metering standards shape product design cycles for industrial customers. Bavaria's automation corridor around Munich anchors European demand for 0.5% accuracy-class sensors in discrete manufacturing lines.
United States
NHTSA functional-safety mandates and FCC electromagnetic-compatibility rules dictate sensor certification for automotive and telecommunications equipment. Data center operators in Northern Virginia specify compact Hall sensors for busbar monitoring in hyperscale facilities. Texas Instruments extends semiconductor-level signal-conditioning integration into module-level designs from its Dallas R&D base.
Japan
Fluxgate and precision magnetic sensor design expertise concentrates among specialists in Nagoya and Tokyo metropolitan manufacturing zones. METI industrial efficiency programs incentivize predictive maintenance integration in automotive parts production. Toyota and Honda EV platforms pull high-bandwidth current sensing for 800V traction inverter architectures.
India
Production-linked incentives for domestic solar inverter and EV component manufacturing attract transducer localization investments from multinational suppliers. CEA grid standards and state-level renewable purchase obligations drive instrument transformer demand in Gujarat and Karnataka solar parks. Tamil Nadu automotive clusters qualify sensors for two-wheeler and passenger EV export programs.
Current Transducer Market Key Industry Players
Top-tier vendors anchor precision-magnetic-sensor supply chains, while mid-tier specialists compete on cost-optimized solid-state integration. The vendor base stratifies between Geneva-based fluxgate innovators, German industrial automation integrators, and semiconductor firms absorbing discrete functions into ASICs. Two strategic archetypes dominate: magnetic-core specialists defending high-accuracy niches, and silicon-integrated players capturing volume automotive electronics. Competitive moves concentrate on strategic partnerships for 800V EV platform qualification and geographic expansion through India PLI scheme localization.
Within the precision-magnetic tier, LEM and Siemens exemplify divergent integration strategies. LEM occupies a position as the archetypal standalone sensor specialist, while Siemens anchors demand through captive consumption in integrated drive systems. Texas Instruments represents semiconductor-led displacement, absorbing transducer functions into signal-conditioning chips. These three illustrate the market's structural tension between discrete magnetic expertise and silicon integration.
| Leading Market Players |
|---|
| Honeywell |
| NK Technologies |
| LEM |
| Phoenix Contact |
| CR Magnetics |
| ABB |
| Texas Instruments |
| Veris Industries |
| Siemens |
| Others |
Cost & Logistics Intelligence
ASIL-D certification tiering bifurcates pricing power between precision-magnetic specialists and commodity shunt integrators, concentrating margin retention in Geneva and Munich while cost-down pressure migrates assembly to Shenzhen and Chennai. This tier divergence manifests in supply chain configurations where rare-earth magnet procurement anchors premium Hall-effect production in Central Europe, and semiconductor-packaged isolation amplifiers enable volume scaling through East Asian foundry partnerships.
Pricing Analysis
Margin tightening in automotive battery management systems traces to shunt resistor displacement of magnetic-core transducers by integrated semiconductor modules. Three-tier pricing structure across ASIL-D certified, industrial-grade, and economy shunt variants reflects functional safety investment and volume scale differentiation. Cost-down pressure on Hall-effect suppliers accelerates because BYD and CATL negotiate direct sourcing contracts with Shenzhen manufacturers. Tier 1 automotive electronics buyers exhibit highest price sensitivity, while German industrial automation customers absorb premium pricing for embedded temperature compensation.
Supply Chain Analysis
Rare-earth magnet supply rests on Chinese neodymium and dysprosium processing facilities, with secondary concentration in Japanese sintering operations for high-coercivity alloys. Manganese-copper shunt elements draw from German precision resistor manufacturers and Taiwanese semiconductor foundries packaging isolation amplifiers. Single-source vulnerability concentrates in Hall-effect ASIC fabrication, where TSMC and GlobalFoundries capacity allocation determines transducer module availability. Distribution runs through Tier 1 automotive electronics suppliers and industrial automation OEMs with captive specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state shunt integration is displacing legacy magnetic-core architectures in volume automotive applications, compressing the addressable market for discrete transducer specialists while expanding semiconductor signal-conditioning opportunities.
For Market Incumbents: Anticipate shunt-based substitution in sub-100A measurement nodes by accelerating fluxgate R&D for 800V traction inverter safety-critical applications. Defend magnetic-sensor margin pools through IEC 61869-2 certification depth in European utility metering. Prioritize backward integration into rare-earth magnet recycling to buffer neodymium price volatility exposure. For New Entrants and Emerging Players: Energy-harvesting wireless transducer architectures offer white-space entry into predictive maintenance applications for rotating machinery and remote substations. India's PLI scheme for solar inverter manufacturing presents the most penetrable geography for localization partnerships with Gujarat and Karnataka renewable energy developers. Lead with cloud-based calibration subscription models to bypass entrenched analog infrastructure resistance. For Investors and Strategic Acquirers: Exit pathways concentrate in semiconductor firms acquiring magnetic-sensor IP for integrated power-module designs, and industrial automation platforms consolidating calibration service capabilities. Long-term viability favors precision-magnetic specialists with captive ASIL-D certification expertise over commodity shunt assemblers. Watch silicon-carbide power electronics adoption rates as inflection indicator for bandwidth demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Qualifies sensors for Toyota and Honda 800V traction inverter programs under METI efficiency mandates. |
| Rare-Earth Magnet Recycling Partnership | Secures neodymium supply chain resilience against MIIT export restriction exposure. |
| Cloud Calibration Platform Launch | Generates recurring revenue from Northern Virginia data center operators bypassing OEM service channels. |
| India PLI Localization | Positions manufacturing for Tamil Nadu two-wheeler and passenger EV export qualification. |
| Fluxgate R&D Expansion | Defends precision-magnetic positioning against Texas Instruments semiconductor integration. |
Research Approach
Multi-period observation of IEC 61869 accuracy class adoption, MIIT NEV certification timelines, and silicon-carbide inverter deployment rates anchored the trend analysis, supplemented by interviews with Tier 1 automotive electronics procurement directors, German industrial automation R&D heads, China State Grid substation engineering managers, and precision magnetic sensor design specialists. Secondary validation drew from SEC semiconductor firm filings, CEA grid standards documentation, EIA power electronics trade data, and IEC technical committee publications. Bottom-up transducer shipment modeling triangulated against top-down EV platform sensor content estimates.
Segment-weighting across product type, application, end user, and technology dimensions structured the analytical framework, with propulsion architecture and functional safety tier as automotive-specific modeling layers. CAGRs derived from shipment-volume trajectories adjusted for content-per-vehicle evolution and grid modernization program spend profiles. Forecast inputs incorporated silicon-carbide switching frequency requirements and rare-earth magnet price elasticity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT domestic content enforcement escalation and neodymium supply disruption scenarios. Forecasts reflect documented assumptions on EV platform refresh cycles and IEC standard adoption timelines. A small set of triggers—silicon-carbide inverter penetration rates, India PLI scheme expansion, and REACH F-Gas regulatory acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Taiwan Sensors Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
APAC Pressure Sensors Market