
 Uncooled Infrared Camera Market | 2026-2036
Uncooled Infrared Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Uncooled Infrared Camera Market Insights
Sensor miniaturization is fragmenting the traditional uncooled infrared supply chain into specialized component layers. Teledyne FLIR leverages its vertically integrated foundry capacity to control detector yield and thermal core quality. Leonardo DRS anchors North American defense procurement through long-term thermal sight contracts. Thales Group competes across European security and aerospace channels with dual-use certified platforms.
An uncooled infrared camera detects thermal radiation without cryogenic cooling, typically employing vanadium oxide or amorphous silicon microbolometers with pixel pitches below 17 micrometers for uncooled operation near room temperature. These devices convert infrared energy into electrical signals for non-contact temperature measurement, night vision, and thermal mapping in industrial and tactical environments. Thermal imager products dominate commercial volume due to their versatility across predictive maintenance and building inspection workflows, while handheld camera formats capture the fastest expansion in field service and first responder segments. Microbolometer technology leads manufacturing scale, though focal plane array architectures sustain premium positioning in defense and perimeter security applications where resolution thresholds determine contract awards.
FDA regulates thermal camera claims for medical screening applications, constraining how manufacturers position fever-detection systems in healthcare-adjacent channels. CE marking under the EU MDR and RoHS directives shapes product access across European industrial and security markets by mandating material disclosure and electromagnetic compatibility validation. FCC certification governs radio-enabled thermal devices in the United States, adding compliance cost for wireless streaming models. Stakeholders must monitor how export control revisions affecting focal plane array specifications reshape cross-border supply strategies and partner qualification timelines.
Market Dynamics
Sensor miniaturization below 12-micron pixel pitch is compressing thermal core footprints and fragmenting the traditional vertically integrated supply chain into specialized component layers, forcing manufacturers to secure captive foundry capacity or risk yield volatility.
Growth Catalysts
- Automotive ADAS integration:Nighttime pedestrian detection mandates in Germany and France are embedding vanadium oxide microbolometers into forward-looking infrared systems for premium vehicle platforms.
- Smart city infrastructure procurement:Chinese municipal governments are deploying thermal surveillance networks for perimeter security and traffic monitoring in Wuhan and Shenzhen urban clusters.
- EU AI Act compliance:Machine vision components now require validated performance protocols for European security and industrial automation deployments, creating certified product demand.
Market Restraints
- Foundry concentration risk:Microbolometer wafer production concentrates among three specialized MEMS facilities, creating single-source vulnerability for thermal core supply.
- Amorphous silicon yield limitations:Material uniformity defects at sub-17-micron pitches constrain resolution scaling for cost-sensitive commercial segments.
- Export control friction:US Commerce Department focal plane array licensing delays extend qualification timelines for cross-border defense and security contracts.
Strategic Opportunities
- India industrial automation:BIS certification pathways for non-contact temperature measurement devices are opening factory predictive maintenance channels previously dominated by contact sensors.
- Drone-mounted thermal payload expansion:FAA Part 107 waiver expansion for beyond-visual-line-of-sight operations is creating aerial inspection demand in agriculture and utility sectors.
- Edge AI convergence:On-device neural processing integration with thermal cores is enabling real-time threat classification without cloud dependency for perimeter security.
Industry Challenges
- MEMS process engineering talent scarcity:Specialized microbolometer fabrication expertise concentrates among retiring cohorts at legacy defense contractors, constraining foundry expansion.
- Multi-certification timeline compression:Simultaneous FCC, CE marking, and FDA validation for multi-use thermal devices extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uncooled Infrared Camera Market |
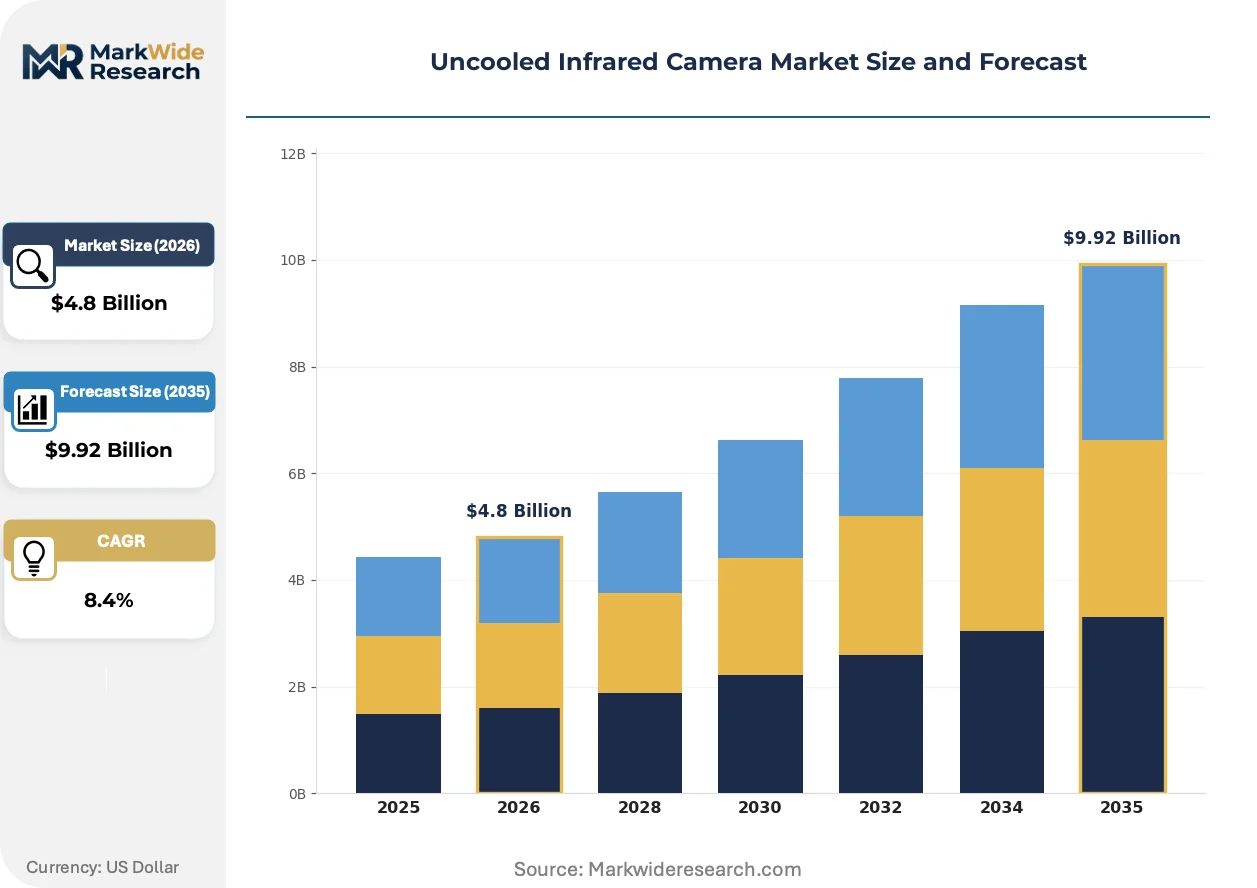
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Imager, Handheld Camera, Fixed Camera, Dual-Use Camera Technology: Microsbolometer, Focal Plane Array, Quantum Well, Thin Film End User: Defense, Security, Automotive, Industrial Application: Surveillance, Fire Detection, Night Vision, Building Inspection |
| Companies Covered | Teledyne FLIR LLC, Fluke Corporation, BAE Systems, Xenics NV, Wuhan Guide Infrared Co., Ltd., L3Harris Technologies, Inc., Leonardo DRS, Thales Group, Hikvision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uncooled Infrared Camera Market Trends and Innovations
Wafer-level packaging and silicon photonics integration are compressing thermal core form factors while elevating resolution thresholds, reshaping competitive positioning around semiconductor process sophistication rather than optical heritage.
12-micron pixel pitch vanadium oxide microbolometers are digitizing thermal imaging module footprints for smartphone and wearable integration. Consumer electronics manufacturers in South Korea and Japan are sampling these cores for night-vision accessories and fever-monitoring peripherals. The technology is digitizing the boundary between professional thermal equipment and mass-market consumer electronics, forcing traditional defense suppliers to develop stripped-down commercial variants.
The EU AI Act's risk classification framework for biometric identification systems is mandating algorithmic transparency documentation for security-grade thermal cameras deployed in European public spaces. Manufacturers must now submit conformity assessment files demonstrating false-positive rates and demographic parity metrics. French and German integrators are prioritizing suppliers with pre-validated AI models to accelerate municipal procurement cycles.
Building inspection contractors are unbundling thermal imaging from bundled facility management contracts, creating spot-procurement demand for handheld devices with cloud-reporting capabilities. This channel shift favors direct-to-contractor e-commerce platforms over traditional distribution through multiline industrial distributors. The pattern is most pronounced in Texas and Florida construction markets, where energy audit mandates are expanding residential thermal survey volumes.
Uncooled Infrared Camera Market Segmentation
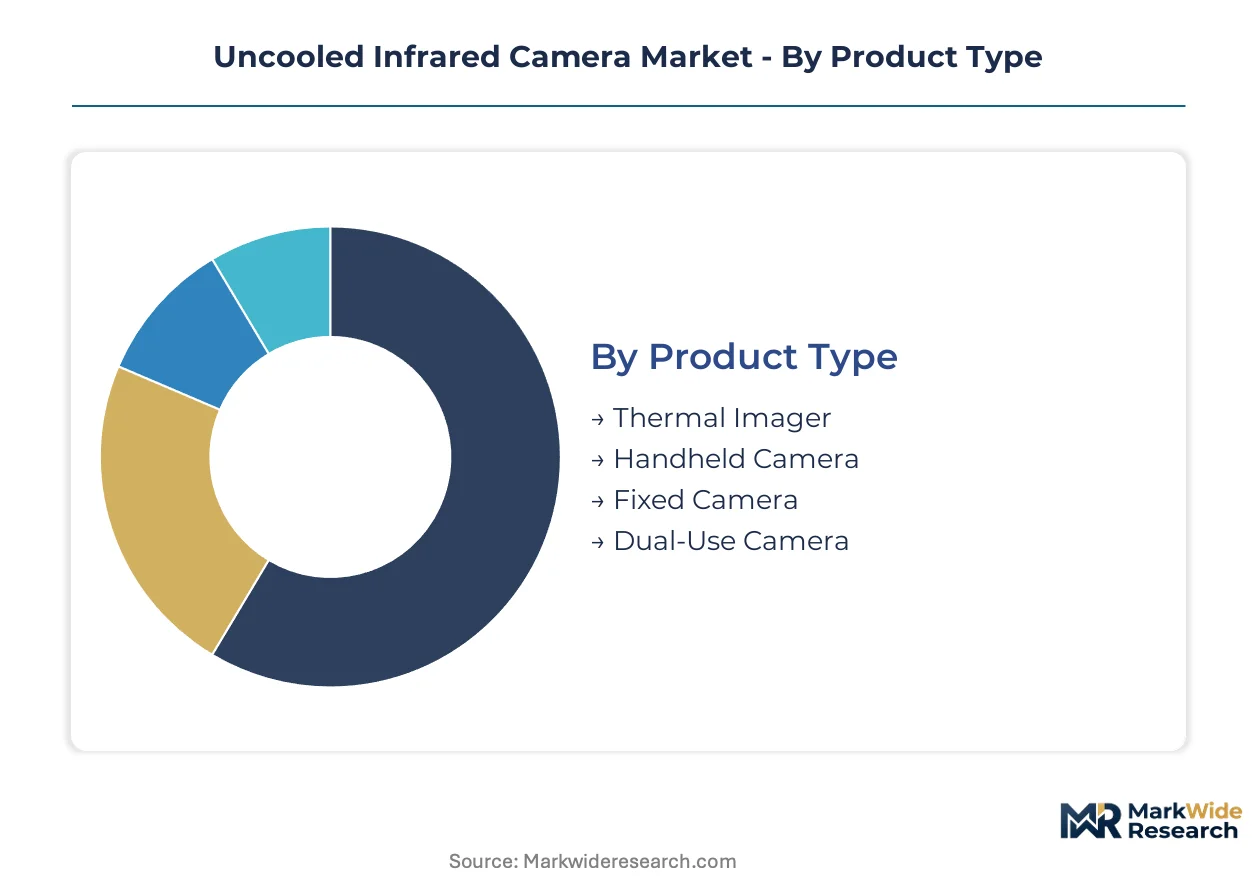
Uncooled infrared camera demand fragments across four distinct axes: product form factor, detector technology, end-user procurement authority, and use-case environment. Each dimension carries its own certification requirements, margin structure, and supply chain configuration that determine vendor positioning.
Product Type:
Cost tier determines thermal core specifications, software integration depth, and channel access across professional and consumer markets.
- Thermal Imager:Modular camera cores without integrated optics dominate commercial volume through OEM integration into predictive maintenance systems and perimeter security networks. Demand concentrates in German industrial automation channels where DIN-certified thermal monitoring is displacing contact pyrometers in steel and glass production facilities. Foundry allocation priority for vanadium oxide microbolometers flows to this segment due to multi-thousand-unit fleet deployments.
- Handheld Camera:Self-contained portable units with integrated displays and battery power capture the steepest expansion trajectory in field service and first responder procurement. Fire departments in Texas and Florida municipalities are replacing legacy models through spot-procurement on municipal e-commerce platforms rather than multiline industrial distributors.
- Fixed Camera:Permanently mounted thermal sensors with PoE connectivity and VMS integration anchor smart city perimeter security deployments in Wuhan and Shenzhen urban clusters.
- Dual-Use Camera:Platforms certified for both civil and military applications under US Commerce Department and EU dual-use regulations serve NATO border surveillance and critical infrastructure protection.
Thermal Imager commands the established base. The steepest expansion runs through Handheld Camera.
Technology:
Application environment dictates detector architecture selection based on resolution requirements, power constraints, and operating temperature range.
- Microbolometer:Vanadium oxide and amorphous silicon microbolometers operating near room temperature without cryogenic cooling enable the manufacturing scale that drives cost reduction across commercial segments. Yield limitations at sub-17-micron pitches constrain resolution scaling for cost-sensitive building inspection workflows where 640x480 resolution thresholds determine contract awards.
- Focal Plane Array:Two-dimensional detector arrays with integrated readout circuits sustain premium positioning in defense and perimeter security applications where NETD performance below 50mK justifies procurement premiums. French and German integrators prioritize FPA suppliers with pre-validated AI models to accelerate municipal procurement cycles under EU AI Act biometric identification requirements.
- Quantum Well:III-V semiconductor heterostructures deliver extended wavelength response for specialized gas detection and spectroscopic applications in petrochemical facilities.
- Thin Film:Emerging deposited thermistor materials on silicon substrates promise simplified fabrication for consumer electronics integration in South Korean and Japanese night-vision accessories.
Microbolometer anchors volume manufacturing. Focal Plane Array captures the fastest share gain in security and defense procurement.
End User:
Customer type shapes procurement protocols, certification requirements, and product lifecycle expectations across fundamentally different buying centers.
- Defense:Long-term thermal sight contracts through US Army and NATO procurement channels prioritize supply assurance and ITAR compliance over unit cost. Leonardo DRS and Teledyne FLIR anchor North American defense procurement through multi-year vehicle and soldier system programs.
- Security:Municipal and enterprise perimeter protection deployments in Chinese smart city infrastructure and European public spaces drive certified product demand under tightening algorithmic transparency mandates.
- Automotive:Tier 1 integration into forward-looking infrared systems for premium German and French vehicle platforms embeds vanadium oxide microbolometers into ADAS architectures for nighttime pedestrian detection compliance.
- Industrial:Predictive maintenance and non-contact temperature measurement in factory automation channels previously dominated by contact sensors are opening through BIS certification pathways in India.
Defense commands procurement value concentration. Industrial end-use is climbing the fastest as factory automation replaces legacy sensing modalities.
Application:
Volume concentration varies by deployment environment, with outdoor and indoor use cases demanding different environmental sealing, thermal drift compensation, and analytics integration.
- Surveillance:Continuous perimeter monitoring applications in critical infrastructure and urban security networks integrate edge AI for real-time threat classification without cloud dependency. EU AI Act compliance documentation for biometric identification systems is mandating false-positive rate validation for European public space deployments.
- Fire Detection:Early warning systems for forest, industrial, and building fire detection leverage thermal contrast algorithms to identify ignition sources before visible flame emergence. California utility wildfire prevention mandates and Australian bushfire management programs are expanding aerial and fixed-mount procurement.
- Night Vision:Driver assistance and tactical mobility applications require thermal cores with rapid startup and minimal power draw for battery-constrained platforms.
- Building Inspection:Energy audit and moisture detection workflows are unbundling from bundled facility management contracts into spot-procurement for handheld devices with cloud-reporting capabilities in Texas and Florida construction markets.
Surveillance holds the installed base. Building Inspection is expanding most quickly through channel shift toward direct contractor procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and municipal security integrators concentrate demand across distinct national regulatory environments, with each geography enforcing specific certification protocols that reshape vendor qualification timelines.
United States
FAA Part 107 waiver expansion for beyond-visual-line-of-sight drone operations is accelerating aerial thermal inspection demand in agriculture and utility sectors. FCC certification governs radio-enabled thermal devices, adding compliance cost layers for wireless streaming models. California utility wildfire prevention mandates and Texas municipal fire department procurement are expanding fixed-mount and handheld volumes through spot-procurement platforms.
China
Wuhan Guide Infrared and domestic security integrators are driving volume procurement for smart city infrastructure in Wuhan and Shenzhen urban clusters. GB standards and MIIT regulations shape product access for machine vision components deployed in public surveillance networks. The Yangtze River Delta manufacturing base is concentrating microbolometer assembly capacity for export-oriented thermal core production.
Germany
Nighttime pedestrian detection mandates are embedding vanadium oxide microbolometers into forward-looking infrared systems for premium vehicle platforms. KBA type-approval requirements and EU AI Act biometric identification protocols are tightening performance validation for ADAS-integrated thermal imagers. Bavaria-based automotive Tier 1 suppliers are qualifying dual-source thermal core supply to meet platform integration timelines.
France
ANSM and CNIL oversight of biometric identification systems is mandating algorithmic transparency documentation for security-grade thermal cameras in public spaces. EU AI Act conformity assessment files demonstrating false-positive rates are accelerating municipal procurement cycles. Paris and Lyon urban security networks are prioritizing suppliers with pre-validated AI models for perimeter surveillance integration.
India
BIS certification pathways for non-contact temperature measurement devices are opening factory predictive maintenance channels previously dominated by contact sensors. CEA electrical safety standards and DGFT import regulations are reshaping component sourcing strategies for domestic thermal camera assembly. Maharashtra and Gujarat industrial corridors are deploying thermal monitoring systems for steel and glass production facilities under DIN-certified specifications.
Uncooled Infrared Camera Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. Defense contractors anchor long-term supply assurance contracts through ITAR-compliant production lines, while commercial specialists capture spot-procurement demand through direct e-commerce platforms. Three archetypes dominate: vertically integrated semiconductor foundries, modular thermal core OEMs, and dual-use certified platform integrators. Competitive intensity concentrates on foundry capacity reservation and multi-certification timeline compression.
Within the defense-contractor archetype, Teledyne FLIR LLC and Leonardo DRS exemplify North American supply assurance positioning through captive detector production. Wuhan Guide Infrared Co., Ltd. occupies a scale-driven role in Chinese municipal procurement channels. Among diversified technology conglomerates, Thales Group and BAE Systems represent dual-use certification capabilities spanning European security and aerospace deployments. L3Harris Technologies, Inc. sits within the mission-systems integrator tier, while Fluke Corporation and Xenics NV exemplify commercial-specialist positioning in industrial predictive maintenance and machine vision segments respectively. Hikvision represents the surveillance-technology convergence archetype in smart city infrastructure bidding.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| Fluke Corporation |
| BAE Systems |
| Xenics NV |
| Wuhan Guide Infrared Co., Ltd. |
| L3Harris Technologies, Inc. |
| Leonardo DRS |
| Thales Group |
| Hikvision |
| Others |
Pricing and Supply Chain Analysis
Single-source microbolometer wafer dependency determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of thermal core assembly. Foundry allocation priority flows to defense contractors with long-term offtake agreements, while commercial buyers face spot-market volatility in vanadium oxide detector supply.
Pricing Analysis
Cost-plus contracts with vanadium oxide wafer price indexation anchor defense procurement, insulating prime contractors from spot volatility while exposing commercial OEMs to material pass-through. Price differentiation rests on ITAR certification tier and thermal core resolution grade, with NETD performance below 50mK commanding substantial premiums. Cost compression in the handheld commercial segment is intensifying because amorphous silicon yield limitations at sub-17-micron pitches constrain supply elasticity. Municipal fire departments in Texas and Florida exhibit the highest price sensitivity, while NATO thermal sight programs demonstrate minimal elasticity due to supply assurance mandates.
Supply Chain Analysis
US Commerce Department focal plane array licensing controls restrict cross-border flows of thermal detector technology, fragmenting procurement channels between ITAR-compliant and commercial-grade supply chains. Manufacturing gravity centers on China, the United States, and France, with Wuhan Guide Infrared dominating municipal security procurement and Teledyne FLIR anchoring North American defense supply. Raw material dependencies include vanadium oxide sputtering targets, amorphous silicon deposition gases, and ceramic vacuum package substrates. Single-source vulnerability concentrates in specialized MEMS foundries with microbolometer process expertise. Distribution runs through direct e-commerce platforms for handheld commercial devices and multiyear prime contracts for integrated thermal sight systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-cost Chinese thermal cores threaten to commoditize the commercial mid-tier, forcing incumbents to defend through certification moats and captive foundry capacity rather than price competition alone.
For Market Incumbents: Insulate defense-grade margins by securing captive vanadium oxide foundry allocation through multi-year thermal sight contracts with the US Army and NATO procurement channels. Deepen backward integration into wafer-level packaging to compress form factors for automotive ADAS integration and outpace emerging Chinese competitors on resolution-per-unit-cost metrics. For New Entrants and Emerging Players: Mid-market industrial automation in India represents the most penetrable entry point, where BIS certification pathways for non-contact temperature measurement devices are displacing legacy contact sensors in Maharashtra and Gujarat steel production corridors. Drone-mounted thermal payloads for FAA Part 107 waiver expansion in US agriculture and utility sectors offer a second white-space target with lower certification barriers than defense or automotive channels. A direct-to-contractor e-commerce go-to-market angle bypasses entrenched multiline industrial distributor relationships. For Investors and Strategic Acquirers: EU AI Act biometric identification compliance deadlines reshape the acquisition landscape, elevating targets with pre-validated algorithmic transparency documentation above pure hardware plays. Long-term viability in this market hinges on semiconductor process sophistication rather than optical heritage, favoring foundry-capable assets over assembly-only operations. The signal to watch is foundry expansion announcements by legacy defense contractors, which would indicate capacity relief and compress valuation multiples for capacity-constrained mid-tier players.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Captive vanadium oxide wafer supply secures thermal core allocation for multi-thousand-unit fleet deployments. |
| EU AI Act Pre-Validation | Algorithmic transparency documentation accelerates municipal procurement cycles in French and German security networks. |
| Wafer-Level Packaging Investment | Silicon photonics integration compresses thermal core footprints for smartphone and wearable accessory integration. |
| Dual-Use Certification Expansion | US Commerce Department and EU dual-use compliance opens NATO border surveillance and critical infrastructure channels. |
| Edge AI Core Integration | On-device neural processing enables real-time threat classification without cloud dependency for perimeter security. |
Research Methodology
Desk research of customs/trade data, SEC 10-K filings, and EU procurement databases preceded structured interviews with thermal core engineering directors, automotive Tier 1 procurement leads, municipal security integrators, and MEMS foundry operations managers. Secondary validation drew from FAA waiver databases, BIS certification registries, and defense contract award announcements. Bottom-up thermal core unit shipment estimates triangulated against top-down end-use market sizing across the projection horizon.
Assumptions held fixed include current export control licensing timelines, vanadium oxide wafer yield curves, and EU AI Act implementation schedules; variables tested included amorphous silicon pitch scaling rates and drone BVLOS regulatory expansion pace. The analytical framework modeled segmentation across product form factor, detector technology, end-user procurement authority, and use-case environment throughout the forecast period. CAGRs derived from regression against historical microbolometer cost curves and automotive ADAS content penetration trajectories.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or defense budget allocation priorities would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Cross-checking against IHS Markit vehicle production data and EIA utility capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Camera Lens Market
Imaging
Global Document Scanner Market
Imaging
Global Label-Free Array Systems Market
Imaging
Asia Pacific IP Camera Market
Imaging
Global Microbolometer Market
Imaging
Hyperspectral Imaging Market
Imaging
Printed Image Sensors Market
Imaging
Compact Camera Module Market
Imaging
Automotive Compact Camera Module Market
Imaging
X Ray Tubes Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Mobile Imaging Services Market
Imaging
Micro Computed Tomography Market
Imaging
Smart Camera Market
Imaging
Image Based Barcode Reader Market
Imaging
Global Automotive Imaging Market