
 Pressure Transducer Market | 2026-2036
Pressure Transducer Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Transducer Market Analysis
Multi-source procurement among Tier-1 automotive suppliers is repositioning contract structures away from sole-source agreements. Honeywell International Inc leverages its aerospace certification depth to sustain premium positioning in flight-qualified pressure sensing. Emerson Electric Co. anchors its industrial automation portfolio with field-proven transmitters for process industries. Sensata Technologies Holdings PLC specializes in MEMS-based automotive pressure modules that dominate underhood applications.
A pressure transducer converts fluid or gas pressure into an electrical signal, typically outputting 4-20 mA or 0-10 V with accuracy classes spanning 0.1% to 0.5% full scale, serving process monitoring and safety interlock systems across hazardous environments. Piezoresistive technology leads unit shipments due to silicon micromachining cost curves, while optical pressure sensing captures margin pools in high-temperature aerospace and downhole oil & gas applications where electromagnetic immunity proves critical. Digital transducers are displacing analog variants in smart factory architectures where IO-Link and Ethernet-APL protocols enable edge diagnostics.
EPA mandates under the Clean Air Act and OSHA process safety management rules shape North American product certification requirements, while REACH and the EU Machinery Directive enforce material disclosure and functional safety standards for European market access. China's GB standards and NMPA medical device regulations create parallel compliance pathways for suppliers serving domestic hospital equipment and industrial instrumentation sectors. Stakeholders must monitor evolving functional safety integrity levels and cybersecurity annexes to IEC 61508 as these become purchase prerequisites rather than optional differentiators.
Market Dynamics
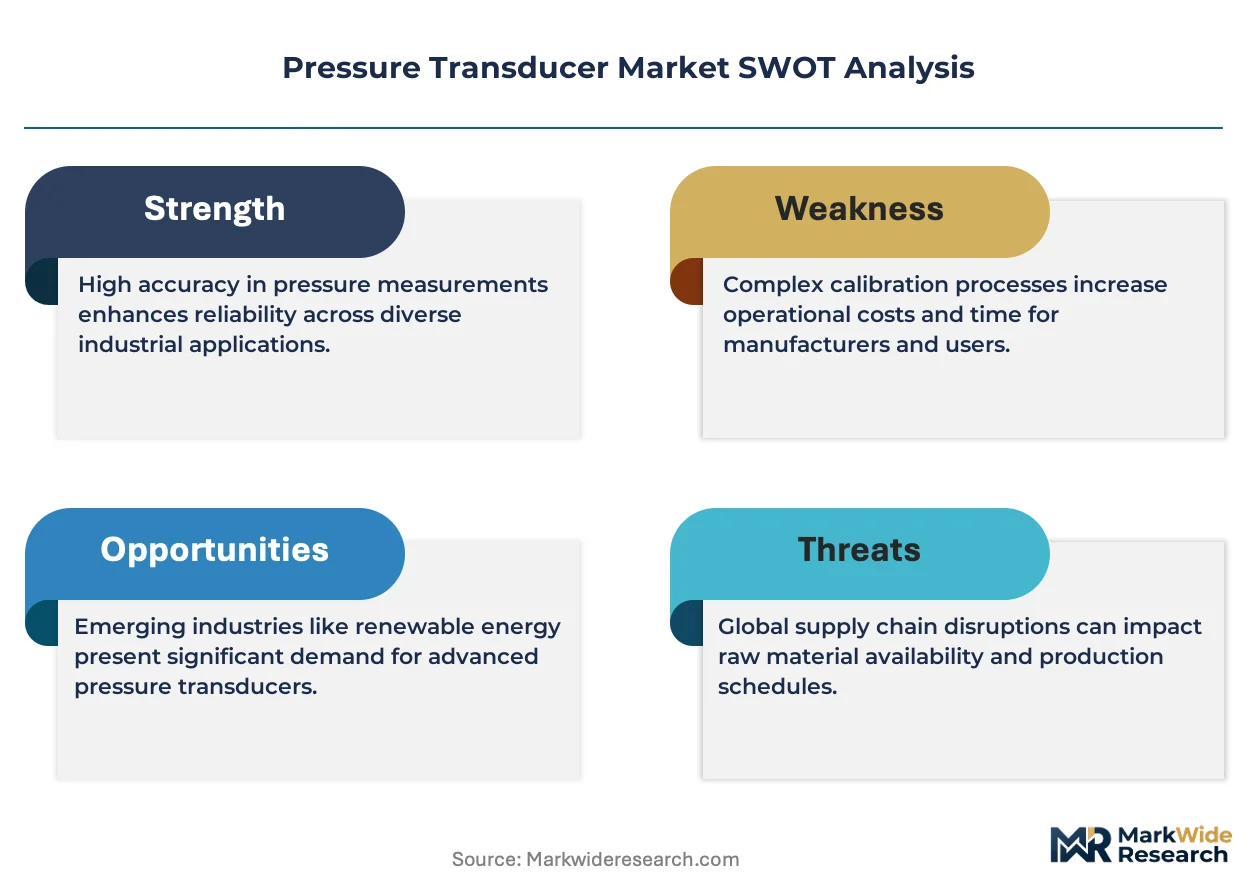
Industrial automation buyers are consolidating sensor procurement around predictive maintenance platforms, forcing suppliers to bundle edge diagnostics and IO-Link connectivity as standard rather than premium features. This shift compresses margins on analog-only transducers while rewarding vendors with embedded software capabilities.
Growth Catalysts
- EPA emissions monitoring mandates:Continuous emission monitoring systems in US power generation and petrochemical facilities require SIL-rated pressure instrumentation with 0.1% accuracy classes, mandating replacement cycles.
- MEMS silicon micromachining:Wafer-scale fabrication of piezoresistive sensing elements reduces unit costs for automotive underhood modules, enabling volume deployment across engine management and brake systems.
- Germany's automotive sensor cluster:Tier-1 suppliers around Stuttgart and Munich are localizing pressure transducer sourcing for electric vehicle thermal management and battery pack safety systems.
Market Restraints
- Optical sensing component costs:Sapphire diaphragms and fiber-optic interrogators for high-temperature aerospace applications carry 8-12x cost premiums versus piezoresistive alternatives, limiting addressable market expansion.
- Rare earth magnet supply concentration:Neodymium and dysprosium dependencies for certain transducer actuator assemblies concentrate in Chinese processing facilities, creating input volatility.
- REACH substance restriction timelines:ECHA candidate list expansions for SVHCs in sensor housings and potting compounds force reformulation cycles that extend new product qualification by 14-18 months.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives for ventilators and dialysis equipment create localized demand for disposable pressure sensors with NMPA-equivalent certification pathways.
- Ethernet-APL protocol adoption:Two-wire intrinsically safe networking in process industries enables single-cable power and data architectures, opening retrofit opportunities in legacy 4-20 mA installations.
- Hydrogen economy infrastructure:700 bar fueling station dispensers and electrolyzer balance-of-plant require specialized high-pressure transducers with hydrogen embrittlement-resistant metallurgy.
Industry Challenges
- IEC 61508 functional safety certification backlog:Third-party assessor capacity constraints extend SIL verification timelines to 22-28 months for new transmitter designs, delaying revenue recognition.
- Cybersecurity annex implementation:IEC 62443-4-2 secure development lifecycle requirements demand firmware architecture redesigns that strain embedded engineering talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Transducer Market |
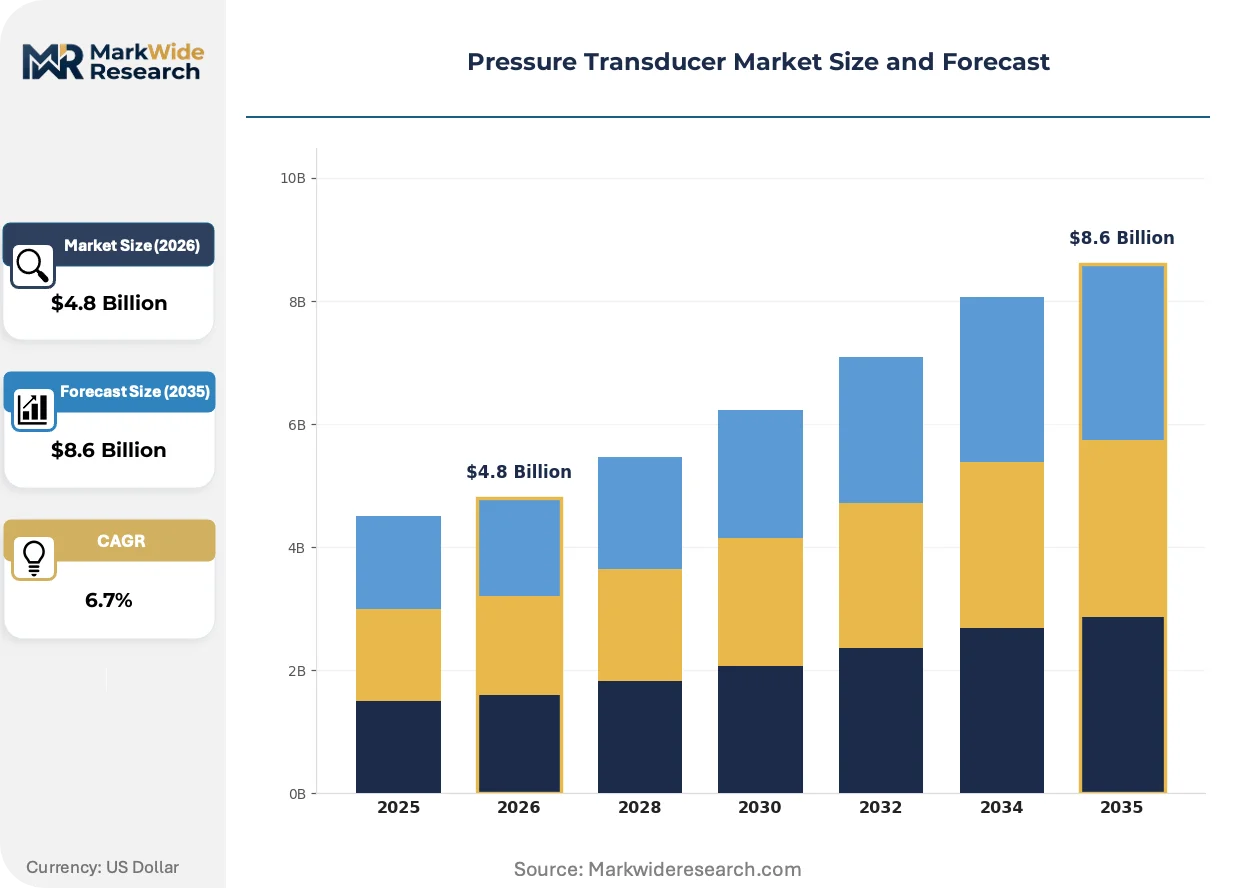
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
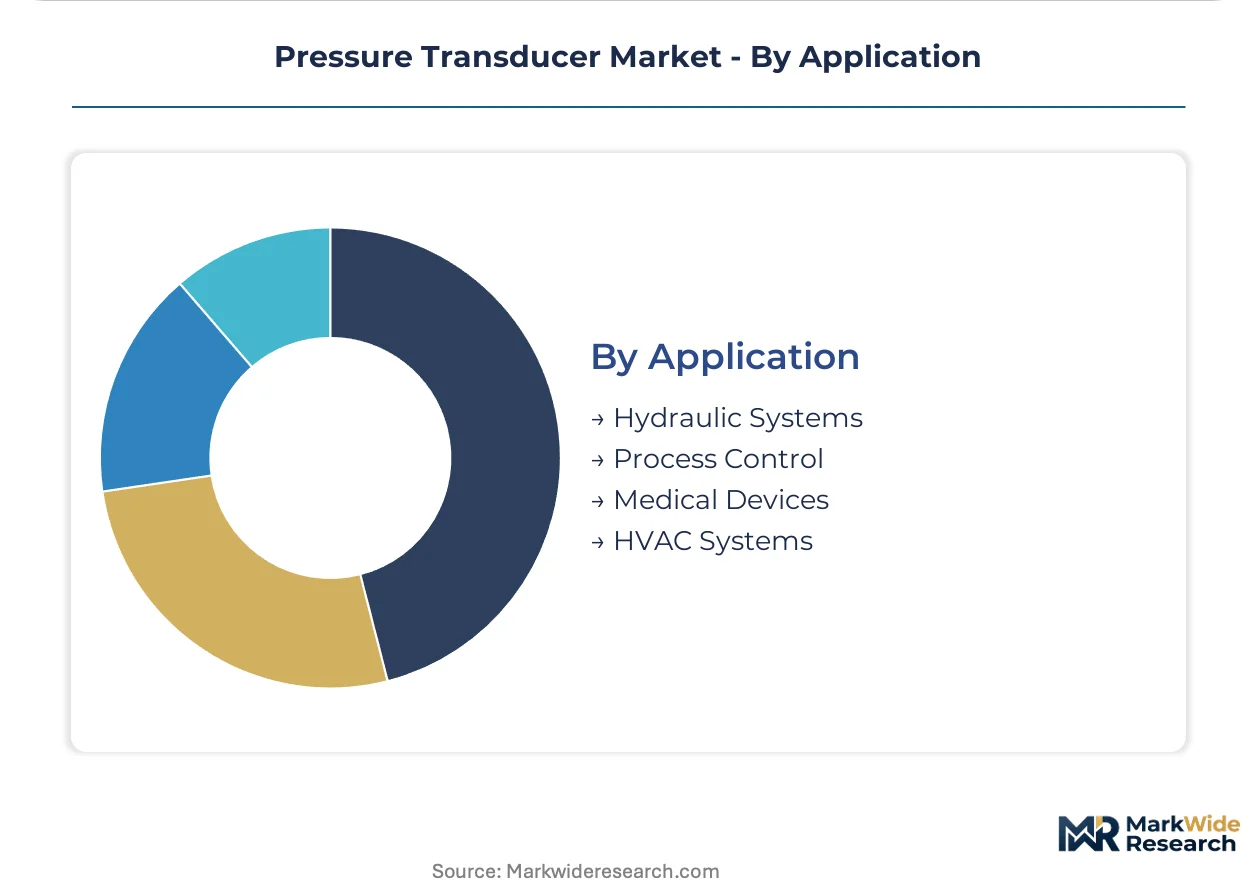
| Segmentation | Product Type: Analog Transducers, Digital Transducers, Membrane Pressure Sensors, Semiconductor Pressure Sensors Technology: Piezoresistive, Capacitive, Optical, Strain Gauge End User: Aerospace, Automotive, Industrial Automation, Oil & Gas Application: Hydraulic Systems, Process Control, Medical Devices, HVAC Systems |
| Companies Covered | Honeywell International Inc, ABB Group, Emerson Electric Co., TE Connectivity, Sensata Technologies Holdings PLC, Robert Bosch GmbH, NXP Semiconductors N.V., Yokogawa Electric Corporation, Endress+Hauser AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Transducer Market Emerging Trajectories
Digital transducer architectures are displacing analog signal chains across smart factory deployments, with edge computing capabilities and predictive diagnostics becoming baseline expectations rather than differentiators.
Silicon carbide MEMS pressure sensing is integrating temperature compensation algorithms directly at the die level, eliminating external signal conditioning boards. Automotive powertrain engineers at German OEMs are specifying these devices for exhaust gas recirculation systems operating above 600°C. The technology is integrating thermal management and pressure measurement into single-package solutions that reduce wiring harness complexity.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing sensor manufacturers to eliminate PTFE-based diaphragm coatings and sealing elements from process industry transmitters. Chemical processors in the EU must now qualify alternative elastomer formulations that maintain media compatibility without restricted fluoropolymers. Downhole oil and gas applications face particular friction, as H2S-resistant coatings historically relied on fluorinated chemistries now subject to sunset dates.
Multi-year framework agreements with embedded service level commitments are displacing transactional spot purchasing for critical pressure instrumentation in US refineries. Maintenance, repair, and operations teams at Gulf Coast petrochemical complexes now prioritize total cost of ownership metrics over unit price in supplier selection. This behavioral shift concentrates volume with vendors capable of calibration logistics and spare pooling across integrated site networks.
Pressure Transducer Market Segmentation
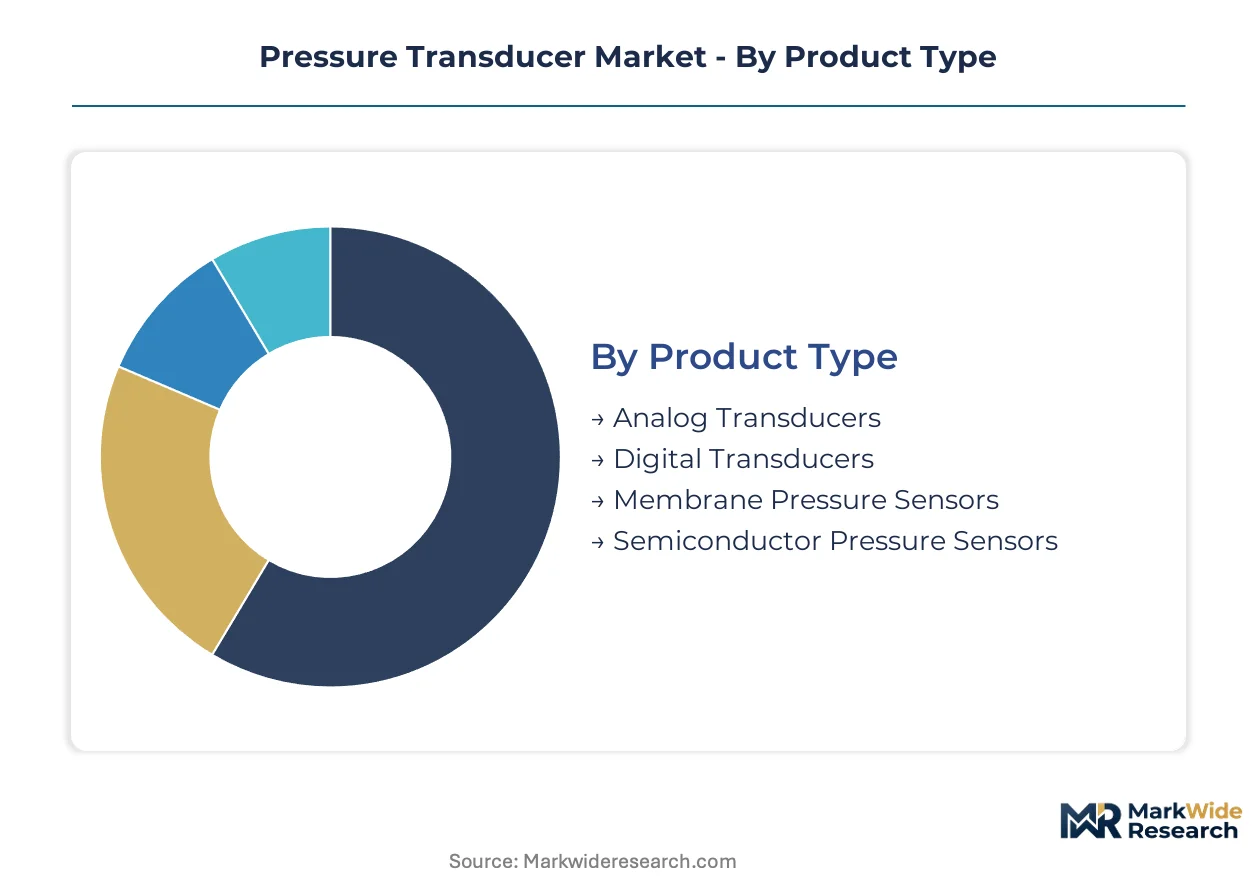
Pressure transducer procurement patterns diverge sharply across technical specifications, with certification requirements and connectivity protocols determining supplier eligibility for specific verticals. Buyers in aerospace and medical segments impose qualification timelines that exclude generalist manufacturers, while automotive volume contracts reward MEMS fabrication scale.
Product Type:
Certification burdens vary dramatically across output architectures, with flight-qualified analog designs requiring FAA airworthiness validation and digital variants demanding IEC 62443 cybersecurity annex compliance for process industry acceptance.
- Analog Transducers:These devices output continuous 4-20 mA or 0-10 V signals through conventional signal conditioning circuits. Demand concentrates in legacy US petrochemical facilities where EPA-mandated continuous emission monitoring systems require SIL-rated instrumentation with minimal firmware attack surfaces. Long replacement cycles and conservative maintenance protocols sustain this segment despite digital displacement pressures.
- Digital Transducers:Embedded microcontrollers enable IO-Link and Ethernet-APL protocol support with edge diagnostics capabilities. German automotive OEMs around Stuttgart specify these devices for electric vehicle battery pack thermal management, where real-time pressure telemetry feeds predictive maintenance algorithms. The architecture commands premium positioning but requires embedded software engineering resources many suppliers lack.
- Membrane Pressure Sensors:Thin-film strain gauge deposits on stainless steel diaphragms deliver media compatibility for aggressive process fluids.
- Semiconductor Pressure Sensors:Silicon micromachined piezoresistive elements achieve wafer-scale cost structures for high-volume automotive underhood deployment.
Leading the category by volume: Semiconductor Pressure Sensors. Growing fastest: Digital Transducers.
Technology:
Cost tiers separate these technologies by three orders of magnitude, with optical interrogation systems commanding aerospace margins and piezoresistive silicon dominating automotive unit economics.
- Piezoresistive:Silicon micromachining enables batch fabrication of sensing elements with temperature compensation at the die level. China's industrial IoT manufacturing corridors absorb massive volumes for pump monitoring and compressor protection, with GB standards compliance enabling domestic substitution of imported instrumentation. The technology captures automotive engine management and brake system applications through cost curves unmatched by alternative sensing principles.
- Optical:Fiber-optic interrogation of sapphire or silicon carbide diaphragms eliminates electromagnetic interference susceptibility in high-temperature environments. Downhole oil and gas applications above 200°C in North Dakota shale formations and Saudi Aramco conventional fields specify these devices where electronics failure rates would cripple operational economics. Component costs restrict expansion beyond safety-critical niches.
- Capacitive:Differential capacitance measurement achieves superior stability for low-pressure medical ventilation applications.
- Strain Gauge:Bonded foil and thin-film metal deposits serve heavy industrial load cell and pressure measurement requirements.
Highest margin capture: Optical. Steepest volume expansion: Piezoresistive.
End User:
Application maturity determines procurement sophistication, with aerospace buyers imposing decade-long qualification horizons and industrial automation adopters consolidating around predictive maintenance platform vendors.
- Industrial Automation:Process industries deploy pressure instrumentation across predictive maintenance platforms with IO-Link connectivity as baseline specification. US Gulf Coast petrochemical complexes and German Ruhr Valley chemical processors prioritize total cost of ownership metrics, concentrating procurement with vendors offering calibration logistics and spare pooling across integrated site networks.
- Automotive:Tier-1 suppliers localize sourcing around Stuttgart and Munich for electric vehicle thermal management and battery pack safety systems. MEMS-based modules dominate underhood applications with wafer-scale fabrication enabling brake system and engine management deployment at automotive cost targets.
- Aerospace:FAA airworthiness certification and EASA design approval requirements sustain multi-year qualification timelines for flight-qualified pressure sensing.
- Oil & Gas:Downhole and subsea applications specify optical and piezoresistive technologies for HPHT environments.
Procurement concentration highest: Industrial Automation. Fastest specification evolution: Automotive.
Application:
Customer type segmentation reveals divergent performance requirements, with medical device manufacturers prioritizing disposable cost structures and process control buyers demanding decades-long service intervals.
- Process Control:Continuous emission monitoring and safety instrumented systems in US power generation and petrochemical facilities mandate SIL-rated pressure transmitters with 0.1% accuracy classes. EPA Clean Air Act enforcement drives replacement cycles, while OSHA process safety management rules shape certification requirements for hazardous environment deployment.
- Medical Devices:Ventilators, dialysis equipment, and infusion pumps require disposable pressure sensors with biocompatibility validation. India's PLI scheme for medical devices creates localized manufacturing demand with NMPA-equivalent certification pathways, attracting suppliers to domestic production incentives.
- Hydraulic Systems:Mobile equipment and industrial machinery specify ruggedized transducers for fluid power monitoring.
- HVAC Systems:Refrigerant pressure monitoring and building automation applications drive volume demand for cost-optimized sensing.
Regulatory intensity highest: Process Control. Policy tailwinds strongest: Medical Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation buyers in Germany and China are driving the majority of new pressure transducer procurement, with automotive electrification and process industry modernization creating concentrated demand pockets across specific manufacturing corridors.
United States
EPA emissions monitoring mandates under the Clean Air Act compel power generation and petrochemical facilities to deploy SIL-rated pressure instrumentation with 0.1% accuracy classes. OSHA process safety management rules shape certification requirements for hazardous environment deployment. Gulf Coast petrochemical complexes in Texas and Louisiana are consolidating procurement around vendors offering calibration logistics and spare pooling across integrated site networks.
Germany
Tier-1 automotive suppliers around Stuttgart and Munich are localizing pressure transducer sourcing for electric vehicle thermal management and battery pack safety systems. REACH substance restrictions enforced by ECHA force reformulation cycles for sensor housings and potting compounds. The Ruhr Valley chemical processing corridor specifies digital transducers with IO-Link connectivity for predictive maintenance platforms.
China
Industrial IoT manufacturing corridors absorb massive volumes of piezoresistive sensors for pump monitoring and compressor protection. GB standards compliance enables domestic substitution of imported instrumentation. Yangtze River Delta manufacturing clusters are scaling MEMS fabrication capacity to serve both automotive underhood applications and process control instrumentation.
India
The PLI scheme for medical devices creates localized demand for disposable pressure sensors with NMPA-equivalent certification pathways for ventilators and dialysis equipment. CDSCO regulations govern medical device market access. Maharashtra and Gujarat industrial zones are attracting suppliers to domestic production incentives for hospital equipment instrumentation.
Japan
Automotive powertrain engineers at OEMs specify silicon carbide MEMS devices for exhaust gas recirculation systems operating above 600°C. METI industrial policy supports advanced sensor technology development. Kanto region manufacturing bases integrate thermal management and pressure measurement into single-package solutions that reduce wiring harness complexity.
Pressure Transducer Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers race to meet automotive electrification and industrial automation demand. The vendor base separates into three distinct tiers: diversified industrial conglomerates with process industry certification depth, MEMS-focused specialists capturing automotive volume, and precision instrumentation houses serving aerospace and medical niches. Portfolio diversification and geographic expansion represent the two most visible competitive vectors, with players extending connectivity protocol support and building regional service networks to anchor multi-year framework agreements.
Among diversified industrial technology providers, Honeywell International Inc, Emerson Electric Co., and Sensata Technologies Holdings PLC exemplify contrasting strategic positions. Honeywell leverages aerospace certification heritage to sustain premium positioning in flight-qualified applications. Emerson anchors industrial automation portfolios with field-proven transmitter architectures for process industries. Sensata occupies the automotive-specialist tier, with MEMS-based module expertise concentrated in underhood thermal and safety system deployments.
| Leading Market Players |
|---|
| Honeywell International Inc |
| ABB Group |
| Emerson Electric Co. |
| TE Connectivity |
| Sensata Technologies Holdings PLC |
| Robert Bosch GmbH |
| NXP Semiconductors N.V. |
| Yokogawa Electric Corporation |
| Endress+Hauser AG |
| Others |
Supply Flow & Price Mechanics
Captive MEMS fabrication in China's Yangtze River Delta manufacturing clusters anchors supply positions for automotive-grade pressure sensing while simultaneously compressing unit economics for commodity piezoresistive devices. This integration choice concentrates pricing power with wafer-scale producers and forces non-integrated suppliers toward premium optical or certified-industrial tiers to escape margin erosion.
Pricing Analysis
Extended calibration and spare-pooling service bundles separate premium industrial automation contracts from unbundled transactional sales. Three-tier pricing structure across SIL-certified process transmitters, automotive MEMS modules, and disposable medical sensors reflects certification depth and volume scale. Pricing pressure stems from Chinese domestic substitution under GB standards, which compresses margins on generic instrumentation. Automotive OEM procurement teams exhibit highest price sensitivity due to wafer-scale cost benchmarks, while aerospace buyers prioritize qualification heritage over unit cost.
Supply Chain Analysis
India's PLI scheme for medical devices and China's NMPA-equivalent certification pathways are reshaping sourcing toward localized final assembly for hospital equipment sensors. Silicon wafer supply concentrates in Taiwan, South Korea, and China's domestic foundry network. Rare earth magnet processing for certain actuator assemblies rests on Chinese refining capacity, creating input concentration risk. Distribution runs through Tier-1 automotive supplier consolidation around Stuttgart and Munich, plus direct framework agreements with US Gulf Coast petrochemical operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where IEC 61508 SIL certification and REACH substance restrictions erect barrier-to-entry moats that reward incumbent investment in qualification infrastructure while filtering out capital-constrained challengers.
For Market Incumbents: Acquire embedded software engineering capabilities to anchor digital transducer architectures with IO-Link and Ethernet-APL protocol support. Backward integration into silicon carbide MEMS fabrication secures thermal management applications above 600°C against emerging Japanese automotive specifications. Consolidate calibration logistics networks across integrated US petrochemical site networks to lock in multi-year framework agreements. For New Entrants and Emerging Players: Enter via India's PLI scheme for medical devices, where domestic manufacturing incentives for ventilators and dialysis equipment create white-space demand for disposable pressure sensors with NMPA-equivalent certification. Target hydrogen economy infrastructure applications, where 700 bar fueling station dispensers and electrolyzer balance-of-plant require specialized metallurgy that generalist suppliers have not addressed. Pursue hospital equipment OEM direct partnerships rather than distribution channel builds. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking MEMS scale or cybersecurity-certified transmitter portfolios. Five-to-ten year viability favors suppliers with IEC 62443-4-2 secure development lifecycle capabilities and hydrogen embrittlement-resistant metallurgy expertise. Watch for inflection when IEC 61508 assessor capacity constraints ease and SIL verification timelines compress from current extended durations.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Scale-Up | Wafer-level silicon micromachining captures automotive brake system and engine management volumes. |
| Backward Integration into Silicon Carbide | In-house SiC MEMS production secures exhaust gas recirculation specifications above 600°C for Japanese OEMs. |
| Ethernet-APL Protocol Certification | Two-wire intrinsically safe networking opens retrofit opportunities in legacy 4-20 mA process installations. |
| REACH-Compliant Material Reformulation | PTFE-free elastomer qualification maintains EU market access as ECHA substance restrictions tighten. |
| Hydrogen Infrastructure Partnership | 700 bar dispenser sensor development anchors position in electrolyzer and fueling station buildouts. |
Methodological Framework
Multi-period observation of EPA enforcement patterns, REACH authorization timelines, and automotive platform electrification roadmaps anchored the trend analysis, supplemented by interviews with maintenance directors at Gulf Coast petrochemical complexes, biomedical engineers specifying ventilator sensors, Tier-1 automotive procurement leads, and MEMS fabrication operations managers. Secondary validation drew from EPA Clean Air Act filings, ECHA SVHC candidate list updates, SEC 10-K instrumentation segment disclosures, and GB standards publication records. Bottom-up sensor shipment estimates triangulated against top-down process industry capital expenditure tracking.
Segment-weighting across product type, technology principle, end-user vertical, and application use-case shaped the analytical framework across the projection horizon. Modeled dimensions included analog versus digital output architectures, piezoresistive versus optical sensing technologies, automotive versus industrial automation versus medical device end-markets, and process control versus safety instrumented system applications. CAGRs derived from regression against industrial automation sensor penetration curves and automotive electrification content-per-vehicle trajectories. Forecast inputs incorporated IEC 61508 certification backlog durations and hydrogen economy infrastructure deployment assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged SIL assessor capacity constraints or accelerated REACH substance restriction timelines. Model assumptions reflect documented regulatory enforcement intensity and OEM platform standardization commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Asia-Pacific Touch Sensor Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
Global E-Nose Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Europe Gas Sensors Market
Sensors and Controls
Ozone Meter Market
Sensors and Controls
North America Fingerprint Sensor Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Quantum Dot Sensor Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Door Control Modules Market